
 Middle-East Aircraft MRO Market | 2026-2036
Middle-East Aircraft MRO Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East Aircraft MRO Market Foresight
Aircraft mechanic and avionics technician shortages across the Gulf Cooperation Council is unwinding capacity expansion timelines at major MRO facilities. Emirates Engineering leverages its Dubai hub scale to anchor wide-body overhaul volumes for the A380 and 777 fleets. Saudia Aerospace Engineering Industries sustains component repair depth through in-house production of structural parts and landing gear sub-assemblies. Etihad Airways Engineering competes on narrow-body line maintenance throughput at Abu Dhabi International Airport.
Middle-East Aircraft MRO encompasses scheduled and unscheduled maintenance, repair, and overhaul of airframes, engines, and components performed to manufacturer specifications and regulatory airworthiness standards, typically requiring specialized tooling, clean-room environments, and certified technician labor pools to restore aircraft systems to approved type design. The primary purpose is ensuring continuous operational safety and dispatch reliability while extending asset economic life. Engine Repair commands premium margin pools due to specialized tooling and OEM intellectual property barriers, while Predictive Maintenance represents the fastest-expanding technology category as airlines deploy sensor analytics to shift from hard-time to condition-based interventions. Heavy Maintenance remains the most mature service type, with capacity utilization dictating regional pricing benchmarks.
GCAA in the UAE, GACA in Saudi Arabia, and EASA through bilateral agreements shape airworthiness certification, technician licensing, and component release standards across the Middle-East MRO landscape. These regulators enforce escalating documentation requirements that filter market access toward facilities with integrated quality management systems and digital record-keeping infrastructure. Stakeholders must monitor how predictive maintenance platform investments align with evolving data sovereignty rules and OEM digital service bundling strategies.
Market Dynamics
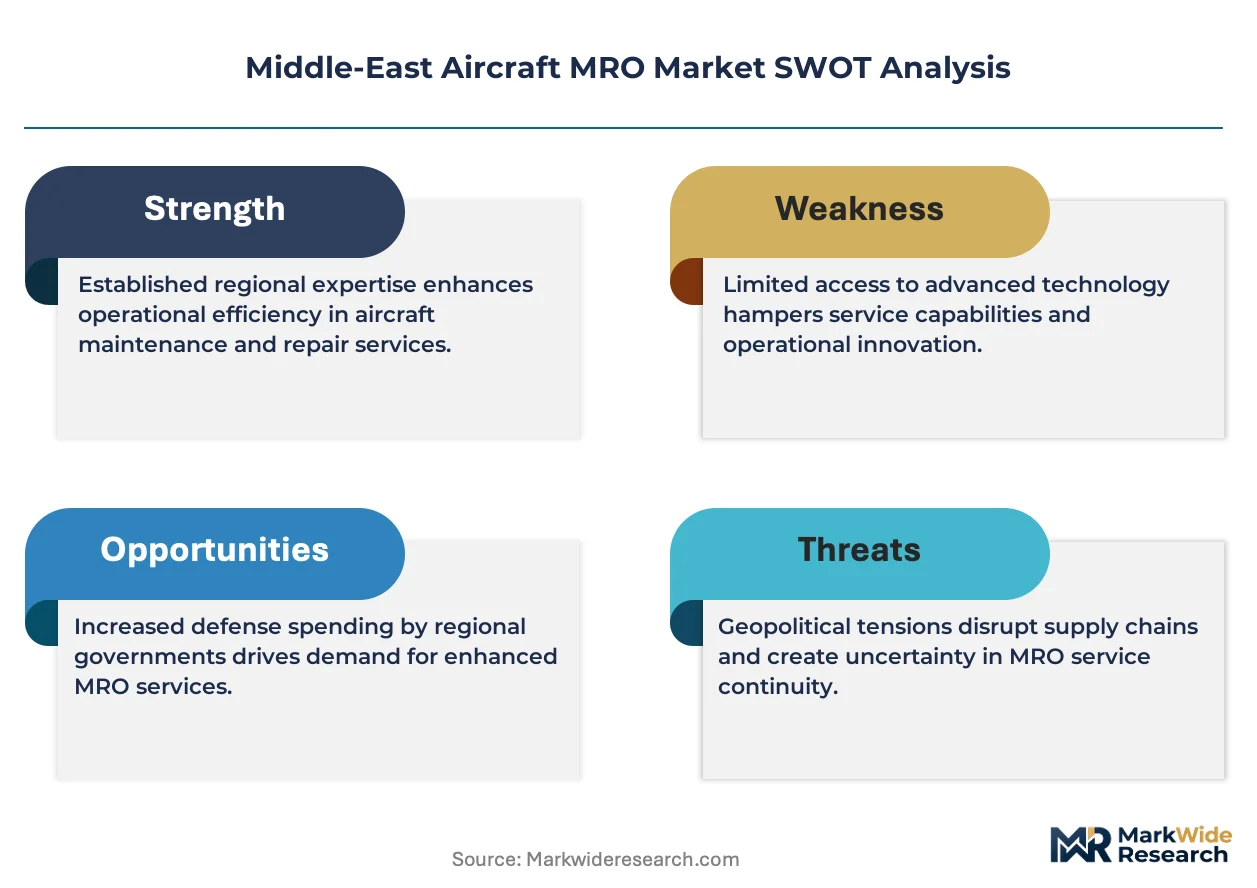
Wide-body fleet renewal across Gulf Cooperation Council carriers is compressing heavy maintenance visit intervals while GCAA and EASA airworthiness mandates escalate documentation burdens. This structural tension between throughput pressure and compliance rigor defines competitive positioning for independent MRO providers.
Growth Catalysts
- New-generation engine entry:Pratt & Whitney GTF and Rolls-Royce Trent XWB inductions are expanding shop visit demand for specialized tooling and clean-room overhaul capacity across Dubai and Abu Dhabi clusters.
- GCAA-EASA bilateral alignment:Harmonized component release standards under the UAE-EU working arrangement are reducing dual-certification overhead for facilities serving European-registered aircraft.
- Hub-and-spoke MRO clustering:Concentration of wide-body fleets at Dubai International and King Abdulaziz International is anchoring line maintenance volume that feeds upstream heavy maintenance demand.
Market Restraints
- Specialized technician scarcity:Aircraft mechanic and avionics certification pipelines across Saudi Arabia and the UAE lag facility expansion timelines, inflating labor cost structures.
- OEM intellectual property barriers:Engine Repair & Overhaul shops face restricted access to proprietary diagnostics and approved repair schemes from Rolls-Royce and GE Aviation.
- Component traceability mandates:EASA Part 145 and GCAA CAR 145 documentation requirements for serialized part histories are filtering market access toward integrated quality management systems.
Strategic Opportunities
- Predictive maintenance platform deployment:Sensor analytics and digital twin integration enable condition-based interventions that compress unscheduled downtime for Emirates and Etihad narrow-body fleets.
- Saudi Arabia localization incentives:GACA Vision 2030 targets for in-country MRO value capture are opening joint-venture structures for component repair depth at King Salman Aerospace Cluster.
- Blockchain-traceability convergence:Distributed ledger systems interfacing with OEM digital service platforms address escalating data sovereignty requirements under UAE data protection frameworks.
Industry Challenges
- Clean-room infrastructure capex intensity:Composite repair stations and avionics test cells require specialized environmental controls that strain facility expansion budgets.
- Dual-certification timeline compression:Simultaneous GCAA and EASA audit cycles for new capability approvals create operational bottlenecks during facility commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East Aircraft MRO Market |
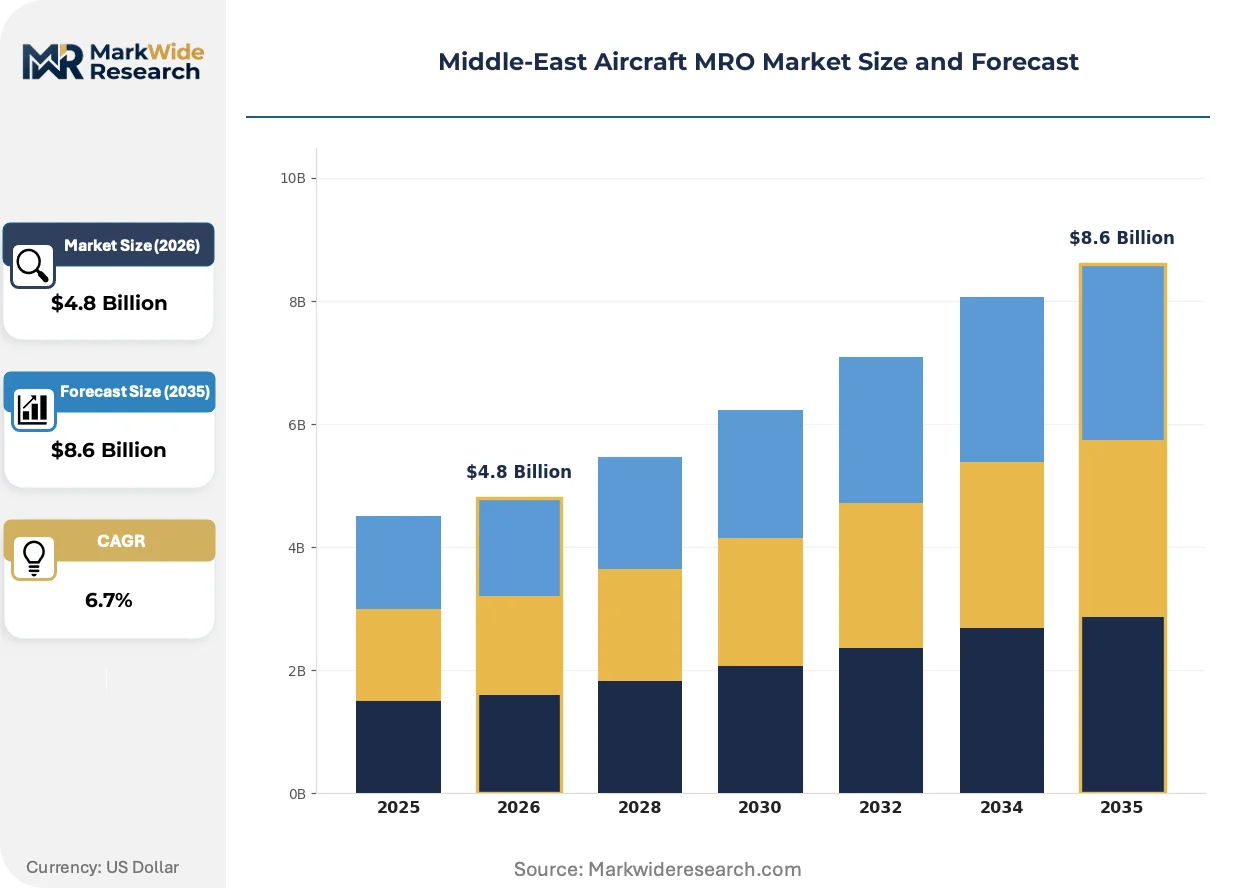
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Heavy Maintenance, Line Maintenance, Component Overhaul, Engine Repair Aircraft Type: Commercial Jets, Business Jets, Helicopters, Military Aircraft End User: Airlines, Cargo Carriers, Military, Private Operators Technology: Advanced Diagnostics, Predictive Maintenance, Repair Technologies, Asset Management Systems |
| Companies Covered | Emirates Engineering, Saudia Aerospace Engineering Industries, Etihad Airways Engineering, Lufthansa Technik AG, General Electric Company, Safran SA, Joramco, Alsalam Aerospace Industries, AMMROC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East Aircraft MRO Market Shifts & Advancements
Digital thread technologies are rewiring how MRO facilities capture, validate, and exchange airworthiness documentation across OEM and regulatory boundaries. This transformation compresses turnaround times while elevating data integrity requirements.
Sensor-based health monitoring is supplanting hard-time maintenance intervals for engine and landing gear systems. Emirates Engineering and Saudia Aerospace Engineering Industries are deploying fleet-wide analytics platforms that feed continuous operational data into predictive algorithms. This shift is compressing unscheduled removal rates while extending on-wing times for high-value rotable assets.
EASA's expanding Part 145 oversight for third-country operators is tightening release documentation standards for Middle-East facilities serving EU-registered aircraft. The regulation is elevating audit frequency and corrective action timelines for non-EU repair stations. Component repair shops across Dubai and Abu Dhabi are responding by integrating digital record-keeping infrastructure that automates traceability workflows.
Airline procurement departments are unbundling line maintenance from heavy maintenance contracts to optimize cash flow and performance accountability. Full-service carriers across the UAE and Saudi Arabia are awarding discrete event-based agreements for C-check and D-check intervals rather than bundled rate-per-flight-hour structures. This pattern is most visible among wide-body operators seeking transparent cost allocation across airframe, engine, and component workscopes.
Middle-East Aircraft MRO Market Segmentation
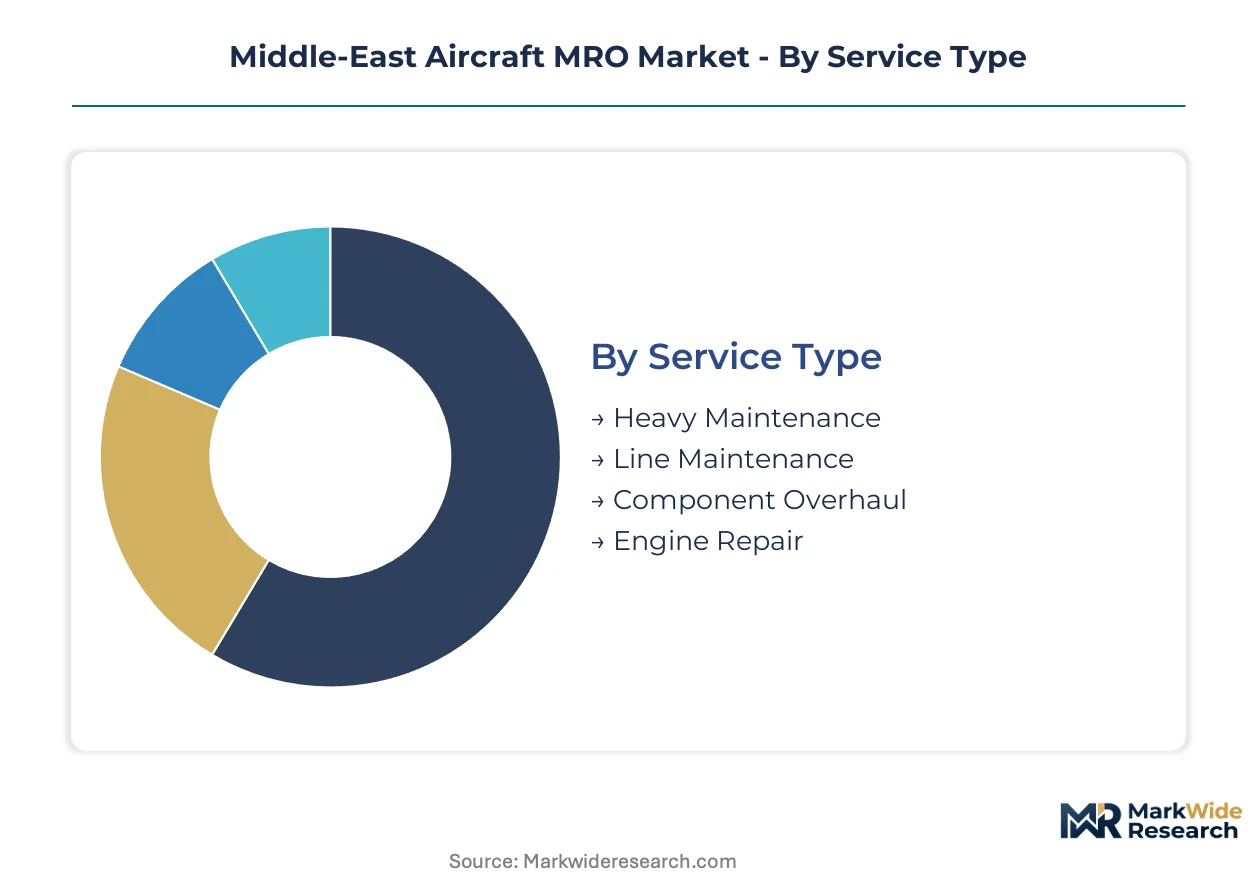
Segmentation in Middle-East Aircraft MRO reveals how regulatory mandates, fleet composition, and technology investments partition margin pools across service providers. Understanding these divisions exposes where capital deployment meets compliance rigor.
Service Type:
Margin pools concentrate in specialized overhaul capabilities where OEM intellectual property creates natural scarcity barriers.
- Engine Repair:Turbofan overhaul demands clean-room environments and proprietary tooling licenses from Rolls-Royce and GE Aviation. Dubai and Abu Dhabi clusters anchor this segment as Emirates and Etihad expand A350 and 777X fleets.
- Heavy Maintenance:C-check and D-check intervals for wide-body fleets require hangar infrastructure and specialized jigs. Saudia Aerospace Engineering Industries leverages in-house structural part production to compress turnaround timelines for 787 and A320neo programs.
- Line Maintenance:Turnaround services at Dubai International and King Abdulaziz International feed upstream heavy maintenance demand through hub-and-spoke volume concentration.
- Component Overhaul:Landing gear and avionics repair shops face EASA Part 145 documentation burdens that filter market access toward integrated quality management systems.
Engine Repair holds installed capacity. Heavy Maintenance is rotating up the share rankings.
Aircraft Type:
Volume distribution tracks fleet renewal patterns across Gulf Cooperation Council carriers and defense procurement cycles.
- Commercial Jets:Narrow-body and wide-body fleets dominate MRO throughput at Emirates Engineering and Etihad Airways Engineering facilities. Predictive maintenance platform deployment is compressing unscheduled removal rates for A320neo and 737 MAX operators.
- Business Jets:Corporate aviation maintenance concentrates in Dubai South and Abu Dhabi clusters serving private aviation terminals. GCAA CAR 145 certification requirements elevate technician licensing standards for this segment.
- Military Aircraft:Royal Saudi Air Force and UAE Air Force sustain sovereign maintenance capabilities through GACA and GCAA defense procurement frameworks.
- Helicopters:Offshore oil and gas transport fleets in the UAE and Saudi Arabia generate specialized rotorcraft overhaul demand.
Commercial Jets anchor facility utilization. Business Jets is climbing the fastest as private aviation infrastructure expands.
End User:
Procurement authority shapes contract structures and performance accountability mechanisms across the value chain.
- Airlines:Full-service carriers unbundle line maintenance from heavy maintenance contracts to optimize cash flow. Emirates and Etihad award discrete event-based agreements for C-check intervals rather than bundled rate-per-flight-hour structures.
- Cargo Carriers:Freighter conversion programs and dedicated cargo fleets at Dubai World Central generate overnight maintenance windows.
- Military:Sovereign airworthiness mandates through GACA and GCAA defense divisions sustain captive maintenance capabilities.
- Private Operators:Corporate flight departments demand flexible scheduling and discrete billing transparency.
Airlines command contract volume. Cargo Carriers is gaining share fastest as e-commerce logistics expand.
Technology:
Digital infrastructure investments determine which facilities meet escalating data sovereignty and traceability mandates.
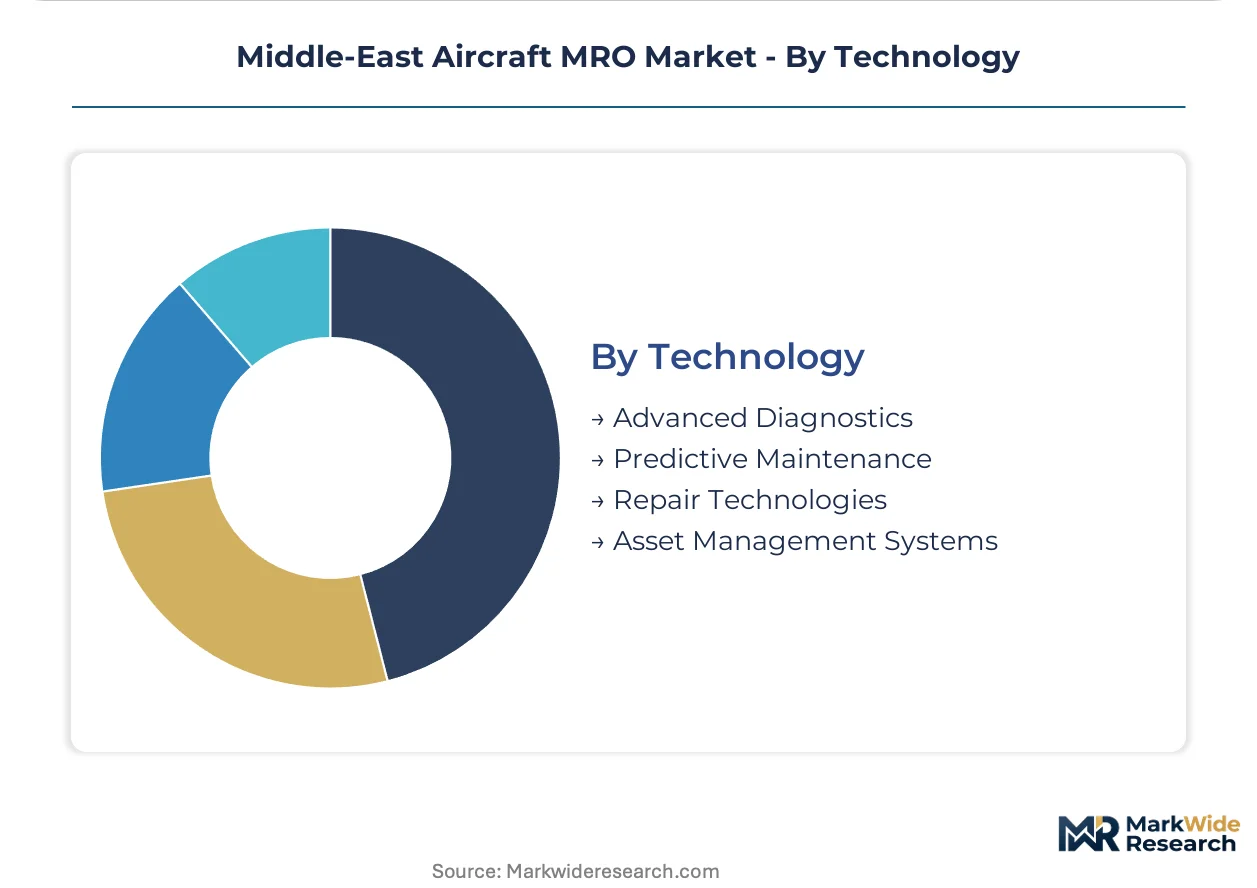
- Predictive Maintenance:Sensor analytics and digital twin integration enable condition-based interventions. Emirates Engineering deploys fleet-wide platforms feeding continuous operational data into predictive algorithms for engine and landing gear systems.
- Advanced Diagnostics:Non-destructive testing and borescope inspection technologies compress defect detection timelines during shop visits.
- Asset Management Systems:Blockchain-traceability convergence addresses UAE data protection frameworks for serialized part histories.
- Repair Technologies:Composite repair stations and additive manufacturing capabilities strain facility expansion budgets.
Predictive Maintenance holds technology leadership. Asset Management Systems is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United Arab Emirates concentrates wide-body heavy maintenance demand through hub-and-spoke fleet clustering, while Saudi Arabia pursues localization through sovereign aerospace clusters. This consumption-mix differential shapes where capital deploys across the Gulf Cooperation Council.
United Arab Emirates
Dubai International and Abu Dhabi International anchor line maintenance volumes that feed upstream engine overhaul demand. GCAA CAR 145 certification requirements filter market access toward facilities with integrated digital record-keeping infrastructure. Dubai South clusters Emirates Engineering and Etihad Airways Engineering operations serving A380 and 777X fleet inductions.
Saudi Arabia
Saudia Aerospace Engineering Industries sustains component repair depth through in-house structural part production for 787 and A320neo programs. GACA Vision 2030 localization targets incentivize joint-venture structures for landing gear and avionics repair capabilities. King Salman Aerospace Cluster in Riyadh is attracting foreign MRO investment through sovereign procurement preferences.
Qatar
Hamad International Airport generates narrow-body turnaround demand that supports line maintenance specialization. QCAA bilateral alignment with EASA reduces dual-certification overhead for facilities serving European-registered aircraft. Doha clusters maintenance operations supporting Qatar Airways' A350 and 777 fleet renewal programs.
Kuwait
Kuwait Airways fleet modernization is expanding shop visit demand for specialized engine tooling and clean-room overhaul capacity. DGCA Kuwait enforces component traceability documentation that elevates quality management system requirements. Kuwait International Airport concentrates third-party MRO services for regional carrier overflow.
Bahrain
Bahrain International Airport serves as a transit maintenance point for Gulf Cooperation Council carrier fleets. CAA Bahrain aligns technician licensing standards with GCAA and EASA frameworks to facilitate cross-border labor mobility. Muharraq hosts specialized avionics repair shops serving business aviation and offshore helicopter operators.
Middle-East Aircraft MRO Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Middle-East Aircraft MRO. Emirates Engineering and Saudia Aerospace Engineering Industries anchor wide-body overhaul capacity through sovereign airline backing, while independent component shops compete on narrow-body line maintenance throughput. The market structures around three archetypes: airline-captive engineering divisions, independent full-service MROs, and OEM-affiliated repair networks. Competitive moves concentrate on capacity expansion in clean-room infrastructure and strategic partnerships for predictive maintenance platform deployment.
Within the airline-captive tier, Emirates Engineering and Saudia Aerospace Engineering Industries exemplify integrated heavy maintenance capabilities. Etihad Airways Engineering occupies a position in the Abu Dhabi cluster competing on narrow-body throughput. Among independent specialists, Joramco represents the third-party full-service archetype serving regional carrier demand.
| Leading Market Players |
|---|
| Emirates Engineering |
| Saudia Aerospace Engineering Industries |
| Etihad Airways Engineering |
| Lufthansa Technik AG |
| General Electric Company |
| Safran SA |
| Joramco |
| Alsalam Aerospace Industries |
| AMMROC |
| Others |
Supply & Pricing Matrix
Wide-body hangar utilization rates at Dubai and Abu Dhabi clusters establish price floors for heavy maintenance slots, compressing margin structures for independent providers while concentrating procurement leverage among Emirates and Etihad engineering divisions. This scale asymmetry feeds into contract negotiations where sovereign airline backing secures preferential slot allocation and tooling access.
Pricing Analysis
Long-term rate-per-flight-hour contracts dominate wide-body heavy maintenance, though Emirates and Etihad are unbundling line maintenance into discrete event-based agreements to optimize cash flow transparency. Price differentiation hinges on EASA Part 145 certification tier and clean-room infrastructure grade, with GCAA-aligned facilities commanding premiums for European-registered aircraft. Pricing pressure intensifies from OEM digital service bundling that restricts independent access to proprietary diagnostics. Cargo carriers exhibit highest price sensitivity due to overnight maintenance windows and fleet utilization pressures, while military operators prioritize sovereign capability over cost.
Supply Chain Analysis
Just-in-time inventory strategies prevail for rotable components at Dubai and Abu Dhabi hubs, though strategic stockpiling of specialized engine tooling persists given Rolls-Royce and GE Aviation licensing bottlenecks. Supply concentration rests on Germany, the United States, and the United Kingdom for precision avionics and composite repair equipment. Raw material dependencies include aerospace-grade aluminum alloys, titanium forgings, and carbon fiber prepregs. Single-source vulnerability from OEM-approved repair scheme restrictions creates structural risk. Distribution runs through sovereign airline engineering divisions that control upstream demand flow to independent component shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across component repair and line maintenance segments creates white-space opportunities as predictive maintenance platform deployment splinters traditional service bundling. Airlines unbundling contracts generate niche entry points for specialized providers with digital certification infrastructure.
For Market Incumbents: Fortify clean-room capacity utilization through multi-year offtake agreements with Qatar Airways and Kuwait Airways fleet renewal programs. Deepen in-house production of structural parts to offset OEM intellectual property restrictions on approved repair schemes. Expand GCAA-EASA dual-certification capabilities to capture European-registered aircraft overflow from Dubai International. For New Entrants and Emerging Players: Anchor in narrow-body line maintenance throughput at King Abdulaziz International and Hamad International Airport, where hub-and-spoke volume concentration feeds predictable demand. Target cargo carrier overnight maintenance windows as the most penetrable segment given flexible scheduling requirements and discrete billing preferences. Pursue joint-venture structures with GACA Vision 2030 localization incentives at King Salman Aerospace Cluster. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among predictive maintenance platform operators with airline fleet-wide deployment contracts. Long-term viability favors facilities with integrated digital record-keeping infrastructure that automates EASA Part 145 traceability workflows. Acquisition focus should center on component repair shops with GCAA CAR 145 certification depth and clean-room environmental controls. Watch for inflection when GACA localization mandates cross procurement preference thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Deployment | Sensor analytics integration enables condition-based interventions that compress unscheduled downtime for Emirates and Etihad narrow-body fleets. |
| Clean-Room Infrastructure Expansion | Composite repair stations and avionics test cells with specialized environmental controls secure EASA Part 145 certification tier premiums. |
| GCAA-EASA Dual-Certification Investment | Harmonized component release standards under UAE-EU working arrangements reduce audit overhead for European-registered aircraft service. |
| Joint Venture with Sovereign Aerospace Clusters | GACA Vision 2030 incentives at King Salman Aerospace Cluster open component repair depth opportunities through localization mandates. |
| Blockchain-Traceability System Integration | Distributed ledger infrastructure addresses escalating UAE data protection requirements for serialized part history documentation. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with MRO facility directors, GCAA certification auditors, airline fleet procurement managers, and OEM aftermarket strategists; and secondary validation through EASA Part 145 oversight reports, GCAA CAR 145 regulatory filings, airline fleet induction announcements, and customs data on aerospace component trade flows. Bottom-up facility capacity assessments and top-down fleet renewal projections were triangulated to constrain estimate variance.
Across the projection horizon, the analytical framework modeled segmentation across service type, aircraft category, end-user procurement authority, and technology deployment stage. CAGRs were derived from facility utilization trends, fleet induction schedules, and regulatory mandate implementation timelines. Forecast inputs incorporated engine shop visit demand curves for Pratt & Whitney GTF and Rolls-Royce Trent XWB programs, plus technician certification pipeline data from Saudi Arabia and the UAE.
Decision-makers should treat outputs as directional under assumptions of sustained GCAA-EASA bilateral alignment and predictable wide-body fleet renewal schedules; material deviation would warrant model refresh. Specific risks include abrupt OEM digital service unbundling, technician scarcity acceleration, or data sovereignty rule changes that disrupt predictive maintenance platform architectures. Revision becomes warranted when GACA localization procurement preferences cross threshold implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Business Jet Mro Market
Aircraft Maintenance and MRO Solutions
US Aerospace Components MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Recycling Market
Aircraft Maintenance and MRO Solutions
Military Aviation Repair Solutions Market
Aircraft Maintenance and MRO Solutions
Aircraft Wheel Bead Breakers Market
Aircraft Maintenance and MRO Solutions
Global Aircraft Heavy Maintenance Visits Market
Aircraft Maintenance and MRO Solutions
Nigeria Aircraft Maintenance Repair and Overhaul Market
Aircraft Maintenance and MRO Solutions
Aircraft Component MRO Market
Aircraft Maintenance and MRO Solutions
Commercial Aircraft Landing Gear MRO Market
Aircraft Maintenance and MRO Solutions
Asia-Pacific Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Frame Alignment Systems Market
Aircraft Maintenance and MRO Solutions
Wide-Body Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Airplane Pushback Tug Market
Aircraft Maintenance and MRO Solutions
Global Aerospace Maintenance Chemical Market
Aircraft Maintenance and MRO Solutions
Colombia Commercial Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Buffing Wheel Market