
 US Aerospace Components MRO Market | 2026-2036
US Aerospace Components MRO Market Size, Share, and Industry Trends Forecast 2026-2036
US Aerospace Components MRO Market Intelligence
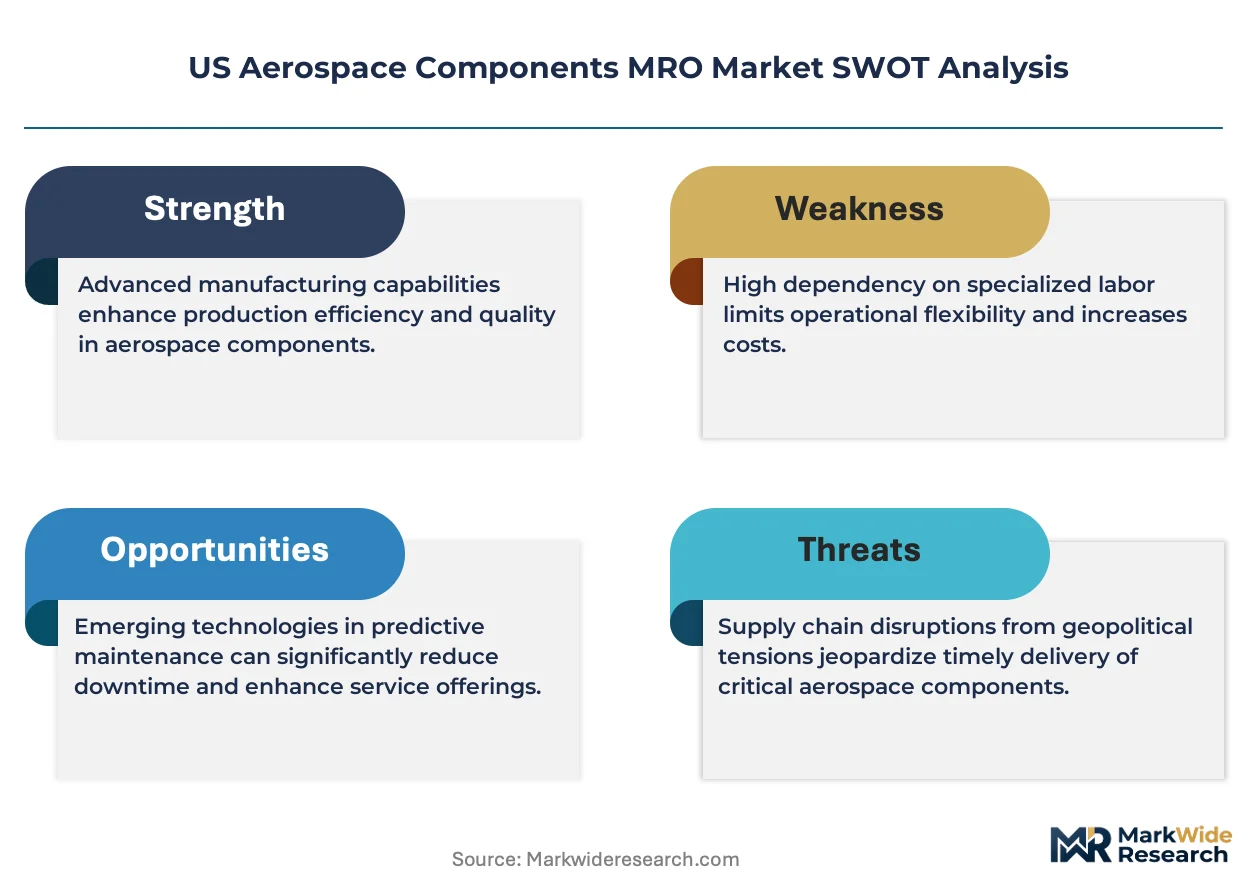
Additive manufacturing adoption is narrowing the gap between OEM replacement timelines and field repair capabilities across turbine blade and structural component workflows. GE Aerospace leverages in-house powder-bed fusion cells to compress lead times on hot-section restorations. StandardAero anchors its competitive position through deep specialization in engine module repair for regional and business jet platforms. Pratt & Whitney dominates the military aftermarket through captive sustainment networks tied to F-135 propulsion system lifecycles.
US Aerospace Components MRO encompasses the inspection, repair, overhaul, and restoration of airworthy structural and propulsion elements to original type certificate specifications, with processes governed by FAA Part 145 repair station certification and AS9110 quality management standards. The primary purpose is to extend safe operational life of flight-critical hardware while maintaining dispatch reliability above regulatory minimums. Engine overhaul commands the largest value pool due to thermal degradation cycles and life-limited part replacement schedules, while predictive maintenance technology represents the fastest-expanding segment as airlines deploy sensor-driven health monitoring to shift from hard-time to condition-based interventions. Digital twin adoption remains concentrated among top-tier MRO providers with integrated fleet data contracts.
FAA Part 145 certification, AS9110 standards, and NDT-specific directives from the FAA's Aging Aircraft Program collectively dictate repair methodology, documentation depth, and technician qualification thresholds across the domestic MRO base. EPA hazardous waste regulations governing chromium plating and solvent recovery further constrain shop-floor process economics, particularly for legacy airframe corrosion treatments. Stakeholders must weigh capital allocation between predictive analytics infrastructure and traditional capacity expansion as fleet demographics skew toward newer-generation platforms with embedded prognostics.
Market Dynamics
Fleet renewal cycles and embedded sensor proliferation are compressing traditional hard-time maintenance intervals toward predictive, condition-based interventions across US commercial and military aviation.
Growth Catalysts
- FAA Part 145 Repair Station Certification:Mandatory certification requirements for airframe, powerplant, and propeller specialties create steady demand for qualified MRO capacity as fleet utilization rebounds post-pandemic.
- Additive Manufacturing:Powder-bed fusion and directed energy deposition processes slash lead times for turbine blade restoration and structural component repairs, narrowing the gap between field capability and OEM replacement timelines.
- Southwest Hub Concentration:Dense MRO clusters in Texas and Arizona generate regional economies of scale that attract specialized tooling investments and technician labor pools.
Market Restraints
- Specialized Alloy Supply Concentration:Nickel-based superalloys and titanium forgings for hot-section components face sourcing bottlenecks from limited domestic mill capacity, inflating raw material carrying costs.
- EPA Hazardous Waste Regulations:Chromium plating baths and solvent recovery systems trigger stringent environmental compliance costs that disproportionately burden smaller repair stations performing legacy airframe corrosion treatments.
- Technical Limitation of NDT Resolution:Conventional ultrasonic and eddy-current methods struggle to detect subsurface microcracking in single-crystal turbine blades, forcing conservative scrap rates on repairable components.
Strategic Opportunities
- Digital Twin Integration:Physics-based modeling combined with real-time sensor feeds from embedded engine health monitoring systems enables remaining-useful-life predictions that optimize shop visit scheduling.
- Regional Jet Fleet Expansion:Underpenetrated MRO capacity for CF34 and PW1000G-powered regional platforms creates white space for specialized engine module repair providers.
- IRA Clean Energy Provisions:Tax incentives for sustainable aviation fuel infrastructure indirectly boost MRO demand through accelerated fleet turnover and new-engine adoption curves.
Industry Challenges
- AS9110-C Certification Timelines:Quality management system audits for repair station expansion average fourteen to eighteen months, throttling capacity additions during demand surges.
- Legacy System Integration Friction:Predictive maintenance platforms must interface with decades-old maintenance tracking databases, creating data standardization bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Aerospace Components MRO Market |
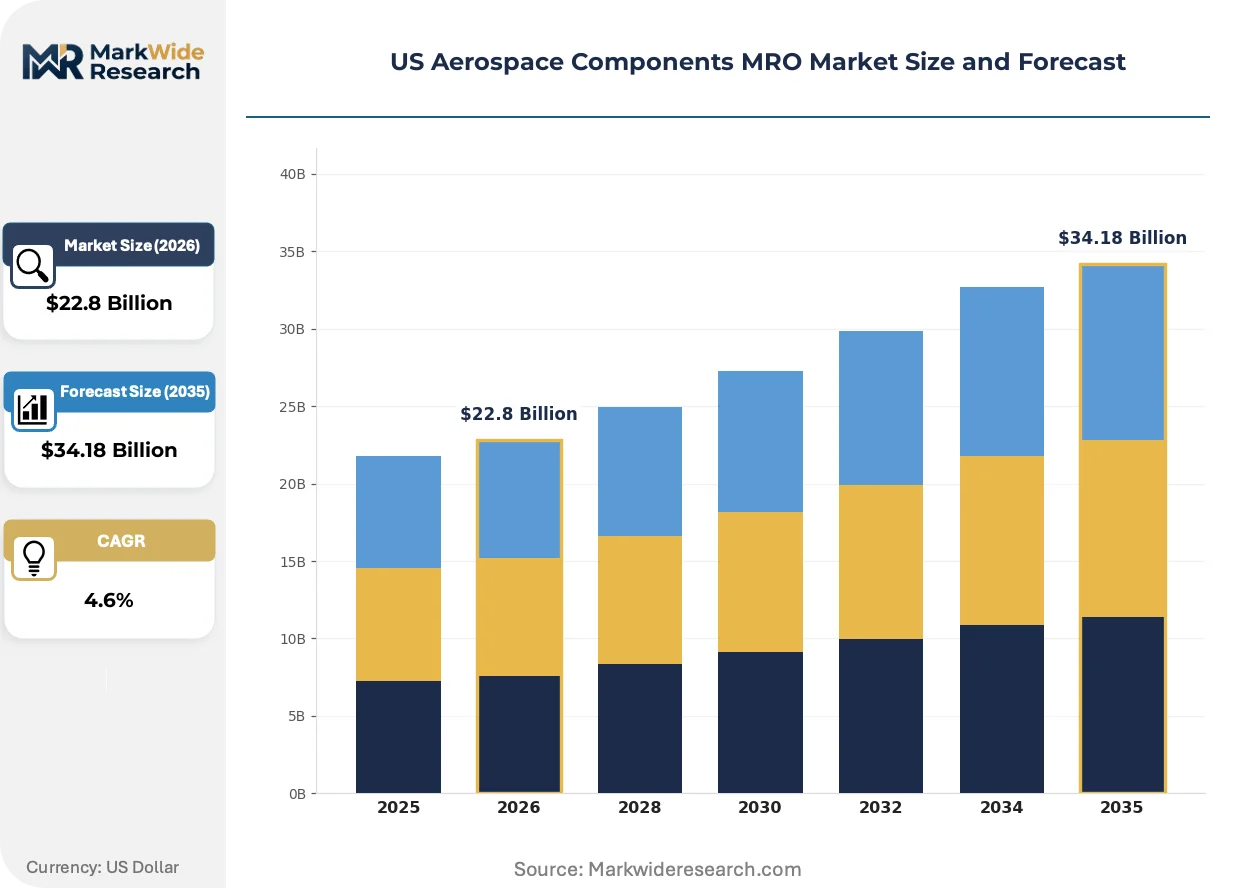
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $34.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Component Repair, Overhaul Services, Maintenance Services, Inspection Services End User: Aerospace OEMs, Airlines, MRO Providers, Defense Contractors Component Type: Engines, Avionics, Landing Gear, Airframe Technology: Traditional Methods, Advanced Materials, Predictive Maintenance, Digital Twin |
| Companies Covered | AAR Corp, Delta TechOps, StandardAero, Barnes Aerospace, RTX Corporation, GE Aerospace, Honeywell International, Pratt & Whitney, Raytheon Technologies Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Aerospace Components MRO Market Strategic Shifts & Innovations
Sensor fusion and physics-based modeling are collapsing the distinction between scheduled overhaul and on-condition maintenance, forcing MRO providers to reconfigure shop floors around data-driven triage rather than calendar-driven workflow.
Digital twin technology is virtualizing engine module diagnostics by creating real-time computational replicas of hot-section components under actual flight loads. Major carriers with integrated fleet data contracts deploy these models to pre-position replacement parts before physical inspection. The technology is virtualizing traditional teardown sequences, compressing turnaround times by identifying specific life-limited parts requiring replacement without full disassembly.
FAA Aging Aircraft Program directives mandate enhanced structural inspection protocols for airframes exceeding twenty years of service, compelling MRO providers to invest in phased-array ultrasonic and computed radiography systems. The regulatory pressure elevates documentation depth and technician qualification thresholds, particularly for corrosion-prone lap joints and pressure bulkhead regions. Cargo conversion specialists face the steepest compliance curves as passenger-to-freighter programs extend airframe lifecycles.
Airlines with dense narrowbody fleets now bundle component repair with flight-hour agreements, transferring inventory risk to MRO providers in exchange for guaranteed unit pricing. The model displaces traditional time-and-material invoicing at major hub carriers, squeezing margin visibility for repair stations lacking predictive analytics infrastructure. Southwest and Southeast US-based low-cost carriers drive the steepest contract restructuring.
US Aerospace Components MRO Market Segmentation
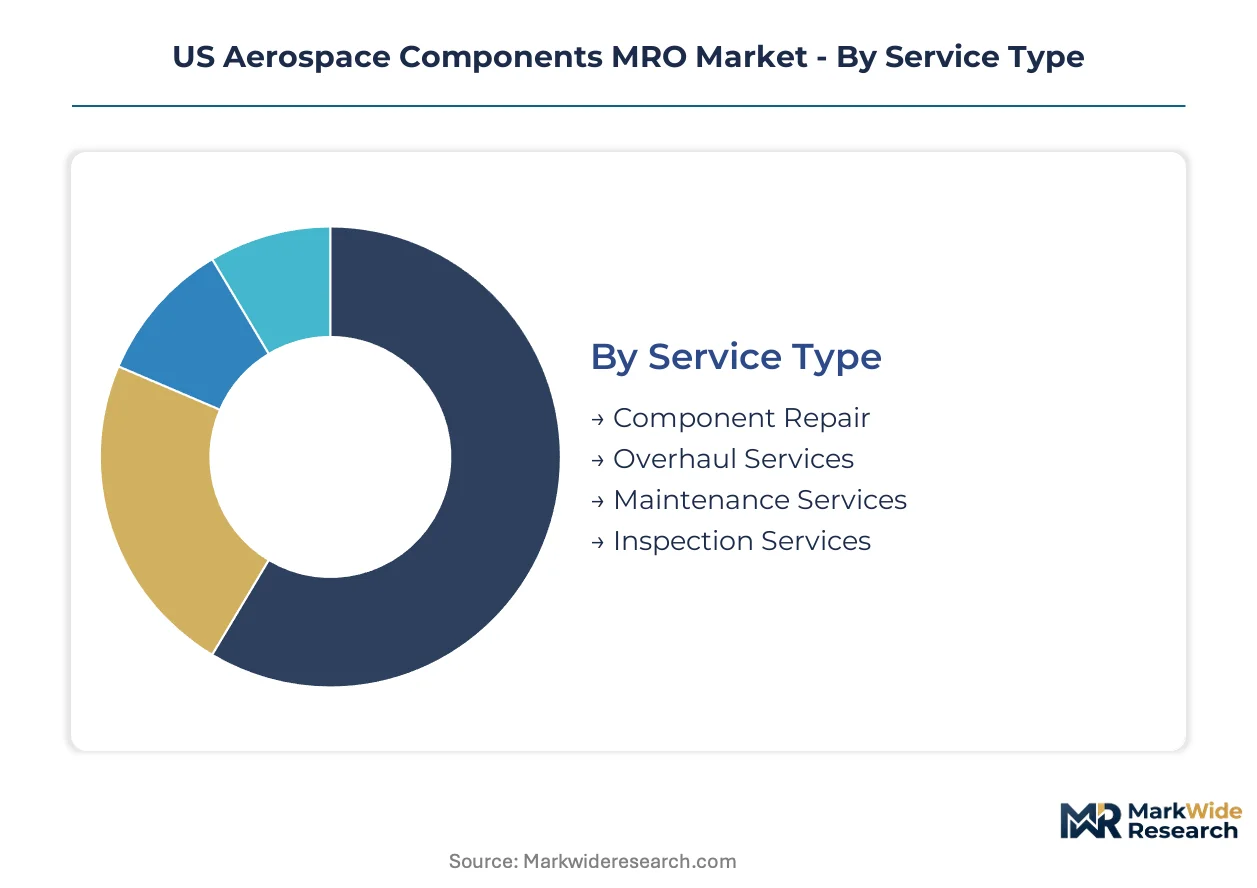
Segmentation reveals how MRO value pools concentrate across service maturity levels and buyer sophistication. Understanding these divides helps providers align capital deployment with where margins and volume actually intersect.
Service Type:
Mature inspection and repair workflows coexist with emerging predictive and overhaul platforms that compress turnaround economics.
- Component Repair:Field-level restoration of turbine blades, actuators, and structural elements using FAA Part 145 certified weld and coating processes. Demand clusters at Southwest hub facilities in Texas and Arizona where narrowbody fleet density justifies dedicated cell investments. Thermal barrier coating restoration and single-crystal blade welding command premium technician qualifications.
- Overhaul Services:Complete module teardown, measurement, and reassembly to OEM service bulletin specifications with full life-limited part replacement. Engine overhaul absorbs the largest capital allocation due to hot-section degradation cycles and FAA-mandated documentation depth.
- Maintenance Services:Scheduled line and base maintenance tasks including lubrication, filter changes, and minor adjustments per aircraft maintenance manual intervals.
- Inspection Services:Non-destructive testing protocols including phased-array ultrasonic and eddy-current scanning for crack detection and corrosion mapping.
Component repair handles the majority of throughput; predictive-enabled overhaul services are climbing the fastest on share.
End User:
Buyer sophistication spans captive OEM networks, cost-focused airlines, independent MRO consolidators, and mission-critical defense programs.
- Aerospace OEMs:GE Aerospace and Pratt & Whitney maintain captive sustainment arms for warranty fulfillment and lifecycle revenue capture. OEM-direct programs leverage factory tooling and proprietary technical data rights to control post-warranty market access.
- Airlines:Major carriers with dense narrowbody fleets drive flight-hour agreement restructuring, transferring inventory risk to providers. Southwest US-based low-cost operators lead contract compression toward guaranteed unit pricing.
- MRO Providers:Independent repair stations and consolidators like StandardAero compete on specialized module expertise and regional proximity. Third-party providers face margin pressure without predictive analytics infrastructure.
- Defense Contractors:Military sustainment networks tied to F-135 and legacy platform propulsion systems operate under cost-plus contracting with distinct security and traceability requirements.
Airlines generate the dominant volume base; defense contractors sustain the most defensible margin structure.
Component Type:
Physical segmentation follows thermal stress concentration and electronic obsolescence patterns across propulsion, avionics, structural, and landing systems.
- Engines:Hot-section modules endure the most severe thermal cycling and require the deepest technical specialization. Nickel-based superalloy restoration and life-limited part management absorb disproportionate MRO capital.
- Avionics:Software-defined systems face obsolescence-driven refresh cycles and cybersecurity-hardened configuration control. Retrofit demand concentrates on legacy fleet glass cockpit upgrades.
- Landing Gear:High-cycle fatigue components require periodic re-chroming and seal replacement under FAA Aging Aircraft Program scrutiny.
- Airframe:Corrosion-prone lap joints and pressure bulkhead regions trigger enhanced inspection protocols for aircraft exceeding twenty years of service.
Engines command the largest absolute spend; avionics is expanding most quickly on digitization tailwinds.
Technology:
Process segmentation tracks the shift from manual craft toward sensor-integrated, model-predictive maintenance systems.
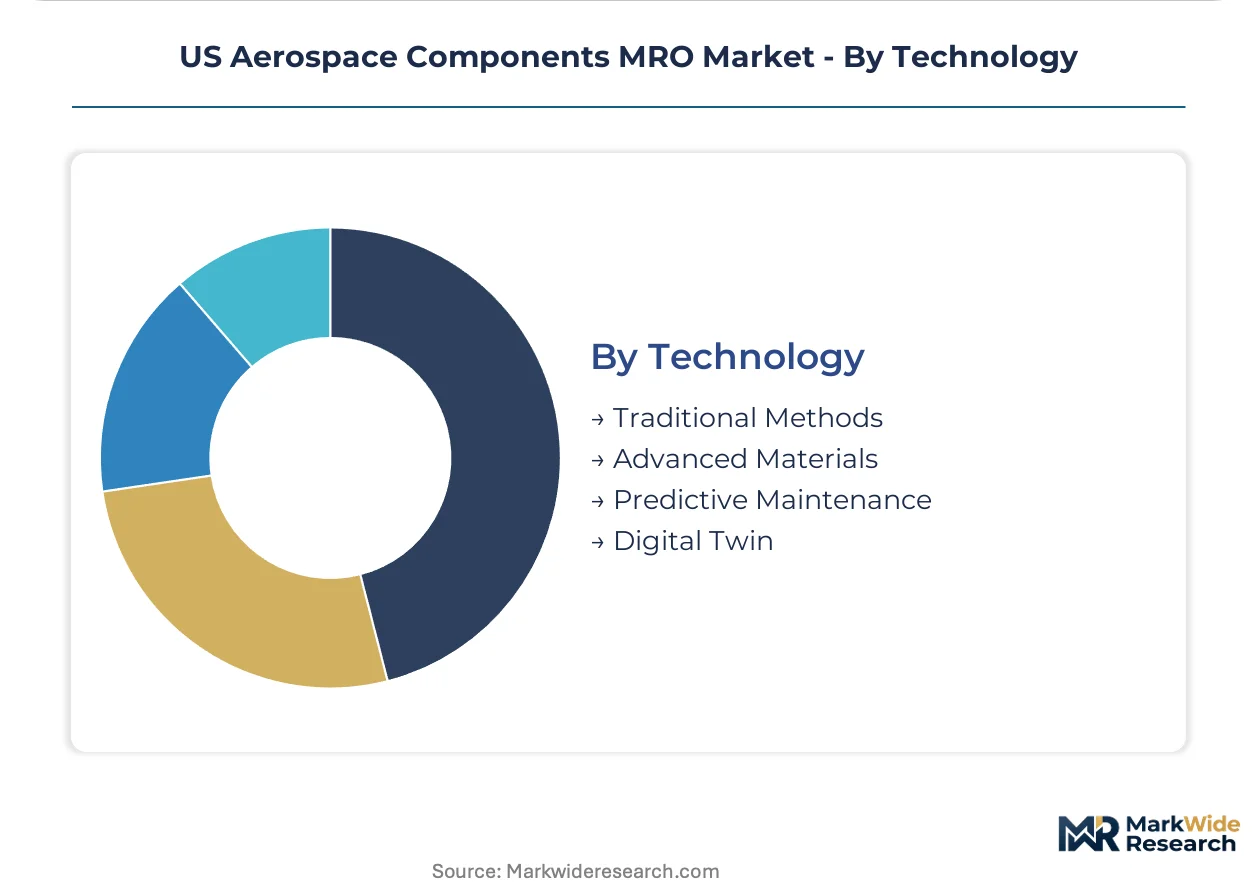
- Traditional Methods:Manual teardown, visual inspection, and hard-time replacement schedules governed by calendar or flight-hour triggers. Legacy workflows persist where sensor penetration remains limited.
- Advanced Materials:Additive manufacturing cells using powder-bed fusion for turbine blade restoration and directed energy deposition for structural repairs. GE Aerospace deploys in-house metal printing to compress OEM replacement timelines.
- Predictive Maintenance:Sensor-driven health monitoring platforms shifting interventions from hard-time to condition-based triggers. Embedded engine diagnostics feed remaining-useful-life algorithms.
- Digital Twin:Physics-based computational replicas of hot-section components under actual flight loads, enabling pre-positioned parts and targeted teardown sequences.
Traditional methods still process the bulk of shop visits; digital twin deployment is gaining share fastest among tier-one integrated providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US aerospace MRO exports flow primarily to Latin American and Caribbean carriers seeking FAA-certified repair capacity, while domestic demand concentrates in states hosting major airline hubs and defense installations.
Texas
Dallas-Fort Worth and Houston anchor the nation's densest MRO corridor, serving American Airlines and United's narrowbody fleets through dedicated engine and component repair cells. FAA Part 145 repair station density here exceeds any other state, with specialized nickel-alloy welding shops clustering near DFW International. San Antonio hosts military sustainment networks tied to Air Force logistics commands, creating dual-use technician labor pools that commercial providers tap during surge demand.
Arizona
Phoenix-Mesa and Tucson generate concentrated demand from low-cost carrier bases and military aircraft storage facilities at Davis-Monthan Air Force Base. The state's dry climate reduces corrosion-related inspection burdens, attracting airframe heavy maintenance providers seeking predictable workflow scheduling. Arizona Commerce Authority tax incentives for aviation workforce training have expanded FAA-certified technician pipelines at community college partnerships.
Florida
Miami and Orlando serve as primary gateways for Latin American carrier MRO demand, with Spanish-speaking technical documentation capabilities creating competitive differentiation. The state's cargo conversion specialists face steep FAA Aging Aircraft Program compliance curves as passenger-to-freighter programs extend airframe lifecycles. Melbourne and Palm Beach host business jet MRO clusters serving fractional ownership fleets.
California
Los Angeles and San Francisco Bay Area facilities specialize in widebody component repair and avionics retrofit for transpacific carrier operations. California Air Resources Board emissions regulations accelerate sustainable aviation fuel infrastructure investments, indirectly boosting new-engine adoption and associated MRO demand. Southern California's defense contractor presence sustains classified repair capabilities with distinct security clearance requirements.
Georgia
Atlanta anchors Delta Air Lines' captive MRO infrastructure, with Delta TechOps representing one of North America's largest independent repair capacities. The state's technical college system feeds FAA-certified airframe and powerplant mechanics directly into Hartsfield-Jackson corridor facilities. Savannah's Gulfstream presence creates specialized business jet MRO demand for composite structure repair and cabin system integration.
US Aerospace Components MRO Market Key Industry Players
On the supply side, the industry is bifurcated between OEM-captive sustainment arms and independent repair stations competing on specialization and regional proximity. Tier-one providers with integrated fleet data contracts capture flight-hour agreement volume, while mid-scale independents defend position through narrow technical excellence in specific engine modules or component categories. Strategic archetypes include OEM-direct networks, independent consolidators, and defense-focused cost-plus contractors. Competitive moves center on additive manufacturing cell investments and predictive analytics infrastructure deployment.
Within the OEM-captive tier, GE Aerospace and Pratt & Whitney occupy positions controlling factory tooling and proprietary technical data rights for post-warranty market access. StandardAero represents the independent specialist archetype, competing through deep module repair expertise for regional and business jet platforms. Among diversified industrial conglomerates, RTX Corporation and Honeywell International sit within structures spanning avionics, propulsion, and aftermarket services.
| Leading Market Players |
|---|
| AAR Corp |
| Delta TechOps |
| StandardAero |
| Barnes Aerospace |
| RTX Corporation |
| GE Aerospace |
| Honeywell International |
| Pratt & Whitney |
| Raytheon Technologies Corporation |
| Others |
Cost & Logistics Intelligence
Nickel-based superalloy and titanium forging supply from limited domestic mill capacity concentrates upstream pricing power in the hands of specialty metal producers, forcing MRO providers to absorb carrying cost inflation or pass through to flight-hour agreement customers. This raw material bottleneck situates margin defense at the alloy sourcing tier rather than the repair station floor.
Pricing Analysis
Next-generation predictive maintenance platforms command premium positioning against legacy hard-time service tiers and emerging digital-twin-enabled overhaul bundles. Three-tier pricing structure across OEM-direct, independent specialist, and regional repair station levels stratifies by certification depth and fleet data integration. Cost compression in legacy component repair is intensifying because flight-hour agreements transfer inventory risk to providers. Low-cost carriers with dense narrowbody fleets exhibit highest price sensitivity; defense contractors with cost-plus sustainment contracts show lowest.
Supply Chain Analysis
ITAR and EAR export controls on single-crystal casting technology and powder-bed fusion systems restrict cross-border equipment flows, fragmenting global supplier networks. Hot-section component supply draws from domestic specialty alloy mills, Japanese precision forging houses, and European coating technology providers. Single-source vulnerability concentrates in nickel superalloy billet supply from domestic mills. Distribution runs through FAA Part 145 repair station networks clustered in Texas and Arizona hub corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat arena where FAA Part 145 certification timelines and proprietary technical data rights create entrenched switching costs. The fourteen-to-eighteen-month AS9110-C audit cycle locks in incumbent position.
For Market Incumbents: Entrench through captive additive manufacturing cell investments that compress OEM replacement timelines, and deepen upstream control over nickel superalloy supply agreements. Emerging predictive analytics platforms from integrated fleet data contractors threaten traditional time-and-material invoicing. Certification investment in phased-array ultrasonic and computed radiography systems defends against FAA Aging Aircraft Program compliance escalation. For New Entrants and Emerging Players: Arizona and Florida regional jet MRO capacity offers the most penetrable white space, with CF34 and PW1000G engine module repair underserved relative to narrowbody density. Specialized composite structure repair for business jet platforms at Savannah and Palm Beach clusters represents secondary entry path. Go-to-market positioning should anchor on Spanish-speaking technical documentation capabilities for Latin American carrier contracts. For Investors and Strategic Acquirers: Capital is best deployed toward independent specialists with deep module expertise and established FAA repair station footprints rather than undifferentiated regional players. Long-term viability hinges on predictive analytics infrastructure deployment across the projection horizon. Watch for flight-hour agreement contract restructuring at Southwest and Southeast low-cost carriers as margin compression signal.| Strategic Initiative | Industry Significance |
|---|---|
| Additive Manufacturing Cell Deployment | Powder-bed fusion capabilities compress turbine blade restoration lead times against OEM replacement schedules. |
| Predictive Analytics Infrastructure | Sensor-driven health monitoring platforms enable condition-based interventions shifting from hard-time maintenance. |
| FAA Part 145 Certification Expansion | Repair station capacity additions capture surge demand from post-pandemic fleet utilization rebound. |
| Digital Twin Integration | Physics-based modeling with embedded engine diagnostics optimizes remaining-useful-life predictions for shop scheduling. |
| Regional Jet Specialization | CF34 and PW1000G module repair expertise addresses underpenetrated capacity in growing regional fleet segments. |
Research Approach
Operator-level perspectives from MRO facility directors, airline fleet managers, FAA certification auditors, and specialty alloy procurement leads anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through FAA repair station databases, EASA regulatory filings, EPA hazardous waste compliance records, and SEC 10-K disclosures from diversified aerospace conglomerates. Bottom-up repair station capacity modeling and top-down fleet demand projections were triangulated against nickel superalloy consumption data.
Scenario-bracketing around fleet renewal cycles and embedded sensor penetration rates bounded the analytical framework across the projection horizon. Segmentation dimensions modeled include service type maturity, end-user sophistication tier, component thermal stress category, and technology adoption curve. CAGRs were derived from repair visit frequency projections and average revenue per shop visit trajectories. Forecast inputs incorporated FAA Aging Aircraft Program directive issuance rates and predictive maintenance platform deployment curves among major carriers.
Practitioners should monitor ITAR regulation expansion and sustainable aviation fuel infrastructure subsidy shifts for early signals. Forecasts reflect documented assumptions on fleet demographics and sensor penetration. Material shifts in nickel superalloy mill capacity or FAA Part 145 certification timeline reform would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Latin America Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Southeast Asia Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aviation Maintenance Software Market
Aircraft Maintenance and MRO Solutions
Nigeria Aircraft Maintenance Repair and Overhaul Market
Aircraft Maintenance and MRO Solutions
Aviation Asset Management Market
Aircraft Maintenance and MRO Solutions
North America Aerospace Maintenance Chemical Market
Aircraft Maintenance and MRO Solutions
Aircraft Weighing Scales Market
Aircraft Maintenance and MRO Solutions
Commercial Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Component MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Line Maintenance Market
Aircraft Maintenance and MRO Solutions
Aircraft Vacuum Cleaners Market
Aircraft Maintenance and MRO Solutions
Africa Aircraft Windshield Wiper and Washer System Market
Aircraft Maintenance and MRO Solutions
Aviation Maintenance Repair and Overhaul MRO Software Market
Aircraft Maintenance and MRO Solutions
Commercial Aircraft Maintenance Repair and Overhaul (MRO) Market
Aircraft Maintenance and MRO Solutions
Asia-Pacific Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Frame Alignment Systems Market