
 Global Aircraft Refurbishing Market | 2026-2036
Global Aircraft Refurbishing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aircraft Refurbishing Market Intelligence
A shortage of certified airframe technicians is rotating toward the most acute bottleneck in aftermarket capacity expansion. Lufthansa Technik leverages its Hamburg headquarters to sustain one of the deepest pools of specialized labor in Europe. AAR Corporation anchors North American MRO capacity through its network of domestic repair stations. ST Engineering competes across Southeast Asia with integrated airframe and component capabilities.
Aircraft refurbishing encompasses the structural restoration, systems modernization, and aesthetic renewal of existing airframes to extend operational life and restore regulatory compliance, typically involving composite panel replacement, wiring harness upgrades, and corrosion treatment across aluminum-lithium structures. The primary purpose is to defer capital-intensive new aircraft procurement while restoring passenger-facing cabin environments and flight-critical avionics to current standards. Cabin retrofitting dominates value pools as airlines prioritize revenue-generating interior reconfigurations over purely mechanical overhauls. Avionics upgrade segments are expanding fastest as NextGen and SESAR mandates force compliance-driven cockpit modernization across aging narrow-body and wide-body fleets.
The FAA mandates specific aging aircraft inspection protocols under AD notes that trigger structural refurbishment demand, while EASA enforces Part-M continuing airworthiness requirements that govern European operator refurbishment cycles. The EU F-Gas Regulation progressively restricts high-global-warming-potential refrigerants in aircraft cabin cooling systems, compelling galley and climate system retrofits during heavy maintenance visits. Stakeholders must monitor how evolving EPA emissions standards for auxiliary power units and emerging ICAO carbon intensity frameworks reshape the economic calculus between deep refurbishment and premature fleet retirement.
Market Dynamics
Supply chain constraints on new aircraft deliveries are forcing carriers to extend existing fleet operational life through comprehensive refurbishment programs rather than replacement procurement.
Growth Catalysts
- FAA Aging Aircraft Directives:Mandatory structural inspection protocols under Airworthiness Directives trigger systematic airframe refurbishment cycles across narrow-body and wide-body fleets operating beyond design service objectives.
- Composite Panel Replacement:Airlines operating Boeing 737NG and Airbus A320ceo families accelerate structural renewal programs to address fatigue-critical zones and corrosion in aluminum-lithium primary structures.
- EU F-Gas Regulation Phase-Down:Progressive restrictions on high-global-warming-potential refrigerants compel galley and cabin climate system retrofits during heavy maintenance visits.
Market Restraints
- Certified Technician Scarcity:The acute shortage of FAA-licensed airframe and powerplant mechanics limits aftermarket capacity expansion regardless of capital availability.
- Titanium and Composite Input Volatility:Aerospace-grade material costs fluctuate with defense sector demand cycles, compressing refurbishment margin predictability for independent MRO providers.
- Substitution by Lease Returns:Airlines with access to mid-life leased aircraft increasingly favor temporary capacity substitution over capital-intensive owned-fleet refurbishment.
Strategic Opportunities
- Cargo Conversion Surge:Passenger-to-freighter modification demand creates dedicated refurbishment revenue streams for wide-body airframes approaching passenger service retirement.
- NextGen Avionics Mandates:FAA ADS-B Out and EU SESAR compliance deadlines force cockpit modernization across aging fleets unable to meet performance-based navigation requirements.
- India Fleet Expansion:Rapid domestic aviation growth generates demand for imported used-aircraft refurbishment to bypass new aircraft delivery backlogs.
Industry Challenges
- Airworthiness Certification Timeline Compression:FAA and EASA supplemental type certificate approval delays extend aircraft downtime and disrupt airline network planning.
- Legacy Wiring Harness Integration:Modern avionics retrofits require extensive electrical system modification to interface with original manufacturer architectures from the 1990s.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aircraft Refurbishing Market |
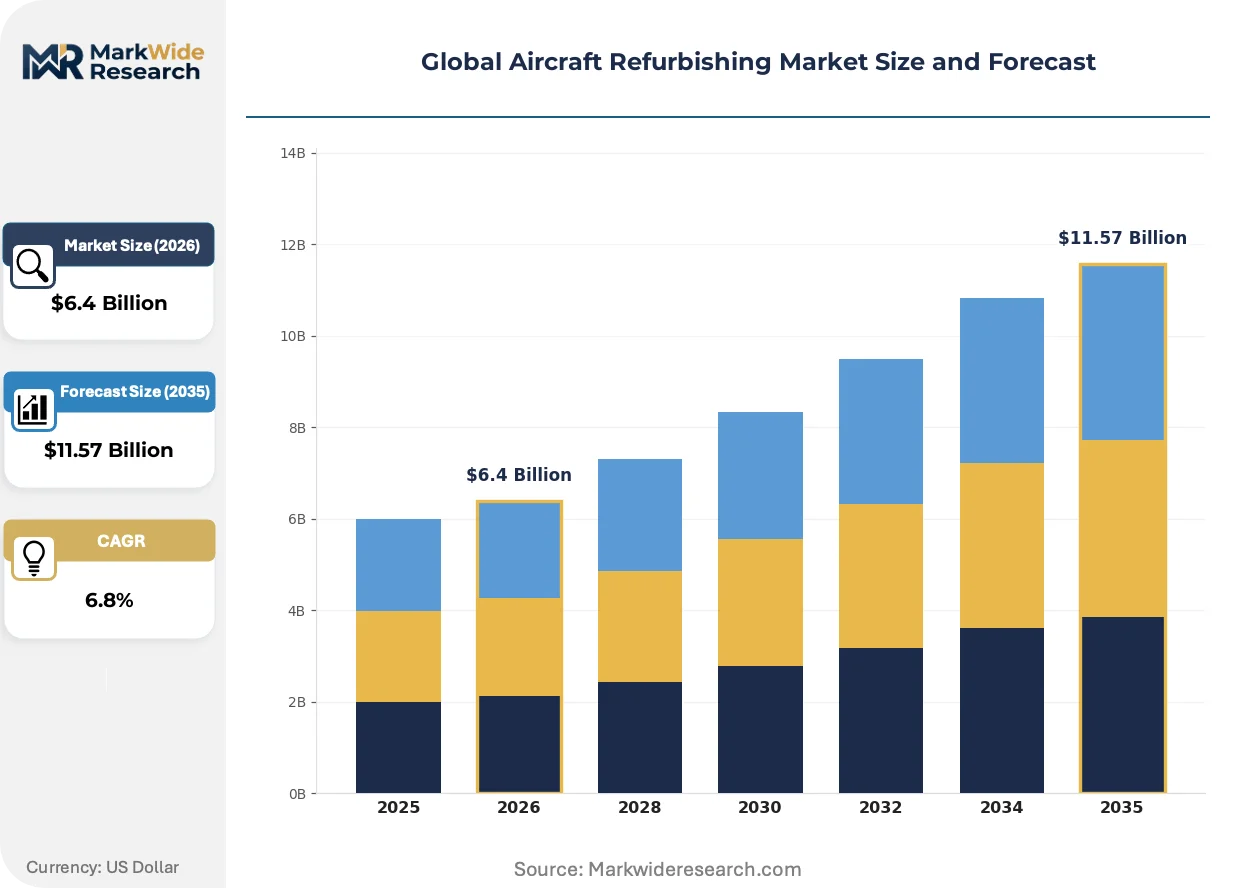
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $11.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cabin Retrofitting, Avionics Upgrade, Interior Refurbishment, Exterior Coating Product Type: Passenger Seating, In-Flight Entertainment, Galley Equipment, Lavatory Systems, Lighting Systems Aircraft Type: Narrow-Body Jets, Wide-Body Jets, Regional Aircraft, Business Jets End User: Airlines, Maintenance Repair Organizations, Government Agencies, Charter Operators |
| Companies Covered | Lufthansa Technik, AAR Corporation, Gulfstream Aerospace Corporation, ST Engineering, Air France Industries KLM Engineering & Maintenance, SIA Engineering Company, Jet Aviation, SAFRAN, Hong Kong Aircraft Engineering Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aircraft Refurbishing Market Strategic Shifts & Innovations
Digital inspection technologies and sustainable material substitution are compressing refurbishment cycle times while regulatory mandates force technology refresh across aging platforms.
Additive manufacturing is decomposing traditional sheet-metal fabrication for non-structural interior components. Airlines retrofitting narrow-body cabins now specify 3D-printed seat parts and galley inserts to reduce lead times from months to weeks. This technology is decomposing established supplier relationships and enabling point-of-use production at major MRO facilities.
The EU F-Gas Regulation mandates progressive phase-down of hydrofluorocarbon refrigerants in aircraft cabin cooling systems. Operators must retrofit or replace climate control units during heavy maintenance visits to maintain airworthiness certification. European narrow-body fleets face the most compressed compliance timeline as 2027 restrictions approach.
Airlines now unbundle interior refurbishment from airframe heavy maintenance, awarding separate contracts to specialized cabin integrators. This procurement fragmentation disrupts traditional full-service MRO bundled offerings. North American carriers lead this disaggregation, driving independent interior specialists to establish dedicated production lines.
Global Aircraft Refurbishing Market Segmentation
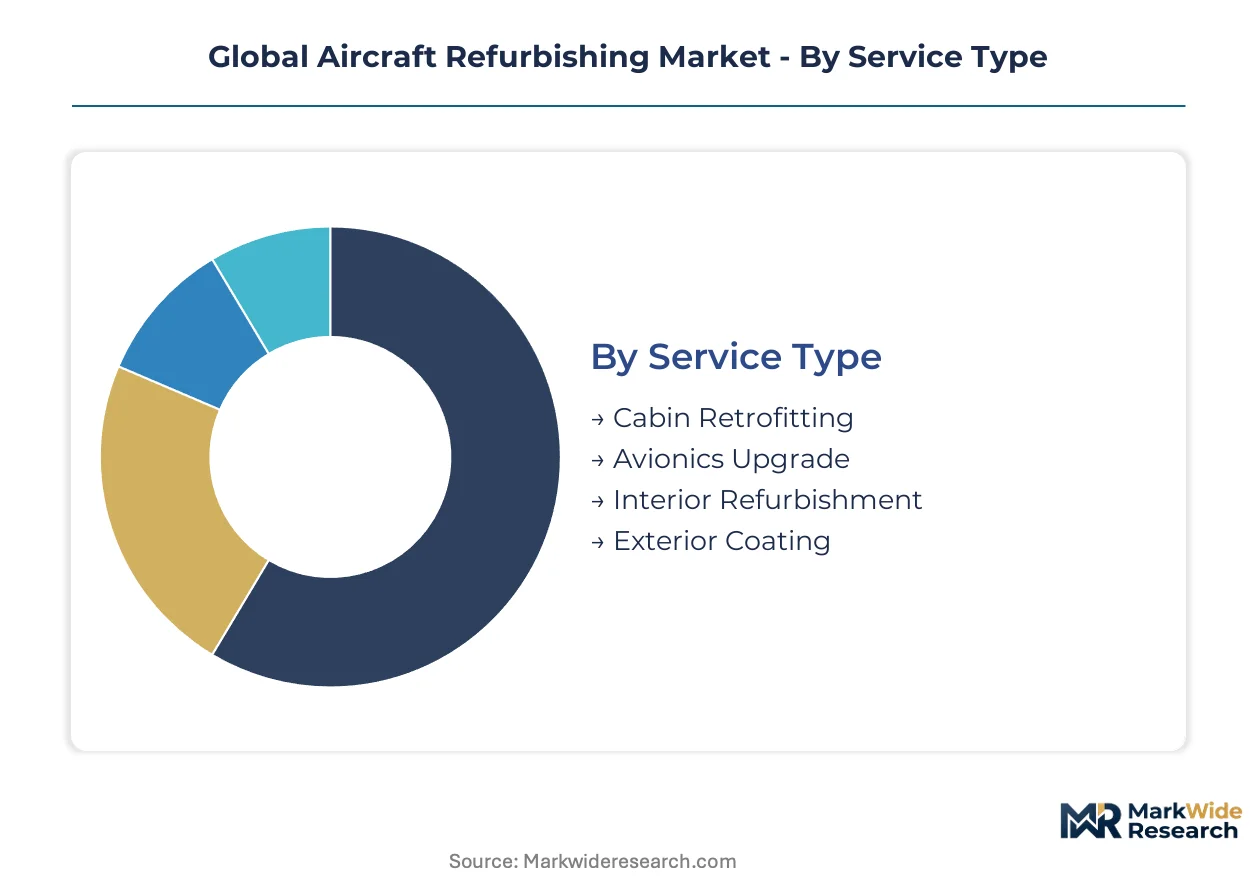
Refurbishment procurement patterns diverge sharply between regulatory compliance mandates and discretionary cabin investments. Airlines segment spending based on airworthiness deadlines versus revenue-per-passenger optimization.
Service Type:
FAA Airworthiness Directives and EASA Part-M requirements create mandatory demand tiers that override commercial preferences for cosmetic upgrades.
- Cabin Retrofitting:Comprehensive interior reconfiguration encompassing seat replacement, monument relocation, and floor reinforcement to accommodate densified layouts. Demand concentrates among US legacy carriers operating aging narrow-body fleets under FAA aging aircraft protocols, with spending prioritized on high-utilization domestic routes.
- Avionics Upgrade:Cockpit modernization integrating ADS-B Out transponders, GPS navigation suites, and flight management system replacements to satisfy NextGen and SESAR performance-based navigation mandates. European operators face the most compressed compliance timelines as EASA mandates approach.
- Interior Refurbishment:Aesthetic renewal including sidewall panel replacement, carpet installation, and overhead bin modification without structural alteration.
- Exterior Coating:Protective paint system application and corrosion-inhibiting treatments for aluminum-lithium skin panels.
Established volume favors Cabin Retrofitting; emerging adoption favors Avionics Upgrade.
Product Type:
Procurement cost tiers separate safety-critical systems from discretionary passenger experience investments.
- Passenger Seating:Lightweight composite seat frames with integrated in-seat power and personal device holders, certified to FAA TSO-C127 and EASA ETSO-C127 standards. US ultra-low-cost carriers drive demand for slimline configurations maximizing cabin density on Boeing 737NG and Airbus A320ceo platforms.
- In-Flight Entertainment:Seatback screen replacement and wireless streaming infrastructure installation. Narrow-body operators in India prioritize portable device streaming over embedded hardware to minimize weight and maintenance burden.
- Galley Equipment:Refrigeration unit replacement and trolley standardization for EU F-Gas Regulation refrigerant compliance.
- Lavatory Systems:Vacuum waste system modernization and touchless fixture installation.
- Lighting Systems:LED cabin illumination retrofitting and mood lighting controller integration.
Volume concentrates in Passenger Seating; margin expansion concentrates in In-Flight Entertainment.
Aircraft Type:
Fleet age distribution and utilization intensity determine refurbishment economics across platform categories.
- Narrow-Body Jets:Single-aisle airframes including Boeing 737 family and Airbus A320 family aircraft undergoing heavy maintenance interval extensions. Demand clusters in the United States and India where high-cycle operations accelerate structural fatigue and avionics obsolescence.
- Wide-Body Jets:Twin-aisle platforms including Boeing 777 and Airbus A330 families requiring comprehensive systems modernization. Cargo conversion demand sustains refurbishment activity for passenger-retiring wide-bodies approaching freighter modification.
- Regional Aircraft:Turboprop and regional jet platforms below 100 seats.
- Business Jets:Corporate and private aviation platforms with customized interior specifications.
Cycle volume dominates Narrow-Body Jets; per-aircraft spending peaks with Wide-Body Jets.
End User:
Customer type dictates procurement structure, contract duration, and technical specification authority.
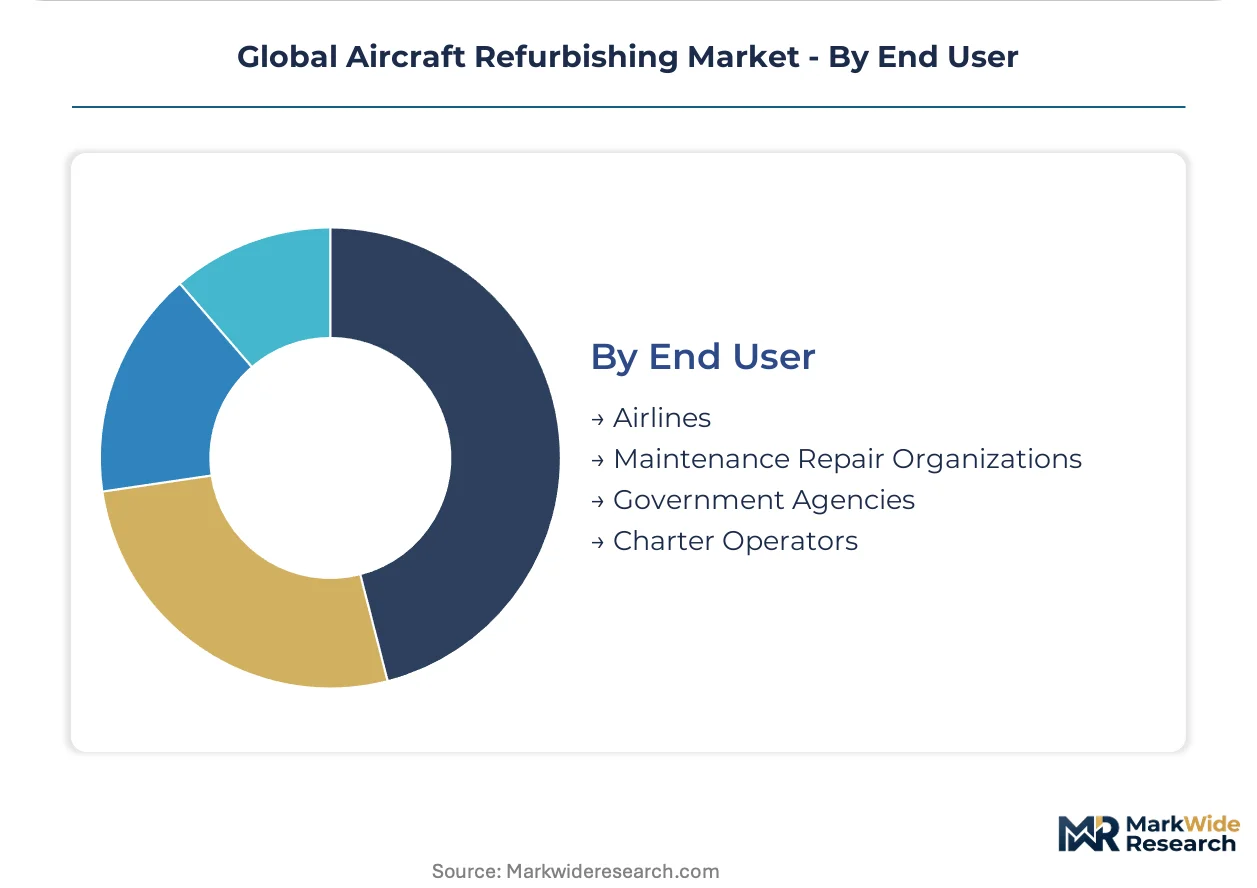
- Airlines:Commercial operators with direct refurbishment responsibility for owned and finance-leased fleets. US major carriers maintain the largest in-house engineering departments, while European and Asian operators rely more heavily on outsourced program management.
- Maintenance Repair Organizations:Third-party MRO providers including Lufthansa Technik, AAR Corporation, and ST Engineering executing refurbishment contracts on behalf of operator customers. These entities aggregate demand across multiple airline clients to sustain specialized production lines.
- Government Agencies:Military and state aviation operators with mission-specific modification requirements.
- Charter Operators:On-demand and fractional ownership fleet managers with irregular refurbishment cycles tied to lease transitions.
Contract value concentrates with Airlines; margin stability concentrates with Maintenance Repair Organizations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FAA anchors the largest refurbishment demand geography through aging aircraft directives that mandate structural inspection cycles across narrow-body and wide-body fleets operating beyond original design service objectives.
United States
Major carriers operate some of the world's oldest active fleets, driving systematic airframe refurbishment programs. The FAA's Airworthiness Directives on corrosion-critical zones trigger heavy maintenance visits at 20-year intervals. Oklahoma City and Miami anchor North American MRO capacity through dense networks of FAA-certified repair stations.
Germany
Lufthansa Technik sustains one of Europe's deepest pools of specialized airframe technicians at its Hamburg headquarters. The EU F-Gas Regulation compels galley and climate system retrofits during heavy maintenance visits as 2027 refrigerant restrictions approach. Hamburg's aerospace cluster concentrates composite panel replacement capabilities for aging Airbus A320ceo families.
India
Rapid domestic aviation growth generates demand for imported used-aircraft refurbishment to bypass new aircraft delivery backlogs. The Directorate General of Civil Aviation enforces continuing airworthiness requirements that align with EASA Part-M standards. Bangalore and Hyderabad host emerging MRO facilities targeting narrow-body avionics modernization for low-cost carriers.
Singapore
ST Engineering competes across Southeast Asia with integrated airframe and component capabilities. The Civil Aviation Authority of Singapore maintains stringent certification protocols that facilitate cross-border maintenance approvals. Seletar Aerospace Park concentrates wide-body cargo conversion activity as passenger-to-freighter modification demand surges.
United Arab Emirates
Emirates and Etihad operate young wide-body fleets but host third-party refurbishment for regional operators. The General Civil Aviation Authority harmonizes standards with EASA to attract European-registered aircraft for heavy maintenance. Dubai South's Al Maktoum International Airport corridor anchors Gulf MRO capacity for composite structural renewal programs.
Global Aircraft Refurbishing Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, creating a two-tier competitive structure. Full-service MRO providers bundle airframe, engine, and component capabilities under single contract umbrellas, while independent cabin integrators capture disaggregated interior refurbishment awards. Three archetypes dominate: legacy airline-captive MROs, independent commercial specialists, and business aviation-focused boutiques. Competitive moves concentrate on geographic expansion through greenfield hangar capacity and strategic partnerships to secure certified technician pipelines.
Within the integrated tier, Lufthansa Technik and AAR Corporation exemplify divergent geographic anchoring strategies—European versus North American—while ST Engineering occupies a position bridging Southeast Asian cost structures with Western certification standards. These three entities represent the scale-driven end of the market, aggregating demand across multiple airline clients to sustain specialized production lines for aging fleet segments.
| Leading Market Players |
|---|
| Lufthansa Technik |
| AAR Corporation |
| Gulfstream Aerospace Corporation |
| ST Engineering |
| Air France Industries KLM Engineering & Maintenance |
| SIA Engineering Company |
| Jet Aviation |
| SAFRAN |
| Hong Kong Aircraft Engineering Company |
| Others |
Cost & Logistics Intelligence
Hangar utilization rates above 85% at Hamburg and Oklahoma City anchor price floors for wide-body heavy maintenance, concentrating bargaining power with MRO providers that operate multi-bay facilities. This scale dynamic compresses margins for independent specialists while allowing integrated leaders to command project-based premiums on cabin retrofits.
Pricing Analysis
North American refurbishment quotes run 15-25% above Southeast Asian benchmarks before logistics adjustments, reflecting FAA certification overhead and technician wage differentials. Project-based contracting dominates, with price differentiation driven by EASA Part-M compliance tier and aftermarket warranty bundling. Cost compression in narrow-body avionics retrofits is intensifying because certified engineering labor pools cannot expand faster than mandate-driven demand. Ultra-low-cost carriers exhibit the highest price sensitivity, while flag carriers with aging owned fleets accept premium positioning for reduced aircraft downtime.
Supply Chain Analysis
Container availability constraints on Hamburg-Singapore lanes inflate inbound logistics costs for aerospace-grade titanium and carbon fiber prepreg, compressing refurbishment margins on European-registered wide-bodies. Supply concentrates in the United States, Germany, and Singapore for structural components; China and Japan dominate avionics module fabrication. The network rests on single-source vulnerability for FAA-certified wiring harness assemblies and corrosion-resistant aluminum-lithium sheet. Distribution runs through MRO facility direct procurement with long-term offtake agreements for high-volume seat and galley suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aircraft refurbishing market is approaching a platform-economics inflection as airlines unbundle interior procurement from airframe maintenance, creating interoperability standards that favor modular cabin integrators over full-service bundlers.
For Market Incumbents: Fortify technician pipelines through apprenticeship partnerships with FAA-certified A&P schools in Oklahoma and Florida, defending against emerging specialized cabin integrators that disaggregate traditional heavy maintenance contracts. Backward integration into 3D-printed interior components at Hamburg and Seletar facilities preserves margin on seat and monument replacement programs. For New Entrants and Emerging Players: Avionics upgrade capacity scarcity in India presents the most penetrable entry point, where DGCA-aligned certification requirements match EASA standards but local MRO capacity lags fleet expansion. Target narrow-body ADS-B Out compliance programs for low-cost carriers through partnerships with Bangalore-based engineering houses that bridge Western certification protocols. For Investors and Strategic Acquirers: Independent cabin specialists with EASA Part-21J design organization approvals represent the optimal acquisition archetype, capturing disaggregated procurement flows that airlines now separate from airframe contracts. Monitor FAA supplemental type certificate approval timelines as the inflection signal—compression below 90 days indicates regulatory capacity expansion that accelerates refurbishment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Technician Pipeline Partnerships | FAA-certified A&P apprenticeships at Oklahoma City repair stations secure labor for aging fleet mandates. |
| Modular Cabin Integration | EASA Part-21J design approvals enable independent specialists to capture disaggregated airline procurement. |
| Cargo Conversion Line Expansion | Seletar Aerospace Park wide-body P-to-F capacity addresses e-commerce-driven freighter demand. |
| EU F-Gas Compliance Retrofit | Hamburg climate system upgrades align with 2027 refrigerant phase-down deadlines. |
| NextGen Avionics STC Acceleration | FAA streamlined certification compresses ADS-B Out installation downtime for narrow-body operators. |
Research Approach
Desk research of FAA Airworthiness Directive databases, EASA Part-M continuing airworthiness filings, and MRO utilization reports preceded structured interviews with airline fleet engineering directors, MRO program managers, and avionics integration specialists. Primary fieldwork with heavy maintenance planners at Lufthansa Technik and AAR Corporation validated secondary projections against actual hangar throughput and technician allocation patterns. Bottom-up segment sizing triangulated against top-down fleet age projections from manufacturer delivery backlogs.
Variance decomposition across service type, aircraft platform, and geographic regulatory cluster shaped the analytical framework over the projection horizon. Modeled dimensions encompassed cabin retrofit intensity, avionics mandate compliance tier, and narrow-body versus wide-body utilization cycles. CAGRs derived from fleet age distribution curves and regulatory deadline clustering, with cross-validation against MRO capacity expansion announcements and technician graduation pipelines.
Underlying assumptions cover sustained new aircraft delivery constraints and stable FAA/EASA regulatory timelines, with deviation risk concentrated in titanium composite input volatility and supplemental type certificate approval delays. Recalibration cycles align with material shifts in aging aircraft directive issuance patterns and EU F-Gas phase-down enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Asia-Pacific Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Africa Aircraft Windshield Wiper and Washer System Market
Aircraft Maintenance and MRO Solutions
Aviation Test Equipment Market
Aircraft Maintenance and MRO Solutions
Aircraft Recycling Market
Aircraft Maintenance and MRO Solutions
Aircraft Weighing Scales Market
Aircraft Maintenance and MRO Solutions
Military Aircraft Maintenance, Repair and Overhaul Market
Aircraft Maintenance and MRO Solutions
Frame Alignment Systems Market
Aircraft Maintenance and MRO Solutions
Digital Aerospace MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Wheel Bead Breakers Market
Aircraft Maintenance and MRO Solutions
Cabin Reconfiguration and Retrofit MRO Services Market
Aircraft Maintenance and MRO Solutions
Aircraft Modernization Market
Aircraft Maintenance and MRO Solutions
Asia-Pacific Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Vacuum Cleaners Market
Aircraft Maintenance and MRO Solutions
GCC Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Nigeria Aircraft Maintenance Repair and Overhaul Market
Aircraft Maintenance and MRO Solutions
Aircraft Autoclave Market