
 Commercial Aircraft Landing Gear MRO Market | 2026-2036
Commercial Aircraft Landing Gear MRO Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Aircraft Landing Gear MRO Market Outlook
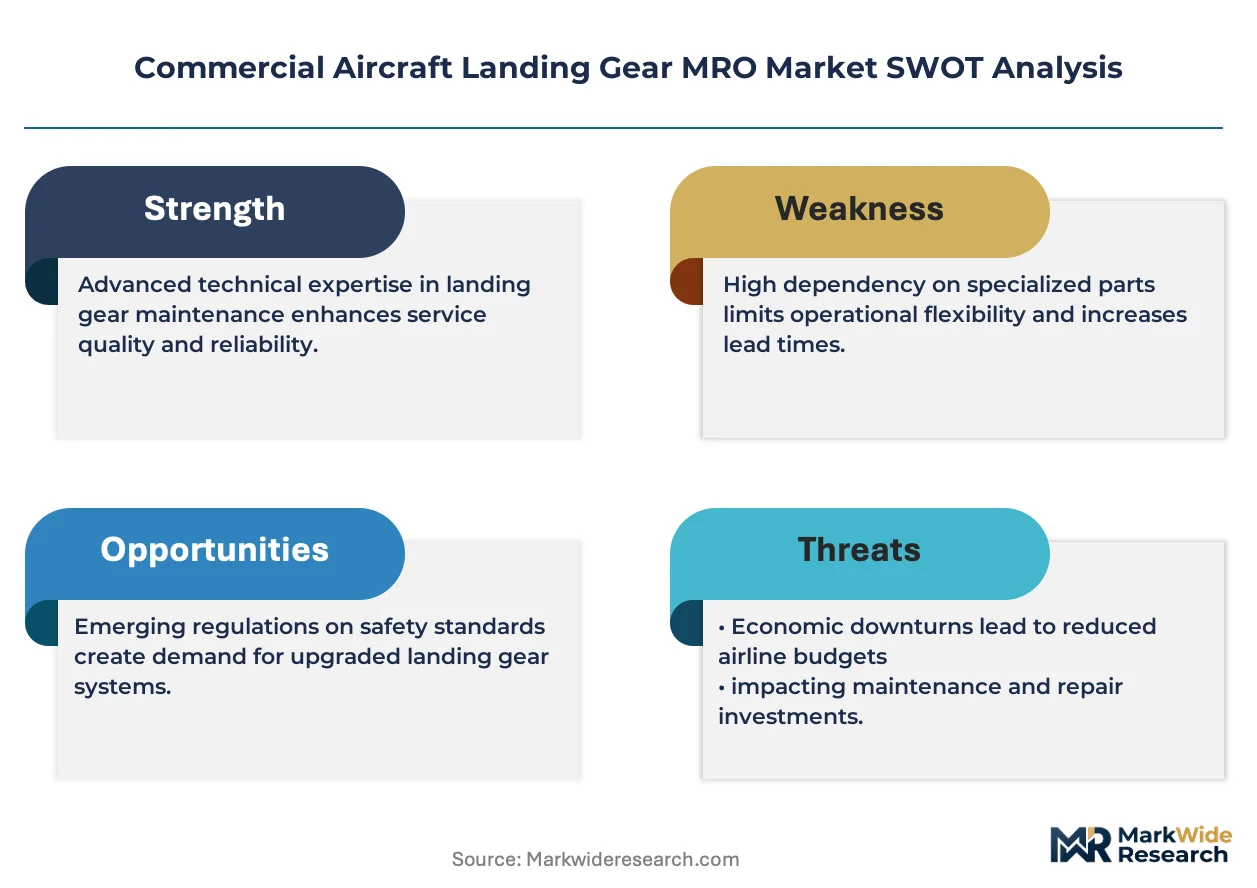
EU MDR and FAA aging-aircraft directives are broadening the cost-of-entry calculus for landing gear overhaul providers, forcing smaller shops to invest in non-destructive testing capabilities or exit the market. Safran SA leverages its integrated landing gear and braking portfolio to capture recurring overhaul streams from operators under long-term service agreements. Héroux-Devtek Inc. anchors its competitive position through specialized strut and actuator repair capabilities serving regional and business aviation platforms. AAR Corp. competes by operating distributed heavy-check facilities that co-locate landing gear overhaul with airframe maintenance to reduce aircraft downtime.
Commercial Aircraft Landing Gear MRO encompasses the inspection, disassembly, repair, reassembly, and testing of landing gear assemblies and subsystems to restore airworthiness after cyclic operational stress, typically requiring magnetic particle inspection of high-steel components and dimensional verification of oleo-pneumatic shock struts against OEM technical drawings. The primary purpose is to extend safe service life while ensuring compliance with manufacturer service bulletins and airworthiness directives. Overhaul services command the largest revenue share due to the labor-intensive teardown and rebuild cycles mandated by flight-hour intervals, while composite materials adoption in newer gear designs is shifting technician skill requirements and parts replacement economics. Wheel assemblies and brake systems represent concentrated margin pools because heat-intensive operations drive frequent wear-part consumption and proprietary OEM coating technologies limit independent repair options.
FAA airworthiness directives and EASA Part 145 oversight govern market access by dictating specialized tooling, technician certification, and parts traceability standards that favor incumbent providers with established quality management systems. The US national aviation regulator maintains stringent repair station authorization requirements that create geographic moats around domestic overhaul capacity. Stakeholders must monitor how OEMs tighten intellectual property controls on proprietary heat treatment processes and composite repair methodologies, as these restrictions could reshape independent MRO competitiveness and parts sourcing economics across the forecast horizon.
Market Dynamics
EASA's tightening Part 145 certification requirements and FAA aging-aircraft directives are elevating technical documentation burdens while compressing the viable supplier base for landing gear overhaul services.
Growth Catalysts
- Narrowbody fleet expansion:Low-cost carriers in Indonesia, Vietnam, and Thailand are extending maintenance contracts to third-party providers as domestic overhaul capacity strains against traffic recovery.
- Composite material penetration:Adoption of carbon-reinforced components in newer landing gear designs is creating specialized repair demand that commands premium technician rates.
- EU MDR traceability mandates:Documentation requirements for heat-treated steel components are driving operators toward certified MROs with established quality management systems.
Market Restraints
- Specialized tooling capex:Magnetic particle inspection rigs and dimensional verification benches for oleo-pneumatic struts require substantial upfront investment that smaller shops cannot absorb.
- OEM intellectual property controls:Proprietary heat treatment processes and composite repair methodologies limit independent repair options and concentrate margin pools with original equipment manufacturers.
- Technician certification scarcity:FAA repair station authorization and EASA Part 66 licensing create multi-year qualification pipelines that constrain labor supply expansion.
Strategic Opportunities
- Southeast Asia capacity gaps:Airport infrastructure expansion in Thailand and Vietnam is outpacing domestic heavy-check capabilities, creating entry points for foreign-certified providers.
- Long-term service agreement penetration:Power-by-the-hour contracts for brake and wheel assemblies offer recurring revenue streams that reduce customer churn.
- Co-location with airframe maintenance:Distributed heavy-check facilities that integrate landing gear overhaul with C-checks reduce aircraft downtime and capture bundled spend.
Industry Challenges
- NDT technician pipeline gaps:Magnetic particle and ultrasonic inspection certification programs produce insufficient graduates to match fleet growth and retirement attrition.
- Parts traceability system integration:Legacy paper-based documentation workflows resist digitization, delaying turnaround times and complicating regulatory audits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Aircraft Landing Gear MRO Market |
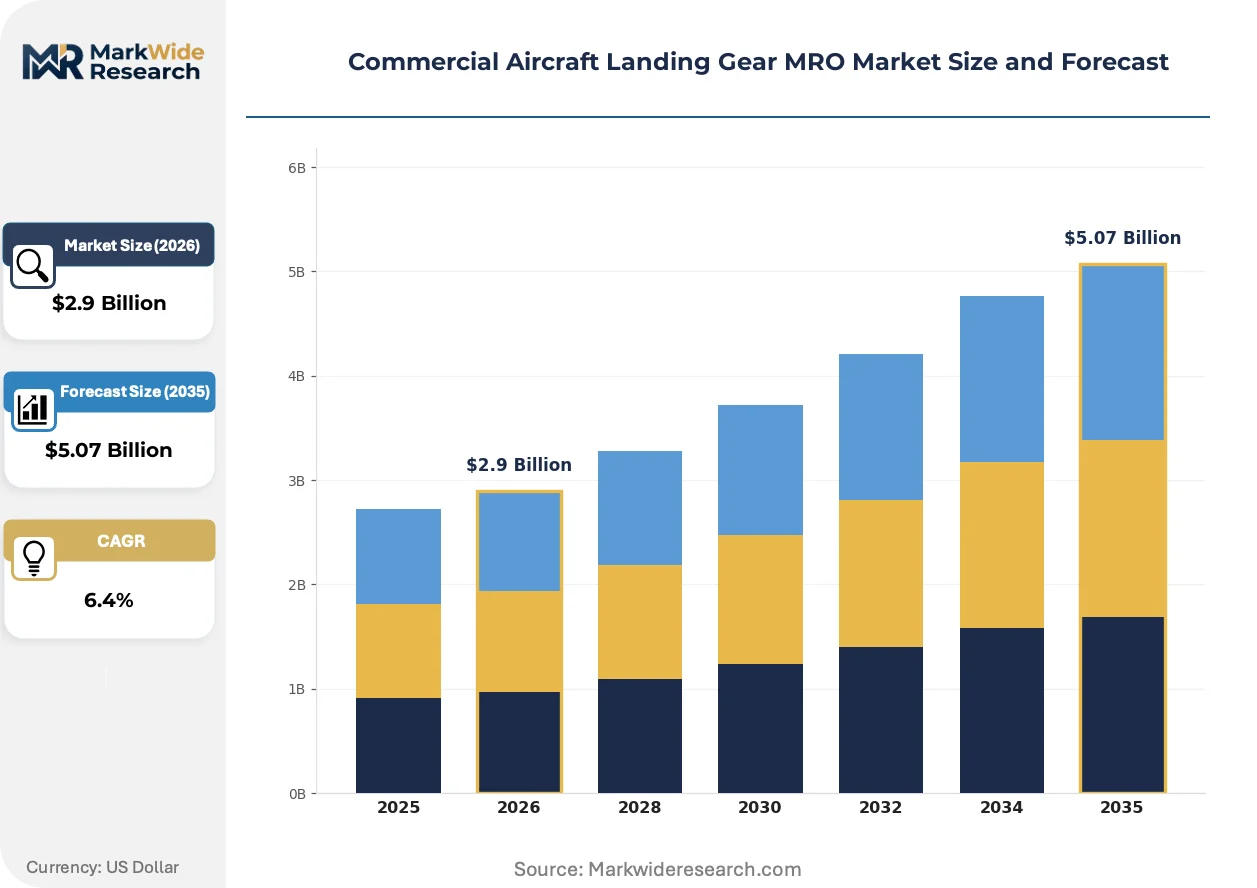
| Market Size in 2026 | $2.9 Billion |
| Market Size in 2035 | $5.07 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Overhaul, Repair, Inspection, Modification End User: Airlines, MRO Providers, OEMs, Military Technology: Hydraulic Systems, Electrical Systems, Pneumatic Systems, Composite Materials Component: Wheel Assemblies, Brake Systems, Struts, Trunnions |
| Companies Covered | Safran SA, Héroux-Devtek Inc., AAR Corp., Magellan Aerospace Corporation, Triumph Group Inc., CIRCOR International Inc., Liebherr-International Deutschland GmbH, Honeywell International Inc., Revima Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Aircraft Landing Gear MRO Market Strategic Shifts
Digital inspection technologies and predictive maintenance platforms are restructuring how operators schedule landing gear overhaul cycles and select service providers.
Electro-hydraulic actuator systems are electrifying legacy landing gear architectures by replacing centralized hydraulic distribution with localized electric power. Regional and business aviation operators are adopting these retrofits to simplify maintenance intervals and reduce fluid contamination risks. This transition is electrifying the competitive landscape for MROs, forcing shops to invest in electric motor testing capabilities or cede overhaul contracts to OEM-captive facilities.
REACH restrictions on hexavalent chromium coatings are compelling European MROs to transition brake component repair lines toward trivalent alternatives and plasma-sprayed ceramic matrices. The industrial consequence is elevated process validation costs and extended qualification timelines for independent shops. Wheel and brake specialists serving the European Union market are responding by consolidating heat treatment capabilities and pursuing OEM licensing agreements to maintain airworthiness certification.
Airlines are unbundling landing gear overhaul from bundled heavy-check contracts and awarding discrete work packages to niche strut and actuator specialists. This procurement fragmentation is disrupting traditional relationships between full-service MROs and legacy carriers. The shift is most visible in North America, where major operators now separately tender brake shop visits, oleo seal replacements, and structural component non-destructive testing to optimize unit economics and compress turnaround times.
Commercial Aircraft Landing Gear MRO Market Segmentation
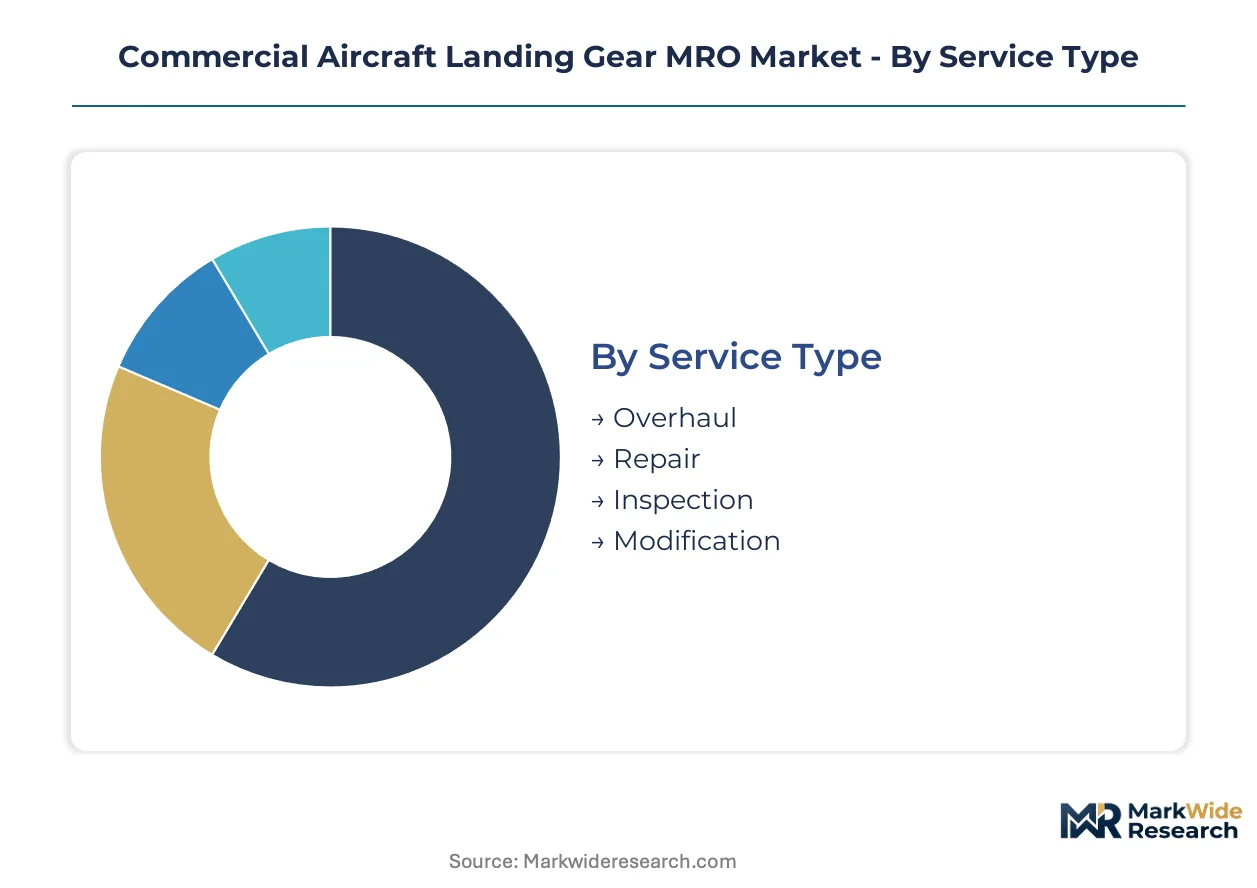
Landing gear MRO procurement patterns diverge sharply across service tiers and operator types. Technical complexity, regulatory certification depth, and fleet age profiles reshape how contracts bundle or fragment across the value chain.
Service Type:
Technical depth and labor intensity separate service tiers, with flight-hour intervals and airworthiness directive compliance driving contract structures.
- Overhaul:Complete disassembly, inspection, repair, and reassembly of landing gear assemblies to restore original performance specifications. Demand concentrates among low-cost carriers operating aging narrowbody fleets in Indonesia and Vietnam, where domestic capacity constraints push contracts toward third-party providers with EASA Part 145 or FAA repair station credentials.
- Repair:Targeted remediation of specific component failures or damage events without full teardown cycles. Airlines in Thailand favor discrete repair packages for brake and wheel assemblies to compress turnaround times during high-season operations.
- Inspection:Scheduled non-destructive testing and dimensional verification against OEM technical drawings. Magnetic particle and ultrasonic inspection protocols dominate, with technician certification scarcity limiting shop expansion.
- Modification:Retrofit installations addressing service bulletins, aging-aircraft directives, or operational upgrades. Electro-hydraulic actuator conversions for regional platforms represent emerging demand.
Mature deployment sits with Overhaul. Newer deployment is concentrated in Modification.
End User:
Procurement authority and technical integration requirements reshape competitive access across customer categories.
- Airlines:Direct contracting for heavy-check intervals and unbundled work packages. North American majors now separately tender brake shop visits, oleo seal replacements, and structural NDT to optimize unit economics.
- MRO Providers:Independent shops and airline-captive facilities competing on turnaround speed and certification breadth. Southeast Asian capacity gaps attract foreign-certified entrants.
- OEMs:Safran and Héroux-Devtek leverage integrated portfolios to capture recurring overhaul streams through long-term service agreements.
- Military:Defense operators with specialized airframe platforms requiring security-cleared facilities and proprietary tooling.
Volume leadership rests with Airlines. Margin expansion concentrates with MRO Providers.
Technology:
Actuation architecture and materials science are redefining technician skill requirements and capital investment thresholds.
- Hydraulic Systems:Centralized fluid distribution architectures in legacy narrowbody and widebody platforms. Mature installed base generates steady seal replacement and contamination remediation demand.
- Electrical Systems:Electro-hydraulic actuators replacing centralized hydraulics with localized electric power. Regional operators adopt these retrofits to simplify maintenance intervals, forcing shops to invest in motor testing capabilities or cede contracts to OEM-captive facilities.
- Pneumatic Systems:Oleo-pneumatic shock struts requiring dimensional verification benches and specialized recharging equipment.
- Composite Materials:Carbon-reinforced components in newer landing gear designs creating specialized repair demand that commands premium technician rates and OEM-licensed methodologies.
Installed base dominance belongs to Hydraulic Systems. Steepest expansion trajectory is concentrated in Electrical Systems.
Component:
Wear intensity and proprietary coating technologies determine margin pools and competitive moats across subsystems.
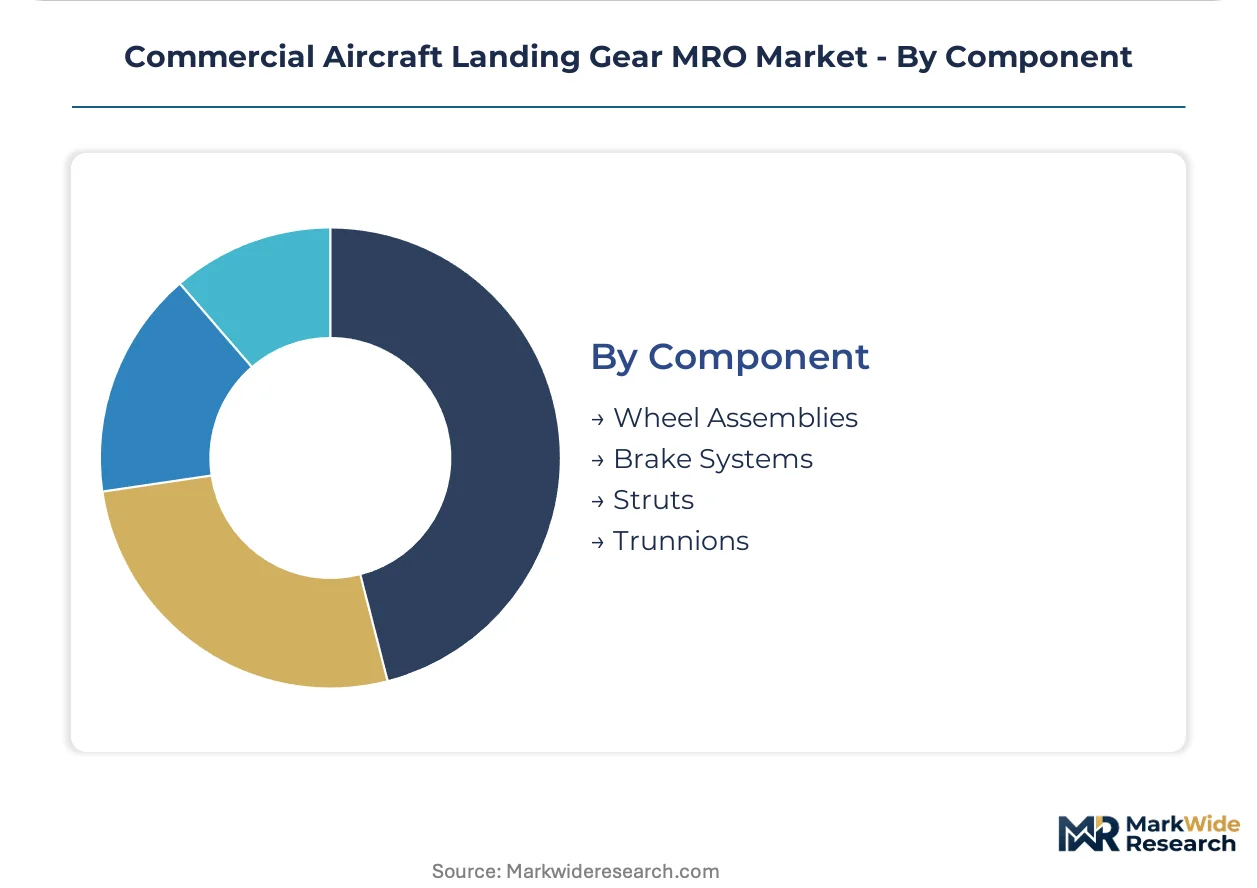
- Wheel Assemblies:Heat-intensive operations drive frequent wear-part consumption. REACH restrictions on hexavalent chromium coatings compel European shops to transition repair lines toward trivalent alternatives and plasma-sprayed ceramic matrices.
- Brake Systems:Proprietary OEM heat treatment processes and coating technologies limit independent repair options, concentrating margin pools with original equipment manufacturers. Power-by-the-hour contracts offer recurring revenue streams that reduce customer churn.
- Struts:Oleo-pneumatic shock absorbers requiring dimensional verification and seal replacement cycles. Specialized strut repair capabilities anchor competitive positioning for regional and business aviation specialists.
- Trunnions:Structural attachment points subject to fatigue cracking and corrosion, demanding magnetic particle inspection of high-steel components.
Revenue concentration sits with Wheel Assemblies. Technical differentiation is expanding fastest in Brake Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seletar Aerospace Park in Singapore concentrates third-party landing gear overhaul capacity for Southeast Asian operators. FAA repair station certifications and EASA Part 145 credentials cluster around this zone, drawing maintenance contracts from Indonesian and Vietnamese low-cost carriers.
United States
FAA aging-aircraft directives expand non-destructive testing mandates for high-cycle narrowbody fleets. Repair station authorization requirements create geographic moats around domestic overhaul capacity. Oklahoma City hosts concentrated heavy-check facilities that co-locate landing gear services with airframe maintenance.
Indonesia
Domestic MRO capacity strains against post-pandemic traffic recovery at Jakarta and Denpasar hubs. The country's civil aviation regulator tightens oversight of foreign-certified repair stations. Batam's free trade zone attracts Singapore-based providers seeking labor cost arbitrage for wheel and brake shop work.
Vietnam
Airport infrastructure expansion at Da Nang and Phu Quoc outpaces certified landing gear overhaul capabilities. Operators extend maintenance contracts to Thai and Malaysian third-party providers. Ho Chi Minh City concentrates the domestic MRO base, though Part 145-equivalent certification remains limited.
Thailand
High-season operational intensity drives discrete brake and wheel repair demand from Bangkok-based carriers. The Civil Aviation Authority of Thailand aligns certification standards with EASA frameworks. U-Tapao aviation city projects target foreign MRO investment to capture Indonesian and Vietnamese overflow contracts.
Germany
REACH restrictions on hexavalent chromium coatings compel brake component repair line transitions toward trivalent alternatives. The country's national aviation regulator enforces stringent traceability documentation for heat-treated steel components. Hamburg and Munich anchor OEM-captive overhaul capacity serving European flag carriers.
Commercial Aircraft Landing Gear MRO Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists for landing gear overhaul contracts across commercial aviation. Market structure tilts toward tiered concentration, with integrated OEM-captive facilities commanding premium-tier pricing and independent shops competing on turnaround velocity. Three archetypes dominate: aerospace conglomerates with integrated landing gear portfolios, specialized strut and actuator repair shops, and distributed heavy-check operators bundling airframe and gear services. Dominant competitive moves include long-term service agreement penetration and co-location strategies that reduce aircraft downtime.
Among diversified aerospace conglomerates, Safran SA and Honeywell International Inc. occupy positions anchored by integrated braking and landing gear portfolios. Héroux-Devtek Inc. exemplifies the specialist archetype, with company nomenclature indicating Canadian origin and focused repair capabilities. AAR Corp. represents the distributed service model, operating heavy-check facilities that bundle multiple maintenance disciplines. These three entities illustrate how competitive positioning fragments across integration depth, geographic reach, and technical specialization.
| Leading Market Players |
|---|
| Safran SA |
| Héroux-Devtek Inc. |
| AAR Corp. |
| Magellan Aerospace Corporation |
| Triumph Group Inc. |
| CIRCOR International Inc. |
| Liebherr-International Deutschland GmbH |
| Honeywell International Inc. |
| Revima Group |
| Others |
Value Chain & Pricing Dynamics
EASA Part 145 certification mandates for heat-treated steel traceability are compressing the supplier base toward accredited MROs, forcing independent shops to absorb specialized tooling costs or exit and allowing certified incumbents to capture pricing power on overhaul contracts.
Pricing Analysis
Lead-time compression commands premium positioning in landing gear MRO, with operators paying above-market rates for turnaround guarantees under 21 days while spot inventory of certified components trades at discounts. Three-tier pricing structure across premium, standard, and economy levels segments by certification depth and OEM authorization status. Pricing pressure stems from low-cost carrier procurement consolidation in Southeast Asia. Narrowbody operators exhibit highest price sensitivity, while business aviation fleets prioritize traceability documentation over unit cost.
Supply Chain Analysis
Freight costs for oversized landing gear assemblies constrain geographic sourcing radius, with shops in Singapore, Germany, and the United States anchoring regional overhaul capacity. Raw material flows draw from specialty steel mills in Austria, heat treatment chemical suppliers in Belgium, and aerospace-grade seal manufacturers in the United States. Single-source vulnerability concentrates in proprietary OEM coating technologies for brake components. Distribution runs through airline procurement departments, heavy-check facilities, and long-term service agreement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where EASA Part 145 and FAA repair station authorization create regulatory moats that reward incumbents with established quality management systems and capital reserves.
For Market Incumbents: Deploy long-term service agreement penetration to lock in recurring overhaul streams from narrowbody operators in Indonesia and Vietnam. Deepen backward integration into proprietary heat treatment capabilities to defend margin position against OEM-captive facilities expanding composite repair offerings. Consolidate regional strut and actuator specialists to capture unbundled procurement fragmentation among North American majors. For New Entrants and Emerging Players: Digital inspection platforms offering predictive maintenance analytics represent the most penetrable wedge for foreign-certified providers targeting Southeast Asian capacity gaps. Target discrete brake and wheel repair packages in Thailand's high-season operational windows where turnaround velocity trumps certification breadth. Pursue OEM licensing agreements for trivalent chromium coating transitions to bypass REACH compliance barriers in European markets. For Investors and Strategic Acquirers: The window for entry favors EASA Part 145-certified specialists with established non-destructive testing pipelines and technician training infrastructure. Acquisition targets should demonstrate recurring revenue concentration under power-by-the-hour contracts and geographic positioning near Indonesian or Vietnamese traffic hubs. Monitor FAA aging-aircraft directive expansion as the inflection signal for NDT capacity scarcity premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Service Agreement Expansion | Power-by-the-hour contracts with Indonesian low-cost carriers lock in recurring overhaul revenue streams. |
| Specialized NDT Capability Investment | Magnetic particle and ultrasonic inspection certification addresses technician pipeline gaps constraining shop expansion. |
| Co-location with Airframe Maintenance | Distributed heavy-check facilities in Oklahoma City reduce aircraft downtime and capture bundled spend from North American operators. |
| OEM Licensing for Coating Transitions | Trivalent chromium and plasma-sprayed ceramic qualifications maintain European market access under REACH restrictions. |
| Electro-hydraulic Retrofit Capability | Electric motor testing infrastructure captures regional platform modification demand displacing legacy hydraulic architectures. |
Study Parameters
Document review covered FAA airworthiness directives, EASA Part 145 certification databases, and airline maintenance contract filings, complemented by interviews with MRO operations directors, airline fleet managers, and OEM aftermarket strategists. Secondary validation drew from repair station authorization records, customs trade data for aerospace components, and SEC filings from diversified aerospace conglomerates. Bottom-up technician pipeline modeling and top-down fleet projection triangulation anchored market sizing.
Market value and volume trajectories across the projection horizon reflect segmented modeling by service type, end user category, and actuation technology architecture. CAGRs derive from flight-hour interval analysis, fleet age distribution curves, and regulatory mandate implementation timelines. Forecast inputs incorporate narrowbody delivery schedules to Southeast Asian operators and composite material penetration rates in new landing gear designs.
Several conditions sit outside the modeled scope, including unforeseen regulatory harmonization between FAA and EASA frameworks, abrupt commodity price volatility in specialty steel alloys, and pandemic-scale demand disruptions. Forecasts reflect assumptions about technician certification completion rates and OEM intellectual property licensing willingness. Stakeholders should weight assumptions against their own operating context and regional regulatory exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Aircraft Landing Gear Repair and Overhaul Market
Aircraft Maintenance and MRO Solutions
Cloud MRO Software Market
Aircraft Maintenance and MRO Solutions
Helicopter MRO Market
Aircraft Maintenance and MRO Solutions
Digital MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Autoclave Market
Aircraft Maintenance and MRO Solutions
Business Jet Mro Market
Aircraft Maintenance and MRO Solutions
United States Airframe MRO Market
Aircraft Maintenance and MRO Solutions
Middle-East and Africa Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
On-Premises MRO Software Market
Aircraft Maintenance and MRO Solutions
Aircraft Weight Scale Market
Aircraft Maintenance and MRO Solutions
Asia-Pacific Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Aviation Test Equipment Market
Aircraft Maintenance and MRO Solutions
Aircraft Wheel Bead Breakers Market
Aircraft Maintenance and MRO Solutions
US Aviation MRO Software Market
Aircraft Maintenance and MRO Solutions
Colombia Commercial Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Weighing Scales Market