
 Gas Turbine Air Filtration Market | 2026-2036
Gas Turbine Air Filtration Market Size, Share, and Industry Trends Forecast 2026-2036
Gas Turbine Air Filtration Market Analysis
Multi-source procurement for filtration media and cartridge assemblies is broadening across the gas turbine supply chain. Camfil leverages its Nordic manufacturing footprint to sustain long-term contracts with European power producers. Parker-Hannifin Corporation anchors its position through integrated hydraulic and filtration platforms that reduce operator procurement complexity. Donaldson Company differentiates via synthetic media R&D programs targeting high-humidity coastal installations.
Gas turbine air filtration encompasses inlet systems, static and self-cleaning filter houses, and final-stage barrier elements engineered to remove particulates, moisture, and corrosive aerosols upstream of compressor sections. These systems typically achieve filtration efficiencies from MERV 8 pre-filtration through EPA-class final stages, with pressure-drop budgets constrained to 1.5–3.0 inches of water column to preserve turbine output and heat rate. Pre-filter and synthetic media segments dominate current volume owing to shorter replacement intervals and lower capital barriers, while coalescing filter technology leads growth as operators prioritize salt and moisture removal for coastal and offshore deployments.
EPA ambient air quality standards and OSHA workplace exposure limits shape filtration specification thresholds for US-based power and oil & gas operators. ISO 29461-1 turbine inlet filtration testing protocols, alongside evolving EU F-Gas Regulation compliance pathways for leak detection, are raising technical bars for market entry. Stakeholders must monitor regulatory divergence between EPA particulate mandates and emerging carbon-border adjustment mechanisms that could alter filter material sourcing economics.
Market Dynamics
Combined-cycle operators face mounting pressure to reconcile EPA emissions mandates with compressor fouling costs, forcing filtration specification upgrades that compress replacement cycles and redirect capital toward high-efficiency inlet architectures.
Growth Catalysts
- EPA Ambient Air Quality Standards:Tightening particulate thresholds for power generation facilities are compelling operators to deploy EPA-class final-stage barrier elements, accelerating filter upgrade timelines across US gas-fired fleets.
- Offshore Wind-to-Hydrogen Clusters:Coastal electrolyzer installations require turbine-driven compression with salt-resistant inlet systems, opening dedicated procurement channels for coalescing filter technology.
- Synthetic Media Formulation Advances:Next-generation pleated synthetics achieving sub-micron retention at reduced pressure drop are displacing glass fiber in humid environments, expanding addressable applications for filter OEMs.
Market Restraints
- Specialized Polymer Feedstock Concentration:High-performance membrane polymers for coalescing stages source predominantly from German and Japanese chemical producers, exposing filter manufacturers to input cost volatility and allocation risk.
- ISO 29461-1 Certification Burden:Turbine inlet filtration testing protocols demand capital-intensive wind tunnel validation that extends product development timelines, particularly constraining mid-tier suppliers without captive testing infrastructure.
- Electrostatic Precipitator Retrofit Competition:Aging coal plants converting to gas firing sometimes retain existing particulate control systems rather than installing dedicated turbine inlet filtration, capping penetration in certain brownfield segments.
Strategic Opportunities
- India National Clean Air Programme:Urban air quality mandates for industrial clusters are creating first-time demand for high-efficiency inlet systems among captive power users in Gujarat and Maharashtra industrial corridors.
- Predictive Maintenance Integration:Differential pressure sensors and IoT-enabled filter monitoring are converging with cloud-based asset management platforms, enabling subscription-based filter lifecycle services that displace transactional cartridge sales.
- Green Hydrogen Production Hubs:Electrolyzer-integrated turbine compressor trains in Saudi Arabia and Australia require specialized filtration for desert dust and marine aerosol environments, opening premium product segments.
Industry Challenges
- Aerodynamic Testing Talent Scarcity:Filter houses engineered for sub-3.0 inch water column pressure drop budgets require specialized computational fluid dynamics expertise that concentrates among aerospace-trained engineers, constraining product development velocity.
- Legacy Control System Interoperability:Self-cleaning pulse-jet filter houses must integrate with existing turbine control architectures from multiple OEMs, complicating commissioning and extending field validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Turbine Air Filtration Market |
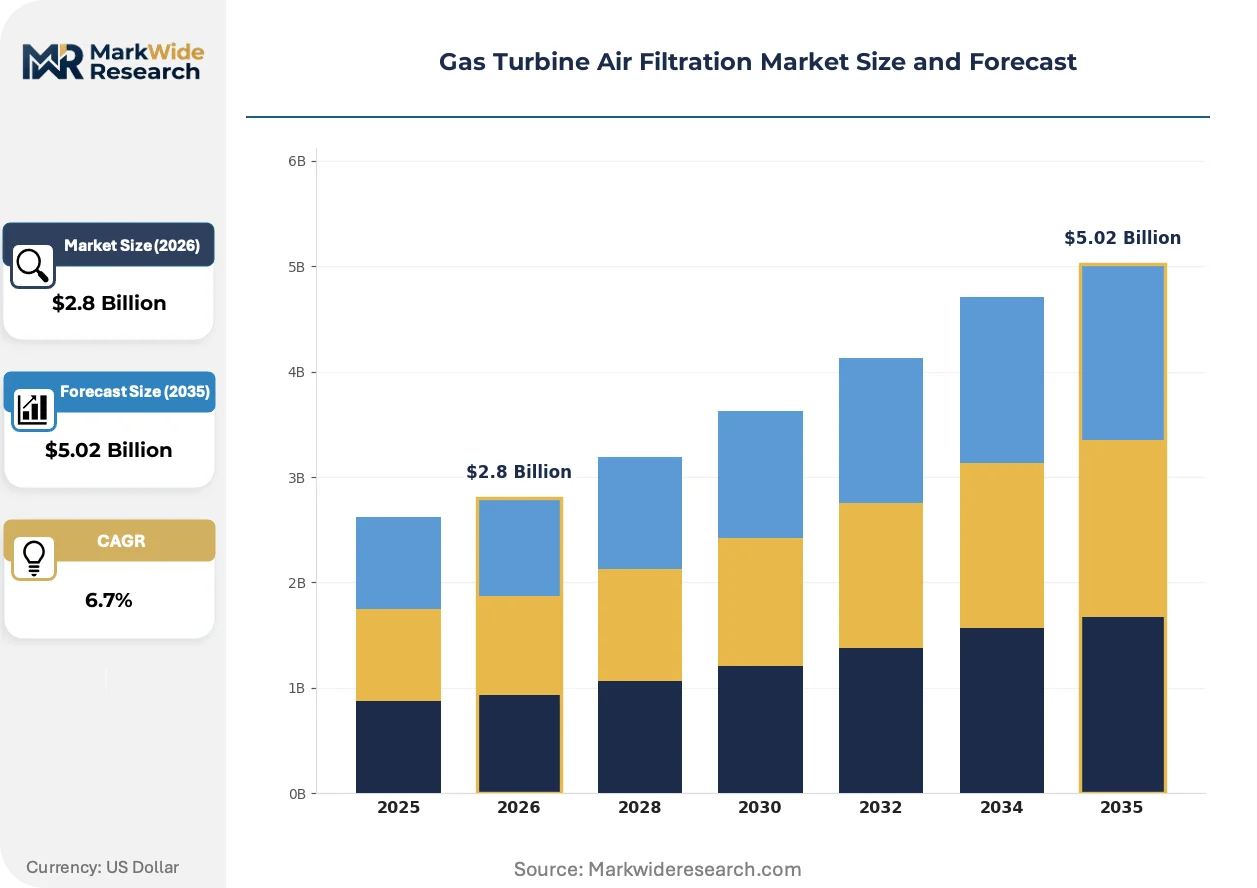
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Filter Type: HEPA, Pre-filter, Oil Mist, Absorbent End User: Power Generation, Marine, Oil & Gas, Aviation Application: Industrial Turbines, Mobile Turbines, Stationary Turbines, Combined Cycle Technology: Coalescing Filters, Synthetic Media, Electrostatic Filters, Activated Carbon |
| Companies Covered | Camfil, Parker-Hannifin Corporation, Donaldson Company, Koch Filter, General Electric Company, Shinwa Corporation, MANN+HUMMEL, Nordic Air Filtration, Graver Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Turbine Air Filtration Market Emerging Trajectories
Active filtration architectures are displacing static systems as operators prioritize compressor availability over capital minimization, reshaping R&D allocation and aftermarket service structures across the supply chain.
Nanofiber surface-loading media is converging with traditional depth-loading substrates to create hybrid filtration structures that capture sub-micron particulates without the pressure-drop penalty of pure nanofiber layers. US independent power producers operating combined-cycle assets in the Permian Basin are piloting these configurations to manage dust loading from oilfield activity. This convergence is compressing the performance gap between economy and premium filter tiers, forcing incumbent suppliers to accelerate material differentiation programs.
EU F-Gas Regulation compliance pathways for leak detection systems are extending to turbine auxiliary equipment, including filter house integrity monitoring. The regulation's phased refrigerant phase-down is compelling operators to scrutinize all potential fugitive emission sources, elevating filtration system sealing specifications. German and Dutch power utilities are leading specification upgrades, with procurement committees now requiring third-party validated leak-tightness documentation for inlet system contracts.
Long-term service agreements are displacing spot procurement for filter cartridge replacements among US merchant power generators facing dispatch volatility. Under these arrangements, filtration OEMs assume inventory risk and guarantee availability, capturing aftermarket revenue streams previously fragmented across distributors. The Texas and California ISO markets exhibit the strongest concentration of this contracting shift, where rapid cycling operations accelerate filter consumption unpredictably.
Gas Turbine Air Filtration Market Segmentation
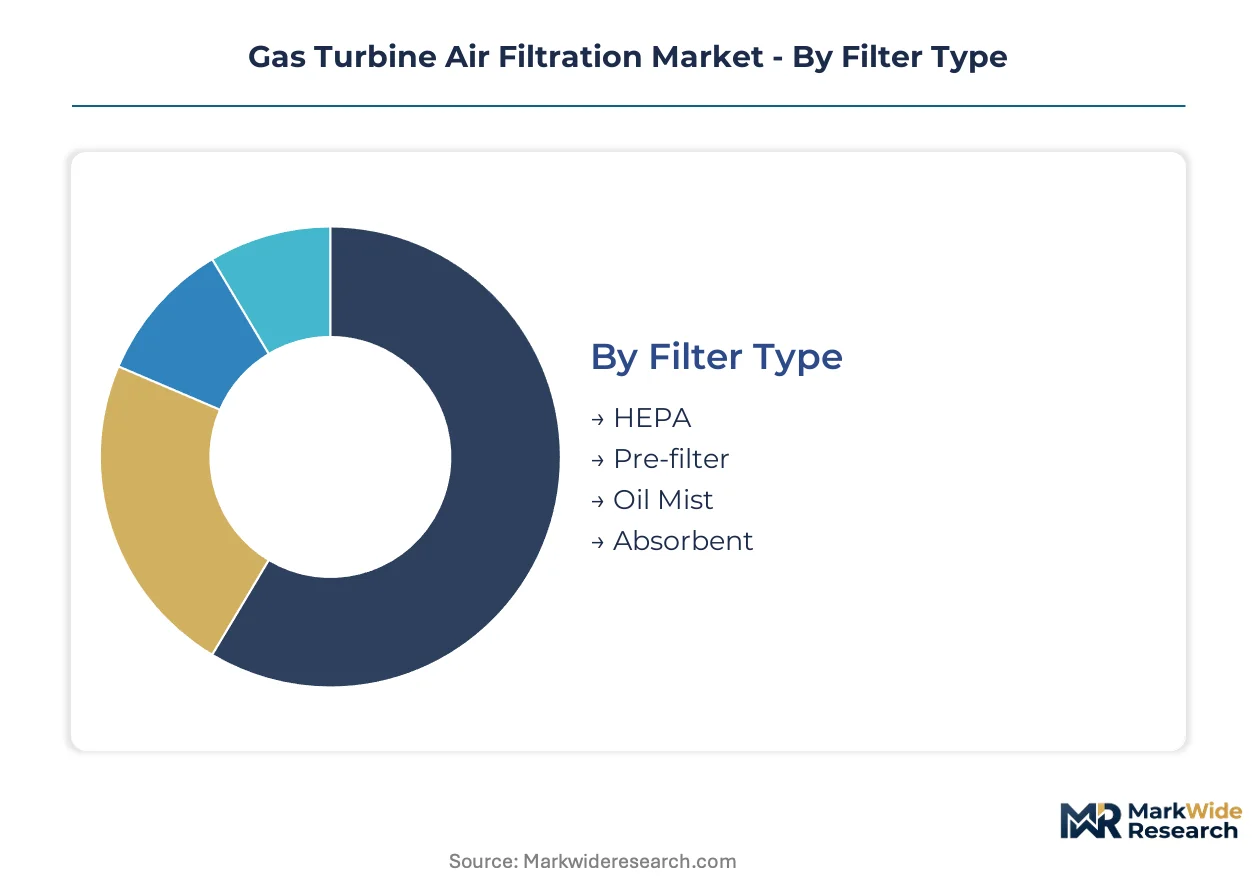
Segmentation in gas turbine air filtration reveals distinct procurement patterns tied to operating environments and replacement cycles. Filter specifications diverge sharply between coastal salt-laden installations and desert dust conditions, while end-user priorities range from compressor availability in power generation to space constraints in marine applications.
Filter Type:
Upgrade cycles for filter media track directly to pressure-drop thresholds and particulate loading rates in specific operating environments.
- Pre-filter:Pleated synthetic and glass fiber configurations capture coarse particulates upstream of final-stage elements. US combined-cycle operators in the Permian Basin are accelerating replacement frequencies to manage oilfield dust loading and protect downstream HEPA stages.
- HEPA:EPA-class barrier elements achieve sub-micron retention efficiencies required for compressor protection in high-particulate environments. Demand concentrates among utilities facing tightening EPA ambient air quality mandates, particularly for aging gas-fired capacity in Texas and California ISO markets.
- Oil Mist:Coalescing configurations remove lubricant aerosols from turbine inlet air in industrial proximity settings.
- Absorbent:Activated carbon and chemically impregnated media target corrosive gas removal in petrochemical cluster environments.
Pre-filter sits at the top of the volume ranking, with HEPA climbing the fastest as operators prioritize compressor protection over capital minimization.
End User:
Customer procurement sophistication varies by sector maturity, with power generation leading specification complexity and marine trailing on standardization.
- Power Generation:Combined-cycle and simple-cycle operators deploy multi-stage inlet architectures with differential pressure monitoring and automated pulse-cleaning systems. Merchant generators in Texas and California are shifting toward long-term service agreements that transfer inventory risk to filtration OEMs.
- Oil & Gas:Upstream compression and LNG liquefaction trains require salt-resistant configurations for coastal installations and dust-tolerant systems for desert production sites. Saudi Arabia and Australian green hydrogen hubs are opening premium procurement channels for specialized desert-marine hybrid specifications.
- Marine:Naval and commercial vessel gas turbines face severe space constraints and salt aerosol exposure, driving compact coalescing system demand.
- Aviation:Auxiliary power units and ground-based turbine test facilities require lightweight, high-flow configurations with rapid-change capabilities.
Power Generation commands the largest installed base, while Oil & Gas is gaining share fastest on hydrogen economy infrastructure investments.
Application:
Capital intensity and operating duty cycles shape filter architecture selection across turbine deployment modes.
- Combined Cycle:Heat recovery steam generator integration creates extended operating runs that accelerate filter loading and compress replacement intervals. US utilities are upgrading from static to self-cleaning inlet houses to maintain output during high-ambient-temperature periods.
- Industrial Turbines:Cogeneration and mechanical drive applications in petrochemical and paper mill settings face variable particulate and chemical exposure profiles. German and Dutch power utilities are specifying enhanced sealing integrity under EU F-Gas Regulation compliance pathways.
- Stationary Turbines:Peaking and backup power installations experience intermittent duty cycles that complicate filter moisture management and biological growth control.
- Mobile Turbines:Drilling rig and emergency power deployments prioritize rapid deployment and field-serviceable cartridge configurations.
Combined Cycle dominates capital deployment, with Industrial Turbines expanding most quickly on process industry decarbonization investments.
Technology:
Material science advances are redrawing performance boundaries between established and emerging filtration mechanisms.
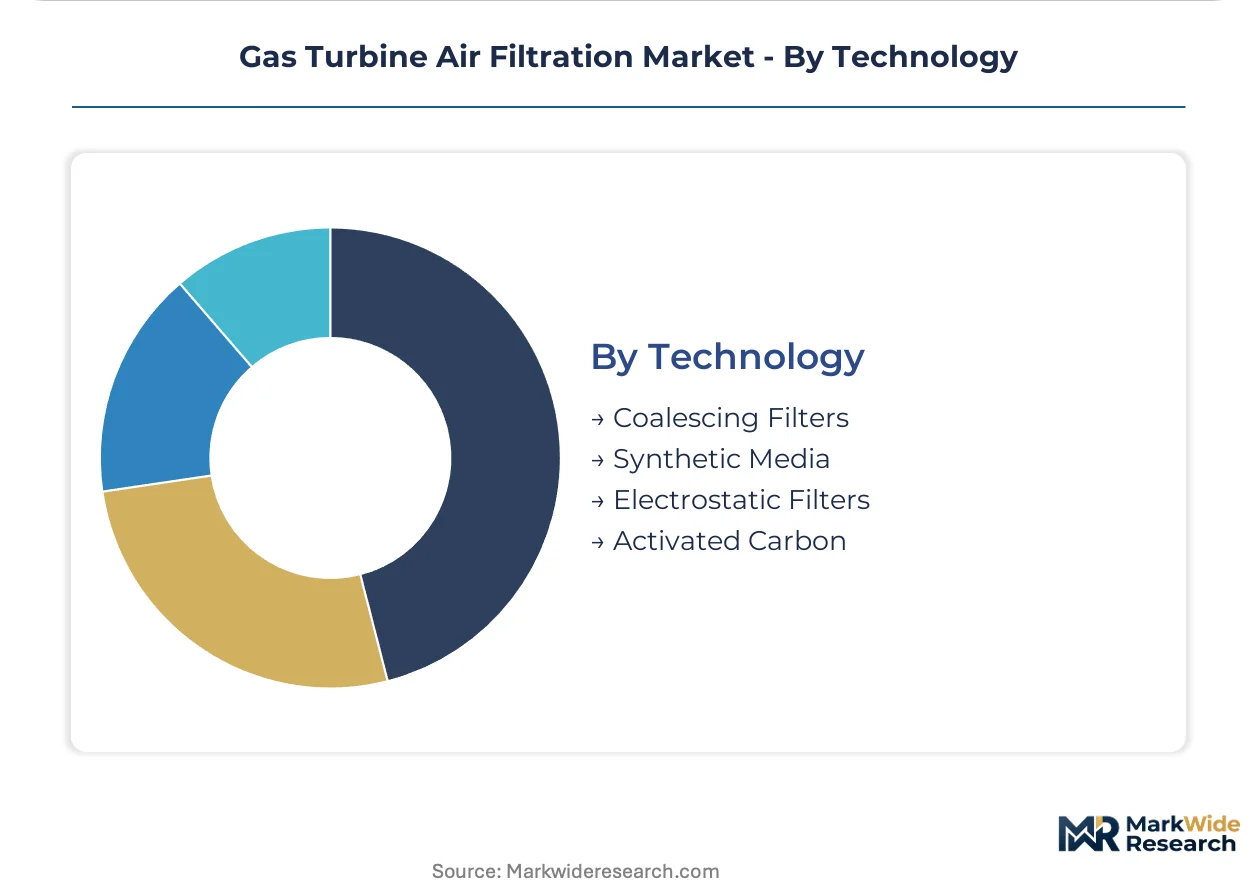
- Synthetic Media:Next-generation pleated synthetics achieve sub-micron retention at pressure drops below comparable glass fiber configurations. Humid coastal environments in the US Gulf Coast and Southeast Asia are displacing traditional depth-loading substrates with these formulations.
- Coalescing Filters:Multi-stage fiber matrix designs capture and drain salt and moisture aerosols before compressor entry. Offshore wind-to-hydrogen clusters in European North Sea developments are creating dedicated procurement channels for marine-grade coalescing specifications.
- Electrostatic Filters:Ionization-assisted particulate capture offers reduced pressure drop for coarse loading applications with accessible cleaning infrastructure.
- Activated Carbon:Chemisorptive media remove acidic gases and hydrocarbon vapors in industrial cluster and airport proximity installations.
Synthetic Media holds the largest volume position, with Coalescing Filters on the steepest expansion trajectory as coastal and offshore deployments multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Permian Basin's oilfield dust loading is accelerating filter replacement cycles among Texas combined-cycle operators. Coastal electrolyzer clusters in European North Sea developments are opening dedicated procurement channels for marine-grade coalescing specifications. Desert-marine hybrid filtration demand is concentrating in Saudi Arabia and Australian green hydrogen hubs.
United States
Merchant generators in Texas and California ISO markets are shifting toward long-term service agreements that transfer inventory risk to filtration OEMs. EPA ambient air quality standards are tightening particulate thresholds for aging gas-fired capacity. The Permian Basin's oilfield activity is driving accelerated pre-filter replacement frequencies to protect downstream HEPA stages.
Germany
German power utilities are leading specification upgrades under EU F-Gas Regulation compliance pathways for leak-tightness documentation. The country's national industrial clusters are prioritizing enhanced sealing integrity for inlet system contracts. Industrial turbine deployments in the Rhine-Ruhr region are specifying chemically impregnated media for petrochemical proximity protection.
Saudi Arabia
Green hydrogen production hubs in the Kingdom are requiring specialized filtration for desert dust and marine aerosol environments. The national clean energy program is driving premium procurement for electrolyzer-integrated turbine compressor trains. NEOM and Eastern Province industrial zones are anchoring demand for hybrid desert-marine specifications.
India
The National Clean Air Programme is creating first-time demand for high-efficiency inlet systems among captive power users. BIS standards are evolving to align with ISO turbine inlet filtration protocols. Gujarat and Maharashtra industrial corridors are specifying multi-stage inlet architectures for combined-cycle assets in urban air quality mandate zones.
Australia
Desert dust conditions in Western Australia and marine aerosol exposure on eastern coasts are driving hybrid filtration specifications. The country's hydrogen export hub investments are requiring salt-resistant configurations for coastal electrolyzer installations. Queensland and New South Wales power utilities are upgrading from static to self-cleaning inlet houses.
Gas Turbine Air Filtration Market Vendor Landscape
Global majors compete with regional champions across integrated hydraulic-filtration platforms and synthetic media specialization. The vendor base concentrates among diversified industrial conglomerates with captive aerospace filtration expertise and mid-tier specialists with coastal environment focus. Three archetypes dominate: integrated platform providers, synthetic media specialists, and regional service contractors. Competitive moves center on long-term service agreement expansion and predictive maintenance platform integration.
Within the integrated platform tier, Parker-Hannifin Corporation exemplifies the hydraulic-filtration convergence archetype. Donaldson Company occupies a position among synthetic media specialists with humidity-focused R&D positioning. Camfil represents the regional manufacturing footprint archetype with Nordic-based production anchoring European utility contracts.
| Leading Market Players |
|---|
| Camfil |
| Parker-Hannifin Corporation |
| Donaldson Company |
| Koch Filter |
| General Electric Company |
| Shinwa Corporation |
| MANN+HUMMEL |
| Nordic Air Filtration |
| Graver Technologies |
| Others |
Supply Flow & Price Mechanics
Performance-grade certification divergence between EPA-class barrier elements and economy pre-filtration tiers manifests in pricing spreads exceeding 400% while simultaneously concentrating supply chain leverage among German and Japanese polymer producers serving the premium segment. This bifurcation forces mid-tier filter OEMs into margin compression as they absorb specialty membrane allocation risk without commanding corresponding price premiums from price-sensitive utility procurement committees.
Pricing Analysis
Specialized polymer feedstock pass-through from German and Japanese chemical producers anchors premium tier pricing for coalescing filter stages serving coastal installations. Three-tier pricing structure across premium, standard, and economy levels separates ISO 29461-1 certified barrier elements from commodity pre-filtration cartridges and unvalidated synthetic media configurations. Pricing pressure stems from merchant generator procurement committees prioritizing capital minimization over compressor availability metrics. Captive power users in Indian industrial corridors exhibit highest price sensitivity, while Saudi green hydrogen developers demonstrate lowest sensitivity due to project-scale procurement and lifecycle cost optimization mandates.
Supply Chain Analysis
Aerospace-trained CFD engineering talent scarcity in Nordic and German manufacturing geographies constrains filter house development velocity and extends product validation timelines. High-performance membrane polymers source predominantly from German and Japanese specialty chemical producers, while pleated synthetic media production concentrates in China and Southeast Asia for economy tier supply. Single-source vulnerability in marine-grade coalescing specifications exposes OEMs to allocation risk during offshore wind-to-hydrogen cluster ramp-ups. Distribution runs through authorized service contractors for aftermarket cartridge replacement, with long-term service agreements displacing spot procurement among US merchant generators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between EPA-mandated US upgrade cycles and India's National Clean Air Programme first-time procurement creates divergent margin profiles for identical filtration technologies, with regulatory stringency differentials exceeding five years in implementation timelines.
For Market Incumbents: Lock in synthetic media formulation advantages through captive R&D partnerships with German polymer producers, insulating against Japanese chemical allocation risk. Defend installed base positions among Texas and California ISO merchant generators by embedding predictive maintenance platforms into long-term service agreements before emerging IoT specialists capture aftermarket data relationships. Prioritize ISO 29461-1 certification investment for mid-tier product lines to forestall competitive displacement from validated regional challengers in Indian and Australian markets.
For New Entrants and Emerging Players: Capture white-space demand among Indian captive power users in Gujarat and Maharashtra industrial corridors where BIS standard evolution creates first-time high-efficiency inlet system specifications without entrenched incumbent relationships. Target marine-grade coalescing filter procurement channels for European North Sea offshore wind-to-hydrogen clusters where specialized salt-resistant configurations command premium pricing and technical validation barriers filter commodity competitors. Pursue go-to-market alignment with electrolyzer EPC contractors rather than direct utility sales to accelerate specification inclusion in green hydrogen hub project documentation.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier synthetic media specialists possessing validated coastal humidity performance and dormant aerospace filtration expertise applicable to sub-3.0 inch water column pressure drop engineering. Long-term viability over the extended infrastructure replacement window hinges on regulatory compliance pathway alignment rather than pure cost positioning. Acquisition target archetype: regional champions with ISO 29461-1 captive testing infrastructure and established utility relationships in EPA-mandated upgrade markets. Signal to monitor: differential adoption velocity between static and self-cleaning inlet architectures as proxy for operator prioritization of compressor availability over capital minimization.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Feedstock | Mitigates allocation risk from German and Japanese specialty chemical producers for coalescing filter stages. |
| Predictive Maintenance Platform Integration | Captures recurring revenue streams from Texas and California ISO merchant generators facing dispatch volatility. |
| ISO 29461-1 Certification Investment | Creates wind tunnel validation barriers against mid-tier competitors lacking captive testing infrastructure. |
| Long-term Service Agreement Expansion | Transfers inventory risk to OEMs while securing aftermarket revenue from fragmented distributor relationships. |
| Coastal Environment R&D Specialization | Addresses salt-resistant demand from European North Sea offshore wind-to-hydrogen clusters and US Gulf Coast installations. |
Methodological Framework
Multiple input streams — primary interviews with gas turbine OEM procurement directors, utility maintenance planners, and EPC contractor filtration specialists; secondary validation through EPA enforcement databases, FERC interconnection filings, and ISO 29461-1 certification registries — were reconciled through bottom-up and top-down triangulation. Field intelligence from plant engineers at combined-cycle facilities in Texas, California, and the Permian Basin was cross-referenced against customs data on polymer feedstock imports and wind tunnel testing facility utilization reports.
Data-stream reconciliation across filter type, end-user sector, application mode, and technology generation enabled segmentation-specific modeling across the projection horizon. Analytical frameworks incorporated replacement cycle dynamics tied to pressure-drop thresholds, regulatory compliance timelines for EPA ambient air quality standards, and hydrogen economy infrastructure deployment patterns. CAGRs were derived from installed base aging profiles, capacity addition pipelines, and technology substitution elasticities between static and self-cleaning inlet architectures.
Feedstock price volatility, regulatory enforcement variance across state implementation plans, and electrolyzer project financing delays are the dominant revision risks to filtration demand projections. Forecasts embed assumptions regarding ISO standard harmonization timelines and polymer supply allocation continuity. Material deviation in named triggers warrants pause and re-evaluation of segment-specific penetration assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Environment Control
Airborne Molecular Contamination Control Services Market
Aircraft Environment Control
Commercial Aircraft Air Management System Market
Aircraft Environment Control
Aerospace Flight Control System Market
Aircraft Environment Control
Ice Protection Systems Market
Aircraft Environment Control
Turbine Air Filtration Market
Aircraft Environment Control
Aircraft Air Conditioning Unit Market
Aircraft Environment Control
Aircraft Waste Tank Market
Aircraft Environment Control
HUD-Compatible Low-Haze Windshield Defogging Coating Systems Market