
 Africa Aviation MRO Market | 2026-2036
Africa Aviation MRO Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Aviation MRO Market Outlook
Component refurbishment is reconfiguring margin distribution across the Africa Aviation MRO landscape. Ethiopian Airlines Engineering leverages in-house production of engine overhaul capacity to capture value upstream. Safran SA anchors its position through technology leadership in digital inspection systems for regional operators. Lufthansa Technik AG competes by extending its European maintenance protocols into sub-Saharan contracts.
Africa Aviation MRO encompasses the technical servicing, repair, and overhaul of airframes, engines, and avionics systems to sustain airworthiness certification and operational safety, requiring compliance with manufacturer-specific maintenance program intervals and national aviation authority directives. The primary commercial purpose centers on extending aircraft economic life while ensuring regulatory conformity for continued passenger and cargo operations. Engine overhaul commands the deepest margin pools given specialized tooling requirements and OEM intellectual property barriers. Base maintenance sustains volume leadership across the continent as aging narrow-body fleets require scheduled heavy checks. Predictive maintenance represents the fastest-expanding technology segment as airlines deploy sensor analytics to minimize unscheduled downtime.
South Africa's Civil Aviation Authority, Ethiopia's Civil Aviation Authority, and Nigeria's Nigerian Civil Aviation Authority collectively shape market access through bilateral airworthiness recognition agreements and foreign repair station certification protocols. These regulators enforce ICAO-aligned standards that determine which MRO facilities qualify for national airline contracts. Stakeholders must monitor regulatory harmonization progress between African aviation authorities and EASA or FAA frameworks to anticipate competitive shifts in cross-border maintenance sourcing.
Market Dynamics
Fleet renewal cycles across East African carriers are compressing maintenance intervals, forcing MRO providers to reconfigure capacity planning around higher aircraft utilization rates and accelerated engine shop visit frequencies.
Growth Catalysts
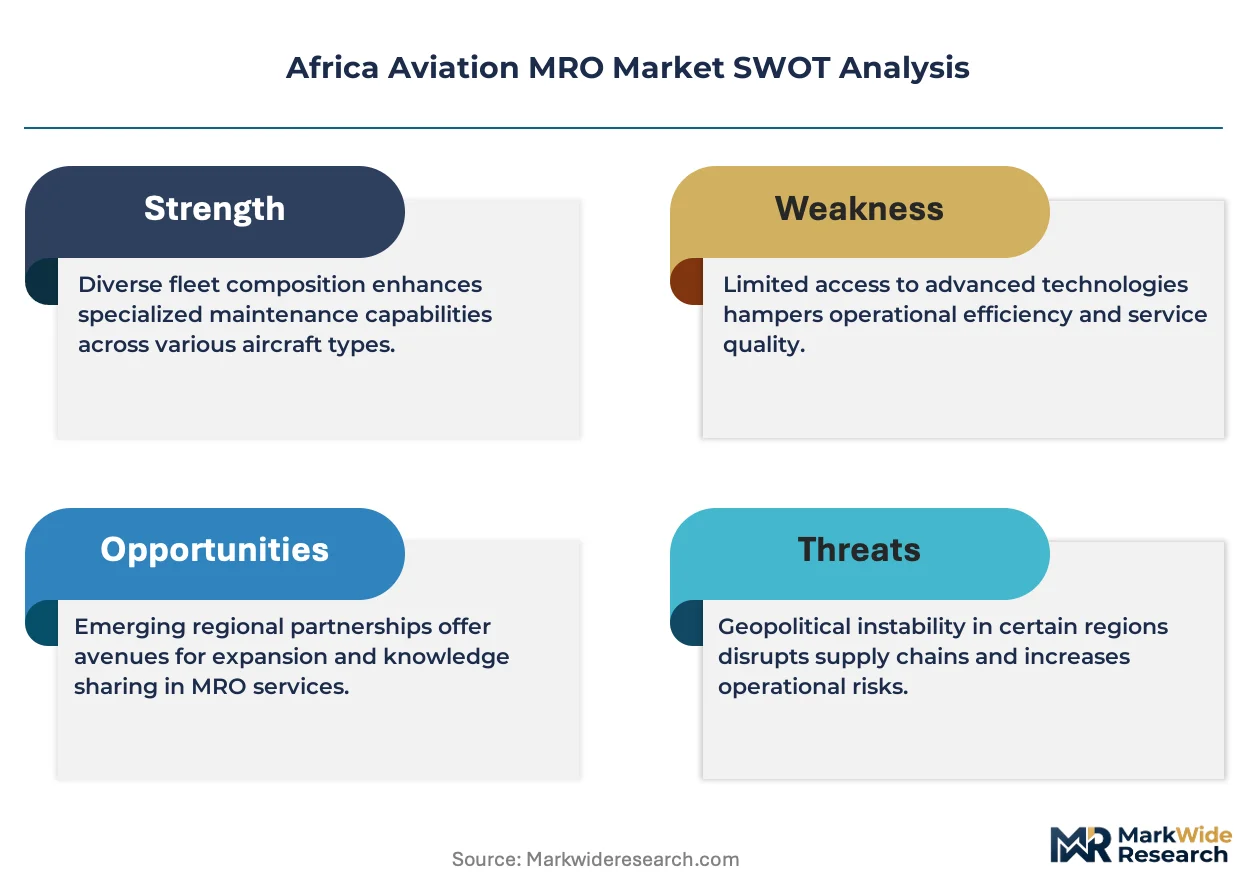
- ICAO-aligned airworthiness harmonization:Bilateral recognition agreements between South Africa's Civil Aviation Authority and European regulators reduce certification friction for cross-border maintenance contracts.
- Sensor analytics deployment:Predictive maintenance platforms using real-time engine health monitoring slash unscheduled downtime for narrow-body operators.
- Addis Ababa cluster concentration:Ethiopian Airlines Engineering anchors heavy maintenance capability, drawing regional airline contracts from neighboring markets.
Market Restraints
- OEM intellectual property barriers:Proprietary engine overhaul tooling and software locks limit independent MRO penetration into high-margin shop visits.
- Specialized technician scarcity:Certified airframe and powerplant mechanics concentrate in South Africa and Ethiopia, constraining capacity expansion elsewhere.
- Foreign exchange volatility:Dollar-denominated spare parts procurement exposes African operators to currency risk, compressing maintenance budget flexibility.
Strategic Opportunities
- Nigerian market underpenetration:Nigeria's Civil Aviation Authority foreign repair station certification protocols create entry paths for EASA-qualified facilities seeking West African contracts.
- Line maintenance network gaps:Turnaround service capacity at secondary airports across Kenya and Tanzania remains underserved relative to fleet growth.
- Component repair technology transfer:Joint ventures with European OEMs enable local landing gear and avionics refurbishment capability.
Industry Challenges
- Airworthiness certification timelines:South Africa's Civil Aviation Authority extended approval cycles for new repair station authorizations delay market entry for foreign competitors.
- Legacy fleet documentation gaps:Aging narrow-body aircraft operating across the continent lack complete maintenance history records, complicating resale and lease-return inspections.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Aviation MRO Market |
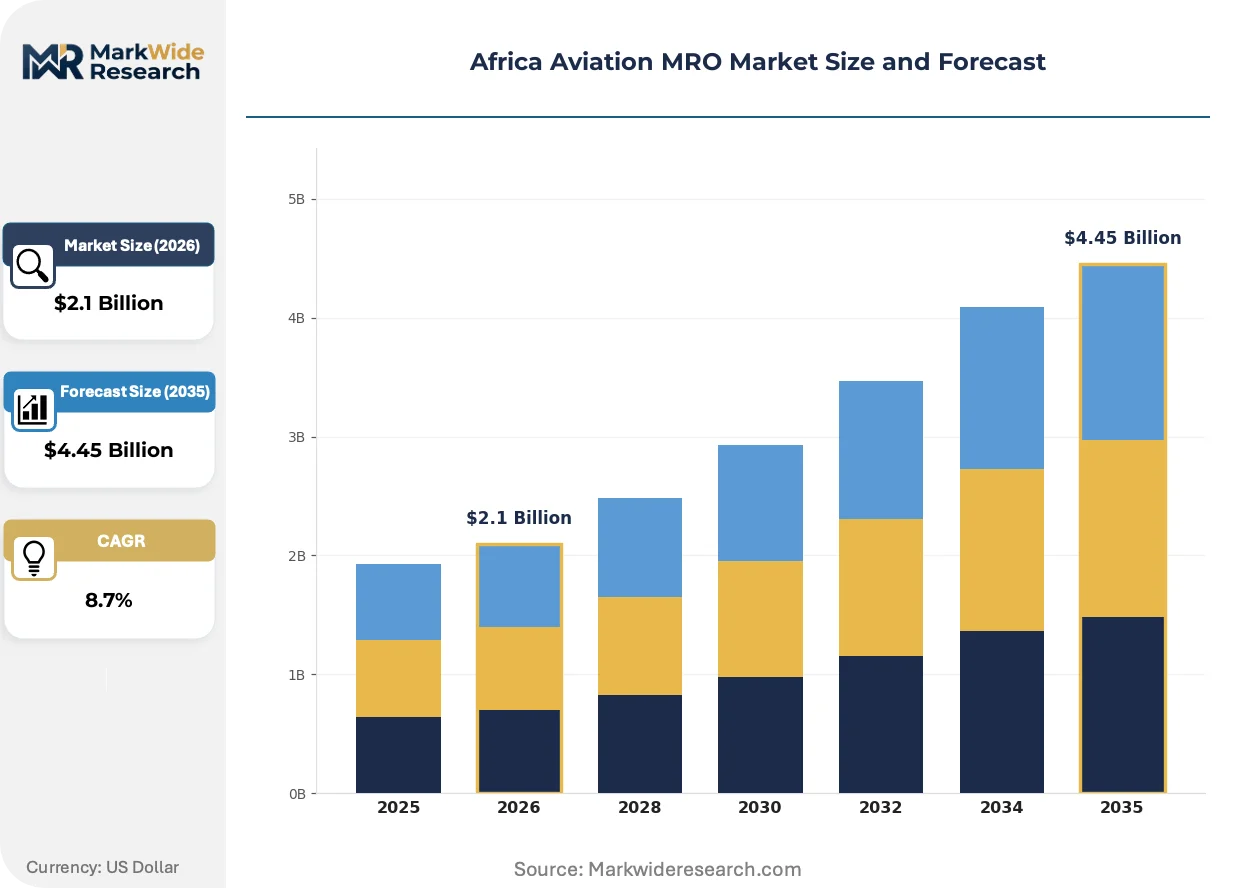
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Line Maintenance, Base Maintenance, Component Maintenance, Engine Overhaul Aircraft Type: Commercial Aircraft, Military Aircraft, Helicopters, Business Jets End User: Airlines, Charters, Freight Carriers, Maintenance Providers Technology: Predictive Maintenance, Digital Inspection, AI Solutions, Repair Technologies |
| Companies Covered | Leonardo S.p.A., Ethiopian Airlines Engineering, Safran SA, South African Airways Technical, EGYPTAIR Maintenance & Engineering, RTX Corporation, Airbus SE, ExecuJet MRO Services, Lufthansa Technik AG, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Aviation MRO Market Strategic Shifts
Digital inspection systems and connected aircraft platforms are reconfiguring how African carriers schedule maintenance events, shifting from calendar-based checks toward condition-driven interventions that align with operational data streams.
Non-destructive testing using phased-array ultrasonic technology is migrating from European MRO hubs to Ethiopian Airlines Engineering and select South African facilities. Regional operators adopting these digital inspection protocols compress heavy check turnaround times by eliminating manual borescope disassembly requirements. The technology is migrating from line maintenance screening into base maintenance workflows, enabling earlier crack detection in high-cycle fuselage sections.
South Africa's Civil Aviation Authority implemented strengthened foreign repair station audit protocols aligned with EASA Part-145 standards. These tightened certification requirements disqualify lower-tier maintenance providers from national airline contracts. Ethiopian and Kenyan operators now prioritize EASA-recognized facilities, compressing procurement options but raising safety assurance levels.
Power-by-the-hour contracts are displacing transactional component repairs among East African carriers seeking to offload inventory risk. Maintenance cost predictability now dominates procurement criteria over unit pricing for engine and landing gear overhauls. Kenya Airways and RwandAir have adopted this model most aggressively, shifting supplier relationships toward long-term performance guarantees.
Africa Aviation MRO Market Segmentation
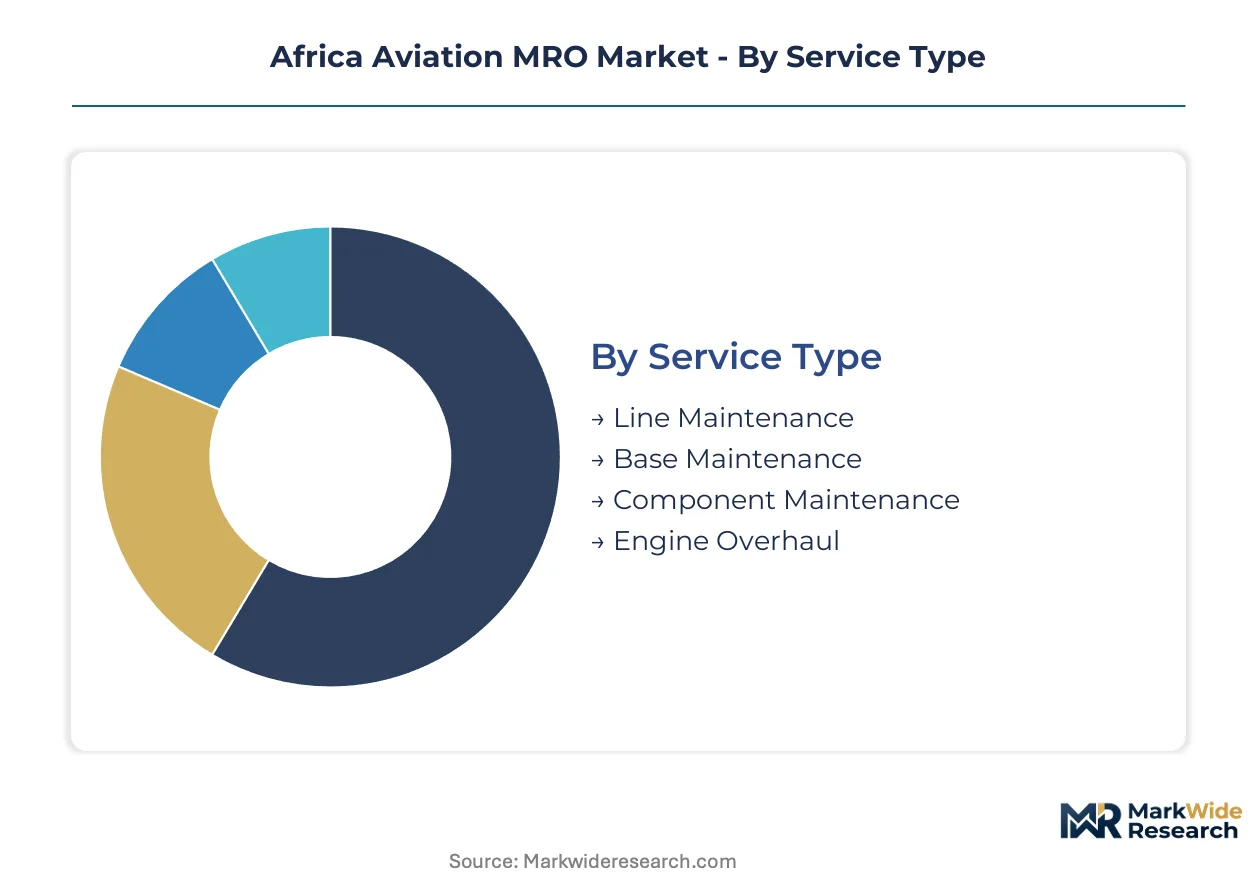
Africa Aviation MRO segmentation reveals how maintenance demand fragments across service intensity tiers, aircraft mission profiles, and technology adoption curves. Each dimension shapes procurement patterns and margin capture differently across Ethiopian, South African, and Nigerian operator bases.
Service Type:
Cost tier differentiation separates scheduled light interventions from capital-intensive heavy maintenance events requiring specialized infrastructure.
- Engine Overhaul:Complete disassembly, inspection, and reassembly of turbine powerplants using proprietary OEM tooling and certified test cells. Ethiopian Airlines Engineering anchors regional capacity, drawing cross-border contracts from Kenyan and Rwandan carriers seeking to avoid European shop visits.
- Base Maintenance:Scheduled heavy checks encompassing airframe structural inspection, system overhaul, and interior refurbishment at multi-day intervals. South African facilities concentrate this capability, though extended certification timelines constrain foreign competitor entry.
- Component Maintenance:Landing gear, avionics, and auxiliary power unit refurbishment to component manual specifications.
- Line Maintenance:Turnaround servicing including fluid replenishment, tire changes, and minor defect rectification between flight cycles.
Engine Overhaul holds installed capacity. Base Maintenance is rotating up the share rankings.
Aircraft Type:
Application mission dictates maintenance interval compression and technology requirements across passenger, cargo, and specialized operations.
- Commercial Aircraft:Narrow-body and regional jet fleets subject to high-cycle utilization rates and accelerated airworthiness directives. East African carriers are expanding fleet deployment, compressing engine shop visit frequencies and driving aftermarket demand concentration in Addis Ababa.
- Helicopters:Rotary-wing platforms serving offshore energy, medical evacuation, and mining logistics with component-limited supply chains and specialized dynamic component overhaul requirements.
- Military Aircraft:Defense fleet maintenance governed by national security procurement protocols and sovereign facility requirements.
- Business Jets:Corporate aviation assets requiring flexible scheduling and premium turnaround guarantees at select hubs.
Commercial Aircraft holds installed capacity. Helicopters is rotating up the share rankings.
End User:
Customer type determines contract structure preferences, from power-by-the-hour arrangements to transactional spot purchasing.
- Airlines:Scheduled carriers operating under continuous airworthiness management programs with predictable maintenance budgeting and long-term supplier relationships. Kenya Airways and RwandAir have adopted performance-based contracts most aggressively.
- Freight Carriers:Cargo operators with night-dominant scheduling patterns and accelerated engine degradation from high-thrust takeoff cycles.
- Charters:Ad-hoc passenger operators with irregular utilization profiles and intermittent maintenance demand spikes.
- Maintenance Providers:Independent MRO facilities and airline engineering subsidiaries serving third-party contracts.
Airlines holds installed capacity. Freight Carriers is rotating up the share rankings.
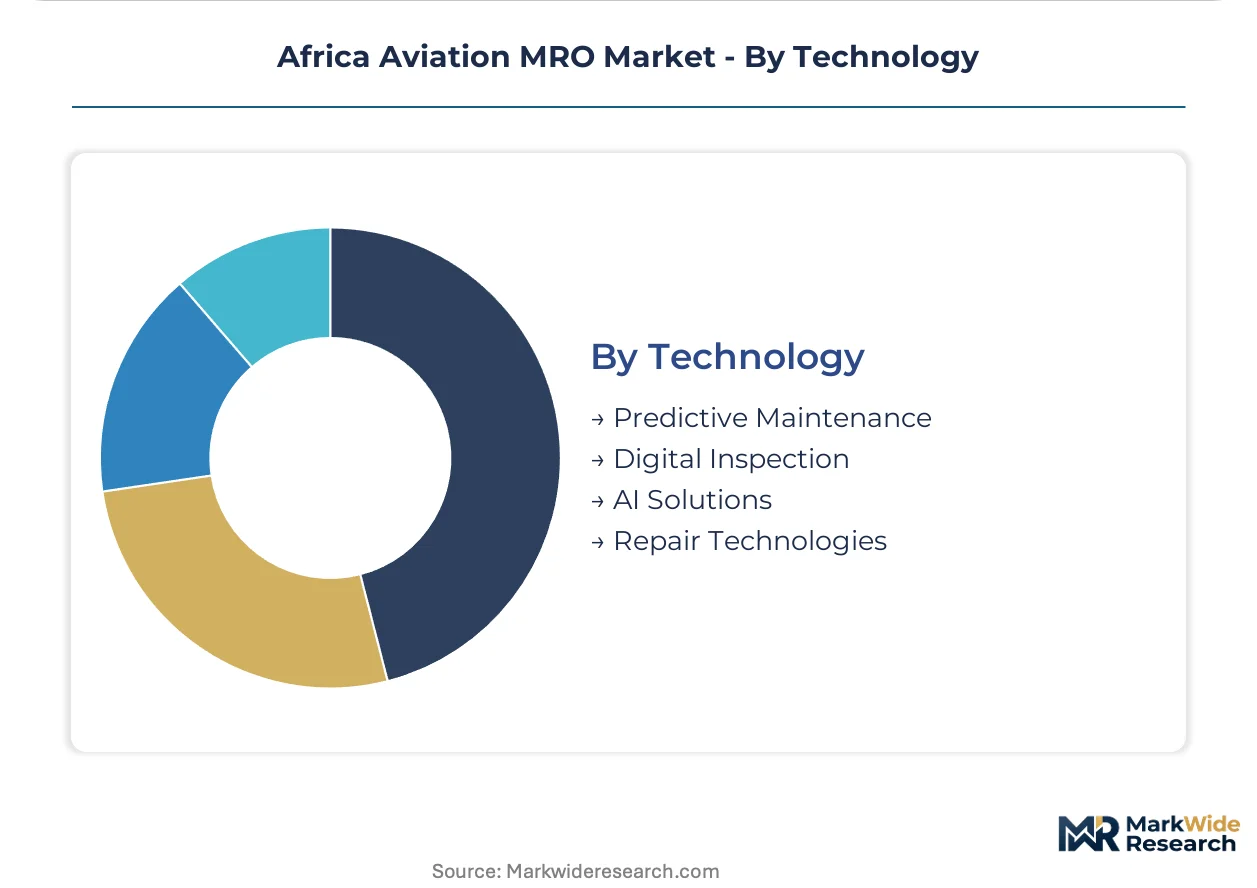
Technology:
Maturity gradients separate established diagnostic methods from emerging analytics platforms reshaping intervention timing.
- Predictive Maintenance:Sensor-based engine health monitoring and machine learning algorithms forecasting component failures before functional degradation. East African carriers deploying these platforms are slashing unscheduled downtime and shifting from calendar-based to condition-driven maintenance events.
- Digital Inspection:Phased-array ultrasonic and borescope technologies eliminating manual disassembly requirements. Ethiopian Airlines Engineering and select South African facilities are migrating this capability from line maintenance screening into base maintenance workflows.
- AI Solutions:Automated defect recognition and maintenance program optimization algorithms.
- Repair Technologies:Conventional welding, composite patching, and surface treatment methodologies.
Repair Technologies holds installed capacity. Predictive Maintenance is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East African carriers exhibit the lowest price elasticity as fleet utilization rates compress maintenance intervals, while West African operators remain highly sensitive to dollar-denominated spare parts procurement costs.
Ethiopia
Ethiopian Airlines Engineering drives continental heavy maintenance demand through in-house engine overhaul capacity and regional third-party contracts. The Ethiopian Civil Aviation Authority enforces ICAO-aligned airworthiness certification that qualifies Addis Ababa facilities for cross-border airline servicing. The Addis Ababa cluster anchors East African MRO capability, drawing Kenyan and Rwandan carriers seeking alternatives to European shop visits.
South Africa
South African Airways Technical and independent facilities concentrate base maintenance capacity for aging narrow-body fleets requiring scheduled heavy checks. South Africa's Civil Aviation Authority tightened foreign repair station audit protocols aligned with EASA Part-145 standards, disqualifying lower-tier providers from national airline contracts. Johannesburg and Cape Town industrial zones host the continent's densest certified airframe and powerplant mechanic pools.
Nigeria
Nigerian carriers lag in heavy maintenance capability, forcing reliance on foreign repair stations for engine overhaul and structural inspection. The Nigerian Civil Aviation Authority foreign repair station certification protocols create entry paths for EASA-qualified facilities seeking West African contracts. Lagos and Abuja maintenance infrastructure remains underdeveloped relative to fleet scale, concentrating line maintenance demand at primary hubs.
Egypt
EGYPTAIR Maintenance & Engineering leverages Cairo's geographic position to capture North African and Middle Eastern transit maintenance contracts. Egyptian civil aviation regulators maintain bilateral airworthiness recognition agreements with European authorities that facilitate cross-border certification. The Cairo industrial corridor sustains component refurbishment capability for landing gear and auxiliary power units.
Kenya
Kenya Airways deploys predictive maintenance platforms aggressively, shifting procurement criteria toward long-term performance guarantees over unit pricing. The Kenya Civil Aviation Authority enforces continuous airworthiness management program compliance for scheduled carriers operating under high-cycle utilization. Nairobi's Jomo Kenyatta International Airport anchors regional line maintenance demand, though secondary airport turnaround capacity remains underserved.
Africa Aviation MRO Market Competitive Environment
Flag carrier engineering subsidiaries and European specialist contractors split the market between captive in-house capability and outsourced technical partnerships. The vendor base concentrates around three strategic archetypes: airline-owned engineering divisions with vertical integration into engine overhaul, European MRO contractors extending protocols into sub-Saharan contracts, and component OEMs leveraging digital inspection technology for regional positioning. Dominant competitive moves include capacity expansion through joint ventures with national carriers and technology licensing agreements that transfer non-destructive testing capabilities to African facilities.
Among airline-owned engineering divisions, Ethiopian Airlines Engineering and South African Airways Technical represent the integrated-service archetype with captive heavy maintenance infrastructure. European specialist contractors include Safran SA and Lufthansa Technik AG, which occupy positions as technology and protocol exporters respectively. These named entities exemplify how competitive positioning fragments between indigenous capability builders and foreign technical partners seeking African market access.
| Leading Market Players |
|---|
| Leonardo S.p.A. |
| Ethiopian Airlines Engineering |
| Safran SA |
| South African Airways Technical |
| EGYPTAIR Maintenance & Engineering |
| RTX Corporation |
| Airbus SE |
| ExecuJet MRO Services |
| Lufthansa Technik AG |
| Others |
Value Chain & Pricing Dynamics
Addis Ababa's engine overhaul cluster concentrates specialized tooling capacity, granting Ethiopian Airlines Engineering pricing leverage over regional carriers seeking alternatives to European shop visits. This geographic supply concentration compresses procurement options for Kenyan and Rwandan operators while amplifying margin capture at the heavy maintenance tier.
Pricing Analysis
Power-by-the-hour service contracts now dominate lifetime value capture among East African carriers, displacing transactional component repairs. Pricing stratifies across EASA-recognized facilities, OEM-authorized centers, and uncertified independent shops based on airworthiness certification tier and bilateral recognition status. Cost compression in line maintenance runs through foreign exchange volatility affecting dollar-denominated spare parts procurement. Freight carriers exhibit the highest price sensitivity due to night-dominant scheduling patterns, while flag carriers prioritize performance guarantees over unit pricing.
Supply Chain Analysis
Export controls on proprietary engine overhaul software and specialized test cell technology limit technology transfer into African facilities, constraining independent MRO penetration. Component refurbishment draws from France, Germany, and the United States for landing gear and avionics systems, while raw material inputs hinge on titanium alloys, nickel-based superalloys, and composite prepregs. Single-source vulnerability concentrates in OEM-certified tooling for turbine blade restoration. Distribution runs through airline engineering subsidiaries and European specialist contractors with bilateral airworthiness agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a substitution defense against European MRO facilities capturing regional airline contracts; incumbents must navigate the threat of East African carriers bypassing local capacity entirely for EASA-recognized shop visits.
For Market Incumbents: Harden certification barriers by accelerating Ethiopian Civil Aviation Authority bilateral recognition negotiations with EASA to preempt European competitor entry. Deepen in-house production of engine overhaul capacity through technology licensing with Safran SA to capture upstream value pools. Anchor procurement relationships via long-term power-by-the-hour contracts that embed inventory risk transfer and performance guarantees. For New Entrants and Emerging Players: Pursue Nigerian market entry through foreign repair station certification under the Nigerian Civil Aviation Authority protocols, targeting the underdeveloped Lagos and Abuja heavy maintenance infrastructure. Capture line maintenance network gaps at secondary Kenyan and Tanzanian airports where turnaround capacity lags fleet growth. Lead with joint venture structures that transfer non-destructive testing capabilities from European OEMs to establish local credibility. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors EASA-qualified facilities with predictive maintenance platform deployment and bilateral airworthiness recognition spanning multiple African regulators. Long-term viability rests on facilities capturing the shift from calendar-based to condition-driven maintenance events. Acquisition targets should demonstrate existing Ethiopian Airlines Engineering or South African Airways Technical supplier relationships. Watch sensor analytics adoption rates among Kenya Airways and RwandAir as the inflection indicator for technology-led competitive separation.| Strategic Initiative | Industry Significance |
|---|---|
| EASA Bilateral Recognition Expansion | Ethiopian Civil Aviation Authority alignment with European standards unlocks cross-border contract eligibility for Addis Ababa facilities. |
| Predictive Maintenance Platform Deployment | Sensor analytics integration by Kenya Airways compresses unscheduled downtime and shifts procurement toward performance-based contracts. |
| Foreign Repair Station Certification | Nigerian Civil Aviation Authority protocols create entry paths for EASA-qualified facilities seeking West African airline contracts. |
| Component Repair Joint Ventures | Technology licensing with Safran SA enables local landing gear and avionics refurbishment capability in South African facilities. |
| Power-by-the-Hour Contract Structuring | Long-term performance guarantees adopted by RwandAir embed inventory risk transfer and supplier relationship lock-in. |
Study Parameters
Operator-level perspectives from airline engineering directors, MRO procurement managers, civil aviation authority certification officers, and OEM regional sales heads anchored the qualitative base. Primary interviews combined with secondary validation against ICAO airworthiness directives, EASA Part-145 certification databases, bilateral recognition agreement records, and airline fleet planning disclosures. Bottom-up triangulation across service type demand estimates and top-down reconciliation against national aviation authority operational statistics ensured cross-verification.
Scenario-bracketing framed the analytical approach across the projection horizon, modeling segmentation dimensions including service intensity tier, aircraft mission profile, technology adoption curve, and end-user contract structure preference. CAGRs derived from fleet utilization rate projections, engine shop visit frequency assumptions, and regulatory harmonization timelines. Industry-specific inputs incorporated narrow-body fleet age distributions, power-by-the-hour contract penetration rates, and digital inspection technology migration curves.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by European MRO contractors or accelerated bilateral recognition between Nigerian Civil Aviation Authority and EASA would shift outcomes. Material shifts in foreign exchange volatility affecting dollar-denominated spare parts procurement or OEM intellectual property licensing terms would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Wide-Body Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
US Aerospace Components MRO Market
Aircraft Maintenance and MRO Solutions
North America Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Towing Equipment Market
Aircraft Maintenance and MRO Solutions
Aircraft Tire Balancer Market
Aircraft Maintenance and MRO Solutions
Europe Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Air Transport MRO Market
Aircraft Maintenance and MRO Solutions
Business Jet Mro Market
Aircraft Maintenance and MRO Solutions
Global Aircraft Heavy Maintenance Visits Market
Aircraft Maintenance and MRO Solutions
Digital Aerospace MRO Market
Aircraft Maintenance and MRO Solutions
Global Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Line Maintenance Market
Aircraft Maintenance and MRO Solutions
Global Aircraft Refurbishing Market
Aircraft Maintenance and MRO Solutions
Commercial Aircraft Maintenance Repair and Overhaul (MRO) Market
Aircraft Maintenance and MRO Solutions
Southeast Asia Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aviation Engine MRO Market