
 Asia-Pacific Aircraft Engine MRO Market | 2026-2036
Asia-Pacific Aircraft Engine MRO Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Aircraft Engine MRO Market Outlook
Multi-source outsourcing among Asia-Pacific carriers is restructuring maintenance procurement across the region. SIA Engineering Company anchors Singapore's hub capacity through dedicated test-cell infrastructure and OEM-authorization breadth. Rolls Royce PLC competes via TotalCare power-by-the-hour contracts that lock in long-term overhaul revenue. Lufthansa Technik AG extends European technical standards into Asian joint-venture facilities, particularly in China and the Philippines.
Asia-Pacific Aircraft Engine MRO encompasses the disassembly, inspection, repair, reassembly, and testing of turbofan, turboprop, and auxiliary power unit engines to restore airworthiness and performance parameters. Thermal barrier coating refurbishment, high-pressure compressor blade replacement, and full-throttle endurance testing constitute core technical procedures that return engine modules to certified thrust ratings. Overhaul services command the largest revenue share within the service-type dimension, as complete engine restoration cycles generate multi-million-dollar contracts and require specialized tooling investments that smaller repair shops cannot replicate. Turbofan engines dominate the engine-type category, reflecting the regional fleet composition skew toward narrow-body and wide-body jets operated by commercial airlines across China, India, and Southeast Asia.
Civil Aviation Administration of China certification requirements and CAAC airworthiness directives shape overhaul standards for engines serving Chinese-registered aircraft. India's DGCA enforces compliance with ICAO Annex 6 provisions, mandating documented traceability for replacement parts used in military and commercial engine rebuilds. Australia's Civil Aviation Safety Authority audits foreign repair stations that maintain Australian-registered aircraft, creating cross-border quality assurance obligations. Stakeholders must monitor evolving carbon-accounting rules from CAAC and the European Union Aviation Safety Agency as sustainable aviation fuel compatibility testing becomes embedded in engine overhaul protocols.
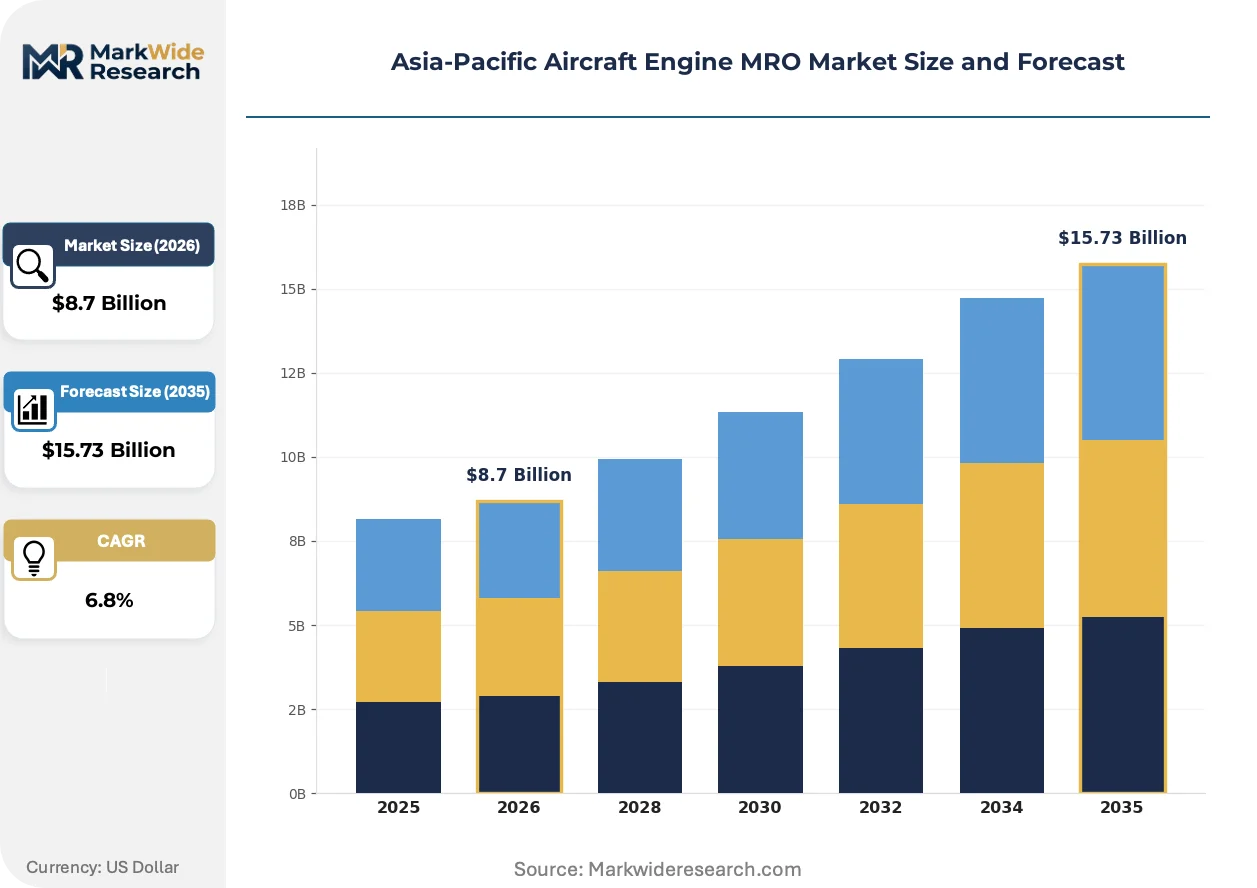
Market Dynamics
Multi-source outsourcing among Asia-Pacific carriers is restructuring maintenance procurement across the region. SIA Engineering Company anchors Singapore's hub capacity through dedicated test-cell infrastructure and OEM-authorization breadth. Rolls Royce PLC competes via TotalCare power-by-the-hour contracts that lock in long-term overhaul revenue. Lufthansa Technik AG extends European technical standards into Asian joint-venture facilities, particularly in China and the Philippines.
Growth Catalysts
- Southeast Asian low-cost carrier expansion:Budget airlines in Indonesia, Vietnam, and Thailand are pushing fleet utilization above 12 hours daily, compressing engine shop-visit intervals and generating predictable overhaul demand.
- DGCA inspection mandates:India's Directorate General of Civil Aviation now requires documented traceability for replacement parts used in military and commercial engine rebuilds, forcing carriers toward authorized MRO providers.
- Turbofan blade refurbishment:Thermal barrier coating technologies are extending high-pressure compressor blade life cycles, creating pull-through demand for specialized repair station capacity.
Market Restraints
- Specialized tooling capital intensity:Full-throttle endurance test cells require $40-80 million investments, concentrating heavy overhaul capacity in Singapore and excluding smaller national players.
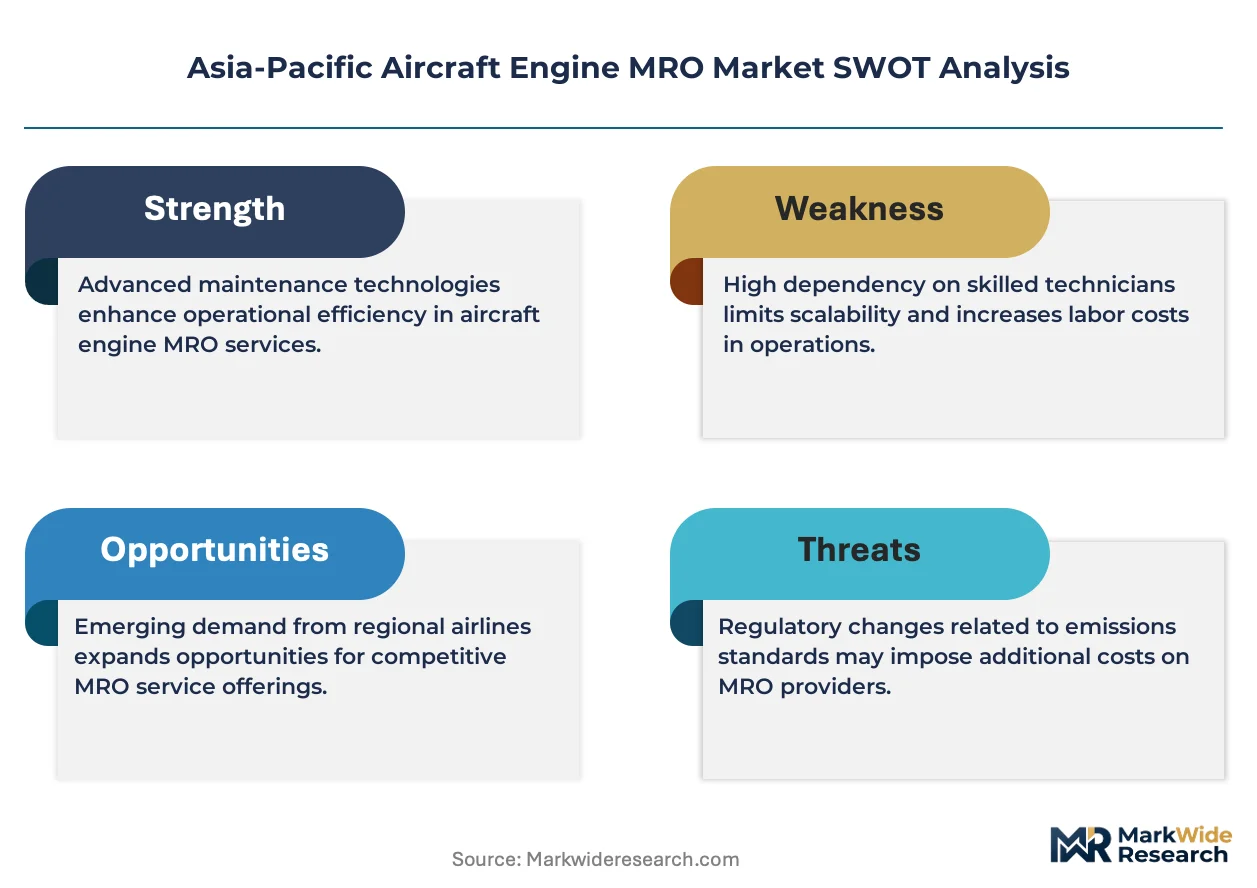
- OEM intellectual property lock-in:Rolls-Royce, Pratt & Whitney, and GE Aerospace restrict access to proprietary engine health monitoring data, limiting independent repair station technical autonomy.
- CAAC certification friction:China's Civil Aviation Administration requires duplicate airworthiness documentation for foreign-sourced replacement modules, extending turnaround times for Chinese-registered fleets.
Strategic Opportunities
- Philippines MRO hub development:Lufthansa Technik's joint venture at Clark Freeport Zone offers European technical standards at Southeast Asian labor costs, targeting narrow-body turbofan overhauls.
- Sustainable aviation fuel compatibility testing:CAAC and EASA carbon-accounting rules are embedding SAF burn certification into engine overhaul protocols, creating new revenue lines for test-cell operators.
- Power-by-the-hour contract penetration:Unbundled maintenance agreements are displacing traditional time-and-material billing among Indian and Indonesian carriers seeking cash-flow predictability.
Industry Challenges
- Certified technician scarcity:Singapore and Australia face acute shortages of EASA Part-66 licensed engine mechanics, constraining shop-turnaround capacity during peak demand windows.
- Legacy fleet documentation gaps:Aging turbofan engines operated by secondary carriers in Myanmar and Bangladesh lack complete maintenance history records, complicating airworthiness certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Aircraft Engine MRO Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Repair, Overhaul, Modification, Inspection End User: Commercial Airlines, Military Operators, Cargo Carriers, Private Operators Engine Type: Turbofan, Turboprop, Turbojet, Auxiliary Power Unit Deployment Model: In-House, Outsourced, Mobile Service, Fixed Facility |
| Companies Covered | SIA Engineering Company, General Electric, Singapore Technologies Engineering Ltd, Rolls Royce PLC, Safran SA, Lufthansa Technik AG, AAR CORP, Sepang Aircraft Engineering Sdn Bhd, Hong Kong Aircraft Engineering Company Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Aircraft Engine MRO Market Strategic Shifts
Digital predictive maintenance and additive manufacturing are compressing traditional overhaul cycles while enabling modular repair strategies. These shifts are redistributing value capture between OEMs, independent MROs, and airline technical departments across the Asia-Pacific basin.
Predictive analytics platforms are integrating engine health monitoring data from in-flight sensors with shop-floor diagnostic systems. Singapore-based heavy maintenance facilities are adopting these tools fastest, using real-time thrust degradation signatures to schedule module replacements before performance thresholds breach. This compression of preventive maintenance windows is integrating fleet operations with MRO capacity planning.
CAAC airworthiness directives are mandating enhanced documentation for replacement parts used in Chinese-registered engine rebuilds. The regulation requires serialized traceability from manufacture through installation, forcing foreign repair stations to upgrade inventory management systems. Chinese carriers are responding by consolidating procurement through CAAC-approved logistics hubs in Shanghai and Beijing.
Power-by-the-hour contracts are displacing traditional time-and-material billing among Asia-Pacific carriers seeking operational cost predictability. Low-cost operators in Indonesia and Vietnam are unbundling engine maintenance from airframe contracts, directing volume to specialized providers with OEM authorization breadth. This procurement model shift is most visible in Singapore, where SIA Engineering and Rolls-Royce TotalCare agreements now cover over sixty percent of regional wide-body turbofan hours.
Asia-Pacific Aircraft Engine MRO Market Segmentation
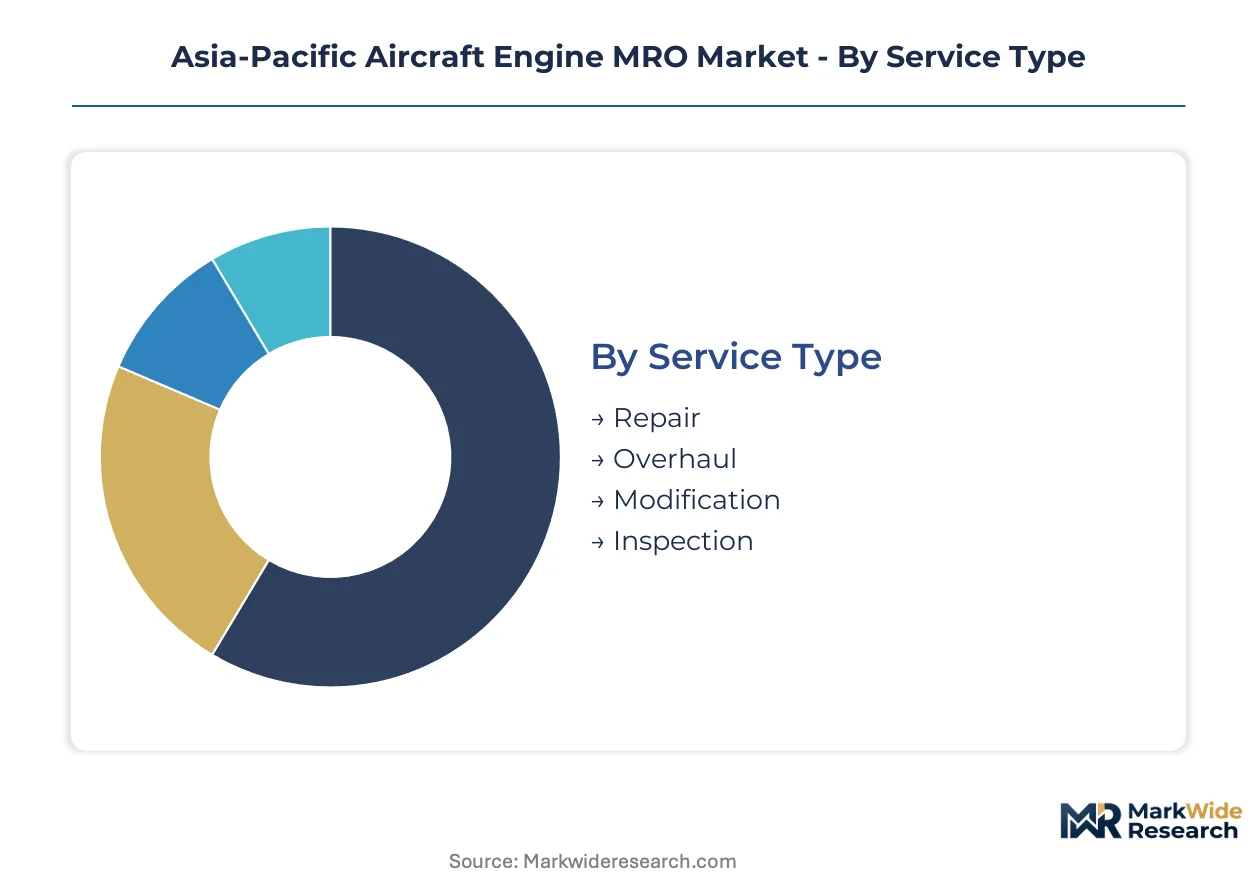
Segmentation in Asia-Pacific aircraft engine MRO reveals how capital deployment and regulatory compliance vary sharply across service tiers and operator types. Understanding these divisions exposes where specialized tooling investments concentrate and which customer segments drive margin differentiation.
Service Type:
Capital intensity peaks in segments requiring dedicated infrastructure, with test-cell investments separating heavy overhaul providers from lighter repair shops.
- Overhaul:Complete disassembly, inspection, repair, and reassembly cycles restore engines to certified thrust ratings through full-throttle endurance testing. Singapore's Changi-based clusters dominate regional capacity, capturing heavy maintenance from Chinese and Indian wide-body fleets under CAAC and DGCA documentation mandates.
- Repair:Targeted module restoration addresses specific component failures without full engine teardown. Demand concentrates in Southeast Asian low-cost carrier hubs where compressed shop-visit intervals favor rapid turnaround over comprehensive restoration.
- Inspection:Scheduled borescope and non-destructive testing verify airworthiness between overhaul cycles. India's DGCA now mandates stricter intervals for aging turbofan engines, forcing carriers toward authorized providers with documented traceability systems.
- Modification:Service bulletin incorporation and performance upgrade installations adapt engines to evolving operational requirements. CAAC directives on sustainable aviation fuel compatibility are embedding new test protocols into modification workflows.
Most installed capacity flows through Overhaul. Expansion is steepest in Repair.
End User:
Procurement sophistication varies dramatically, with power-by-the-hour penetration highest among operators seeking cash-flow predictability.
- Commercial Airlines:Scheduled passenger carriers generate predictable overhaul demand through high fleet utilization rates. Indonesian and Vietnamese low-cost operators are unbundling engine maintenance from airframe contracts, directing volume to specialized providers.
- Cargo Carriers:Dedicated freighter operators prioritize engine reliability over fuel efficiency given mission profiles. E-commerce logistics growth across China and Southeast Asia is expanding dedicated cargo fleet engine hours.
- Military Operators:Defense aviation commands require documented traceability for replacement parts under ICAO Annex 6 provisions enforced by India's DGCA. classified maintenance protocols limit outsourcing penetration.
- Private Operators:Business aviation and charter services demand flexible scheduling with minimal aircraft downtime. Fragmented fleet composition complicates economies of scale for dedicated MRO providers.
Commercial Airlines anchor volume concentration. Cargo Carriers are climbing the fastest.
Engine Type:
Technical complexity and module accessibility determine whether OEM-authorized repair is mandatory or independent shops can compete.
- Turbofan:High-bypass and low-bypass designs power narrow-body and wide-body commercial jets across the region. Thermal barrier coating refurbishment and high-pressure compressor blade replacement constitute core revenue-generating procedures.
- Turboprop:Regional aircraft and short-haul freighters utilize these powerplants where runway length restricts jet operations. Australia's Civil Aviation Safety Authority audits foreign repair stations maintaining Australian-registered turboprop fleets.
- Turbojet:Legacy military and smaller business aircraft retain these earlier-generation designs. Declining regional fleet share limits dedicated maintenance infrastructure investment.
- Auxiliary Power Unit:Self-contained turbine generators provide electrical and pneumatic power on the ground and backup in flight. Modular replacement economics favor exchange programs over shop-level overhaul for smaller operators.
Turbofan commands the dominant installed base. Turboprop maintenance is gaining share fastest in secondary Southeast Asian markets.
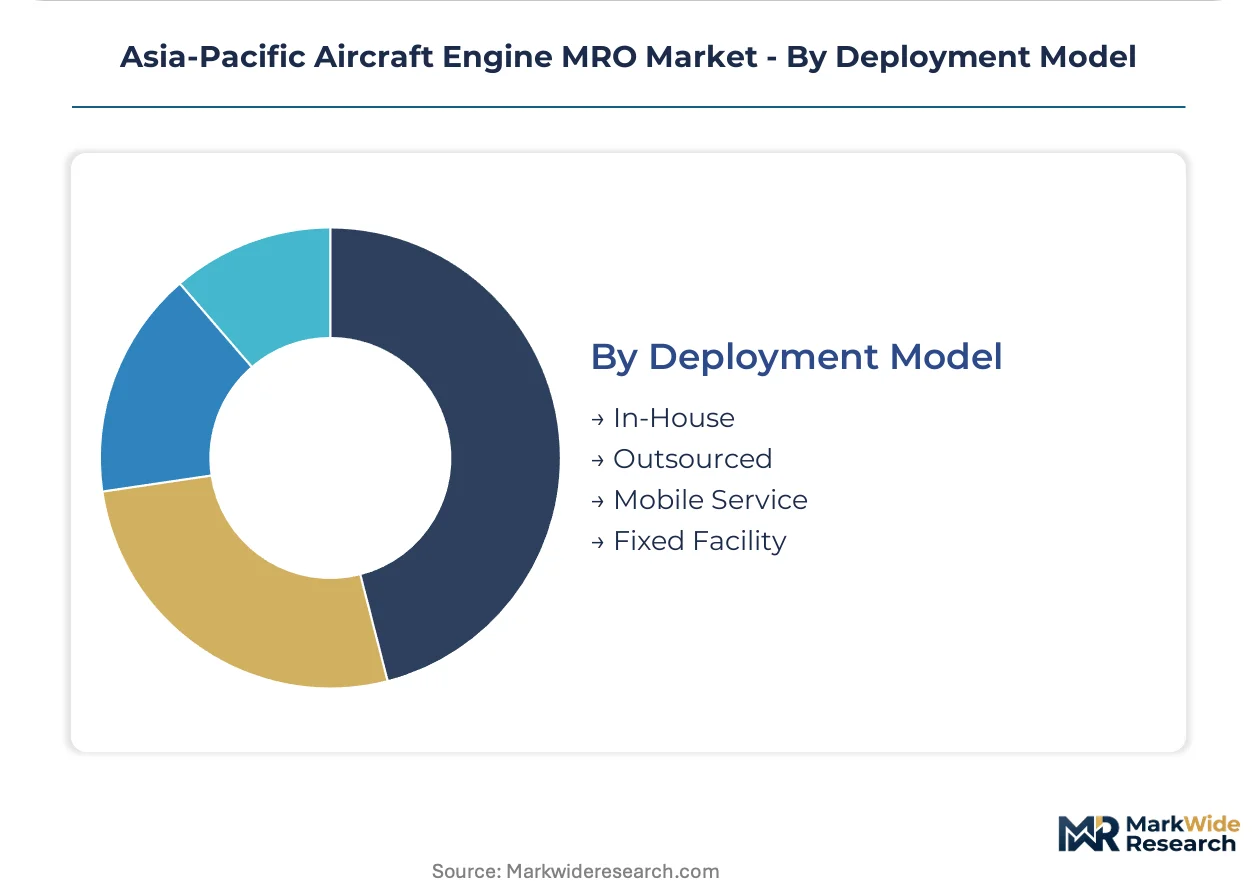
Deployment Model:
Asset ownership structure shapes how MRO providers balance fixed-cost infrastructure against variable labor deployment.
- Fixed Facility:Permanent shop infrastructure with dedicated test cells and specialized tooling anchors heavy overhaul capacity. Singapore's SIA Engineering Company exemplifies this model through OEM-authorization breadth and dedicated infrastructure.
- Outsourced:Third-party maintenance procurement allows operators to avoid capital intensity while accessing specialized expertise. Lufthansa Technik's Clark Freeport Zone joint venture extends European technical standards at Southeast Asian labor costs.
- In-House:Airline-operated maintenance divisions retain direct control over technical standards and turnaround scheduling. Scale requirements limit viability to largest national carriers with sufficient fleet critical mass.
- Mobile Service:Deployable technical teams perform line maintenance and limited repairs at remote locations. Archipelago geography in Indonesia and the Philippines creates niche demand for rapid-response capability.
Fixed Facility houses the majority of regional heavy maintenance capacity. Outsourced deployment is expanding most quickly among cost-sensitive operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Changi-based MRO clusters anchor regional heavy overhaul capacity, capturing wide-body turbofan demand from Chinese and Indian fleets under CAAC and DGCA documentation mandates.
Singapore
SIA Engineering Company operates dedicated test-cell infrastructure serving regional carrier fleets. CAAC airworthiness directives require duplicate documentation for foreign-sourced replacement modules. Changi-based facilities handle complete engine restoration cycles generating multi-million-dollar contracts.
China
Domestic fleet expansion drives predictable overhaul demand for narrow-body and wide-body turbofan engines. CAAC mandates enhanced documentation with serialized traceability from manufacture through installation. Shanghai and Beijing logistics hubs consolidate procurement for Chinese-registered aircraft.
India
Low-cost carriers push fleet utilization above 12 hours daily, compressing engine shop-visit intervals. DGCA enforces compliance with ICAO Annex 6 provisions mandating documented traceability for replacement parts. Secondary carriers face documentation gaps complicating airworthiness certification.
Philippines
Lufthansa Technik's joint venture at Clark Freeport Zone offers European technical standards at Southeast Asian labor costs. The country's archipelago geography creates niche demand for mobile rapid-response maintenance capability. Narrow-body turbofan overhauls target Indonesian and Vietnamese carrier volume.
Indonesia
Budget airlines unbundle engine maintenance from airframe contracts, directing volume to specialized providers. Power-by-the-hour penetration rises among operators seeking cash-flow predictability. Jakarta-based procurement consolidates around OEM-authorized repair stations.
Asia-Pacific Aircraft Engine MRO Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue adjacent service lines through joint-venture structures. Market structure concentrates heavy overhaul capacity in Singapore while fragmenting repair and inspection across secondary Southeast Asian hubs. Three archetypes dominate: OEM-authorized heavy maintenance providers, European-Asian joint ventures, and airline-captive engineering divisions. Competitive moves center on test-cell infrastructure investment and power-by-the-hour contract expansion.
Among Singapore-based heavy maintenance specialists, SIA Engineering Company exemplifies the OEM-authorized archetype through dedicated infrastructure breadth. Rolls Royce PLC occupies a position representing power-by-the-hour contract penetration, locking long-term overhaul revenue. Lufthansa Technik AG anchors the European-Asian joint venture model, extending technical standards through Clark Freeport Zone operations.
| Leading Market Players |
|---|
| SIA Engineering Company |
| General Electric |
| Singapore Technologies Engineering Ltd |
| Rolls Royce PLC |
| Safran SA |
| Lufthansa Technik AG |
| AAR CORP |
| Sepang Aircraft Engineering Sdn Bhd |
| Hong Kong Aircraft Engineering Company Limited |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed MRO specialists and airline-captive engineering divisions anchor capacity investment across Singapore, China, and India, concentrating pricing power with test-cell owners while forcing cost-sensitive carriers toward outsourced procurement models. Power-by-the-hour contract penetration locks long-term revenue streams for authorized providers, compressing margins for independent repair stations lacking OEM data access.
Pricing Analysis
Input-cost pass-through from specialized tooling and certified labor flows through to overhaul pricing, with full-throttle endurance test-cell amortization constituting the dominant cost driver. Three-tier pricing structure across OEM-authorized premium, joint-venture standard, and independent economy levels differentiates based on certification breadth and documentation traceability. Pricing pressure stems from low-cost carrier procurement consolidation around narrow-body turbofan specialists. Indonesian and Vietnamese budget airlines exhibit highest price sensitivity, while Singapore-based wide-body operators prioritize turnaround reliability over unit cost.
Supply Chain Analysis
CAAC, DGCA, and EASA certification gating concentrates approved component sourcing through Shanghai, Singapore, and Frankfurt logistics hubs. Supply chains draw from titanium alloy forgings, thermal barrier coating precursors, and serialized replacement modules. Single-source vulnerability persists for proprietary engine health monitoring data controlled by Rolls-Royce, Pratt & Whitney, and GE Aerospace. Distribution runs through OEM-authorized logistics hubs consolidating procurement for Chinese-registered fleets under serialized traceability mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder, with DGCA inspection mandates and CAAC documentation requirements structurally expanding authorized MRO demand regardless of fleet growth cycles.
For Market Incumbents: Hedge against OEM intellectual property lock-in by deepening backward integration into component repair capabilities and securing EASA Part-66 certification pipelines in Singapore and Australia. Test-cell infrastructure expansion at Changi anchors capacity for Chinese and Indian wide-body demand, while mobile service deployment addresses Indonesian archipelago geography.
For New Entrants and Emerging Players: Enter via Philippines-based narrow-body turbofan overhaul at Clark Freeport Zone, exploiting European-Asian joint-venture structures and lower labor costs against Singaporean incumbents. Target Indonesian low-cost carrier unbundled procurement as the most penetrable segment, with power-by-the-hour contract structuring as the go-to-market angle.
For Investors and Strategic Acquirers: Valuations sit cheapest among independent repair stations lacking OEM authorization but possessing CAAC or DGCA certification infrastructure. Long-term viability hinges on SAF compatibility testing capability buildout and predictive analytics platform integration. Watch for inflection upon CAAC mandating carbon-accounting embeddedness in overhaul protocols.
| Strategic Initiative | Industry Significance |
|---|---|
| Test-Cell Infrastructure Expansion | SIA Engineering's Changi capacity captures Chinese and Indian wide-body turbofan demand under documentation mandates. |
| Power-by-the-Hour Contract Penetration | Rolls-Royce TotalCare agreements lock sixty percent of regional wide-body hours through cash-flow predictability offerings. |
| Joint-Venture Facility Development | Lufthansa Technik's Clark Freeport Zone extends European technical standards at Southeast Asian labor cost structures. |
| Predictive Maintenance Platform Integration | Real-time thrust degradation signatures compress preventive windows and integrate fleet operations with MRO planning. |
| Sustainable Aviation Fuel Certification | CAAC and EASA carbon-accounting rules embed SAF burn testing into overhaul protocols, creating new revenue lines. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with MRO operations directors, airline fleet managers, CAAC certification officers, and EASA Part-66 training administrators with secondary validation. Bottom-up and top-down triangulation drew from CAAC airworthiness directives, DGCA inspection circulars, airline procurement disclosures, and OEM maintenance contract filings. Cross-referencing fleet utilization data with shop-visit interval compression patterns validated demand modeling.
Segment-weighting approaches distributed value across overhaul, repair, inspection, and modification service types, with turbofan, turboprop, and auxiliary power unit engine categories further disaggregated. Commercial airline, cargo carrier, military operator, and private operator end-use segments were modeled separately. CAGRs were derived from fleet expansion trajectories and regulatory-mandated visit interval compression across the projection horizon. Forecast inputs incorporated thermal barrier coating life extension curves and power-by-the-hour contract penetration rates.
Inputs from CAAC directive filings and DGCA inspection records were available through the study window; gaps in proprietary OEM engine health monitoring data introduce uncertainty bands around independent repair station market share assumptions. Forecasts reflect documented assumptions regarding fleet utilization rates and regulatory enforcement intensity. A model refresh is warranted upon material change in CAAC carbon-accounting rule implementation timelines or SAF compatibility testing mandate scope.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
US Aviation MRO Software Market
Aircraft Maintenance and MRO Solutions
Latin America Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Europe Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
GCC Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
MRO Protective Coatings Market
Aircraft Maintenance and MRO Solutions
Aviation Test Equipment Market
Aircraft Maintenance and MRO Solutions
Wide-Body Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Nigeria Aircraft Maintenance Repair and Overhaul Market
Aircraft Maintenance and MRO Solutions
North America Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Global Aircraft Heavy Maintenance Visits Market
Aircraft Maintenance and MRO Solutions
North America Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
MRO Software Market
Aircraft Maintenance and MRO Solutions
Africa Aviation MRO Market
Aircraft Maintenance and MRO Solutions
Aviation Engine MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Vacuum Cleaners Market
Aircraft Maintenance and MRO Solutions
Aircraft Autoclave Market