
 Global Commercial Aircraft Disassembly Market | 2026-2036
Global Commercial Aircraft Disassembly Market Size, Share, and Industry Trends Forecast 2026-2036
Global Commercial Aircraft Disassembly Market Analysis
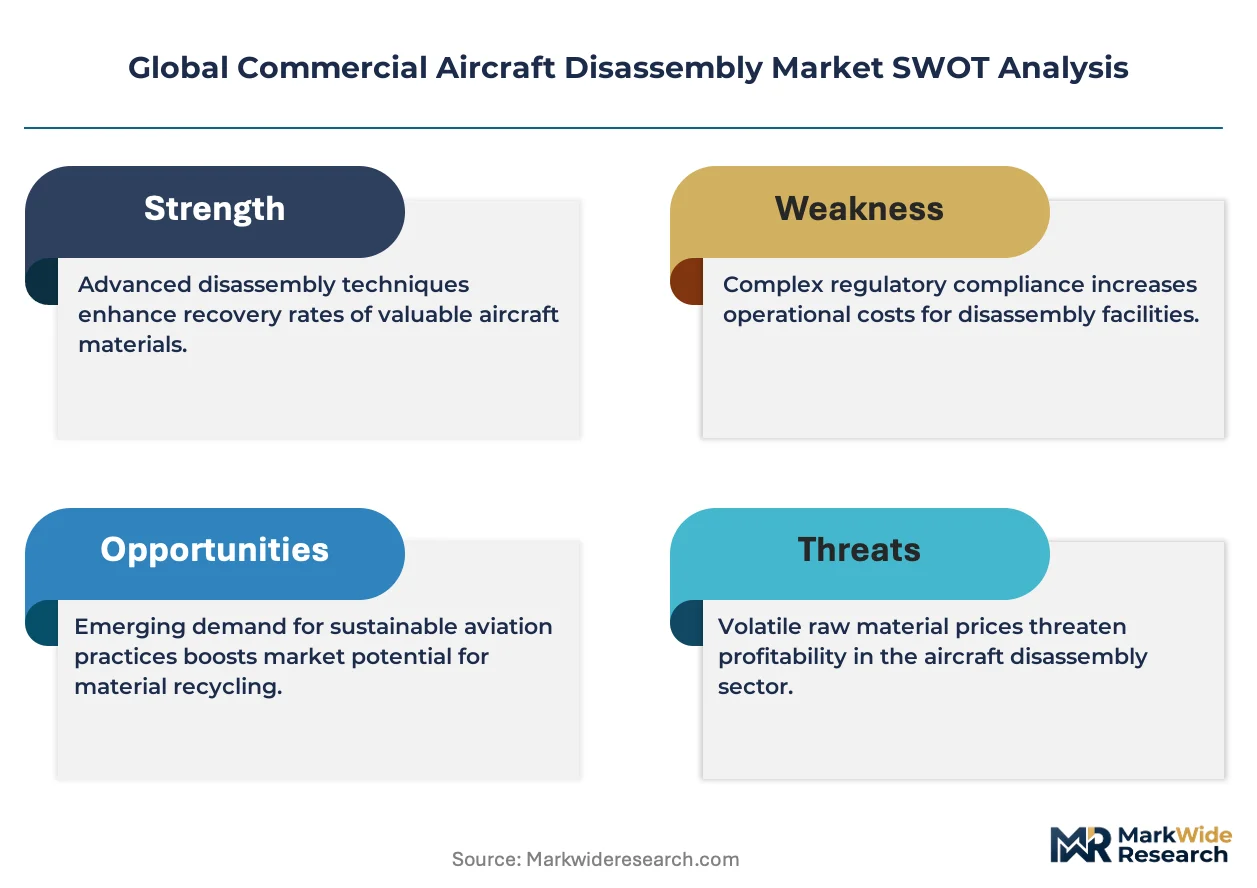
The wide capital-intensity divergence between full-service teardown operators and narrow component traders is rotating competitive dynamics across the Global Commercial Aircraft Disassembly Market. TARMAC Aerosave leverages integrated hangar-and-recycling infrastructure at Tarbes and Teruel to capture value across the entire end-of-life chain. Air Salvage International Limited anchors its position through proprietary logistics networks that sustain rapid airframe transport from retirement sites to UK disassembly yards. AerSale competes by extending aftermarket certification capabilities that position recovered components for immediate return-to-service eligibility.
Commercial aircraft disassembly encompasses the systematic deconstruction of retired airframes to recover reusable components, recyclable materials, and residual fuel systems, typically involving specialized cutting, non-destructive testing, and hazardous material handling protocols governed by airworthiness directives. The primary industrial purpose centers on converting aging aviation assets into certified aftermarket parts and raw material streams that feed MRO networks and secondary manufacturing. Component Recovery services dominate value capture due to engine and avionics part scarcity, while Recycling segments face margin compression from volatile aluminum and titanium scrap pricing. Parts Resale channels sustain premium pricing for rotable components with full traceability documentation, whereas Teardown services compete on volume throughput and labor efficiency metrics.
FAA airworthiness standards govern component recertification eligibility for US-registered recovered parts, while EASA Part 145 regulations shape European MRO provider acceptance of disassembly-sourced materials. REACH chemical restrictions and the EU Green Deal carbon-accounting frameworks are forcing recyclers to document material recovery rates and eliminate landfill disposal of composite structures. Stakeholders must monitor evolving Extended Producer Responsibility proposals from the European Commission that could shift end-of-life liability toward original aircraft manufacturers.
Market Dynamics
The EU Green Deal's carbon-accounting mandates are forcing disassembly operators to certify material recovery rates, compressing margins for recyclers while creating compliance premiums for integrated teardown-to-recycling facilities.
Growth Catalysts
- Narrowbody Fleet Retirement Waves:Aging Boeing 737NG and Airbus A320ceo fleets in the United States generate concentrated feedstock pools that sustain component recovery economics.
- REACH Chemical Compliance:European recyclers must document elimination of landfill disposal for composite structures, accelerating investment in advanced material separation technologies.
- Secondary Parts Demand:MRO networks facing engine and avionics part scarcity are expanding teardown capacity to secure certified aftermarket inventory.
Market Restraints
- Aluminum and Titanium Scrap Volatility:Recycling segments face margin compression from fluctuating commodity metal pricing that undermines fixed-cost recovery models.
- Extended Producer Responsibility Proposals:European Commission initiatives threaten to shift end-of-life liability toward original aircraft manufacturers, creating legal uncertainty for independent disassembly operators.
- Composite Structure Landfill Bans:Technical limitations in thermoset carbon-fiber reclamation force costly alternative disposal routes that erode recycling segment profitability.
Strategic Opportunities
- UK Disassembly Hub Expansion:Proprietary logistics networks enabling rapid airframe transport from retirement sites to centralized yards offer geographic arbitrage for European feedstock.
- Immediate Return-to-Service Certification:Aftermarket certification capabilities that bypass traditional MRO inspection queues command premium pricing from time-sensitive operators.
- Dual Carbon Goals Alignment:China's MEE circular economy targets create regulatory tailwinds for material recovery joint ventures with domestic aviation maintenance providers.
Industry Challenges
- Traceability Documentation Talent Gap:Shortage of personnel capable of generating full chain-of-custody records for rotable components delays parts resale eligibility.
- FAA-EASA Recertification Divergence:Inconsistent airworthiness standards between US and European regulators fragment component marketability and extend compliance timelines.
- Hangar-and-Recycling Integration Capex:Full-service teardown operators require simultaneous investment in specialized cutting equipment and non-destructive testing infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Commercial Aircraft Disassembly Market |
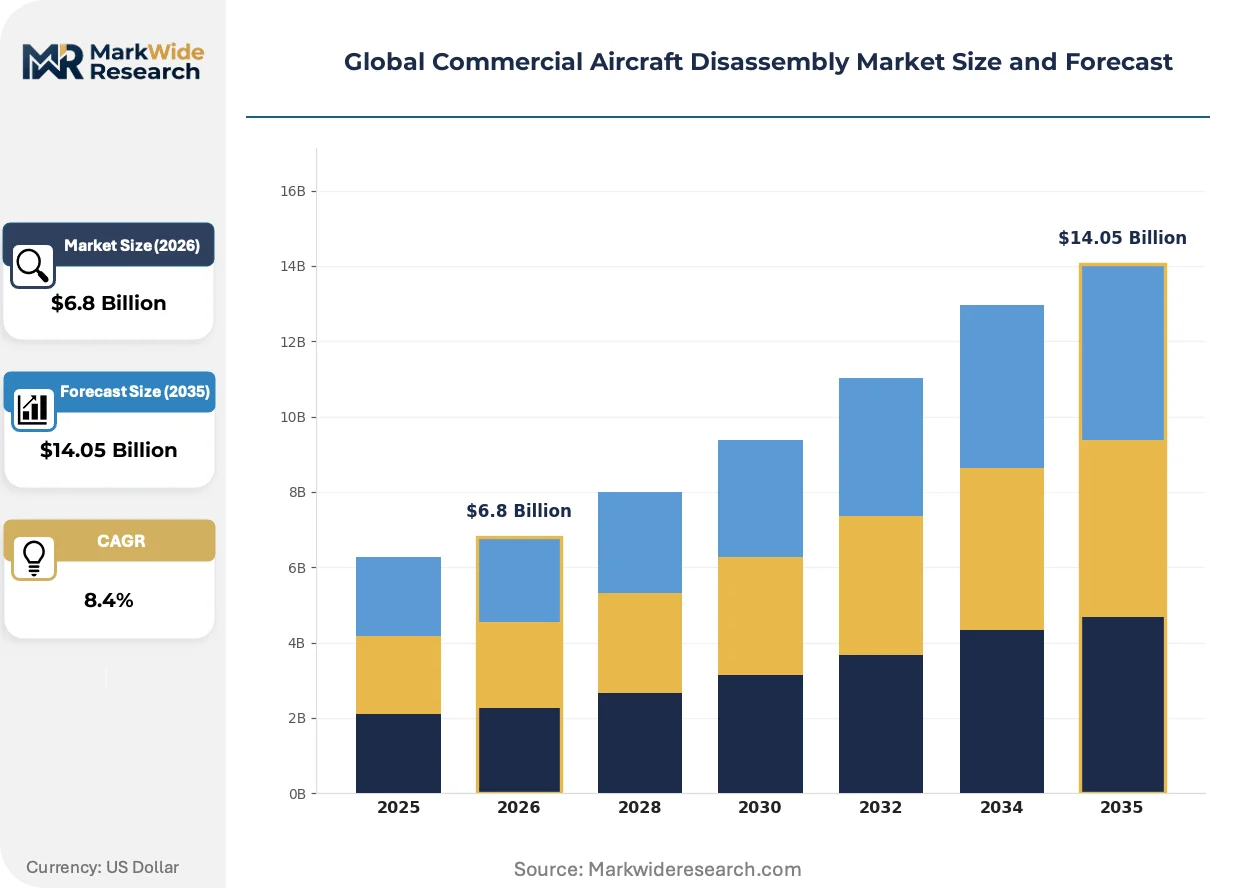
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Teardown, Component Recovery, Recycling, Parts Resale End User: MRO Providers, Airlines, Aircraft Manufacturers, Part Suppliers Process Stage: Disassembly, Decommissioning, Inspection, Material Separation Material Type: Aluminum, Titanium, Composites, Steel |
| Companies Covered | TARMAC Aerosave, Air Salvage International Limited, AerSale, AAR Corp., CAVU Aerospace, GA Telesis, Aircraft End-of-Life Solutions, Lufthansa Technik, eCube Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Commercial Aircraft Disassembly Market Emerging Trajectories
Robotic deconstruction systems and blockchain traceability platforms are compressing teardown cycle times while hardening documentation integrity for secondary parts markets.
Automated abrasive waterjet cutting systems equipped with real-time thickness sensing are supplanting manual plasma cutting in aluminum fuselage sectioning. European disassembly yards at Tarbes and Teruel are deploying these systems at scale. The technology is supplanting labor-intensive manual processes while reducing heat-affected zones that compromise material recyclability.
REACH chemical restrictions and the EU Green Deal carbon-accounting frameworks now require documented material recovery rates and elimination of landfill disposal for composite structures. Recyclers must invest in thermoplastic separation and pyrolysis-based fiber reclamation. German and French operators are consolidating to share compliance infrastructure costs.
Airlines and lessors are unbundling teardown service contracts from traditional asset disposal arrangements, seeking direct relationships with certified component traders. This channel disintermediation bypasses legacy lessor-managed disassembly brokers. The shift is most visible in North American narrowbody retirements where carriers retain title to high-value engine modules.
Global Commercial Aircraft Disassembly Market Segmentation
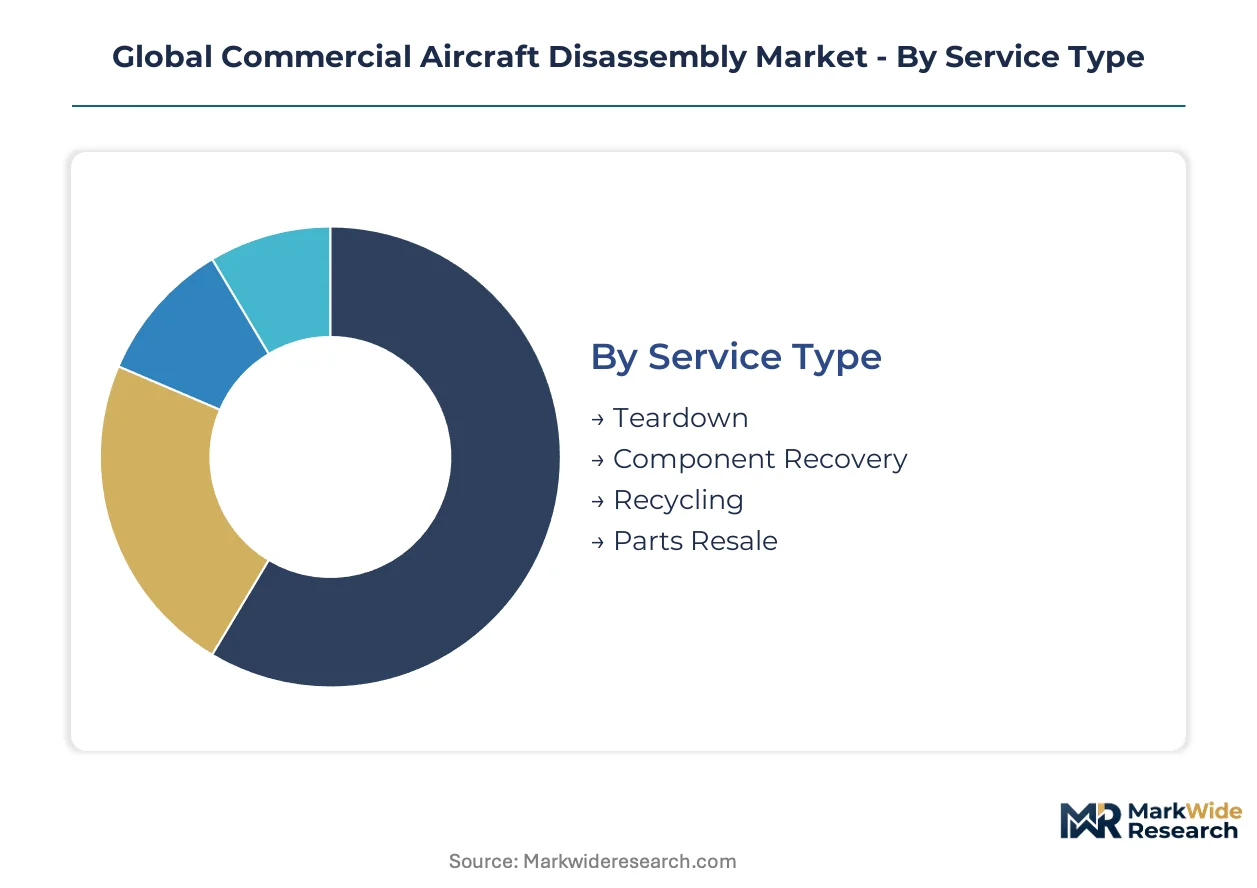
Segmentation in aircraft disassembly reveals how value migrates across distinct operational layers, from labor-intensive teardown execution through high-margin component certification. Margin concentration varies sharply by service complexity and regulatory documentation burden.
Service Type:
Margin pools concentrate in activities requiring specialized airworthiness certification rather than commodity material recovery.
- Teardown:Systematic airframe deconstruction using abrasive waterjet cutting and non-destructive testing protocols. Demand concentrates in United States narrowbody retirements where Boeing 737NG feedstock sustains volume throughput economics.
- Component Recovery:Extraction and documentation of rotable parts with full chain-of-custody records for FAA-EASA recertification. Engine and avionics module scarcity drives premium pricing from MRO providers facing extended OEM lead times.
- Recycling:Material separation and scrap preparation governed by EU Green Deal recovery rate mandates.
- Parts Resale:Certified aftermarket inventory distribution through direct airline and lessor relationships.
Component Recovery holds installed capacity. Teardown is rotating up the share rankings.
End User:
Procurement authority determines contract structure, with asset owners increasingly bypassing traditional lessor-managed brokers.
- MRO Providers:Maintenance networks seeking certified aftermarket parts to circumvent engine and avionics shortages. European EASA Part 145 facilities drive acceptance standardization for disassembly-sourced materials.
- Airlines:Carriers retaining title to high-value modules and unbundling teardown contracts from asset disposal arrangements. North American narrowbody operators lead this channel disintermediation.
- Aircraft Manufacturers:OEMs monitoring Extended Producer Responsibility proposals that could shift end-of-life liability.
- Part Suppliers:Certified traders building direct relationships with disassembly yards for traceable inventory access.
MRO Providers dominate current contract volumes. Airlines are expanding fastest as procurement authority consolidates.
Process Stage:
Documentation intensity escalates through sequential stages, with inspection and material separation commanding specialized labor premiums.
- Disassembly:Physical deconstruction employing robotic abrasive cutting systems with real-time thickness sensing. Tarbes and Teruel facilities deploy these technologies at scale for aluminum fuselage sectioning.
- Decommissioning:Fuel system purge and hazardous material isolation per REACH chemical handling protocols.
- Inspection:Non-destructive testing and airworthiness documentation generation. Talent scarcity for full chain-of-custody record creation delays parts resale eligibility.
- Material Separation:Thermoset carbon-fiber reclamation and pyrolysis-based fiber recovery. Technical limitations force costly alternative disposal routes that erode recycling margins.
Inspection absorbs specialized labor capacity. Material Separation is climbing the fastest as composite landfill bans tighten.
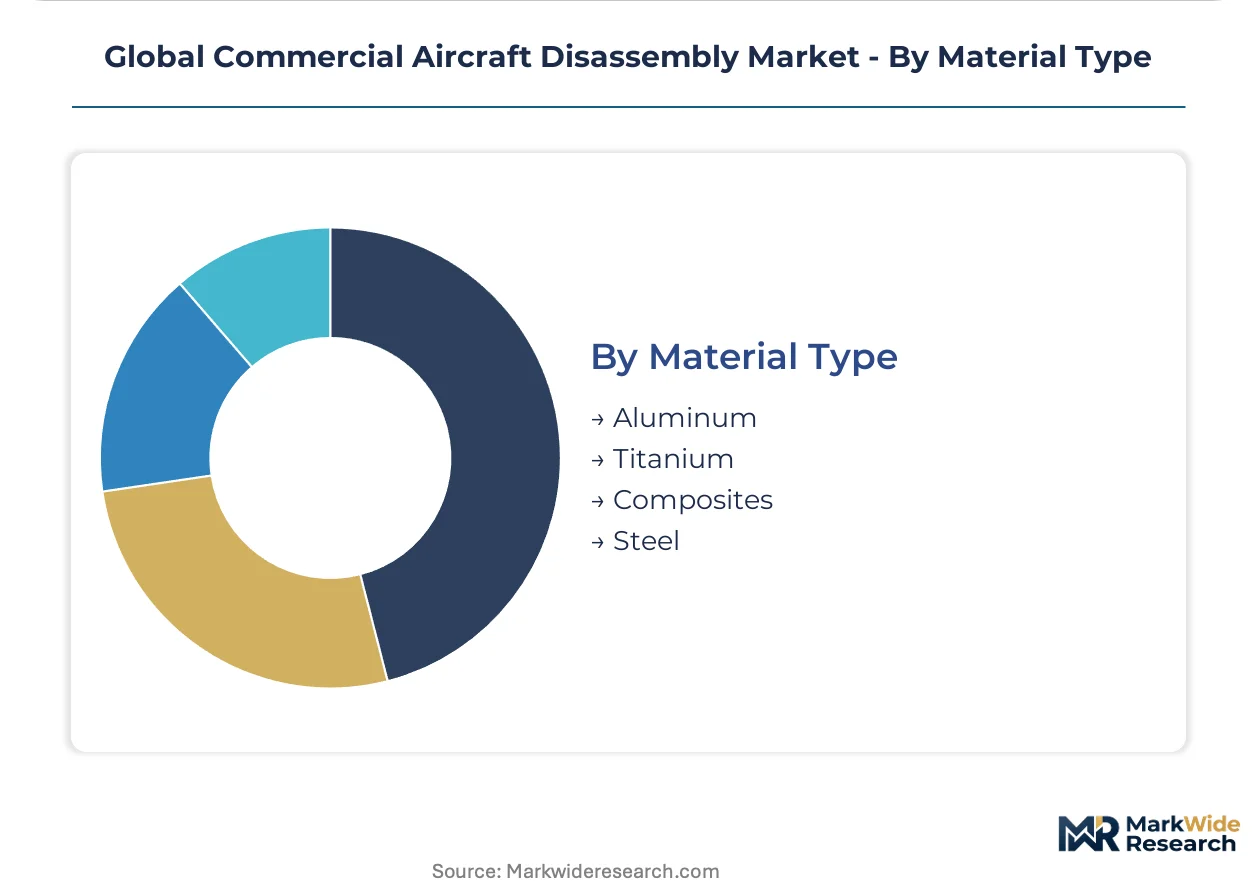
Material Type:
Scrap pricing volatility creates divergent margin stability across metal and advanced material categories.
- Aluminum:Fuselage-grade alloy recovery subject to commodity market fluctuations that undermine fixed-cost recycling models.
- Titanium:High-value engine and landing gear alloy with concentrated demand from aerospace secondary manufacturing.
- Composites:Thermoset carbon-fiber structures requiring pyrolysis or solvolysis reclamation. German and French operators consolidate to share EU Green Deal compliance infrastructure costs.
- Steel:Landing gear and structural component recovery with established ferrous scrap market channels.
Aluminum maintains volume dominance. Composites are gaining share fastest as airframe composition shifts toward carbon-fiber reinforced polymers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in disassembly services tilt toward net outflows from United States feedstock pools toward European and Asian MRO demand centers. Regulatory divergence between FAA and EASA certification standards fragments component marketability across Atlantic trade lanes.
United States
Boeing 737NG and Airbus A320ceo retirements concentrate in Arizona and California desert storage facilities. FAA airworthiness standards govern component recertification eligibility for domestic MRO networks. CAVU Aerospace operates teardown facilities in Arkansas and Illinois serving narrowbody feedstock pools.
Germany
EASA Part 145 regulations shape European acceptance standards for disassembly-sourced materials entering maintenance networks. REACH chemical restrictions mandate documented elimination of composite landfill disposal. Lufthansa Technik anchors industrial capacity in Hamburg and Frankfurt for integrated teardown-to-MRO workflows.
United Kingdom
Proprietary logistics networks enable rapid airframe transport from Mediterranean retirement sites to centralized disassembly yards. Air Salvage International Limited maintains operations at Cotswold Airport processing narrowbody and widebody retirements. UK regulatory alignment with EASA sustains component export eligibility toward continental European MRO providers.
France
EU Green Deal carbon-accounting frameworks require certified material recovery rates from disassembly operators. TARMAC Aerosave leverages integrated hangar-and-recycling infrastructure at Tarbes and Teruel facilities. French recyclers consolidate to share compliance infrastructure costs for thermoset carbon-fiber reclamation.
China
MEE circular economy targets create regulatory tailwinds for material recovery joint ventures with domestic aviation maintenance providers. Dual carbon goals accelerate investment in aluminum and titanium scrap processing capacity. Yangtze River Delta clusters concentrate emerging teardown capacity serving Asia-Pacific MRO demand.
Global Commercial Aircraft Disassembly Market Vendor Landscape
Concentration sits with integrated teardown-to-recycling operators possessing captive hangar infrastructure and certified component trading capabilities. The vendor base spans three tiers: full-service operators controlling end-to-end value chains, specialized component traders leveraging documentation expertise, and regional recyclers competing on material recovery throughput. Strategic moves center on M&A consolidation of logistics networks and backward integration into hazardous material handling certifications.
Among full-service teardown operators, TARMAC Aerosave and Air Salvage International Limited exemplify the integrated infrastructure archetype combining physical disassembly capacity with proprietary airframe transport logistics. AerSale occupies a position bridging teardown execution and immediate aftermarket certification, representing the component-trading specialization vector. These three entities anchor competitive positioning across the Atlantic basin where narrowbody retirement waves concentrate feedstock access.
| Leading Market Players |
|---|
| TARMAC Aerosave |
| Air Salvage International Limited |
| AerSale |
| AAR Corp. |
| CAVU Aerospace |
| GA Telesis |
| Aircraft End-of-Life Solutions |
| Lufthansa Technik |
| eCube Solutions |
| Others |
Supply Flow & Price Mechanics
Robotic abrasive waterjet cutting systems replacing manual plasma cutting in aluminum fuselage sectioning are simultaneously shifting supply geography toward European yards at Tarbes and Teruel while compressing labor cost premiums that previously anchored pricing power in legacy teardown facilities.
Pricing Analysis
Industrial OEM buyers anchor contract structures around long-term offtake agreements for certified rotable components. Price differentiation hinges on full FAA-EASA traceability documentation and immediate return-to-service eligibility versus standard MRO queue timelines. Cost compression in recycling segments is intensifying because aluminum and titanium scrap volatility undermines fixed-cost recovery models. Airlines retaining title to high-value engine modules exhibit lowest price sensitivity, while regional recyclers competing on material throughput face acute margin pressure.
Supply Chain Analysis
Inventory lead times for thermoset carbon-fiber reclamation equipment stretch 18-24 months, constraining rapid capacity response to EU Green Deal mandates. Supply concentrates in the United States for narrowbody feedstock, the United Kingdom for proprietary airframe transport logistics, and France for integrated hangar-and-recycling infrastructure. Raw material flows draw from retired Boeing 737NG and Airbus A320ceo fleets, pyrolysis-based fiber recovery systems, and REACH-compliant chemical handling protocols. Single-source vulnerability sits with German-French consolidations sharing compliance infrastructure costs. Distribution runs through direct airline relationships bypassing legacy lessor-managed brokers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The commercial aircraft disassembly market sits at an early-cycle expansion phase justified by unbundling of teardown contracts from traditional asset disposal arrangements that concentrates procurement authority with asset owners.
For Market Incumbents: Secure captive hangar infrastructure through M&A consolidation of logistics networks in Arizona and California desert storage corridors. Extend backward integration into hazardous material handling certifications to defend against emerging component traders leveraging blockchain traceability platforms. Lock in long-term offtake agreements with MRO providers facing engine and avionics part scarcity. For New Entrants and Emerging Players: Documentation-intensive inspection services where incumbents under-serve present the most penetrable white-space target. Concentrate on thermoset carbon-fiber reclamation joint ventures with German and French operators sharing EU Green Deal compliance costs. Enter through immediate return-to-service certification capabilities that command premium pricing from time-sensitive North American narrowbody operators. For Investors and Strategic Acquirers: The market sits at a capacity-constrained phase that favors integrated teardown-to-recycling operators with proprietary logistics networks. Long-term viability over a 5-10 year window rests on regulatory alignment with Extended Producer Responsibility proposals and REACH chemical restrictions. Watch FAA-EASA recertification convergence as the inflection signal for cross-Atlantic component marketability expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Robotic Decommissioning Deployment | Abrasive waterjet systems at Tarbes and Teruel reduce heat-affected zones compromising aluminum recyclability. |
| Blockchain Traceability Integration | Hardcoded chain-of-custody records accelerate FAA-EASA recertification timelines for rotable engine modules. |
| Pyrolysis Reclamation Joint Venture | German-French consolidation shares EU Green Deal compliance infrastructure costs for thermoset carbon-fiber recovery. |
| Direct Airline Contracting | Bypassing lessor-managed brokers captures margin from unbundled teardown arrangements in North American narrowbody retirements. |
| REACH Certification Investment | Documented elimination of composite landfill disposal sustains recycler operating licenses under ECHA enforcement. |
Methodological Framework
A standing panel of teardown facility operations directors, MRO procurement managers, EASA Part 145 compliance officers, and aviation lessor asset management executives provided ongoing calibration across the study period. Primary interview data combined with secondary validation from FAA airworthiness directives, EASA regulatory filings, EU Green Deal implementation guidelines, and aluminum-titanium scrap commodity exchanges. Bottom-up facility capacity assessments and top-down feedstock availability estimates were triangulated against industry association disclosures.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. The analytical framework modeled segmentation by service type, end user procurement authority, process stage documentation intensity, and material type scrap pricing volatility. CAGRs were derived from compound growth trajectory analysis applied to narrowbody retirement wave schedules and MRO network expansion plans. Forecast inputs incorporated REACH chemical restriction compliance timelines and Extended Producer Responsibility proposal tracking.
Forecasts assume regulatory continuity in FAA airworthiness standards, EASA Part 145 acceptance protocols, and EU Green Deal carbon-accounting frameworks; material policy shifts would require re-modeling. Composite landfill ban enforcement intensity and thermoset reclamation technology cost curves represent specific risk factors that could revise trajectory assumptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Commercial Aircraft Market
Aircraft
Aero Wing Market
Aircraft
Airplane Brackets Market
Aircraft
Global Aircraft Towbars Market
Aircraft
Military Aircraft Market
Aircraft
Global Helicopter Market
Aircraft
Utility Aircraft Market
Aircraft
Evtol (Electric Vertical Takeoff and Landing) Airplane Market
Aircraft
Aircraft Aerostructures Market
Aircraft
Aircraft Radome Market
Aircraft
Special Mission Aircraft Market
Aircraft
Global Aircraft Tugs Market
Aircraft
Afterburner Market
Aircraft
Aircraft Window Frame Market
Aircraft
Asia-Pacific Commercial Aircraft Market
Aircraft
Aeronautic Propeller Market