
 Aircraft Weighing Scales Market | 2026-2036
Aircraft Weighing Scales Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Weighing Scales Market Analysis
Aftermarket service revenue is rewriting margin distribution across the aircraft weighing scales value chain. Intercomp Company leverages its load cell manufacturing depth to capture recurring calibration contracts. Vishay Precision Group sustains technology leadership through strain gauge innovation for high-capacity platforms. General Electrodynamics Corporation anchors its position in military aviation with ruggedized field-deployable systems.
Aircraft weighing scales are precision measurement instruments that determine total aircraft weight and center of gravity through distributed load cell arrays, typically achieving accuracy within 0.1% of rated capacity for platforms exceeding 10,000 kg. These systems serve critical functions in flight safety certification, fuel efficiency optimization, and regulatory compliance for both fixed-wing and rotary aircraft. Digital scales now dominate commercial installations where real-time data integration with maintenance software commands premium positioning. Electronic technology leads new procurement given its superior repeatability and immunity to temperature drift compared to hydraulic alternatives. MRO Services represents the fastest-growing end user segment as third-party maintenance providers expand weighbridge capabilities to capture airline outsourcing contracts.
The FAA mandates periodic weighing under 14 CFR Part 43, while EASA enforces comparable requirements through CS-25 certification standards, collectively shaping product design and documentation protocols. The EU AI Act introduces emerging compliance dimensions for smart scales with embedded diagnostic algorithms, potentially fragmenting certification pathways. Stakeholders must monitor regulatory divergence between FAA and EASA digital certification frameworks when allocating R&D budgets.
Market Dynamics
The FAA's Advisory Circular 120-27E rewrite is forcing fleet operators to replace legacy hydraulic scales with digital platforms capable of real-time data logging, compressing replacement cycles and elevating calibration service intensity.
Growth Catalysts
- 14 CFR Part 43 Mandates:FAA periodic weighing requirements drive replacement demand as aging platforms lose calibration certification, compelling MRO facilities to upgrade distributed load cell arrays.
- Commercial Aviation Fleet Expansion:Narrow-body aircraft deliveries concentrate procurement in the United States, where major carriers anchor weighbridge installation programs at hub maintenance facilities.
- Strain Gauge Innovation:Temperature-compensated sensors eliminate drift errors in high-capacity platforms, enabling precision within 0.1% for rotary aircraft exceeding 10,000 kg.
Market Restraints
- Load Cell Supply Concentration:Precision strain gauge manufacturing concentrates among specialized European and Japanese suppliers, exposing procurement to lead time volatility.
- Aluminum Alloy Price Volatility:Platform construction depends on aerospace-grade aluminum, with input cost swings compressing margins for scale fabricators.
- Hydraulic Scale Substitution Resistance:Military operators retain field-proven hydraulic systems for expeditionary deployment, slowing electronic platform penetration in defense applications.
Strategic Opportunities
- EU AI Act Compliance Pathways:Embedded diagnostic algorithms in smart scales create first-mover advantage for manufacturers securing CE marking under emerging AI device frameworks.
- India MRO Infrastructure Buildout:Greenfield maintenance facilities at Delhi and Mumbai airports lack installed weighbridge capacity, opening direct sales channels for portable electronic platforms.
- Blockchain-Integrated Calibration Records:Immutable service history documentation converges with maintenance software APIs, creating subscription revenue streams for verification services.
Industry Challenges
- Metrology Technician Scarcity:Certified calibration specialists remain concentrated at legacy MRO hubs, constraining third-party provider expansion into secondary airports.
- EASA-FAA Digital Certification Divergence:Competing documentation protocols for software-enabled scales force dual-track R&D investment, extending product launch timelines.
- Legacy System Integration Complexity:Proprietary data formats in incumbent maintenance management systems resist API connectivity, requiring custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Weighing Scales Market |
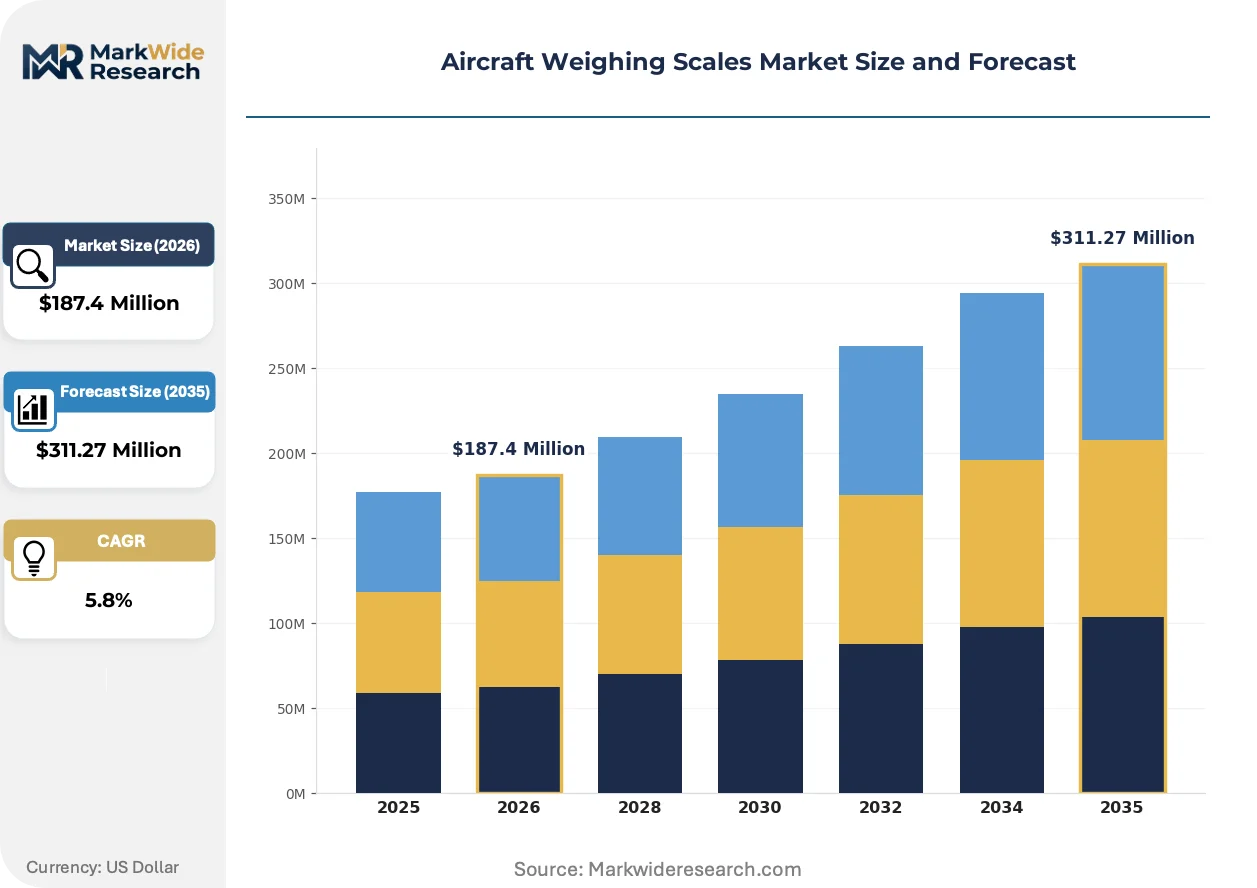
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Scales, Mechanical Scales, Load Cells, Weighbridges Technology: Hydraulic, Pneumatic, Electronic, Ultrasonic End User: Commercial Aviation, Military Aviation, MRO Services, Cargo Handling Capacity: Below 1000 kg, 1000-5000 kg, 5000-10000 kg, Above 10000 kg |
| Companies Covered | Intercomp Company, Vishay Precision Group, General Electrodynamics Corporation, Henk Maas Weegschalen BV, Jackson Aircraft Weighing Systems LLC, Langa Industrial, Teknoscale OY, Alliance Scale, Nicol Scales & Measurement, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Weighing Scales Market Emerging Trajectories
Digital weighing platforms are compressing total cost of ownership through predictive maintenance algorithms and cloud-connected diagnostics, shifting vendor revenue toward recurring service contracts.
Wireless load cell networks are migrating from hardwired analog systems to Bluetooth-enabled distributed architectures. Regional carriers operating turboprop fleets adopt these platforms fastest, drawn by reduced installation downtime. The technology is migrating from commercial aviation into general aviation hangars, compressing price points for entry-level systems.
EASA's CS-25 certification standards now explicitly address software validation for electronic weighing systems, mirroring FAA digital documentation requirements. This regulatory convergence forces manufacturers to harmonize quality management systems across both jurisdictions. MRO providers in Germany and France face accelerated compliance deadlines for smart scale deployments.
Airline procurement departments now unbundle after-sales service from hardware acquisition, pitting specialized calibration firms against original equipment manufacturers for long-term contracts. Third-party maintenance providers capture this disintermediation opportunity through fixed-price multi-year service agreements. The shift is most visible in the United States, where major carriers outsource weighbridge operations to independent MRO specialists.
Aircraft Weighing Scales Market Segmentation
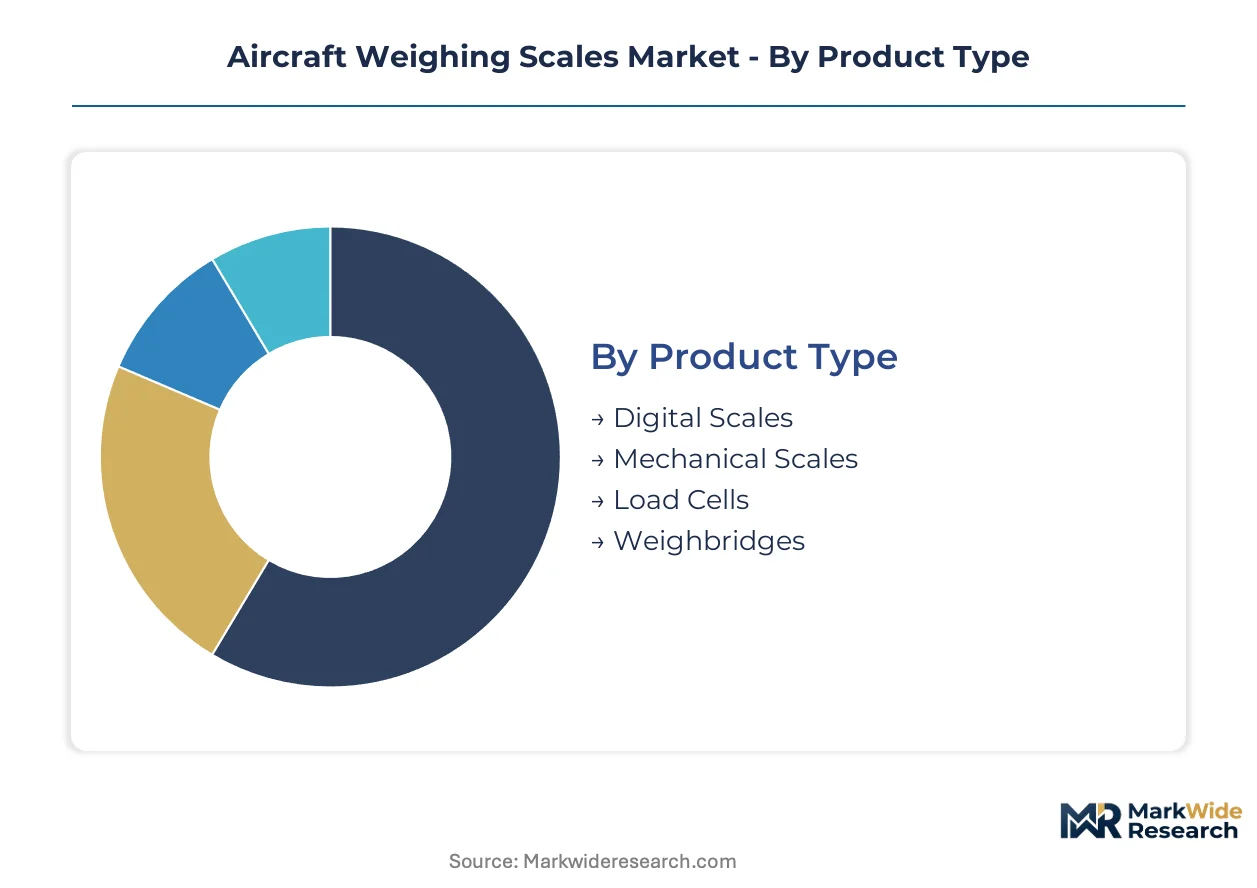
Aircraft weighing scales serve divergent operational profiles across aviation subsectors. Procurement patterns cluster around calibration intensity, platform durability requirements, and integration complexity with legacy maintenance systems.
Product Type:
After-sales service intensity varies dramatically across product categories, with distributed load cell arrays demanding recurring calibration contracts while mechanical platforms require minimal field support.
- Digital Scales:Real-time data logging platforms integrate with maintenance management software through standardized APIs. Commercial carriers at US hub facilities drive procurement as FAA Advisory Circular 120-27E mandates electronic documentation for weight-and-balance records.
- Load Cells:Strain gauge assemblies constitute the precision measurement core, typically achieving accuracy within 0.1% of rated capacity. Temperature-compensated variants command premium positioning for rotary aircraft operations in Arizona and Oklahoma MRO corridors.
- Mechanical Scales:Legacy hydraulic platforms persist in military expeditionary deployments where field reliability trumps data connectivity.
- Weighbridges:Fixed-installation systems anchor major maintenance hangars at Dallas-Fort Worth and Phoenix Sky Harbor.
Digital scales hold the largest share; momentum sits with load cells as modular replacement cycles accelerate.
Technology:
Platform selection tracks directly against environmental exposure, with temperature drift tolerance and electromagnetic immunity determining specification choices for outdoor versus hangar-based operations.
- Electronic:Strain gauge-based systems with Bluetooth-enabled distributed architectures eliminate hardwired installation downtime. Regional turboprop operators adopt these platforms fastest, compressing deployment timelines at secondary airports.
- Hydraulic:Fluid-pressure measurement systems retain dominance in expeditionary military applications where electromagnetic hardening and mechanical simplicity outweigh data integration benefits.
- Pneumatic:Air-actuated platforms serve specialized general aviation hangars with limited electrical infrastructure.
- Ultrasonic:Non-contact measurement technology remains experimental for aircraft applications, constrained by surface irregularity compensation challenges.
Electronic technology commands the installed base; pneumatic systems are climbing the fastest as retrofit economics improve for legacy facilities.
End User:
Customer procurement sophistication spans from standardized fleet-wide tenders to fragmented spot purchasing, with contract duration and service bundling terms varying sharply across segments.
- MRO Services:Third-party maintenance providers expand weighbridge capabilities to capture airline outsourcing contracts, with independent specialists at Oklahoma City and Goodyear, Arizona disintermediating original equipment manufacturers for long-term calibration agreements.
- Commercial Aviation:Major carriers unbundle after-sales service from hardware acquisition, pitting specialized calibration firms against scale manufacturers for multi-year fixed-price contracts.
- Military Aviation:Defense operators prioritize ruggedized field-deployable systems with expeditionary logistics compatibility over precision specifications.
- Cargo Handling:Freight operators at Memphis and Louisville hubs deploy high-capacity platforms for freighter weight verification.
MRO Services holds the largest share; Commercial Aviation is gaining share fastest as fleet expansion intensifies weighbridge installation programs.
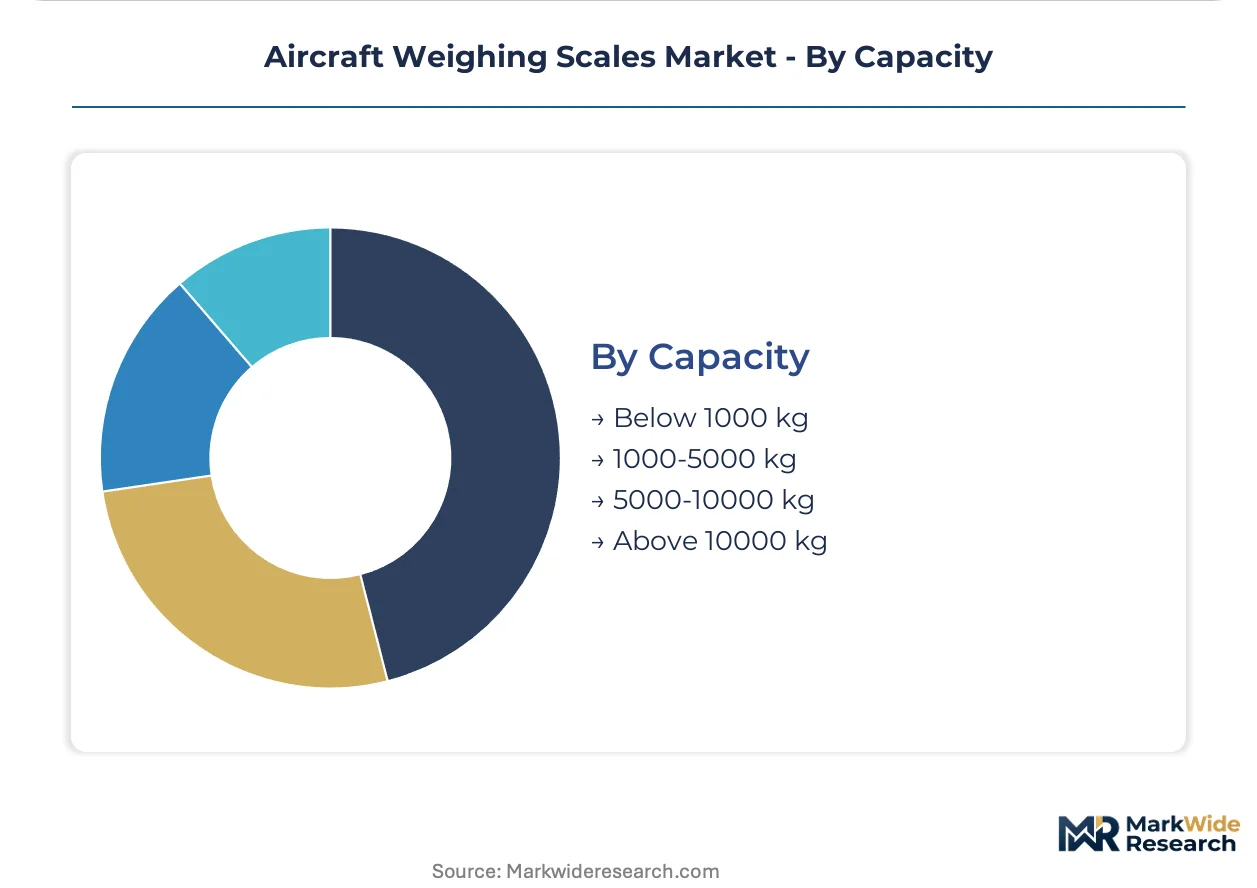
Capacity:
Platform sizing correlates with aircraft category and operational throughput, with narrow-body maintenance driving mid-range specifications and rotary operations fragmenting demand across lower capacity tiers.
- Above 10000 kg:High-capacity platforms serve wide-body and freight aircraft at major hub facilities, requiring distributed load cell arrays with redundant measurement channels for regulatory compliance.
- 5000-10000 kg:Narrow-body aircraft concentrate procurement in this range, with US carriers anchoring installation programs at Dallas and Phoenix maintenance centers.
- 1000-5000 kg:Regional turboprop and business jet operations drive demand for portable electronic platforms with rapid deployment characteristics.
- Below 1000 kg:General aviation and unmanned aerial system applications populate this segment, with price-sensitive buyers compressing margin structures.
5000-10000 kg holds the largest share; 1000-5000 kg shows the steepest expansion trajectory as regional fleet modernization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision strain gauge manufacturing concentrates among specialized European and Japanese suppliers, while MRO infrastructure buildout drives procurement across North American hub facilities. Fleet expansion mandates and regulatory compliance deadlines reshape regional demand patterns.
United States
Narrow-body aircraft deliveries concentrate procurement at Dallas-Fort Worth and Phoenix Sky Harbor maintenance centers. FAA Advisory Circular 120-27E mandates electronic documentation for weight-and-balance records, compressing replacement cycles for legacy hydraulic platforms. Oklahoma City and Goodyear, Arizona anchor independent MRO specialist corridors disintermediating original equipment manufacturers for calibration contracts.
Germany
EASA CS-25 certification standards now explicitly address software validation for electronic weighing systems, forcing harmonized quality management across jurisdictions. MRO providers in Hamburg and Frankfurt face accelerated compliance deadlines for smart scale deployments. The country's precision sensor fabricators supply temperature-compensated strain gauge assemblies to rotary aircraft operators.
China
Domestic aviation fleet expansion drives weighbridge installation programs at Beijing and Shanghai maintenance facilities. GB standards for measurement instrumentation converge with international metrology protocols, streamlining certification for imported electronic platforms. Yangtze River Delta manufacturing clusters produce aluminum alloy platform components for regional export markets.
India
Greenfield MRO facilities at Delhi and Mumbai airports lack installed weighbridge capacity, opening direct sales channels for portable electronic platforms. Directorate General of Civil Aviation mandates align with FAA periodic weighing requirements under 14 CFR Part 43 equivalents. Karnataka and Maharashtra industrial corridors attract calibration service providers establishing regional technical centers.
Japan
METI industrial standards for precision measurement equipment shape procurement specifications for domestic carriers. Strain gauge innovation from Nagoya and Osaka manufacturing clusters feeds global supply chains for high-capacity platforms. Tokyo and Kansai hub airports deploy redundant measurement channel systems for wide-body maintenance compliance.
Aircraft Weighing Scales Market Vendor Landscape
Load cell specialists and platform integrators split the market between component supply and system assembly. Consolidation pressure concentrates among mid-tier fabricators as calibration service bundling reshapes procurement economics. Three archetypes dominate: precision sensor manufacturers with captive metrology capabilities, MRO-anchored system integrators with regional service networks, and defense-focused ruggedization specialists. Capacity expansion and strategic partnerships constitute the dominant competitive moves as vendors secure aluminum alloy supply agreements and calibration technician training pipelines.
Within the precision sensor tier, Intercomp Company and Vishay Precision Group exemplify manufacturers leveraging strain gauge depth to capture recurring calibration contracts. General Electrodynamics Corporation occupies a position among ruggedization specialists serving military aviation requirements. Henk Maas Weegschalen BV and Jackson Aircraft Weighing Systems LLC represent regional platform integrators with established MRO service relationships. Langa Industrial and Teknoscale OY sit within the European specialist segment, while Alliance Scale and Nicol Scales & Measurement anchor North American distribution and service networks.
| Leading Market Players |
|---|
| Intercomp Company |
| Vishay Precision Group |
| General Electrodynamics Corporation |
| Henk Maas Weegschalen BV |
| Jackson Aircraft Weighing Systems LLC |
| Langa Industrial |
| Teknoscale OY |
| Alliance Scale |
| Nicol Scales & Measurement |
| Others |
Supply Flow & Price Mechanics
Nagoya and Osaka manufacturing clusters anchor global strain gauge supply, with their capacity utilization rates directly transmitting to downstream platform pricing power for electronic aircraft weighing systems. Temperature-compensated sensor availability compresses lead time premiums for MRO providers in Arizona and Oklahoma corridors, while aluminum alloy input cost swings force platform fabricators into quarterly price renegotiations with airline procurement departments.
Pricing Analysis
FAA Advisory Circular 120-27E dictates the pricing tier structure across the aircraft weighing scales market. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked smart scales with embedded diagnostics from basic electronic platforms and legacy hydraulic systems. Certification grade and after-sales service bundling drive price differentiation, with calibration-inclusive contracts commanding substantial premiums over hardware-only transactions. Cost compression in the standard tier is intensifying because airline procurement departments now unbundle service from acquisition, forcing manufacturers to compete on platform-only economics. Regional turboprop operators exhibit highest price sensitivity, while major US carriers with outsourced MRO contracts show lowest sensitivity due to fixed-price multi-year agreements.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk assessment for aircraft weighing platform manufacturers. Precision strain gauge manufacturing concentrates in Japan, Germany, and the United States, while aerospace-grade aluminum alloy supply draws from Chinese and Russian smelters subject to trade policy volatility. Single-source vulnerability in temperature-compensated sensor supply exposes procurement to lead time volatility when Nagoya facilities operate at capacity. Distribution runs through authorized MRO service networks at Dallas-Fort Worth, Phoenix Sky Harbor, and Oklahoma City hub facilities, with direct sales channels penetrating greenfield installations at Delhi and Mumbai airports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified metrology technician scarcity constrains third-party MRO expansion and creates defendable positioning for incumbents with captive calibration training pipelines. The gap between FAA and EASA digital certification requirements fragments R&D investment and elevates compliance costs for manufacturers lacking harmonized quality management systems.
For Market Incumbents: Insulate recurring revenue streams by deepening calibration service contracts with independent MRO specialists at Oklahoma City and Goodyear, Arizona corridors. Acquire or partner with European strain gauge fabricators to secure temperature-compensated sensor supply against Japanese supplier concentration. Invest in dual-track FAA-EASA software validation capabilities ahead of regulatory divergence hardening, as emerging entrants without certification depth face extended product launch timelines. For New Entrants and Emerging Players: Build out portable electronic platform offerings targeting India's greenfield MRO infrastructure at Delhi and Mumbai airports, where installed weighbridge capacity remains underdeveloped. Establish calibration service partnerships with Karnataka and Maharashtra technical training centers to address metrology technician scarcity. Pursue fixed-price multi-year service agreements with regional turboprop operators as the most penetrable segment, leveraging Bluetooth-enabled distributed architectures to compress installation downtime against incumbent hardwired systems. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision sensor manufacturers with captive metrology capabilities and established airline calibration relationships. Long-term viability rests on software-enabled diagnostic platforms with recurring service revenue models displacing transactional hardware sales. Target acquisition archetypes include regional platform integrators with MRO-anchored service networks in Germany and France facing accelerated EASA CS-25 compliance deadlines. Monitor FAA-EASA digital certification harmonization progress as the signal indicating whether dual-track R&D investment burdens persist or consolidate competitive advantage for harmonized vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Service Contract Expansion | Captures recurring revenue from airline outsourcing contracts at US hub MRO facilities. |
| Dual-Track Certification Investment | Harmonizes FAA-EASA software validation to accelerate product launch timelines. |
| Strain Gauge Supply Partnership | Secures temperature-compensated sensor access against Japanese supplier concentration. |
| Portable Platform Development | Addresses greenfield MRO infrastructure gaps at Delhi and Mumbai airports. |
| Blockchain Calibration Records Integration | Creates subscription verification services through immutable maintenance history APIs. |
Methodological Framework
The analysis maps digital scale platforms, load cell assemblies, mechanical systems, and weighbridge installations, each validated through MRO operations directors, airline procurement managers, calibration service technicians, and precision sensor manufacturing engineers. Primary interviews with these stakeholders combined with secondary validation against FAA Advisory Circular documentation, EASA CS-25 certification standards, EU AI Act device frameworks, and customs trade data for aluminum alloy and strain gauge imports. Bottom-up triangulation across installed base estimates and top-down verification against MRO infrastructure investment flows anchored market sizing.
Forecasts assume stable regulatory enforcement intensity across FAA and EASA jurisdictions, with aluminum alloy price volatility and strain gauge supplier capacity treated as exogenous stress variables. Segmentation dimensions modeled include product type, technology architecture, end-user procurement sophistication, and aircraft capacity tier alongside regional MRO infrastructure maturity. CAGRs derived from weighted average of historical replacement cycle compression, fleet expansion trajectories, and compliance deadline acceleration. Forecast inputs incorporated narrow-body delivery schedules and periodic weighing mandate enforcement patterns.
Stress conditions across aluminum alloy price bands, strain gauge lead time volatility, and metrology technician availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions of continued regulatory divergence between FAA and EASA digital certification pathways, with revision triggers including harmonization agreements or AI Act enforcement delays. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Middle-East Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Washing Systems Market
Aircraft Maintenance and MRO Solutions
Aircraft Line Maintenance Market
Aircraft Maintenance and MRO Solutions
Air Transport MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Weight Scale Market
Aircraft Maintenance and MRO Solutions
Colombia Commercial Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Business Jet Mro Market
Aircraft Maintenance and MRO Solutions
Military Aviation Repair Solutions Market
Aircraft Maintenance and MRO Solutions
Aviation Maintenance Software Market
Aircraft Maintenance and MRO Solutions
Aircraft Towing Equipment Market
Aircraft Maintenance and MRO Solutions
Aviation Maintenance Repair and Overhaul MRO Software Market
Aircraft Maintenance and MRO Solutions
Aircraft Wheel Bead Breakers Market
Aircraft Maintenance and MRO Solutions
Global Aircraft Heavy Maintenance Visits Market
Aircraft Maintenance and MRO Solutions
Global Aircraft Refurbishing Market
Aircraft Maintenance and MRO Solutions
Commercial Aircraft Disassembly Dismantling and Recycling Market
Aircraft Maintenance and MRO Solutions
Aircraft Storage, Preservation and Reactivation Services Market