
 Collapsible Tube Packaging Market | 2026-2036
Collapsible Tube Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Collapsible Tube Packaging Market Intelligence
Asset-light contract manufacturing models are narrowing the capital investment required for market entry, intensifying competition among specialized producers. Amcor leverages its extensive global manufacturing footprint and R&D capabilities to serve multinational personal care brands. In contrast, Berry Global specializes in high-volume plastic tube production for the food and household goods sectors. Montebello Packaging differentiates through its focus on high-purity aluminum tubes for pharmaceutical and specialty industrial applications.
Collapsible tube packaging is a flexible container, typically cylindrical with a sealed end, designed to dispense viscous products upon squeezing. These tubes often feature multi-layer laminate constructions or aluminum barriers to protect sensitive contents from oxygen, moisture, and light. Their primary purpose is the controlled, hygienic dispensing of gels, creams, and pastes. Laminated tubes represent the fastest-growing product type for pharmaceuticals, while cost-effective plastic tubes continue to dominate the personal care segment.
Product safety and material composition are governed by stringent global regulations. The US FDA sets standards for materials in direct contact with food and drugs, while the EU's REACH regulation restricts specific chemical substances in packaging components. These frameworks compel manufacturers to validate raw material supply chains and invest in compliance testing. Stakeholders must prioritize material innovations that meet sustainability targets without compromising product protection requirements.
Market Dynamics
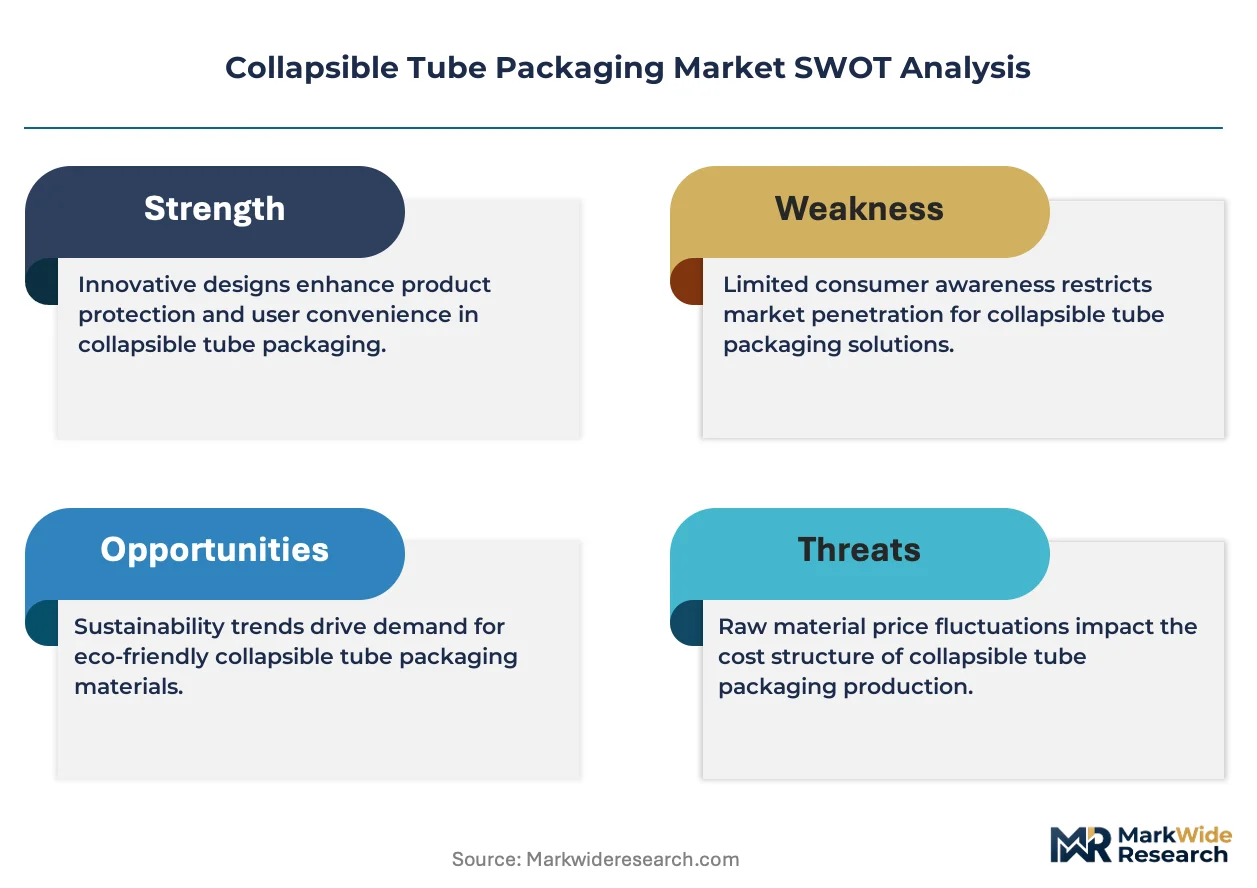
The central dynamic is the collision between sustainability mandates demanding mono-material solutions and product protection requirements for sensitive formulations. This tension drives material science innovation and redefines packaging design priorities for pharmaceutical and personal care applications.
Growth Catalysts
- EU Green Deal Framework:Mandates for increased post-consumer recycled (PCR) content and improved recyclability are accelerating the adoption of mono-material tubes in Europe.
- Pharmaceutical Dispensing:The pharmaceutical sector's demand for precise, hygienic, and tamper-evident dispensing for topical medications and ointments stimulates growth for specialized tube designs.
- Indian CMO Growth:India's expanding role as a contract manufacturing hub for global pharmaceutical companies drives regional demand for compliant packaging solutions.
Market Restraints
- Input Cost Volatility:Fluctuations in the price of raw materials like aluminum and polymer resins create margin pressure and complicate long-term supply contracts.
- Substitution from Airless Pumps:In the premium cosmetics segment, airless pump dispensers pose a substitution threat by offering superior product evacuation and protection from oxidation.
- Recyclability Hurdles:The multi-layer composition of many high-barrier laminate tubes makes them difficult to process in standard municipal recycling streams, creating end-of-life challenges.
Strategic Opportunities
- Mono-Dose Formats:Developing single-use or travel-sized tubes caters to consumer demand for convenience and sampling, opening new avenues in the beauty and hospitality sectors.
- Bio-Based Plastics:Commercializing tubes made from renewable resources, such as sugarcane-derived polyethylene, offers a path to improve sustainability metrics and appeal to eco-conscious brands.
- Southeast Asia Expansion:Growing disposable incomes and the expansion of modern retail and healthcare infrastructure in countries like Vietnam and Indonesia present untapped geographic markets.
Industry Challenges
- Regulatory Compliance Burden:Adhering to divergent chemical substance regulations, such as the EU's REACH and individual US state-level restrictions, requires significant investment in testing and documentation.
- High-Speed Line Capex:The capital expenditure for advanced co-extrusion and lamination lines capable of producing sophisticated multi-layer barrier tubes is a significant barrier for smaller producers.
- PCR Resin Validation:Securing a consistent supply of high-quality post-consumer recycled resin that meets stringent safety standards for food and drug contact remains a major operational hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Collapsible Tube Packaging Market |
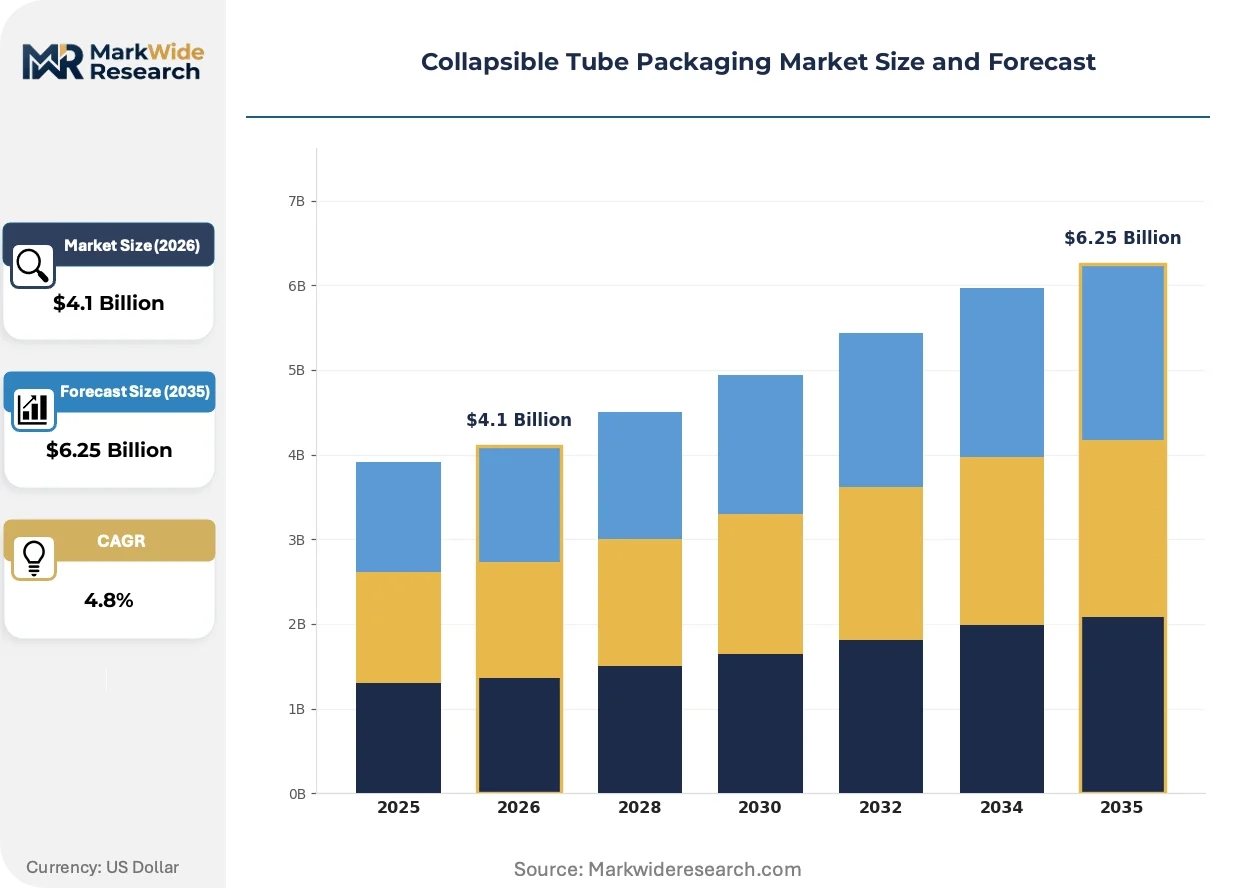
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $6.25 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Tubes, Aluminum Tubes, Laminated Tubes, Other Materials End User: Personal Care, Pharmaceuticals, Food & Beverage, Household Products Closure Type: Screw Caps, Flip Top Caps, Nozzle Caps, Others Production Method: Extrusion, Injection Molding, Blow Molding, Other Techniques |
| Companies Covered | Essel Propack, Sonoco Products Company, Berry Global, Montebello Packaging, Constantia Flexibles, Amcor, Albea Group, VisiPak, CCL Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Collapsible Tube Packaging Market Strategic Shifts & Innovations
Material science advancements are fundamentally reconfiguring the market, balancing environmental pressures with the need for high-performance barrier protection. This evolution is most apparent in the push for circular materials without compromising the shelf life of sensitive contents.
Multi-layer laminate constructions combine different polymers and thin foil layers to create a highly protective barrier. The pharmaceutical and premium cosmetic sectors are rapidly adopting these for oxygen-sensitive and active ingredient formulations. This technology is hybridizing material science, blending the impermeability of aluminum with the tactile feel and printability of plastic.
The European Union’s Packaging and Packaging Waste Regulation (PPWR) introduces stringent design-for-recycling criteria and recycled content mandates. This directive effectively curtails the use of certain complex multi-material structures common in tube packaging. Consequently, manufacturers supplying the EU personal care market are accelerating the transition to mono-material PE and PP tube solutions.
A pronounced shift toward direct-to-consumer (DTC) e-commerce models alters packaging design priorities for many brands. This channel requires tubes that are durable enough for individual shipment while also offering premium unboxing experiences. This change is most evident within the North American and European specialty cosmetics and personal care segments.
Collapsible Tube Packaging Market Segmentation
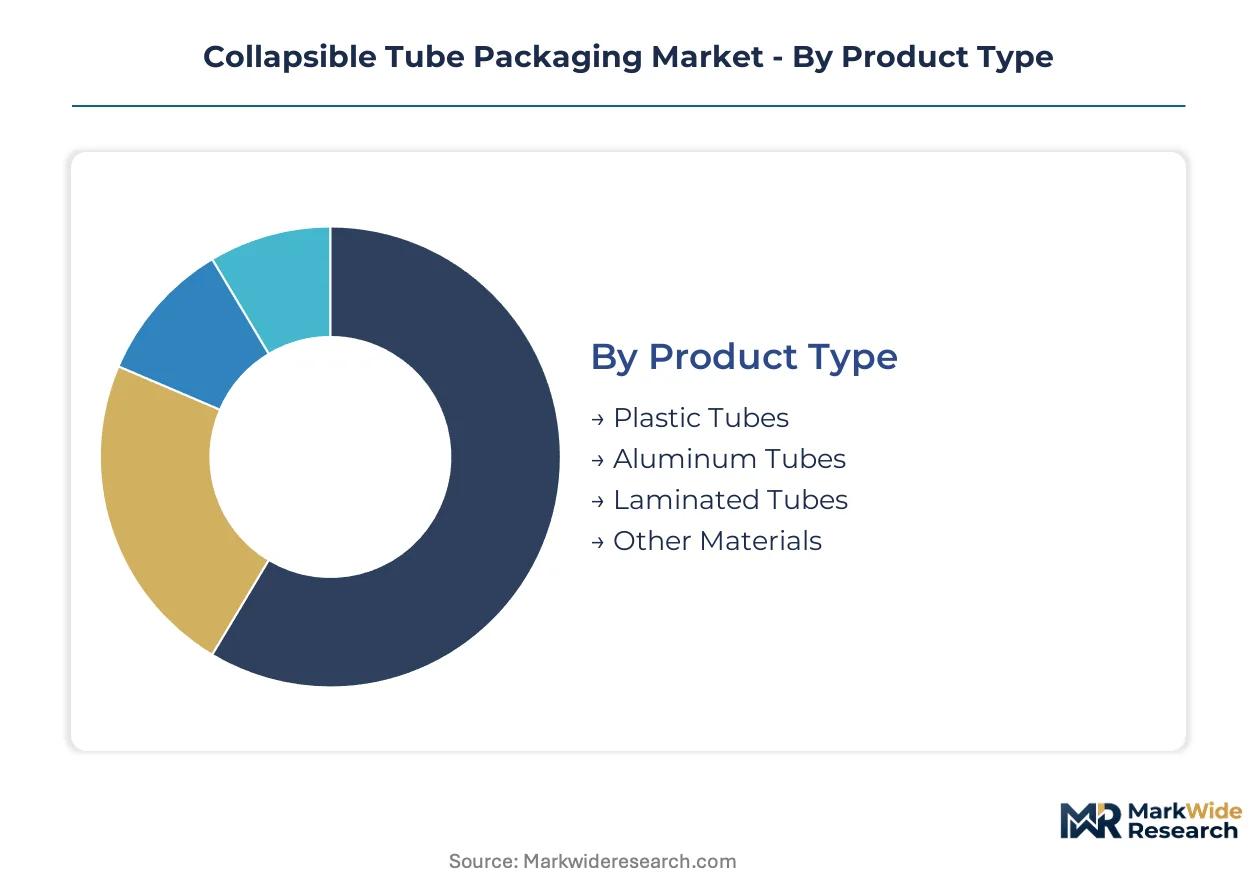
Market segmentation provides a critical framework for understanding the diverse applications and technological requirements within the collapsible tube packaging industry. Material science advancements and evolving regulatory landscapes drive distinct demands across various product categories and end-user sectors. Analyzing these segments reveals specific growth drivers and competitive dynamics influencing market participants.
Product Type:
The spectrum of product applications dictates the choice of material for collapsible tubes, influencing barrier properties and cost. Each material type offers unique advantages in terms of protection, aesthetics, and recyclability, catering to specific market needs.
- Plastic Tubes:These tubes, primarily made from polyethylene (PE) and polypropylene (PP), offer cost-effectiveness, flexibility, and excellent printability. The personal care segment extensively utilizes plastic tubes for high-volume products like lotions and creams due to their economic production and tactile properties.
- Laminated Tubes:Comprising multiple layers of plastic and often an aluminum barrier, these tubes provide superior protection against oxygen, moisture, and light. The pharmaceutical sector and premium cosmetic brands adopt laminated tubes for sensitive active ingredient formulations, ensuring product integrity and extended shelf life.
- Aluminum Tubes:Constructed from high-purity aluminum, these tubes offer an impermeable barrier, safeguarding contents from external contaminants and UV light. Pharmaceutical topical medications and specialized industrial lubricants frequently employ aluminum tubes for their complete barrier properties and sterility.
- Other Materials:This category includes tubes made from bio-based plastics like sugarcane-derived polyethylene, catering to brands focused on improved sustainability metrics.
The dominant share belongs to Plastic Tubes, while Laminated Tubes is closing the gap fastest.
End User:
Diverse industry applications drive distinct demands for tube design, material composition, and dispensing mechanisms.
- Pharmaceuticals:This sector requires precise, hygienic, and tamper-evident dispensing for topical medications, ointments, and gels. Stringent regulations from bodies like the US FDA and Europe's EMA mandate high material purity and barrier protection for these critical applications.
- Personal Care:The personal care segment utilizes collapsible tubes for a wide array of products including cosmetics, oral care, and skincare. Cost-effectiveness, aesthetic appeal, and consumer convenience are primary drivers, often favoring plastic and laminate constructions.
- Food & Beverage:Tubes in this segment protect perishable contents from spoilage, extending shelf life for products like condensed milk, sauces, and condiments. Portion control and hygienic dispensing are key benefits for food applications.
- Household Products:This category includes tubes for adhesives, polishes, and cleaning agents, demanding durability and chemical resistance.
Personal Care holds the largest volume, while the Pharmaceutical sector exhibits the steepest expansion trajectory.
Closure Type:
Consumer convenience and product integrity shape the selection of closure types for various collapsible tube applications.
- Screw Caps:These caps provide a secure, tight seal, preventing leakage and maintaining product freshness, often with tamper-evident features. Pharmaceutical products and industrial adhesives frequently use screw caps for their reliability and robust protection.
- Flip Top Caps:Offering single-handed operation and ease of use, flip top caps are popular in the personal care and cosmetic segments. Their design enhances consumer convenience for products requiring frequent access, such as shampoos and facial cleansers.
- Nozzle Caps:Designed for controlled and precise dispensing, nozzle caps are ideal for specialty products requiring targeted application. Adhesives, eye creams, and certain pharmaceutical gels benefit from the accuracy provided by nozzle caps.
- Others:This category encompasses child-resistant closures, tamper-evident seals, and custom dispensing mechanisms tailored for specific product requirements.
Screw Caps maintain a foundational market presence, with Flip Top Caps gaining consumer preference across many segments.
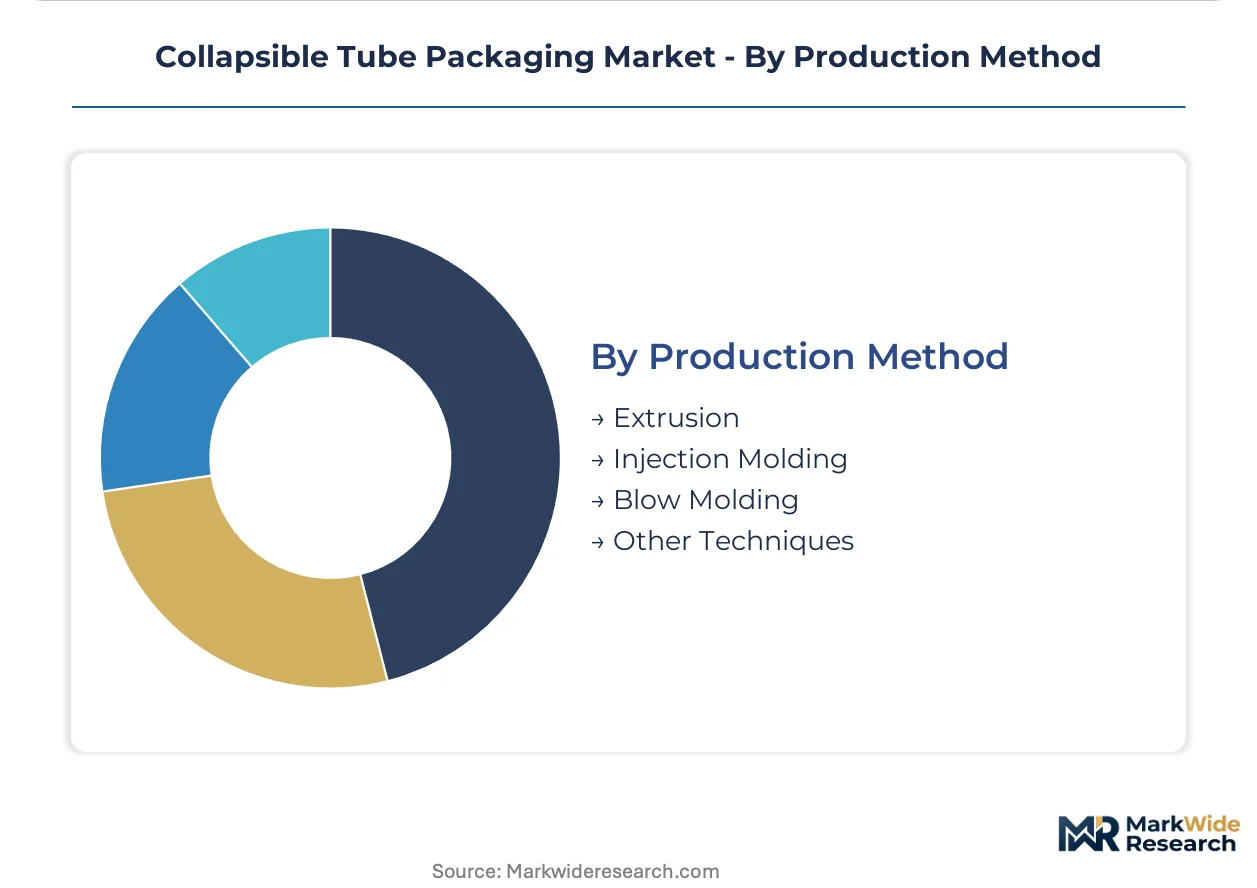
Production Method:
The manufacturing complexity and desired material properties determine the appropriate production method for collapsible tubes.
- Extrusion:This continuous process is widely used for producing plastic tube bodies from resins like PE and PP, offering high-volume and cost-efficient manufacturing. Many personal care and household product tubes are formed through extrusion due to its scalability and material versatility.
- Injection Molding:This method creates complex shapes and precise components, primarily used for manufacturing tube closures, caps, and shoulders. The accuracy achieved through injection molding is critical for ensuring proper sealing and dispensing functionality.
- Blow Molding:Primarily used for hollow plastic products, blow molding finds limited application in collapsible tube bodies but can be employed for specific geometries. This technique is more common for bottles and jars than for flexible tubes.
- Other Techniques:This includes co-extrusion for multi-layer plastic tubes and lamination processes for creating high-barrier laminate tubes.
Extrusion remains the dominant production technique for tube bodies, while Injection Molding is critical for intricate closure designs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal framework significantly influences regional demand for collapsible tube packaging, mandating increased post-consumer recycled content and improved recyclability. This directive drives material science innovation and accelerates the adoption of mono-material solutions across European markets. Global pharmaceutical and personal care brands adapt their packaging strategies to meet these evolving sustainability standards.
India
India's expanding contract pharmaceutical manufacturing industry drives significant demand for compliant packaging solutions, particularly for export markets. The country's Central Drugs Standard Control Organization (CDSCO) sets stringent standards for pharmaceutical packaging materials. Manufacturing hubs in Gujarat and Maharashtra are experiencing increased investment in advanced tube production capabilities to serve this growth.
Germany
German demand for collapsible tubes is shaped by robust pharmaceutical and personal care sectors, emphasizing high-barrier protection and sustainable materials. The EU's REACH regulation restricts specific chemical substances in packaging components, compelling manufacturers to validate supply chains. Production facilities in North Rhine-Westphalia and Bavaria focus on high-purity aluminum and advanced laminate tubes.
United States
The United States market sees strong demand for both pharmaceutical and premium personal care applications, with a focus on product safety and convenient dispensing. The US FDA sets strict standards for materials in direct contact with food and drugs, influencing material selection and compliance testing. Major packaging clusters in the Midwest and Northeast are developing innovative multi-layer and mono-material tube solutions.
China
China's vast consumer market and expanding pharmaceutical sector fuel substantial demand for collapsible tube packaging, prioritizing cost-effectiveness and aesthetic appeal. The NMPA (National Medical Products Administration) regulates pharmaceutical packaging, ensuring product integrity and safety. Industrial zones in the Yangtze River Delta and Pearl River Delta are centers for high-volume plastic and laminated tube production.
Brazil
Brazil's growing personal care and food & beverage industries contribute to rising demand for collapsible tubes, with an increasing focus on sustainable options. ANVISA, the national health surveillance agency, oversees packaging regulations for health products and food. Production facilities in São Paulo and Minas Gerais are expanding capabilities to meet domestic and regional market needs.
Collapsible Tube Packaging Market Key Industry Players
Channel-controlling players compete with product-specialist players across the collapsible tube packaging market, creating a tiered competitive structure. The market exhibits both consolidation among large, diversified packaging conglomerates and fragmentation among specialized regional producers. Strategic archetypes include global material science innovators and high-volume, cost-efficient manufacturers. Dominant competitive moves involve capacity expansion and portfolio diversification to meet evolving material demands.
At the scale-driven end, Berry Global and Amcor exemplify diversified packaging providers, leveraging extensive global manufacturing footprints to serve multinational brands across various sectors. Montebello Packaging, in contrast, represents a specialist archetype, focusing its expertise on high-purity aluminum tubes for pharmaceutical and niche industrial applications. These players differentiate through material science innovation and adherence to stringent regulatory requirements.
| Leading Market Players |
|---|
| Essel Propack |
| Sonoco Products Company |
| Berry Global |
| Montebello Packaging |
| Constantia Flexibles |
| Amcor |
| Albea Group |
| VisiPak |
| CCL Industries |
| Others |
Cost & Logistics Intelligence
Global shipping routes' cost dynamics influence the supply concentration of polymer resins and aluminum, affecting downstream price differentiation for collapsible tubes. This market navigates material cost volatility alongside evolving regulatory demands for sustainable packaging solutions. Supply chain resilience determines the ability to meet diverse regional requirements.
Pricing Analysis
Certification level for pharmaceutical applications creates the primary spread in collapsible tube pricing. Contract-based long-term offtake models dominate for large pharmaceutical and personal care brands, while smaller volumes are transactional. Price differentiation stems from material purity, barrier properties, and customization requirements. Margin pressure stems from input cost volatility for aluminum and polymer resins. The personal care segment exhibits higher price sensitivity compared to the pharmaceutical sector.
Supply Chain Analysis
Regulatory frameworks governing material sourcing, such as the EU's REACH regulation, limit the flow of certain chemical substances, impacting supply chain choices. Supply concentration for raw materials like polymer resins and aluminum primarily centers in China and specialized European producers. Key dependencies include high-purity aluminum and advanced barrier films. Commodity price volatility presents a structural risk to manufacturers. Distribution runs through direct sales to large CPG and pharmaceutical manufacturers, complemented by specialized packaging distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The collapsible tube packaging market is an early-cycle expansion story, primarily driven by the accelerating adoption of sustainable packaging solutions. This transition creates opportunities across material science and regional manufacturing.
For Market Incumbents: Build a regulatory compliance moat by investing in post-consumer recycled (PCR) resin validation and expanding specialized production lines in regulated markets like the EU. This mitigates the threat of stringent EU Green Deal mandates. Leverage global manufacturing footprints to serve diverse regional demands, focusing R&D on advanced mono-material solutions.
For New Entrants and Emerging Players: Build out niche capabilities in sustainable materials. Target bio-based plastic tubes for eco-conscious brands and mono-dose formats for beauty sampling. The Southeast Asian personal care market offers a penetrable segment due to growing disposable incomes. A go-to-market angle should emphasize design-for-recyclability and small-batch customization.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates seeking to divest non-core assets. The market's long-term viability is anchored in essential product dispensing needs and the global circular economy transition. Acquire innovators in high-purity aluminum or advanced mono-material solutions. The widespread commercial adoption of certified food-grade PCR resins is a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in India | Addresses growing contract pharmaceutical manufacturing demand in a key export hub. |
| Green Manufacturing Transition | Aligns production with EU Green Deal mandates for reduced environmental impact. |
| Product Launch: Bio-Based Tubes | Captures demand from eco-conscious brands seeking renewable packaging alternatives. |
| Strategic Partnership with PCR Suppliers | Secures consistent supply of high-quality post-consumer recycled resins. |
| Geographic Expansion into Southeast Asia | Penetrates new markets with rising disposable incomes and modern retail growth. |
Research Approach
Desk research of industry reports, regulatory filings, and trade publications preceded structured interviews with packaging engineers, procurement managers, R&D directors, and regulatory affairs specialists. This approach combined primary insights with secondary validation from sources like US FDA guidelines and EU REACH documents. Bottom-up data collection was triangulated with top-down market sizing for accuracy.
Assumptions regarding macroeconomic stability and current regulatory trajectories were held fixed over the projection horizon. The analytical framework modeled segmentation dimensions including product type, end-user, closure type, production method, and regional regulatory clusters. Compound annual growth rates were derived from historical trends and projected market dynamics. Key forecast inputs included raw material price forecasts and pharmaceutical R&D pipelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by large chemical suppliers or multinational personal care brands would shift outcomes. Projections reflect current market understanding and inherent uncertainties. Material shifts in major sustainability frameworks would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Organic Substrate Packaging Material Market
Packaging Materials
Food Grade Sealant Market
Packaging Materials
Packaging Laminates Market
Packaging Materials
Bakeable Trays Market
Packaging Materials
Twist Tie Market
Packaging Materials
Global Anti Counterfeit Automobile Packaging Market
Packaging Materials
Wrapping Tissues Market
Packaging Materials
Cast Polypropylene (CPP) Films Market
Packaging Materials
Strapping Materials Market
Packaging Materials
Protein Packaging Market
Packaging Materials
Packaging Suction Cups Market
Packaging Materials
MDO Films Market
Packaging Materials
Cold Seal Films Market
Packaging Materials
Non-Breathable Films Market
Packaging Materials
Europe Consumer Packaging Market
Packaging Materials
Thermoformed Trays Market