
 Organic Substrate Packaging Material Market | 2026-2036
Organic Substrate Packaging Material Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Substrate Packaging Material Market Intelligence
Subscription-based material certification and compliance monitoring is pivoting how buyers evaluate organic substrate suppliers. Texas Instruments Incorporated leverages its semiconductor-grade packaging expertise to anchor high-reliability substrate demand from electronics OEMs. LG Innotek Co., Ltd competes through vertical integration of resin formulation and lamination processes. Amkor Technology Inc sustains global assembly scale by qualifying multiple organic substrate sources across its packaging facilities.
Organic substrate packaging material comprises cellulose-derived paperboard, polylactic acid bioplastics, compostable polymer films, and hemp fiber composites engineered for protective containment with end-of-life biodegradability. These materials typically achieve ASTM D6400 or EN 13432 compostability certification while providing moisture vapor transmission rates below 10 g/m²/day for sensitive electronics and food applications. Bioplastic formulations currently lead material type revenue due to resin cost convergence with conventional plastics, though hemp fiber substrates represent the fastest-growing category as automotive and industrial buyers seek fiber-reinforced rigidity without petrochemical content. Moisture barrier functionality commands premium positioning among electronics end users where organic substrates must match synthetic material performance.
FDA food contact substance regulations, the EU Packaging and Packaging Waste Regulation, and China's GB standards for biodegradable plastics collectively determine which organic substrate formulations achieve commercial scale in their respective markets. REACH compliance in Europe restricts certain compostable additives, redirecting R&D toward bio-based alternatives that satisfy both performance and chemical safety thresholds. Stakeholders must monitor evolving extended producer responsibility frameworks that shift end-of-life cost accountability upstream to material suppliers and brand owners.
Market Dynamics
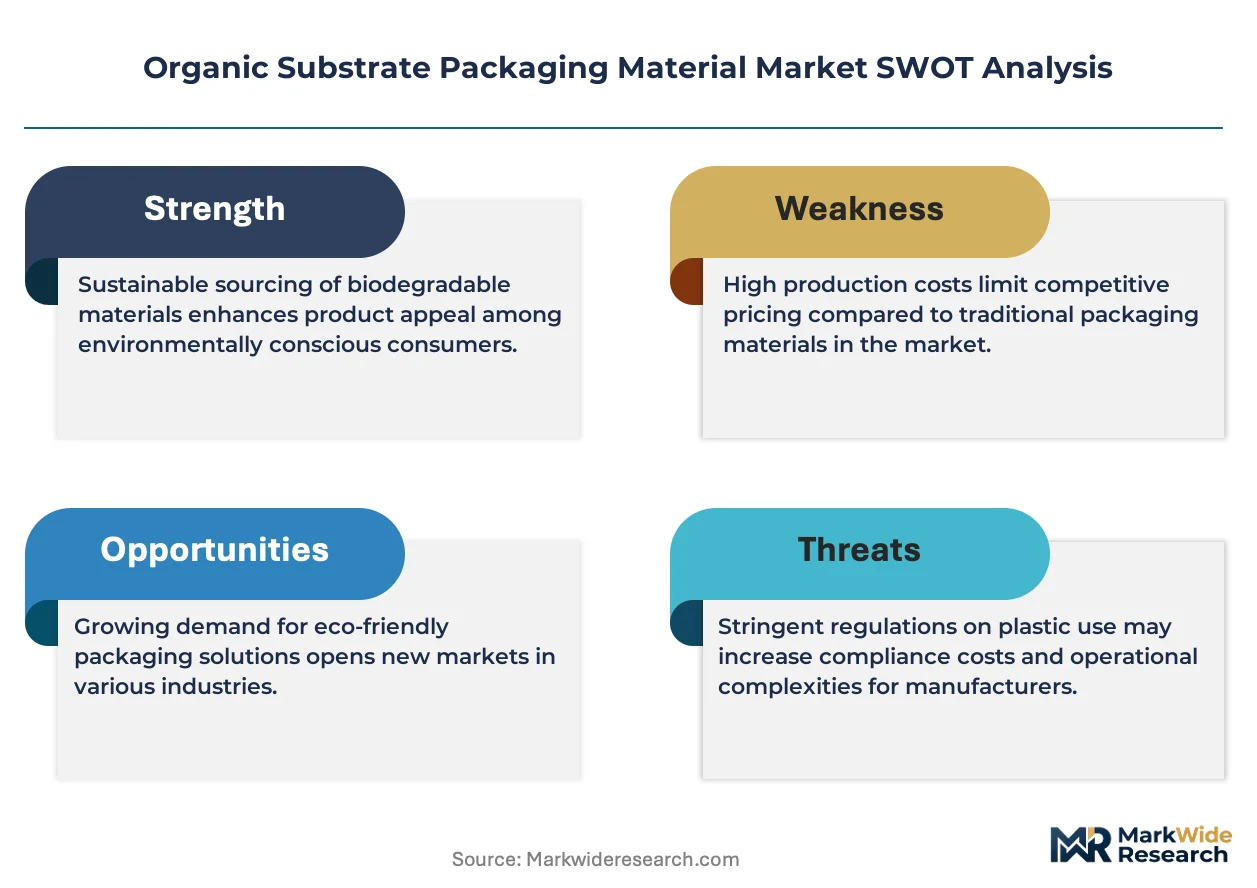
The EU Packaging and Packaging Waste Regulation is compressing formulation windows for substrate suppliers, forcing simultaneous compliance with compostability mandates and electronics-grade moisture barriers. This regulatory compression is redrawing supplier qualification timelines across food and semiconductor packaging segments.
Growth Catalysts
- Bioplastic resin cost convergence:Polylactic acid formulations now price-compete with petroleum-derived alternatives in high-volume food tray applications. Brand procurement teams at major retailers have removed cost barriers to compostable adoption.
- Extended producer responsibility frameworks:France's AGEC law and similar mechanisms across EU member states assign end-of-life cost accountability to packaging producers. This liability shift accelerates substrate replacement cycles.
- Electronics OEM moisture barrier requirements:Semiconductor packaging buyers now specify organic substrates achieving below 5 g/m²/day vapor transmission. This performance threshold opens premium positioning for cellulose-laminate suppliers.
Market Restraints
- Raw material concentration in East Asian biopolymer feedstock:Corn and cassava starch supply for PLA production clusters in Thailand and Chinese coastal provinces. Buyers face single-source risk during agricultural yield volatility.
- Industrial composting infrastructure gaps:ASTM D6400-certified substrates require municipal composting facilities operating at thermophilic temperatures. North American and European facility coverage remains patchy outside major metropolitan corridors.
- Performance ceiling in high-humidity electronics applications:Organic substrates absorb moisture at rates exceeding synthetic alternatives in tropical climates. This limitation constrains adoption in Southeast Asian contract manufacturing.
Strategic Opportunities
- Automotive interior panel applications:Hemp fiber-reinforced substrates meet OEM sustainability targets while providing acoustic dampening. European automakers have established material qualification programs for door trim and headliner components.
- Subscription-based certification monitoring:Third-party compliance services track evolving REACH additive restrictions and FDA food contact notifications. Suppliers bundling certification maintenance with substrate sales capture recurring revenue.
- Pharmaceutical cold-chain packaging:Insulated cellulose-based shippers displace expanded polystyrene in temperature-sensitive biologics distribution. This application leverages existing pharmaceutical logistics infrastructure.
Industry Challenges
- Cross-functional formulation expertise scarcity:Substrate development requires simultaneous mastery of polymer science, paperboard engineering, and compostability certification. Talent pools with this intersection remain shallow.
- Multi-certification timeline compression:Suppliers must sequence EN 13432, ASTM D6400, and FDA food contact approvals for global food brands. Parallel track submission costs strain mid-cap R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Substrate Packaging Material Market |
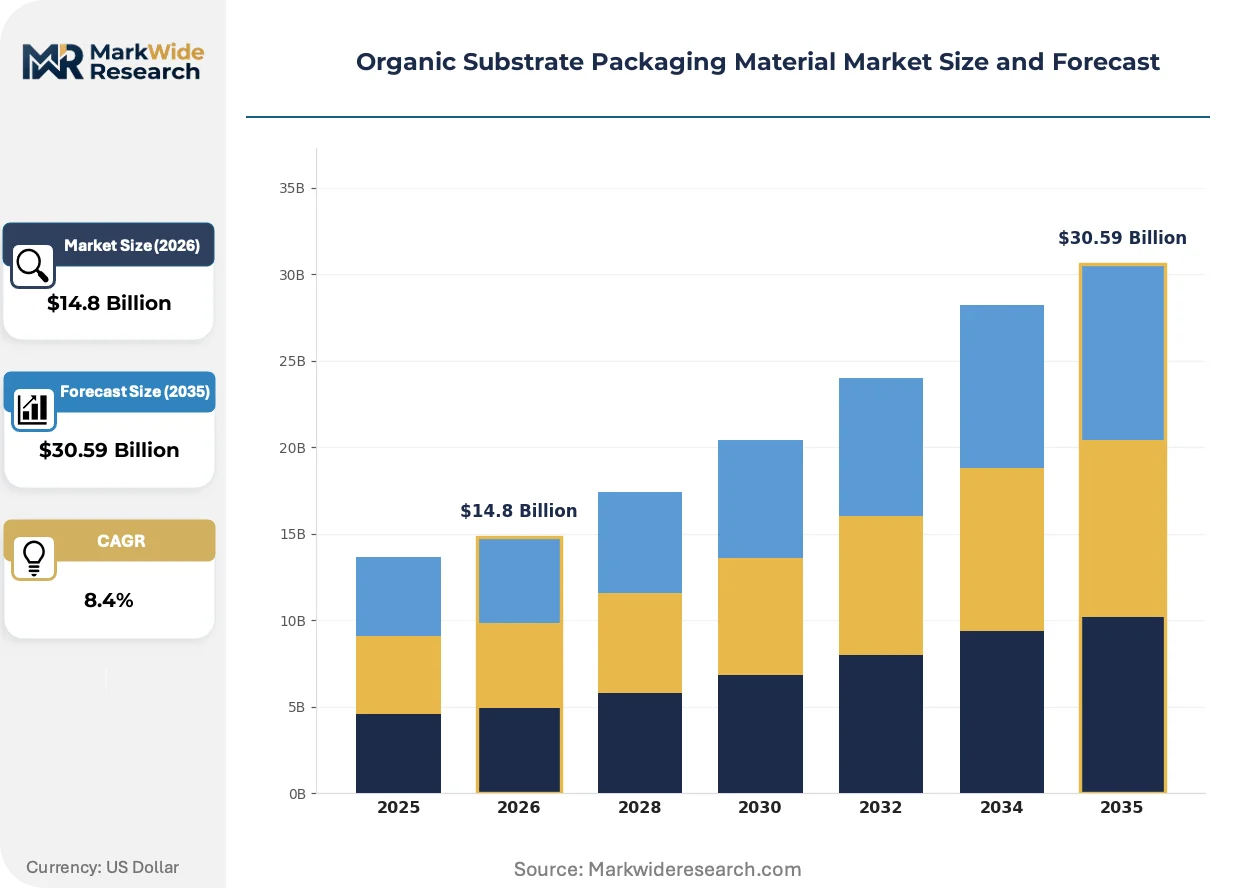
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $30.59 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Paperboard, Bioplastic, Compostable Film, Hemp Fiber End User: Food Industry, Personal Care Products, Electronics, Household Goods Functionality: Moisture Barrier, Biodegradability, Lightweight, Printability Distribution Channel: Online Retail, Wholesale, Direct Sales, E-commerce |
| Companies Covered | Texas Instruments Incorporated, LG Innotek Co., Ltd, Amkor Technology Inc, Daeduck Electronics Co., Ltd, AT&S, Kyocera Corporation, Simmtech Co., Ltd, Shinko Electric Industries Co., Ltd, Microchip Technology Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Substrate Packaging Material Market Strategic Shifts & Innovations
Material science convergence is eroding boundaries between electronics-grade performance and end-of-life biodegradability. Suppliers now engineer single substrates satisfying both semiconductor moisture barriers and food contact compostability.
Multilayer cellulose-laminate technology is consolidating substrate architectures previously requiring separate synthetic and organic material stacks. Semiconductor packaging houses in South Korea and Taiwan have qualified these laminates for flip-chip ball grid array applications. The technology is consolidating supplier tiers by eliminating the need for distinct electronics and consumer packaging material streams.
REACH additive restrictions are redirecting R&D investment toward bio-based plasticizers and slip agents. ECHA's expanding candidate list of substances of very high concern now captures several conventional compostable polymer modifiers. European substrate formulators are reformulating around citrate esters and epoxidized vegetable oils to maintain certification compliance.
Certification-driven procurement now dominates buyer evaluation criteria for organic substrate suppliers. Food brands and electronics OEMs alike require pre-submitted compostability documentation before contract negotiation. This pattern is most pronounced in German and French manufacturing supply chains, where extended producer responsibility enforcement has tightened most rapidly.
Organic Substrate Packaging Material Market Segmentation
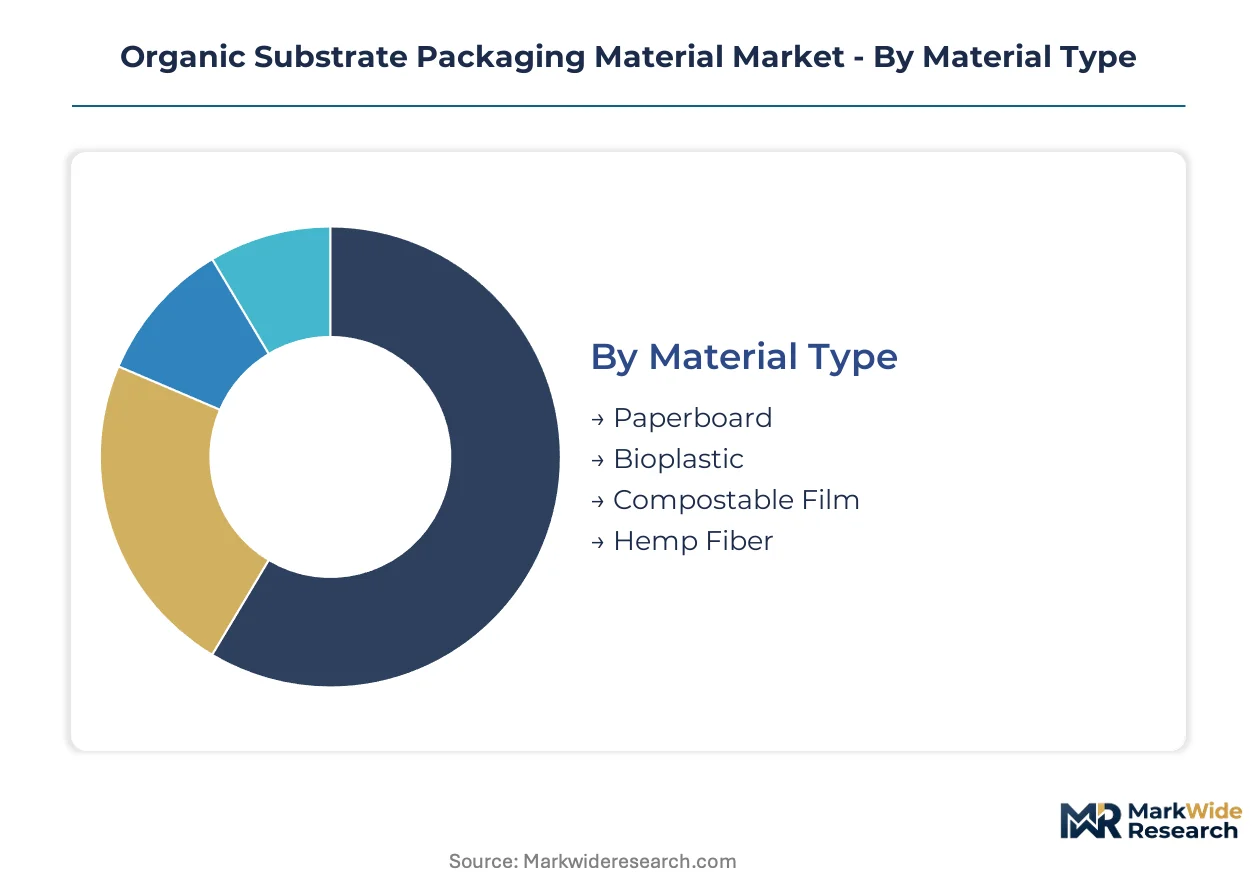
Organic substrate packaging material segments slice across incompatible performance requirements. Material chemistry determines compostability certification paths while end-use functionality dictates moisture barrier specifications. Procurement teams navigate these trade-offs through tiered supplier qualification frameworks.
Material Type:
Bioplastic formulations command volume leadership while hemp fiber substrates capture premium positioning in automotive and industrial applications.
- Paperboard:Cellulose-derived substrates laminated with bio-based barrier coatings achieve moisture vapor transmission below 10 g/m²/day. Food tray manufacturers in Germany and France specify this material for extended producer responsibility compliance under AGEC law and similar frameworks.
- Bioplastic:Polylactic acid resins now price-compete with petroleum-derived alternatives in high-volume food packaging. Thai and Chinese coastal provinces concentrate corn and cassava starch feedstock supply, creating single-source exposure during agricultural yield volatility.
- Compostable Film:Polymer formulations certified to ASTM D6400 or EN 13432 serve flexible packaging applications requiring transparency and sealability.
- Hemp Fiber:Fiber-reinforced composites deliver acoustic dampening and rigidity without petrochemical content. European automakers have established qualification programs for door trim and headliner components.
Today's leader: Bioplastic. Tomorrow's challenger: Hemp Fiber.
End User:
Food industry procurement drives standard-grade volume while electronics OEMs specify performance premiums for semiconductor-grade moisture barriers.
- Food Industry:Brands replace conventional plastics with compostable alternatives across tray, wrap, and container applications. EU Packaging and Packaging Waste Regulation tightens material compliance requirements across member states.
- Electronics:Semiconductor packaging buyers specify organic substrates achieving below 5 g/m²/day vapor transmission. South Korean and Taiwanese packaging houses have qualified multilayer cellulose-laminates for flip-chip ball grid array applications.
- Personal Care Products:Cosmetic and hygiene brands adopt compostable primary packaging for sustainability positioning in European retail channels.
- Household Goods:Durable product manufacturers specify fiber-reinforced substrates for protective shipping and retail display applications.
Food Industry generates the highest contract volumes. Electronics commands the steepest expansion trajectory as moisture barrier performance converges with biodegradability.
Functionality:
Moisture barrier specifications separate electronics-grade suppliers from commodity food packaging producers.
- Moisture Barrier:Substrates engineered for below 5 g/m²/day vapor transmission serve semiconductor and sensitive electronics containment. This performance tier opens premium positioning for cellulose-laminate suppliers with South Korean and Taiwanese packaging house qualifications.
- Biodegradability:ASTM D6400 and EN 13432 certification enables municipal composting disposal pathways. Industrial composting infrastructure gaps in North American and European corridors outside major metropolitan areas constrain end-of-life realization.
- Lightweight:Reduced material density cuts shipping costs and carbon intensity for e-commerce fulfillment applications.
- Printability:Surface engineering for high-resolution graphics serves brand differentiation requirements in retail-facing packaging.
Moisture Barrier functionality captures the highest margin premiums. Biodegradability determines regulatory access across EU member states.
Distribution Channel:
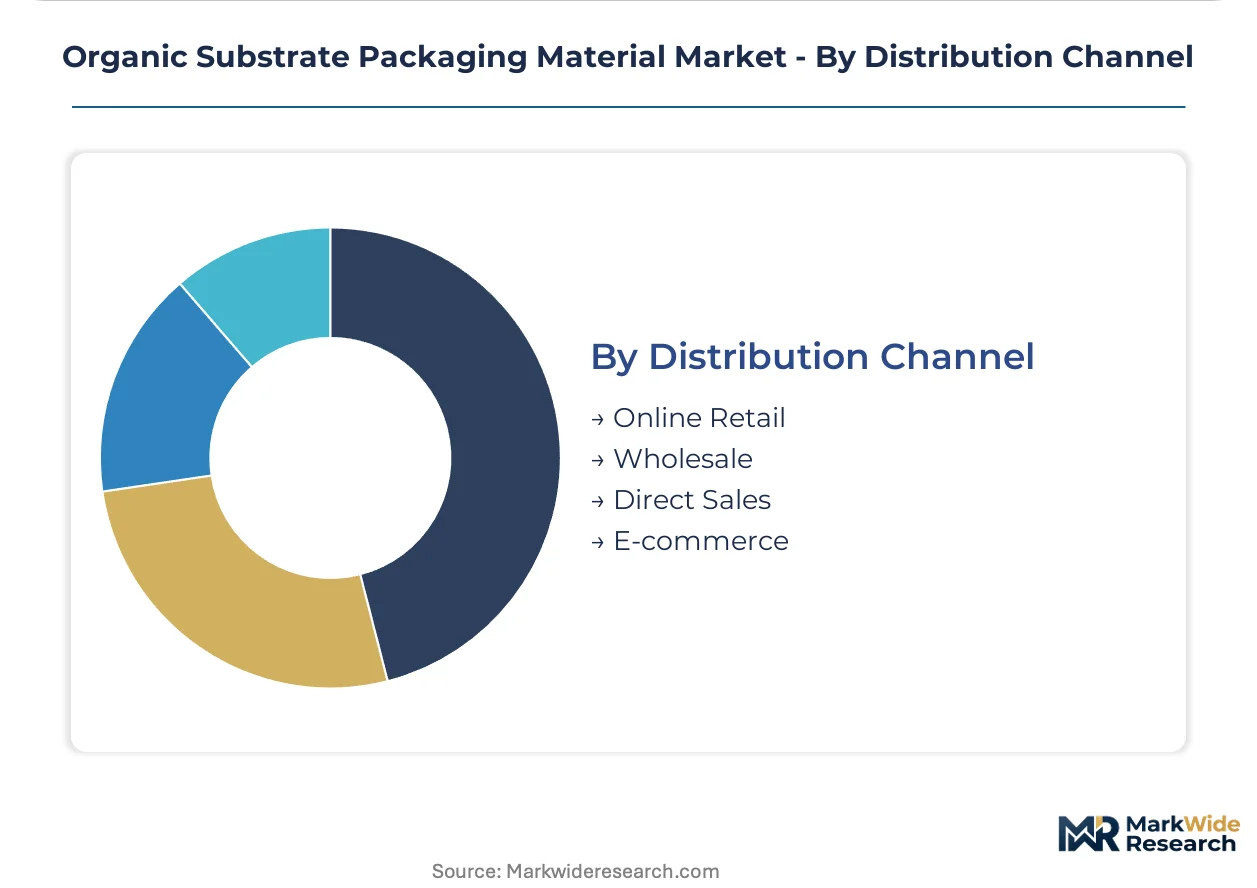
Direct sales relationships dominate electronics and food industry procurement while wholesale channels aggregate mid-volume buyers.
- Direct Sales:Substrate suppliers maintain technical service teams for semiconductor packaging houses and major food brands. These relationships span formulation co-development, certification documentation, and lot-to-lot quality assurance.
- Wholesale:Distributors aggregate demand from mid-cap converters and regional packaging producers across multiple end-use segments.
- Online Retail:Digital procurement platforms serve small-batch buyers and specialty product manufacturers with standardized substrate specifications.
- E-commerce:Brand-direct channels enable subscription-based certification monitoring services bundled with substrate supply.
Direct Sales anchors supplier profitability. E-commerce channels are gaining share fastest among compliance-service bundling strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China and South Korea dominate substrate manufacturing capacity, while Germany and the United States anchor demand from electronics OEMs and food brands seeking compostable alternatives.
China
Chinese bioplastic output expands fastest globally, driven by cassava starch feedstock concentration in coastal provinces and GB standards for biodegradable plastics enforcement. The Ministry of Ecology and Environment tightens compliance timelines for industrial composting infrastructure. Shenzhen and Shanghai clusters host multilayer cellulose-laminate qualification programs for semiconductor packaging houses.
South Korea
Semiconductor packaging buyers in South Korea specify organic substrates achieving below 5 g/m²/day vapor transmission for flip-chip applications. The Ministry of Food and Drug Safety aligns with EU Packaging and Packaging Waste Regulation compliance requirements for food-contact materials. Busan-Ulsan corridor concentrates lamination process expertise serving both domestic electronics OEMs and export markets.
Germany
German food tray manufacturers specify paperboard substrates under AGEC law extended producer responsibility frameworks. ECHA REACH restrictions redirect R&D toward bio-based plasticizers and slip agents. Bavaria and Baden-Württemberg industrial clusters host qualification programs for automotive interior panel applications using hemp fiber-reinforced substrates.
United States
FDA food contact substance regulations determine which organic substrate formulations achieve commercial scale for food industry procurement teams. EPA industrial composting facility gaps outside major metropolitan corridors constrain end-of-life realization for ASTM D6400-certified materials. Texas and California anchor demand from electronics OEMs and sustainable food brands respectively.
France
French packaging producers face compressed multi-certification timelines sequencing EN 13432, ASTM D6400, and FDA approvals for global food brands. ANSM monitors cosmetic and hygiene sector compostable packaging adoption. Île-de-France and Auvergne-Rhône-Alpes clusters lead pharmaceutical cold-chain packaging qualification for insulated cellulose-based shippers.
Organic Substrate Packaging Material Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with semiconductor-grade substrate suppliers commanding premium positioning while food packaging producers compete on volume scale and certification bundling. The market structure concentrates around vertically integrated resin-to-lamination players and specialized cellulose-coating houses. Three archetypes dominate: electronics-grade moisture barrier specialists, bioplastic resin formulators with captive substrate production, and subscription-based certification service bundlers. Capacity expansion and strategic partnerships represent the dominant competitive moves as suppliers sequence global qualification programs.
Within the electronics-grade substrate tier, Texas Instruments Incorporated and LG Innotek Co., Ltd exemplify divergent strategic positions—Texas Instruments leverages semiconductor-grade packaging expertise to anchor high-reliability demand from OEMs, while LG Innotek occupies a position defined by backward integration into resin formulation and lamination processes. Amkor Technology Inc represents the contract manufacturing archetype, sustaining global assembly scale through qualification of multiple organic substrate sources across packaging facilities. These three companies collectively illustrate how supplier selection criteria vary across moisture barrier performance, vertical integration depth, and global qualification breadth.
| Leading Market Players |
|---|
| Texas Instruments Incorporated |
| LG Innotek Co., Ltd |
| Amkor Technology Inc |
| Daeduck Electronics Co., Ltd |
| AT&S |
| Kyocera Corporation |
| Simmtech Co., Ltd |
| Shinko Electric Industries Co., Ltd |
| Microchip Technology Inc. |
| Others |
Cost & Logistics Intelligence
Corn and cassava starch feedstock costs in Thai and Chinese coastal provinces cascade through polylactic acid resin pricing tiers, compressing margins for European compounders while opening arbitrage windows for Asia-Pacific substrate suppliers serving export markets.
Pricing Analysis
Capacity additions in China's coastal provinces are reshaping price floors for bioplastic resin substrates. Three-tier pricing structure across premium, standard, and economy levels separates semiconductor-grade moisture barrier laminates from commodity food tray materials. Price differentiation hinges on EN 13432 certification tier and vapor transmission performance grade. Cost compression in standard-grade bioplastics intensifies because Thai starch supply expansion outpaces European compounder capacity. Food industry procurement teams exhibit highest price sensitivity; electronics OEMs accept premiums for sub-5 g/m²/day barrier performance.
Supply Chain Analysis
PLA resin supply rests on Thai and Chinese cassava starch processors and coastal biopolymer fermentation facilities. Raw material flows draw from agricultural feedstock clusters, bio-based plasticizer additive houses, and multilayer lamination equipment manufacturers. Single-source vulnerability concentrates in Thai starch supply during monsoon yield volatility. Distribution runs through direct technical service relationships for semiconductor packaging houses and wholesale distributors aggregating mid-volume food converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Organic substrate packaging material functions as a regulatory-arbitrage play where EU REACH additive restrictions inflate European production costs against Chinese GB standards enforcement that accelerates domestic bioplastic output.
For Market Incumbents: To counter hemp fiber substrate entrants in automotive interior panels, anchor electronics-grade moisture barrier qualifications with South Korean packaging houses while deepening backward integration into bio-based plasticizer formulation to deflect REACH compliance cost shocks. For New Entrants and Emerging Players: Enter via pharmaceutical cold-chain packaging white space where insulated cellulose-based shippers displace expanded polystyrene. Target French and German pharmaceutical logistics clusters with bundled ASTM D6400 certification maintenance services to bypass incumbent qualification timelines. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap cellulose-laminate specialists because electronics OEMs consolidate supplier tiers around dual-use substrates satisfying both semiconductor moisture barriers and food contact compostability. Long-term viability favors targets with existing South Korean or Taiwanese packaging house qualifications. Watch ECHA SVHC candidate list expansion velocity as inflection indicator for bio-based additive R&D investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Plasticizers | Citrate ester and epoxidized vegetable oil captive production deflects REACH SVHC restriction cost shocks for European formulators. |
| Multilayer Cellulose-Laminate Capacity Expansion | Consolidated substrate architectures eliminate separate electronics and consumer packaging material streams for South Korean packaging houses. |
| Subscription-Based Certification Monitoring Launch | Recurring revenue capture from evolving EU Packaging and Packaging Waste Regulation compliance documentation bundling. |
| Automotive Interior Panel Qualification Program | Hemp fiber-reinforced acoustic dampening substrates access European OEM sustainability targets for door trim components. |
| Pharmaceutical Cold-Chain Packaging Partnership | Insulated cellulose shipper qualification leverages existing Île-de-France biologics distribution infrastructure. |
Research Approach
Bottom-up food and electronics end-use modeling reconciled against top-down biopolymer resin production tracking forms the analytical core. Primary interviews with substrate R&D directors, food brand procurement managers, semiconductor packaging house engineers, and composting facility operators combined with secondary validation against ECHA REACH filings, FDA food contact notifications, and Chinese GB standards enforcement records. Trade data from Thai and Chinese customs authorities, SEC 10-K disclosures from packaging technology suppliers, and EU extended producer responsibility framework implementation timelines triangulate volume estimates.
Historical trendline analysis across material type adoption curves and end-use penetration rates informs projection frameworks. Segmentation dimensions span material chemistry, functionality tier, end-use industry, and regional regulatory cluster. CAGRs derive from fitted growth curves calibrated against bioplastic resin cost convergence trajectories and electronics OEM moisture barrier specification tightening. Forecast inputs incorporate industrial composting infrastructure buildout velocity and REACH additive restriction expansion scope.
Inputs from ECHA candidate list updates and FDA food contact substance notification databases were available through the study window; gaps in real-time agricultural yield data from Thai cassava regions introduce uncertainty bands around PLA resin cost assumptions. Forecasts reflect documented assumptions regarding EU Packaging and Packaging Waste Regulation enforcement timelines and Chinese bioplastic capacity expansion schedules. Material deviation in ECHA SVHC list velocity or Chinese MEE composting infrastructure compliance deadlines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Direct Thermal Printing Films Market
Packaging Materials
Cutterbox Films Market
Packaging Materials
Lidding Foil Market
Packaging Materials
Global Adherence Packaging Market
Packaging Materials
Cohesive Packaging Market
Packaging Materials
Fiber Lids Market
Packaging Materials
Global Anti Counterfeit Automobile Packaging Market
Packaging Materials
Europe Consumer Packaging Market
Packaging Materials
Heat Shrink Packaging Market
Packaging Materials
Cutting Tool Packaging Market
Packaging Materials
Hygiene Packaging Market
Packaging Materials
Asia-Pacific Airless Packaging Market
Packaging Materials
Global Thin Wall Packaging Market
Packaging Materials
Cold Form Foil Market
Packaging Materials
VCI Shrink Films Market
Packaging Materials
Corrugated Wrap Around Market