
 Dispensing Spouts Market | 2026-2036
Dispensing Spouts Market Size, Share, and Industry Trends Forecast 2026-2036
Dispensing Spouts Market Outlook
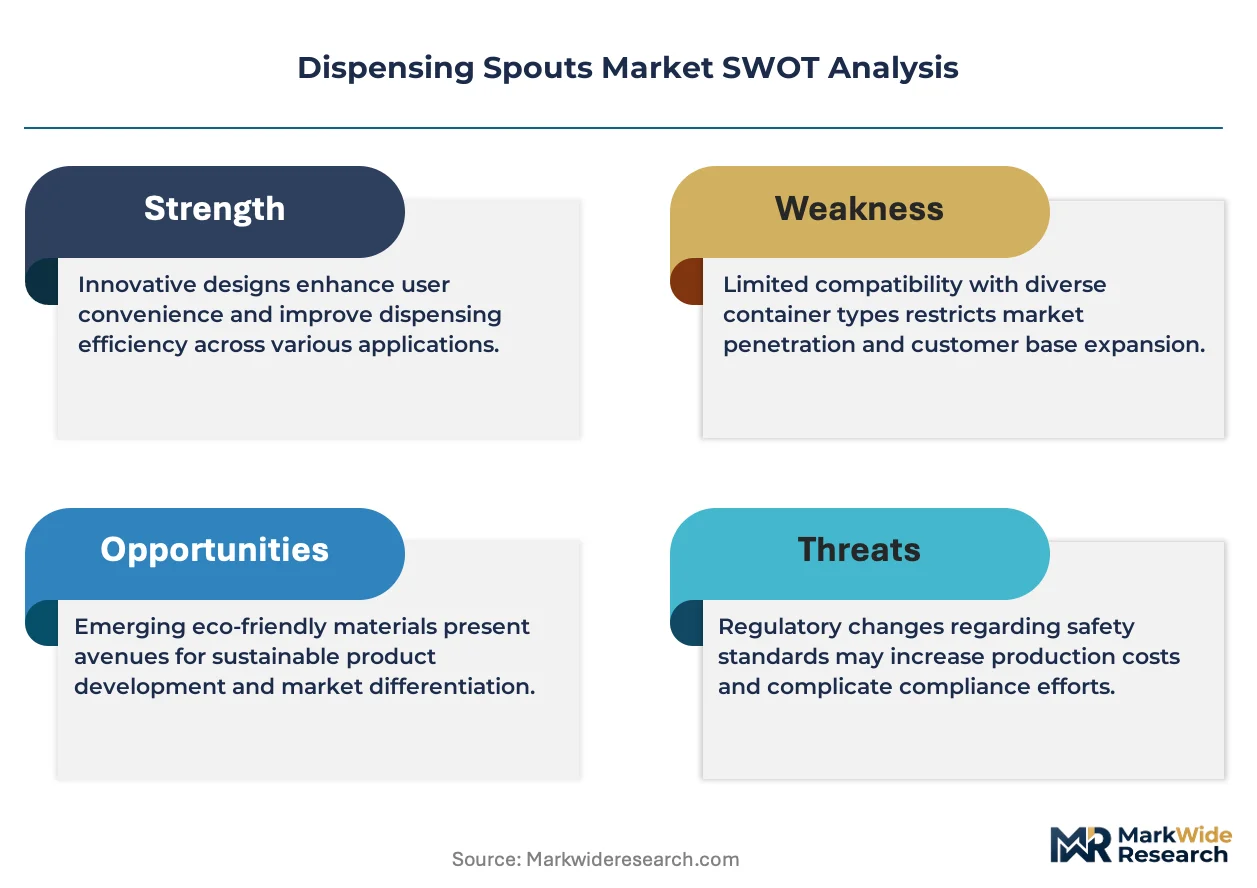
Buyer concentration among large food and beverage packagers is pivoting toward dual-source strategies, fragmenting order volumes across more spout suppliers than in prior cycles. AptarGroup Inc. leverages its global tooling network to serve multinational condiment brands with standardized dispensing platforms. Berry Global Inc. sustains cost leadership through captive resin compounding and high-speed injection molding across North American plants. Silgan Holdings Inc. anchors its position via metal closure integration, offering hybrid metal-plastic dispensing systems for industrial chemical clients.
Dispensing spouts are precision-engineered flow-control devices, typically injection-molded from food-grade polypropylene or polyethylene with shore hardness specifications between 60A and 80D, designed to regulate viscous and liquid product delivery while preventing contamination and enabling resealability. Plastic spouts dominate unit volumes due to cost scalability and color customization, though silicone spouts are gaining fastest in premium infant nutrition and medical food segments where squeeze compliance and thermal stability command margin premiums. Metal spouts retain durable positioning in industrial chemical applications where solvent resistance and mechanical impact tolerance outweigh material cost disadvantages.
FDA food-contact substance notifications and EU REACH migration testing frameworks shape material selection and supplier qualification timelines, with EFSA additive approvals increasingly required for European market access. The EPA and OSHA jointly influence industrial chemical dispensing designs through emissions containment and workplace exposure standards. Stakeholders must monitor evolving bioplastic certification schemes and state-level extended producer responsibility laws that will redefine resin sourcing decisions and recyclability claims.
Market Dynamics
Precision molding clusters in Germany are consolidating regional supply capacity while FDA and EFSA migration limits force simultaneous material reformulation across the value chain.
Growth Catalysts
- Tamper-evident closure mandates:Food packaging manufacturers in the European Union are expanding orders under EFSA food-contact substance frameworks. Retail chains now require visible integrity seals for condiment and beverage products.
- Dual-source procurement normalization:Large food and beverage packagers are fragmenting order volumes across multiple spout suppliers. This procurement pattern creates volume lift for secondary tooling networks.
- Silicone compliance premiums:Infant nutrition and medical food segments command margin premiums for squeeze-compliant, thermally stable dispensing. Shore hardness specifications between 60A and 80D enable precise flow control in these applications.
Market Restraints
- Resin cost volatility:Polypropylene and polyethylene input prices fluctuate with petrochemical feedstock markets. Captive resin compounding provides partial insulation only to vertically integrated molders.
- German supply concentration:Precision molding capacity clusters heavily in southern Germany. Geographic density creates single-point vulnerability for European beverage brand supply chains.
- Metal spout cost disadvantage:Industrial chemical applications face persistent material cost penalties for solvent-resistant metal dispensing systems. Plastic alternatives lack comparable mechanical impact tolerance.
Strategic Opportunities
- Bioplastic certification pathways:EFSA additive approvals and emerging EU bioplastic certification schemes will redefine resin sourcing decisions. First-movers in compostable polypropylene formulations capture sustainability-driven brand contracts.
- Hybrid metal-plastic integration:Industrial chemical clients seek unified dispensing systems combining metal closure durability with plastic precision. Silgan Holdings anchors this positioning through captive metal closure technology.
- Extended producer responsibility tailwinds:State-level EPR laws in multiple US jurisdictions mandate recyclability claims. Spout suppliers with verified post-consumer recycled content access preferential supplier status.
Industry Challenges
- Migration testing timeline compression:FDA food-contact substance notifications and EU REACH testing frameworks extend supplier qualification cycles. Parallel regulatory submissions strain technical documentation capacity.
- Tooling reconfiguration costs:High-speed injection molding platforms require capital-intensive retooling for shore hardness specification shifts. Mid-cap specialists face balance sheet constraints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dispensing Spouts Market |
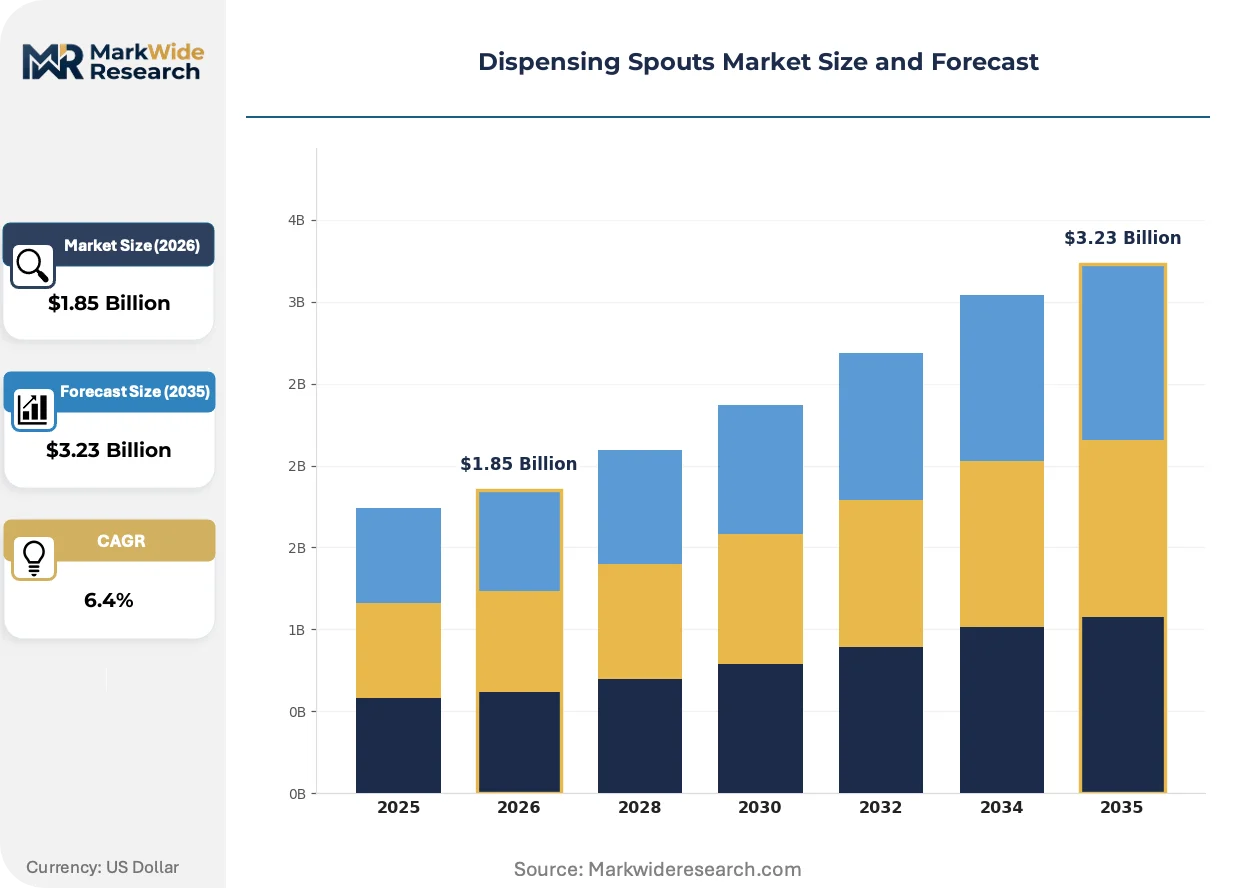
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Spouts, Metal Spouts, Silicone Spouts, Glass Spouts Application: Food Packaging, Beverage Dispensing, Industrial Chemicals, Household Products End User: Manufacturers, Retailers, Wholesalers, Consumers Distribution Channel: Online Sales, Direct Sales, Retail Stores, Distributors |
| Companies Covered | AptarGroup Inc., Berry Global Inc., Silgan Holdings Inc., Rieke Corporation, Weener Plastik GmbH, Nilkanth Polyplast, O.Berk Company LLC, Elkay Manufacturing Company Inc., Uflex Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dispensing Spouts Market Strategic Shifts
Active material science advances and regulatory harmonization pressures are compressing product development cycles while fragmenting procurement authority across buyer organizations.
Silicone spout technology is consolidating premium positioning in squeeze-sensitive applications. Infant nutrition brands and medical food manufacturers adopt these formulations for thermal stability and compliance performance. The material shift is compressing commodity polypropylene margins in adjacent segments.
REACH migration testing frameworks and FDA food-contact notifications are tightening in parallel. Industrial consequence includes mandatory third-party laboratory certification for all new resin formulations. European market access now requires dual EFSA additive approval and REACH compliance documentation.
Buyer technical specifications are fragmenting across procurement functions. Food packaging engineers now specify shore hardness independently of purchasing departments, compressing supplier negotiation cycles. This pattern is most visible in German beverage brand supply chains where precision molding tolerances are non-negotiable.
Dispensing Spouts Market Segmentation
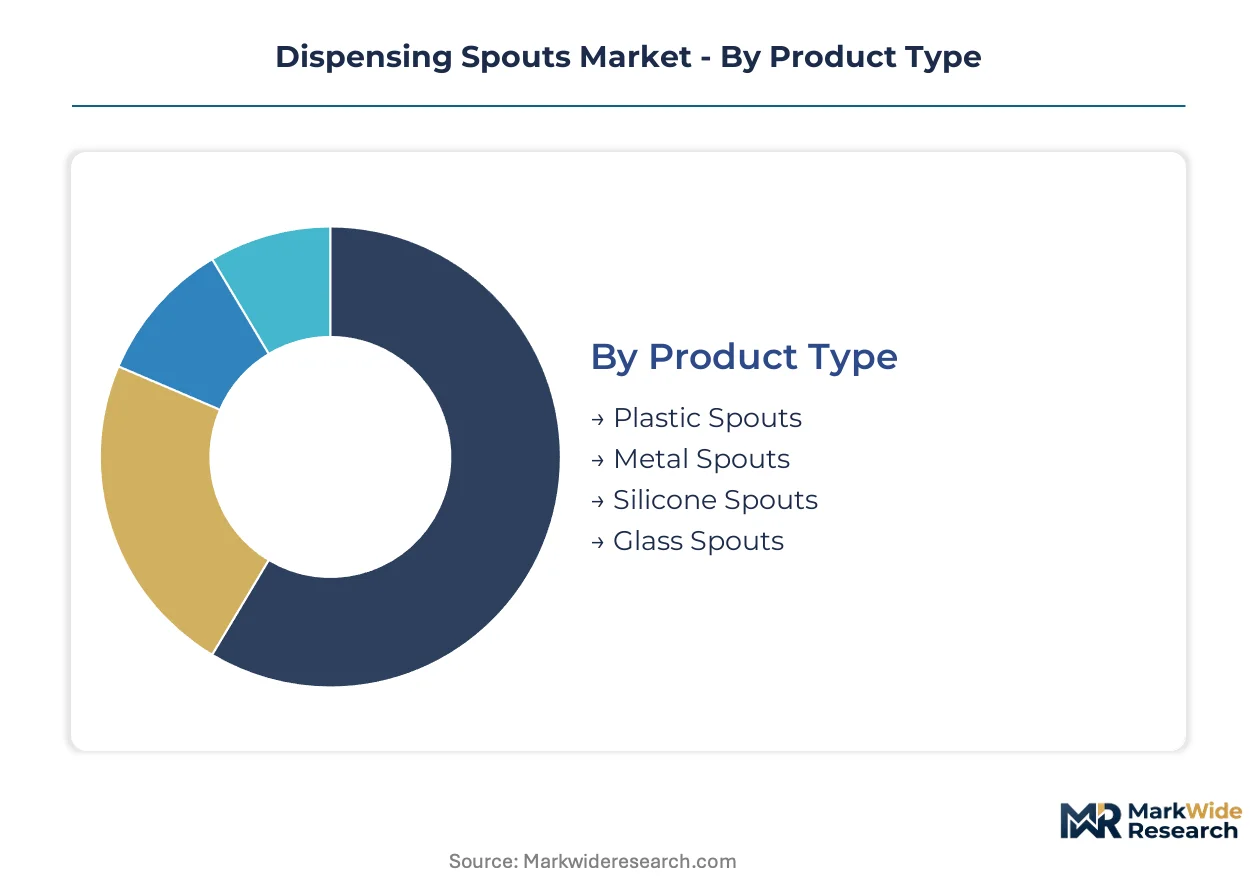
Precision molding tolerances and regulatory migration limits fragment the dispensing spouts landscape into materially distinct supply chains. Each segmentation dimension carries unique qualification barriers and margin structures that reshape procurement patterns across food, beverage, and industrial end-uses.
Product Type:
Standardization dominates commodity resin formulations while customization premiums concentrate in Shore hardness specifications and thermal stability ratings.
- Plastic Spouts:Injection-molded from food-grade polypropylene or polyethylene with shore hardness between 60A and 80D. Unit volumes concentrate in condiment and beverage applications across German precision molding clusters serving EFSA food-contact substance frameworks. Cost scalability and color customization sustain dominance despite resin price volatility.
- Silicone Spouts:Thermally stable formulations with squeeze compliance command margin premiums in infant nutrition and medical food segments. Demand is accelerating fastest where FDA food-contact notifications intersect with REACH migration testing requirements for thermal stability performance.
- Metal Spouts:Solvent-resistant dispensing for industrial chemical applications where mechanical impact tolerance outweighs material cost penalties.
- Glass Spouts:Premium positioning in artisanal food packaging with inert material properties satisfying migration limit stringency.
Most installed capacity flows through Plastic Spouts. Expansion is steepest in Silicone Spouts.
Application:
Volume scale separates high-throughput beverage dispensing from qualification-intensive industrial chemical segments.
- Food Packaging:Tamper-evident closure mandates under EU retail chain specifications drive order expansion. EFSA additive approvals and visible integrity seals now condition supplier qualification across condiment and sauce applications.
- Beverage Dispensing:Precision molding tolerances are non-negotiable for German beverage brands. Dual-source procurement normalization fragments order volumes across secondary tooling networks serving multinational brand portfolios.
- Industrial Chemicals:EPA emissions containment and OSHA workplace exposure standards govern design specifications. Hybrid metal-plastic systems address solvent resistance requirements.
- Household Products:Cost-driven procurement with recyclability claims increasingly conditioned by state-level extended producer responsibility laws.
Food Packaging commands the largest revenue pool. Beverage Dispensing is climbing the fastest on precision specification premiums.
End User:
Technical specification authority fragments across procurement functions depending on scale and integration depth.
- Manufacturers:Direct material specification authority with captive tooling investments or dual-source vendor qualification programs. Shore hardness specifications now route through engineering departments independent of purchasing negotiation cycles.
- Retailers:Private label brands imposing tamper-evident and sustainability requirements on contracted packaging suppliers.
- Wholesalers:Volume aggregation with limited technical specification influence beyond commodity grade standardization.
- Consumers:Premium segment pull-through in squeeze-sensitive applications where thermal stability and resealability drive replacement purchase decisions.
Manufacturers absorb the majority of direct procurement volume. Retailers are gaining share fastest through private label specification authority.
Distribution Channel:
Channel selection correlates with order scale, technical service requirements, and qualification documentation intensity.
- Direct Sales:Dominates large food and beverage packager relationships requiring parallel FDA and EFSA documentation submission. Technical service integration and tooling co-development justify relationship density.
- Distributors:Serves mid-cap molders and regional beverage brands with fragmented order volumes across multiple spout specifications.
- Online Sales:Emerging in standard commodity grades with documented shore hardness certifications and verified post-consumer recycled content claims.
- Retail Stores:Minimal direct penetration; limited to replacement and aftermarket applications in household product segments.
Direct Sales channels carry the heaviest transaction value. Online Sales is expanding most quickly on documentation transparency and standardized certification availability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates precision molding capacity for European beverage brands, while the United States sustains dual-source procurement networks across multiple domestic tooling suppliers. Demand fragmentation and regulatory tightening are reshaping supplier qualification timelines across both markets.
Germany
Bavarian precision molding clusters serve multinational condiment and beverage brands with non-negotiable tolerance specifications. EFSA food-contact substance frameworks mandate additive approvals for all new resin formulations entering European supply chains. Stuttgart and Munich anchor the densest concentration of high-speed injection molding capacity serving EFSA-compliant dispensing platforms.
United States
Large food packagers fragment order volumes across secondary tooling networks under FDA food-contact notification requirements. EPA emissions containment standards and OSHA workplace exposure rules govern industrial chemical dispensing designs. Midwestern injection molding corridors in Ohio and Illinois host captive resin compounding operations insulating against polypropylene price volatility.
China
Domestic beverage brands and export-oriented packaging manufacturers drive unit volume scale for commodity-grade plastic spouts. GB standards and SAMR food-contact regulations tighten migration testing protocols for polypropylene formulations. Yangtze River Delta molding clusters supply standardized dispensing platforms to Southeast Asian condiment exporters.
India
Domestic infant nutrition brands command silicone spout premiums for thermal stability and squeeze compliance performance. FSSAI food safety standards and BIS certification requirements extend supplier qualification timelines for imported resin formulations. Maharashtra and Gujarat host emerging precision molding capacity serving regional pharmaceutical and medical food packaging demand.
Japan
Premium household product brands specify shore hardness tolerances independently through engineering departments. METI industrial standards and PMDA medical device frameworks intersect for medical food dispensing applications. Kanto region tooling networks supply precision-molded spouts to domestic beverage brands with zero-defect procurement protocols.
Dispensing Spouts Market Competitive Environment
German producers anchor the precision-molding tier; North American specialists hold cost-leadership positions through captive resin integration. The vendor base separates into three functional layers: multinational platform standardizers, regional high-speed molders, and hybrid metal-plastic integrators. Competitive maneuvering concentrates on dual-source vendor qualification capture and EFSA additive approval first-mover positioning.
Within the multinational platform tier, AptarGroup Inc. and Berry Global Inc. occupy positions defined by global tooling network scale and captive supply chain control respectively. Silgan Holdings Inc. exemplifies the hybrid integration archetype through metal closure technology anchoring. German specialists including Weener Plastik GmbH represent regional precision-density positioning against commodity-scale competitors.
| Leading Market Players |
|---|
| AptarGroup Inc. |
| Berry Global Inc. |
| Silgan Holdings Inc. |
| Rieke Corporation |
| Weener Plastik GmbH |
| Nilkanth Polyplast |
| O.Berk Company LLC |
| Elkay Manufacturing Company Inc. |
| Uflex Ltd. |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal compliance timelines gate qualified supply access and premium-tier pricing power for dispensing spout manufacturers serving European beverage brands. EFSA additive approvals and REACH migration certification now separate price-accessible commodity tiers from margin-rich precision-molding contracts.
Pricing Analysis
Capacity additions in southern Germany are reshaping price floors for precision-molded beverage dispensing platforms. Three-tier pricing structure across premium silicone, standard food-grade polypropylene, and economy polyethylene levels stratifies by shore hardness certification and EFSA compliance documentation. Pricing pressure stems from resin cost volatility in petrochemical feedstock markets. Large food packagers exhibit lowest price sensitivity due to dual-source procurement normalization, while household product distributors face acute cost compression.
Supply Chain Analysis
Freight cost escalation from German precision molding clusters to pan-European beverage brand distribution networks is compressing delivered margins for secondary tooling suppliers. Geographic supply concentration centers on Germany, the United States, and China for injection-molded capacity. Raw material dependencies draw from polypropylene resin compounding, silicone elastomer formulations, and metal closure substrates. Single-source vulnerability persists in Bavarian high-speed molding corridors. Distribution runs through direct sales channels for multinational packagers and distributor networks for mid-cap regional brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through silicone spout premiumization and captive resin compounding cost control. The shift from commodity polypropylene to certified thermal-stable formulations enables pricing power capture.
For Market Incumbents: Deepen EFSA additive approval first-mover positioning to defend against bioplastic certification pathway disruption. Anchor dual-source vendor qualification capture through technical documentation capacity expansion. Invest in hybrid metal-plastic integration tooling to serve industrial chemical solvent resistance requirements. For New Entrants and Emerging Players: Silicone squeeze-compliance technology offers wedge positioning in infant nutrition and medical food segments where FDA food-contact notifications intersect with thermal stability premiums. Target Indian domestic pharmaceutical packaging demand and Southeast Asian condiment export supply chains. Pursue online sales channel entry with documented shore hardness certifications and verified post-consumer recycled content claims. For Investors and Strategic Acquirers: Roll-up economics work for regional precision molders with EFSA-compliant tooling because migration testing timeline compression creates qualification barriers for new entrants. Mid-cap German specialists with captive high-speed injection capacity represent attractive acquisition targets. Monitor state-level extended producer responsibility law passage as inflection signal for recyclability claim premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Additive Approval Investment | Secures European market access for new resin formulations ahead of REACH migration testing deadlines. |
| Silicone Spout Capacity Expansion | Captures margin premiums in infant nutrition segments where FDA food-contact notifications command compliance pricing. |
| Captive Resin Compounding Integration | Insulates polypropylene cost exposure through backward control over feedstock formulation and color customization. |
| Hybrid Metal-Plastic System Development | Addresses EPA emissions containment requirements for industrial chemical dispensing with unified closure durability. |
| Post-Consumer Recycled Content Verification | Unlocks preferential supplier status under state-level extended producer responsibility mandates in multiple US jurisdictions. |
Study Parameters
Direct dialogue with injection molding plant managers, food packaging procurement leads, beverage brand technical specification engineers, and EFSA regulatory affairs consultants grounded the qualitative foundation. Secondary validation drew from FDA food-contact substance notification databases, EU REACH compliance registries, SEC 10-K filings of listed packaging suppliers, and German plastics industry association technical reports. Bottom-up capacity assessments across Bavarian precision molding clusters triangulated against top-down demand estimates from condiment and beverage brand order flow analysis.
Segment-level value and volume trajectories across the projection horizon reflect modeled interactions between shore hardness specification premiums, resin price volatility corridors, and dual-source procurement normalization patterns. The analytical framework incorporated product type segmentation by material formulation, application segmentation by regulatory intensity, and end-user segmentation by technical specification authority. CAGRs derived from regression against historical tooling investment cycles and migration testing timeline compression effects.
The model holds under stable EFSA and FDA regulatory enforcement intensity; deviation in bioplastic certification scheme acceleration or extended producer responsibility law expansion would shift resin sourcing economics. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Brush and Dauber Caps Market
Caps and Closures
Plastic Sifter Caps Market
Caps and Closures
Bi-Injected Snap Hinge Closure Market
Caps and Closures
Plastic Caps and Closure Market
Caps and Closures
Europe Plastic Caps and Closures Market
Caps and Closures
Push Pull Closure Market
Caps and Closures
Japan Plastic Caps and Closures Market
Caps and Closures
Dropper Caps Market
Caps and Closures
Buttress Closures Market
Caps and Closures
Lug Caps Market
Caps and Closures
Plunger Stopper Market
Caps and Closures
Fixed Length Seals Market
Caps and Closures
Colombia Plastic Caps and Closures Market
Caps and Closures
Crimp Top Cap Market
Caps and Closures
Foam Cap Liners Market
Caps and Closures
Pharmaceutical Caps and Closures Market