
 Thermoformed Trays Market | 2026-2036
Thermoformed Trays Market Size, Share, and Industry Trends Forecast 2026-2036
Thermoformed Trays Market Outlook
Medical device OEMs is bifurcating the Thermoformed Trays demand base away from commodity food service buyers. Amcor plc leverages its pharmaceutical-grade cleanroom manufacturing network across multiple continents to capture high-margin sterile barrier contracts. Pactiv LLC anchors the North American food service segment through scale-driven sheet extrusion and forming operations. DS Smith differentiates via fiber-based tray alternatives that compete directly with plastic formats in select European retail channels.
Thermoformed trays are rigid packaging components produced by heating thermoplastic sheets and vacuum- or pressure-forming them over molds, typically achieving wall thicknesses of 0.005 to 0.060 inches depending on structural requirements. These trays function primarily as protective containment, unitization, and presentation platforms across automated filling, sterilization, and distribution systems. PET material type commands the largest volume share due to clarity, barrier performance, and established recycling infrastructure, while polypropylene gains fastest in medical applications requiring steam sterilization compatibility. Food packaging application remains the mature volume base, though medical packaging carries substantially higher per-unit margins and stricter qualification barriers.
FDA enforces sterility assurance and quality system requirements under 21 CFR Part 820 that directly determine tray design validation protocols for medical device clients. EU MDR and REACH chemical restrictions jointly reshape material composition decisions, particularly for phthalate-free and recycled content pathways. Stakeholders must monitor evolving Extended Producer Responsibility frameworks and single-use plastic directives across multiple European member states, as these regulations will increasingly dictate capital allocation between virgin and recycled feedstock capacity.
Market Dynamics
Medical device sterilization requirements under FDA 21 CFR Part 820 and EU MDR are forcing thermoformed tray manufacturers to reallocate capacity toward pharmaceutical-grade cleanroom production, compressing margins for commodity food-service suppliers.
Growth Catalysts
- EU MDR sterilization validation mandates:European medical device regulations now require documented sterile barrier integrity, driving qualified tray demand from German manufacturers in the Tuttlingen corridor.
- Steam sterilization compatibility:Polypropylene formulations tolerate repeated autoclave cycles, expanding tray deployment into surgical kits and implant packaging workflows.
- Recycled PET infrastructure:Germany's dual waste collection systems and mechanical recycling facilities enable closed-loop feedstock for non-medical tray applications.
Market Restraints
- Virgin resin price volatility:PET and polypropylene feedstock costs fluctuate with crude oil derivatives, squeezing converter margins on fixed-price annual contracts.
- Cleanroom capacity concentration:Pharmaceutical-grade thermoforming capacity clusters in Switzerland, Germany, and the United States, creating geographic supply bottlenecks for new market entrants.
- Fiber-based substitution:DS Smith and European molded fiber competitors displace plastic trays in ambient retail applications through compostable alternatives.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO regulatory alignment with EU MDR standards positions Indian generic drug producers as export-oriented tray buyers.
- RFID-embedded traceability:Convergence of thermoforming with printed electronics enables unit-level sterilization tracking for high-value implants.
- Extended Producer Responsibility frameworks:France and Italy's packaging waste directives mandate recycled content thresholds, rewarding early movers with certified circular feedstock.
Industry Challenges
- ISO 13485 certification timelines:Medical tray qualification requires 12-18 month validation cycles, delaying revenue recognition for new product lines.
- Cleanroom technician scarcity:Qualified operators for pharmaceutical-grade thermoforming equipment command premium wages in Germany's medical technology corridor.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermoformed Trays Market |
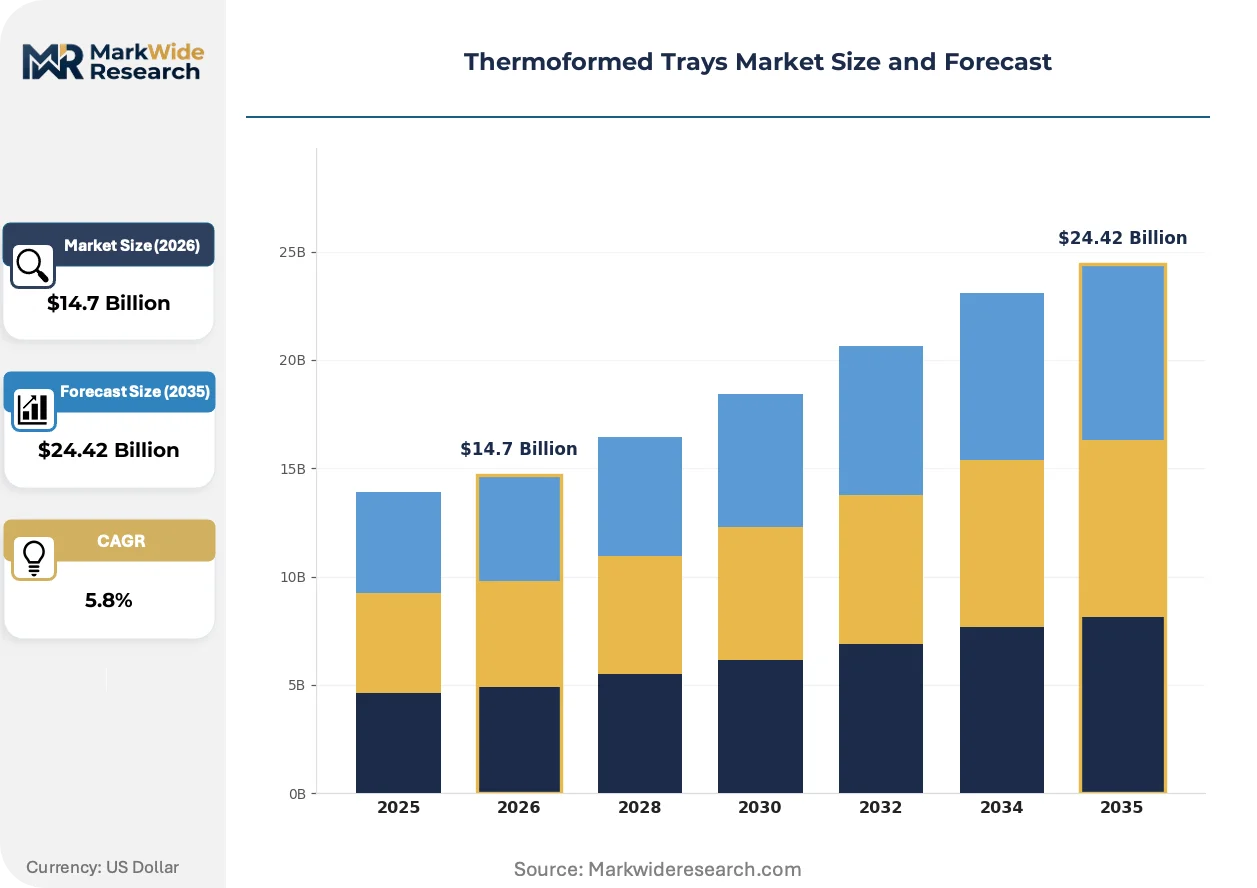
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $24.42 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Containers, Lids, Bases, Pallets Material Type: Polyethylene, Polypropylene, PS, PET Application: Food Packaging, Medical Packaging, Electronics, Industrial Supply End User: Food Manufacturers, Hospitals, Retailers, Warehouses |
| Companies Covered | Amcor plc, Pactiv LLC, Berry Global Inc, Sonoco Products Company, DS Smith, Placon Corporation, Nelipak Corporation, Huhtamaki, WestRock Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermoformed Trays Market Strategic Shifts
Material science advances and regulatory digitization are splitting the thermoformed tray market into parallel tracks: high-assurance medical packaging and cost-optimized consumer applications.
Multi-layer coextrusion technology is bifurcating the barrier tray segment. Advanced structures combining EVOH oxygen barriers with PET structural layers enable extended shelf-life pharmaceutical packaging. Large medical device OEMs specify these configurations for moisture-sensitive biologics. The technology is bifurcating supplier tiers, separating capital-intensive coextrusion operators from single-layer commodity converters.
REACH chemical restrictions are reshaping material composition roadmaps. ECHA's phthalate bans and emerging restrictions on intentionally added microplastics force reformulation of legacy PVC and certain plasticizer systems. Tray producers serving EU medical markets accelerate migration to phthalate-free polypropylene and PET-G alternatives. German compounders lead this transition with pre-validated medical-grade resin portfolios.
Hospital procurement consortia are consolidating supplier relationships. Group purchasing organizations in the United States and national tender systems in France aggregate demand across multiple device categories, compressing vendor counts. Tray manufacturers respond with multi-year sterilization service contracts bundling packaging with ethylene oxide or gamma processing. This consolidation is most visible in the US Midwest, where integrated health networks standardize barrier formats across affiliated surgical centers.
Thermoformed Trays Market Segmentation
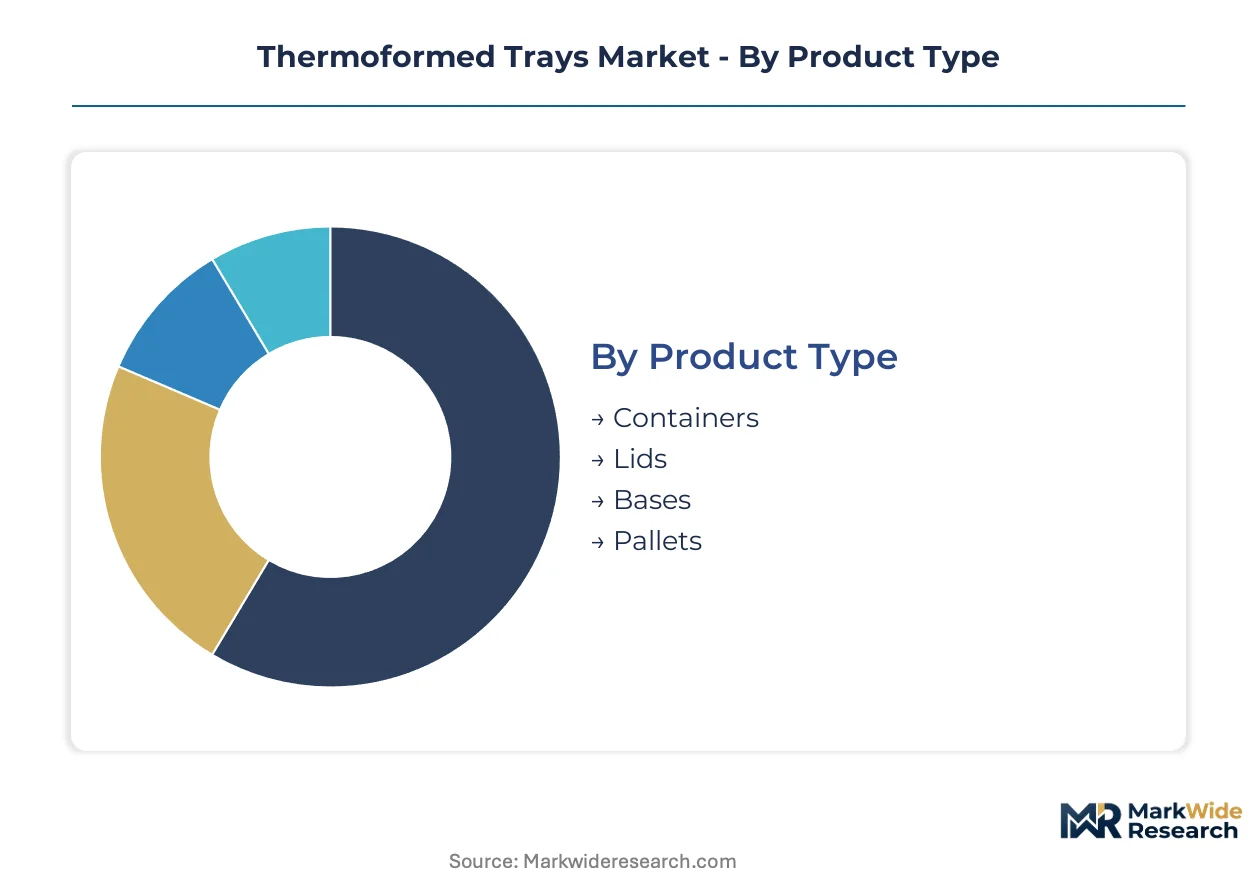
Thermoformed tray demand fragments across incompatible performance specifications. Medical sterilization requirements impose material purity thresholds that commodity food packaging cannot satisfy. This segmentation analysis maps where technical qualification barriers create pricing power versus where scale economies dominate.
Product Type:
Domestic consumption drives containers and lids through regional food service networks. Export-oriented medical device manufacturers source specialized bases and pallets through validated supply chains in Germany, Switzerland, and the United States.
- Containers:Deep-drawn structures with 0.020-0.060 inch wall thickness handle bulk food distribution and institutional meal preparation. German dual waste collection systems feed closed-loop PET recycling for this segment, though virgin resin price volatility compresses converter margins on fixed-price annual contracts.
- Lids:Thin-gauge formations (0.005-0.015 inch) provide sealing surfaces for modified atmosphere packaging. French and Italian retail consolidation favors standardized lid formats that reduce tooling changeover costs across high-volume production lines.
- Bases:Structural platforms for surgical kits and implant presentation.
- Pallets:Heavy-duty formats for automated warehouse handling systems.
Containers command the established base. The steepest expansion runs through bases serving EU MDR-validated medical workflows.
Material Type:
Cost tiers separate commodity polyethylene from pharmaceutical-grade alternatives. Recycled content mandates in France and Italy reshape material selection for non-medical applications.
- Polyethylene:Low-density formulations dominate disposable food service trays through extrusion-thermoforming integration. India's CDSCO-aligned pharmaceutical sector sources medical-grade HDPE for non-sterile secondary packaging of generic drug exports.
- PET:Amorphous and crystalline grades deliver optical clarity plus established mechanical recycling infrastructure. Germany's medical technology corridor around Tuttlingen specifies PET-G variants for gamma-sterilizable barrier applications requiring phthalate-free compliance under REACH restrictions.
- Polypropylene:Steam autoclave compatibility drives fastest medical adoption.
- PS:Polystyrene retains niche cost-sensitive food service positions.
PET commands the established base. Polypropylene gains share fastest through surgical kit sterilization requirements.
Application:
Volume concentration in food packaging contrasts with margin concentration in medical sterilization barriers. Electronics and industrial supply occupy intermediate positions on both dimensions.
- Food Packaging:Mature segment spanning retail ready meals, fresh produce containment, and food service disposables. DS Smith and European molded fiber competitors displace plastic formats in ambient retail channels through compostable alternatives, constraining growth in single-use thermoformed formats.
- Medical Packaging:Sterile barrier systems for devices, surgical kits, and implant presentation. FDA 21 CFR Part 820 quality system regulations and EU MDR sterilization validation requirements force 12-18 month qualification timelines, creating vendor stickiness and pricing premiums for qualified suppliers.
- Electronics:ESD-dissipative trays for component handling and shipping.
- Industrial Supply:Work-in-process containment for manufacturing logistics.
Food packaging commands the established base. Medical packaging climbs the fastest through regulatory-driven vendor consolidation.
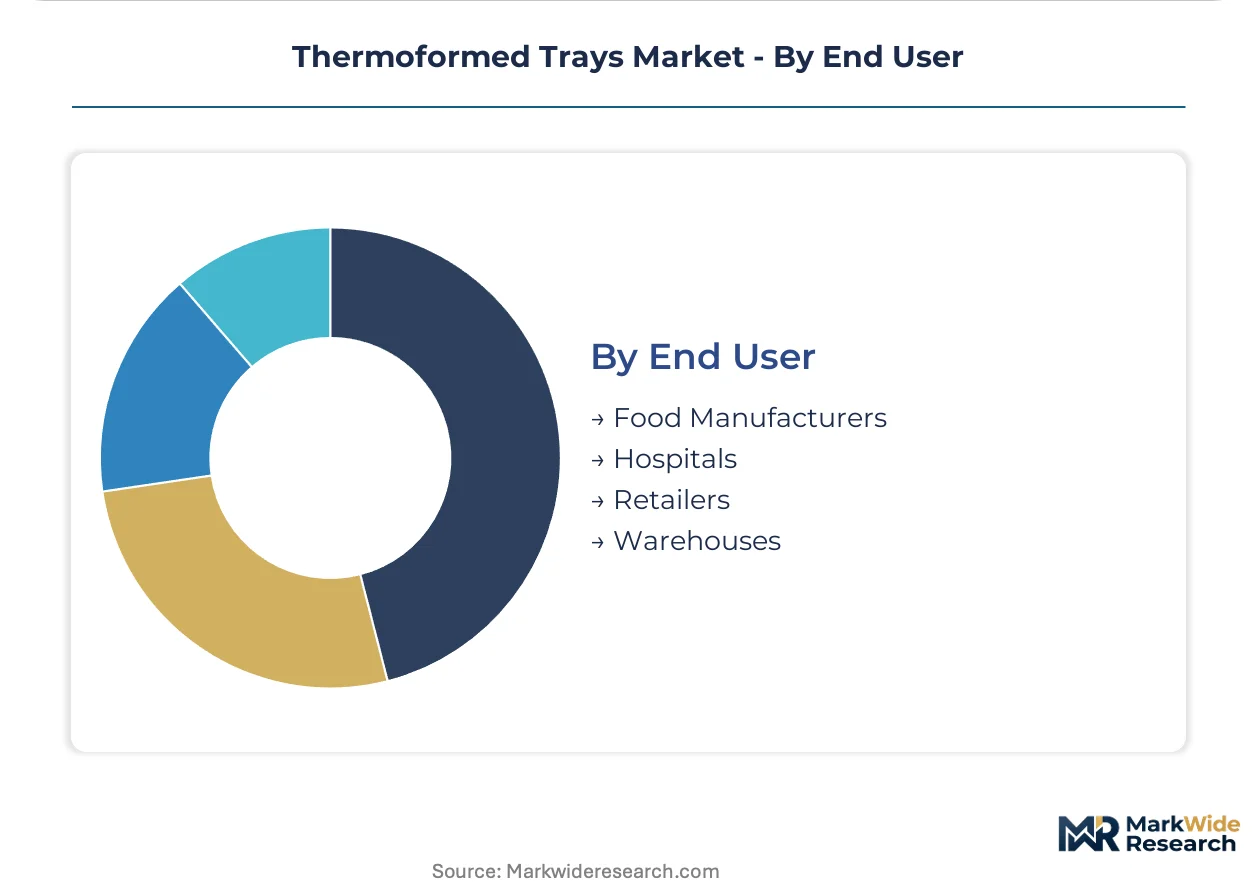
End User:
Customer procurement patterns split between price-tendered commodity contracts and multi-year sterilization service agreements. Hospital group purchasing organizations aggregate demand across device categories, compressing vendor counts.
- Food Manufacturers:High-volume buyers specifying standardized tray formats across automated filling lines. Pactiv LLC anchors North American supply through scale-driven sheet extrusion and forming operations, though resin price volatility squeezes margins on annual fixed-price commitments.
- Hospitals:Integrated health networks in the US Midwest standardize barrier formats across affiliated surgical centers. Amcor plc captures multi-year sterilization service contracts bundling thermoformed trays with ethylene oxide or gamma processing, leveraging pharmaceutical-grade cleanroom manufacturing networks.
- Retailers:Private-label food service and fresh produce presentation specifications.
- Warehouses:Automated material handling system integration requirements.
Food manufacturers command the established base. Hospitals climb the fastest through bundled sterilization service contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German medical device manufacturers export sterile barrier trays to North American hospital networks, creating a transatlantic trade corridor anchored by EU MDR compliance standards.
United States
FDA 21 CFR Part 820 quality system regulations drive sterile barrier validation protocols for surgical kit packaging. Hospital group purchasing organizations in the Midwest aggregate demand across integrated health networks, compressing vendor counts through multi-year sterilization service contracts. The Minneapolis corridor concentrates pharmaceutical-grade thermoforming capacity serving orthopedic implant manufacturers.
Germany
EU MDR sterilization validation mandates force documented sterile barrier integrity for medical device exports. REACH chemical restrictions and phthalate bans accelerate migration to PET-G and polypropylene alternatives. The Tuttlingen medical technology corridor hosts specialized cleanroom operations supplying precision surgical instrument packaging to European and Asian markets.
Switzerland
Swissmedic regulations align with EU MDR standards, enabling seamless cross-border supply into German and French medical device supply chains. Precision manufacturing traditions support high-assurance barrier systems for implantable devices. Basel and Zurich regions concentrate pharmaceutical packaging operations serving global biologics manufacturers.
India
CDSCO regulatory alignment with EU MDR positions Indian generic drug producers as export-oriented tray buyers for secondary pharmaceutical packaging. Domestic food service demand expands through quick-service restaurant chains and organized retail. Gujarat and Maharashtra industrial corridors attract thermoforming investments serving both pharmaceutical and consumer goods sectors.
France
Extended Producer Responsibility frameworks mandate recycled content thresholds for non-medical packaging applications. ANSM pharmaceutical regulations govern sterile barrier requirements for device distribution within French hospital networks. The Île-de-France region concentrates demand from centralized hospital procurement systems and retail consolidation.
Thermoformed Trays Market Competitive Environment
Listed leaders compete with private specialists across capital intensity and regulatory qualification dimensions. The market structure bifurcates between multinational packaging conglomerates with pharmaceutical-grade cleanroom networks and regional converters serving commodity food service segments. Three archetypes dominate: integrated healthcare packaging providers, scale-driven food service suppliers, and fiber-based material innovators. Competitive moves concentrate on cleanroom capacity expansion in regulated markets and backward integration into sheet extrusion to control resin cost exposure.
Among integrated healthcare packaging providers, Amcor plc and Nelipak Corporation exemplify the regulatory-qualification tier, occupying positions that bundle sterile barrier manufacturing with sterilization validation services. Pactiv LLC anchors the scale-driven food service segment through North American sheet extrusion and forming operations. DS Smith represents the fiber-based innovation vector, competing directly with plastic formats in European retail channels through compostable alternatives.
| Leading Market Players |
|---|
| Amcor plc |
| Pactiv LLC |
| Berry Global Inc |
| Sonoco Products Company |
| DS Smith |
| Placon Corporation |
| Nelipak Corporation |
| Huhtamaki |
| WestRock Company |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization differentials between pharmaceutical-grade cleanroom operations and commodity food-service extrusion lines create divergent price floors across the thermoformed tray market. German medical technology corridors command premium pricing through EU MDR-validated sterile barrier production, while scale-driven North American converters absorb resin volatility through annual fixed-price contracts with institutional food buyers.
Pricing Analysis
Single-layer commodity thermoforming, multi-layer coextrusion barrier systems, and next-generation RFID-embedded traceable formats stratify across three performance tiers. Pricing separates gamma-sterilizable PET-G medical grades from steam-compatible polypropylene and standard polyethylene food-service formats, with certification under FDA 21 CFR Part 820 and ISO 13485 commanding substantial premiums. Cost compression in commodity food packaging intensifies as DS Smith fiber alternatives displace plastic volumes in European retail channels. Hospital group purchasing organizations exhibit lowest price sensitivity through bundled sterilization service contracts, while quick-service restaurant chains drive hardest bargaining on standardized container specifications.
Supply Chain Analysis
Inventory cycles for medical-grade resin validation extend 12-18 months, creating pronounced lead-time asymmetries between qualified pharmaceutical supply chains and commodity converters. Raw material sourcing draws from Saudi petrochemical feedstock, German compounding operations for medical-grade polypropylene, and post-consumer PET reclamation facilities in France and Italy. Single-source vulnerability concentrates in Switzerland-Germany pharmaceutical-grade cleanroom capacity clusters. Distribution runs through validated logistics networks for sterile barrier applications and regional sheet extrusion integration for food-service disposables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive outcomes as RFID-embedded traceability and sterilization-as-a-service bundling transform standalone tray manufacturing into integrated healthcare packaging ecosystems. Interoperability between thermoformed barriers and automated hospital inventory systems creates winner-take-most dynamics.
For Market Incumbents: Fortify cleanroom capacity positions in Germany's Tuttlingen corridor and the US Minneapolis medical technology cluster against fiber-based substitution threats from DS Smith and European molded fiber competitors. Prioritize backward integration into medical-grade resin compounding to capture margin currently flowing to German specialty compounders, while accelerating multi-year sterilization service contracts that bundle ethylene oxide and gamma processing with barrier supply. For New Entrants and Emerging Players: Lead with CDSCO-aligned regulatory positioning to capture Indian pharmaceutical export demand for secondary packaging of generic drug shipments. The most penetrable white space sits in RFID-embedded surgical kit trays serving mid-tier US hospital networks outside consolidated group purchasing organization contracts. Pursue white-label manufacturing partnerships with established sterilization service providers to bypass 12-18 month ISO 13485 qualification timelines. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors pharmaceutical-grade cleanroom operators with validated EU MDR and FDA dual-qualification status over commodity food-service scale players facing fiber substitution headwinds. Acquisition targets should display captive sterilization service relationships and multi-year hospital system contracts. Watch for inflection signals in French and Italian Extended Producer Responsibility enforcement thresholds that would accelerate recycled content mandates and reshape feedstock economics.| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Capacity Expansion | EU MDR validation requirements concentrate supply in Germany and Switzerland, creating scarcity rents for qualified operators. |
| Backward Integration into Resin Compounding | Captive supply of medical-grade polypropylene and PET-G insulates margins from petrochemical feedstock volatility. |
| RFID-Enabled Traceability Development | Convergence with printed electronics enables unit-level sterilization tracking for high-value implant packaging workflows. |
| Sterilization Service Bundling | Multi-year contracts combining ethylene oxide or gamma processing with barrier supply lock in hospital procurement relationships. |
| Recycled Content Certification | France and Italy EPR frameworks reward early movers with certified circular feedstock for non-medical tray applications. |
Study Parameters
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings in documented sterilization validation protocols and supply chain configurations. Conversations with biomedical engineers, hospital GPO contracts managers, pharmaceutical packaging procurement leads, and cleanroom operations directors informed demand-side segmentation. Secondary sources include FDA 510(k) submissions, EU MDR technical documentation, ECHA REACH restriction dossiers, and customs trade data for thermoplastic sheet imports. Bottom-up capacity estimates for pharmaceutical-grade cleanroom operations were triangulated against top-down medical device packaging spend allocations.
Sensitivity analysis tested forecast outputs against resin price volatility scenarios and regulatory timeline acceleration assumptions across the projection horizon. The analytical framework models demand by product type, material grade tier, sterilization compatibility requirement, and end-user procurement pattern. CAGRs were derived from segmented volume build-ups incorporating medical device OEM packaging roadmaps and food service disposable consumption trends. Industry-specific inputs include EU MDR implementation pace, CDSCO regulatory alignment progress, and fiber substitution rates in European retail channels.
The analysis sits within stated boundaries; outcomes outside sustained EU MDR enforcement intensity, stable petrochemical feedstock pricing, or continued hospital consolidation trajectories would require recalibration. Forecasts reflect assumptions about qualification timeline durations and sterilization modality preferences that could shift with emerging alternative technologies. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Postal Packaging Market
Packaging Materials
Plastic Strapping Materials Market
Packaging Materials
Mylar Market
Packaging Materials
Die Cut Support Pads Market
Packaging Materials
Graphene Infused Packaging Market
Packaging Materials
Thermoformed Skin Packaging Market
Packaging Materials
Anti-Static Liners Market
Packaging Materials
Asia-Pacific Airless Packaging Market
Packaging Materials
Organic Substrate Packaging Material Market
Packaging Materials
Battery Packaging Material Market
Packaging Materials
Middle East and Africa Single-Use Packaging Market
Packaging Materials
Cement Packaging Market
Packaging Materials
Squeeze Tube Market
Packaging Materials
Punnet Packaging Market
Packaging Materials
Myanmar Packaging Market
Packaging Materials
Asia - Pacific Disposable Tableware Market