
 Bakeable Trays Market | 2026-2036
Bakeable Trays Market Size, Share, and Industry Trends Forecast 2026-2036
Bakeable Trays Market Analysis
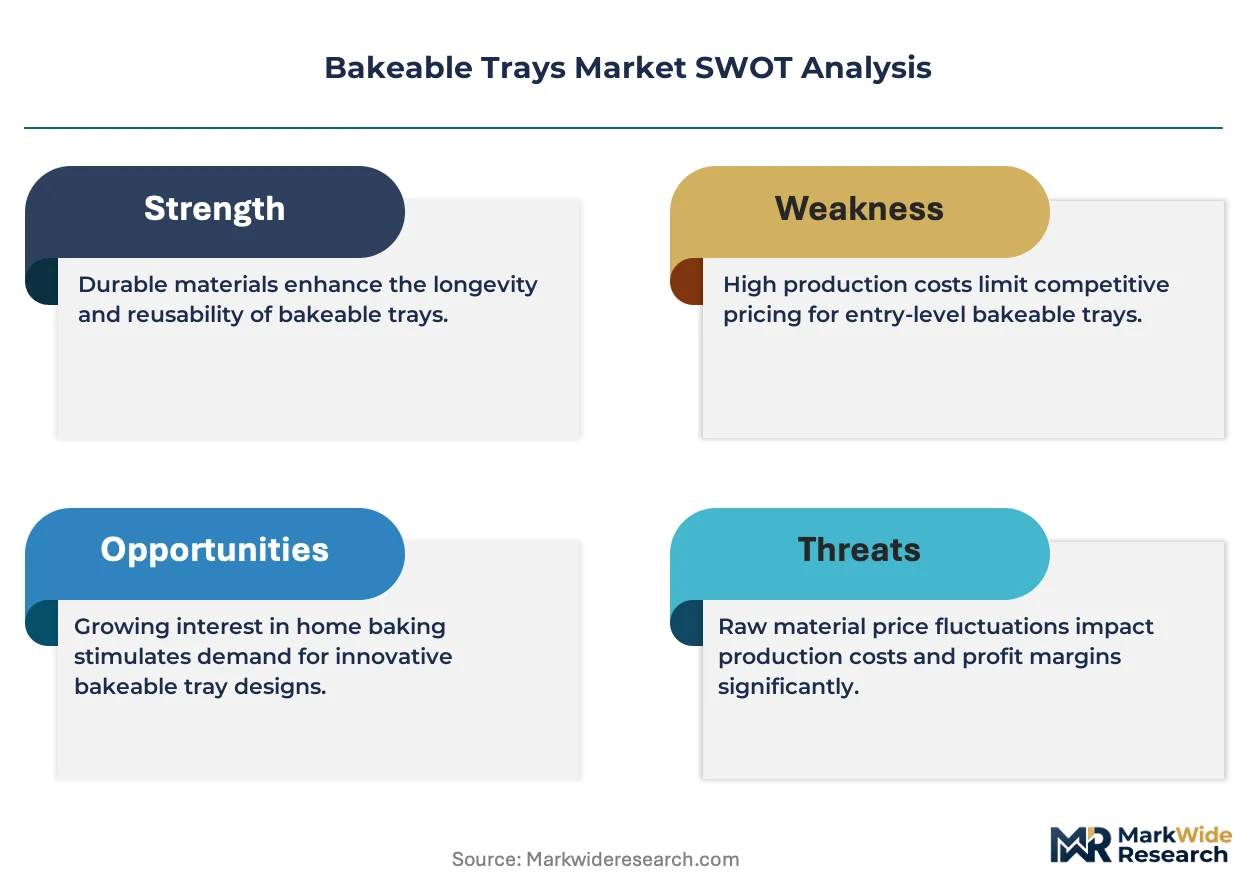
Subscription-based tray refurbishment and coating renewal services is rebalancing how commercial buyers manage capital expenditure versus operating expense. Huhtamaki BCP Ltd. leverages its European manufacturing footprint to sustain long-term supply agreements with industrial bakeries. Pactiv Evergreen Inc. anchors North American distribution through direct channel control over foodservice operators. Amcor competes on material science leadership, extending its barrier-coating expertise into high-temperature applications.
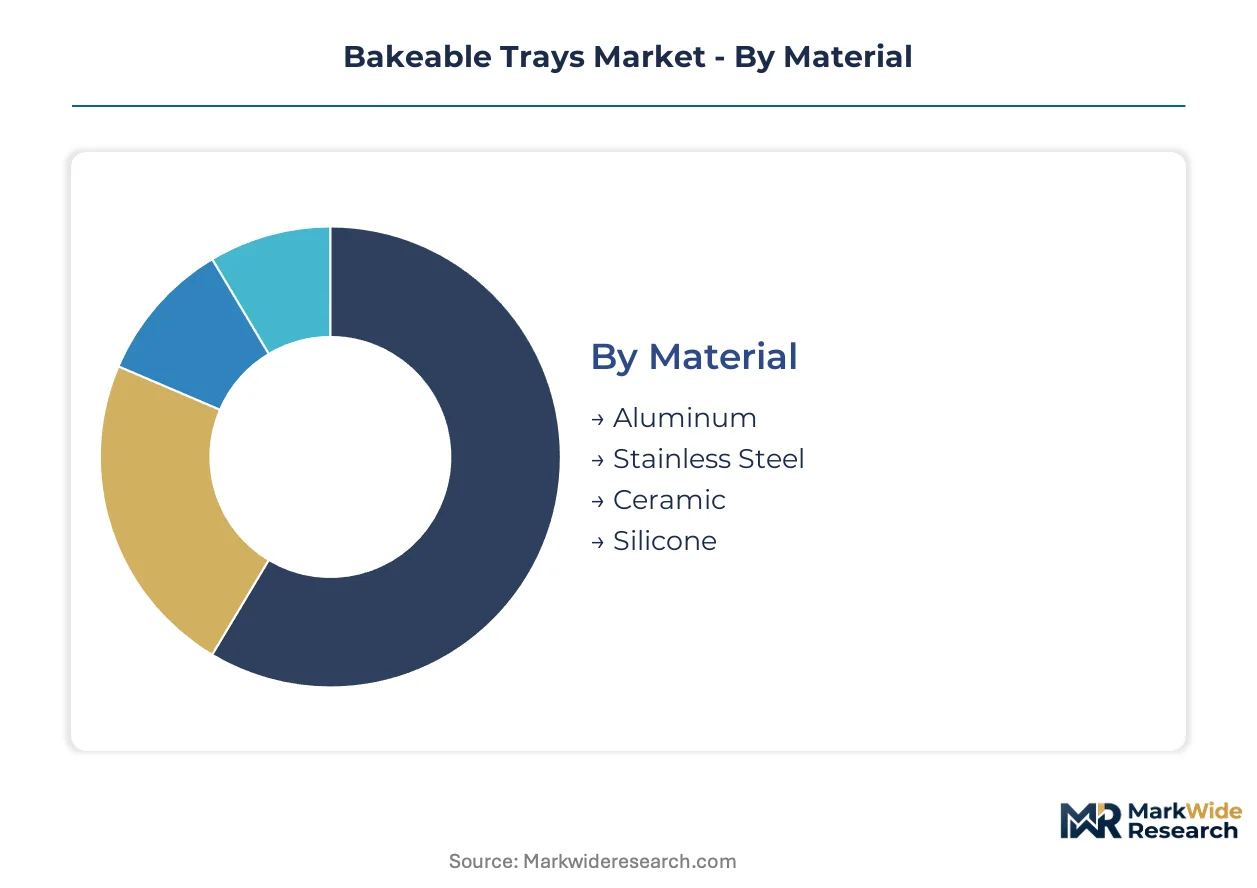
Bakeable trays are rigid or semi-rigid containers engineered from aluminum alloys, stainless steel, ceramic composites, or silicone elastomers, typically rated for sustained oven temperatures exceeding 200°C, designed to support thermal conduction and structural integrity during commercial baking and food preparation cycles. Aluminum dominates unit volume due to cost-efficient thermal performance and recyclability, while silicone represents the fastest-expanding material segment driven by flexibility and reduced sticking properties. Non-stick coatings command premium positioning and repeat-purchase revenue, whereas traditional uncoated surfaces occupy commodity tiers in high-volume institutional settings.
The FDA governs food-contact substances under 21 CFR regulations, directly influencing coating formulations and migration testing protocols for bakeable trays sold into United States foodservice channels. The EPA's per- and polyfluoroalkyl substance restrictions are forcing coating suppliers toward ceramic and sol-gel alternatives, reshaping R&D allocation across the supply base. ISO 9001 and ISO 22000 certifications function as baseline market-access requirements for contract manufacturers serving multinational bakery chains. Stakeholders must monitor evolving state-level chemical disclosure mandates and assess whether coating technology roadmaps align with anticipated regulatory timelines.
Market Dynamics
Coating chemistry transitions driven by EPA per- and polyfluoroalkyl substance restrictions are restructuring supplier R&D priorities and procurement specifications across commercial bakery supply chains.
Growth Catalysts
- Commercial bakery expansion:Industrial-scale bread and pastry production facilities in Germany and France are accelerating replacement cycles for oven-rated containers to match higher throughput demands.
- REACH compliance migration:European coating suppliers are reformulating sol-gel and ceramic alternatives ahead of ECHA substance restrictions, creating certified-product preference premiums.
- Silicone elastomer performance:Flexibility and release properties of food-grade silicone trays are displacing rigid formats in artisan and specialty baking segments.
Market Restraints
- Aluminum price volatility:LME aluminum contract fluctuations compress margin stability for tray fabricators dependent on rolled alloy feedstock.
- Coating supply concentration:Fluoropolymer alternative chemistry development clusters among three German specialty chemical suppliers, creating single-source risk.
- Ceramic coating durability limits:Sol-gel surface treatments exhibit accelerated wear above 250°C sustained cycles, restricting application in high-temperature industrial ovens.
Strategic Opportunities
- India foodservice modernization:Quick-service bakery chains in Mumbai and Bangalore are adopting standardized bakeable tray formats for central kitchen consistency.
- Subscription refurbishment services:Coating renewal and structural inspection programs convert capital equipment into recurring revenue relationships with industrial bakeries.
- EU Green Deal alignment:Recyclable aluminum tray circularity claims supported by EMAS-registered remelting facilities command procurement preference from sustainability-mandated buyers.
Industry Challenges
- Migration testing expertise shortage:Qualified analytical chemists capable of executing FDA 21 CFR food-contact substance protocols remain scarce in contract testing laboratories.
- ISO 22000 certification timelines:HACCP integration and documentation requirements extend supplier qualification periods for multinational bakery chain contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bakeable Trays Market |
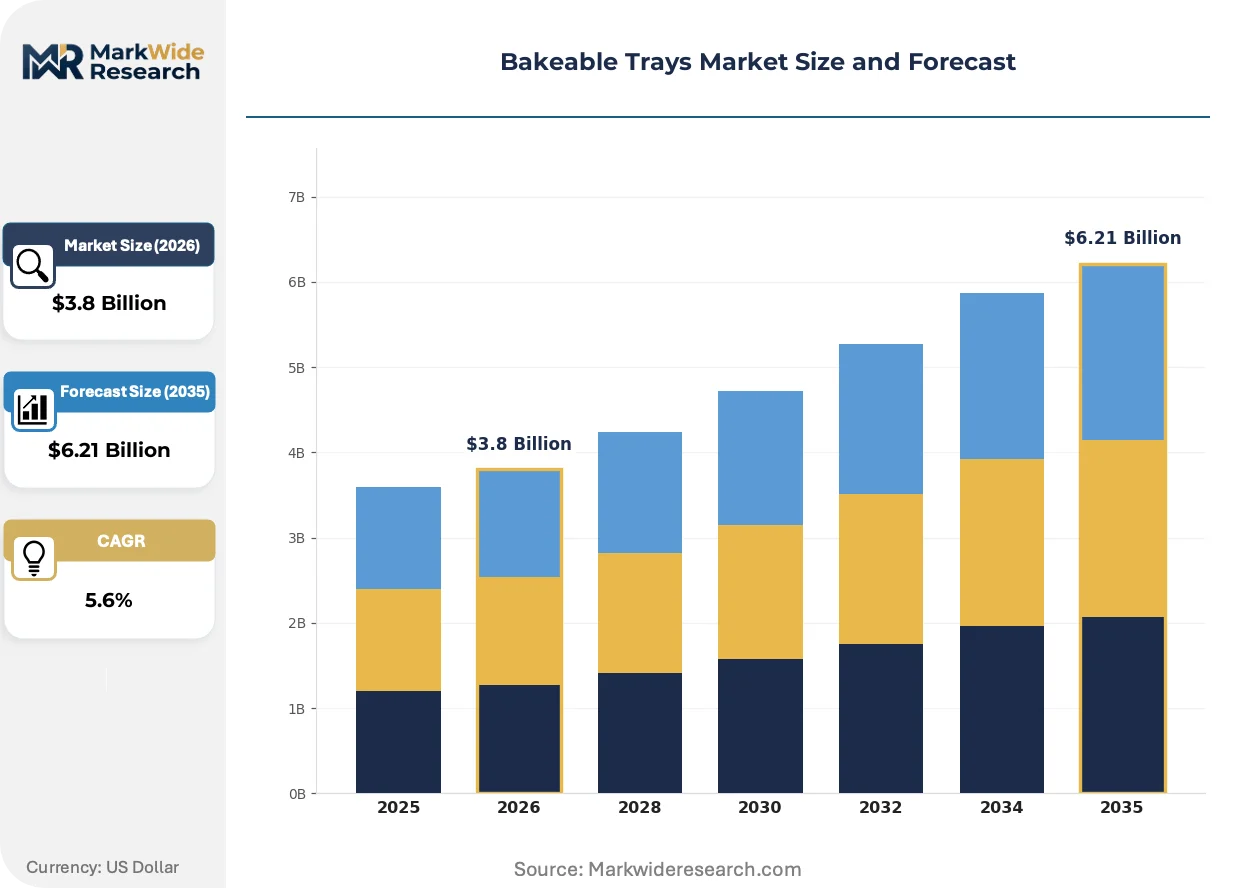
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Aluminum, Stainless Steel, Ceramic, Silicone Size: Small, Medium, Large, Extra Large Shape: Rectangular, Round, Square, Oval Coating Type: Non-stick, Traditional, Anodized, Others |
| Companies Covered | Genpak LLC, Huhtamaki BCP Ltd., Northland Aluminum Products Inc., Menasha Corporation, iVEX Protective Packaging Inc., Pactiv Evergreen Inc., Amcor, Graphic Packaging Holding Company, EasyPak LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bakeable Trays Market Emerging Trajectories
Active coating reformulation and procurement model restructuring are compressing traditional supply relationships while elevating material science capabilities as a competitive differentiator.
Ceramic and sol-gel non-stick coatings are consolidating market position as EPA restrictions eliminate legacy fluoropolymer options from new product development pipelines. Mid-sized industrial bakeries in Italy and Spain are adopting these alternatives at accelerated rates despite 15-20% unit cost premiums. The technology is consolidating supplier bases toward chemical firms with in-house high-temperature formulation expertise.
ECHA substance evaluation under REACH Annex XV is forcing coating manufacturers to submit extended technical dossiers for ceramic precursor chemistries. Industrial consequence includes 18-24 month registration delays for novel surface treatments. German and Dutch bakery equipment OEMs are responding by pre-qualifying alternative suppliers before legacy coating obsolescence deadlines.
Direct long-term supply agreements between tray fabricators and industrial bakery chains are displacing distributor-mediated spot purchasing in North American and European markets. Foodservice operators with 50+ outlet networks now negotiate coating refresh schedules and volume commitments directly with manufacturing partners. This pattern is most visible in Germany's Mittelstand bakery sector, where family-owned chains consolidate procurement through single-source tray lifecycle contracts.
Bakeable Trays Market Segmentation
Segmentation in bakeable trays determines replacement cadence, coating refurbishment economics, and thermal specification matching across industrial bakery equipment fleets. Material and coating combinations dictate capital allocation between disposable formats and capital-intensive reusable systems.
Material:
Upgrade cycles for industrial baking equipment drive material selection, with thermal conductivity requirements and recyclability mandates reshaping procurement priorities.
- Aluminum:Rolled alloy substrates deliver cost-efficient heat distribution and full recyclability through EMAS-registered remelting streams. German commercial bakeries favor aluminum for high-throughput bread lines where rapid thermal response reduces cycle times.
- Silicone:Food-grade elastomer formulations provide flexibility and superior release properties without surface coatings. Artisan bakeries in France and specialty producers in Italy are displacing rigid formats for delicate pastry applications.
- Stainless Steel:Austenitic grades withstand mechanical abrasion and aggressive cleaning protocols in institutional foodservice settings.
- Ceramic:Composite structures tolerate extreme thermal shock for pizza and hearth-bread applications requiring sustained temperatures above 280°C.
Aluminum sits at the top of the volume ranking, with silicone climbing the fastest.
Size:
Equipment standardization across quick-service bakery chains is consolidating demand toward formats compatible with automated loading systems and conveyorized ovens.
- Medium:Dimensions matching European EN-standard rack ovens dominate contract manufacturing volumes for central kitchen operations. Mumbai and Bangalore quick-service chains specify medium formats for cross-location equipment compatibility.
- Large:Industrial-scale dimensions align with automated depanning systems in high-capacity bread facilities. German Mittelstand bakery chains negotiate lifecycle contracts around large-format standardization to reduce SKU complexity.
- Small:Compact dimensions serve countertop convection ovens in café and small-batch artisan settings.
- Extra Large:Custom dimensions accommodate specialty equipment for frozen dough-to-oven operations.
Medium formats command the highest procurement volumes, while large formats gain share fastest through central kitchen consolidation.
Shape:
Product geometry requirements and oven chamber configurations determine shape preference, with rectangular formats dominating industrial lines and round formats persisting in artisan segments.
- Rectangular:Standardized length-to-width ratios optimize rack loading density and automated handling in continuous production environments. French industrial bakeries specify rectangular formats for baguette and sandwich bread lines.
- Round:Curved geometries suit pizza, tart, and cake applications where uniform edge browning matters. Italian specialty producers maintain round-format procurement for traditional product categories.
- Square:Equal-edge dimensions serve portion-controlled meal preparation and ready-to-eat tray bake applications.
- Oval:Elongated curves accommodate artisan bread shapes and roasting applications requiring presentation aesthetics.
Rectangular shapes anchor procurement volumes, with round formats expanding most quickly through artisan segment premiumization.
Coating Type:
Regulatory pressure on fluoropolymer chemistries is restructuring coating selection, with ceramic and sol-gel alternatives capturing procurement specifications previously held by legacy non-stick systems.
- Non-stick:Ceramic and sol-gel surface treatments now dominate new product development as EPA restrictions eliminate PTFE options. Spanish and Italian mid-sized bakeries absorb 15-20% unit cost premiums to secure REACH-compliant alternatives ahead of ECHA deadlines.
- Traditional:Uncoated metal surfaces occupy commodity tiers where aggressive mechanical cleaning and high-temperature durability outweigh release performance requirements.
- Anodized:Electrochemical oxide layers on aluminum provide moderate corrosion resistance without organic coatings, serving institutional buyers with chemical-sensitivity protocols.
- Others:Emerging plasma-deposited and hybrid ceramic-metallic treatments target niche high-temperature applications above 250°C sustained cycles.
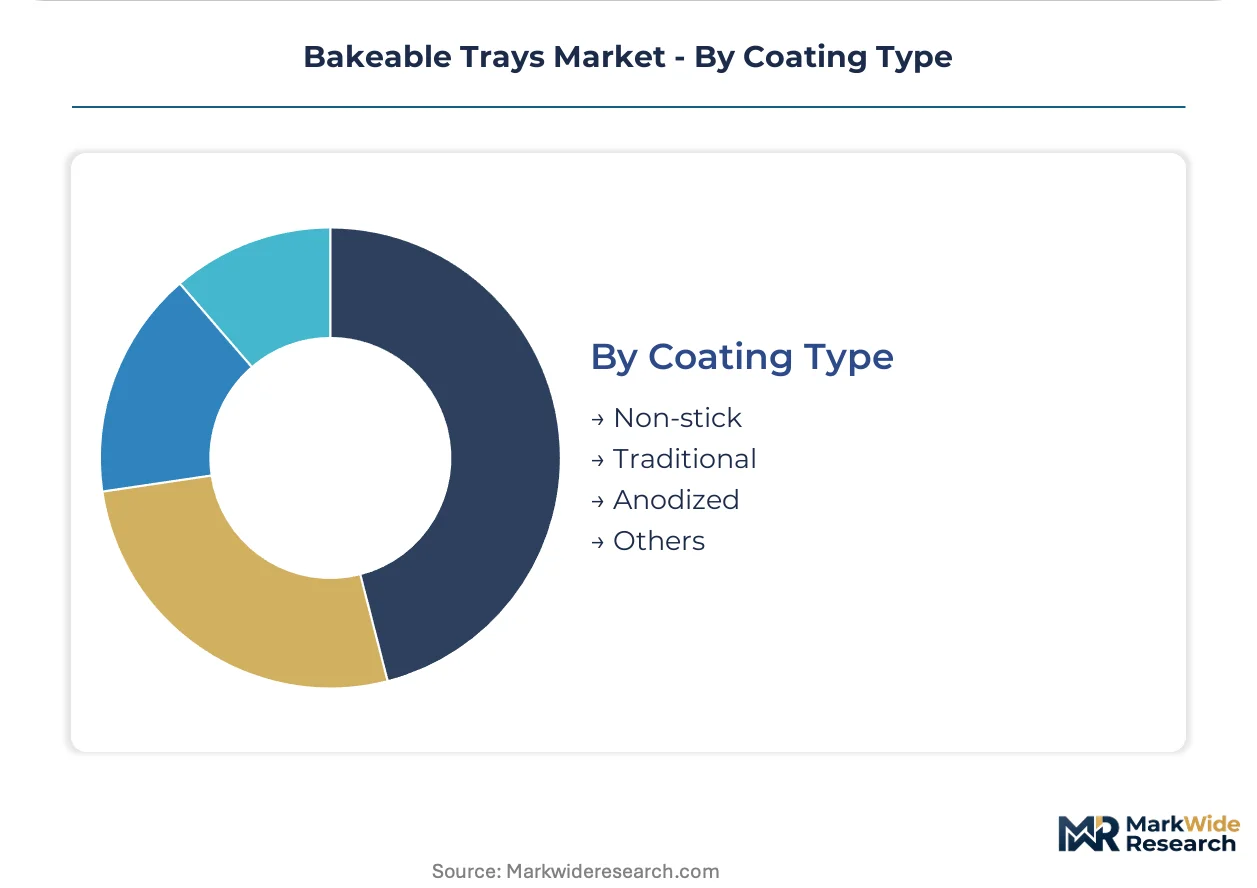
Non-stick coatings lead value concentration, with anodized formats gaining share fastest through chemical-compliance positioning in institutional channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium tray replacement cycles through dense industrial baking equipment networks, while India quick-service chains in Mumbai and Bangalore are just beginning standardized format adoption for central kitchen consistency.
United States
Foodservice operators with 50-plus outlet networks negotiate coating refresh schedules directly with manufacturing partners, bypassing traditional distributors. FDA 21 CFR food-contact substance regulations govern coating formulations and migration testing protocols for all trays sold into domestic channels. Chicago and Minneapolis industrial bakery clusters anchor procurement volumes for large-format aluminum systems.
Germany
Family-owned Mittelstand bakery chains consolidate procurement through single-source tray lifecycle contracts covering standardization and refurbishment. ECHA substance evaluation under REACH Annex XV forces 18-24 month registration delays for novel ceramic precursor chemistries. Stuttgart and Munich equipment OEMs pre-qualify alternative coating suppliers ahead of legacy fluoropolymer obsolescence deadlines.
France
Industrial bakeries specify rectangular formats for baguette and sandwich bread lines, matching standardized rack oven dimensions. EU Green Deal circularity claims supported by EMAS-registered aluminum remelting facilities command procurement preference from sustainability-mandated buyers. Lyon and Lille production facilities drive replacement cycle acceleration to match higher throughput demands.
Italy
Mid-sized industrial bakeries absorb 15-20% unit cost premiums for ceramic and sol-gel REACH-compliant coating alternatives ahead of regulatory deadlines. Artisan producers maintain round-format procurement for traditional pastry categories where uniform edge browning matters. Bologna and Parma specialty baking clusters displace rigid formats with food-grade silicone trays for delicate applications.
India
Quick-service bakery chains adopt standardized medium-format trays for cross-location equipment compatibility in emerging central kitchen operations. FSSAI food safety standards shape coating chemistry selection for imported and domestically manufactured bakeable containers. Mumbai and Bangalore foodservice modernization programs drive first-time procurement of oven-rated container systems at scale.
Bakeable Trays Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium coating tiers consolidating around chemical firms with in-house high-temperature formulation expertise while commodity aluminum fabrication fragments across regional metalworkers. Three strategic archetypes dominate: integrated packaging conglomerates with European manufacturing footprints, North American foodservice distributors with direct channel control, and material science leaders extending barrier-coating expertise into high-temperature applications. M&A activity clusters around coating technology assets, while capacity expansion concentrates in EMAS-registered aluminum remelting corridors.
Among the integrated packaging tier, Huhtamaki BCP Ltd. and Pactiv Evergreen Inc. exemplify divergent geographic anchoring strategies, with the former leveraging European manufacturing presence for long-term supply agreements and the latter controlling North American distribution through direct foodservice relationships. Amcor occupies a position on the material science vector, representing the archetype of barrier-coating specialists extending technical capabilities into oven-rated applications.
| Leading Market Players |
|---|
| Genpak LLC |
| Huhtamaki BCP Ltd. |
| Northland Aluminum Products Inc. |
| Menasha Corporation |
| iVEX Protective Packaging Inc. |
| Pactiv Evergreen Inc. |
| Amcor |
| Graphic Packaging Holding Company |
| EasyPak LLC |
| Others |
Supply Flow & Price Mechanics
LME aluminum contract fluctuations cascade through rolled alloy feedstock costs into three-tier pricing structures across premium, standard, and economy levels for bakeable tray procurement. German fabricators pass volatility into annual contract escalators while spot purchasers absorb margin compression.
Pricing Analysis
Capacity additions in Germany are reshaping price floors for EMAS-registered aluminum tray remelting. Three-tier pricing structure across premium, standard, and economy levels separates REACH-compliant ceramic-coated formats from traditional uncoated commodity tiers. Price differentiation hinges on ISO 22000 certification tier and volume scale commitments. Cost compression in standard-tier silicone trays is intensifying because Italian mid-sized bakeries absorb 15-20% premiums for regulatory-compliant alternatives. Institutional foodservice operators exhibit highest price sensitivity; Mittelstand bakery chains with lifecycle contracts demonstrate lowest.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Munich, and Lyon anchor hub-and-spoke patterns for European industrial bakery supply. Manufacturing concentrates in Germany, France, and Italy. Raw material flows draw from LME-registered aluminum smelters, German specialty chemical suppliers for sol-gel precursors, and food-grade silicone elastomer compounders. Single-source vulnerability clusters among three German coating chemistry developers. Distribution runs through direct long-term agreements between fabricators and 50-plus outlet bakery chains, bypassing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bakeable trays constitute a late-cycle quality story as EPA fluoropolymer restrictions and REACH Annex XV deadlines force procurement shifts toward premium ceramic and sol-gel specifications. Industrial bakeries now prioritize coating durability and compliance certification over unit cost minimization.
For Market Incumbents: Acquire ceramic precursor formulation expertise from German specialty chemical suppliers before ECHA registration deadlines eliminate legacy coating options. Backward integration into EMAS-registered aluminum remelting secures circularity claims for EU Green Deal-mandated buyers. Channel control through direct lifecycle contracts with Mittelstand bakery chains defends against distributor disintermediation. For New Entrants and Emerging Players: Sol-gel coating durability above 250°C sustained cycles offers a technology-first wedge into high-temperature industrial oven segments where incumbent ceramic treatments fail. White-space targets include India's quick-service bakery central kitchen operations in Mumbai and Bangalore, and artisan silicone tray displacement of rigid formats in Italian specialty segments. Go-to-market through FSSAI pre-certified product lines accelerates import substitution. For Investors and Strategic Acquirers: Asymmetric upside sits with coating technology specialists possessing in-house high-temperature formulation capabilities and existing REACH dossier submissions. Long-term viability over the projection horizon favors assets with demonstrated migration testing expertise for FDA 21 CFR compliance. Watch ECHA substance evaluation timelines for ceramic precursor chemistries as inflection indicators for supplier consolidation windows.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Coating Reformulation | EPA restrictions eliminate PTFE options, forcing 18-24 month R&D cycles for sol-gel alternatives. |
| Direct Lifecycle Contracting | Foodservice operators with 50-plus outlets negotiate coating refresh schedules directly with fabricators. |
| EMAS-Registered Remelting Integration | EU Green Deal circularity claims command procurement preference from sustainability-mandated bakery chains. |
| Subscription Refurbishment Services | Coating renewal programs convert capital equipment into recurring revenue with industrial bakeries. |
| India Central Kitchen Standardization | Quick-service chains in Mumbai and Bangalore adopt medium-format trays for cross-location compatibility. |
Methodological Framework
Multiple input streams — primary interviews with industrial bakery procurement directors, coating R&D leads, and foodservice equipment OEMs; secondary validation through FDA 21 CFR filings, ECHA REACH Annex XV dossiers, and EMAS facility registrations; plus customs trade data for aluminum alloy feedstock flows — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across material segmentation, coating chemistry tiers, and regional regulatory clusters anchored volume and value projections over the analysis window. CAGRs derived from replacement cycle analysis, central kitchen expansion rates, and coating reformulation adoption curves. Forecast inputs incorporated LME aluminum price trajectory assumptions and ECHA substance evaluation timeline probabilities.
The model holds under stable regulatory enforcement timelines and sustained industrial bakery capacity expansion; deviation in EPA enforcement intensity or ECHA registration delays would shift coating chemistry adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Production Page Volume Market
Packaging Materials
Kraft Packaging Market
Packaging Materials
Refrigerator Door Seal Gaskets Market
Packaging Materials
Spices, Dry Mixes and Extracts Packaging Market
Packaging Materials
MDO Films Market
Packaging Materials
Chemical Packaging Market
Packaging Materials
PET Strap Market
Packaging Materials
Mylar Market
Packaging Materials
PCR Thermoforms Market
Packaging Materials
Insulated Box Liner Market
Packaging Materials
Single Dose Detergent Packaging Market
Packaging Materials
Thermoformed Skin Packaging Market
Packaging Materials
Tube and Stick Packaging Market
Packaging Materials
Aerosol Packaging Market
Packaging Materials
Cork Packaging Market
Packaging Materials
VCI Shrink Films Market