
 Europe Personal Care Plastic Tube Packaging Market | 2026-2036
Europe Personal Care Plastic Tube Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Personal Care Plastic Tube Packaging Market Insights
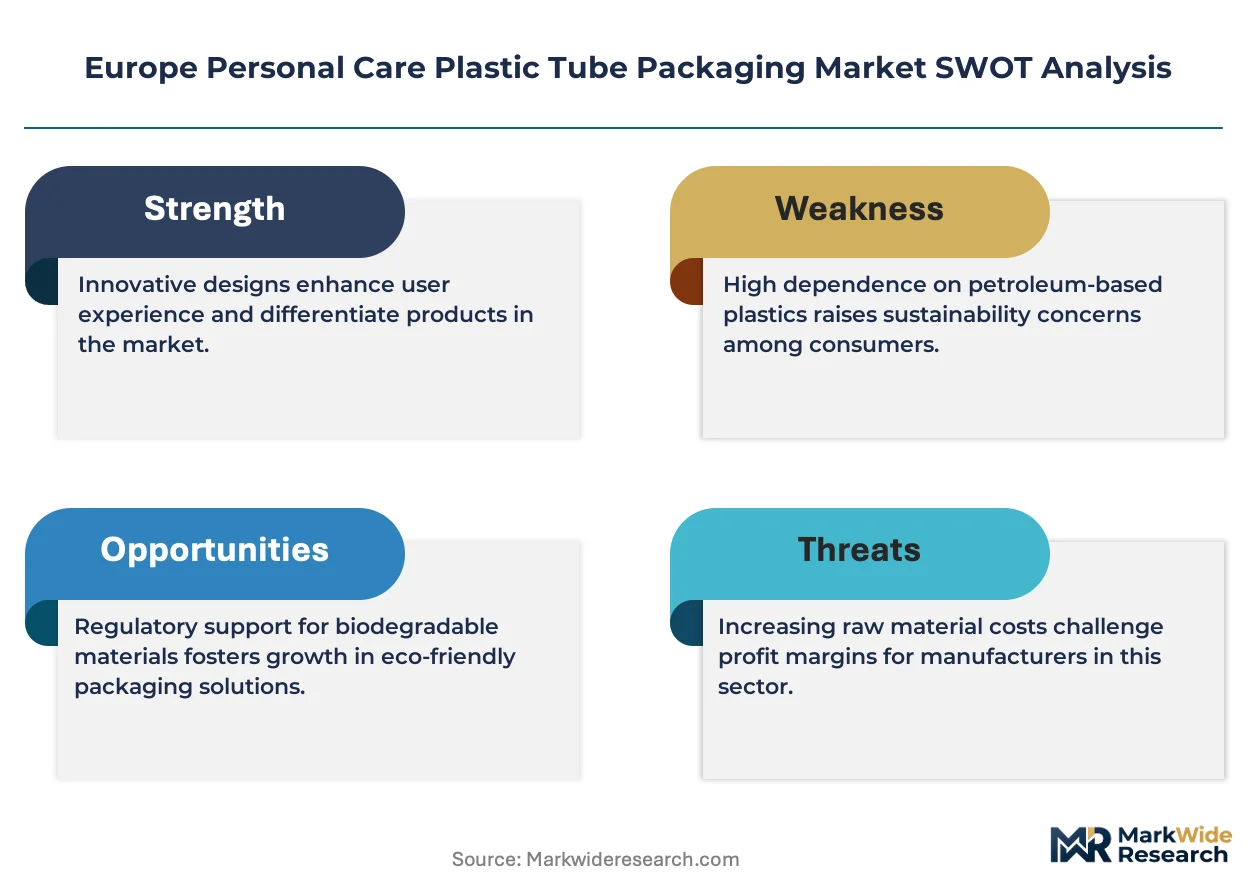
The EU Packaging and Packaging Waste Regulation is recalibrating the cost-of-entry calculus for tube converters across Europe. Berry Global Inc leverages its multi-site extrusion footprint to sustain compliance-ready material streams. Albéa Group anchors its competitive position through specialized laminate and mono-material tube platforms. Hoffmann Neopac AG differentiates via high-barrier solutions for premium skincare applications.
Europe personal care plastic tube packaging comprises extruded or coextruded cylindrical containers, typically 15–200 ml capacity, with multilayer or mono-material walls sealed by heat-sealed crimp or welded heads, designed for viscous product dispensing with controlled dosage and shelf-life protection. Cosmetic tubes lead volume consumption given mascara, foundation, and hair care formats, while bioplastics represents the fastest-expanding material category as beauty brands pursue renewable content claims. LDPE retains structural dominance in mass-market oral care and shampoo segments where cost efficiency and established recycling pathways outweigh premium material substitution.
REACH compliance, CE marking requirements, and the EU Green Deal's packaging waste targets collectively constrain material choices and mandate design-for-recycling protocols across the value chain. ECHA substance restrictions and national extended producer responsibility schemes tighten further, elevating documentation and testing burdens for tube suppliers. Stakeholders must monitor regulatory implementation timelines and pre-emptively revalidate material portfolios against evolving recyclability criteria.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing tube converters to reengineer material formulations and scrap legacy multilayer structures before recyclability mandates take full effect.
Growth Catalysts
- Skincare format expansion:Serum and cream brands are migrating from jars to tubes as controlled-dosage dispensing becomes a hygiene priority for German and French consumers.
- REACH substance restrictions:ECHA's tightening limits on phthalates and heavy metals are accelerating adoption of bio-based PE and PP alternatives that satisfy compliance without performance trade-offs.
- Italy's recycling infrastructure:Northern Italian converters benefit from advanced mechanical recycling streams that accept mono-material LDPE tubes at scale, lowering circularity costs versus mixed-laminate alternatives.
Market Restraints
- Ethylene feedstock volatility:LDPE and LLDPE resin prices fluctuate with naphtha and natural gas benchmarks, compressing converter margins on fixed-price annual contracts with mass-market oral care brands.
- Barrier property limitations:Mono-material tubes struggle to match aluminum-laminate oxygen transmission rates for vitamin C serums and retinol formulations, restricting addressable premium applications.
- Extended producer responsibility fees:France's Citeo and Germany's Der Grüne Punkt schemes impose per-unit packaging taxes that disproportionately burden small-batch cosmetic tube runs.
Strategic Opportunities
- Poland and Czech Republic manufacturing:Central European locations offer labor cost advantages and proximity to expanding beauty brand distribution centers serving Eastern European markets.
- Pharmaceutical tube qualification:CE-marked medical device tube production for dermatological prescriptions commands price premiums and longer contract durations versus commoditized cosmetic segments.
- Digital printing integration:Direct-to-tube inkjet decoration eliminates label substrates and enables short-run personalization for influencer collaboration drops and limited-edition skincare lines.
Industry Challenges
- Mono-material validation timelines:Recyclability certification through Germany's Interseroh and France's Recyclass requires 12-18 month testing protocols that delay new product launches.
- Barrier coating compatibility:SiOx and AlOx vapor-deposited layers must demonstrate delamination resistance in existing polyethylene recycling streams without contaminating flake quality.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Personal Care Plastic Tube Packaging Market |
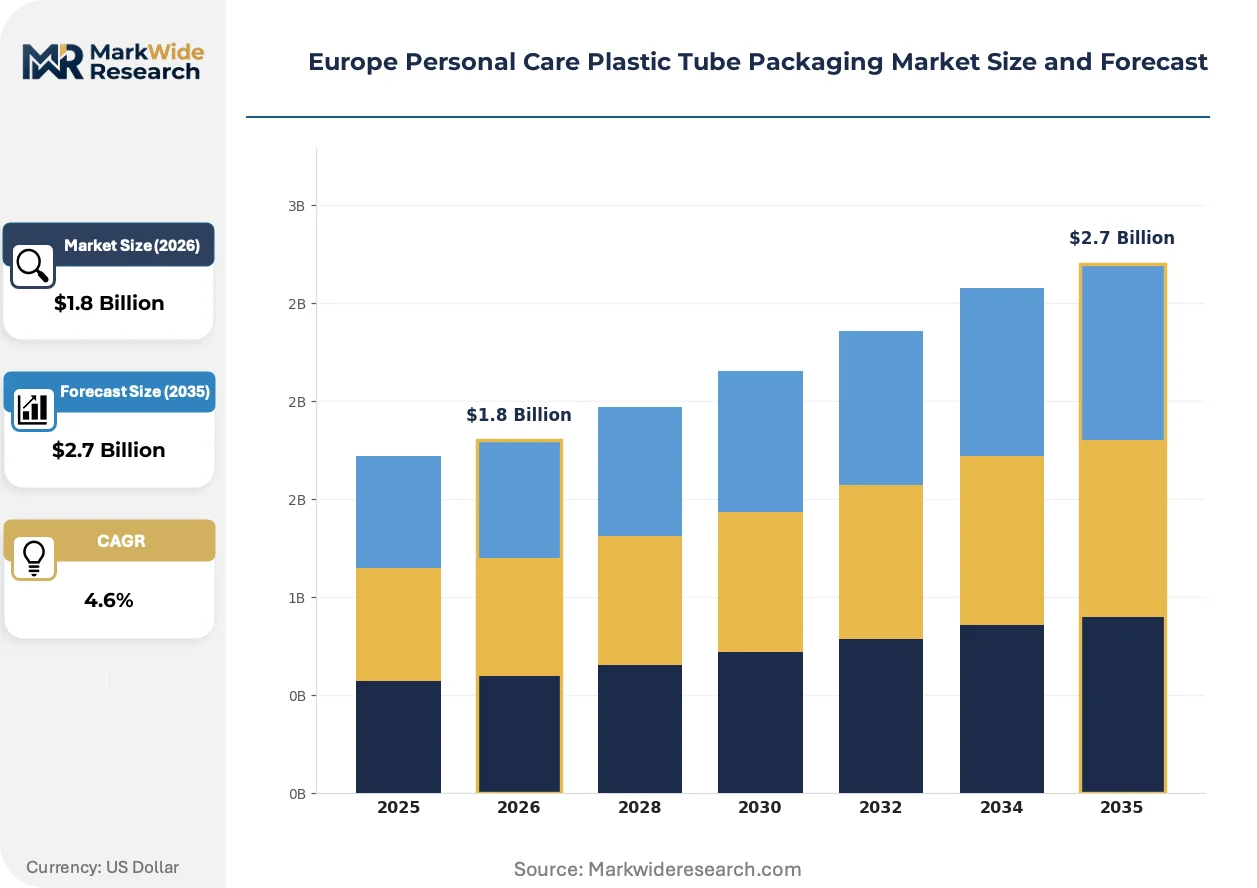
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toothpaste Tubes, Cosmetic Tubes, Shampoo Tubes, Lotion Tubes Material: LDPE, HDPE, PVC, Bioplastics Closure Type: Flip Top, Screw Cap, Snap-On Cap, Spout End User: Beauty Brands, Skincare Manufacturers, Oral Care Producers, Others |
| Companies Covered | Berry Global Inc, ALLTUB SAS, Global Tube SpA, EPL Limited, ALPLA Group, Hoffmann Neopac AG, Albéa Group, HCT Group, CTLpack Group SLU, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Personal Care Plastic Tube Packaging Market Trends and Innovations
Tube packaging innovation is pivoting from decorative differentiation toward material science breakthroughs that satisfy regulatory recyclability thresholds without sacrificing shelf-life performance.
Mono-material barrier technology is converging with high-definition printing capabilities to displace multilayer laminates in premium skincare applications. L'Oréal and Beiersdorf are piloting all-PE tubes with EVOH oxygen barriers in German and French markets. This convergence is compressing the technology gap between mass-market and prestige tube specifications.
The EU Green Deal's packaging waste targets are mandating 70% recyclable content thresholds by 2030. Tube converters must redesign head, shoulder, and cap components from compatible resins rather than conventional PP or ABS. Premium cosmetic brands in Italy face the steepest compliance curve given their reliance on metallized finishes and complex closure systems.
Beauty brands are consolidating supplier relationships around converters with integrated recycling partnerships and verified mass-balance certification. Direct-to-consumer subscription models in the UK and Netherlands favor smaller tube formats with minimal secondary packaging. This channel rotation is favoring regional converters with agile changeover capabilities over high-volume commodity producers.
Europe Personal Care Plastic Tube Packaging Market Segmentation
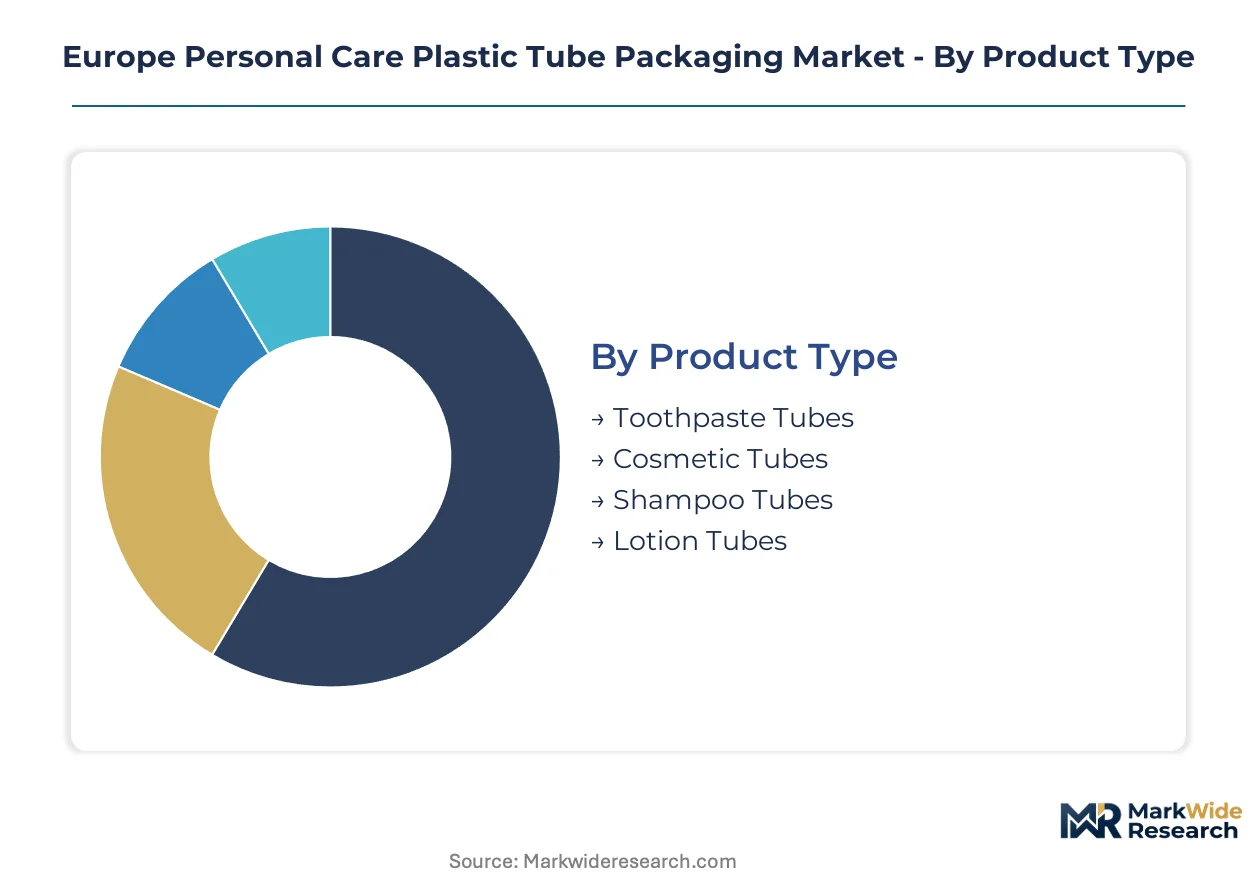
Tube packaging specifications vary sharply across personal care categories, with material barriers, closure mechanics, and end-user compliance requirements driving divergent converter capabilities. Segmentation clarity enables suppliers to align extrusion assets with the precise technical and regulatory demands of each application cluster.
Product Type:
Tube diameter, wall thickness, and head-seal specifications map directly to product viscosity, dispensing pressure, and shelf-life requirements across personal care formulations.
- Cosmetic Tubes:These deploy multilayer EVOH or aluminum-laminate walls to protect oxygen-sensitive mascaras and foundations. L'Oréal and Beiersdorf specifications in France and Germany mandate high-definition decoration compatibility and mono-material recyclability pathways.
- Toothpaste Tubes:Laminate structures with aluminum foil barriers dominate, though Colgate-Palmolive and Unilever are piloting all-PE alternatives to meet EU Green Deal targets. Italian converters lead mechanical recycling qualification for these high-volume formats.
- Shampoo Tubes:LDPE dominates mass-market formats where cost efficiency outweighs barrier sophistication. Hoffmann Neopac supplies high-barrier variants for premium salon-positioned brands in Switzerland and Germany.
- Lotion Tubes:These require controlled-dosage shoulder designs for viscous body and hand formulations. Demand concentrates in German drugstore channels wheredm-drogerie markt and Rossmann specifications prioritize shelf-ready stacking stability.
Cosmetic tubes lead on scale; bioplastics-compatible lotion formats lead on momentum.
Material:
Resin selection balances mechanical performance, regulatory compliance, and recyclability certification timelines across European converter portfolios.
- LDPE:Low-density polyethylene offers superior flexibility and stress-crack resistance for squeezable formats. Germany's Der Grüne Punkt scheme recognizes LDPE tubes in its sorting infrastructure, lowering extended producer responsibility fees for mass-market oral care brands.
- Bioplastics:Bio-based PE and PLA alternatives satisfy beauty brand renewable content claims and REACH phthalate restrictions. Albéa Group has scaled mass-balance certified tube production for L'Oréal's Garnier lines in France and Italy.
- HDPE:Higher stiffness suits stand-up tubes and pharmaceutical applications requiring dimensional stability. Berry Global extrudes HDPE for dermatological prescription tubes with CE marking compliance.
- PVC:Declining share given ECHA substance restrictions and limited mechanical recycling acceptance. Remains in legacy pharmaceutical formats where barrier specifications resist material substitution.
LDPE commands installed capacity; bioplastics claims the steepest expansion trajectory.
Closure Type:
Cap mechanics determine dispensing control, secondary packaging elimination, and resin compatibility for mono-material recyclability.
- Flip Top:Hinged polypropylene designs dominate oral care and mass-market shampoo segments. One-handed operation suits gym and travel usage scenarios prioritized by UK and Netherlands direct-to-consumer subscription brands.
- Screw Cap:Threaded closures allow precise dosage control for premium skincare serums. German beauty brands specify screw-cap compatibility with high-barrier laminate tubes for retinol and vitamin C formulations.
- Snap-On Cap:Press-fit assemblies reduce component count and assembly complexity. Italian converters favor snap-on designs for cost-optimized cosmetic tubes serving Southern European private-label markets.
- Spout:Directional flow control suits hair dye and intensive treatment applications. Limited penetration outside professional salon channels given higher unit costs and specialized filling equipment requirements.
Flip-top formats dominate volume; spout configurations gain share in professional channels.
End User:
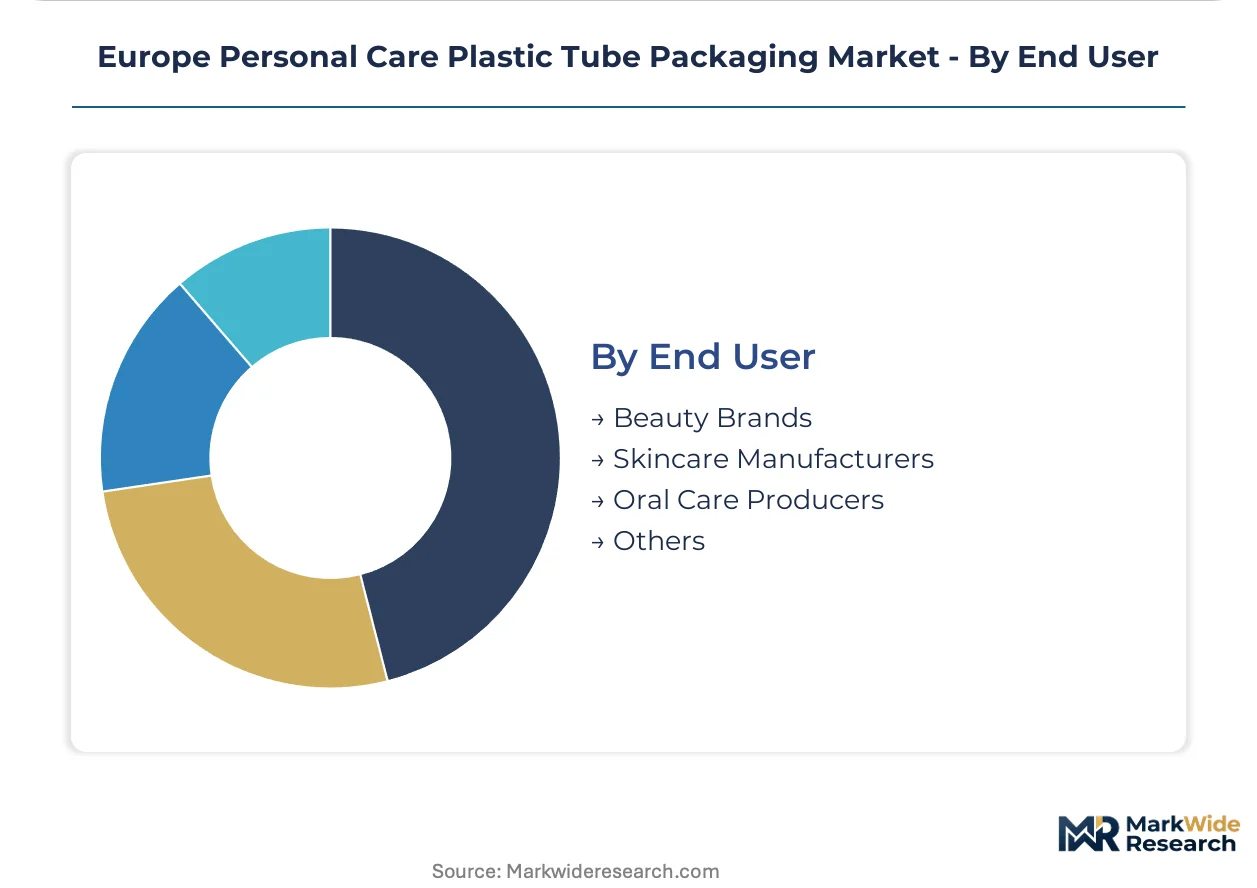
Customer procurement patterns split between multinational beauty conglomerates with sustainability mandates and regional skincare specialists prioritizing speed-to-market.
- Beauty Brands:L'Oréal, Beiersdorf, and Coty impose rigorous sustainability scorecards requiring mass-balance certification and Recyclass recyclability validation. These specifications compress supplier margins while locking in multi-year contract durations.
- Skincare Manufacturers:Mid-sized formulators in France's Cosmet'Agile cluster and Germany's SME skincare sector prioritize agile changeover capabilities and short-run digital printing for limited-edition launches.
- Oral Care Producers:Colgate-Palmolive and Unilever procurement emphasizes scale economies and fixed-price annual contracts. Ethylene feedstock volatility creates margin pressure for converters serving this segment.
- Others:Pharmaceutical and veterinary dermatology applications require CE-marked medical device compliance. Hoffmann Neopac and select German converters specialize in this higher-barrier, longer-qualification niche.
Beauty brands dictate sustainability specifications; skincare manufacturers drive format innovation velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tube converter talent clusters in Northern Italy, the Rhine-Ruhr corridor, and Île-de-France anchor Europe's packaging innovation capacity. These workforce concentrations sustain specialized extrusion, barrier coating, and digital printing capabilities that migrate slowly to lower-cost peripheries.
Germany
Beauty brand headquarters in Düsseldorf and Hamburg drive demand for high-barrier mono-material tubes. Der Grüne Punkt extended producer responsibility fees incentivize recyclability investments. The Rhine-Ruhr corridor hosts Berry Global's multi-site extrusion footprint serving mass-market oral care contracts.
France
L'Oréal and Coty sustainability scorecards mandate mass-balance certification from tube suppliers. Citeo packaging taxes burden small-batch cosmetic runs disproportionately. The Cosmet'Agile cluster outside Paris specializes in agile changeover capabilities for limited-edition skincare launches.
Italy
Northern Italian converters leverage advanced mechanical recycling streams accepting mono-material LDPE tubes at scale. Recyclass certification timelines of 12-18 months delay new product launches. Bologna and Milan anchor production for premium cosmetic tubes with metallized finishes.
United Kingdom
Direct-to-consumer subscription models favor smaller tube formats with minimal secondary packaging. REACH compliance documentation burdens elevate testing costs for importers. London-based beauty startups prioritize digital printing integration for influencer collaboration drops.
Poland
Central European labor cost advantages attract converter capacity expansion serving Eastern European distribution centers. EU Green Deal packaging waste targets apply with full regulatory force. Warsaw and Łódź emerge as secondary hubs for mass-market shampoo and lotion tube production.
Europe Personal Care Plastic Tube Packaging Market Competitive Landscape
The competitive structure tilts toward multi-national converters with integrated recycling partnerships and mass-balance certification capabilities. Tiered specialization separates high-volume commodity producers from premium barrier specialists and agile regional fabricators. Strategic moves concentrate on mono-material validation investments and digital printing integration rather than capacity expansion.
Among Switzerland-based specialists, Hoffmann Neopac AG occupies a position exemplifying high-barrier premium tier capabilities. Berry Global Inc and Albéa Group represent scale-driven and sustainability-certified archetypes respectively, anchoring distinct competitive vectors within the supplier base.
| Leading Market Players |
|---|
| Berry Global Inc |
| ALLTUB SAS |
| Global Tube SpA |
| EPL Limited |
| ALPLA Group |
| Hoffmann Neopac AG |
| Albéa Group |
| HCT Group |
| CTLpack Group SLU |
| Others |
Pricing and Supply Chain Analysis
The EU Green Deal's packaging waste targets gate qualified supply for converters seeking premium-tier pricing access, as recyclability certification through Germany's Interseroh and France's Recyclass demands 12-18 month validation timelines that exclude uncertified competitors from L'Oréal and Beiersdorf procurement shortlists.
Pricing Analysis
Tube converters split bundled and unbundled service offerings, with mass-market oral care brands demanding fixed-price annual contracts that exclude decoration and logistics while premium skincare manufacturers absorb full-service packaging including digital printing and mass-balance certification. Price differentiation hinges on recyclability tier and barrier performance, with mono-material EVOH tubes commanding premiums over commodity LDPE formats. Cost compression in mass-market segments is intensifying because ethylene feedstock volatility erodes converter margins on fixed contracts. Oral care producers exhibit highest price sensitivity given volume scale and specification standardization, whereas pharmaceutical dermatology buyers prioritize barrier reliability over unit economics.
Supply Chain Analysis
Workforce availability for specialized extrusion and barrier coating talent concentrates in Northern Italy's Bologna-Milan corridor, Germany's Rhine-Ruhr region, and France's Île-de-France, constraining rapid capacity expansion regardless of capital deployment. Raw material dependencies center on LDPE and LLDPE resins from European naphtha crackers, bio-based PE feedstocks from mass-balance certified suppliers, and EVOH barrier resins sourced from Asian polymer producers. Single-source vulnerability pervades EVOH supply given limited European production capacity. Distribution runs through beauty brand headquarters clusters in Düsseldorf, Hamburg, and Paris for direct procurement, with secondary channels serving drugstore retailers through regional logistics hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe personal care plastic tube packaging market functions as a regulatory compounder where EU Green Deal packaging waste thresholds mechanically expand addressable demand for certified-converter capacity regardless of underlying volume growth.
For Market Incumbents: Anchor defensive positioning through captive recycling partnerships and backward integration into mass-balance certified resin supply, as beauty brand sustainability scorecards increasingly disqualify converters lacking verified circularity credentials. Accelerate mono-material validation timelines to preempt competitor certification of high-barrier EVOH tube platforms for vitamin C and retinol applications. For New Entrants and Emerging Players: Mid-sized skincare manufacturers in France's Cosmet'Agile cluster represent an underserved buyer archetype with unmet demand for agile changeover capabilities and short-run digital printing for limited-edition launches. Poland and Czech Republic manufacturing locations offer labor cost advantages with full EU regulatory compliance, enabling competitive positioning for Eastern European distribution center proximity without REACH documentation burdens faced by non-EU importers. For Investors and Strategic Acquirers: Roll-up economics work for regional mono-material specialists because extended producer responsibility fee structures in Germany and France disproportionately burden small-batch runs, creating acquisition targets with compliance-ready assets that larger platforms can scale. Watch Recyclass certification backlog duration as the inflection indicator; delays beyond 18 months signal supply-constrained pricing power for certified converters.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Platform Validation | Recyclass certification unlocks L'Oréal and Beiersdorf procurement eligibility across German and French markets. |
| Backward Integration into Bio-Based Resin Supply | Mass-balance certification secures margin protection against fossil feedstock volatility for Albéa Group and comparable converters. |
| Digital Printing Capability Expansion | Direct-to-tube inkjet decoration eliminates label substrates for UK and Netherlands direct-to-consumer subscription brands. |
| Central European Manufacturing Footprint | Poland and Czech Republic locations capture labor cost advantages while maintaining EU Green Deal compliance for Eastern European distribution. |
| Pharmaceutical Tube Qualification | CE-marked medical device production commands price premiums and longer contract durations through Hoffmann Neopac specialization. |
Research Methodology
Coverage spans Germany, France, Italy, the United Kingdom, and Poland, with primary inputs from each market gathered through structured interviews with tube converter plant managers, beauty brand packaging procurement leads, sustainability compliance officers at L'Oréal and Beiersdorf, and recycling stream operators at Der Grüne Punkt and Citeo. Secondary validation drew from ECHA substance restriction databases, EU Packaging and Packaging Waste Regulation implementation timelines, Recyclass certification records, and customs trade data for LDPE and bioplastic resin flows. Bottom-up demand modeling triangulated against top-down market sizing from converter capacity assessments.
Granularity-level framing applied country-specific regulatory cluster modeling for Germany, France, and Italy alongside material-grade tier segmentation across LDPE, bioplastics, and high-barrier laminates, with closure type and end-user channel dimensions incorporated for demand allocation. CAGRs were derived from segment-level volume trajectories reconciled against macroeconomic indicators and regulatory compliance cost absorption rates. Forecast inputs included ethylene feedstock price sensitivity thresholds and beauty brand sustainability procurement mandate adoption curves.
Underlying measurement precision varies by segment; mono-material tube volumes carry tighter precision than multilayer laminate forecasts given certification transparency, while bioplastics expansion trajectories reflect higher uncertainty due to mass-balance accounting variability. Forecasts embed assumptions regarding EU Green Deal implementation timelines and ECHA substance restriction enforcement intensity. Material deviation in recycling infrastructure investment rates or feedstock price volatility warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
United Kingdom Plastic Bottles Market
Plastic Packaging
Philippines Plastics Market
Plastic Packaging
Global Plastic Straps Market
Plastic Packaging
Saudi Arabia Plastic Packaging Market
Plastic Packaging
PET Jars Market
Plastic Packaging
Latin America Plastic Bottles Market
Plastic Packaging
Africa BOPP Films Market
Plastic Packaging
Plastic Vials Market
Plastic Packaging
North America Blow Molded Plastics Market
Plastic Packaging
PCR Films Market
Plastic Packaging
India Plastic Bottles Market
Plastic Packaging
Blow Molded Plastics Market
Plastic Packaging
Blow Molded Plastic Bottles Market
Plastic Packaging
Plastic Keg Market
Plastic Packaging
Polyethylene Corrugated Packaging Market
Plastic Packaging
Plastic Crates Market