
 Packaging Laminates Market | 2026-2036
Packaging Laminates Market Size, Share, and Industry Trends Forecast 2026-2036
Packaging Laminates Market Outlook
India is rewriting regional supply dynamics with new coextrusion capacity coming online at Uflex Limited's facilities. Amcor plc leverages its integrated film-to-laminate platform to sustain margins across Australasia. Mondi Group anchors European demand through kraft-paper laminate hybrids that compete with conventional plastic structures. Huhtamaki Oyj differentiates via fiber-based barrier solutions that occupy niche positions in ready-meal packaging.
Packaging laminates are multilayer structures bonded through adhesive lamination, extrusion coating, or thermal fusion, typically achieving oxygen transmission rates below 1 cc per square meter per day for high-barrier grades. These structures protect oxygen-sensitive and moisture-critical contents across extended distribution chains. Plastic laminates dominate value pools in retort pouch applications where aluminum-plastic combinations command premium positioning. Biodegradable laminates represent the fastest-expanding material category as brand owners navigate EPR obligations and retailer sustainability scorecards. Flexible packaging applications absorb the majority of laminate tonnage, with pouches and rollstock formats leading conversion growth.
The EU F-Gas Regulation and REACH restrictions on perfluorinated compounds are forcing reformulation of high-barrier films across European converter networks. India's BIS certification requirements for food-contact laminates are tightening testing protocols for migration limits and adhesive safety. The US FDA maintains active oversight of indirect food additive clearances for new adhesive chemistries in laminate constructions. Stakeholders must monitor how divergent recyclability labeling rules across EU member states, India, and the US reshape product development roadmaps and capital allocation priorities.
Market Dynamics
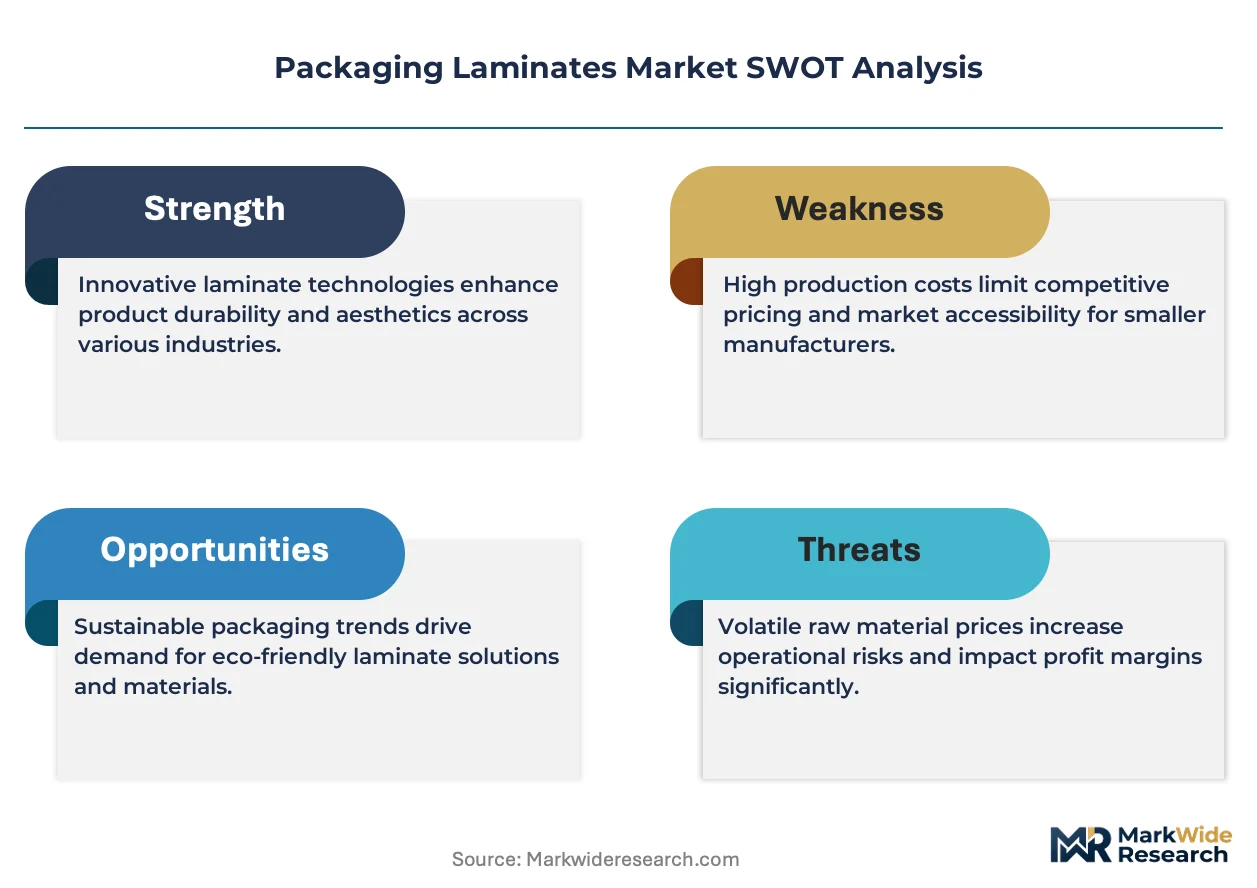
The EU F-Gas Regulation and REACH restrictions on perfluorinated compounds are forcing a structural reformulation of high-barrier films across European converter networks, compressing margins for legacy fluoropolymer-dependent laminates while opening substitution pathways for bio-based alternatives.
Growth Catalysts
- Retort pouch demand in ready-meal segments:Extended shelf-life requirements from food processors are pulling multilayer aluminum-plastic laminates into premium positioning across refrigerated and ambient distribution chains.
- EU Green Deal circular economy mandates:Packaging converters in Germany are investing in solventless lamination lines to meet recyclability targets and EPR obligations ahead of enforcement deadlines.
- Coextrusion capacity expansion:New film lines at Indian facilities are rewriting regional supply dynamics for barrier-grade substrates serving South Asian export markets.
Market Restraints
- Aluminum foil supply concentration:Converter dependence on limited European and Gulf smelter sources creates input volatility for high-barrier retort structures.
- REACH perfluorinated compound restrictions:The regulatory friction is forcing premature obsolescence of established oxygen barrier chemistries before certified replacements achieve scale.
- Mechanical recycling incompatibility:Current multilayer adhesive lamination processes produce structures that municipal sorting infrastructure cannot separate, limiting circular claims.
Strategic Opportunities
- Kraft-paper laminate hybrids:Fiber-based barrier solutions are penetrating ready-meal and dry-food segments where plastic reduction drives retailer scorecard compliance.
- Solventless adhesive adoption:Convergence of reactive polyurethane chemistry with high-speed lamination equipment is eliminating VOC emissions and thermal energy costs.
- Extended Producer Responsibility tailwinds:India's BIS certification tightening for food-contact laminates creates first-mover advantage for converters with pre-certified substrate libraries.
Industry Challenges
- Migration testing protocol complexity:Divergent food-contact safety requirements across EU member states, India, and the US are fragmentating product development roadmaps and extending certification timelines.
- Laminate-to-laminate adhesive qualification:Each new substrate combination requires full indirect food additive clearance from the US FDA, creating IP and documentation bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaging Laminates Market |
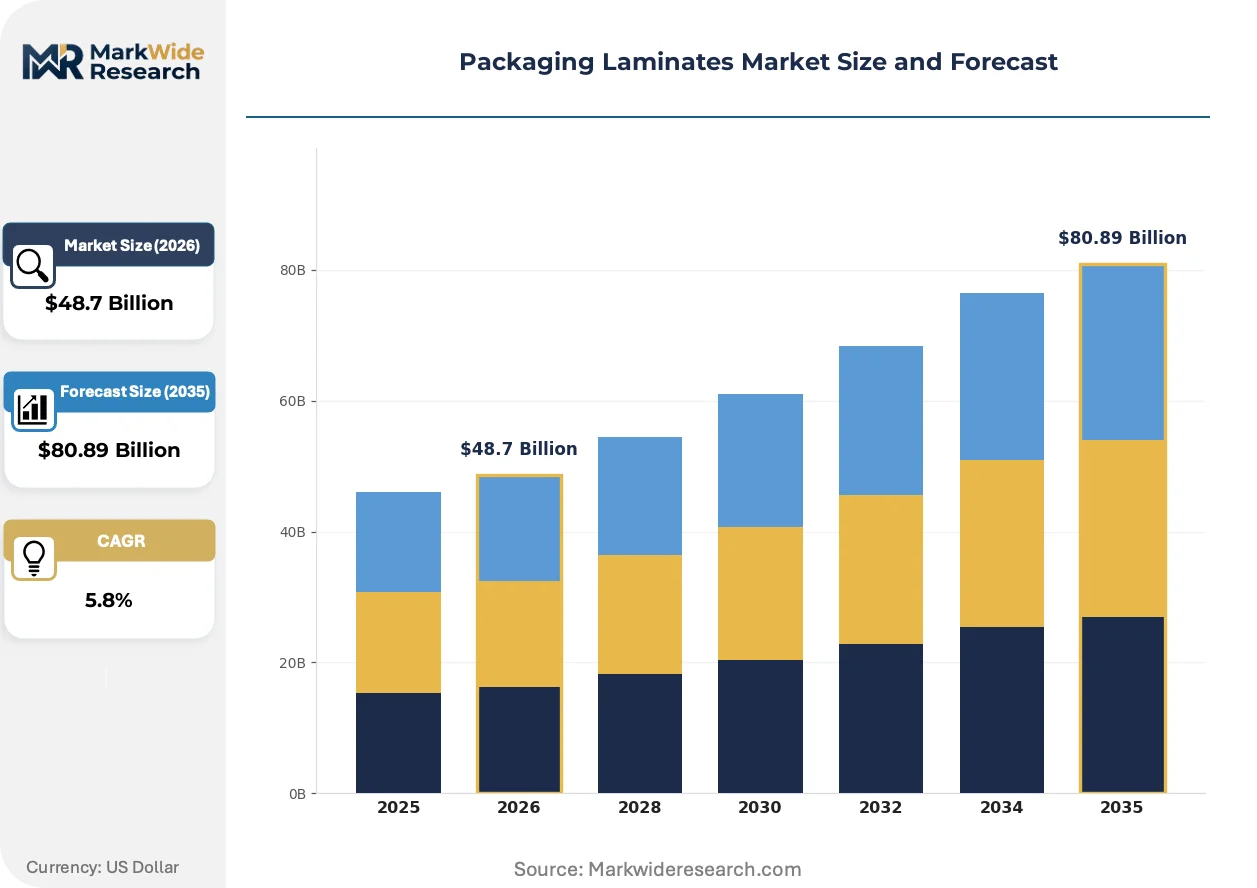
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $80.89 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Aluminum, Plastic, Paper, Biodegradable End Use: Food & Beverage, Personal Care, Healthcare, Consumer Goods Form: Rolls, Sheets, Pouches, Bags Application: Flexible Packaging, Labels, Coatings, Wrapping |
| Companies Covered | Constantia Flexibles, Mondi Group, Amcor plc, Huhtamaki Oyj, Pro Ampac LLC, Berry Global Inc., Coveris Holdings S.A., Uflex Limited, Sealed Air Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaging Laminates Market Strategic Shifts
Active reformulation of barrier chemistries is compressing technology cycles across converter networks, with sustainability mandates and performance requirements now advancing in parallel rather than sequence.
Water-based and solventless adhesive systems are penetrating high-speed lamination lines previously dependent on solvent-borne polyurethane chemistries. European converters serving brand-owner sustainability scorecards are adopting these platforms at accelerated pace. The elimination of thermal drying stages is rendering obsolete energy-intensive solvent recovery infrastructure that anchored legacy cost structures.
The EU F-Gas Regulation is tightening phase-down schedules for hydrofluorocarbon blowing agents and fluoropolymer barriers used in oxygen transmission control. Industrial consequence includes forced migration to silicon oxide and aluminum oxide vapor-deposited alternatives before full technical qualification. Retort pouch applications in ambient-stable ready meals face the steepest compliance compression and are responding with hybrid inorganic-organic barrier stacks.
Brand-owner sustainability procurement is consolidating supplier panels around converters with certified circular-design capabilities and verified lifecycle data. Retailer private-label buyers are displacing spot-market purchasing with multi-year framework agreements tied to recyclability performance guarantees. This pattern is most visible in German and French grocery channels where EPR fees now flow through to shelf-price negotiations.
Packaging Laminates Market Segmentation
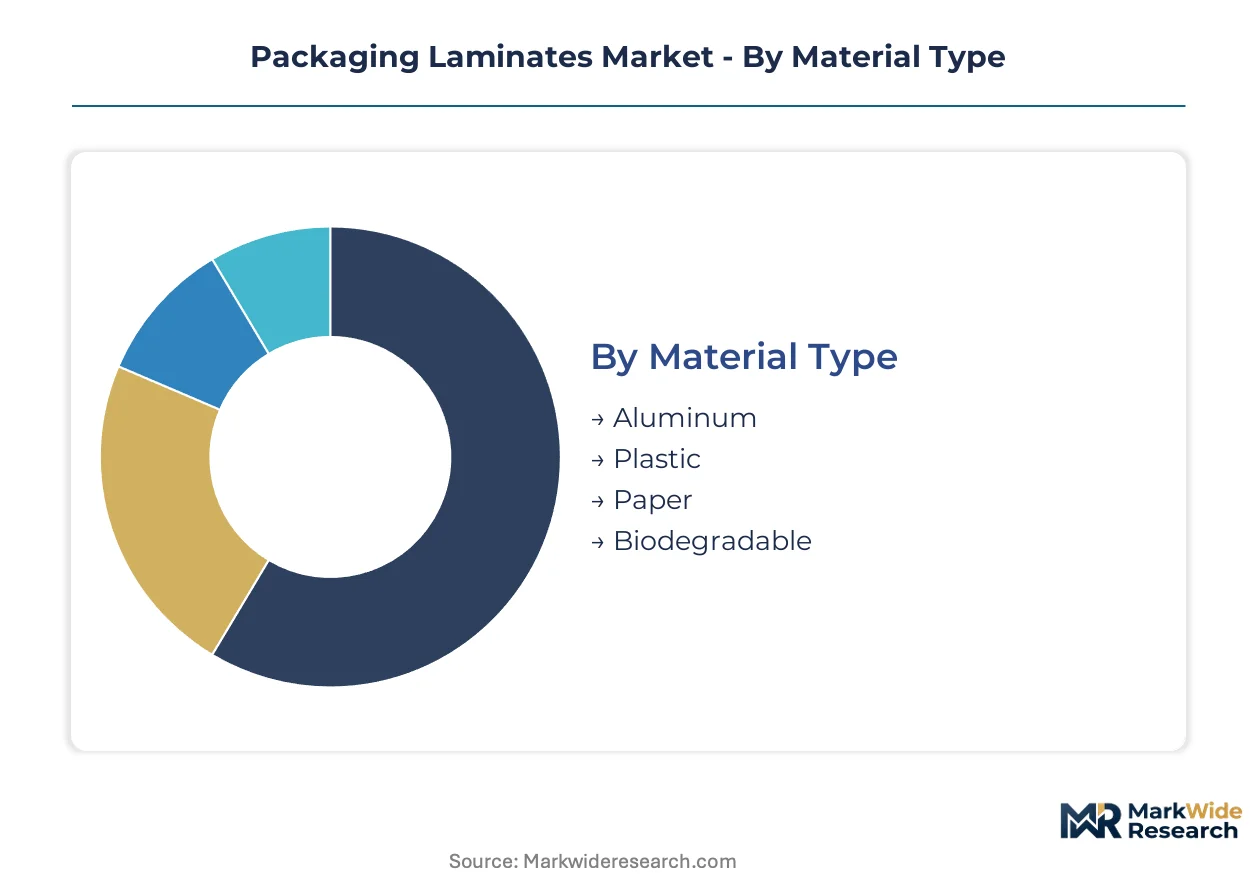
Packaging laminates serve divergent performance requirements across oxygen-sensitive food chains, moisture-critical pharmaceuticals, and shelf-stable consumer goods. Segment boundaries reflect tension between barrier specifications, recyclability mandates, and conversion economics that reshape converter investment priorities.
Material Type:
Use cases span from high-barrier retort applications to compostable single-serve formats, with material selection governing oxygen transmission rates and end-of-life pathways.
- Aluminum:Foil-containing multilayers achieve sub-0.1 cc/m²/day oxygen transmission for ambient-stable ready meals. Retort pouch demand in Germany and Japan pulls aluminum-plastic combinations into premium positioning despite mechanical recycling incompatibility.
- Plastic:Coextruded polyethylene and polyamide structures dominate flexible packaging tonnage through cost-efficient barrier tuning. India's BIS certification tightening for food-contact laminates is accelerating migration toward certified plastic substrate libraries.
- Paper:Kraft-paper laminate hybrids compete in dry-food segments where fiber content satisfies retailer sustainability scorecards.
- Biodegradable:PLA and cellulose-based laminates occupy niche positions in compostable packaging mandates.
Established volume favors plastic; emerging adoption favors biodegradable alternatives as EPR obligations harden.
End Use:
Customer requirements fragment across shelf-life extension demands, regulatory compliance burdens, and aesthetic performance specifications.
- Food & Beverage:Extended distribution chains for ambient-stable products pull multilayer barrier films into retort pouches and aseptic cartons. EU Green Deal circular economy mandates are forcing reformulation of legacy fluoropolymer-dependent structures.
- Healthcare:Sterile barrier systems for medical devices demand validated seal integrity and particulate control. FDA oversight of indirect food additive clearances extends to pharmaceutical laminate constructions, lengthening qualification timelines.
- Personal Care:Moisture and fragrance retention drives coextruded structures for sachets and sample packs.
- Consumer Goods:Durability and printability requirements shape adhesive selection for household product overwrap.
Food and beverage commands current capacity allocation; healthcare qualification protocols create the steepest barrier to entry.
Form:
Conversion economics and line speed requirements dictate format selection across converter networks and brand-owner filling operations.
- Pouches:Stand-up and flat pouch formats absorb the majority of laminate value in ready-meal and snack segments. Solventless lamination lines in Germany are displacing solvent-borne capacity to meet VOC emissions targets.
- Rolls:Master roll supply to downstream converters enables customization of final dimensions and printing. Uflex Limited's Indian coextrusion expansion is rewriting regional rollstock supply dynamics for South Asian export markets.
- Sheets:Cut-to-size formats serve short-run label and card lamination applications.
- Bags:Pre-formed bag-in-box and side-gusseted formats target bulk liquid and dry goods distribution.
Rolls dominate converter procurement; pouches capture the fastest value expansion in branded food channels.
Application:
Functional performance requirements separate commodity wrapping from engineered barrier systems in regulated environments.
- Flexible Packaging:Multilayer films for form-fill-seal and pre-made pouch operations constitute the primary laminate demand pool. REACH perfluorinated compound restrictions are forcing premature obsolescence of established oxygen barrier chemistries.
- Labels:Pressure-sensitive and in-mold label laminates require adhesive compatibility with container substrates and print durability.
- Coatings:Protective overlaminates extend graphic life for outdoor and industrial signage applications.
- Wrapping:General-purpose stretch and shrink films serve palletization and temporary protection needs.
Flexible packaging anchors installed capacity; label applications are gaining share fastest in premium cosmetic and beverage segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA's REACH restrictions on perfluorinated compounds are compressing margins for European converters while redirecting investment toward bio-based barrier alternatives. Divergent recyclability mandates across major economies are fragmentating product development roadmaps and extending certification timelines.
Germany
Retort pouch demand from ambient-stable ready-meal processors pulls aluminum-plastic laminates into premium positioning. The EU F-Gas Regulation accelerates phase-down schedules for fluoropolymer barriers, forcing migration to silicon oxide alternatives. Packaging converters in Baden-Württemberg and North Rhine-Westphalia are installing solventless lamination lines to meet circular economy targets.
United States
Extended distribution chains for shelf-stable food products sustain multilayer barrier film consumption across refrigerated and ambient channels. FDA oversight of indirect food additive clearances for new adhesive chemistries lengthens qualification timelines for laminate constructions. Industrial concentration clusters around Chicago-area converting facilities and Southeast packaging corridors.
India
Coextrusion capacity expansion at major film producers is rewriting regional supply dynamics for South Asian export markets. BIS certification tightening for food-contact laminates accelerates migration toward pre-certified substrate libraries. Gujarat and Maharashtra host the dominant converting clusters serving domestic food processors and export channels.
Japan
Sterile barrier requirements for medical devices and oxygen-sensitive food packaging sustain demand for high-performance multilayer structures. METI guidance on sustainable packaging materials influences converter investment priorities toward recyclable mono-material alternatives. The Chubu-Nagoya industrial corridor anchors laminate production for pharmaceutical and precision food applications.
Brazil
Moisture-critical food distribution infrastructure drives coextruded polyethylene and polyamide laminate consumption across extended supply chains. ANVISA pharmaceutical packaging regulations create qualification barriers for imported barrier structures. São Paulo-state converting facilities dominate capacity allocation for Mercosur regional supply.
Packaging Laminates Market Competitive Environment
Capability concentration sits with integrated film-to-laminate platforms; scale advantage sits with diversified multinational converters. The vendor base organizes around three strategic archetypes: integrated materials-science conglomerates with captive resin and film operations; mid-cap specialists focused on barrier technology or sustainable substrates; and regional converters serving spot-market procurement with commodity laminations. Dominant competitive moves include capacity expansion in high-growth geographies and technology licensing for solventless adhesive platforms.
Among integrated packaging conglomerates, Amcor plc and Mondi Group exemplify the capability-heavy tier with backward integration into substrate production. Uflex Limited occupies a position as a regional scale anchor with coextrusion capacity expansion serving South Asian export markets. Huhtamaki Oyj represents the specialist archetype through fiber-based barrier solutions targeting ready-meal and sustainable packaging niches.
| Leading Market Players |
|---|
| Constantia Flexibles |
| Mondi Group |
| Amcor plc |
| Huhtamaki Oyj |
| Pro Ampac LLC |
| Berry Global Inc. |
| Coveris Holdings S.A. |
| Uflex Limited |
| Sealed Air Corporation |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in European solventless lamination lines is compressing converter margins while simultaneously accelerating price competition for barrier-grade substrates. This utilization dynamic forces suppliers to absorb regulatory compliance costs rather than pass them downstream, reshaping procurement negotiations across food-contact laminate tiers.
Pricing Analysis
Geographic price spreads between German and Indian laminate converters now exceed transport-adjusted input differentials, reflecting certification-premium capture at European facilities. Three-tier pricing structure across premium, standard, and economy levels stratifies by barrier performance and recyclability certification, with EU Green Deal compliance tiers commanding 15-20 point spreads. Pricing pressure stems from REACH-driven reformulation costs that legacy fluoropolymer-dependent producers cannot fully recover. Brand-owner procurement teams exhibit highest price sensitivity in commodity snack packaging, while pharmaceutical barrier systems show inelastic demand.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates laminate substrate sourcing decisions, particularly for vapor-deposited barrier films. Supply concentrates in Germany, India, and Japan for high-performance coextrusion capacity, with converter networks drawing from Gulf aluminum smelters and South Korean resin producers. Single-source vulnerability in aluminum foil supply creates input volatility for retort pouch manufacturers. Distribution runs through master roll supply to downstream converters, with direct-to-brand procurement gaining share in German retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where circular-design certification is becoming the interoperability standard for supplier-panel consolidation, locking out uncertified converters from multi-year framework agreements.
For Market Incumbents: Harden barrier-chemistry IP positions through accelerated silicon oxide vapor-deposition qualification ahead of EU F-Gas enforcement deadlines. Consolidate solventless adhesive capacity in Baden-Württemberg and North Rhine-Westphalia to capture EPR-fee pass-through opportunities in German retail channels. Vertical integration into captive resin production insulates margin compression from polyamide price volatility. For New Entrants and Emerging Players: Pursue biodegradable laminate niches in Indian export markets where BIS certification tightening creates first-mover advantage for pre-certified substrate libraries. White-space concentration sits in fiber-based barrier solutions for ready-meal segments where retailer sustainability scorecards displace conventional plastic structures. Channel entry through coextrusion tolling agreements with established film producers reduces capital intensity. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated film-to-laminate platforms with multi-year brand-owner framework agreements tied to recyclability performance guarantees. Long-term viability favors converters with certified circular-design capabilities and verified lifecycle data across the analysis window. Acquisition targets should demonstrate solventless lamination technology licensing or proprietary barrier-chemistry IP. The signal to watch is retailer private-label procurement shifting from spot-market purchasing to sustainability-linked multi-year agreements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive polyamide supply from BASF or Lanxess facilities insulates converters from petrochemical price cycles. |
| Solventless Lamination Technology Licensing | Reactive polyurethane chemistry adoption eliminates VOC emissions and qualifies converters for EU Green Deal procurement panels. |
| Certified Circular-Design Library Expansion | Pre-qualified substrate combinations accelerate BIS and FDA clearance timelines for food-contact laminate applications. |
| Regional Coextrusion Capacity Buildout | New film lines in Gujarat and Maharashtra capture South Asian export demand while reducing freight exposure to European tariff volatility. |
| Fiber-Based Barrier Solution Development | Kraft-paper laminate hybrids penetrate German and French retail channels where EPR fees now flow through to shelf-price negotiations. |
Study Parameters
The analysis maps aluminum-barrier, plastic-coextrusion, paper-hybrid, and biodegradable laminate sub-sectors, each validated through packaging converter executives, food-brand procurement directors, and regulatory affairs specialists. Primary fieldwork combined structured interviews with plant managers at solventless lamination facilities and category buyers at German grocery retailers. Secondary validation drew from ECHA REACH substance restrictions, EU F-Gas Regulation phase-down schedules, BIS certification protocols, and FDA indirect food additive clearance databases. Bottom-up capacity assessments triangulated against top-down brand-owner procurement spend estimates.
Assumptions held fixed include current EU Green Deal enforcement timelines and existing REACH perfluorinated compound restriction scopes; variables tested included accelerated biodegradability mandates and aluminum foil supply disruptions. Segmentation modeling spanned material type, end-use industry, form factor, and application across the projection horizon. CAGRs derived from installed capacity utilization curves and brand-owner sustainability procurement velocity indices, with oxygen transmission rate specifications and adhesive chemistry migration limits as laminate-specific forecast inputs.
Sensitivities concentrate around regulatory acceleration in fluoropolymer phase-downs and mechanical recycling infrastructure deployment rates. Forecasts reflect documented assumptions on certification adoption curves and raw material price stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Face Stock Films Market
Packaging Materials
Bulb Packaging Market
Packaging Materials
Foam Bottle Technology Market
Packaging Materials
Global Hot Stamping Foils Market
Packaging Materials
Tamper Evident Shrink Bands Market
Packaging Materials
Heat Shrink Packaging Market
Packaging Materials
Packaging Straps and Buckles Market
Packaging Materials
Card Films Market
Packaging Materials
VCI Shrink Films Market
Packaging Materials
Protein Packaging Market
Packaging Materials
Tube Packaging Market
Packaging Materials
Die Cut Support Pads Market
Packaging Materials
Metallized Rollstock Film Market
Packaging Materials
Global Adherence Packaging Market
Packaging Materials
Food Grade Sealant Market
Packaging Materials
Latin America Single-Use Packaging Market