
 Topical Drugs Packaging Market | 2026-2036
Topical Drugs Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Topical Drugs Packaging Market Analytics
Dermatology clinics and home care channels is rebalancing the volume mix for topical drugs packaging as chronic skin condition management shifts away from hospital settings. Gerresheimer sustains glass and polymer primary packaging capacity for high-barrier topical applications across European and North American manufacturing sites. Amcor leverages multi-layer laminate and foil technologies to extend shelf stability for transdermal and semi-solid formulations in tropical climates.
Topical drugs packaging encompasses primary and secondary containment systems engineered to protect semi-solid, liquid, and gel formulations from moisture ingress, oxidation, and microbial contamination while enabling precise dosing and patient handling. Tubes dominate unit volume due to their compatibility with aluminum-laminate and all-plastic extrusion lines that support crimp-seal integrity and controlled dispensing. Plastic materials lead value contribution given their adaptability to co-extrusion barrier technologies, though composite laminates are gaining share in premium dermatology segments where EVOH and foil layers address aggressive oxygen sensitivity.
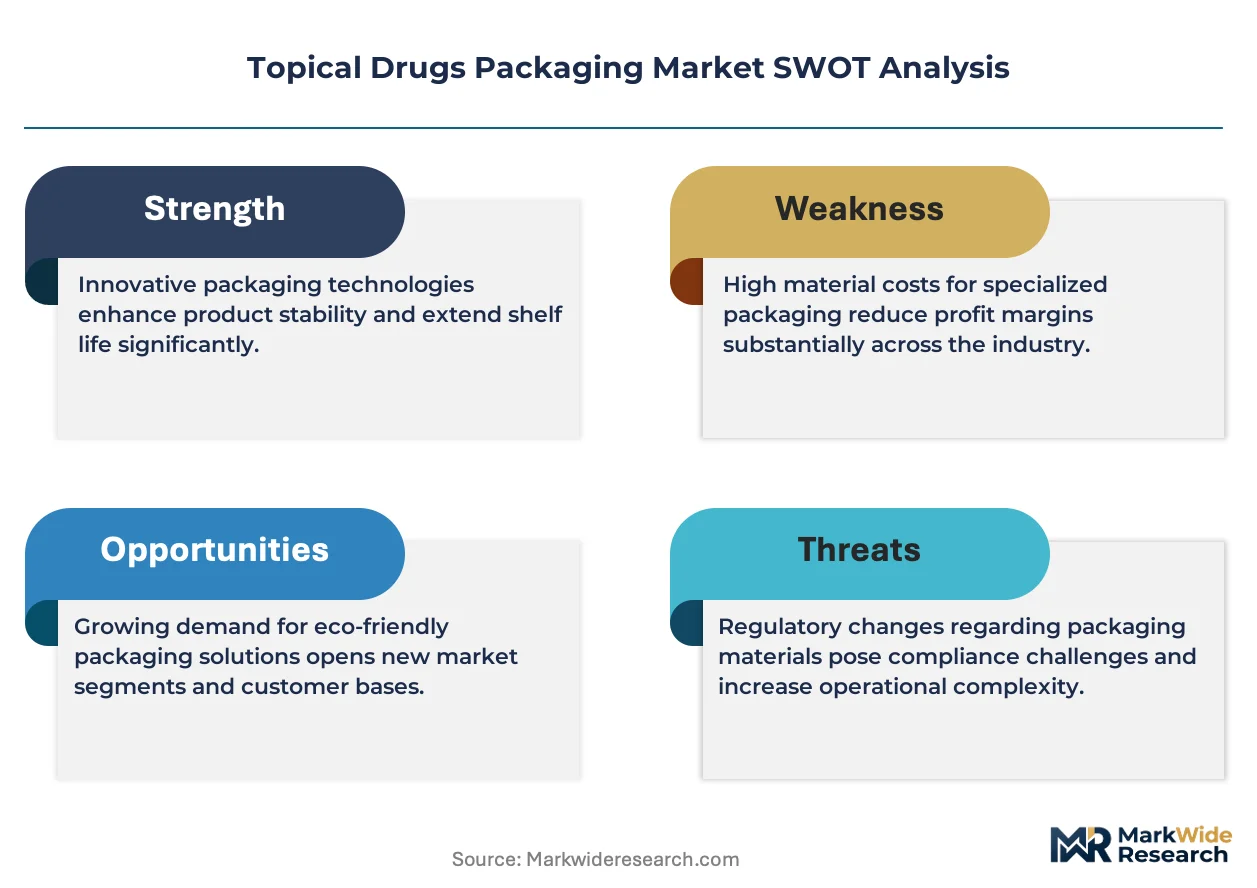
FDA stability guidance for semi-solid drug products and EMA Annex 1 revisions on container closure integrity shape material selection and validation protocols for topical packaging suppliers. REACH compliance in Europe and state-level pharmaceutical waste regulations in California restrict certain phthalate plasticizers and single-use formats, redirecting R&D toward recyclable polyolefin structures and bio-based barrier coatings. Stakeholders must monitor evolving pharmacopeial extractables testing standards and regional extended producer responsibility mandates to align capital allocation with compliance-ready material platforms.
Market Dynamics
Home care administration of dermatology treatments is concentrating demand for unit-dose and compliance-packaged topical formats, forcing suppliers to reconfigure production lines away from hospital-centric bulk containers toward patient-handling-optimized designs.
Growth Catalysts
- EMA Annex 1 revisions:The updated sterile manufacturing guidelines mandate enhanced container closure integrity testing for semi-solid dosage forms, compelling packaging converters to invest in validated barrier technologies.
- Aluminum-laminate tube expansion:Co-extrusion lines capable of crimp-seal aluminum barrier layers are capturing volume from conventional plastic tubes in oxygen-sensitive dermatology segments.
- Germany's OTC topical sales:Elevated consumer self-medication rates for chronic skin conditions are absorbing unit-dose sachets and metered-dispensing pumps through pharmacy and e-commerce channels.
Market Restraints
- EVOH resin supply concentration:Barrier layer production depends on ethylene vinyl alcohol supply chains centered in East Asian petrochemical clusters, exposing converters to input volatility.
- REACH phthalate restrictions:ECHA limitations on plasticizer chemistries in pharmaceutical contact materials are forcing reformulation of flexible polyolefin closures and tube shoulders.
- Glass-to-plastic substitution ceiling:High-barrier dermatology creams requiring inert primary contact surfaces retain glass jar specifications despite plastic cost advantages, limiting material conversion rates.
Strategic Opportunities
- Japan's aging dermatology patient base:Geriatric populations managing chronic psoriasis and eczema are generating demand for arthritis-friendly tube dispensers and tactile-differentiated compliance packaging.
- California pharmaceutical waste regulations:State-level extended producer responsibility mandates are creating first-mover advantage for suppliers offering recyclable mono-material tube structures with bio-based barrier coatings.
- Connected packaging convergence:Near-field communication tags integrated with primary containers are enabling dose-tracking adherence programs for biologic topical therapies.
Industry Challenges
- Extractables validation timelines:USP and EP chapters on pharmaceutical packaging leachables are extending qualification cycles for novel co-extrusion barrier materials by twelve to eighteen months.
- Multi-site compliance coordination:FDA stability-testing requirements for semi-solid drug products demand harmonized documentation across contract manufacturing organizations and packaging converters in dispersed supply networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Topical Drugs Packaging Market |
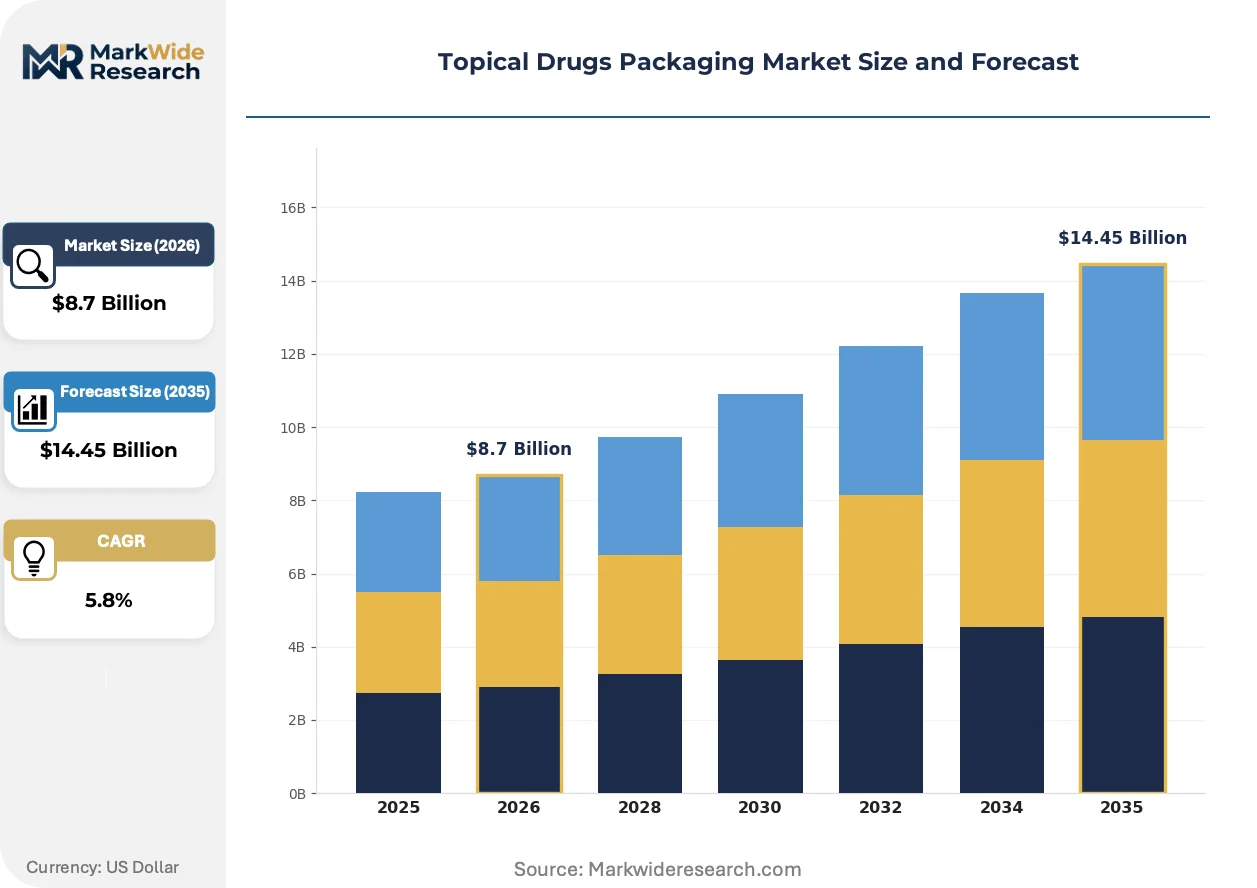
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Tubes, Jars, Pouches, Sachets Material: Plastic, Glass, Aluminum, Composite End User: Pharmacies, Hospitals, Clinics, Home Care Application: Dermatology, Pain Relief, Antiseptic, Hydration |
| Companies Covered | West Pharmaceutical Services, Schott, Amcor, Halo Pharma, Origin Pharma Packaging, Gerresheimer, Berry Global, Aphena Pharma Solutions, AptarGroup, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Topical Drugs Packaging Market Evolving Landscape
Intelligent dispensing systems and sustainable material platforms are reconfiguring competitive priorities across topical packaging value chains, with automation and regulatory alignment emerging as decisive capability differentiators.
Vision-guided robotic tube-filling lines are automating high-speed assembly of aluminum-laminate containers with integrated applicator tips. Contract packagers serving US dermatology brands are deploying these systems to compress changeover times between product SKUs. The technology is automating quality inspection tasks previously requiring manual verification of crimp-seal integrity.
FDA stability guidance for semi-solid drug products is tightening documentation requirements for moisture vapor transmission rates and oxygen ingress across primary container systems. Packaging converters are responding with enhanced in-house barrier testing laboratories and accelerated aging protocols. Semi-solid formulations with hygroscopic active ingredients face the steepest compliance burden.
Patient self-administration patterns are fragmenting procurement decisions across retail pharmacy, mail-order, and direct-to-consumer channels. Dermatology clinics are unbundling prescription fulfillment from consultation services, forcing packaging suppliers to qualify containers for automated pharmacy dispensing systems. This channel rotation is most pronounced in United States markets where formulary management incentives concentrate volume with specialty distributors.
Topical Drugs Packaging Market Segmentation
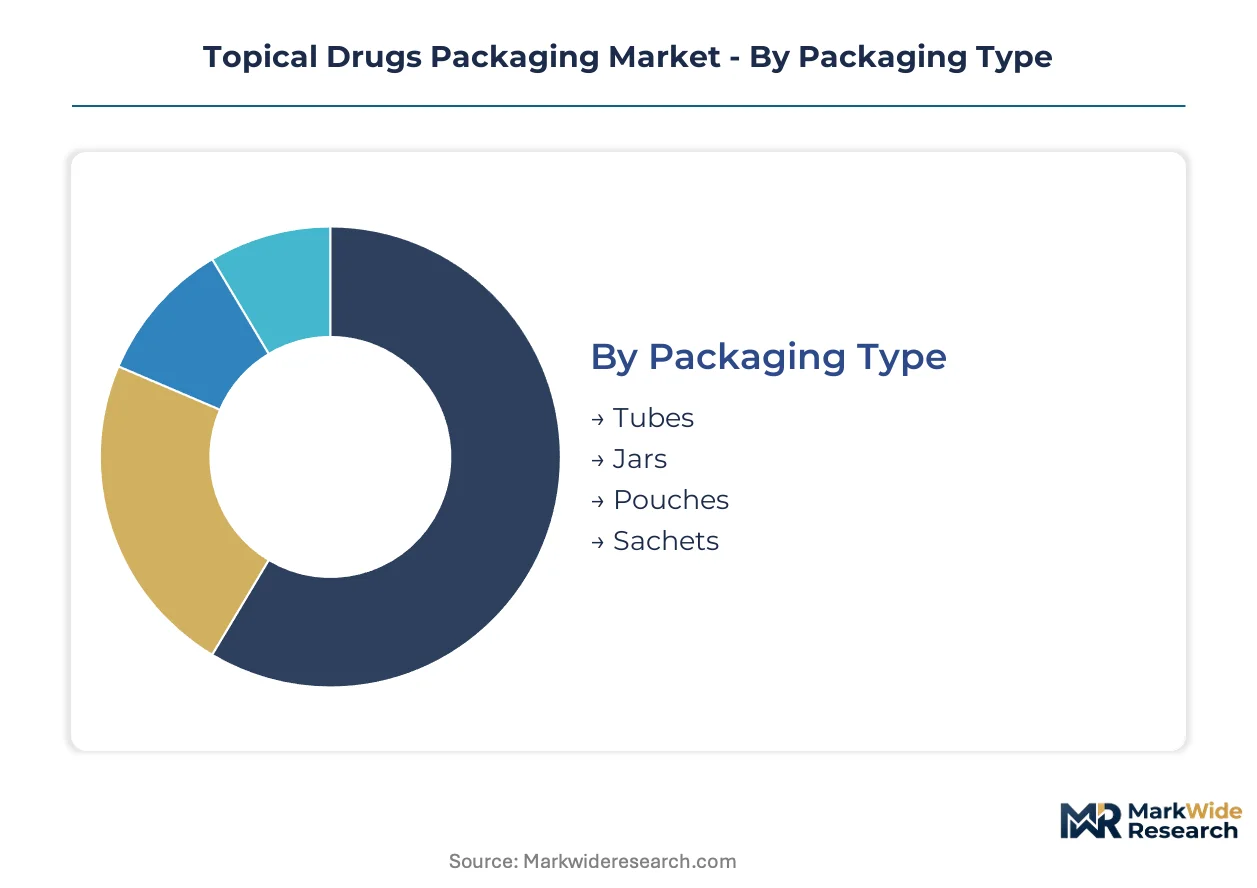
Topical drugs packaging segmentation reveals how formulation chemistry, administration setting, and regulatory exposure reshape procurement priorities across container formats. Material selection and barrier architecture vary sharply between hospital bulk dispensing and patient-directed home care channels.
Packaging Type:
Aluminum-laminate and all-plastic extrusion technologies define the performance frontier for semi-solid containment and controlled dispensing.
- Tubes:Aluminum-laminate and all-plastic extrusion lines deliver crimp-seal integrity with controlled dispensing mechanics. Dermatology prescription volumes in Germany and the United States absorb the majority of high-barrier tube output for oxygen-sensitive creams.
- Jars:Glass and polymer primary containers protect hygroscopic formulations through threaded closure systems with induction-sealed liners. Hospital pharmacies in Japan specify wide-mouth glass jars for compounding dermatology preparations requiring inert contact surfaces.
- Pouches:Multi-layer flexible structures accommodate transdermal patch and gel sachet formats with peelable foil laminates.
- Sachets:Unit-dose foil-paper laminates enable single-use antiseptic and hydration product distribution through pharmacy and e-commerce channels.
Tubes lead on scale; pouches lead on momentum.
Material:
Cost tiers separate commodity polyolefin structures from premium barrier systems required for aggressive stability profiles.
- Plastic:Co-extrusion barrier technologies adapt polyolefin structures to EVOH and nylon interlayers for moisture and oxygen resistance. California's pharmaceutical waste regulations are redirecting R&D toward recyclable mono-material tube structures with bio-based barrier coatings.
- Glass:Borosilicate and soda-lime formulations provide chemically inert primary contact for high-value dermatology creams. FDA stability guidance for semi-solid drug products preserves glass jar specifications despite plastic cost advantages in segments requiring extractables minimization.
- Aluminum:Cold-form foil and extruded tube stocks deliver absolute oxygen and light barriers for sensitive actives.
- Composite:Aluminum-plastic laminates and glass-polymer hybrids balance barrier performance with handling durability.
Plastic leads on scale; composite climbs the fastest.
End User:
Volume concentration shifts from institutional procurement toward patient-directed channels as chronic disease management migrates from facilities to homes.
- Pharmacies:Automated dispensing systems and compliance packaging specifications dominate procurement criteria. Germany's OTC topical sales through pharmacy channels absorb unit-dose sachets and metered-dispensing pumps for consumer self-medication.
- Home Care:Arthritis-friendly dispensers and tactile-differentiated compliance packaging address geriatric patient needs. Japan's aging dermatology patient base generates demand for ergonomic tube designs with integrated applicator tips.
- Hospitals:Bulk container specifications and sterilization compatibility requirements govern material selection.
- Clinics:Sample-sized formats and professional-use applicator systems support in-office treatment protocols.
Pharmacies lead on scale; home care gains share fastest.
Application:
Maturity gradients separate established dermatology segments from emerging therapeutic categories with distinct barrier and dosing requirements.
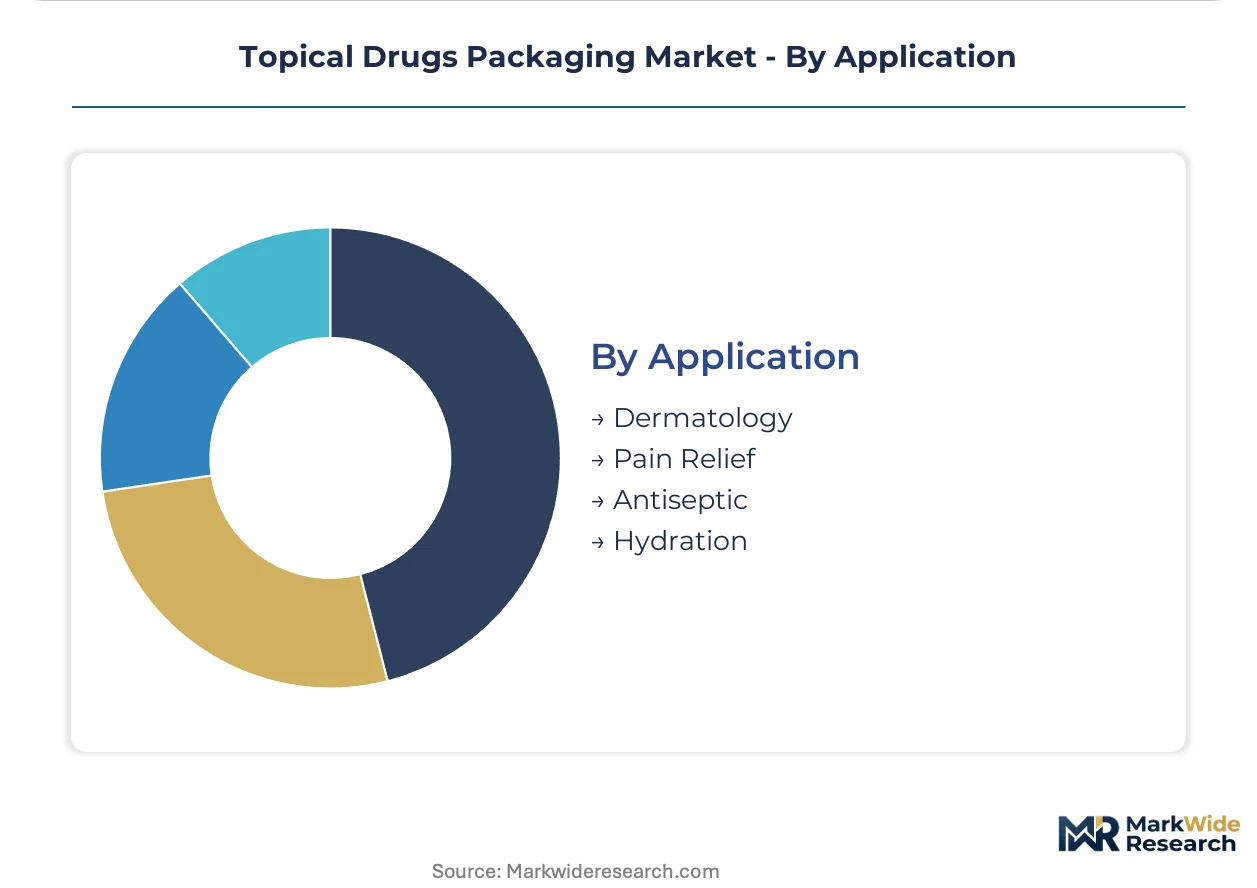
- Dermatology:Eczema, psoriasis, and acne formulations demand oxygen-sensitive barrier systems with precise dosing control. FDA and EMA stability-testing requirements for semi-solid dosage forms tighten material specifications for dermatology cream containers across United States and European manufacturing sites.
- Pain Relief:Transdermal patch and topical analgesic formats require adhesive-compatible barrier films with consistent drug release profiles. Tropical climate distribution challenges are accelerating multi-layer laminate adoption for pain relief products in high-humidity markets.
- Antiseptic:Alcohol-based and iodine formulations prioritize chemical resistance and child-resistant closure integration.
- Hydration:Emulsion stability and cosmetic elegance drive premium jar and tube specifications for consumer skincare.
Dermatology leads on scale; pain relief shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rhineland-Palatinate's pharmaceutical packaging corridor anchors European production capacity for barrier laminate tubes. FDA and EMA regulatory tightening is redistributing investment toward validated manufacturing clusters in Germany, the United States, and Japan.
United States
New Jersey's contract packaging corridor absorbs high-barrier tube output for dermatology prescriptions. FDA stability guidance for semi-solid drug products mandates enhanced container closure integrity documentation. Greater Philadelphia's pharmaceutical manufacturing belt is expanding aluminum-laminate co-extrusion capacity for oxygen-sensitive creams.
Germany
OTC topical sales through pharmacy channels concentrate demand for unit-dose sachets and metered pumps. EMA Annex 1 revisions on sterile manufacturing compel barrier technology upgrades. North Rhine-Westphalia's packaging engineering cluster is validating robotic tube-filling lines for automated crimp-seal inspection.
Japan
Geriatric dermatology patients generate demand for arthritis-friendly dispensers and tactile compliance packaging. PMDA stability requirements preserve glass jar specifications for high-value cream formulations. Kansai's pharmaceutical manufacturing zone is retrofitting tube lines for ergonomic applicator integration.
India
Domestic dermatology prescription growth and export contract manufacturing expand flexible laminate demand. CDSCO extractables testing standards extend qualification timelines for novel co-extrusion materials. Gujarat's pharmaceutical packaging belt is installing EVOH-compatible barrier film production for tropical climate distribution.
Switzerland
Premium dermatology brands sustain glass-polymer hybrid container specifications despite cost pressures. Swissmedic pharmacopeial standards enforce rigorous leachables documentation for semi-solid contact materials. Basel's pharmaceutical innovation corridor is piloting connected packaging with near-field communication adherence tracking.
Topical Drugs Packaging Market Competitive Landscape
Capacity expansion dominates the current landscape as converters scale aluminum-laminate tube production for oxygen-sensitive dermatology segments. The vendor base clusters around three strategic archetypes: diversified packaging conglomerates with multi-material platforms, specialized pharmaceutical primary packaging firms with regulatory validation depth, and regional contract manufacturers serving local pharmacy channels. M&A activity concentrates barrier technology acquisition, while geographic expansion targets proximity to FDA and EMA inspection-heavy manufacturing zones.
Among diversified packaging conglomerates, Amcor and Berry Global occupy positions spanning multi-layer laminate and polymer structures for tropical climate stability. Gerresheimer anchors the specialized pharmaceutical tier with glass and polymer primary packaging capacity validated for high-barrier topical applications. West Pharmaceutical Services exemplifies the regulatory-validated archetype, serving contract manufacturing networks with documented container closure integrity protocols. These three represent distinct competitive vectors: materials breadth, pharmaceutical regulatory depth, and integrated device-drug combination expertise.
| Leading Market Players |
|---|
| West Pharmaceutical Services |
| Schott |
| Amcor |
| Halo Pharma |
| Origin Pharma Packaging |
| Gerresheimer |
| Berry Global |
| Aphena Pharma Solutions |
| AptarGroup |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap European tube converters anchor supply-side discipline through generational ownership structures that resist short-term margin compression, translating into pricing stability for aluminum-laminate barrier formats even as EVOH resin costs fluctuate. This ownership pattern concentrates production capacity in Rhineland-Palatinate and North Rhine-Westphalia, creating regional pricing power that downstream dermatology brands must absorb or qualify alternative suppliers against FDA stability timelines.
Pricing Analysis
Distributor margin layers capture 18-25 points between converter ex-works and pharmacy shelf pricing for aluminum-laminate tubes, with three-tier pricing structure across premium, standard, and economy levels differentiated by barrier layer complexity and EVOH content. Certification-grade pricing separates FDA-validated formats from CE-marked equivalents, while volume scale discounts concentrate with specialty distributors serving United States dermatology clinics. Pricing pressure stems from REACH compliance costs transferring to converters reformulating phthalate-free polyolefin closures. Hospital pharmacies demonstrate lowest price sensitivity due to sterilization compatibility requirements, whereas direct-to-consumer channels absorb margin compression through automated pharmacy dispensing system qualifications.
Supply Chain Analysis
Single-source vulnerability sits with East Asian petrochemical clusters supplying EVOH resin for oxygen-barrier interlayers, exposing European and North American converters to input volatility that propagates through 12-18 month extractables validation cycles. Geographic supply concentration centers on Germany, the United States, and Japan for validated tube-filling capacity, while raw material dependencies draw from Saudi Arabian polyethylene feedstocks, South Korean EVOH polymerization, and domestic aluminum cold-rolling. Tariff exposure on aluminum laminate stocks threatens cost structures for tropical climate distribution formats. Distribution runs through specialty pharmaceutical distributors in the United States, pharmacy cooperative networks in Germany, and regional medical-device wholesalers in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Topical drugs packaging represents a late-cycle quality story where chronic dermatology management shifts toward home care settings demand premium barrier specifications and patient-handling-optimized designs that sustain margin structures despite input volatility.
For Market Incumbents: Deepen regulatory validation depth by expanding in-house barrier testing laboratories to compress USP and EP extractables qualification cycles, defending against emerging contract manufacturers with accelerated aging protocols. Prioritize backward integration into EVOH-compatible co-extrusion capacity to reduce East Asian resin dependency, while securing pharmacy channel control through automated dispensing system qualifications that lock out unvalidated competitors. For New Entrants and Emerging Players: Launch via direct-to-consumer pharmacy partnerships targeting Japan's geriatric dermatology segment with arthritis-friendly tube dispensers, bypassing incumbent distributor relationships. White-space availability concentrates in California's recyclable mono-material tube structures with bio-based barrier coatings, where extended producer responsibility mandates create first-mover advantage before incumbents reformulate legacy platforms. Near-field communication adherence tracking integration offers differentiated entry into biologic topical therapy packaging. For Investors and Strategic Acquirers: Diversified packaging conglomerates with pharmaceutical regulatory divisions represent the most active acquirer category in this space, seeking barrier technology assets to complement multi-material platforms. Long-term viability hinges on 5-10 year compliance-ready material platform positioning as FDA and EMA stability-testing requirements tighten. Target acquisition archetype: specialized pharmaceutical primary packaging firms with documented container closure integrity protocols and validated European manufacturing footprints. Signal to monitor: CDSCO and PMDA harmonization timelines that would expand addressable market for qualified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Validation Investment | FDA stability guidance compliance preserves premium pricing for validated barrier formats. |
| Backward Integration into Barrier Film | Captive EVOH co-extrusion capacity insulates margin from East Asian petrochemical volatility. |
| Connected Packaging Development | Near-field communication integration enables adherence program revenue streams for biologic therapies. |
| Sustainable Material Transition | California pharmaceutical waste regulations reward recyclable mono-material tube structures with bio-based coatings. |
| Robotic Automation Deployment | Vision-guided tube-filling lines compress changeover times between dermatology SKUs for contract packagers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with packaging converter operations directors, dermatology brand supply chain managers, FDA regulatory affairs consultants, and European pharmacy procurement officers with secondary validation against FDA guidance documents, EMA Annex 1 revisions, USP and EP pharmacopeial chapters, and customs trade data on EVOH resin imports. Bottom-up capacity assessments at manufacturing clusters in Germany, the United States, and Japan were triangulated against top-down prescription volume projections for semi-solid dosage forms.
Historical reference periods anchored volume and value trajectories across the modeling period, with segmentation dimensions covering packaging type, material platform, end-user channel, and therapeutic application. CAGRs were derived from regression analysis of prescription volume trends, regulatory approval timelines for novel barrier materials, and capacity expansion announcements. Industry-specific forecast inputs included EMA Annex 1 implementation schedules and REACH phthalate restriction phase-out calendars.
Several conditions sit outside the modeled scope, including potential EVOH supply disruptions from East Asian petrochemical facility outages, unanticipated FDA guidance revisions on extractables testing methodologies, and accelerated substitution of glass jars by advanced polymer barriers in high-value dermatology segments. Forecasts reflect documented assumptions on regulatory harmonization timelines and resin cost trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
United States Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
Cartoning Machines for Pharmaceutical Industry Market
Pharmaceutical Packaging
Europe Dietary Supplement Packaging Market
Pharmaceutical Packaging
India Pharmaceutical Packaging Market
Pharmaceutical Packaging
Pharmaceutical Labeling Market
Pharmaceutical Packaging
Global Vaccine Storage and Packaging Market
Pharmaceutical Packaging
Global Parenteral Packaging Market
Pharmaceutical Packaging
Plastic Vials and Ampoules Market
Pharmaceutical Packaging
North America Pharmaceutical Vials Market
Pharmaceutical Packaging
Philippines Pharmaceutical Packaging Market
Pharmaceutical Packaging
Temperature Controlled Pharmaceutical Containers Market
Pharmaceutical Packaging
Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Pharmaceutical Tubes Market
Pharmaceutical Packaging
Polymer Vials Market
Pharmaceutical Packaging
Oral Dose Packaging Market
Pharmaceutical Packaging
Asia-Pacific Pharmaceutical Plastic Bottles Market