
 Tube Closures Market | 2026-2036
Tube Closures Market Size, Share, and Industry Trends Forecast 2026-2036
Tube Closures Market Analytics
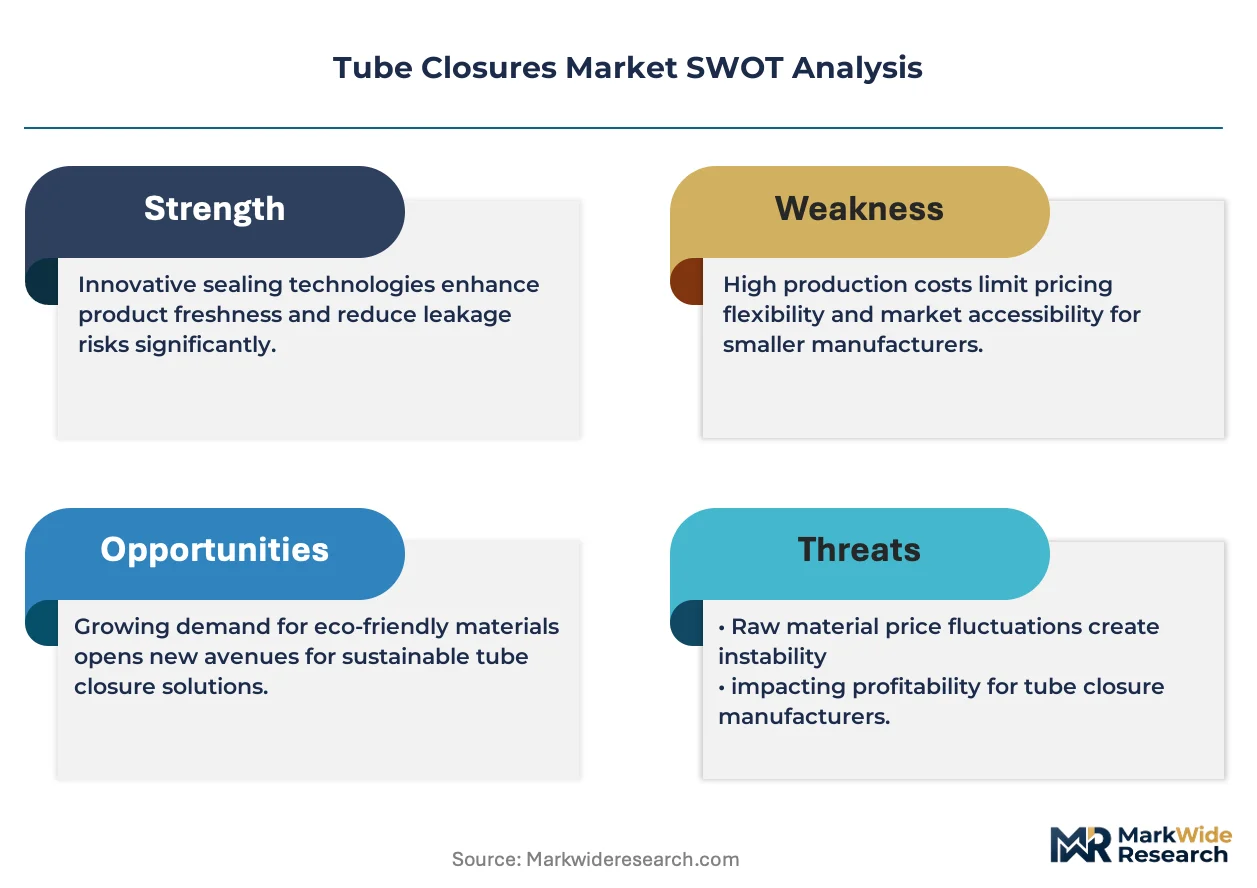
The gulf between premium dispensing closures and commodity screw caps is broadening in both unit economics and technical specification. Berry Global Inc. leverages its North American thermoforming footprint to anchor high-volume personal care contracts. AptarGroup Inc. differentiates through precision-engineered flip-top mechanisms for pharmaceutical dosing. Albéa Group specializes in sustainable material formulations that meet emerging recycled-content mandates across European cosmetics.
Tube closures are mechanical sealing devices engineered to dispense, protect, and preserve semi-viscous contents within collapsible or rigid tubes, typically incorporating thread geometries between 20mm and 40mm diameter and torque-release specifications measured in inch-pounds. Their primary industrial purpose centers on maintaining product integrity from fill through end-use while enabling controlled consumer access. Dispensing closures command margin premiums in pharmaceutical applications where dose accuracy determines therapeutic outcomes. Plastic resins dominate tonnage but aluminum closures retain structural importance in food and beverage segments requiring oxygen barrier performance. Child-resistant designs face escalating compliance complexity as regulatory thresholds tighten across multiple jurisdictions.
The FDA enforces child-resistant packaging standards under 16 CFR 1700 that directly shape closure engineering requirements for over-the-counter pharmaceutical tubes. EMA's Medical Device Regulation and REACH chemical restrictions in Europe compound material selection constraints for converters serving dual-market customers. Stakeholders must monitor how evolving extended producer responsibility frameworks in Germany and France reshape cost allocation across virgin and recycled resin supply channels.
Market Dynamics
Post-consumer recycled resin mandates are forcing converters to reengineer closure specifications while maintaining torque-release performance, compressing development timelines and fragmenting supplier qualification pools.
Growth Catalysts
- EU Single-Use Plastics Directive:Mandatory recycled-content thresholds for plastic packaging create guaranteed demand pull for compliant closure converters across German and French cosmetics supply chains.
- Pharmaceutical dose-precision requirements:FDA 16 CFR 1700 child-resistant standards and EMA Medical Device Regulation tighten specifications for over-the-counter tube dispensing, elevating technical barriers that favor engineered-solution providers.
- Rhine-Main packaging cluster concentration:Proximity to filling operations for personal care brands in Hesse reduces logistics costs and enables just-in-time closure delivery contracts.
Market Restraints
- Recycled resin feedstock volatility:Post-consumer polyethylene and polypropylene availability fluctuates with collection infrastructure investment cycles, compressing margin predictability for converters committed to recycled-content targets.
- Tooling capex concentration:Precision mold fabrication for flip-top and disc-top mechanisms requires specialized cavity machining that clusters with German and Italian equipment suppliers, creating geographic supply risk.
- Aluminum substitution ceiling:Oxygen barrier requirements in food and beverage tube applications prevent full plastic displacement despite sustainability pressures, locking dual-material production complexity into converter operations.
Strategic Opportunities
- Extended producer responsibility frameworks:Germany's VerpackG and France's AGEC law create compliance-service revenue streams for closure providers offering design-for-recycling consultation alongside physical components.
- Biopolymer torque engineering:Polylactic acid and bio-based polyethylene formulations that achieve thread engagement specifications without virgin petroleum inputs open premium positioning in Nordic personal care markets.
- Direct-to-brand digital channels:E-procurement platforms for mid-size cosmetics brands bypass traditional distributor markups, enabling margin capture for converters with configurable minimum order quantities.
Industry Challenges
- Multi-jurisdiction child-resistant certification:Divergent testing protocols between FDA, ISO 8317, and ANSM requirements extend product validation timelines and duplicate third-party laboratory expenditure.
- Legacy injection molding asset retrofitting:Existing hot-runner systems designed for virgin resin rheology require screw and barrel modification to process degraded molecular-weight recycled feedstock without flash defects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tube Closures Market |
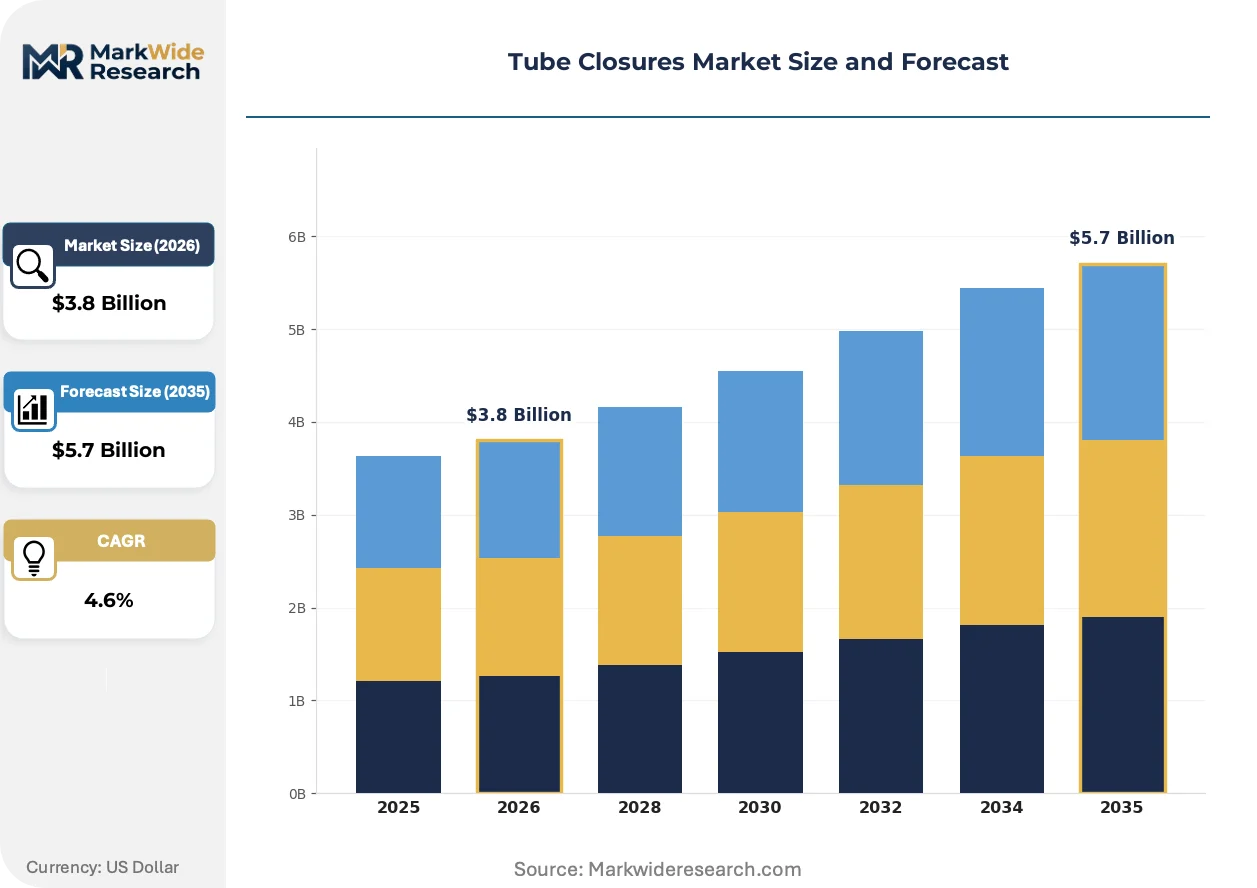
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Screw Caps, Snap Caps, Flip Tops, Dispensing Closures Material: Plastic, Aluminum, Glass, Cork Application: Pharmaceuticals, Personal Care, Food & Beverage, Household Products Closure Design: Child-Resistant, Tamper-Evident, Easy-Open, Standard |
| Companies Covered | IntraPac International Corporation, Berry Global Inc., Essel Propack Limited, AptarGroup Inc., Silgan Holdings Inc., Amcor Plc, Albéa Group, Kap Group, Winpak Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tube Closures Market Evolving Landscape
Digital thread measurement and closed-loop torque feedback systems are compressing quality variance in high-speed closure production, while regulatory chemical restrictions and brand sustainability commitments reshape material selection priorities.
Smart dispensing closures with integrated flow sensors and Bluetooth connectivity are integrating dose-tracking capabilities for pharmaceutical adherence applications. Chronic disease management brands in North American markets pilot these devices for insulin and topical hormone therapies. The technology is integrating patient data capture into closure hardware, shifting value propositions from mechanical sealing toward therapeutic outcome verification.
REACH chemical restrictions on intentionally added microplastics and ECHA proposals for PFAS limitations constrain lubricant and slip-agent formulations in polypropylene closures. German converters reformulate internal mold release compounds to maintain ejection consistency without restricted substances. Cosmetic tube brands serving EU markets accelerate supplier audits to preempt compliance gaps ahead of enforcement phase-ins.
Brand procurement teams consolidate closure specifications across regional product portfolios to achieve volume-scale pricing and reduce SKU complexity. Personal care multinationals in the Rhine-Main corridor now mandate pan-European platform designs that sacrifice some local customization for supply chain efficiency. This consolidation pressure most visibly affects mid-size regional cosmetics brands that previously relied on differentiated closure aesthetics for shelf positioning.
Tube Closures Market Segmentation
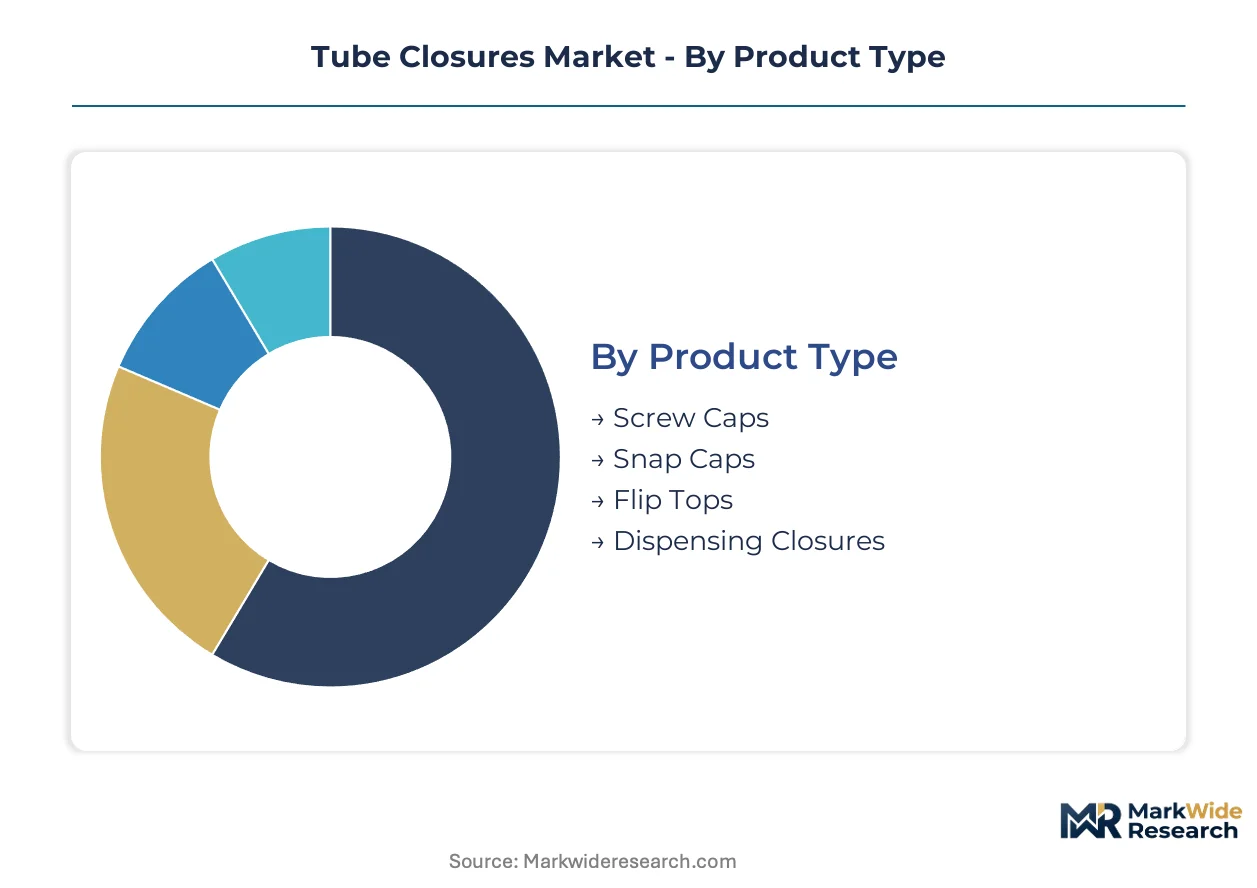
Tube closure specifications fragment across torque tolerances, barrier requirements, and regulatory compliance tiers. Each segmentation axis carries distinct margin profiles and supplier qualification barriers that shape converter strategy.
Product Type:
Thread geometry and actuation mechanisms define the technical specification ladder.
- Screw Caps:Helical thread engagement between 20mm and 40mm diameters delivers predictable torque-release performance. Food and beverage brands in Germany's Rhine-Main cluster specify these for oxygen-sensitive condiments where seal integrity outweighs dispensing convenience.
- Dispensing Closures:Precision-engineered orifice geometries control viscosity-dependent flow rates for semi-viscous pharmaceuticals. FDA 16 CFR 1700 child-resistant requirements and EMA Medical Device Regulation tighten validation protocols for dose-accuracy applications.
- Snap Caps:Radial interference fits eliminate thread wear in high-cycle personal care tubes.
- Flip Tops:Living-hinge mechanisms enable single-handed actuation for on-the-go consumption.
Screw caps lead on scale; dispensing closures lead on momentum.
Material:
Barrier performance and recycled-content mandates drive specification divergence.
- Plastic:Polyethylene and polypropylene formulations dominate tonnage across personal care and household segments. EU Single-Use Plastics Directive recycled-content thresholds force converters to reengineer screw and barrel systems for degraded molecular-weight feedstock.
- Aluminum:Rolled metal closures deliver oxygen barrier performance that plastic cannot replicate in food paste applications. French and German food brands retain aluminum specifications despite sustainability pressures, locking dual-material production complexity into converter operations.
- Glass:Borosilicate and soda-lime formulations serve premium cosmetic positioning.
- Cork:Natural and agglomerated variants anchor niche organic personal care branding.
Plastic commands volume; aluminum commands specification premiums.
Application:
End-use regulatory exposure determines compliance investment intensity.
- Pharmaceuticals:FDA, EMA, and ANSM child-resistant protocols demand multi-jurisdiction certification. Topical hormone and insulin tube brands pilot Bluetooth-enabled dose-tracking closures for chronic disease management adherence.
- Personal Care:REACH chemical restrictions and brand sustainability commitments accelerate supplier audits for Nordic market access.
- Food & Beverage:Oxygen barrier requirements preserve shelf stability in condiment and puree tubes.
- Household Products:Cost-optimized specifications prioritize fill-line throughput over dispensing precision.
Pharmaceuticals absorb the highest compliance burden; personal care absorbs the fastest material transition pressure.
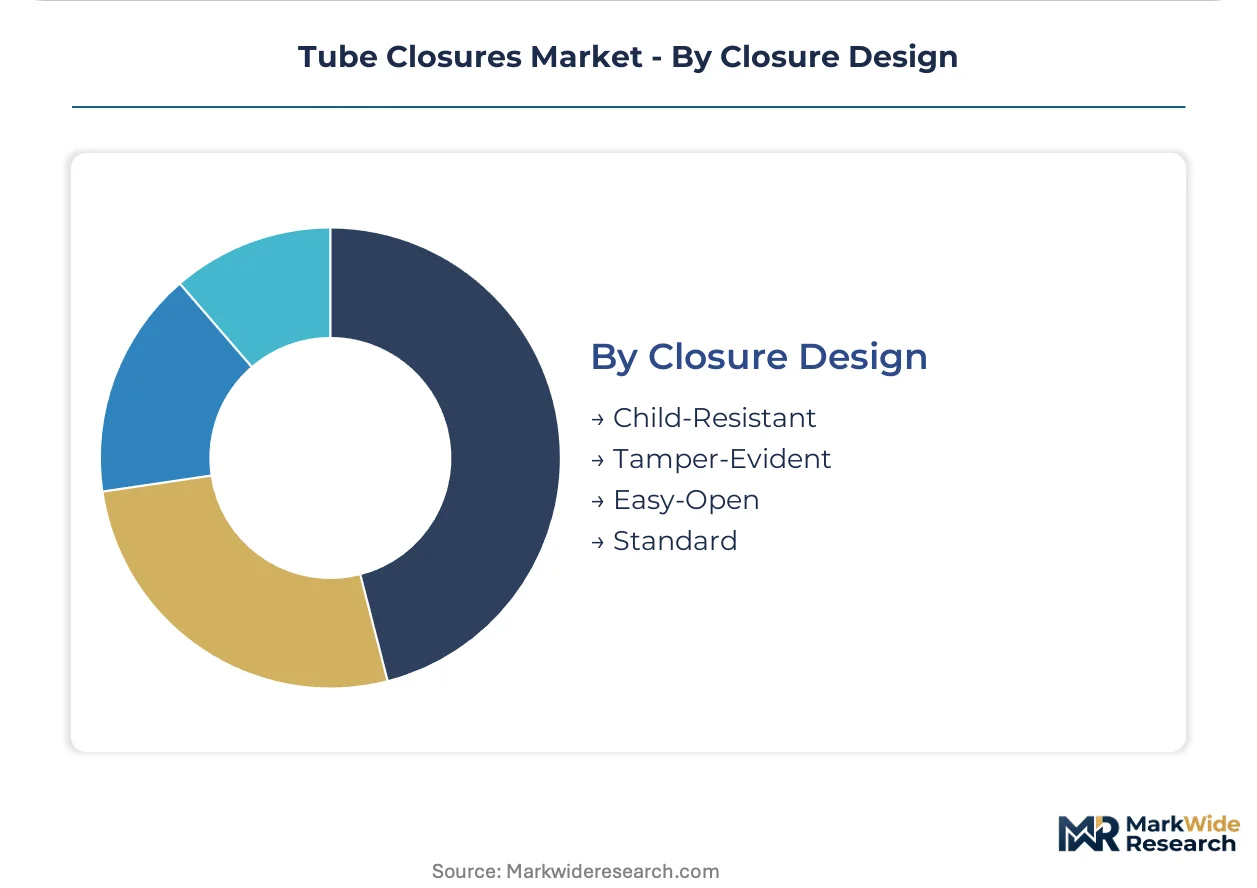
Closure Design:
Regulatory threshold differentiation creates tiered engineering requirements.
- Child-Resistant:ISO 8317, FDA 16 CFR 1700, and ANSM testing protocols extend validation timelines. Divergent jurisdiction requirements duplicate third-party laboratory expenditure for dual-market suppliers.
- Tamper-Evident:Break-ring or membrane integrity features satisfy supply chain security demands.
- Easy-Open:Reduced torque-release specifications serve aging demographics and accessibility requirements.
- Standard:Unadorned thread geometries minimize tooling capex for commodity volume contracts.
Child-resistant designs concentrate regulatory complexity; tamper-evident designs concentrate brand security investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled toolmakers and precision mold engineers cluster in Germany's Rhine-Main corridor, anchoring European closure production. North American thermoforming specialists concentrate around Chicago and Toronto logistics hubs. Asian converters scale polymer processing in coastal manufacturing zones.
United States
Chicago-area thermoforming plants supply personal care brands with high-volume screw cap contracts. FDA 16 CFR 1700 child-resistant standards drive validation investment for pharmaceutical tube applications. Wisconsin and Illinois host precision mold fabrication facilities serving North American cosmetics filling operations.
Germany
Hesse's Rhine-Main packaging cluster enables just-in-time closure delivery to Frankfurt-region cosmetics headquarters. VerpackG extended producer responsibility law creates compliance-service revenue for design-for-recycling consultation. Tooling suppliers in Baden-Württemberg specialize in living-hinge mechanisms for flip-top pharmaceutical dispensers.
China
Yangtze River Delta converters process polyethylene and polypropylene at scale for export-oriented personal care brands. GB standards for food-contact plastics shape material selection in condiment tube applications. Zhejiang and Jiangsu provinces house injection molding capacity serving domestic and Southeast Asian markets.
France
AGEC law anti-waste provisions accelerate supplier audits for recycled-content compliance in Paris-region cosmetics headquarters. ANSM pharmaceutical packaging requirements tighten validation protocols for dose-precision closures. Lyon-area converters reformulate mold release compounds to meet ECHA microplastic restrictions.
India
Maharashtra and Gujarat plastic processors supply cost-optimized screw caps for domestic FMCG tube brands. BIS certification requirements for food-contact materials influence resin selection in condiment applications. Mumbai-Pune corridor hosts conversion capacity serving South Asian personal care markets.
Tube Closures Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the tube closures market. Integrated resin compounders and precision molders anchor high-volume contracts, while specialized engineering firms capture premium dispensing applications. Three archetypes dominate: diversified packaging conglomerates with thermoforming scale, precision-engineering specialists focused on pharmaceutical compliance, and regional converters serving local FMCG brands. Competitive moves concentrate on recycled-content qualification partnerships and mold technology licensing agreements.
Within the diversified packaging tier, Berry Global Inc. and Amcor Plc exemplify scale-driven positioning across multiple substrate categories. AptarGroup Inc. occupies the precision-engineering archetype with its focus on flip-top and disc-top mechanisms. Albéa Group represents the sustainability-forward specialist segment, anchoring European recycled-content mandates through material formulation expertise.
| Leading Market Players |
|---|
| IntraPac International Corporation |
| Berry Global Inc. |
| Essel Propack Limited |
| AptarGroup Inc. |
| Silgan Holdings Inc. |
| Amcor Plc |
| Albéa Group |
| Kap Group |
| Winpak Ltd. |
| Others |
Value Network & Pricing Analysis
Precision-dispensing closure premiums diverge from commodity screw-cap baselines across torque-tolerance certification tiers, with pharmaceutical-grade child-resistant mechanisms commanding engineering-intensive pricing while German Rhine-Main cluster buyers negotiate volume-scaled commodity contracts. This bifurcation concentrates margin capture among Baden-Württemberg tooling specialists for premium tiers and Hesse-based converters for high-throughput personal care supply chains.
Pricing Analysis
Bundled design-for-recycling consultation services separate German VerpackG-compliant converters from unbundled commodity suppliers competing on per-unit transactional pricing alone. Three-tier pricing structure across premium, standard, and economy levels tracks FDA 16 CFR 1700 certification status, with child-resistant validated closures carrying 40-60% premiums over standard thread geometries. Cost compression in recycled-content tiers intensifies because post-consumer polyethylene feedstock volatility erodes margin predictability for converters committed to EU Single-Use Plastics Directive thresholds. Household product brands exhibit highest price sensitivity, while pharmaceutical dose-precision buyers absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Regional distribution centers in Hesse, Baden-Württemberg, and North Rhine-Westphalia form a hub-and-spoke pattern serving Frankfurt-region cosmetics headquarters with just-in-time delivery contracts. Manufacturing concentrates in Germany, China, and the United States, with Yangtze River Delta processors feeding export-oriented personal care brands and Chicago-area thermoforming plants anchoring North American volume. Virgin and recycled polypropylene resins, precision-machined mold cavities, and aluminum coil stock constitute critical input dependencies. Single-source vulnerability clusters with Italian and German tooling equipment suppliers for living-hinge flip-top mechanisms. Distribution runs through brand-direct procurement platforms and specialized packaging distributors serving mid-size cosmetics formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where personal care brand procurement teams consolidate specifications toward pan-European platform designs, elevating converters with validated recycled-content formulations and precision torque engineering over commodity competitors.
For Market Incumbents: Deepen backward integration into post-consumer recycled resin compound operations to secure feedstock certainty against collection infrastructure volatility. Anchor capacity expansion in the Rhine-Main corridor to capture just-in-time delivery premiums from Frankfurt-region cosmetics headquarters. Defend margin position by accelerating FDA and EMA dual-certification timelines before regulatory divergence widens compliance cost gaps. For New Entrants and Emerging Players: EU Single-Use Plastics Directive in Germany and France opens a window for biopolymer torque engineering specialists to capture Nordic personal care sustainability premiums. Target mid-size cosmetics brands bypassing traditional distributor markups through e-procurement platforms with configurable minimum order quantities. Penetrate the pharmaceutical dose-tracking closure segment where Bluetooth-enabled adherence hardware remains underdeveloped outside North American chronic disease management pilots. For Investors and Strategic Acquirers: Consolidation pressure builds where VerpackG compliance-service revenue streams and recycled-content qualification capabilities concentrate among fragmented mid-size German converters. Long-term viability favors asset-light designers with mold technology licensing agreements over capital-heavy resin compounders facing feedstock volatility. Watch for inflection signals in ECHA PFAS enforcement phase-ins that could disqualify legacy lubricant formulations and trigger rapid supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Recycled-Content Formulation Partnership | EU Single-Use Plastics Directive mandates secure guaranteed demand pull from German cosmetics brands. |
| Precision Mold Technology Licensing | Baden-Württemberg living-hinge expertise transfers to Asian converters seeking pharmaceutical compliance. |
| Design-for-Recycling Consultation Service | VerpackG extended producer responsibility frameworks create recurring revenue alongside physical components. |
| Biopolymer Torque Engineering R&D | Polylactic acid thread engagement specifications unlock premium positioning in Nordic sustainability markets. |
| Direct-to-Brand Digital Channel Buildout | E-procurement platforms bypass distributor markups for mid-size cosmetics formulators with flexible MOQs. |
Research Methodology
Direct dialogue with closure engineering directors, brand procurement managers at personal care multinationals, regulatory affairs leads at pharmaceutical tube manufacturers, and precision mold fabricators in Baden-Württemberg grounded qualitative findings. Secondary validation drew from FDA 16 CFR 1700 filings, EMA Medical Device Regulation guidance documents, German VerpackG implementation reports, and EU Single-Use Plastics Directive threshold announcements. Bottom-up resin consumption estimates and top-down packaging value chain triangulation cross-verified market sizing across the analysis window.
Segment-level projections incorporated thread geometry categories, material formulation tiers, end-use regulatory exposure, and regional production cluster concentration throughout the forecast period. CAGRs derived from regression against historical resin price elasticity, regulatory compliance cost trajectories, and brand consolidation patterns in the Rhine-Main corridor. Forecast inputs included post-consumer recycled polyethylene availability indices and pharmaceutical dose-precision adoption curves in chronic disease management applications.
Revisions become necessary when ECHA microplastic enforcement timelines accelerate, when recycled resin collection infrastructure investment cycles diverge from modeled assumptions, or when FDA-EMA regulatory harmonization fractures further. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Crimp-On Spouts Market
Caps and Closures
Brazil Plastic Caps and Closures Market
Caps and Closures
Steel Ring Pull Caps Market
Caps and Closures
Twist Caps Market
Caps and Closures
Cap Liner Market
Caps and Closures
Shrink Bands Market
Caps and Closures
Aerosol Valves Market
Caps and Closures
Crown Caps Market
Caps and Closures
Magnetic Closure Box Market
Caps and Closures
United Kingdom Plastic Caps and Closures Market
Caps and Closures
Lug Caps Market
Caps and Closures
Vietnam Plastic Caps and Closures Market
Caps and Closures
Spigot End Cap Market
Caps and Closures
Spouted Dispensing Closures Market
Caps and Closures
Bag Closures and Seals Market
Caps and Closures
Brush and Dauber Caps Market