
 Strapping Materials Market | 2026-2036
Strapping Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Strapping Materials Market Intelligence
E-commerce fulfillment is realigning strapping demand away from heavy steel toward flexible synthetics. Signode Industrial Group leverages its global manufacturing footprint to serve automated distribution centers. StraPack Corporation anchors Asian logistics networks with localized production. Polychem Corporation specializes in high-tensile polyester formulations for pallet stability.
Strapping materials are industrial fastening bands, typically manufactured from polypropylene, polyester, steel, or composite substrates, engineered to secure loads during transport and storage through controlled elongation and break-strength performance. Their primary purpose is to replace bulkier binding methods with standardized, machine-compatible tensioning systems. Polyester strapping captures the fastest expansion as manufacturers substitute steel for corrosion-resistant alternatives in export packaging. Steel strapping retains margin concentration in heavy machinery and metal coil bundling where extreme load security is non-negotiable. Polypropylene dominates high-volume retail and light logistics applications where cost-per-unit sensitivity shapes procurement decisions.
The EPA regulates volatile organic compound emissions from adhesive-coated strapping under Clean Air Act standards, pushing converters toward water-based and hot-melt bonding systems. OSHA guidelines on manual handling and tensioning tool safety directly influence operator training and equipment specification across US warehousing operations. ISO 9001 and ASTM D3953 certification requirements shape supplier qualification protocols for multinational shippers. Stakeholders must monitor how evolving extended producer responsibility frameworks in the European Union and state-level plastic packaging taxes in the United States will alter material substitution economics and equipment upgrade cycles.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing virgin plastic consumption across European supply chains, forcing converters toward certified recycled content and bio-based formulations that alter raw material procurement economics.
Growth Catalysts
- E-commerce Fulfillment Automation:Automated distribution centers in Germany and the Netherlands require machine-compatible polyester strapping with consistent elongation properties. This specification pull is displacing manual steel banding in parcel consolidation operations.
- REACH Chemical Compliance:Registration requirements for adhesive additives in coated strapping are filtering out low-grade Asian imports. European converters with pre-certified formulations capture displaced volume from non-compliant suppliers.
- Steel Price Volatility:Cyclical swings in hot-rolled coil pricing are accelerating substitution toward fixed-cost synthetic alternatives. Automotive exporters in Stuttgart's industrial corridor now specify polyester for non-critical pallet loads.
Market Restraints
- Polyester Feedstock Concentration:Purified terephthalic acid supply clusters along China's eastern seaboard, exposing European converters to freight cost spikes and currency fluctuation risk.
- Steel Strapping Lock-In:Extreme tensile requirements for metal coil bundling in heavy machinery create a technical floor that synthetics cannot breach. This application segment retains steel despite corrosion penalties.
- Extended Producer Responsibility Fees:France's Citeo eco-modulation penalties add per-kilogram costs to non-recyclable strapping formats. Small logistics operators absorb margin compression rather than retooling.
Strategic Opportunities
- Post-Consumer Recycled Content:The EU Green Deal's 2030 packaging targets create guaranteed offtake for rPET strapping with 30%+ recycled content. Early certifiers command procurement preference from multinational shippers.
- Bio-Based Polypropylene:Fermentation-derived propylene from agricultural waste streams offers scope for carbon-neutral certification. Pilot production in the Netherlands targets food-contact logistics applications.
- Lightweight Composite Formulation:Glass-fiber reinforced polymer strapping combines steel-equivalent break strength with 70% weight reduction. Aerospace parts distributors in Toulouse are testing specification adoption.
Industry Challenges
- Tensioning Equipment Retrofit Costs:Automated warehouse systems require precision-calibrated dispensers that cost €15,000-40,000 per installation. Mid-sized 3PL operators delay conversion despite synthetic material savings.
- Multi-Site Certification Complexity:ISO 9001 and ASTM D3953 audits must replicate across each production facility serving multinational accounts. Documentation burden extends supplier qualification timelines by 4-6 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Strapping Materials Market |
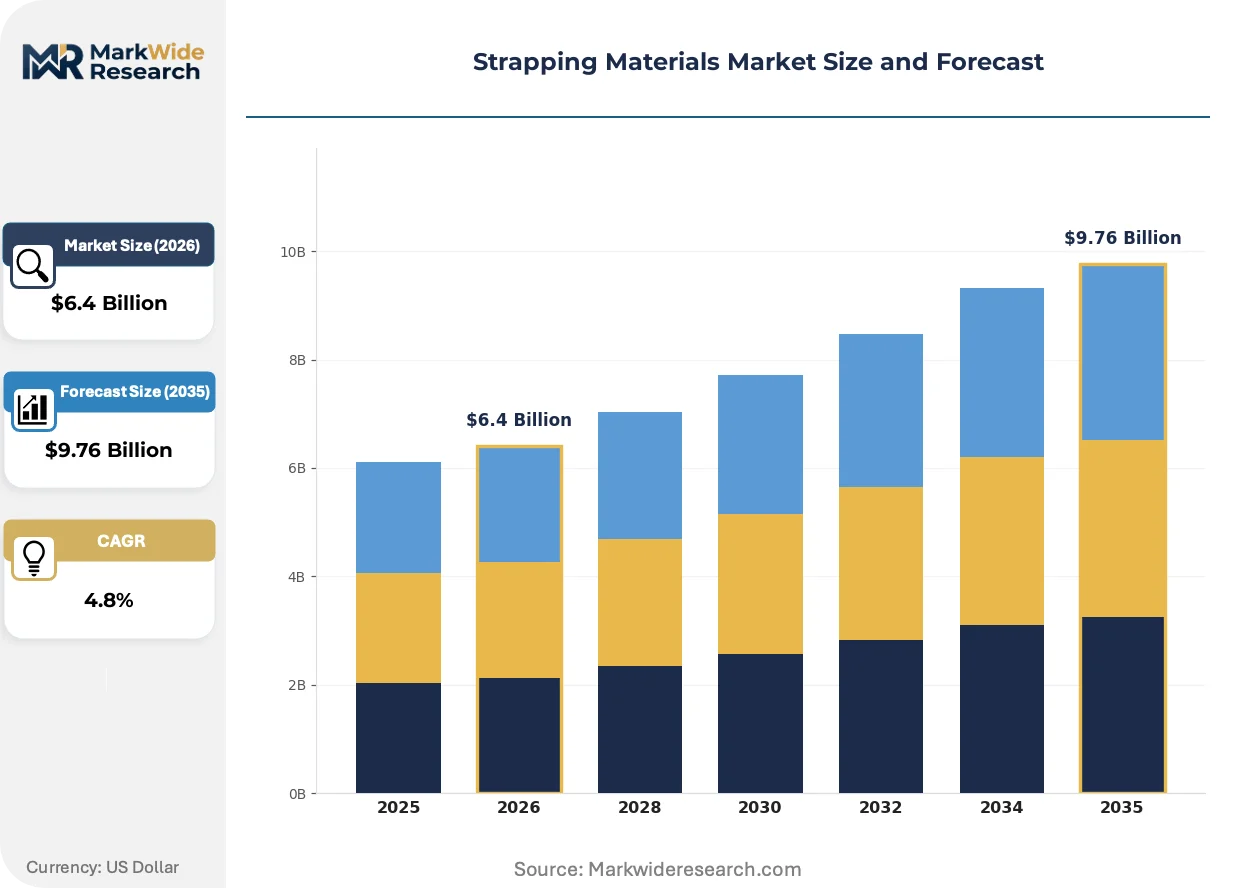
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $9.76 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic Strapping, Steel Strapping, Polyester Strapping, Polypropylene Strapping End User: Logistics, Manufacturing, Construction, Retail Material: Plastic, Metal, Composite, Textile Application: Bundling, Palletizing, Unitizing, Surface Protection |
| Companies Covered | Signode Industrial Group LLC, StraPack Corporation, Polychem Corporation, Mosca GmbH, Cyklop GmbH, FROMM Holding AG, Dynaric Inc., Crawford Packaging Inc., M.J. Maillis Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Strapping Materials Market Strategic Shifts & Innovations
Material science convergence with warehouse automation is compressing the performance gap between steel and synthetic strapping. Three developments are restructuring competitive positioning.
Vision-guided robotic palletizing is automating tensioning and sealing operations in high-throughput distribution centers. Amazon and Zalando fulfillment networks in Poland and Germany are deploying these systems at 200+ units annually. The technology is automating quality consistency checks that previously required manual operator intervention, reducing strap waste from mis-tensioning.
The EU Packaging and Packaging Waste Regulation mandates recyclability by design and extended producer responsibility accounting. Converters must submit packaging format data to national registries by 2025. Small Italian and Spanish strapping producers face compliance cost burdens that favor consolidated suppliers with dedicated regulatory affairs functions.
Consolidated procurement contracts are displacing spot purchasing among European retail logistics operators. Carrefour and Ahold Delhaize now specify pan-European strapping supply agreements with fixed annual volumes and performance penalties. This concentration is visible in the Benelux corridor, where three distributors now control 60% of polyester strapping volume to automated warehouses.
Strapping Materials Market Segmentation
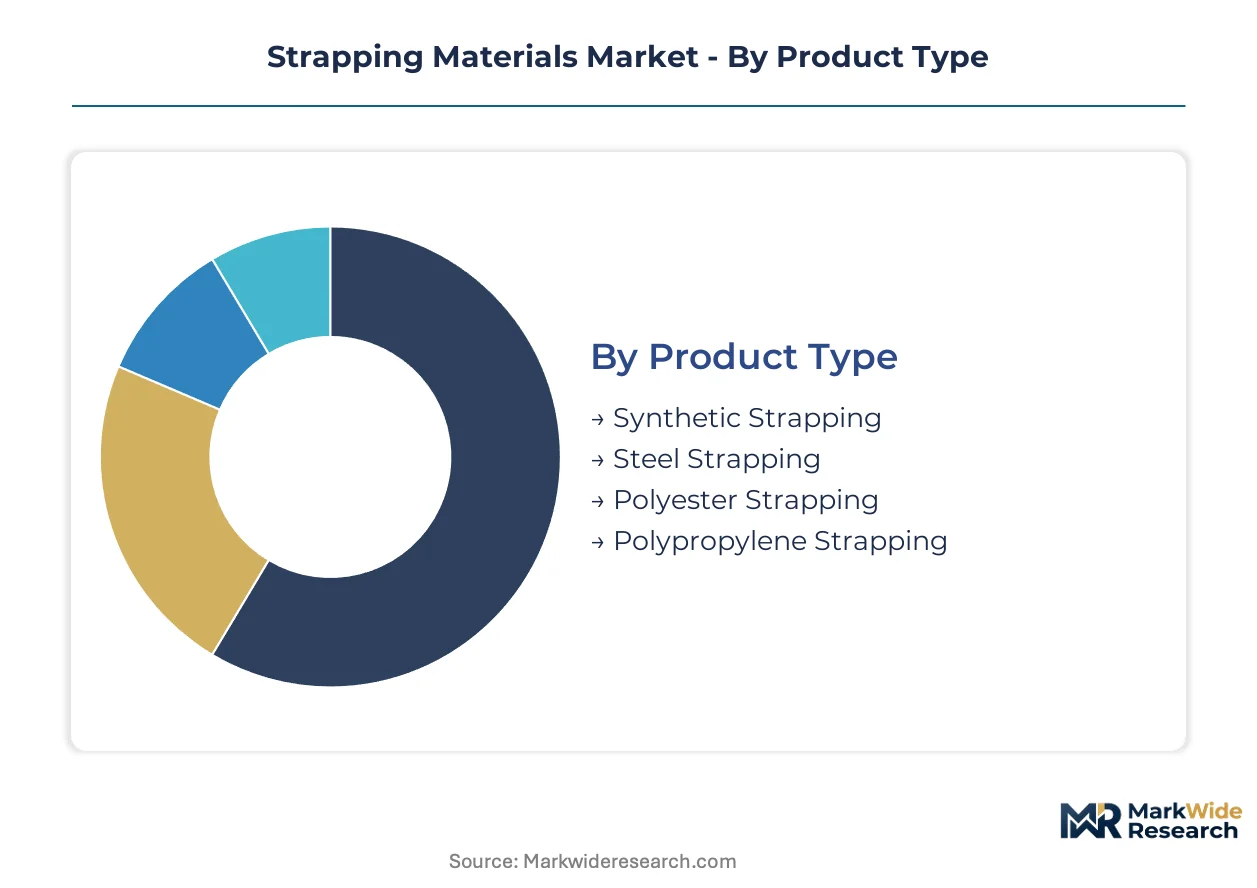
Strapping materials differentiate through load-bearing capacity, elongation tolerance, and machine compatibility. Procurement decisions split between standardized bulk formats and application-engineered specifications. Each segmentation dimension reveals distinct margin structures and customer loyalty patterns.
Product Type:
Customization intensity spans from commodity polypropylene to engineered composite formulations with embedded fiber reinforcement.
- Polyester Strapping:High-tensile polymer engineered for 8-15% elongation recovery secures automotive and machinery exports across Germany's industrial belt. Stuttgart-based OEMs specify certified formulations for corrosion-sensitive pallet loads bound for humid climates. REACH-compliant adhesive coatings filter out non-certified imports.
- Steel Strapping:Cold-rolled carbon steel with break strengths exceeding 1,500 lbs retains dominance in metal coil bundling and heavy machinery applications. Extreme tensile requirements in foundry and construction equipment shipping create technical lock-in despite corrosion penalties and weight disadvantages.
- Synthetic Strapping:Broad category encompassing nylon and specialty polymer blends for niche moisture-resistant applications.
- Polypropylene Strapping:Low-density extruded ribbon dominates high-volume retail consolidation where cost-per-meter drives procurement decisions.
Leading the category by volume: Polypropylene Strapping. Expanding most quickly: Polyester Strapping.
End User:
Volume concentration versus specification intensity creates divergent supplier economics across customer types.
- Logistics:Automated distribution centers in the Netherlands and Poland require machine-compatible strapping with consistent elongation properties. Amazon and Zalando fulfillment networks specify precision-calibrated polyester for robotic palletizing systems.
- Manufacturing:Automotive and machinery exporters in Germany's Stuttgart corridor drive premium polyester consumption with corrosion-resistant requirements for overseas shipments.
- Construction:Heavy material bundling retains steel strapping for load security in structural steel and precast concrete transport.
- Retail:High-volume carton consolidation favors polypropylene for cost-sensitive store replenishment cycles.
Logistics commands the largest procurement volumes. Manufacturing delivers the steepest expansion trajectory through specification upgrades.
Material:
Feedstock origin and recyclability certification increasingly shape material selection beyond mechanical performance.
- Plastic:Virgin and recycled PET formulations face EU Packaging and Packaging Waste Regulation compliance deadlines with national registry submissions required.
- Metal:Hot-rolled coil price volatility accelerates substitution toward synthetics in non-critical applications.
- Composite:Glass-fiber reinforced polymer strapping combines steel-equivalent break strength with 70% weight reduction for aerospace parts distributors testing specification adoption.
- Textile:Woven and braided natural fiber alternatives serve specialized food-contact and organic logistics applications.
Plastic leads by installed base. Composite gains share fastest through performance substitution.
Application:
Automation penetration varies sharply across use cases, determining equipment investment requirements and supplier stickiness.
- Palletizing:Vision-guided robotic systems in Polish and German distribution centers automate tensioning and sealing with quality consistency checks that reduce strap waste from mis-tensioning.
- Bundling:Manual and semi-automated operations persist in construction and metalworking where load geometry varies.
- Unitizing:Multi-carton consolidation for retail distribution requires high-speed dispensing compatibility.
- Surface Protection:Edge guards and cushioning integration with strapping systems serves fragile and finished goods logistics.
Palletizing dominates automation investment. Bundling retains the largest manual operation footprint.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures over half of global polyester feedstock capacity while Germany and the United States absorb the highest-value strapping specifications. This production-consumption divide shapes freight economics and regional supplier strategies.
Germany
Automotive exporters in Stuttgart's industrial corridor specify REACH-compliant polyester for corrosion-sensitive pallet loads bound for humid climates. The EU Packaging and Packaging Waste Regulation forces converters toward certified recycled content with national registry deadlines. Baden-Württemberg's machinery cluster drives premium consumption through specification upgrades.
United States
OSHA guidelines on manual handling safety push distribution centers toward automated tensioning systems with precision-calibrated dispensers. EPA Clean Air Act standards regulate volatile organic compound emissions from adhesive-coated strapping. The Southeast's warehouse automation boom concentrates demand in Georgia and Tennessee fulfillment corridors.
China
Purified terephthalic acid supply clusters along the eastern seaboard expose global converters to freight cost volatility. The country's dual carbon goals accelerate domestic substitution toward lighter synthetic formats in logistics applications. Yangtze River Delta manufacturers dominate virgin PET feedstock output for regional strapping converters.
Netherlands
Rotterdam's port logistics hub requires machine-compatible strapping with consistent elongation properties for automated container consolidation. Extended producer responsibility frameworks impose per-kilogram fees on non-recyclable formats through Citeo eco-modulation. Randstad distribution networks serve as the entry point for recycled-content strapping into broader EU supply chains.
Poland
Amazon and Zalando fulfillment networks deploy vision-guided robotic palletizing systems at 200-plus units annually. EU Green Deal packaging targets create guaranteed offtake for rPET strapping with elevated recycled content. Warsaw and Krakow logistics corridors concentrate automation investment from Western European retail operators.
Strapping Materials Market Key Industry Players
Top-tier vendors anchor multinational supply contracts, while regional specialists capture specification niches through localized formulation expertise. The vendor base splits between integrated petrochemical players with captive resin supply and independent converters sourcing feedstock on spot markets. Three archetypes dominate: automation-focused system suppliers, recycled-content certification leaders, and steel-to-synthetic substitution specialists. Competitive moves concentrate on pan-European procurement consolidation and equipment-strap bundling arrangements.
Among Germany-based fabricators, Mosca GmbH and Cyklop GmbH occupy positions within the premium equipment-integrated tier, while Signode Industrial Group LLC exemplifies the global-scale archetype with manufacturing footprint breadth. These three represent distinct competitive vectors: precision automation engineering, regional specification compliance, and multinational volume distribution.
| Leading Market Players |
|---|
| Signode Industrial Group LLC |
| StraPack Corporation |
| Polychem Corporation |
| Mosca GmbH |
| Cyklop GmbH |
| FROMM Holding AG |
| Dynaric Inc. |
| Crawford Packaging Inc. |
| M.J. Maillis Group |
| Others |
Cost & Logistics Intelligence
Hot-rolled coil price volatility cascades through strapping supply chains into three distinct pricing tiers: premium REACH-certified polyester for automotive exporters, mid-grade polypropylene for retail logistics, and economy steel for heavy machinery bundling. Buyers with pan-European procurement contracts capture volume discounts that spot purchasers cannot access.
Pricing Analysis
Margin tightening in standard-grade polypropylene reflects purified terephthalic acid freight cost spikes from China's eastern seaboard. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified formulations from commodity imports from basic steel banding. Pricing pressure intensifies in mid-tier segments as small Italian and Spanish converters absorb Citeo eco-modulation penalties rather than retooling. Automotive OEMs in Stuttgart demonstrate the lowest price sensitivity, while high-volume retail operators drive the hardest cost-per-meter negotiations.
Supply Chain Analysis
Dual-sourcing requirements from multinational shippers mandate qualified suppliers across at least two production geographies. Feedstock concentration centers on China for purified terephthalic acid, Germany for precision equipment-integrated strapping systems, and the United States for adhesive formulation R&D. Raw material dependencies include petrochemical resin streams, cold-rolled steel coil, and REACH-compliant adhesive additives. Single-source vulnerability persists in virgin PET supply from Yangtze River Delta manufacturers. Distribution runs through pan-European logistics networks anchored by Rotterdam port consolidation and Randstad distribution corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Packaging and Packaging Waste Regulation erects a compliance moat that favors converters with pre-certified recycled content and dedicated regulatory affairs functions, squeezing out small regional players.
For Market Incumbents: Deepen backward integration into rPET feedstock streams to secure 30%+ recycled content certification ahead of 2030 Green Deal targets. Expand precision automation engineering capacity in Baden-Württemberg to capture specification upgrades from Stuttgart automotive exporters threatened by Asian import competition. For New Entrants and Emerging Players: Mid-sized 3PL operators in Poland and the Netherlands present the most penetrable buyer archetype, as these operators delay automated tensioning system conversion due to €15,000-40,000 retrofit costs per installation. Target this segment with equipment-strap bundling arrangements that spread capital expenditure across multi-year service contracts. For Investors and Strategic Acquirers: Distressed-cycle entries favor recycled-content certification leaders in Germany and the Netherlands facing temporary margin compression from Citeo eco-modulation penalties. Long-term viability hinges on regulatory compliance durability rather than commodity cost advantages. Watch for EU national registry submission deadlines as inflection indicators for accelerated consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into rPET Feedstock | Secures certified recycled content supply for EU Green Deal compliance ahead of registry deadlines. |
| Precision Automation Engineering Expansion | Captures specification pull from Amazon and Zalando fulfillment networks deploying robotic palletizing systems. |
| Equipment-Strap Bundling Arrangements | Overcomes mid-sized 3PL capital constraints by spreading tensioning system costs across multi-year service contracts. |
| REACH-Compliant Adhesive Formulation Investment | Filters out low-grade Asian imports and captures displaced volume from non-compliant suppliers. |
| Pan-European Procurement Consolidation | Mirrors Carrefour and Ahold Delhaize supply agreement structures to secure fixed annual volumes with performance penalties. |
Research Approach
Document review covered EU regulatory filings, petrochemical trade data, and SEC disclosures from listed industrial packaging companies, complemented by interviews with plant managers at polyester converters, procurement leads at German automotive OEMs, distribution channel partners in the Benelux corridor, and technical R&D directors at adhesive formulation specialists. Secondary validation drew from customs records, Cefic chemical industry reports, and ASTM certification databases. Bottom-up volume modeling triangulated against top-down market sizing from feedstock capacity analysis.
Segment-level projections across product type, end user, material, and application dimensions were generated through elasticity modeling of substitution patterns between steel and synthetic formats throughout the forecast period. CAGRs were derived from regression analysis of historical price-volume relationships and forward-looking regulatory compliance cost trajectories. Key inputs included e-commerce fulfillment automation deployment rates, REACH chemical registration timelines, and extended producer responsibility fee schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU packaging waste regulation enforcement intensity and purified terephthalic acid supply disruptions from China's eastern seaboard. Model outputs reflect documented assumptions regarding substitution elasticity and automation penetration curves. A model refresh is warranted upon material change in EU national registry compliance deadlines or significant steel price volatility events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Shrink Packaging Market
Packaging Materials
Standard Liner Market
Packaging Materials
Asia-Pacific Solar Control Window Films Market
Packaging Materials
Refrigerator Door Seal Gaskets Market
Packaging Materials
Cardboard Trays Market
Packaging Materials
Cushion Case Liner Market
Packaging Materials
Transit Packaging Market
Packaging Materials
Tube Packaging Market
Packaging Materials
Africa Packaging Market
Packaging Materials
Strip Pack Laminates Market
Packaging Materials
Non-Plastic Punnets Market
Packaging Materials
US Packaging Market
Packaging Materials
Laminated Tubes Market
Packaging Materials
North America Stick Packaging Market
Packaging Materials
Corrugated Wrap Around Market
Packaging Materials
Cast Polypropylene (CPP) Films Market