
 Tabletop Tape Dispensers Market | 2026-2036
Tabletop Tape Dispensers Market Size, Share, and Industry Trends Forecast 2026-2036
Tabletop Tape Dispensers Market Analytics
E-commerce fulfillment centers are rotating toward automated packaging workflows, pulling demand from traditional office supply channels. 3M Company leverages its adhesive technology leadership to dominate premium electric dispenser segments. Tesa SE anchors European industrial demand through specialized solutions for automotive assembly lines. Intertape Polymer Group competes on manufacturing scale across North American distribution networks.
Tabletop tape dispensers are bench-mounted devices engineered to hold, cut, and feed adhesive tapes with blade mechanisms typically rated for 2-inch width capacity, serving commercial packaging and assembly operations. Manual dispensers retain the largest volume share due to low capital requirements and universal compatibility with standard tape rolls. Electric dispensers represent the fastest-growing category as manufacturing facilities automate repetitive sealing tasks. Metal-bodied units command higher margins in industrial settings where durability specifications exceed plastic alternatives.
FDA indirect food contact regulations and OSHA workplace safety standards govern material selection and blade guard design in US-sold equipment, while EU REACH compliance restricts hazardous substances in adhesive components and painted finishes. Germany's KBA and France's ANSM do not directly regulate this equipment class, though CE marking requirements under EU machinery directives establish baseline safety protocols for electric variants. Stakeholders must monitor evolving e-commerce packaging automation roadmaps and regional material compliance timelines to align product development with shifting procurement criteria.
Market Dynamics
E-commerce fulfillment centers are rotating toward automated packaging workflows, pulling demand from traditional office supply channels and compressing replacement cycles for manual dispenser units. This structural shift toward electric variants is reshaping procurement criteria across industrial and commercial buyer segments.
Growth Catalysts
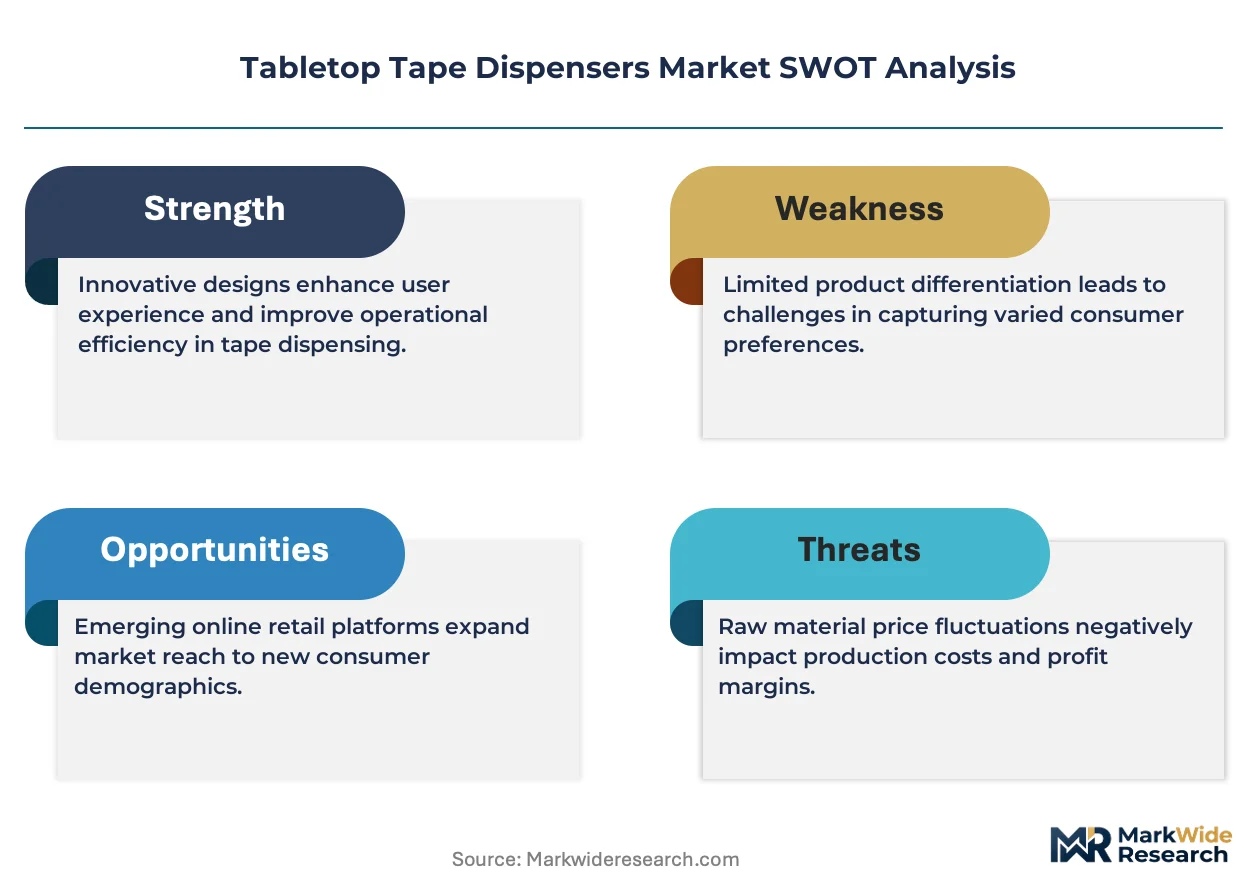
- EU REACH chemical safety frameworks:These regulations restrict hazardous substances in adhesive components and painted finishes, driving manufacturers toward compliant material formulations that command premium positioning in European industrial channels.
- Automotive assembly line automation:Precision sealing operations in Germany's manufacturing corridor require specialized tape application equipment with exact repeatability specifications.
- ISO 9001 quality management standards:Certification mandates across supply chains favor suppliers with documented quality systems, filtering smaller competitors from enterprise procurement lists.
Market Restraints
- Steel and aluminum input cost volatility:Metal-bodied units face margin pressure from commodity price swings that plastic alternatives largely avoid.
- Supply concentration in East Asian electronics:Electric dispenser motor and control module sourcing clusters in a narrow supplier base, creating single-source vulnerability.
- Substitution by adhesive dispensing systems:Liquid adhesive applicators are capturing segments of packaging automation where tape was previously standard.
Strategic Opportunities
- Underpenetrated Indian manufacturing sector:Domestic production incentives under India's PLI scheme are attracting packaging equipment investment as contract manufacturing expands.
- Convergence of IoT sensors with electric dispensers:Connected units enabling usage tracking and predictive maintenance are opening subscription revenue models.
- FDA indirect food contact regulations:Compliance-focused designs for food packaging applications create defensible positioning in US pharmaceutical and nutraceutical fulfillment.
Industry Challenges
- Integration complexity with legacy warehouse management systems:Electric dispenser deployment requires API development and staff retraining that delays rollout timelines.
- CE marking certification timeline compression:EU machinery directive compliance for electric variants demands extended testing cycles that strain product launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tabletop Tape Dispensers Market |
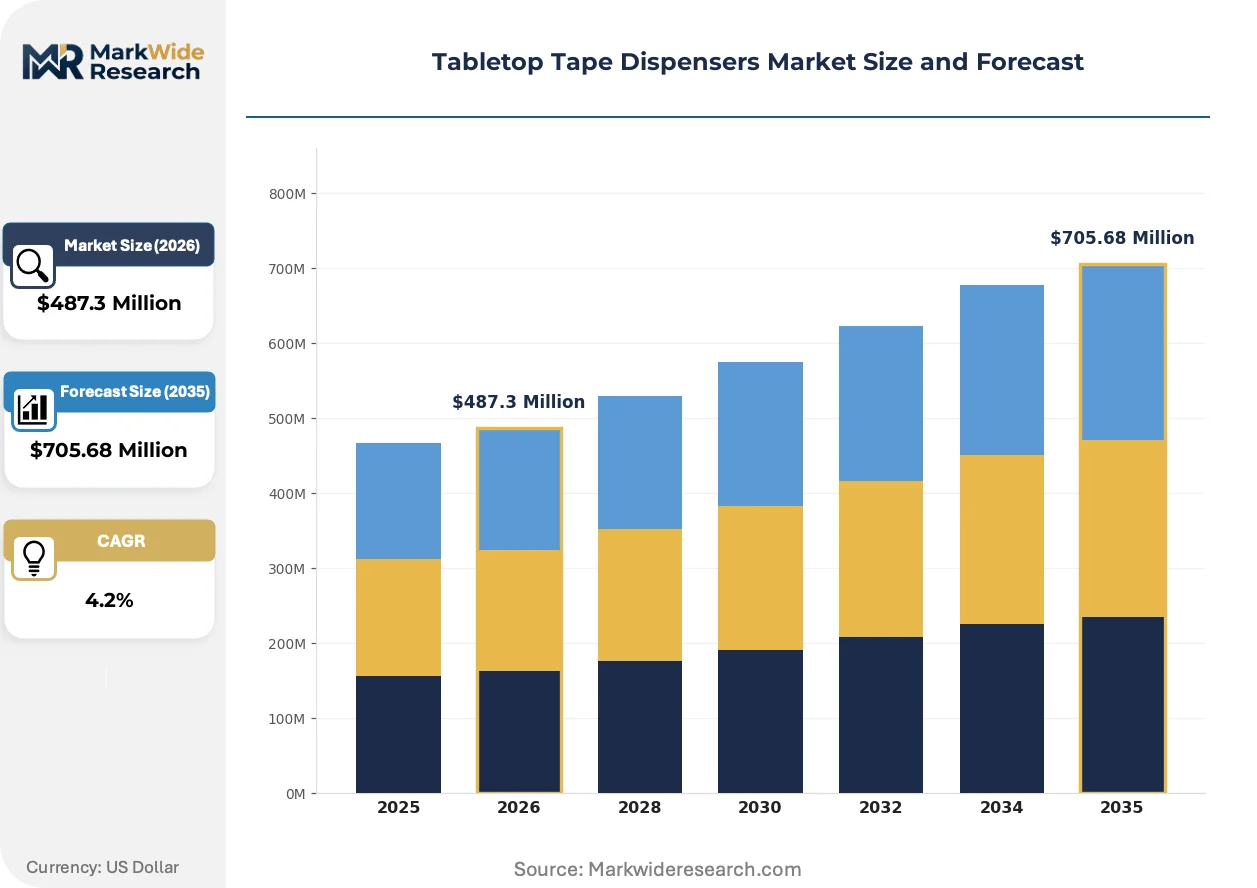
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $705.68 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Dispensers, Electric Dispensers, Desktop Units, Wall-Mounted Dispensers End User: Offices, Schools, Retail Stores, Manufacturing Facilities Size: Small, Medium, Large, Compact Material: Plastic, Metal, Wood, Composite |
| Companies Covered | 3M Company, Tesa SE, Intertape Polymer Group, Shurtape Technologies, Uline, Scotch Brand, Better Packages, Nichiban Co., Ltd., Officemate International Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tabletop Tape Dispensers Market Evolving Landscape
Active developments across materials science, regulatory compliance architecture, and procurement systems are fragmenting established competitive positions. Three vectors dominate current investment priorities.
Brushless DC motor technology is decomposing the cost-performance tradeoff that previously separated premium electric dispensers from economy manual units. Mid-sized fulfillment operators in the Netherlands and Belgium are adopting these systems at twice the pace of larger facilities, compressing the price umbrella that incumbent suppliers maintained across tiered product lines.
EU F-Gas Regulation restrictions on fluorinated greenhouse gases are forcing adhesive formulation changes that affect tape release properties and dispenser blade wear patterns. Industrial buyers in France and Italy are responding by specifying equipment warranties that explicitly cover performance under reformulated tape chemistries.
Buyer concentration among third-party logistics providers is consolidating procurement authority into fewer decision-makers with standardized equipment specifications. Regional distributors in Spain and Poland are losing shelf space to direct manufacturer relationships as volume contracts centralize through national purchasing cooperatives.
Tabletop Tape Dispensers Market Segmentation
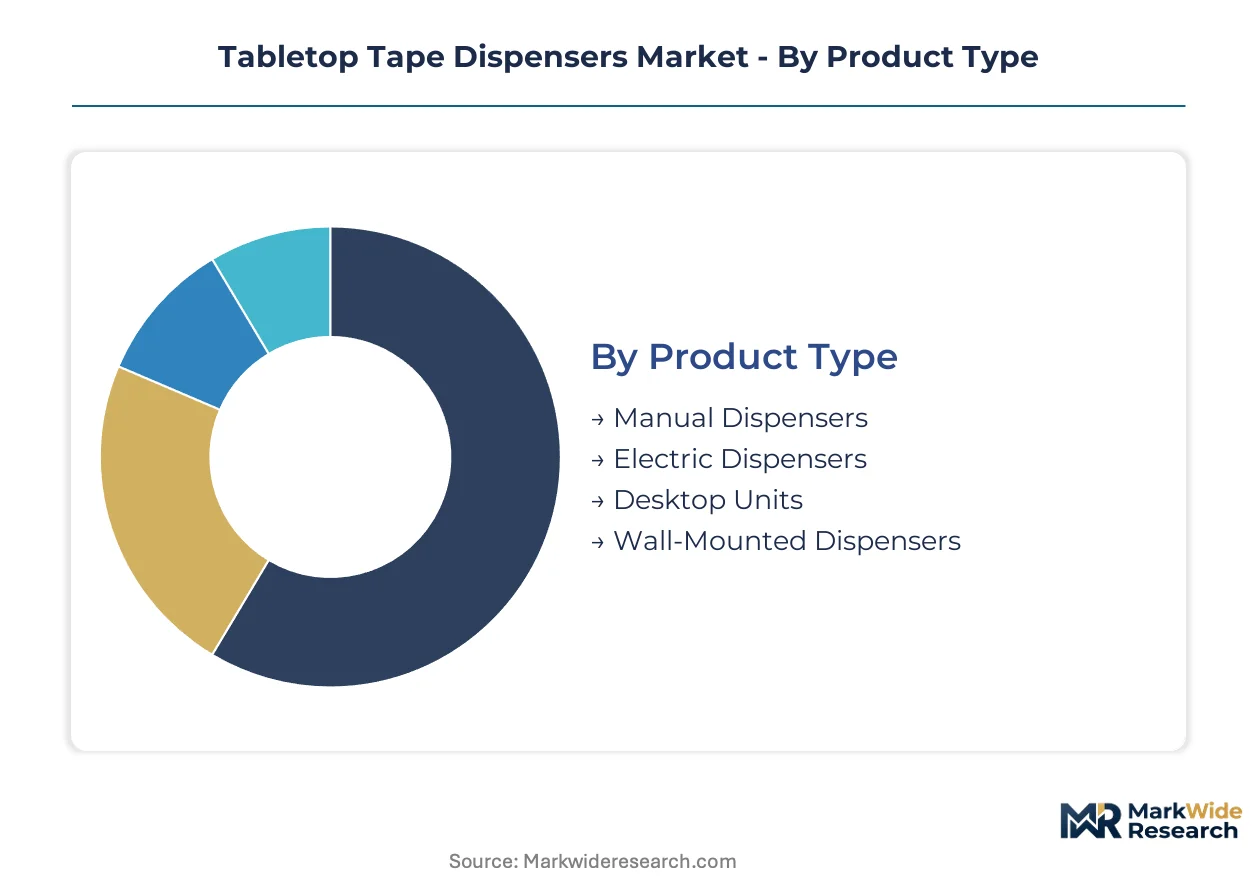
Segmentation in the tabletop tape dispenser market reveals how procurement authority splits between capital-constrained buyers seeking basic functionality and industrial operators demanding automation-ready equipment. Understanding these divides exposes where suppliers can defend margin pools against commoditization pressures.
Product Type:
Margin pools concentrate in electric variants where motor and control module integration creates technical barriers to entry that manual units cannot replicate.
- Manual Dispensers:Spring-loaded blade mechanisms with fixed tape roll capacity dominate procurement lists for small offices and educational institutions. Demand clusters in Germany's Mittelstand manufacturing belt where low-volume packaging stations prioritize capital efficiency over throughput.
- Electric Dispensers:Brushless DC motor systems with programmable feed lengths and sensor-activated cutting command premium positioning in e-commerce fulfillment centers. Netherlands and Belgium mid-sized operators are adopting these systems at accelerated rates, compressing the pricing umbrella incumbents maintained across tiered product lines.
- Desktop Units:Bench-anchored designs with weighted bases serve individual workstations in pharmaceutical packaging cleanrooms where FDA indirect food contact compliance is mandatory.
- Wall-Mounted Dispensers:Vertical installations with retractable tape arms optimize floor space in retail backrooms and hospital supply closets where footprint constraints override mobility requirements.
Manual dispensers hold installed capacity across legacy office supply channels. Electric dispensers are rotating up the share rankings as fulfillment automation roadmaps accelerate replacement cycles.
End User:
Application requirements fragment procurement specifications between environments prioritizing blade safety versus those demanding throughput repeatability.
- Offices:OSHA workplace safety standards govern blade guard design for US corporate procurement, favoring enclosed cutting mechanisms over exposed edges.
- Schools:Budget constraints and liability concerns drive demand for plastic-bodied units with rounded profiles and tamper-resistant blade housings.
- Retail Stores:High-frequency carton sealing at point-of-receipt positions requires durability specifications that metal-bodied units satisfy despite higher upfront cost.
- Manufacturing Facilities:ISO 9001 certification mandates filter supplier pools to documented quality systems, concentrating procurement authority among enterprise-grade vendors with traceable component sourcing.
Manufacturing facilities anchor premium segment revenue. E-commerce fulfillment centers are climbing fastest in procurement volume rankings.
Size:
Volume concentration sits with medium and large formats where standard 2-inch tape width compatibility aligns with industrial packaging norms.
- Small:Portable designs with 1-inch tape capacity serve mobile repair technicians and field service operations where kit weight minimization overrides cutting precision.
- Medium:Dual-roll capacity with adjustable blade spacing dominates commercial procurement in France and Italy, where reformulated adhesive chemistries under EU F-Gas Regulation are forcing equipment warranty renegotiations.
- Large:Heavy-duty frames accommodating 3-inch industrial tape widths anchor automotive assembly line installations in Germany's precision manufacturing corridor.
- Compact:Miniaturized mechanisms for drawer storage and personal workspaces capture residual demand in residential and home-office segments.
Medium formats hold the broadest installed base. Compact units are gaining share fastest as distributed work arrangements fragment centralized supply closets.
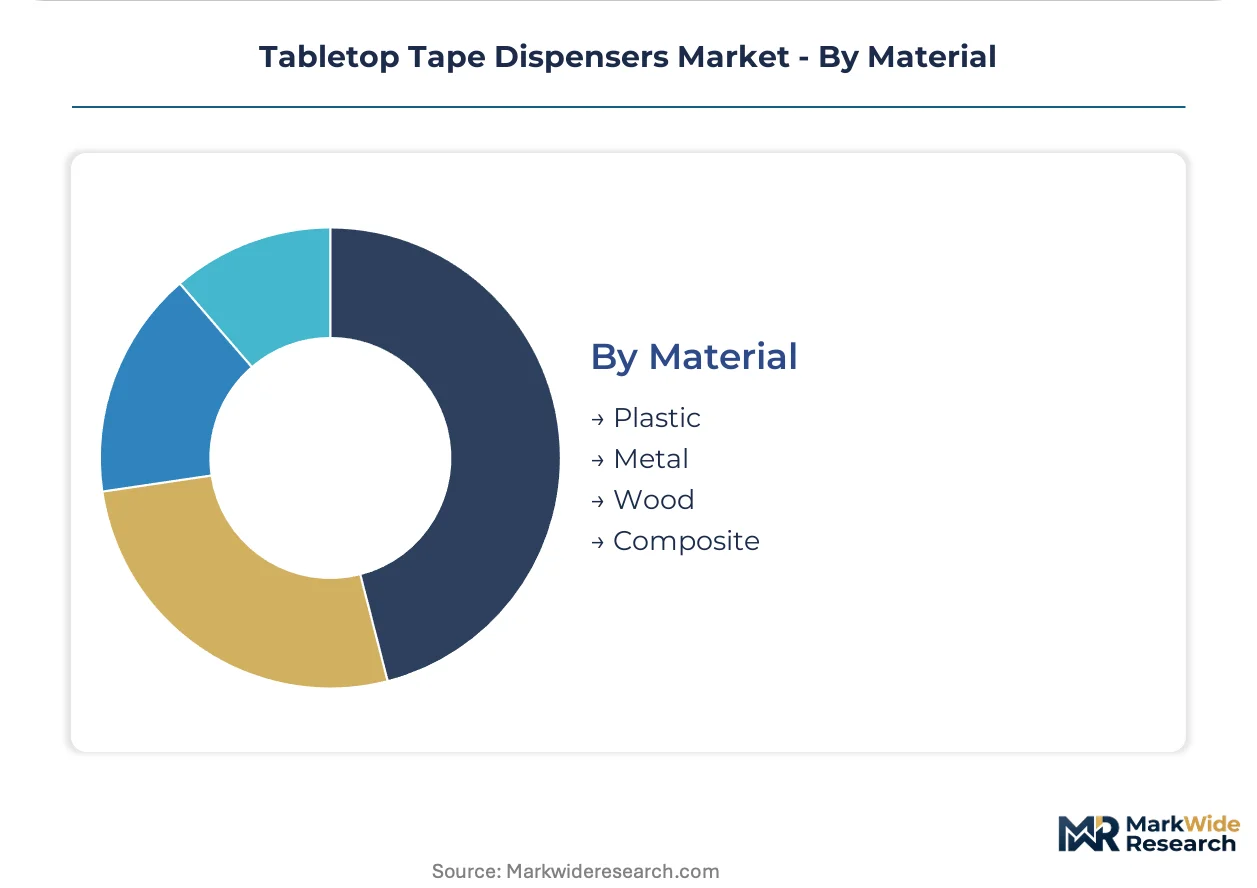
Material:
Cost tier separation between plastic and metal construction determines which suppliers can access industrial procurement lists with durability specifications.
- Plastic:Injection-molded ABS and polycarbonate formulations dominate high-volume production for price-sensitive channels, though steel and aluminum input cost volatility creates intermittent margin compression for metal alternatives.
- Metal:Steel and aluminum bodies with powder-coated finishes command 3-5 year lifecycle expectations in automotive and aerospace assembly environments where equipment replacement downtime carries penalty costs.
- Wood:Aesthetic-focused designs for executive office suites and hospitality settings where visual integration with furniture finishes overrides functional performance metrics.
- Composite:Fiber-reinforced polymer blends targeting weight reduction in portable field kits without sacrificing structural rigidity.
Metal construction anchors industrial margin pools. Composite materials are rotating up the technology rankings as formulation science advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export precision electric dispensers to automotive assembly plants across Poland and Czechia, establishing a north-south equipment corridor that channels premium industrial demand through Central European distribution nodes.
United States
OSHA workplace safety standards mandate blade guard specifications for corporate procurement, favoring enclosed cutting mechanisms in high-volume office supply channels. FDA indirect food contact regulations govern material selection for pharmaceutical packaging applications. E-commerce fulfillment clusters in Pennsylvania and Ohio are accelerating electric dispenser deployment as automated packaging workflows compress replacement cycles.
Germany
Automotive assembly line automation in Baden-Württemberg and Bavaria requires specialized tape application equipment with exact repeatability specifications. EU REACH chemical safety frameworks restrict hazardous substances in adhesive components, driving compliant material formulations. The Mittelstand manufacturing belt anchors demand for both precision electric units and capital-efficient manual dispensers across tiered procurement lists.
Netherlands
Mid-sized fulfillment operators adopt brushless DC motor systems at twice the pace of larger facilities, compressing price umbrellas incumbents maintained across product tiers. CE marking requirements under EU machinery directives establish baseline safety protocols for electric variants. Rotterdam's logistics corridor concentrates procurement authority among third-party logistics providers with standardized equipment specifications.
China
Domestic e-commerce platforms drive demand for cost-optimized electric dispensers in automated sorting facilities. GB standards and SAMR oversight shape equipment safety certification timelines. Yangtze River Delta manufacturing clusters supply motor and control modules to international dispenser assemblers, creating sourcing concentration vulnerability.
India
Domestic production incentives under the PLI scheme attract packaging equipment investment as contract manufacturing expands. BIS certification requirements filter supplier pools for enterprise procurement. Maharashtra and Gujarat industrial corridors concentrate demand from pharmaceutical packaging cleanrooms requiring FDA-aligned compliance specifications.
Tabletop Tape Dispensers Market Competitive Landscape
Listed leaders compete with private specialists across capital access and operational agility dimensions, producing a tiered structure where scale-driven incumbents defend position through manufacturing breadth while nimble specialists capture niche specifications. Three archetypes dominate: diversified adhesive conglomerates with captive dispenser divisions, pure-play equipment fabricators with regional manufacturing footprints, and private-label assemblers serving price-sensitive distribution channels. Competitive moves concentrate on strategic partnerships for IoT sensor integration and backward integration into brushless motor supply.
Among diversified adhesive conglomerates, 3M Company and Tesa SE exemplify the technology-leader archetype, anchoring premium electric dispenser segments through adhesive chemistry expertise and documented quality systems. Intertape Polymer Group occupies a position within the scale-driven tier, competing across North American distribution networks through manufacturing breadth. These three represent the competitive poles around which mid-sized specialists and regional fabricators organize their market positioning.
| Leading Market Players |
|---|
| 3M Company |
| Tesa SE |
| Intertape Polymer Group |
| Shurtape Technologies |
| Uline |
| Scotch Brand |
| Better Packages |
| Nichiban Co., Ltd. |
| Officemate International Corporation |
| Others |
Value Network & Pricing Analysis
Brushless DC motor adoption displaces brushed motor systems across mid-tier electric dispensers, simultaneously relocating component sourcing toward Yangtze River Delta manufacturing clusters and compressing price premiums that previously separated premium from standard equipment tiers. This substitution dynamic redraws procurement geography while eroding legacy supplier margin structures.
Pricing Analysis
Current-generation brushless DC systems, prior-generation brushed motor units, and emerging IoT-enabled connected dispensers define a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on motor efficiency ratings and CE marking certification tiers, with ISO 9001-documented quality systems commanding measurable premiums. Cost compression in economy manual tiers is intensifying because of commodity resin price volatility. Small offices and educational institutions exhibit highest price sensitivity; automotive assembly facilities show lowest.
Supply Chain Analysis
China, Germany, and the United States anchor distinct supply chain functions—China for motor and control module production, Germany for precision assembly equipment, and the United States for FDA-compliant pharmaceutical packaging variants. Raw material dependencies include rare earth magnet feeds for brushless motors, aluminum and steel for industrial-grade housings, and specialized adhesive formulations. Single-source vulnerability concentrates in East Asian electronics for motor controllers. Distribution runs through third-party logistics providers consolidating procurement authority into national purchasing cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of brushless motor integration expertise and predictive maintenance software capability filters supplier pools, concentrating contract awards among vendors with documented mechatronics competency.
For Market Incumbents: Fortify backward integration into brushless motor supply and captive adhesive formulation capacity to defend against liquid adhesive dispensing system substitution. Secure CE marking certification pipelines ahead of EU machinery directive enforcement waves. Channel control through direct relationships with third-party logistics cooperatives represents the critical defensive lever. For New Entrants and Emerging Players: Predictive maintenance service layers where incumbents under-serve open white-space targets for subscription revenue models. India's PLI scheme-attracted contract manufacturing expansion offers the most penetrable geography. Lead with IoT sensor integration as the specific go-to-market angle, positioning against legacy equipment replacement cycles. For Investors and Strategic Acquirers: The market sits at an automation-infusion phase that favors equipment-as-a-service archetypes over pure hardware vendors. Long-term viability hinges on recurring revenue attachment rates rather than unit shipment volumes. Acquisition targets should demonstrate documented quality systems and existing third-party logistics relationships. Monitor e-commerce fulfillment center automation roadmap announcements as the specific inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brushless Motor Supply | Captive motor production insulates margin structures from Yangtze River Delta sourcing concentration risk. |
| IoT Sensor Platform Development | Connected dispenser architectures enable predictive maintenance subscriptions that transform revenue models. |
| CE Marking Pre-Certification Investment | Accelerated EU machinery directive compliance compresses product launch timelines against competitors. |
| Direct 3PL Relationship Establishment | Bypassing regional distributors captures procurement authority consolidating into national cooperatives. |
| FDA Indirect Food Contact Compliance Design | Pharmaceutical packaging specifications create defensible positioning in US nutraceutical fulfillment channels. |
Research Methodology
Operator-level perspectives from packaging line engineers, third-party logistics procurement directors, automotive assembly maintenance managers, and adhesive formulation specialists anchored the qualitative base. Primary interview findings combined with secondary validation from SEC equipment manufacturer filings, EU machinery directive compliance databases, customs trade flow records, and e-commerce fulfillment automation investment disclosures. Bottom-up shipment estimates and top-down industrial equipment spend analysis provided triangulation across the analysis window.
Sensitivity analysis tested volume and value outputs against motor cost trajectory scenarios and regulatory timeline variations. Segmentation dimensions modeled include product type, end-user environment, size format, material construction, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to disclosed equipment procurement patterns and automation roadmap announcements. Brushless DC motor adoption curves and EU F-Gas Regulation compliance timelines served as industry-specific forecast inputs.
Forecasts assume regulatory continuity in EU REACH, FDA indirect food contact, and OSHA workplace safety regimes; material policy shifts would require re-modeling. Commodity price volatility in steel and aluminum inputs, plus single-source vulnerability in East Asian motor controller supply, represent specific revision triggers. Recalibration cycles align with material shifts in e-commerce automation investment and adhesive chemistry reformulation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
North America Packaging Tapes Market
Tapes
Nano Tapes Market
Tapes
Aerospace Tapes Market
Tapes
Strapping Tapes Market
Tapes
Thermal Release Tapes Market
Tapes
Sterilization Tape Market
Tapes
Tear Tape Dispenser Market
Tapes
Foil Tapes Market
Tapes
Mastic Tapes Market
Tapes
Galley Tapes Market
Tapes
Pre-Printed Tape Market
Tapes
Seam Tapes Market
Tapes
Heat Sealing Tape Market
Tapes
Double Sided Tape Market
Tapes
Correction Tapes Market
Tapes
Smart Card Tapes Market