
 Protein Packaging Market | 2026-2036
Protein Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Protein Packaging Market Outlook
Buyer concentration among e-commerce protein retailers is expanding as meal-kit platforms and direct-to-consumer meat brands aggregate order volumes. Amcor plc leverages global manufacturing scale to serve these consolidated accounts with customized high-barrier films. Mondi Group anchors European supply through integrated paper-based packaging solutions. Sealed Air differentiates via automated vacuum-sealing systems that reduce labor costs at protein processing plants.
Protein packaging encompasses engineered containment systems designed to preserve muscle-based and alternative protein integrity through controlled atmosphere, moisture regulation, and contamination prevention, typically employing multi-layer coextruded films with oxygen transmission rates below 5 cm³/m²/day to extend chilled shelf life. Flexible packaging dominates unit volume in poultry and seafood applications due to material efficiency and logistics optimization. Modified atmosphere packaging captures expanding margin pools in premium fresh meat segments where retailers demand case-ready presentation. Biodegradable materials represent the fastest-growing material trajectory as brand owners respond to corporate sustainability commitments.
The US FDA and USDA-FSIS jointly govern protein packaging through food contact substance notifications and hazard analysis mandates, while the EU F-Gas Regulation and REACH restrict certain barrier coatings and refrigerants used in cold-chain distribution. Compliance with these frameworks shapes material selection timelines and capital allocation for packaging converters. Stakeholders must monitor evolving extended producer responsibility schemes that will shift recycling infrastructure costs upstream to packaging suppliers.
Market Dynamics
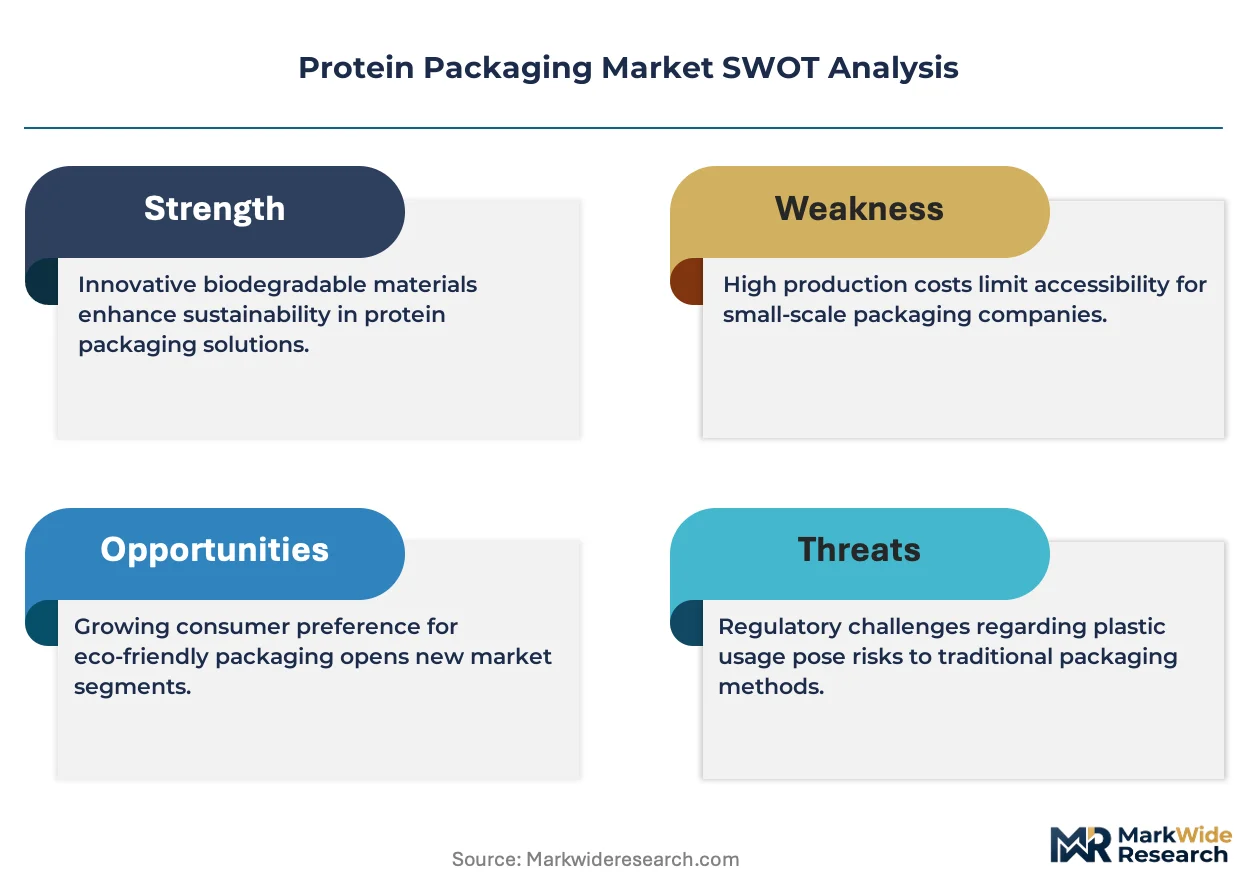
EU Packaging and Packaging Waste Regulation compliance deadlines are compressing material selection timelines for converters serving protein brands, forcing accelerated capital redeployment toward recyclable mono-material structures before mandate enforcement begins.
Growth Catalysts
- Plant-based protein expansion:Alternative meat brands require oxygen barrier properties equivalent to conventional films, pulling investment into bio-based coating technologies.
- REACH-compliant barrier coatings:Reformulated chemistries free of restricted fluorinated compounds unlock continued market access across EU member states.
- Meal-kit platform consolidation:Direct-to-consumer protein subscription services aggregate order volumes, justifying customized high-barrier film production runs.
Market Restraints
- Ethylene-vinyl alcohol resin volatility:EVOH supply concentrates among three petrochemical producers, exposing converters to input cost spikes.
- Multi-layer film incompatibility:Existing mechanical recycling infrastructure cannot separate polyamide from polyethylene streams, limiting circular economy claims.
- Cold-chain energy intensity:Refrigerated transport accounts for disproportionate carbon footprint in chilled meat distribution, inviting regulatory scrutiny.
Strategic Opportunities
- German chilled meat export corridor:Premium shelf-life extension demand from processors supplying Middle Eastern markets justifies advanced modified atmosphere packaging investment.
- Paper-based barrier convergence:Fiber substrates integrated with bio-polymer coatings capture sustainability-minded retail procurement specifications.
- Automated vacuum-sealing integration:Labor cost reduction at processing plants creates equipment-plus-consumables bundling potential.
Industry Challenges
- Migration testing protocols:Food contact substance notification timelines with FDA and USDA-FSIS extend new product commercialization by 12-18 months.
- Legacy extrusion asset retrofit:Existing coextrusion lines require substantial modification to process novel biodegradable resins at commercial throughput rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Protein Packaging Market |
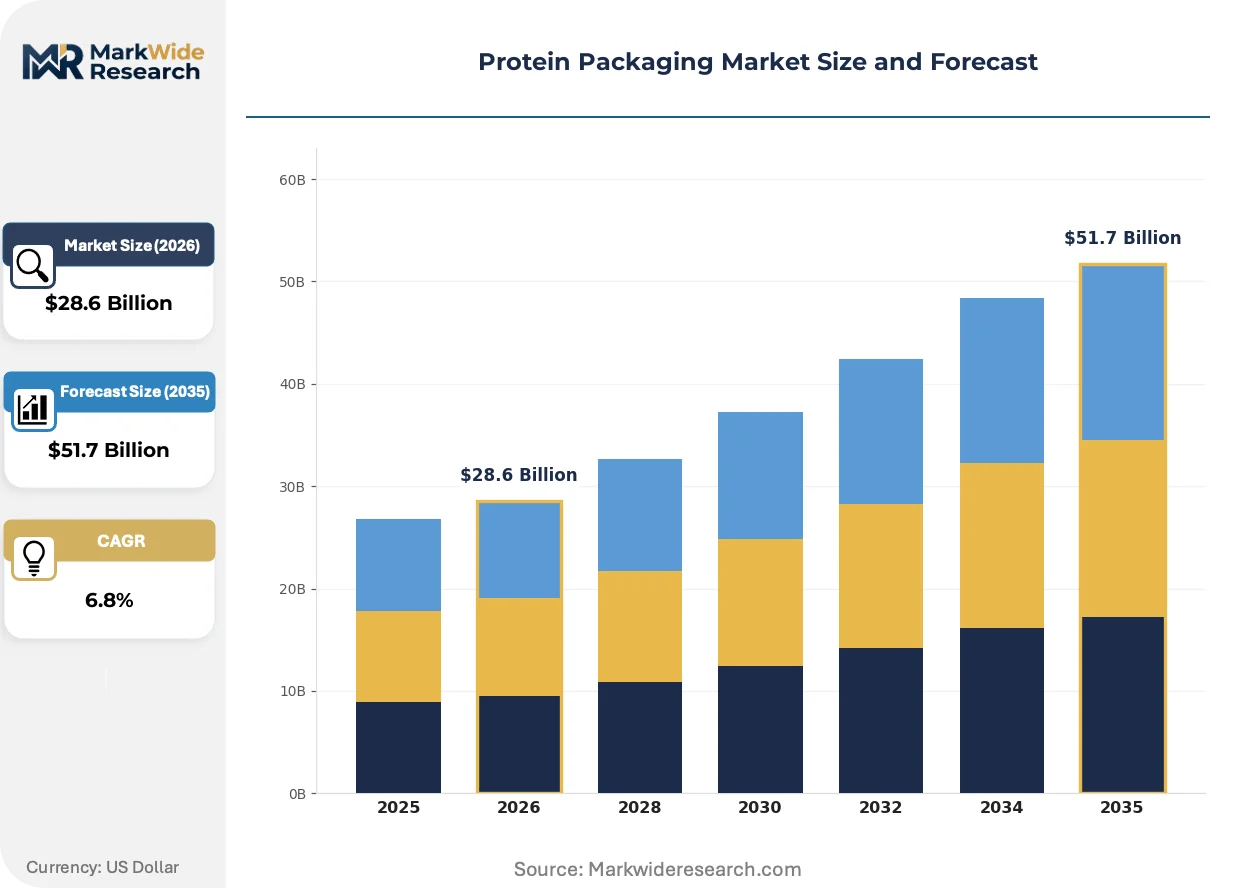
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Flexible Packaging, Rigid Packaging, Vacuum Packaging, Modified Atmosphere Packaging Material: Plastic, Paper, Metal, Biodegradable Materials End User: Retail, Food Service, Wholesale, E-commerce Application: Meat, Poultry, Seafood, Plant-Based Proteins |
| Companies Covered | Mondi Group, Tetra Pak International SA, Amcor plc, ProAmpac, Sealed Air, Berry Global Group, Constantia Flexibles, Smurfit Westrock, Sonoco Products Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Protein Packaging Market Strategic Shifts
Active packaging technologies and regulatory chemistry restrictions are converging to reshape material specifications across fresh and frozen protein segments. Converter R&D priorities reflect this dual pressure toward performance maintenance and environmental compliance.
Intelligent freshness indicators integrated directly into barrier films are electrifying quality assurance protocols for premium seafood distributors. Nordic retailers are piloting color-changing oxygen scavenger layers that eliminate separate sensor inserts. This convergence is compressing differentiation timelines for conventional passive packaging formats.
EU F-Gas Regulation phase-down schedules are eliminating hydrofluorocarbon refrigerants from cold-chain distribution networks. Protein logistics operators must retrofit transport refrigeration units with natural refrigerant alternatives or CO2 transcritical systems. Chilled beef exporters to Gulf Cooperation Council markets face the steepest compliance cost burden given journey duration requirements.
Retail procurement teams are consolidating supplier relationships around vertically integrated packaging converters offering design-to-recycling accountability. Direct sourcing agreements are displacing traditional distributor intermediaries in poultry and processed meat categories. German supermarket chains are most advanced in this transition, leveraging aggregated national volume for customized specification development.
Protein Packaging Market Segmentation
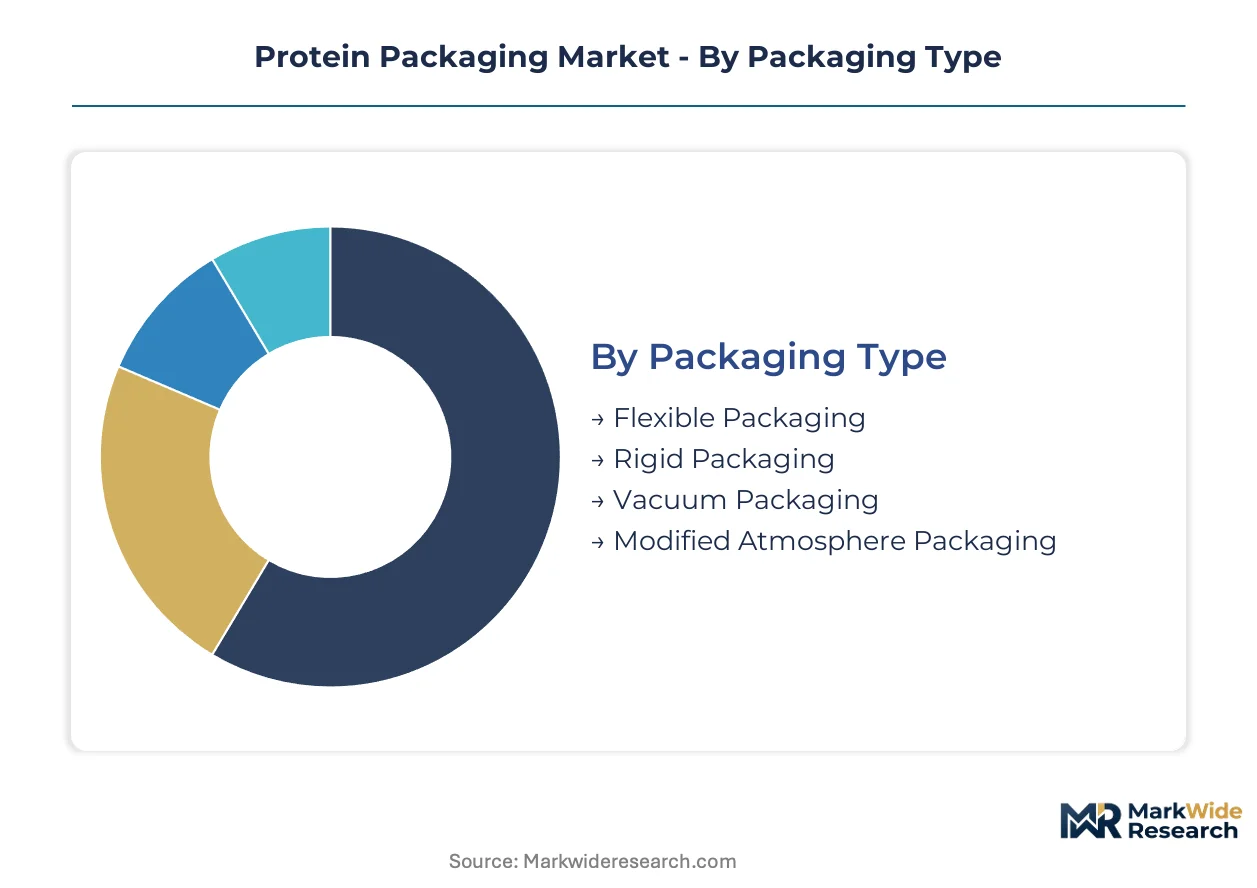
Protein packaging segmentation reflects divergent technical requirements across preservation intensity, material compliance, and distribution channel specifications. Converters configure asset deployment differently for each segment combination given incompatible barrier specifications and regulatory exposure profiles.
Packaging Type:
Standalone preservation systems operate independently of external equipment, while embedded formats require processing line integration and gas-flushing infrastructure.
- Flexible Packaging:Multi-layer coextruded films with oxygen transmission rates below 5 cm³/m²/day dominate poultry and seafood unit volumes. Demand concentrates in meal-kit platforms and direct-to-consumer meat brands where logistics optimization overrides rigid format protection.
- Modified Atmosphere Packaging:Gas-flushed tray-lid systems with residual oxygen below 0.5% capture premium fresh meat segments. German chilled meat exporters serving Middle Eastern markets drive specification intensity for extended shelf-life presentation.
- Vacuum Packaging:Thermoformed barrier webs with automated sealing integration reduce labor costs at protein processing plants. Sealed Air equipment-plus-consumables bundling dominates this embedded-system category.
- Rigid Packaging:Injection-molded or thermoformed containers with snap-fit closures serve prepared protein retail formats. Mondi Group integrated paper-based solutions are displacing conventional plastic trays in EU supermarket chains.
Volume placements concentrate in Flexible Packaging; the faster expansion belongs to Modified Atmosphere Packaging.
Material:
Cost tiers separate commodity petrochemical inputs from reformulated compliance-grade and certified biodegradable alternatives.
- Plastic:Polyethylene-polyamide-EVOH multilayers deliver barrier performance against moisture and oxygen ingress. EVOH supply concentration among three petrochemical producers exposes converters to input cost volatility.
- Biodegradable Materials:PLA and PHA resins with bio-polymer coatings capture sustainability procurement specifications from retail brand owners. EU Packaging and Packaging Waste Regulation deadlines compress material selection timelines toward recyclable mono-material structures.
- Paper:Fiber substrates with barrier coatings from Mondi Group anchor European supply for chilled meat applications. REACH-compliant coating reformulations free of fluorinated compounds unlock continued EU market access.
- Metal:Aluminum foil laminates and tinplate containers preserve shelf-stable protein formats. Cold-chain energy intensity concerns limit metal format expansion in fresh segments.
Plastic retains volume dominance; biodegradable materials are climbing the fastest.
End User:
Customer type determines order aggregation patterns and specification customization depth.
- Retail:Case-ready presentation requirements from supermarket chains drive modified atmosphere packaging specification intensity. German retailers are most advanced in direct sourcing agreements displacing distributor intermediaries.
- E-commerce:Direct-to-consumer protein subscription services aggregate order volumes justifying customized high-barrier film production runs. Amcor plc global manufacturing scale serves these consolidated accounts.
- Food Service:Bulk portioning and institutional distribution favor cost-optimized flexible formats with standard barrier specifications.
- Wholesale:Intermediate distribution tiers face margin compression as retail procurement consolidation eliminates traditional channel roles.
Retail commands absolute volume; e-commerce is gaining share fastest.
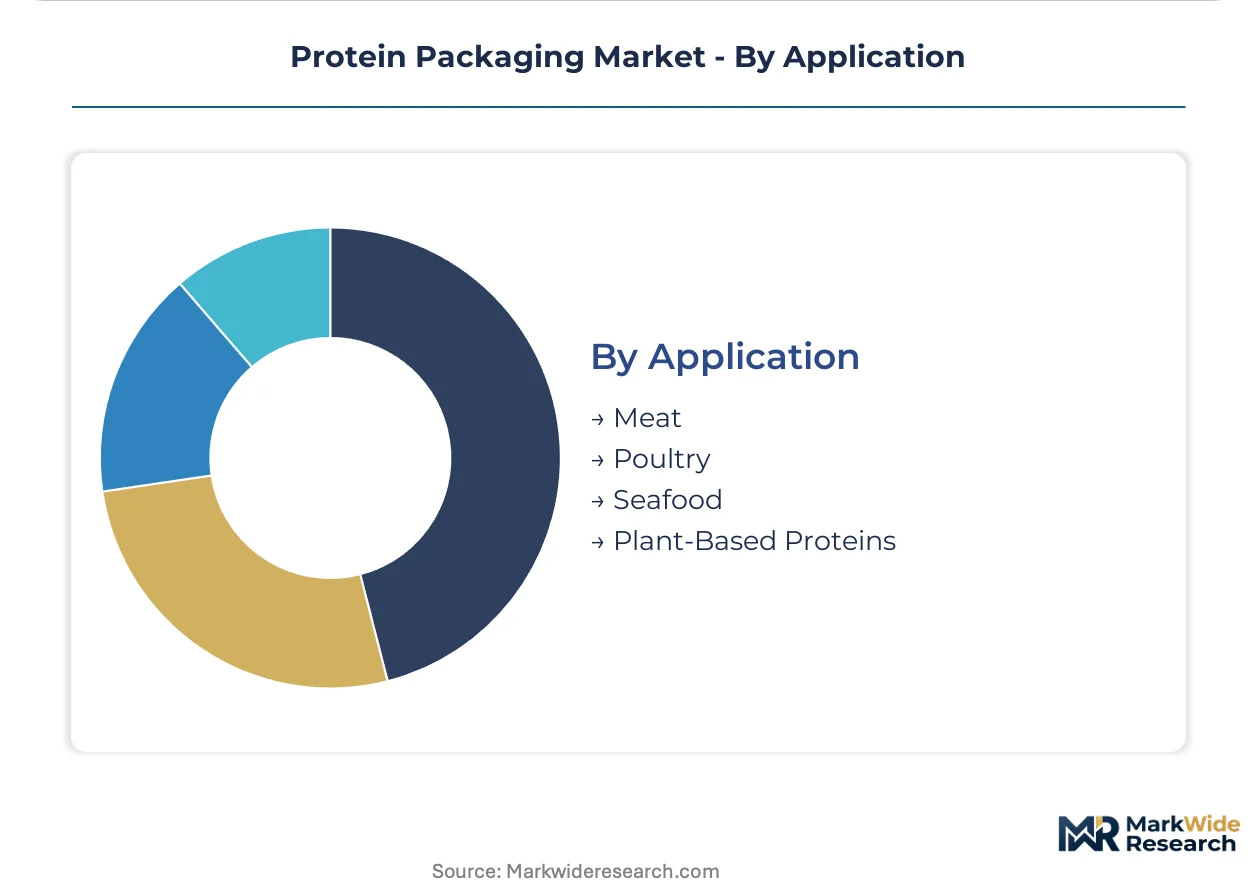
Application:
Protein source chemistry dictates barrier specification intensity and regulatory scrutiny exposure.
- Meat:Chilled beef and pork require oxygen exclusion and carbon dioxide flushing to control microbial spoilage. USDA-FSIS hazard analysis mandates shape material selection timelines for domestic US processors.
- Seafood:Premium distributors deploy intelligent freshness indicators integrated directly into barrier films. Nordic retailers pilot color-changing oxygen scavenger layers eliminating separate sensor inserts.
- Poultry:High unit volume and standardized cuts favor flexible packaging material efficiency. FDA food contact substance notifications extend new product commercialization timelines.
- Plant-Based Proteins:Alternative meat brands require oxygen barrier properties equivalent to conventional films, pulling converter R&D investment into bio-based coating technologies.
Meat anchors volume placement; plant-based proteins show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Protein packaging demand clusters in Germany, where chilled meat exporters drive specification intensity for extended shelf-life formats. The EU Packaging and Packaging Waste Regulation compresses material selection timelines across member states. Brand owners in multiple geographies are consolidating supplier relationships around vertically integrated converters.
United States
Meal-kit platforms and direct-to-consumer meat brands aggregate order volumes, justifying customized high-barrier film production runs. FDA and USDA-FSIS joint oversight through food contact substance notifications and hazard analysis mandates shapes material selection timelines. Chicago-area protein processing clusters deploy automated vacuum-sealing systems to reduce labor costs at plant level.
Germany
Premium chilled beef and pork exports to Middle Eastern markets require advanced modified atmosphere packaging with residual oxygen below 0.5%. REACH-compliant barrier coating reformulations free of fluorinated compounds unlock continued EU market access. The Bavarian meat processing corridor anchors specification development for case-ready retail presentation formats.
China
Domestic cold-chain infrastructure expansion supports chilled poultry and seafood distribution to tier-one cities. SAMR food contact material standards and GB compliance frameworks govern packaging converter qualification. Yangtze River Delta packaging clusters integrate intelligent freshness indicators for premium seafood distributors serving high-end retail.
Netherlands
Rotterdam port logistics and EU distribution hub status concentrate protein re-export packaging demand. ECHA chemical restriction enforcement through REACH shapes coating chemistry selection for converters serving pan-European brands. Randstad-based integrated paper-based packaging specialists capture sustainability procurement specifications from supermarket chains.
Saudi Arabia
Gulf Cooperation Council chilled beef import demand from European exporters drives premium shelf-life extension requirements. SFDA food contact regulations align with Gulf standardization initiatives for packaging material safety. Jeddah and Riyadh cold-chain logistics hubs require retrofit of transport refrigeration units to comply with EU F-Gas Regulation phase-down schedules for natural refrigerant alternatives.
Protein Packaging Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue bio-based coating technologies and paper-based barrier convergence. The vendor base spans multinational converters with global manufacturing scale, European-anchored integrated fiber specialists, and equipment-plus-consumables bundling operators. Three archetypes dominate: scale-driven film suppliers, sustainability-focused substrate innovators, and automated system integrators. Competitive moves concentrate on capacity redeployment toward recyclable mono-material structures and strategic partnerships with meal-kit platforms.
Among European-based integrated packaging specialists, Mondi Group and Smurfit Westrock occupy positions exemplifying the fiber substrate convergence archetype. Amcor plc represents the scale-driven global manufacturing tier with customized production capability for consolidated e-commerce accounts. Sealed Air sits within the equipment-integrated consumables segment, anchoring automated vacuum-sealing bundling strategies for protein processing plant labor cost reduction.
| Leading Market Players |
|---|
| Mondi Group |
| Tetra Pak International SA |
| Amcor plc |
| ProAmpac |
| Sealed Air |
| Berry Global Group |
| Constantia Flexibles |
| Smurfit Westrock |
| Sonoco Products Company |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up packaging specialists have consolidated European converter assets, tightening supply discipline while extracting pricing power through volume commitments to meal-kit aggregators and supermarket procurement teams. This ownership pattern concentrates bargaining leverage against petrochemical feedstock suppliers and anchors contract structures that penalize spot-market volatility.
Pricing Analysis
Volume placements in flexible poultry films run at compressed margins, while modified atmosphere packaging for German chilled beef exports commands premium pricing tied to residual oxygen specifications below 0.5%. Three-tier pricing structure across premium, standard, and economy levels separates EVOH-reinforced barrier grades from mono-material recyclable alternatives and commodity polyethylene formats. Pricing pressure stems from EVOH resin concentration among three petrochemical producers, which exposes converters to input cost spikes. E-commerce protein subscription services show lowest price sensitivity due to bundled logistics optimization, whereas wholesale intermediaries face margin compression from direct retail sourcing.
Supply Chain Analysis
EU Packaging and Packaging Waste Regulation domestic-content mandates are reshaping sourcing toward recyclable mono-material structures produced within member states, displacing multi-layer imports. Raw material supply concentrates in Germany, the Netherlands, and Belgium for barrier coating formulation, with EVOH resin dependency on petrochemical producers in Asia and the Middle East. Supply chain risk centers on single-source vulnerability for oxygen-scavenger chemistries subject to REACH restriction. Distribution runs through vertically integrated converters offering design-to-recycling accountability, eliminating traditional distributor tiers in poultry and processed meat categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The protein packaging market has become a vertical-integration race, with players pursuing captive supply of bio-based coating technologies to secure differentiation as regulatory chemistry restrictions tighten.
For Market Incumbents: Extend equipment-plus-consumables bundling strategies into automated vacuum-sealing integration, capturing labor cost reduction budgets at protein processing plants. Anchor European supply positions through backward integration into paper-based barrier substrate production before REACH-compliant coating reformulations consolidate around fiber specialists. Threat exposure from plant-based protein brands pulling R&D investment into bio-based alternatives demands accelerated mono-material recyclable capacity deployment. For New Entrants and Emerging Players: EU F-Gas Regulation phase-down schedules in Germany and the Netherlands open a window for natural refrigerant alternative packaging logistics partnerships with chilled beef exporters serving Gulf Cooperation Council markets. Target paper-based barrier convergence specifications from sustainability-minded retail procurement teams in German supermarket chains. Go-to-market angle: pilot intelligent freshness indicator integration for premium seafood distributors in Nordic retail networks. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap converters with stranded multi-layer extrusion assets in Bavaria and the Randstad region, where EU mandate enforcement will force capital redeployment. Long-term viability hinges on recyclable mono-material process capability and direct sourcing relationships with consolidated e-commerce accounts. Signal to watch: meal-kit platform procurement consolidation triggering customized high-barrier film contract reassignments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Coating Production | Captures REACH-compliant chemistry supply as fluorinated compound restrictions eliminate incumbent coating suppliers from EU market access. |
| Automated Vacuum-Sealing Equipment Bundling | Locks in consumables volume through Sealed Air-style labor cost reduction contracts at Chicago-area protein processing clusters. |
| Recyclable Mono-Material Capacity Expansion | Aligns asset deployment with EU Packaging and Packaging Waste Regulation enforcement timelines across member states. |
| Direct Sourcing Agreement with Meal-Kit Platforms | Displaces distributor intermediaries by aggregating order volumes for customized high-barrier film production runs. |
| Intelligent Freshness Indicator Integration | Differentiates barrier films for Nordic retailers piloting color-changing oxygen scavenger layers in premium seafood segments. |
Study Parameters
Multi-period observation of EVOH resin pricing volatility, EU regulatory enforcement timelines, and retail procurement consolidation patterns anchored the trend analysis, supplemented by interviews with packaging converter plant managers, supermarket category buyers, protein processing procurement leads, and regulatory affairs directors at barrier coating suppliers. Secondary validation drew from EU Packaging and Packaging Waste Regulation filing databases, ECHA chemical restriction announcements, SEC 10-K disclosures by listed packaging converters, and customs trade data for multilayer film imports. Bottom-up segment sizing triangulated against top-down market value estimates derived from petrochemical feedstock consumption patterns.
Segment-weighting approaches distributed value across packaging type, material compliance tier, and end-user channel specifications, with additional dimensioning by protein source chemistry and regional cold-chain infrastructure maturity. CAGRs were derived from elasticity modeling of substitution effects between conventional multi-layer films and emerging biodegradable alternatives, calibrated against historical adoption curves for REACH-compliant coating reformulations. Forecast inputs incorporated meal-kit platform order aggregation trajectories and German chilled meat export corridor volume projections.
The model assumes a particular technology adoption path for bio-based barrier coatings; alternative pathways involving accelerated PHA resin commercialization would alter the outlook for biodegradable material segment expansion. Forecasts reflect assumptions regarding EU mandate enforcement consistency, EVOH supply concentration stability, and cold-chain energy intensity regulatory scrutiny intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Face Stock Films Market
Packaging Materials
Absorbent Tray Liners Market
Packaging Materials
Microwave Packaging Market
Packaging Materials
Cupcake Wrappers Market
Packaging Materials
Spices, Dry Mixes and Extracts Packaging Market
Packaging Materials
Gift Wrapping Product Market
Packaging Materials
Thermoformed Tubs Market
Packaging Materials
Book Wraps Market
Packaging Materials
Sealed Wax Packaging Market
Packaging Materials
Insulated Box Liner Market
Packaging Materials
Reel in Box Market
Packaging Materials
Cutting Tool Packaging Market
Packaging Materials
Asia-Pacific Solar Control Window Films Market
Packaging Materials
Europe Airless Packaging Market
Packaging Materials
Global Anti-Static Films Market
Packaging Materials
Stick Packaging Market