
 Non-Breathable Films Market | 2026-2036
Non-Breathable Films Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Breathable Films Market Outlook
China is tilting toward expanded polyethylene film capacity to serve domestic food packaging and export demand. Berry Global leverages vertical integration across resin conversion and finished film to sustain margin control in North America. Amcor Limited anchors Asia-Pacific supply through regional manufacturing scale, while Toray Plastics (America) specializes in high-barrier nylon films for medical and electronics end users.
Non-breathable films are impermeable polymer barriers engineered to block moisture vapor and gas transmission, typically manufactured through cast or blown extrusion with thickness precision below 50 microns for critical barrier applications. Polyethylene dominates volume across food Industry packaging where oxygen exclusion extends product shelf life, while polypropylene captures premium positioning in pharmaceutical blister packs demanding thermal stability and optical clarity. PVC retains niche medical applications despite regulatory pressure, and nylon films command the highest unit margins in electronics moisture-barrier segments.
US FDA food-contact regulations and EPA emissions standards shape resin selection and extrusion plant compliance costs, while Europe's REACH chemical restrictions and MDR medical device rules filter market access for non-breathable film suppliers. China's GB standards and MIIT industrial policy direct domestic capacity investments toward import substitution. Stakeholders must monitor evolving packaging waste directives across these jurisdictions to anticipate material substitution risks and certification requirements.
Market Dynamics
Food Industry shelf-life extension mandates are compressing specification windows for oxygen and moisture vapor transmission rates, forcing resin suppliers and converters to synchronize qualification cycles with multinational brand owners.
Growth Catalysts
- REACH chemical restrictions:Europe's tightening substance authorization protocols are filtering out legacy plasticizers and stabilizers, creating certified-supplier premiums for compliant film manufacturers.
- Blown film coextrusion advances:Nine-layer and eleven-layer die technologies enable nanometer-grade barrier layer distribution, unlocking medical and electronics applications previously reserved for metalized substrates.
- India packaging demand:Domestic food processing expansion and cold chain infrastructure buildout are concentrating procurement volumes with local film converters.
Market Restraints
- Ethylene feedstock volatility:Crude oil and naphtha price swings transmit directly to polyethylene film margins, compressing converter profitability during upstream spikes.
- China capacity concentration:Blown and cast film additions along the eastern seaboard are creating export surplus conditions that pressure pricing in Southeast Asian and Middle Eastern markets.
- Mechanical recycling incompatibility:Multi-layer barrier constructions resist conventional reprocessing, exposing producers to extended producer responsibility levies under emerging packaging waste frameworks.
Strategic Opportunities
- Brazil food export packaging:Agricultural commodity processors require high-barrier formats for meat and grain shipments, with domestic film supply gaps creating import substitution openings.
- Digital printing convergence:Electron beam and UV inkjet systems enable short-run customization without plate costs, collapsing minimum order quantities for regional brand owners.
- EU Green Deal packaging mandates:Recycled content thresholds and design-for-recycling standards are accelerating qualification of chemically recycled and bio-based barrier resins.
Industry Challenges
- Multi-layer extrusion technician scarcity:Die gap calibration and layer ratio optimization require specialized expertise that outpaces vocational training pipeline output.
- Medical device certification timelines:FDA and MDR biocompatibility documentation cycles extend 18-24 months, freezing formulation changes and locking suppliers into legacy resin approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Breathable Films Market |
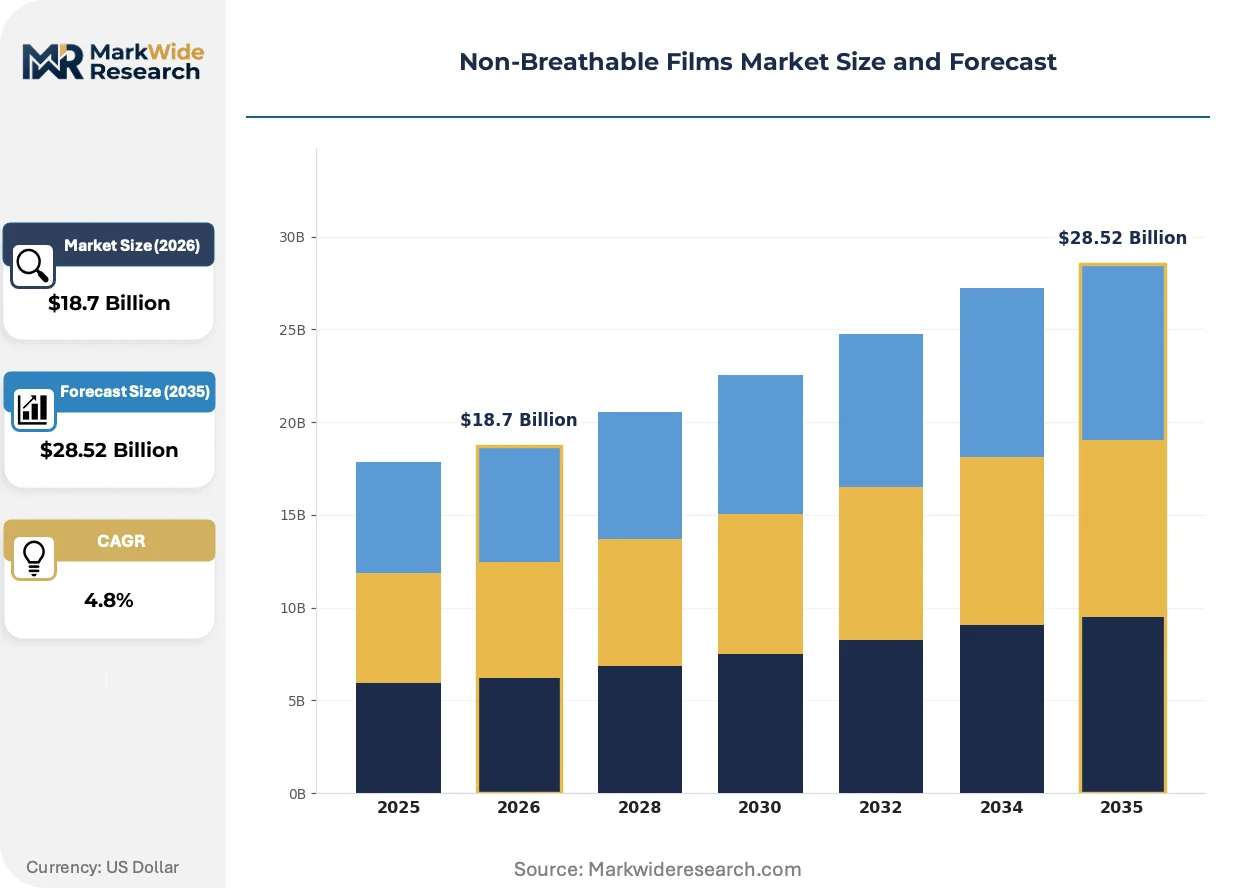
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, PVC, Nylon Application: Packaging, Agriculture, Medical, Construction End User: Food Industry, Pharmaceuticals, Textiles, Electronics Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | Berry Global, Inc., Uflex Ltd., Jindal Poly Films Limited, RKW Group, Polyplex Corporation Ltd., Winpak Ltd., Bischof + Klein SE & Co. KG, Toray Plastics (America), Inc., Amcor Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Breathable Films Market Strategic Shifts
Barrier performance specifications are tightening faster than conventional material science can accommodate, opening entry points for alternative substrate technologies and process innovations.
Atomic layer deposition (ALD) of aluminum oxide onto polymer webs delivers gas barrier performance approaching metalized films at sub-micron coating thicknesses. Medical device and organic electronics manufacturers are qualifying ALD-coated polyethylene terephthalate for hermetic packaging applications. Vapor-phase deposition is rendering obsolete thick aluminum metallization layers that add weight and complicate microwave compatibility.
Europe's F-Gas Regulation is phasing down hydrofluorocarbon blowing agents used in certain foam and film production processes. Extrusion equipment suppliers are retrofitting lines for hydrocarbon and carbon dioxide alternatives, adding capital recovery burdens to converter balance sheets. Medical and cold-chain packaging segments face the steepest reformulation timelines given stringent thermal performance requirements.
Brand owner sustainability scorecards now weight recyclability and recycled content above unit cost in supplier selection criteria. Major food and personal care manufacturers are consolidating film procurement with converters offering mass-balance certified resins and design-for-recycling documentation. This preference shift is most visible in Western European markets where extended producer responsibility fees create direct cost linkage to end-of-life packaging outcomes.
Non-Breathable Films Market Segmentation
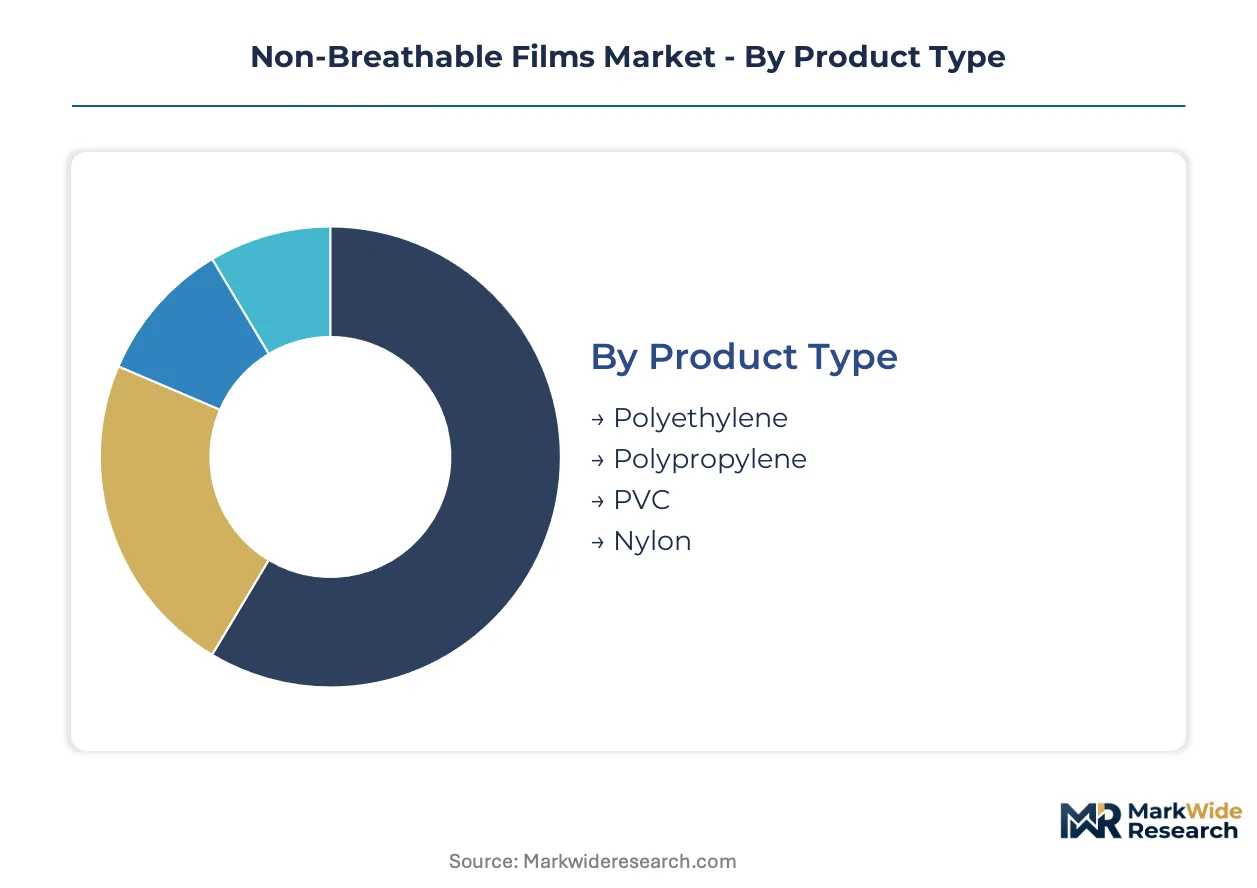
Non-breathable films serve divergent performance requirements across moisture-sensitive applications, from oxygen-exclusion food packaging to hermetic medical device barriers. Segmentation reveals how material selection, channel configuration, and end-use specifications create distinct competitive arenas with unique margin profiles and qualification cycles.
Product Type:
Film chemistry determines barrier performance, thermal stability, and regulatory compliance burden across the use-case spectrum.
- Polyethylene:Blown and cast extrusion formats dominate food Industry volume, with linear low-density grades offering moisture vapor transmission rates below 0.5 g/m²/day. India's Uflex and Jindal Poly Films anchor domestic supply chains for flexible laminates serving processed food exporters.
- Polypropylene:Biaxially oriented films deliver thermal stability and optical clarity for pharmaceutical blister packs. FDA and EMA drug master file requirements lock converters into lengthy resin qualification protocols that freeze formulation choices for 18-24 month cycles.
- PVC:Calendered and extruded formats retain niche medical tubing and IV bag applications despite REACH plasticizer restrictions and EPA emissions scrutiny.
- Nylon:Coextruded and metallized nylon films command premium positioning in electronics moisture-barrier packaging for semiconductor and display manufacturers.
The dominant share belongs to Polyethylene, while Nylon is closing the gap fastest on unit margin expansion.
Application:
Specification intensity varies sharply by application, with medical and electronics segments demanding nanometer-grade barrier precision that agricultural and construction films rarely require.
- Packaging:Multi-layer coextrusion and ALD-coated substrates serve shelf-life extension mandates for meat, dairy, and snack foods. Europe's packaging waste directives are forcing design-for-recycling redesigns that complicate legacy barrier constructions.
- Medical:Sterile barrier systems for implants and drug-device combinations require ISO 11607 compliance and MDR technical documentation. Toray Plastics anchors North American supply of high-barrier nylon for this segment.
- Agriculture:Greenhouse cladding and silage wrap films prioritize UV stabilization and tear resistance over gas barrier performance, opening the segment to commodity polyethylene producers.
- Construction:Vapor retarders and under-slab moisture barriers use reinforced polyethylene and polypropylene scrims, with building code adoption driving regional demand concentration.
Packaging retains volume leadership, though Medical is expanding most quickly on regulatory-driven specification upgrades.
End User:
Procurement patterns diverge between price-sensitive commodity buyers and specification-locked premium segments with extended qualification timelines.
- Food Industry:Extended shelf-life mandates compress oxygen transmission rate specifications, forcing converters to synchronize resin qualification with multinational brand owner R&D cycles. Berry Global's vertical integration across resin conversion sustains margin control in this segment.
- Pharmaceuticals:Blister packs, cold-form foils, and sachet laminates demand thermal stability and child-resistance compliance. Amcor Limited leverages Asia-Pacific manufacturing scale to serve regional drug packaging demand.
- Electronics:Organic photovoltaics and flexible circuit manufacturers qualify ALD-coated films for hermetic packaging that blocks moisture ingress during reflow soldering.
- Textiles:Synthetic leather backing and protective garment membranes use breathable-non-breathable film laminates with polyurethane or polyethylene cores.
Food Industry commands the largest procurement volumes, while Electronics is gaining share fastest on ALD coating adoption.
Distribution Channel:
Channel selection reflects order scale, customization requirements, and the buyer's technical specification capability.
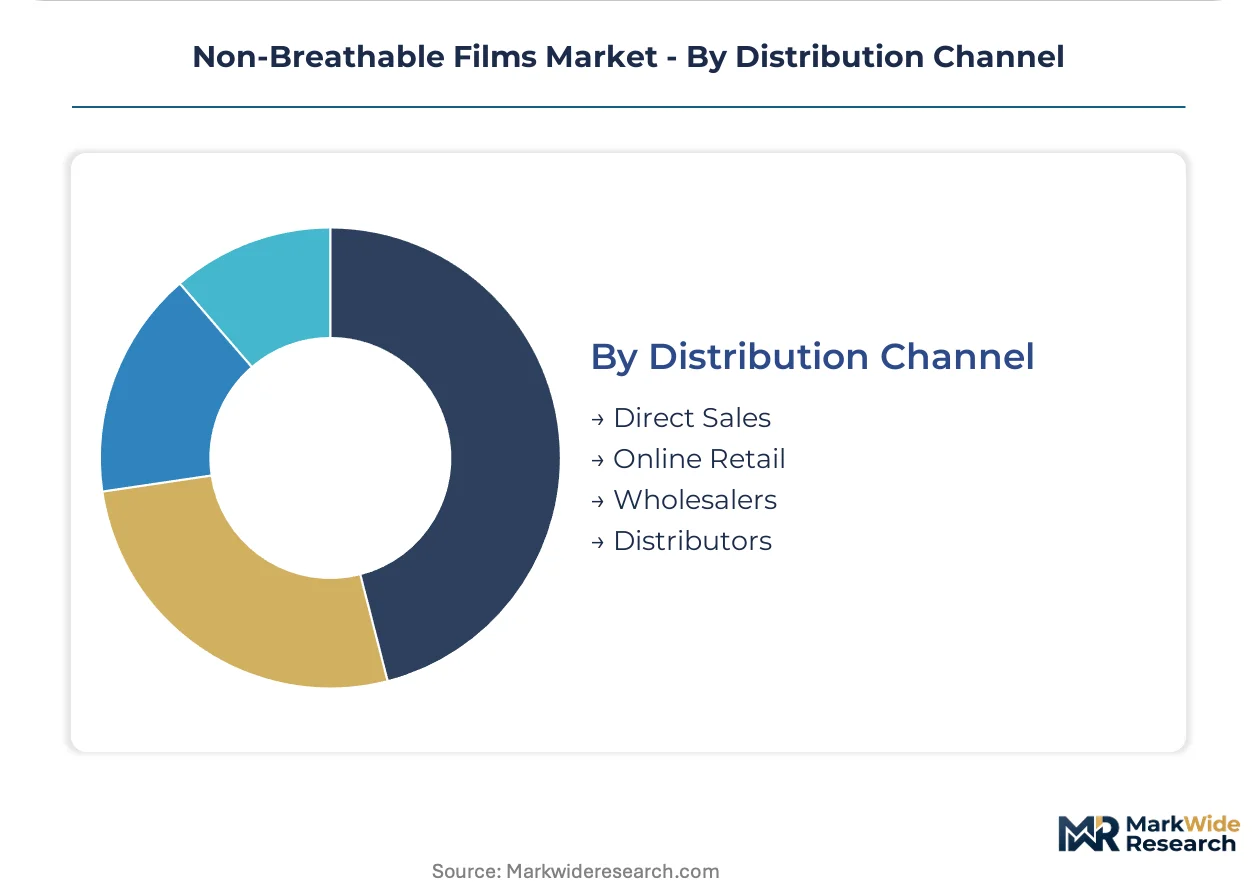
- Direct Sales:Converters and brand owners with dedicated packaging engineers negotiate multi-year supply agreements specifying resin grades, barrier performance, and sustainability certifications. Digital printing convergence enables short-run customization without plate costs.
- Distributors:Regional film distributors stock standard gauges for mid-tier food processors and agricultural users, offering technical support and just-in-time delivery that direct mill relationships rarely match.
- Wholesalers:Volume aggregation for commodity polyethylene sheeting and construction-grade vapor barriers serves price-sensitive contractors and small-scale greenhouse operators.
- Online Retail:E-commerce platforms capture prototype and R&D quantities for medical device startups and electronics manufacturers qualifying new barrier formats.
Direct Sales holds the dominant channel position, though Online Retail is climbing the fastest on digital procurement platform expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical tanker throughput anchors Europe's polymer resin distribution to film converters serving pharmaceutical and food packaging demand.
United States
Gulf Coast ethane crackers feed polyethylene film plants across Texas and Louisiana with cost-advantaged feedstock. EPA emissions standards and FDA food-contact regulations shape resin selection and extrusion plant compliance investments. Berry Global operates integrated resin-to-film capacity across multiple Midwest and Southeast locations.
Germany
Automotive and medical device clusters in Baden-Württemberg and Bavaria drive demand for high-barrier nylon and coextruded films. REACH chemical restrictions and MDR medical device rules filter market access for imported film suppliers. The Rhine-Main industrial corridor concentrates blown film conversion capacity serving Central European pharmaceutical packaging.
China
Domestic food processing expansion and export packaging demand absorb polyethylene film additions along the eastern seaboard. MIIT industrial policy and GB standards direct capacity investments toward import substitution in barrier film grades. The Yangtze River Delta hosts the densest concentration of cast and blown film lines serving electronics and consumer goods exporters.
India
Cold chain infrastructure buildout and processed food sector growth concentrate procurement volumes with domestic converters. FSSAI packaging safety regulations and BIS standards govern film specifications for food-contact applications. Gujarat and Maharashtra anchor Uflex Ltd. and Jindal Poly Films Limited manufacturing clusters supplying flexible laminate demand.
Non-Breathable Films Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in resin and masterbatch supply. The market exhibits moderate consolidation with multinational converters holding scale advantages in multi-layer coextrusion while regional specialists capture niche medical and electronics segments. Strategic archetypes include vertically integrated resin-to-film operators, technology-licensed regional converters, and specialty nylon film manufacturers. Dominant competitive moves encompass backward integration into resin production and geographic expansion through distribution partnerships.
Among North American-based converters, Berry Global, Inc. and Toray Plastics (America), Inc. occupy positions spanning commodity food packaging and premium medical barrier applications respectively. Uflex Ltd. and Jindal Poly Films Limited exemplify the emerging-market integrated model with captive resin sourcing and regional distribution depth. RKW Group represents the European specialist archetype with focused expertise in agricultural and construction film segments.
| Leading Market Players |
|---|
| Berry Global, Inc. |
| Uflex Ltd. |
| Jindal Poly Films Limited |
| RKW Group |
| Polyplex Corporation Ltd. |
| Winpak Ltd. |
| Bischof + Klein SE & Co. KG |
| Toray Plastics (America), Inc. |
| Amcor Limited |
| Others |
Value Chain & Pricing Dynamics
The Port of Rotterdam's chemical tanker throughput anchors resin distribution cost dynamics that concentrate supply power among integrated polyethylene producers while forcing downstream converters into volume-discount tiering structures that separate multinational brand owners from regional processors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates medical-grade certified film from food-contact compliant grades from commodity construction sheeting. Price differentiation hinges on barrier certification tier and volume scale, with FDA drug master file status commanding substantial premiums over FSSAI food-contact compliance. Cost compression in standard-grade polyethylene laminates is intensifying because China's eastern seaboard capacity additions are creating export surplus conditions. Regional food processors exhibit the highest price sensitivity, while medical device manufacturers locked into 18-24 month qualification cycles show minimal elasticity.
Supply Chain Analysis
Contract manufacturing concentration among blown film specialists in India, China, and Germany holds capacity for multi-layer coextrusion with nanometer-grade barrier precision. Raw material dependencies draw from Gulf Coast ethane crackers, Middle Eastern naphtha derivatives, and Asian purified terephthalic acid feedstocks. Single-source vulnerability around specialized nine-layer and eleven-layer die equipment creates bottleneck exposure for medical and electronics qualification timelines. Distribution runs through direct mill relationships for specification-intensive buyers and regional distributors for mid-tier agricultural and construction segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering cyclical recovery as ethylene feedstock volatility moderates and cold chain infrastructure buildout in India accelerates procurement volumes. The recovery trajectory rests on resin price stabilization and qualification cycle normalization.
For Market Incumbents: Build regulatory certification moats by accelerating MDR technical documentation and FDA drug master file submissions ahead of competitor qualification cycles. Defensive consolidation through captive resin sourcing in Gujarat and Maharashtra manufacturing clusters protects margin structures against China's export surplus pricing. Channel control via direct sales relationships with multinational food brand owners locks out regional converter competition.
For New Entrants and Emerging Players: Establish a beachhead in Brazil's agricultural export packaging segment where domestic high-barrier film supply gaps create import substitution openings. The most penetrable white-space target lies in ALD-coated substrate qualification for organic electronics manufacturers seeking hermetic moisture barriers. A go-to-market angle through digital printing convergence enables short-run customization without plate costs, collapsing minimum order quantities for regional brand owners.
For Investors and Strategic Acquirers: Specialty nylon film manufacturers with ISO 11607 certification and Toray Plastics-style medical segment positioning represent the priority acquisition archetype. Long-term viability over the coming decade hinges on chemical recycling infrastructure maturation and bio-based barrier resin qualification under EU Green Deal mandates. The signal to watch is extended producer responsibility fee implementation across European packaging waste frameworks as an inflection indicator for material substitution economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Gulf Coast ethane cracker access secures cost-advantaged polyethylene feedstock against naphtha price volatility. |
| Multi-Layer Coextrusion Capacity Expansion | Eleven-layer die installations in Gujarat and Maharashtra serve India's cold chain infrastructure buildout demand. |
| ALD Coating Technology Licensing | Vapor-phase deposition capabilities unlock medical device and organic electronics hermetic packaging applications. |
| Chemical Recycling Partnership | Mass-balance certified resin qualification addresses EU Green Deal recycled content thresholds for European brand owners. |
| Direct Sales Channel Deepening | Multi-year supply agreements with multinational food processors freeze out regional distributor competition. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with blown film plant managers, pharmaceutical packaging procurement leads at multinational brand owners, medical device regulatory affairs directors, and electronics manufacturing services barrier film specialists. Secondary validation drew from FDA 510(k) filings, EMA medical device submissions, REACH substance authorization databases, and BIS packaging safety standards. Bottom-up resin consumption modeling and top-down packaging value chain sizing were triangulated against trade flow data and extrusion line capacity announcements.
Calibration against historical capacity utilization rates and qualification cycle durations anchored the analytical framework across the projection horizon. Segmentation dimensions modeled encompassed film chemistry tier, end-use application intensity, barrier performance specification, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections and supply-side capacity absorption curves. Industry-specific forecast inputs included ethylene-naphtha spread trajectories and medical device MDR transition timelines.
Stress conditions across crude oil price bands, REACH substance restriction scenarios, and China capacity addition rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about resin qualification cycle stability and extended producer responsibility fee implementation schedules. Quarterly review of ethylene feedstock spreads, ALD coating adoption rates in electronics, and EU packaging waste directive enforcement intensity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Global Packaging Foams Market
Packaging Materials
Cash Management Supplies Packaging Market
Packaging Materials
Collapsible Tube Packaging Market
Packaging Materials
Bottle Sealing Wax Market
Packaging Materials
Anti-Static Liners Market
Packaging Materials
Cement Packaging Market
Packaging Materials
Book Wraps Market
Packaging Materials
Child Resistant Zipper Market
Packaging Materials
Neoprene Coffee Sleeves Market
Packaging Materials
Thermoformed Trays Market
Packaging Materials
Wrapping Tissues Market
Packaging Materials
Latin America Single-Use Packaging Market
Packaging Materials
Cold Form Foil Market
Packaging Materials
Spices, Dry Mixes and Extracts Packaging Market
Packaging Materials
Production Page Volume Market
Packaging Materials
Sealed Wax Packaging Market