
 Tote and Ingredient Bags Packaging Market | 2026-2036
Tote and Ingredient Bags Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Tote and Ingredient Bags Packaging Market Analytics
Polypropylene woven fabric is repositioning multilayer paper kraft in bulk ingredient logistics, cutting unit weight and improving moisture resistance for cross-border grain and dairy powder shipments. Amcor PLC leverages vertical integration across blown film and woven conversion to control resin specifications for food-grade totes. Mondi Group anchors European supply through integrated kraft-paper and plastic hybrid lines serving agricultural cooperatives. Berry Global Group Inc. competes on high-throughput extrusion capacity for polyethylene-based flexible intermediate bulk containers.
Tote and ingredient bags packaging denotes industrial containers engineered for dry bulk transport, typically fabricated from woven polypropylene, polyethylene film laminates, or multiwall paper with load-bearing straps rated between 500 kg and 2,000 kg safe working capacity. These units serve food processors, chemical formulators, and agricultural distributors requiring contamination-resistant, stackable, and pallet-compatible handling systems. Flexible bags and bulk bags together capture the dominant volume share, with flexible formats expanding fastest in dairy powder and spice applications where space-efficient cube utilization reduces freight cost per ton. Polypropylene material grades command the widest specification range, while biodegradable alternatives remain confined to niche organic ingredient channels where composting infrastructure justifies premium positioning.
FDA food-contact notification requirements govern polymer migration limits for dairy and pharmaceutical-grade totes distributed across United States processing plants. EU REACH and F-Gas Regulation constrain fluorinated barrier coatings, pushing converters toward non-PFAS high-density polyethylene laminates for chemical and agricultural end users. Germany's national packaging ordinance, aligned with extended producer responsibility frameworks, mandates minimum recycled content thresholds that reshape raw material procurement for suppliers serving Central European food manufacturers. Stakeholders must monitor evolving state-level plastic bans in the United States and pending EU Packaging and Packaging Waste Regulation amendments that could mandate reusable ratios for bulk ingredient transport by the end of the forecast window.
Market Dynamics
Polypropylene woven totes are consolidating share from multilayer paper kraft across bulk ingredient logistics, driven by moisture resistance requirements and cross-border grain shipment protocols. This material transition is compressing converter margins while redirecting capital toward blown film and woven conversion assets.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation amendments:Pending mandates on reusable transport ratios are accelerating food processor audits of bulk bag lifecycle performance. German bakery cooperatives are piloting closed-loop tote pooling systems ahead of formal compliance deadlines.
- Dairy powder exporters:Cube-efficient flexible formats are displacing rigid intermediate bulk containers in ocean freight lanes, cutting dunnage weight and pallet repositioning costs for New Zealand and Dutch processors.
- Co-extruded polyethylene laminates:Non-PFAS barrier films are capturing pharmaceutical-grade tote specifications previously held by fluorinated coatings, opening formulation pathways for converters with FDA master file submissions.
Market Restraints
- Propylene monomer volatility:Crude-linked feedstock swings compress margin predictability for woven polypropylene converters serving annual contract bakery accounts.
- Recycled content certification bottlenecks:EU REACH traceability requirements for post-consumer polymer streams are limiting qualified substrate supply for Central European food-contact applications.
- Rigid IBC residual demand:Chemical formulators handling hygroscopic powders retain steel and composite intermediate bulk containers where electrostatic discharge protocols override flexible bag economics.
Strategic Opportunities
- India FSSAI food-grade certification pathway:Domestic spice processors are qualifying woven polypropylene totes for export-compliant bulk packaging, creating substrate demand outside established European supply chains.
- RFID-embedded traceability:Converging polymer identification tags with blockchain lot tracking is enabling premium pricing for pharmaceutical ingredient totes requiring chain-of-custody documentation.
- Agricultural cooperative direct sourcing:Bypassing distributor markup through mill-direct tote procurement is spreading among French and Italian grain handling associations.
Industry Challenges
- FDA food-contact notification timelines:Polymer migration study submissions for dairy-grade totes face 180-day review windows that delay new product launches.
- Woven conversion technician scarcity:Circular loom operation and ultrasonic sealing calibration require apprenticeship pipelines that regional vocational programs have not scaled.
- Legacy paper kraft line stranded assets:Multilwall bag converters face write-down pressure as bakery accounts accelerate polypropylene transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tote and Ingredient Bags Packaging Market |
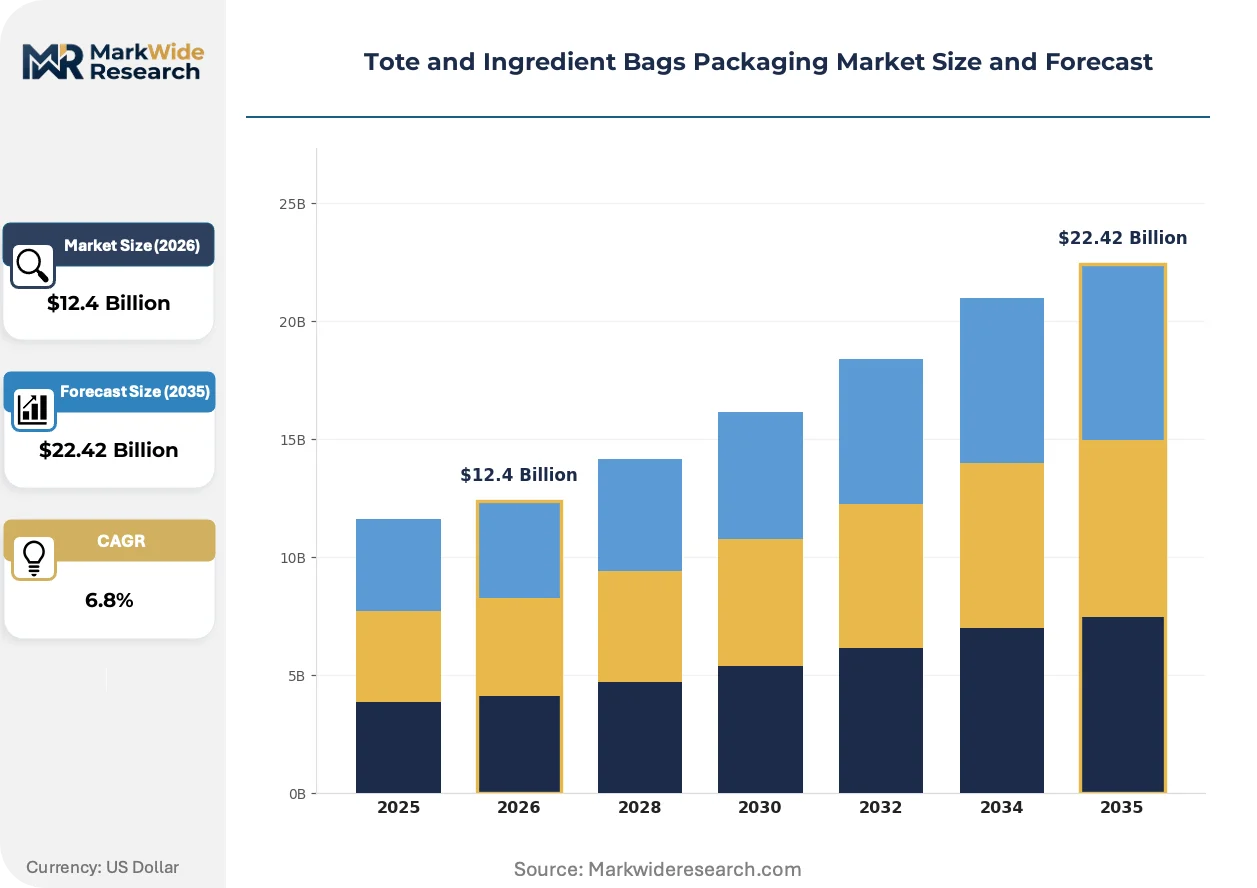
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Flexible Bags, Rigid Containers, Bulk Bags, Pouches Material: Polyethylene, Polypropylene, Paper, Biodegradable Materials End User: Food Industry, Agriculture, Chemical Industry, Pharmaceuticals Capacity: Small Capacity, Medium Capacity, Large Capacity, Custom Sizes |
| Companies Covered | Amcor PLC, Mondi Group, Berry Global Group Inc., Sonoco Products Company, International Paper Company, Smurfit Kappa Group PLC, Huhtamaki Oyj, Sealed Air Corporation, Nanchang Cloud Power E-commerce Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tote and Ingredient Bags Packaging Market Evolving Landscape
Active reshaping in this market centers on barrier technology substitution, regulatory compliance automation, and procurement model compression. These forces are converging to redefine converter capability requirements and buyer-vendor contracting structures.
Co-extruded high-density polyethylene laminates with oxygen scavenger layers are consolidating specification control for moisture-sensitive dairy and pharmaceutical powders. North American whey protein isolate processors are specifying these structures for trans-Pacific container shipments. The technology is consolidating technical differentiation around converters with in-house film extrusion and lamination assets.
EU F-Gas Regulation constraints on perfluorinated barrier coatings are forcing formulation pivots toward silicone oxide and aluminum oxide vapor-deposited films. Chemical agricultural distributors are qualifying these alternatives for pesticide-grade totes previously dependent on fluoropolymer liners. German and Dutch cooperatives are demanding ECHA-compliant substrate documentation as a gatekeeping criterion in tender evaluations.
Direct mill procurement by large-scale food processors is compressing distributor intermediation in bulk bag supply chains. Multinational dairy cooperatives are negotiating multi-year polymer specifications directly with woven converters, unbundling logistics and technical service. This pattern is most visible in Netherlands and Denmark where concentrated buyer power supports captive inventory arrangements.
Tote and Ingredient Bags Packaging Market Segmentation
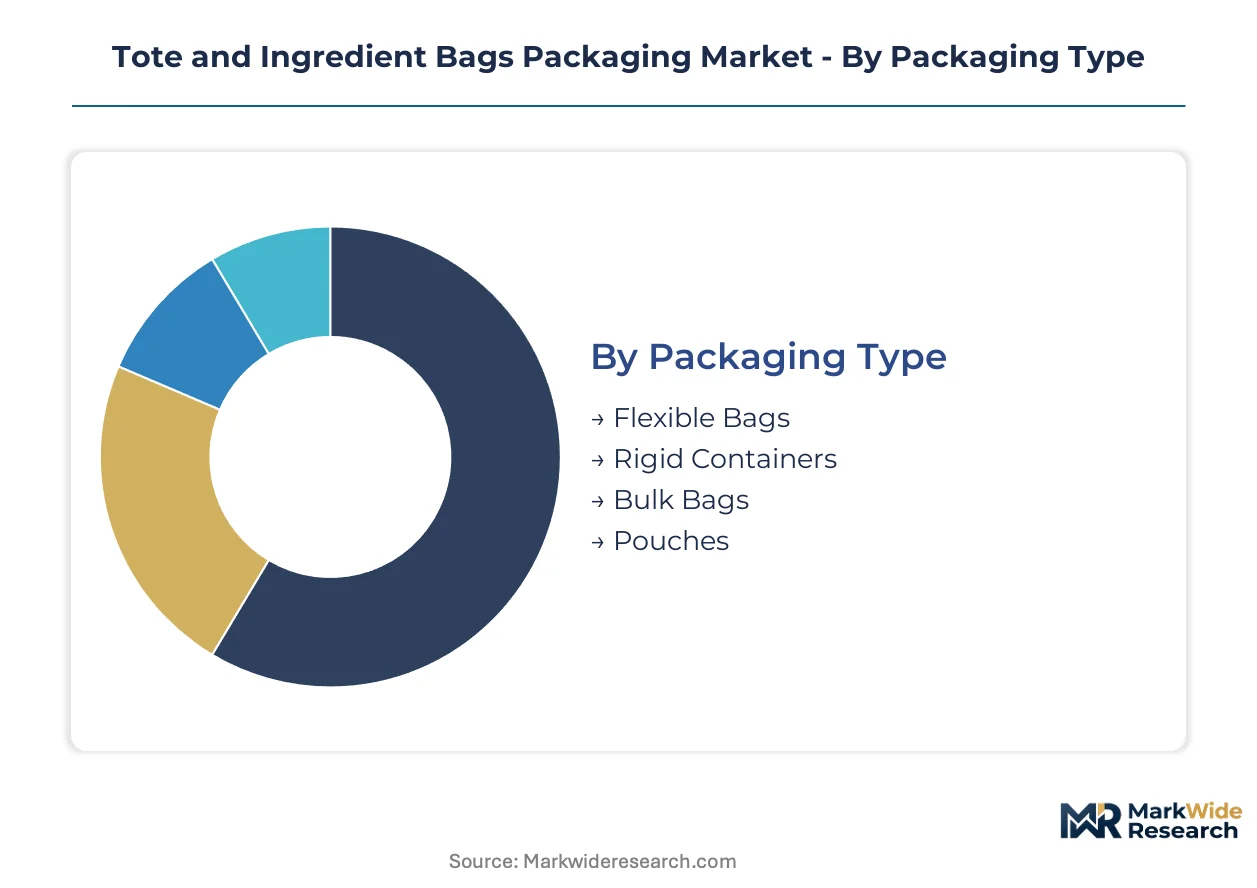
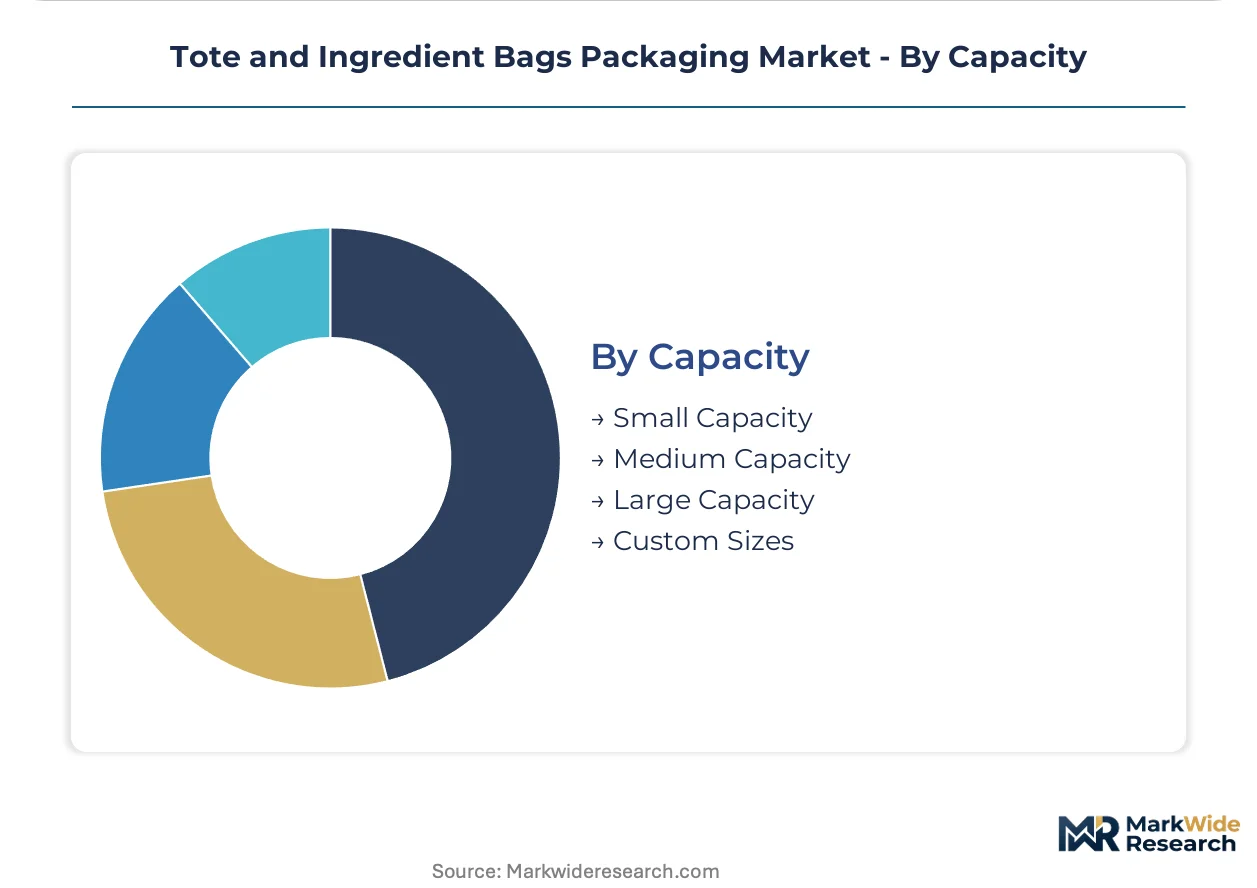
Segmentation in this market separates commodity volume plays from specification-driven premium tiers. Converter investment priorities and buyer procurement patterns diverge sharply across packaging formats, material grades, and end-use compliance requirements.
Packaging Type:
Flexible formats dominate tonnage while rigid alternatives retain specification premiums in moisture-critical applications.
- Flexible Bags:Woven polypropylene and polyethylene film laminates serve grain, dairy powder, and spice transport with cube-efficient pallet utilization. German bakery cooperatives are scaling flexible bag procurement for cross-border ingredient flows under pending EU reusable transport mandates.
- Bulk Bags:Flexible intermediate bulk containers rated 500-2,000 kg capture pharmaceutical and agricultural volumes where forklift handling and stackability reduce warehouse repositioning costs. Dutch dairy exporters specify these for ocean freight lanes to cut dunnage weight.
- Rigid Containers:Steel and composite intermediate bulk containers persist in chemical formulator accounts handling hygroscopic powders where electrostatic discharge protocols override flexible economics.
- Pouches:Smaller-format flexible packaging serves retail ingredient repackaging and foodservice portion control with lower capital barriers to entry.
Today's leader: Flexible Bags. Tomorrow's challenger: Bulk Bags.
Material:
Polymer grades command specification range while paper and biodegradable alternatives occupy contracting niches.
- Polypropylene:Woven fabric grades reposition multilayer kraft across bulk logistics with superior moisture resistance and lighter unit weights for grain and dairy powder shipments. FDA food-contact notification requirements govern polymer migration limits for dairy-grade specifications.
- Polyethylene:Co-extruded high-density laminates with oxygen scavenger layers consolidate control for moisture-sensitive pharmaceutical powders. EU F-Gas Regulation constraints on fluorinated barriers push converters toward non-PFAS polyethylene formulations.
- Paper:Multiwall kraft structures face accelerating displacement as bakery accounts transition to woven polypropylene, stranding legacy converter assets.
- Biodegradable Materials:Compostable substrates remain confined to organic ingredient channels where infrastructure justifies premium positioning and EU extended producer responsibility frameworks create compliance pull.
Polypropylene captures current volume concentration. Polyethylene films are gaining specification share fastest in pharmaceutical-grade barriers.
End User:
Food industry buyers drive standardization while pharmaceutical and chemical accounts impose certification premiums.
- Food Industry:Bakery, confectionery, and dairy processors scale reusable bulk packaging for dry ingredient transport with traceable polymer chain documentation. Germany's national packaging ordinance mandates minimum recycled content thresholds reshaping procurement.
- Agriculture:Grain handling associations in France and Italy are piloting direct mill procurement to bypass distributor markup, compressing supply chain intermediation.
- Chemical Industry:Formulators handling hygroscopic and hazardous materials retain rigid container specifications where safety protocols override flexible bag economics.
- Pharmaceuticals:Whey protein isolate and active ingredient processors specify co-extruded barrier films with RFID-embedded traceability for chain-of-custody documentation, enabling premium converter pricing.
Food Industry anchors present volume. Pharmaceuticals offer the steepest expansion trajectory through compliance-driven specification upgrades.
Capacity:
Scale economies concentrate in standardized large formats while customization captures fragmented small-batch premiums.
- Large Capacity:1,000-2,000 kg flexible intermediate bulk containers serve high-volume grain and dairy powder flows with maximum cube utilization and minimal handling labor per ton.
- Medium Capacity:500-1,000 kg formats balance handling flexibility with freight density for mid-scale processors lacking bulk receiving infrastructure.
- Small Capacity:Sub-500 kg bags serve specialty ingredient distributors and foodservice channels with lower minimum order quantities and faster inventory turns.
- Custom Sizes:Non-standard dimensions capture pharmaceutical and chemical accounts with proprietary equipment interfaces or unique stacking constraints, commanding specification premiums.
Large Capacity commands current tonnage economics. Custom Sizes extract margin premiums from compliance-intensive verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German bakery and confectionery clusters anchor industrial demand for traceable polymer chains in bulk ingredient logistics, with regulatory pressure from EU REACH and national packaging ordinances redirecting converter investments toward certified substrates across multiple jurisdictions.
United States
Dairy powder processors and whey protein isolate exporters drive specification demand for FDA food-contact compliant totes with oxygen scavenger barrier layers. FDA notification requirements govern polymer migration limits for pharmaceutical-grade applications. Wisconsin and California dairy cooperatives are qualifying co-extruded polyethylene laminates for trans-Pacific container shipments to cut dunnage weight.
Germany
Bakery cooperatives and agricultural distributors scale reusable bulk packaging procurement ahead of EU Packaging and Packaging Waste Regulation compliance deadlines. The national packaging ordinance mandates minimum recycled content thresholds under extended producer responsibility frameworks. North Rhine-Westphalia and Bavaria host concentrated flexible bag converter operations serving Central European food manufacturers with traceable substrate documentation.
Netherlands
Dairy exporters specify cube-efficient flexible intermediate bulk containers for ocean freight lanes to Asia and North America. EU F-Gas Regulation constraints on fluorinated barrier coatings push converters toward non-PFAS polyethylene formulations. Rotterdam and Groningen processing clusters pilot closed-loop tote pooling systems with RFID-embedded traceability for chain-of-custody documentation.
India
Domestic spice processors qualify woven polypropylene totes for FSSAI food-grade certification pathways serving export markets. The FSSAI framework establishes migration limits and substrate safety standards for food-contact applications. Gujarat and Maharashtra handling associations are bypassing distributor markup through direct mill procurement agreements with woven converters.
France
Grain handling cooperatives and agricultural associations compress supply chain intermediation through mill-direct tote procurement. EU REACH traceability requirements for post-consumer polymer streams limit qualified substrate supply for food-contact applications. The Île-de-France and Hauts-de-France regions concentrate distributor networks transitioning toward specification-driven premium tiers.
Tote and Ingredient Bags Packaging Market Competitive Landscape
Global majors compete with regional champions across substrate certification and barrier technology dimensions, with market structure tiering between integrated resin-to-film converters and specialized woven fabric producers. Consolidation pressure concentrates around FDA master file submissions and EU REACH documentation capabilities. Three archetypes dominate: vertically integrated polymer producers with captive extrusion assets, regional woven specialists with circular loom scale, and hybrid paper-plastic converters managing kraft-to-polypropylene transitions. Dominant competitive moves include backward integration into resin specification control and multi-year polymer supply agreements with food processor accounts.
Among integrated packaging conglomerates with extrusion and lamination assets, Amcor PLC, Mondi Group, and Berry Global Group Inc. occupy positions exemplifying the scale-driven archetype. Amcor represents converters with blown film and woven conversion control over resin specifications. Mondi anchors European supply through integrated kraft-paper and plastic hybrid lines. Berry Global sits within the high-throughput extrusion tier for polyethylene-based flexible intermediate bulk containers. These three entities illustrate how substrate diversification and regulatory compliance automation separate premium-tier positioning from commodity volume plays.
| Leading Market Players |
|---|
| Amcor PLC |
| Mondi Group |
| Berry Global Group Inc. |
| Sonoco Products Company |
| International Paper Company |
| Smurfit Kappa Group PLC |
| Huhtamaki Oyj |
| Sealed Air Corporation |
| Nanchang Cloud Power E-commerce Co. |
| Others |
Value Network & Pricing Analysis
EU REACH traceability mandates for post-consumer polymer streams gate qualified substrate supply and premium-tier pricing access for food-contact totes, compressing margins for converters lacking certified resin documentation while enabling margin capture by integrated players with in-house extrusion control.
Pricing Analysis
Propylene monomer cost pass-through dominates contract negotiations between woven converters and annual bakery accounts, with crude-linked feedstock swings compressing margin predictability. Three-tier pricing structure across pharmaceutical-grade barrier laminates, standard food-contact woven fabric, and commodity grain bags reflects FDA master file submission costs and EU REACH documentation burdens. Pricing pressure stems from recycled content certification bottlenecks limiting qualified substrate availability. Small-scale spice processors exhibit highest price sensitivity, while pharmaceutical ingredient handlers accept specification premiums for RFID-embedded traceability.
Supply Chain Analysis
Ocean freight dunnage weight reductions drive cube-efficient flexible format adoption across trans-Pacific dairy powder lanes, with Rotterdam and Groningen processing clusters anchoring European distribution. Resin specification control concentrates in Germany, the Netherlands, and India, where integrated converters manage blown film and woven conversion assets. Raw material flows draw from Saudi and Qatari propylene feedstock, German kraft-paper pulp, and Chinese circular loom equipment. Single-source vulnerability runs through qualified post-consumer polymer streams under EU REACH traceability requirements. Distribution runs through agricultural cooperative direct procurement and multinational dairy captive inventory arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU REACH compliance costs in Germany and FSSAI certification pathways in India, where substrate qualification timelines diverge by eighteen to twenty-four months.
For Market Incumbents: Acquire circular loom operations and ultrasonic sealing calibration assets to offset technician scarcity stranding competitor expansion. Consolidate FDA master file submission capabilities against emerging regional specialists with faster EU REACH documentation turnaround. Backward integration into resin specification control defends margin position against propylene monomer volatility. For New Entrants and Emerging Players: Blockchain-integrated RFID traceability platforms offer wedge positioning in pharmaceutical-grade tote segments where chain-of-custody documentation commands specification premiums. Target Indian spice export processors qualifying woven polypropylene under FSSAI pathways outside established European supply chains. Lead with pilot closed-loop pooling system deployments to bypass distributor intermediation. For Investors and Strategic Acquirers: Roll-up economics work for regional woven specialists with circular loom scale because EU REACH certification bottlenecks create captive demand for documented substrate supply. Five-to-ten-year viability hinges on converter consolidation around barrier technology substitution and regulatory compliance automation. Monitor India FSSAI export qualification volumes as inflection signal for geographic supply shift.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Specification Control | Amcor's blown film assets demonstrate margin defense against propylene feedstock swings. |
| Non-PFAS Barrier Film Formulation Pivot | EU F-Gas Regulation constraints force silicone oxide vapor deposition qualification for agricultural distributors. |
| Closed-Loop Tote Pooling System Deployment | German bakery cooperatives pilot RFID-tracked reuse ahead of EU Packaging and Packaging Waste Regulation mandates. |
| Direct Mill Procurement Agreement Structuring | French grain handling associations bypass distributor markup through cooperative converter contracts. |
| FDA Master File Submission Acceleration | Polymer migration study pipelines reduce 180-day notification delays for dairy-grade tote launches. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining converter operations directors, food processor procurement leads, agricultural cooperative supply managers, and pharmaceutical ingredient logistics coordinators with secondary validation from FDA food-contact notifications, EU ECHA substance registrations, FSSAI certification databases, and customs trade flow records. Bottom-up capacity modeling triangulates against top-down end-use demand aggregation.
Rate-of-change decomposition separates volume growth from specification upgrade value capture across packaging format, material grade, end-use compliance tier, and regional regulatory cluster dimensions. CAGRs derive from segment-level growth rate reconciliation with aggregate market trajectory. Forecast inputs incorporate propylene monomer price elasticity coefficients and EU Packaging and Packaging Waste Regulation compliance timeline assumptions.
The model holds under stable regulatory enforcement intensity and intact ocean freight rate structures; deviation in EU REACH traceability requirement stringency or trans-Pacific container capacity constraints would shift substrate qualification timelines and geographic supply concentration. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Mattress and Furniture Bags Market
Bags and Containers
Liner Bags Market
Bags and Containers
Big Bag Discharge Station Market
Bags and Containers
Jumbo Bags Market
Bags and Containers
Bagster Bag Market
Bags and Containers
Crates Market
Bags and Containers
Loose-Fill Peanuts Market
Bags and Containers
Bakery Bread Bag Market
Bags and Containers
Centerfold Laminated Bags Market
Bags and Containers
Trash Can Liners Market
Bags and Containers
Lawn and Leaf Bags Market
Bags and Containers
Twisted Handle Bags Market
Bags and Containers
North America Retail Bags Market
Bags and Containers
Gusseted Bags Market
Bags and Containers
Insulated Bags Market
Bags and Containers
Bag-On-Valve Laminates Market