
 Packaging Suction Cups Market | 2026-2036
Packaging Suction Cups Market Size, Share, and Industry Trends Forecast 2026-2036
Packaging Suction Cups Market Analytics
Aftermarket service revenue for suction cup replacement and vacuum system calibration is narrowing as OEMs bundle longer-life silicone compounds into initial equipment sales. J. Schmalz GmbH leverages its Stuttgart engineering base to dominate high-cycle automotive handling applications. Piab AB sustains technology leadership through decentralized vacuum ejector architectures that reduce energy draw per pick-and-place cycle. ANVER Corporation anchors North American distribution with heavy-duty cup portfolios for glass and sheet-metal transfer lines.
Packaging suction cups are elastomeric or thermoplastic vacuum gripping devices, typically molded from silicone, nitrile rubber, or thermoplastic polyurethane with Shore A durometer ratings between 40 and 70, designed to create temporary seals against porous and non-porous surfaces for automated material handling. Their primary industrial purpose is to enable high-speed, damage-free transfer of packaged goods, fragile electronics, and food containers across conveyor, robotic, and palletizing systems. Standard suction cups occupy the largest volume share across food packaging lines where frequent changeover demands interchangeable geometries, while heavy-duty variants command premium positioning in automotive sheet handling where oil resistance and load capacity determine specification. Silicone formulations are displacing PVC in electronics assembly applications as OEMs phase out halogenated materials to meet customer sustainability protocols.
FDA food-contact substance regulations and EU REACH chemical restrictions jointly constrain material formulation choices, compelling manufacturers to maintain dual compound portfolios and regional certification documentation. The EU F-Gas Regulation and US EPA SNAP program indirectly shape demand by accelerating pneumatic-to-electric vacuum system conversions that require redesigned cup interfaces and sealing geometries. China's GB standards for food machinery hygiene and Japan's METI energy-efficiency labeling for industrial equipment add further compliance layers for suppliers serving multi-regional OEM accounts. Stakeholders must monitor regulatory divergence between silicone migration limits in food-contact applications and emerging per- and polyfluoroalkyl substance restrictions that could eliminate certain surface-treatment chemistries from supply chains.
Market Dynamics
Food packaging automation is forcing a wholesale replacement of mechanical grippers with vacuum handling systems, compressing equipment refresh cycles and reshaping supplier relationships across the value chain.
Growth Catalysts
- EU REACH chemical restrictions:Manufacturers are accelerating silicone compound R&D to eliminate restricted plasticizers, creating pull for certified food-grade suction cup portfolios.
- Automotive sheet-metal handling:Electric vehicle production lines in Germany and the US Midwest specify oil-resistant heavy-duty cups for battery enclosure transfer operations.
- China's export packaging belt:E-commerce fulfillment centers in Guangdong and Zhejiang provinces deploy high-cycle vacuum systems for fragile electronics handling.
Market Restraints
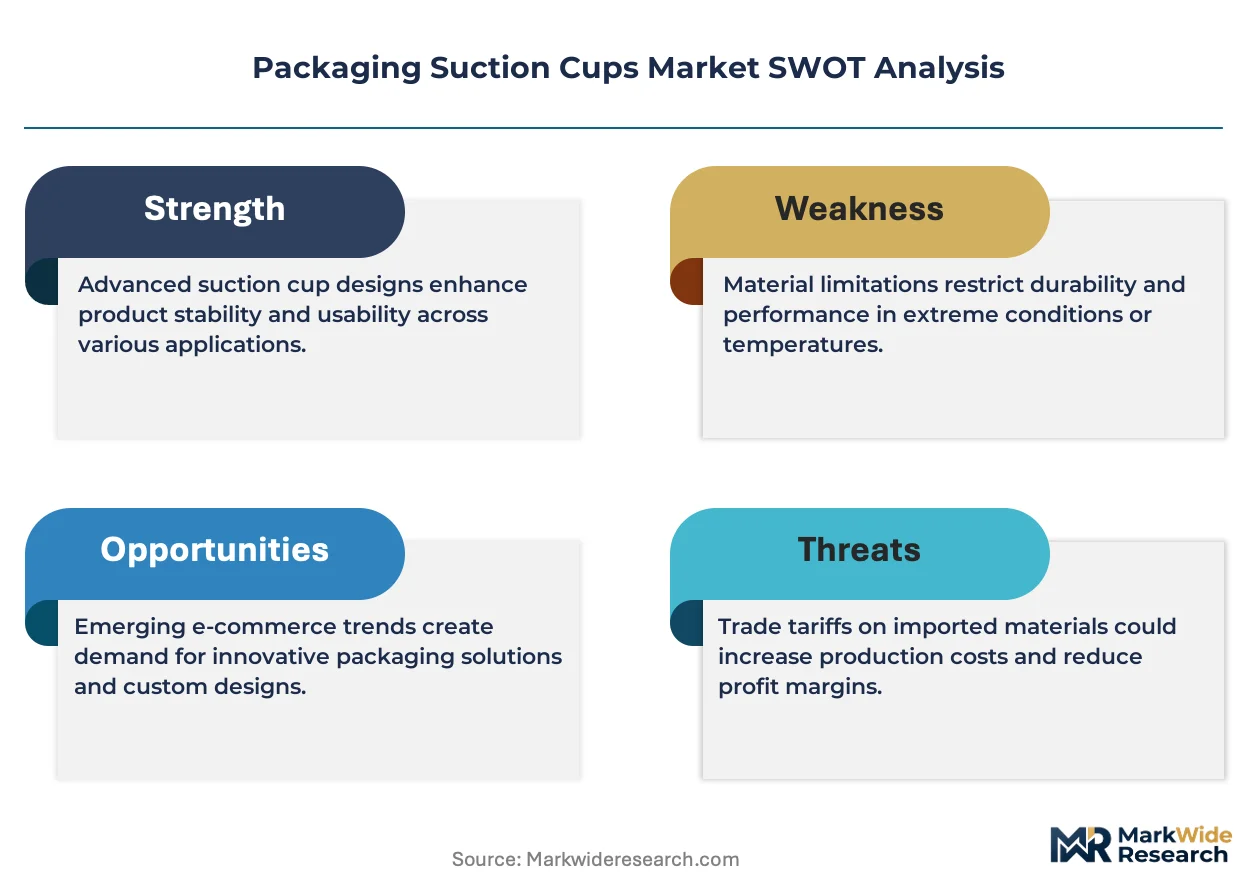
- Silicone raw material concentration:Specialty silicone feedstock supply concentrates among German and Chinese chemical producers, exposing cup molders to input cost volatility.
- Technical limitation in porous substrates:Standard vacuum geometries fail on corrugated fiberboard with high moisture content, restricting deployment in fresh produce logistics.
- Regulatory friction from EU F-Gas Regulation:Pneumatic vacuum system phase-outs force OEMs to redesign cup interfaces for electric ejector architectures.
Strategic Opportunities
- Underpenetrated cold-chain logistics in India:Temperature-resistant silicone formulations address pharmaceutical and dairy packaging automation gaps in Mumbai and Hyderabad industrial corridors.
- Technology convergence of IoT sensors and vacuum systems:Smart cups with embedded pressure monitoring enable predictive maintenance contracts in Japanese automotive plants.
- US Inflation Reduction Act domestic content incentives:North American cup suppliers qualify for credits when serving battery and solar panel packaging OEMs.
Industry Challenges
- Multi-regional certification timelines:Simultaneous FDA, EU REACH, and China GB compliance documentation extends product launch cycles by 8-14 months.
- Integration complexity with legacy robotic arms:Retrofitting vacuum end-effectors onto 15-20 year old palletizing equipment requires custom adapter engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaging Suction Cups Market |
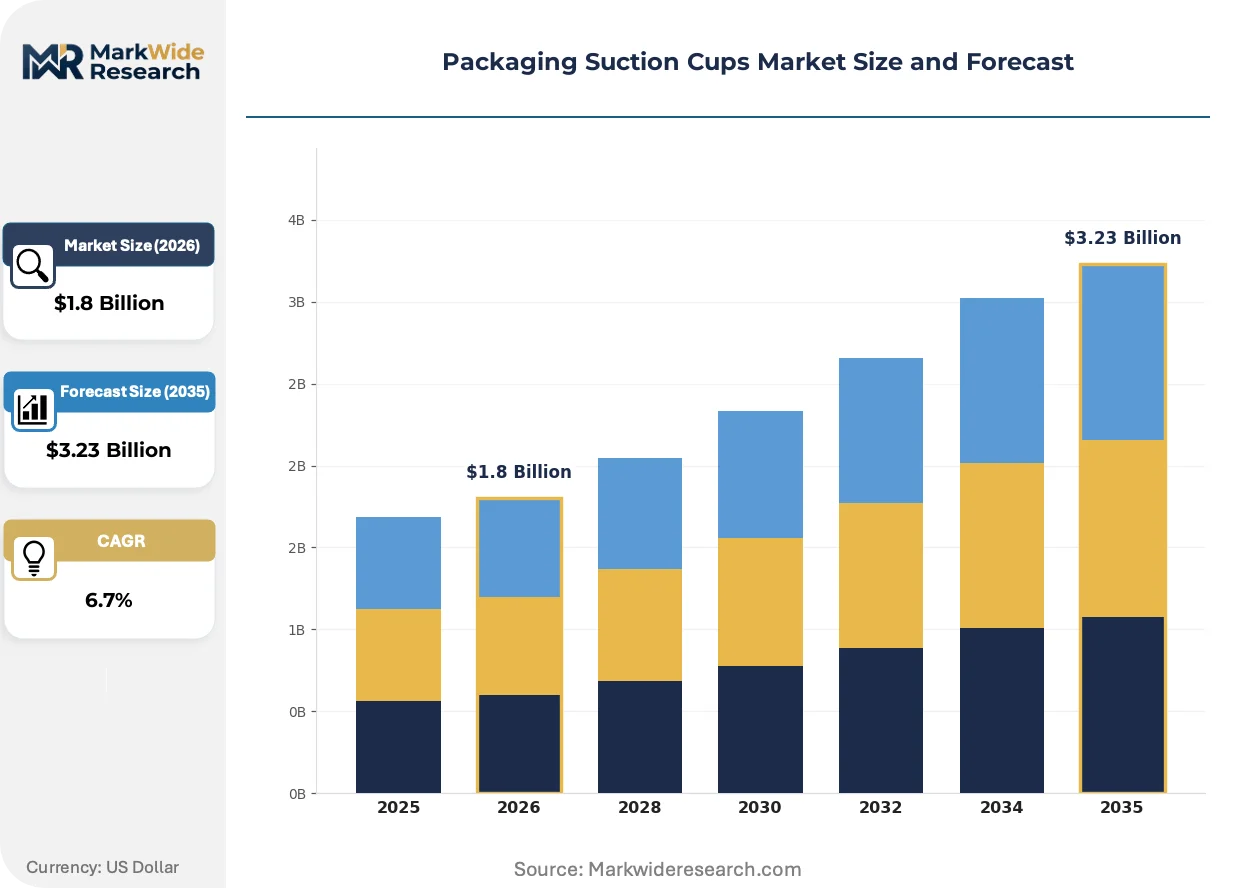
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Suction Cups, Heavy-Duty Suction Cups, Mini Suction Cups, Vacuum Suction Cups Material: Silicone, Rubber, PVC, Polycarbonate Application: Food Packaging, Electronics Assembly, Product Display, Automotive Size: Small, Medium, Large, Custom |
| Companies Covered | J. Schmalz GmbH, Piab AB, ANVER Corporation, Coval Inc., SMC Corporation, All-Vac Industries, Adams Manufacturing Corporation, Vi-Cas Manufacturing Company, William B. Rudow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaging Suction Cups Market Evolving Landscape
Active sensor integration and material chemistry advances are compressing the boundary between gripping hardware and intelligent automation systems, forcing suppliers to expand beyond commodity molding.
Smart suction cups with embedded pressure transducers and wireless connectivity are digitizing predictive maintenance workflows in high-throughput automotive and electronics assembly lines. Tier-1 automotive suppliers in Stuttgart and Detroit are specifying these units for 24/7 battery pack handling operations. The technology is digitizing traditional aftermarket service models by enabling remote vacuum system calibration and wear-state monitoring.
The EU F-Gas Regulation and US EPA SNAP program are jointly accelerating pneumatic-to-electric vacuum system conversions across food packaging lines. Industrial equipment OEMs must redesign cup sealing geometries and interface specifications to accommodate decentralized ejector architectures. German automation integrators are most affected, with Stuttgart engineering clusters retooling entire product families for electric vacuum compatibility.
Aftermarket service unbundling is fragmenting traditional supplier-OEM relationships as food packagers internalize vacuum system calibration capabilities. Direct procurement of replacement cup inventories from distributors is displacing bundled maintenance contracts in North American logistics corridors. This shift is most visible in the US Midwest, where warehousing operators now specify cup lifespans and replacement intervals in original equipment tenders.
Packaging Suction Cups Market Segmentation
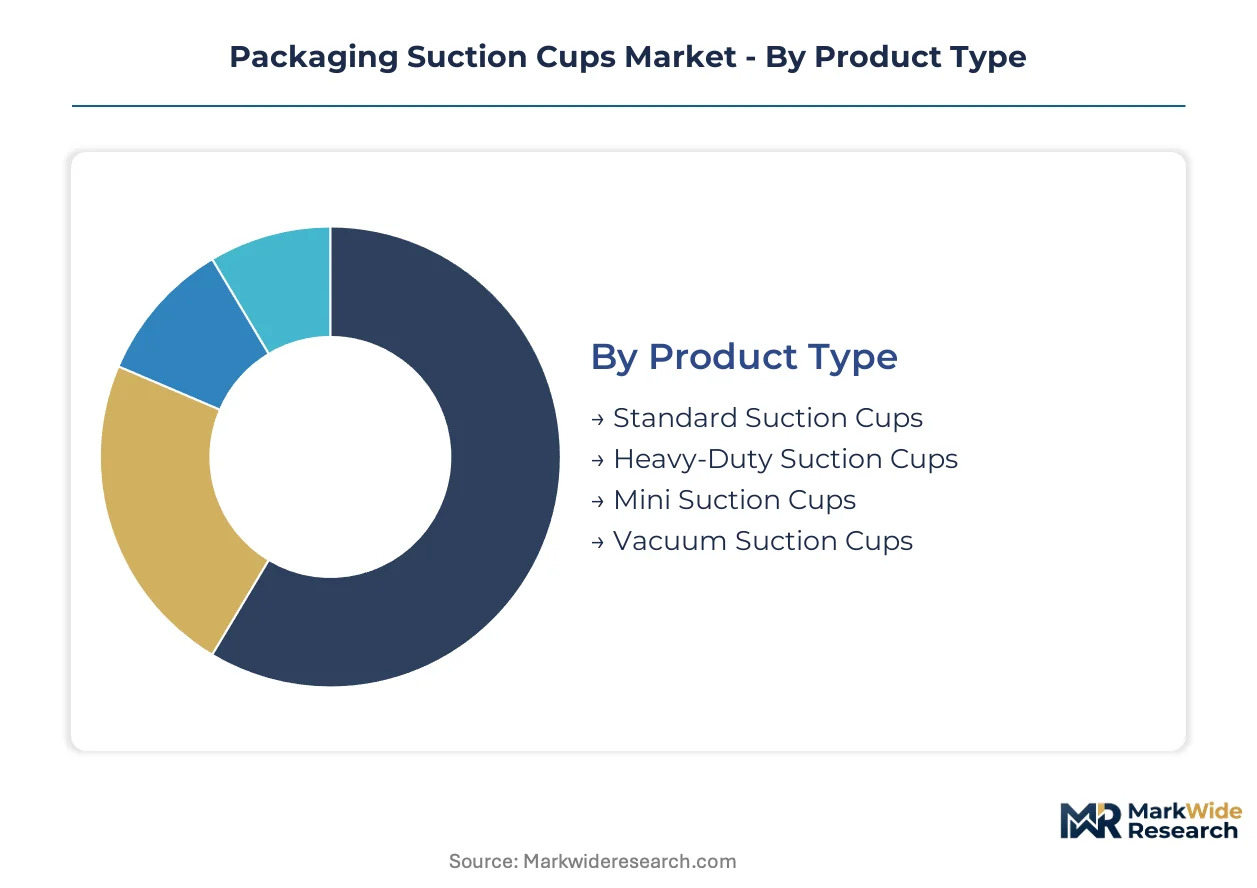
Packaging suction cup segmentation reveals how material chemistry, load-bearing geometry, and end-use contamination requirements fragment procurement patterns across automation tiers. Suppliers must maintain parallel compound portfolios and diameter ranges to serve food-grade lines alongside oil-resistant automotive cells.
Product Type:
Load capacity and cycle frequency divide the use-case spectrum from fragile electronics handling to sheet-metal transfer operations.
- Standard Suction Cups:Molded silicone or nitrile rubber geometries with 40-70 Shore A durometer ratings dominate food packaging lines where frequent tool changeover demands interchangeable diameters. Germany's industrial automation cluster specifies these for dairy container palletizing where FDA-compliant compounds are mandatory.
- Heavy-Duty Suction Cups:Reinforced lip structures and thicker elastomer walls handle 50-200 kg loads in automotive battery enclosure transfer. Stuttgart engineering bases and Detroit EV production lines specify oil-resistant formulations for 24/7 sheet handling cycles.
- Mini Suction Cups:Compact 10-30 mm diameters serve precision electronics assembly in Shenzhen and Seoul SMT lines where component damage tolerance approaches zero.
- Vacuum Suction Cups:Integrated ejector-compatible geometries accommodate pneumatic-to-electric system conversions driven by EU F-Gas Regulation phase-outs.
The dominant share belongs to Standard Suction Cups, while Heavy-Duty Suction Cups is closing the gap fastest.
Material:
Regulatory compliance layers and surface energy requirements stratify procurement across FDA, REACH, and GB standard jurisdictions.
- Silicone:Platinum-cured formulations with sub-0.5% plasticizer migration dominate food-contact applications. China's export packaging belt and North American logistics corridors specify these for temperature cycling between -40°C and 200°C.
- Rubber:Nitrile and EPDM compounds retain share in automotive handling where petroleum-based hydraulic fluid exposure demands solvent resistance. German OEMs specify nitrile for battery pack assembly lines.
- PVC:Phthalate-plasticized formulations are contracting as EU REACH restrictions and customer sustainability protocols eliminate halogenated materials from electronics assembly supply chains.
- Polycarbonate:Thermoplastic structural cups serve lightweight display and consumer goods handling where visual transparency aids robotic vision alignment.
Silicone commands the volume lead, yet polycarbonate is expanding most quickly in vision-guided automation cells.
Application:
Contamination sensitivity and throughput velocity determine specification intensity across end-use verticals.
- Food Packaging:FDA food-contact substance regulations and EU EFSA migration limits compel dedicated silicone compound portfolios. Automated dairy and ready-meal lines in Wisconsin and the Netherlands specify washdown-compatible geometries.
- Electronics Assembly:Static-dissipative formulations and ionic contamination controls dominate semiconductor and PCB handling in Taiwan and South Korea.
- Product Display:Clear polycarbonate and colored silicone variants serve retail fixture automation where aesthetic presentation intersects with gentle handling.
- Automotive:EV battery enclosure and solar panel handling specify heavy-duty oil-resistant cups in US Midwest and Stuttgart manufacturing corridors.
Food Packaging retains the largest procurement volume, though Electronics Assembly is gaining share fastest on semiconductor capacity expansion.
Size:
Gripping force requirements and payload geometry dictate diameter selection across robotic end-effector configurations.
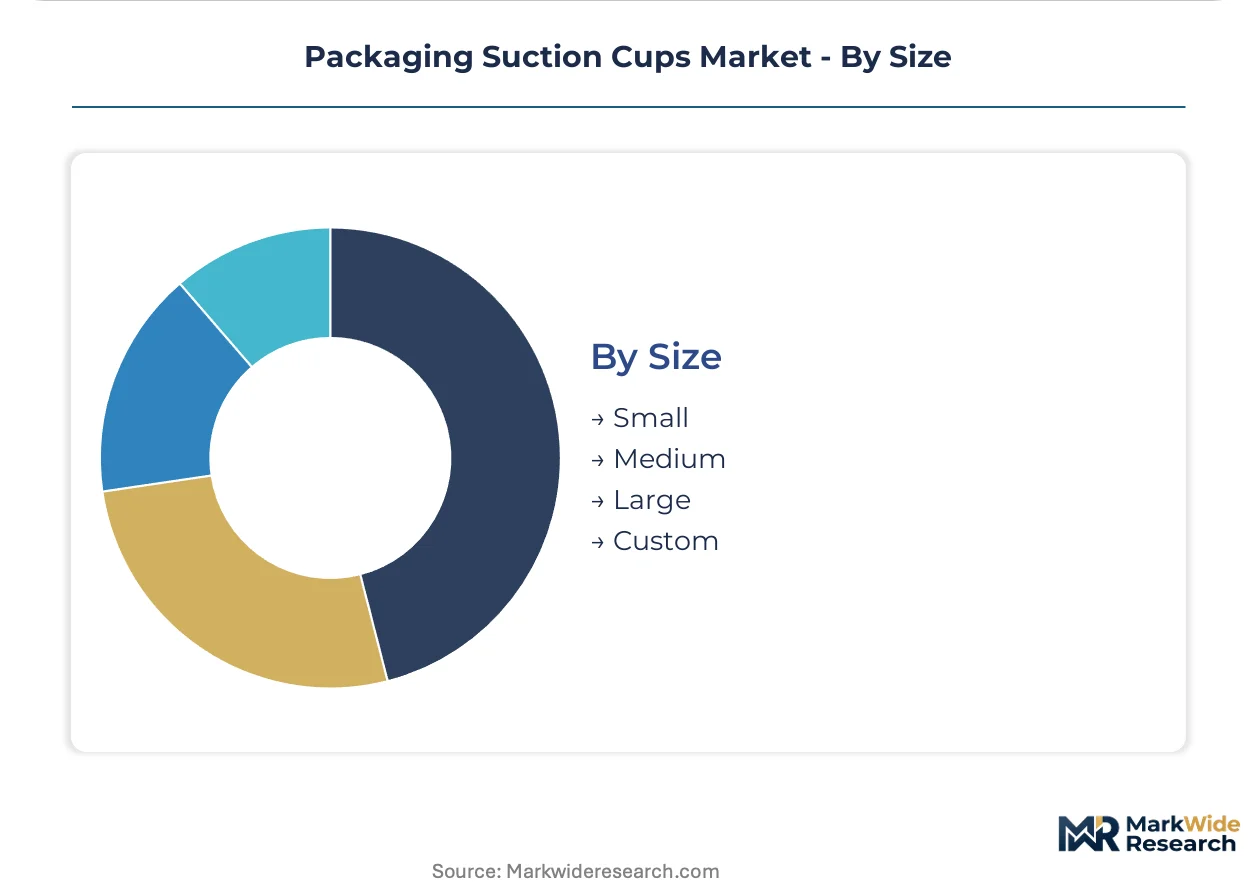
- Small:10-30 mm diameters handle SMT components and pharmaceutical vials in precision assembly cells.
- Medium:40-80 mm geometries balance holding force and footprint for consumer goods and food container handling.
- Large:100-200 mm cups manage corrugated cases and bulk produce bins in logistics and agricultural automation.
- Custom:Application-specific lip geometries and multi-bellows designs address irregular substrates in aerospace composite and glass handling.
Medium sizes anchor procurement volumes, while Custom configurations are climbing the fastest on specialized EV battery and solar wafer handling requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China's export packaging belt exhibit the highest price elasticity, squeezing margins on standard silicone geometries, while German automotive OEMs absorb premium pricing for heavy-duty oil-resistant formulations without volume reduction.
United States
Midwest logistics corridors drive heavy-duty cup procurement for EV battery enclosure handling as Ford and GM expand Detroit-area assembly capacity. FDA food-contact substance regulations compel dedicated silicone compound portfolios for Wisconsin dairy automation lines. Chicago and Milwaukee warehousing operators now specify cup replacement intervals directly in original equipment tenders.
Germany
Stuttgart's industrial automation cluster sustains premium demand for high-cycle automotive handling systems as Mercedes-Benz and Porsche accelerate EV transitions. EU REACH chemical restrictions force rapid reformulation of plasticizer-free silicone compounds for food-grade certification. Bavarian packaging OEMs in Nuremberg and Munich are retooling entire product families for electric vacuum ejector compatibility under F-Gas Regulation timelines.
China
E-commerce fulfillment centers in Guangdong and Zhejiang provinces deploy vacuum systems for fragile electronics handling at volumes unmatched elsewhere. GB standards for food machinery hygiene add compliance layers for suppliers serving multi-regional accounts. Shenzhen SMT lines specify mini suction cups with zero component damage tolerance for semiconductor packaging automation.
Japan
Automotive plants in Toyota City and Yokohama specify smart cups with embedded pressure monitoring for predictive maintenance contracts. METI energy-efficiency labeling for industrial equipment shapes vacuum system procurement criteria. Nagoya engineering clusters integrate IoT sensor convergence into 24/7 battery pack handling operations.
India
Pharmaceutical and dairy packaging automation gaps in Mumbai and Hyderabad industrial corridors create demand for temperature-resistant silicone formulations. Central government PLI scheme incentives accelerate cold-chain infrastructure investment. Gujarat's expanding food processing belt represents the fastest-growing regional opportunity for washdown-compatible vacuum geometries.
Packaging Suction Cups Market Competitive Landscape
Engineering-intensive specialists and scale-driven diversified industrials split the market into complementary rather than directly competing tiers. Consolidation concentrates among Stuttgart-based automation component houses and Japanese pneumatic conglomerates with captive vacuum divisions. Three archetypes dominate: family-owned German engineering houses with century-long automation lineages, Nordic decentralized vacuum technology platforms, and North American distribution-anchored heavy-duty specialists. Competitive moves center on electric ejector architecture redesigns and regional certification documentation bundling to compress OEM procurement cycles.
Within the German engineering house tier, J. Schmalz GmbH and Piab AB exemplify divergent strategic postures toward vacuum handling intelligence. Schmalz represents the vertically integrated Stuttgart archetype with captive silicone compounding and automotive line integration capabilities. Piab occupies the technology-licensing position through decentralized ejector architectures that reduce energy draw per cycle. ANVER Corporation anchors the North American heavy-duty distribution model with glass and sheet-metal transfer specialization.
| Leading Market Players |
|---|
| J. Schmalz GmbH |
| Piab AB |
| ANVER Corporation |
| Coval Inc. |
| SMC Corporation |
| All-Vac Industries |
| Adams Manufacturing Corporation |
| Vi-Cas Manufacturing Company |
| William B. Rudow |
| Others |
Value Network & Pricing Analysis
Stuttgart's engineering cluster concentrates captive silicone compounding capacity, granting German incumbents pricing power over heavy-duty automotive formulations while Chinese molders compete on standard geometries for export packaging lines. This geographic asymmetry compresses margins on commodity cups while sustaining premium capture for oil-resistant, high-cycle compounds.
Pricing Analysis
Aftermarket service contracts and predictive maintenance subscriptions now drive lifetime value more than initial hardware sales. Three-tier pricing structure across premium, standard, and economy levels separates FDA-certified food-grade compounds from general industrial geometries. Cost compression in China's export packaging belt is intensifying because buyers specify replacement intervals upfront, eroding bundled service margins. E-commerce fulfillment centers in Guangdong exhibit the highest price sensitivity, while Stuttgart automotive OEMs absorb premiums without volume reduction.
Supply Chain Analysis
Specialty silicone feedstock draws from German chemical producers and Chinese petrochemical complexes, with platinum-cured formulations resting on concentrated catalyst supply. Nitrile rubber and thermoplastic polyurethane hinge on petroleum derivative availability, while polycarbonate structural cups feed from Asian polymer resin streams. Single-source vulnerability in platinum group metal supply creates exposure for food-grade certification tiers. Distribution runs through OEM direct procurement for automotive lines and industrial distributors for warehousing retrofit projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance subscriptions and remote vacuum calibration services are expanding faster than hardware replacement cycles, reframing suction cup markets as recurring-revenue platforms rather than consumable components.
For Market Incumbents: Pre-empt unbundling of aftermarket service relationships by embedding IoT-enabled pressure monitoring into premium cup portfolios before food packagers internalize calibration capabilities. Deepen backward integration into platinum-cured silicone compounding to defend margin position against Chinese molders with feedstock cost advantages. Certification investment in simultaneous FDA, EU REACH, and China GB documentation compresses rival launch timelines. For New Entrants and Emerging Players: Temperature-resistant silicone formulations for Indian pharmaceutical and dairy cold-chain automation represent the most penetrable entry point, with Mumbai and Hyderabad industrial corridors underserved by incumbent distribution. Smart cup architectures with wireless connectivity for Japanese automotive predictive maintenance contracts offer a technology-differentiated go-to-market angle against established Stuttgart engineering houses. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors engineering-intensive specialists with captive material science capabilities over scale-driven diversified industrials. Long-term viability across the projection horizon rests on electric vacuum ejector compatibility and regional certification bundling. The signal to watch is OEM procurement cycle compression toward 8-14 month multi-regional compliance timelines as an inflection indicator for consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Compounding | Captive platinum-cured formulation control secures FDA food-grade certification tiers against feedstock volatility. |
| Smart Cup Architecture Development | Embedded pressure transducers enable predictive maintenance contracts in Toyota City and Detroit battery handling lines. |
| Multi-Regional Certification Bundling | Simultaneous FDA, EU REACH, and China GB documentation compresses OEM procurement cycles by eliminating sequential filings. |
| Electric Vacuum Ejector Redesign | Sealing geometry retooling captures F-Gas Regulation-driven pneumatic-to-electric conversion demand in Bavarian packaging OEMs. |
| Cold-Chain Distribution Partnership | Temperature-resistant compound access opens pharmaceutical and dairy automation gaps in Gujarat's expanding food processing belt. |
Research Methodology
A standing panel of maintenance directors at automotive OEMs, plant engineers at food packaging lines, aftermarket service heads at vacuum system integrators, and procurement leads at warehousing operators provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with secondary validation against customs trade data, SEC 10-K filings from listed automation component suppliers, and industrial equipment registration databases. Bottom-up demand modeling across end-use installations was triangulated against top-down chemical feedstock consumption patterns.
Scenario-bracketing across regulatory acceleration, raw material cost volatility, and electric vacuum adoption curves bounded the projection envelope. Segmentation dimensions modeled include product type, material chemistry, application vertical, and regional automation cluster. CAGRs were derived from installation base expansion rates and replacement cycle compression. Industry-specific forecast inputs incorporated EU F-Gas Regulation phase-out timelines and METI energy-efficiency labeling adoption curves.
Stress conditions across silicone raw material price spikes, multi-regional certification timeline extensions, and pneumatic system conversion delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about electric ejector penetration rates and food packaging automation capital expenditure trajectories. Cross-checking against industrial automation equipment shipment data from Germany's VDMA and Japan's JARA is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Global Anti Counterfeit Automobile Packaging Market
Packaging Materials
Anti-Static Liners Market
Packaging Materials
Crimped End Mailing Tubes Market
Packaging Materials
PET Material Packaging Market
Packaging Materials
Construction Films Market
Packaging Materials
Tertiary Packaging Market
Packaging Materials
Expendable Packaging Market
Packaging Materials
Packaging Laminates Market
Packaging Materials
Corrugated Wraps Market
Packaging Materials
Brazil Packaging Market
Packaging Materials
EPE Liner Market
Packaging Materials
Global Packaging Foams Market
Packaging Materials
Germany Packaging Market
Packaging Materials
Spices, Dry Mixes and Extracts Packaging Market
Packaging Materials
Urn Liners Market
Packaging Materials
Wooden and Plywood Packaging Market