
 Military Radar Market | 2026-2036
Military Radar Market Size, Share, and Industry Trends Forecast 2026-2036
Military Radar Market Analysis
Active electronically scanned array standards is bifurcating the competitive landscape between legacy platform retrofits and clean-sheet designs. Lockheed Martin Corporation leverages its F-35 radar integration pipeline to anchor long-term program revenue. RTX Corporation sustains dominance in naval fire-control radars through captive gallium nitride foundry capacity. Northrop Grumman Corporation differentiates via space-based sensor payloads for missile warning architectures.
Military radar denotes radio detection and ranging systems engineered for target acquisition, tracking, and fire control in contested electromagnetic environments, typically operating across L-band through Ku-band frequencies with pulse repetition frequencies exceeding tens of kilohertz for moving-target discrimination. The primary purpose spans battlespace awareness, weapons guidance, and electronic protection for air, maritime, and ground forces. Airborne radar captures the largest value pool as fighter and surveillance fleets modernize, while phased array technology commands premium positioning due to semiconductor content and beam-agility requirements. Ground-based radar segments face margin compression from sovereign offset demands and technology transfer mandates.
Defense procurement in the United States flows through NHTSA spectrum coordination and FCC export licensing for dual-use components, while European deployments navigate CE marking and EU Green Deal energy-efficiency thresholds for shore-based installations. The UK's Ministry of Defence and Australia's Defence Science and Technology Group impose sovereign capability requirements that reshape supply chain localization. Stakeholders must monitor gallium nitride substrate availability and AUKUS technology-sharing protocols as determinants of program viability and partner access.
Market Dynamics
The transition from mechanically steered radar arrays to active electronically scanned array architectures is compressing supplier margins while fragmenting procurement authority across sovereign defense ministries and multinational consortiums.
Growth Catalysts
- AUKUS technology-sharing protocols:The trilateral security pact between Australia, the United Kingdom, and the United States is accelerating joint development programs for next-generation maritime surveillance systems. Integrated deterrence requirements mandate interoperable radar standards across naval platforms.
- Tightened electromagnetic spectrum regulations:FCC licensing constraints and NHTSA spectrum coordination in the United States are forcing defense contractors toward solid-state architectures with lower interference signatures. This regulatory pressure retrofits legacy platforms with modern semiconductor-based systems.
- Gallium nitride substrate maturation:Foundry capacity expansion for wide-bandgap semiconductors is enabling higher power density in fire-control radars. Naval fleets prioritize these materials for extended-range target discrimination in contested environments.
Market Restraints
- Input cost volatility in rare earth processing:Neodymium and dysprosium supply concentration in Chinese refining operations creates pricing instability for permanent magnet components in radar motors and beam-steering mechanisms.
- Sovereign offset demands:European Union member states impose domestic content thresholds through the EU Green Deal and CE marking requirements for shore-based installations. These mandates fragment procurement scale and duplicate certification costs.
- Technical limitation in thermal management:High-pulse-repetition-frequency operation generates heat dissipation challenges that constrain duty cycles in compact airborne platforms. Packaged cooling solutions add mass penalties incompatible with unmanned system constraints.
Strategic Opportunities
- Space-based sensor architectures:Missile warning constellations require distributed radar payloads for hypersonic threat tracking. Low-earth-orbit deployment models reduce per-unit cost barriers for defense agencies.
- Dual-use component pathways:Commercial 5G base station semiconductors share process nodes with military phased array elements. FAA and FCC export licensing frameworks create channel arbitrage for qualified suppliers.
- Regulatory tailwind from IRA domestic manufacturing credits:United States defense contractors qualify for advanced manufacturing tax incentives when sourcing gallium nitride from domestic foundries. This policy redirects supply chain investment toward captive production.
Industry Challenges
- Electromagnetic compatibility certification timelines:MIL-STD-461 testing requirements for conducted emissions and susceptibility extend development schedules by 18-24 months. Program managers face schedule risk from iterative redesign cycles.
- Legacy platform integration complexity:Analog-to-digital interface mismatches between 1980s-era airframes and modern software-defined radar processors require custom adapter development. These engineering costs erode retrofit program profitability.
- Cleared workforce scarcity:Security clearance backlogs and STEM pipeline gaps constrain hiring for radio-frequency engineering and systems integration roles. Defense primes compete for limited talent pools against commercial semiconductor firms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Radar Market |
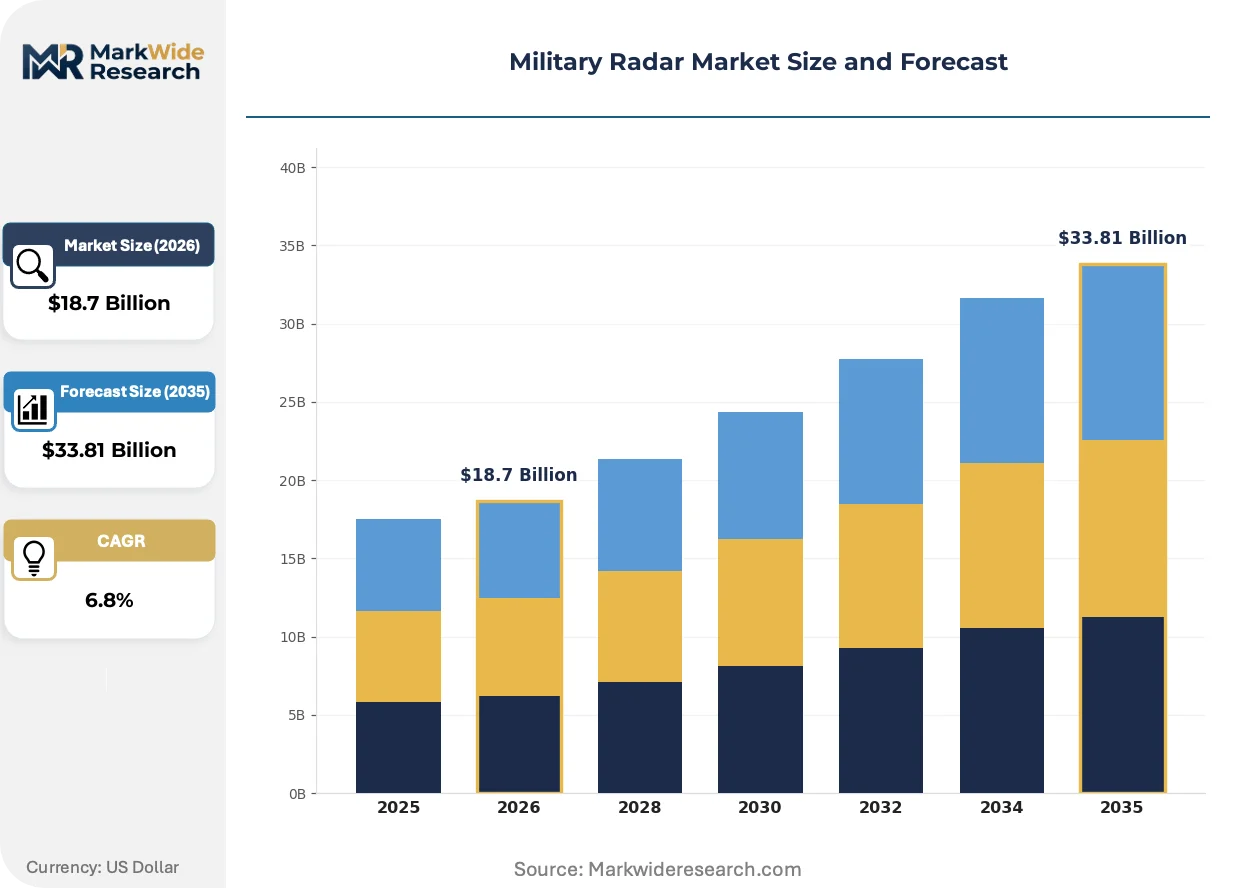
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Airborne Radar, Ground-Based Radar, Naval Radar, Space-Based Radar Technology: Phased Array, Doppler, Synthetic Aperture, Frequency Modulated Continuous Wave Application: Surveillance, Target Detection, Air Traffic Control, Weather Monitoring End User: Defense Forces, Aerospace Manufacturers, Research Institutions, Contractors |
| Companies Covered | Lockheed Martin Corporation, RTX Corporation, Northrop Grumman Corporation, Thales Group, L3Harris Technologies, Inc., BAE Systems, Leonardo S.p.A., Israel Aerospace Industries, Saab AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Radar Market Emerging Trajectories
Semiconductor material transitions and software-defined architectures are collapsing the traditional hardware-software boundary in radar system design. Procurement authorities now prioritize upgradeable platforms over fixed-configuration legacy investments.
Gallium nitride power amplifiers are supplanting gallium arsenide devices in fire-control and surveillance applications. Naval procurement offices in the United States and United Kingdom mandate GaN for new shipboard installations. The technology is supplanting legacy traveling-wave tube amplifiers by delivering comparable output power at one-third the volume and enabling instantaneous frequency agility for electronic protection.
The EU Green Deal energy-efficiency thresholds now apply to shore-based radar installations across NATO European territory. These mandates accelerate retirement of vacuum-tube transmitters and incentivize solid-state replacements. Ground-based early-warning segments face the steepest compliance costs as aging sites require complete electrical infrastructure overhaul.
Defense agencies now unbundle hardware acquisition from sustainment services through performance-based logistics contracts. Prime contractors retain system availability risk while transferring component repair to depot-level maintenance networks. The United Kingdom Ministry of Defence and Australian Defence Science and Technology Group pilot these models for maritime patrol radar fleets.
Military Radar Market Segmentation
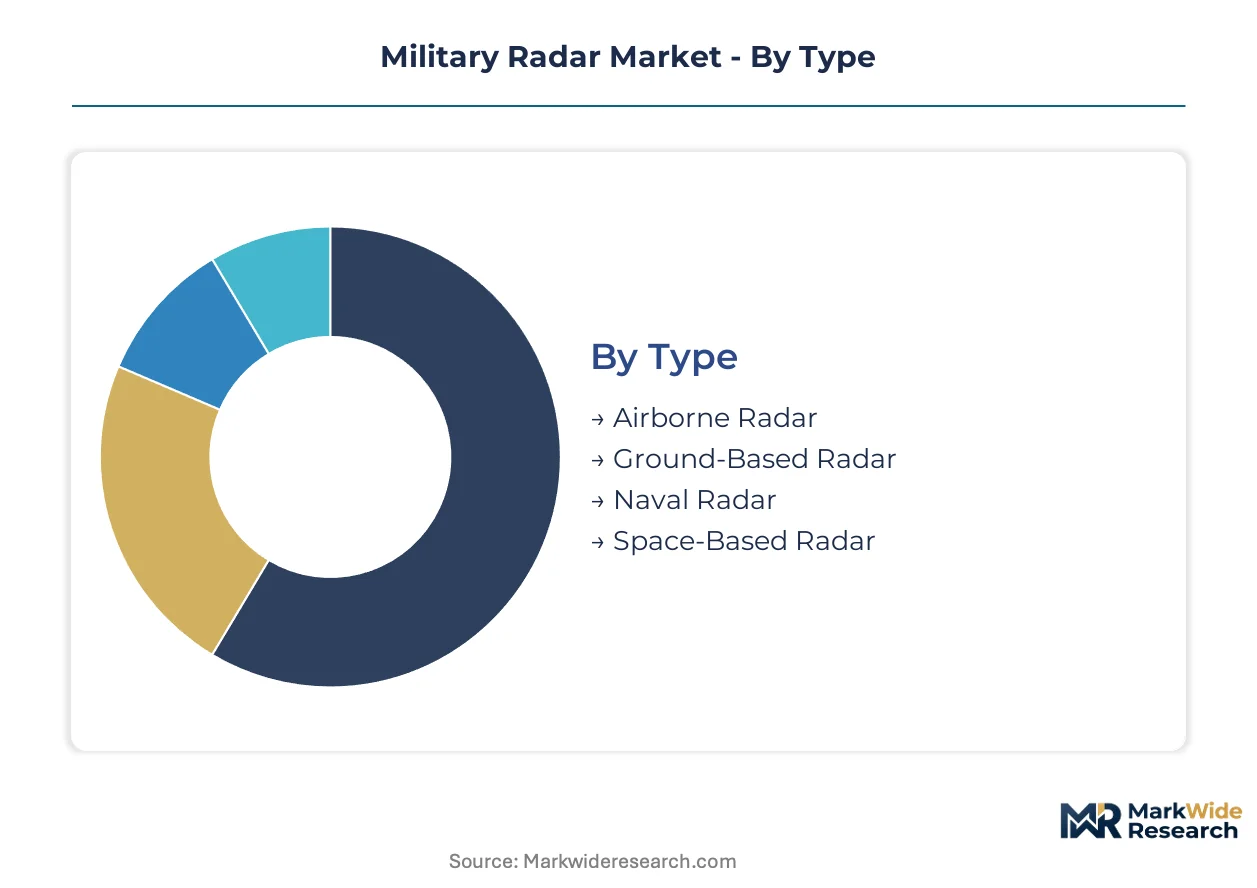
Military radar procurement channels diverge sharply by platform type and technology maturity. Prime contractors route high-value airborne and naval systems through defense ministry acquisition offices, while ground-based segments fragment across sovereign offset mandates.
Type:
Channel concentration varies by platform mobility—airborne and naval arrays flow through integrated prime contractor pipelines, while ground installations disperse across national infrastructure programs.
- Airborne Radar:Fighter and surveillance aircraft integration dominates procurement value. Demand concentrates in United States F-35 programs and United Kingdom Tempest development, driven by active electronically scanned array retrofit cycles and fifth-generation platform production ramps.
- Ground-Based Radar:Early-warning and air-defense installations anchor sovereign capability requirements. European deployments face EU Green Deal energy-efficiency mandates for shore-based electrical infrastructure, compressing margins on vacuum-tube transmitter replacements.
- Naval Radar:Shipboard fire-control and surveillance arrays prioritize gallium nitride power density for extended-range discrimination. AUKUS technology-sharing protocols accelerate joint procurement across United States, United Kingdom, and Australian naval modernization programs.
- Space-Based Radar:Missile warning constellations and orbital surveillance payloads represent emerging procurement channels. Low-earth-orbit deployment models reduce per-unit cost barriers for hypersonic threat tracking architectures.
By volume, Ground-Based Radar leads. By growth pace, Space-Based Radar is climbing the fastest.
Technology:
Cost tier stratification separates premium semiconductor architectures from legacy tube-based systems, with foundry access determining supplier positioning.
- Phased Array:Electronically steered beam agility enables simultaneous multi-target tracking and electronic protection. Active electronically scanned array standards displace mechanically steered systems under tightened FCC and NHTSA spectrum regulations, concentrating demand in fighter and naval fire-control applications.
- Doppler:Pulse-Doppler processing discriminates moving targets against clutter backgrounds through velocity filtering. Weather monitoring and air traffic control applications sustain procurement through dual-use FAA certification pathways.
- Synthetic Aperture:Coherent processing of radar returns generates high-resolution imagery regardless of physical antenna dimensions. Intelligence, surveillance, and reconnaissance platforms prioritize this technology for standoff target identification.
- Frequency Modulated Continuous Wave:Continuous transmission architecture enables low-probability-of-intercept operation with reduced peak power signatures. Compact implementations suit unmanned platforms where thermal management constraints limit pulsed system duty cycles.
By revenue concentration, Phased Array dominates. By technology transition velocity, Frequency Modulated Continuous Wave is gaining share fastest.
Application:
Customer type segmentation separates strategic defense programs from civil-military dual-use installations, with procurement authority residing in distinct institutional channels.
- Surveillance:Wide-area situational awareness drives border monitoring and maritime domain awareness programs. NATO members accelerate next-generation array procurement for integrated deterrence architectures spanning Arctic to Indo-Pacific operating areas.
- Target Detection:Fire-control quality tracking enables weapons engagement at extended ranges. Naval surface fire support and air-to-air engagement modes demand gallium nitride amplifier density for thermal and power efficiency.
- Air Traffic Control:Military-civil interoperability requirements shape secondary surveillance radar and precision approach radar specifications. Dual-use component pathways leverage commercial 5G semiconductor process nodes for cost reduction.
- Weather Monitoring:Meteorological radar networks support operational planning and launch safety. Ground-based installations face EU Green Deal energy thresholds across European NATO territory.
By installed base, Surveillance leads. By modernization urgency, Target Detection shows the steepest expansion trajectory.
End User:
Maturity gradients separate established defense procurement systems from emerging research partnerships, with contract vehicles determining supplier access.
- Defense Forces:National military services drive platform-integrated radar acquisition through defense ministry budget authorities. United States Department of Defense, United Kingdom Ministry of Defence, and Australian Defence Science and Technology Group impose sovereign capability requirements reshaping supply chain localization.
- Aerospace Manufacturers:Prime contractors integrate radar subsystems into complete weapon systems. Lockheed Martin, RTX Corporation, and Northrop Grumman retain captive design authority for fighter and surveillance platform radar suites.
- Research Institutions:Defense laboratories and university-affiliated research centers prototype advanced concepts. DST Group Australia and United Kingdom Defence Science and Technology Laboratory pilot performance-based logistics models for maritime patrol radar fleets.
- Contractors:Subsystem specialists and maintenance providers compete for depot-level sustainment services. Performance-based logistics contracts transfer component repair risk while prime contractors retain system availability guarantees.
By contract value, Defense Forces lead. By partnership model innovation, Research Institutions are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Australia and the United Kingdom demonstrate the least price sensitivity due to AUKUS-linked technology access premiums, while European NATO members face the most acute cost pressure from sovereign offset mandates and EU Green Deal compliance burdens.
United States
F-35 production ramps and next-generation fighter development drive airborne radar demand through the Department of Defense. FCC spectrum coordination and NHTSA electromagnetic regulations enforce solid-state AESA architectures. Defense procurement clusters concentrate in Maryland-Virginia corridor and Southern California aerospace corridors.
United Kingdom
Tempest sixth-generation fighter and maritime patrol modernization programs anchor naval and airborne radar procurement. Ministry of Defence sovereign capability requirements reshape supply chain localization under AUKUS protocols. Defence Science and Technology Laboratory partnerships concentrate activity in Wiltshire and Bristol aerospace clusters.
Australia
AUKUS submarine and surface fleet modernization accelerates joint radar development with US and UK partners. Defence Science and Technology Group imposes interoperability standards for integrated deterrence architectures. Procurement authority concentrates in Canberra-Queanbeyan defense corridor with Sydney manufacturing spillover.
Germany
FCAS fighter program and naval frigate modernization sustain phased array demand despite budget fragmentation across federal states. KBA and BAAINBw procurement regulations impose CE marking and domestic content thresholds. Industrial activity clusters in Bavaria and Baden-Württemberg with Munich-Stuttgart aerospace axis.
Japan
F-X indigenous fighter and Aegis destroyer radar upgrades drive fire-control and surveillance procurement. METI and Ministry of Defense coordinate semiconductor substrate security policies for GaN supply chain resilience. Manufacturing concentrates in Nagoya aerospace cluster and Kanto defense electronics corridor.
Military Radar Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where premium semiconductor integration separates high-margin positions from commodity retrofit suppliers. The vendor base consolidates around defense primes with captive foundry access while fragmenting across regional specialists serving sovereign offset requirements. Three archetypes dominate: integrated platform primes with radar design authority, GaN semiconductor specialists controlling upstream substrate supply, and sustainment contractors executing performance-based logistics contracts. Competitive moves center on foundry capacity expansion for wide-bandgap semiconductors and strategic partnerships to secure AUKUS technology-sharing access.
Within the integrated prime tier, Lockheed Martin Corporation and RTX Corporation exemplify platform-anchored radar revenue models, while Northrop Grumman Corporation occupies a position bridging airborne fire-control and emerging space-based sensor architectures. These three entities represent the dominant archetype of captive design authority over fighter and naval platform radar suites.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| RTX Corporation |
| Northrop Grumman Corporation |
| Thales Group |
| L3Harris Technologies, Inc. |
| BAE Systems |
| Leonardo S.p.A. |
| Israel Aerospace Industries |
| Saab AB |
| Others |
Supply Flow & Price Mechanics
Gallium nitride power amplifier substitution for legacy traveling-wave tube transmitters simultaneously redistributes manufacturing gravity toward foundry-capable economies and compresses unit economics through semiconductor volume learning curves. This material transition concentrates pricing power with substrate suppliers in the United States and Japan while eroding margins for tube-based system integrators facing EU Green Deal compliance deadlines.
Pricing Analysis
Performance-based logistics contracts now drive lifetime value capture, with depot-level sustainment services contributing margins that hardware sales alone cannot match. Three-tier pricing structure across AESA retrofit programs, clean-sheet platform integrations, and legacy tube system maintenance reflects certification grade and sovereign offset compliance costs. Cost compression in ground-based early-warning segments intensifies because EU energy-efficiency mandates force complete electrical infrastructure overhaul. European NATO members exhibit the highest price sensitivity due to fragmented procurement scale, while AUKUS partners accept technology-access premiums for interoperability guarantees.
Supply Chain Analysis
Trans-Pacific container availability fluctuations and port congestion at Long Beach and Yokohama elevate inbound logistics costs for gallium nitride substrates and rare earth magnet components. Manufacturing concentrates in the United States, Japan, and Taiwan for wide-bandgap semiconductors, with China dominating neodymium and dysprosium refining for radar motor assemblies. Single-source vulnerability in Chinese rare earth processing creates pricing instability for permanent magnet beam-steering mechanisms. Distribution runs through defense ministry acquisition offices for platform-integrated systems, while sustainment services fragment across depot-level maintenance networks and contractor logistics support arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics logic now governs military radar procurement as AUKUS interoperability standards create winner-take-most dynamics around integrated sensor architectures. The shift from hardware acquisition to availability-based contracting rewards ecosystem control over discrete component sales.
For Market Incumbents: Fortify captive gallium nitride foundry capacity through backward integration into substrate supply, while securing AUKUS technology-sharing protocol access to lock out non-aligned competitors. The emergence of commercial 5G semiconductor firms with transferable process-node capabilities threatens RF engineering talent pools and demands security clearance pipeline investment to protect cleared workforce access. For New Entrants and Emerging Players: Differentiate on space-based sensor payload miniaturization for low-earth-orbit missile warning constellations, where prime contractor incumbency is weakest and per-unit cost barriers have collapsed. The most penetrable white space sits with unmanned platform fire-control radars constrained by thermal management mass penalties that FMCW architectures can address through reduced peak power signatures. Pursue FAA dual-use certification pathways to leverage commercial semiconductor cost structures for military-adjacent revenue. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed GaN semiconductor specialists holding captive substrate supply agreements but lacking platform integration channels. Long-term viability over the next decade hinges on AUKUS program participation and foundry capacity expansion timing. Monitor gallium nitride substrate allocation announcements from Japanese and US foundries as the critical inflection signal for supply-constrained program viability.| Strategic Initiative | Industry Significance |
|---|---|
| Captive GaN Foundry Expansion | RTX Corporation's internal substrate capacity insulates naval fire-control radar margins from supply shocks. |
| AUKUS Technology-Sharing Access | Lockheed Martin's F-35 integration pipeline secures interoperability premiums across trilateral procurement. |
| Space-Based Sensor Payload Development | Northrop Grumman's orbital architectures address hypersonic threat tracking gaps in distributed architectures. |
| Performance-Based Logistics Contracts | UK Ministry of Defence availability models transfer component repair risk while retaining system accountability. |
| Dual-Use Semiconductor Certification | Commercial 5G process node qualification under FCC export licensing creates cost arbitrage for qualified suppliers. |
Methodological Framework
Operator-level perspectives from radar systems engineers, defense ministry procurement officers, gallium nitride foundry operations managers, and performance-based logistics contract administrators anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through Department of Defense budget justification documents, FCC spectrum allocation filings, SEC 10-K disclosures from defense primes, and AUKUS trilateral communiqués. Bottom-up platform delivery forecasts triangulated against top-down defense expenditure projections across the analysis window.
Sensitivity analysis tested forecast robustness against gallium nitride substrate supply constraints, rare earth price volatility, and AUKUS program acceleration scenarios. The analytical framework modeled volume and value across platform type, technology tier, application mission profile, and end-user procurement authority, with regional regulatory cluster effects layered as cross-cutting dimensions. CAGRs derived from fitted growth curves applied to defense modernization cycle timing and semiconductor process node transition schedules.
Material uncertainties — electromagnetic spectrum reallocation, sovereign offset mandate tightening, and cleared workforce pipeline disruptions — sit outside the modeled envelope. Forecasts reflect assumptions about AUKUS technology-sharing protocol continuity and GaN foundry capacity expansion timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Surveillance
Military Manportable Surveillance Radar Market
Military Surveillance
Manportable Radar Market
Military Surveillance
Hydrographic Survey Equipment Market
Military Surveillance
Maritime Surveillance Market
Military Surveillance
Global Military Thermal Imaging Market
Military Surveillance
Military Imaging System Market
Military Surveillance
Passive Radar Market
Military Surveillance
Missile Seeker Detector Market
Military Surveillance
Long Range Radar Systems Market
Military Surveillance
Tactical Optics Market
Military Surveillance
Global Radar Market
Military Surveillance
Night Vision Devices Market
Military Surveillance
Early Warning Radar Market
Military Surveillance
UXO Detection Market
Military Surveillance
Surveillance Radar System Market
Military Surveillance
North America Hydrographic Survey Equipment Market