
 Over the Horizon Radar Market | 2026-2036
Over the Horizon Radar Market Size, Share, and Industry Trends Forecast 2026-2036
Over the Horizon Radar Market Analytics
Multi-source procurement is consolidating as defense ministries favor integrated system-of-systems contracts over discrete radar purchases. Lockheed Martin leverages its layered defense portfolio to bundle over-the-horizon capabilities with satellite and command infrastructure. Raytheon Technologies anchors its position through sustained R&D investment in high-frequency surface wave propagation. Northrop Grumman competes by specializing in software-defined signal processing architectures that reduce hardware refresh cycles.
Over the horizon radar detects targets beyond the line of sight by exploiting ionospheric reflection or surface wave propagation, typically operating in the high-frequency band from 3 to 30 MHz with detection ranges extending from 500 to 3,000 nautical miles. The primary purpose is persistent wide-area surveillance for early warning of aircraft, vessels, and missile threats where conventional line-of-sight radars face geometric limitations. Ground-based radar installations dominate capital deployment due to their fixed infrastructure requirements and sovereign control advantages, while airborne radar variants represent the fastest-expanding segment as naval forces seek mobile coverage gaps. Phased array technology commands the deepest margin pools because active electronically scanned arrays enable rapid beam steering without mechanical rotation, though passive radar architectures are gaining traction among research institutions seeking lower electromagnetic signatures.
The US Department of Defense imposes frequency allocation standards through the NTIA and FCC that constrain civilian spectrum encroachment on military HF bands, while Australia's Defence Science and Technology Group mandates interoperability certifications for coastal surveillance networks. The EU's CE marking framework and electromagnetic compatibility directives shape export eligibility for European suppliers such as Thales Group and BAE Systems. Stakeholders must monitor how emerging spectrum-sharing agreements between defense and commercial maritime users reshape system design priorities and procurement timelines.
Market Dynamics
Phased array technology is compressing system footprints while defense ministries consolidate procurement around integrated surveillance architectures rather than discrete radar units. This structural shift favors suppliers capable of bundling over-the-horizon detection with satellite networks and command infrastructure.
Growth Catalysts
- Maritime Boundary Tensions:Coastal surveillance procurement is accelerating in Australia, Japan, and South Korea as territorial disputes intensify across the East and South China Seas.
- CE Marking Alignment:European electromagnetic compatibility directives are streamlining export eligibility for defense electronics manufacturers seeking cross-border sales within EU member states.
- Surface Wave Propagation:High-frequency surface wave radar advances are extending detection ranges for vessel tracking without requiring ionospheric reflection, reducing operational complexity.
Market Restraints
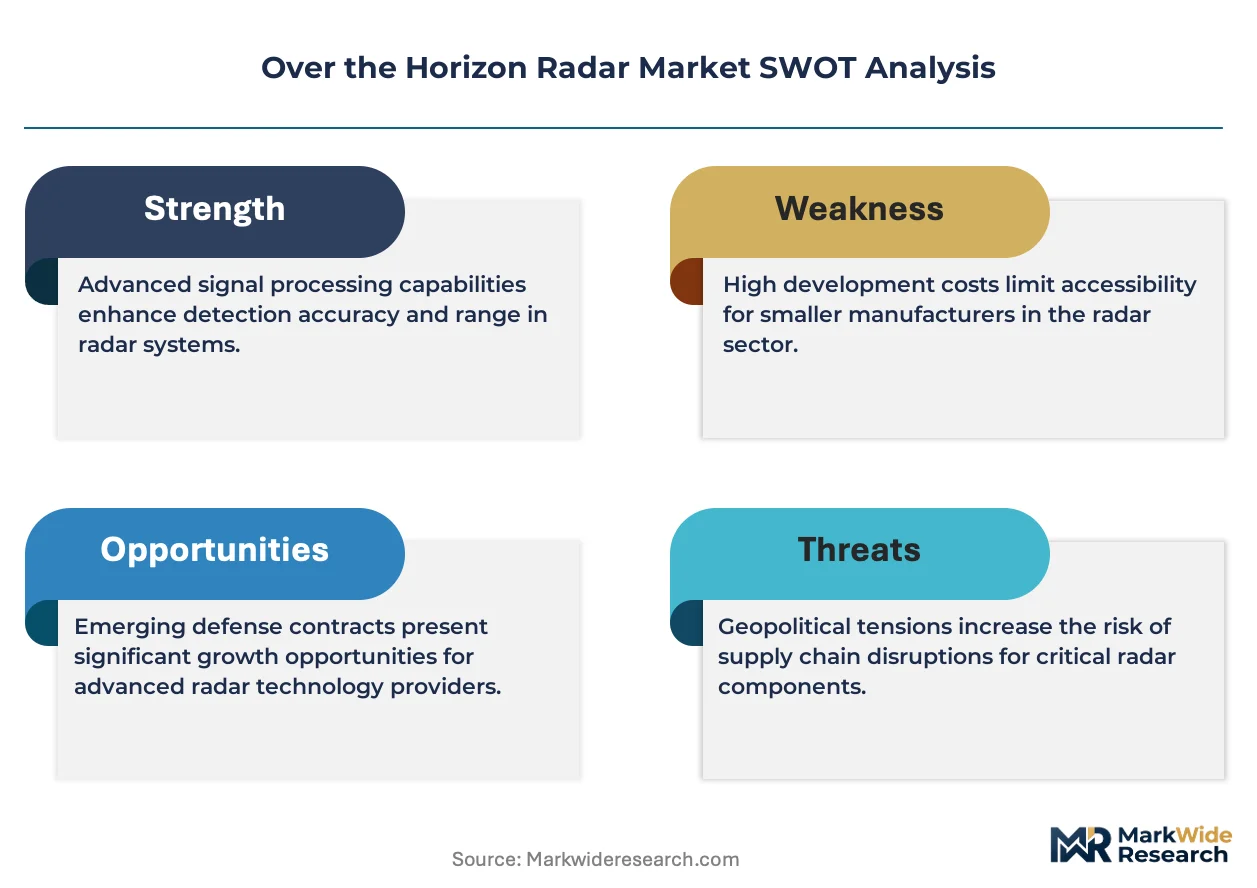
- Spectrum Allocation Constraints:The US NTIA and FCC frequency standards limit civilian encroachment on military HF bands, constraining dual-use technology development pathways.
- Fixed Infrastructure Dependency:Ground-based installations require sovereign territory access, restricting deployment flexibility in contested or allied-nation basing scenarios.
- Passive Radar Substitution:Research institutions are pursuing lower electromagnetic signature architectures that reduce detectability but compress margins for active system suppliers.
Strategic Opportunities
- Airborne Segment Expansion:Naval forces are prioritizing mobile coverage gaps through airborne radar variants, creating white space for platform-integrated system developers.
- Software-Defined Architectures:Signal processing virtualization is enabling hardware refresh cycle compression and reducing sovereign control dependencies on foreign component suppliers.
- Spectrum-Sharing Frameworks:Emerging defense-commercial maritime agreements are reshaping system design priorities for dual-use coastal monitoring applications.
Industry Challenges
- HF Engineering Talent Scarcity:Ionospheric physics and high-frequency propagation expertise is concentrating among aging specialist cohorts, constraining workforce expansion.
- Legacy System Integration:NATO interoperability standards require backward compatibility with existing command infrastructure, compling new radar deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Over the Horizon Radar Market |
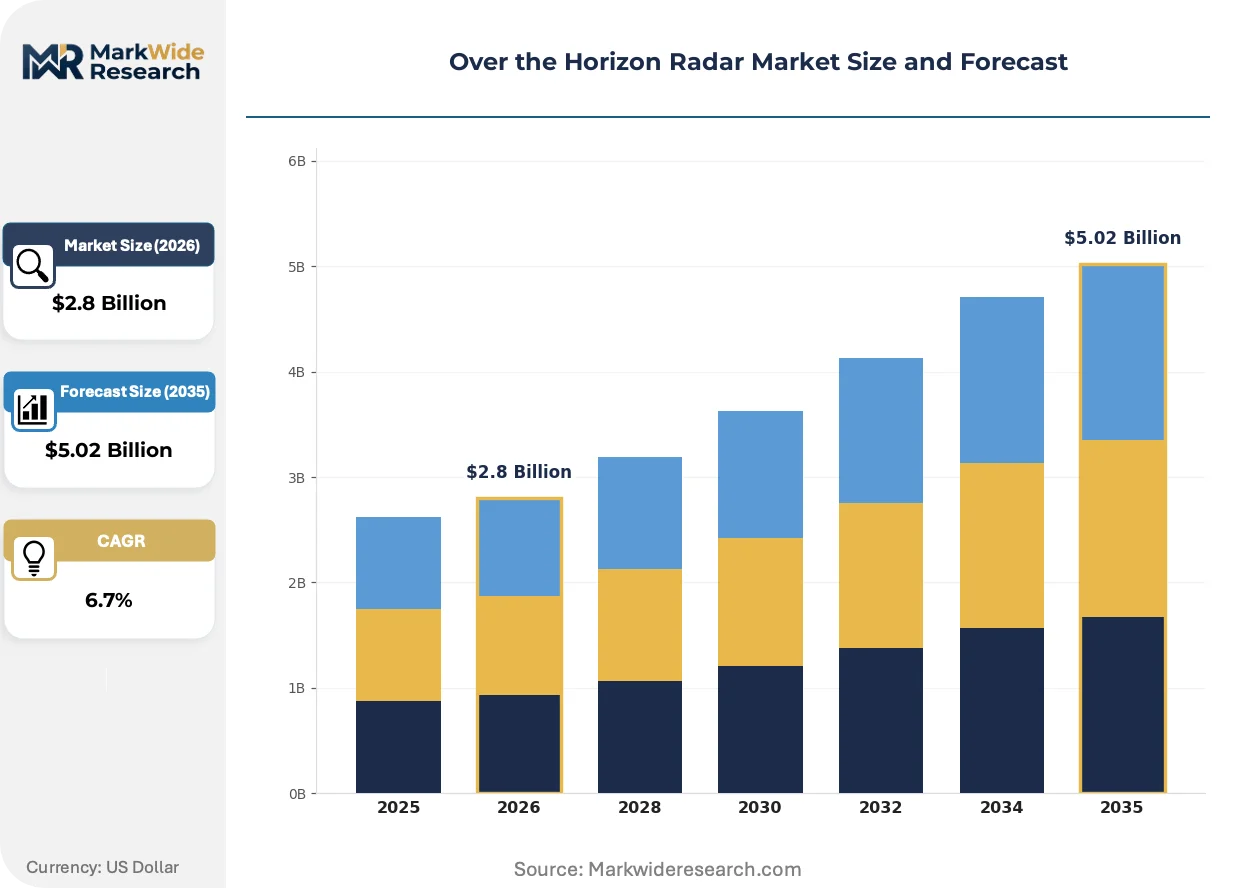
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surface Wave Radar, Airborne Radar, Maritime Radar, Ground-based Radar End User: Defense Agencies, Commercial Shipping, Aerospace Sector, Research Institutions Technology: Phased Array, Doppler Radar, Frequency Modulated Continuous Wave, Passive Radar Application: Coastal Surveillance, Border Security, Search and Rescue, Weather Monitoring |
| Companies Covered | Lockheed Martin Corporation, Raytheon Technologies Corporation, Northrop Grumman Corporation, BAE Systems, Thales Group, Leonardo S.p.A., Saab AB, Israel Aerospace Industries, L3Harris Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Over the Horizon Radar Market Evolving Landscape
Active electronically scanned arrays are displacing mechanically rotated systems across defense procurement portfolios. This technology transition is compressing beam steering latency while expanding simultaneous target tracking capacity.
Digital beamforming is electrifying radar signal processing by replacing analog phase shifters with software-controlled element weighting. The US Department of Defense and allied Pacific navies are accelerating procurement of digitally configurable arrays. This transition is electrifying competitive positioning toward suppliers with captive semiconductor fabrication capabilities.
Australia's Defence Science and Technology Group interoperability certifications are mandating standardized data formats for coastal surveillance networks. This regulatory framework is forcing European and North American exporters to redesign interface protocols prior to market entry. Naval forces across Southeast Asia are delaying procurement decisions pending certification alignment.
Defense ministries are unbundling discrete radar purchases in favor of system-of-systems contracts spanning detection, communications, and command layers. Prime contractors are absorbing subsystem suppliers to capture integrated program margins. This consolidation is most visible in Japan and South Korea, where maritime surveillance budgets are concentrating among three national champions.
Over the Horizon Radar Market Segmentation
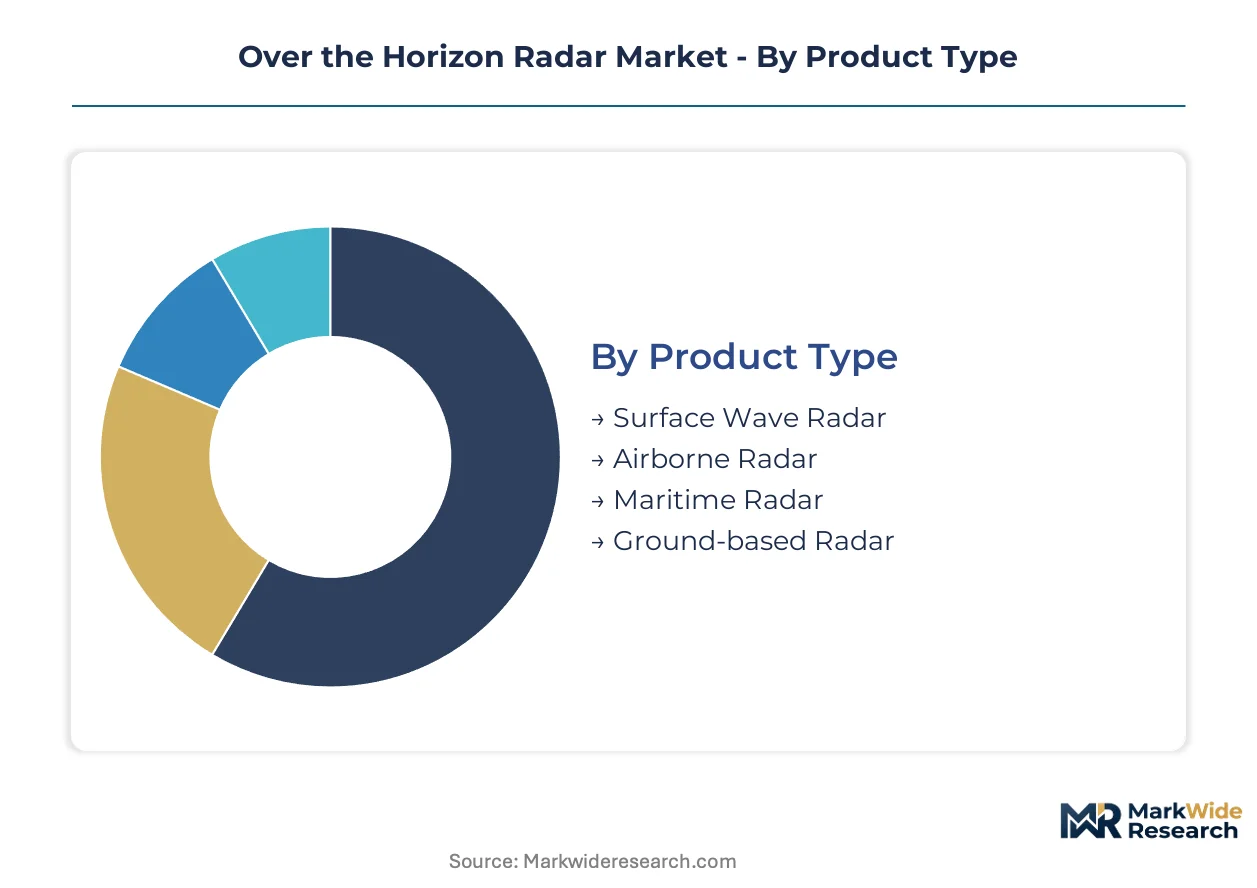
Over the horizon radar procurement varies sharply across product configurations, with certification requirements from Australia's DSTG and interoperability mandates from NATO shaping supplier eligibility. Defense ministries prioritize segments offering sovereign control and spectrum resilience, while commercial end-users face stricter electromagnetic compatibility thresholds under EU CE marking frameworks.
Product Type:
Australia's DSTG interoperability certifications and US NTIA frequency allocations impose divergent hardware standards across product categories, with ground-based installations facing the most stringent sovereign territory verification protocols.
- Ground-based Radar:Fixed installations exploit ionospheric reflection or surface wave propagation in the 3-30 MHz band, achieving detection ranges of 500-3,000 nautical miles. Defense agencies in Australia and Japan dominate procurement, driven by persistent wide-area surveillance requirements for early warning against aircraft and missile threats where mechanical rotation systems once prevailed.
- Airborne Radar:Naval forces deploy platform-integrated variants to close mobile coverage gaps, with beam steering latency compression enabling rapid repositioning. South Korea's maritime patrol programs and US Navy distributed sensing architectures concentrate demand, as territorial disputes across the East and South China Seas accelerate fleet modernization timelines.
- Surface Wave Radar:High-frequency surface wave systems extend vessel tracking ranges without ionospheric dependency, reducing operational complexity for coastal monitoring.
- Maritime Radar:Ship-mounted configurations integrate with command infrastructure for fleet-level situational awareness, subject to NATO interoperability standards.
Ground-based Radar leads this category by volume. Airborne Radar is expanding most quickly as naval procurement prioritizes mobility.
End User:
Defense ministries command premium pricing tiers through integrated system-of-systems contracts, while research institutions and commercial operators navigate compressed margins under civilian spectrum-sharing agreements.
- Defense Agencies:Sovereign control requirements and persistent surveillance mandates drive capital deployment, with Australia's coastal surveillance networks and Japan's maritime boundary monitoring programs representing concentrated demand centers. Procurement consolidates around bundled detection, communications, and command layers rather than discrete radar units.
- Commercial Shipping:Fleet operators adopt over-the-horizon capabilities for route optimization and threat avoidance, constrained by FCC and NTIA frequency allocation standards that limit civilian encroachment on military HF bands.
- Aerospace Sector:Platform integrators seek lightweight, software-defined architectures for unmanned surveillance applications.
- Research Institutions:Universities and national laboratories pursue passive radar architectures to minimize electromagnetic signatures, compressing margins for active system suppliers.
Defense Agencies capture the deepest revenue pools. Research Institutions are gaining share fastest through low-signature technology development.
Technology:
Semiconductor fabrication capabilities determine competitive positioning, with captive foundry access enabling rapid transition from analog phase shifters to software-controlled element weighting.
- Phased Array:Active electronically scanned arrays displace mechanically rotated systems by enabling rapid beam steering without physical antenna movement. The US Department of Defense and allied Pacific navies accelerate procurement of digitally configurable arrays, with simultaneous target tracking capacity expansion driving premium positioning.
- Passive Radar:Research institutions favor lower electromagnetic signature architectures that exploit third-party illuminators, reducing detectability in contested environments but constraining supplier margins through simplified hardware requirements.
- Doppler Radar:Velocity measurement capabilities support moving target indication for air defense applications.
- Frequency Modulated Continuous Wave:Compact implementations suit short-range coastal monitoring with reduced peak power requirements.
Phased Array dominates technology revenue. Passive Radar shows the steepest expansion trajectory among emerging architectures.
Application:
Coastal surveillance procurement concentrates in disputed maritime zones, with certification alignment delays affecting Southeast Asian naval modernization schedules.
- Coastal Surveillance:Persistent monitoring of territorial waters and exclusive economic zones drives installation across Australia's northern approaches and Japan's southwestern islands. Australia's DSTG mandates standardized data formats, forcing European and North American exporters to redesign interface protocols prior to market entry.
- Border Security:Land-based over-the-horizon systems monitor remote air corridors and littoral approaches where conventional radar geometry fails, with South Korea prioritizing integration with existing command infrastructure.
- Search and Rescue:Wide-area coverage supports detection of distressed vessels and aircraft across vast ocean expanses.
- Weather Monitoring:Ionospheric research applications leverage existing HF infrastructure for atmospheric science.
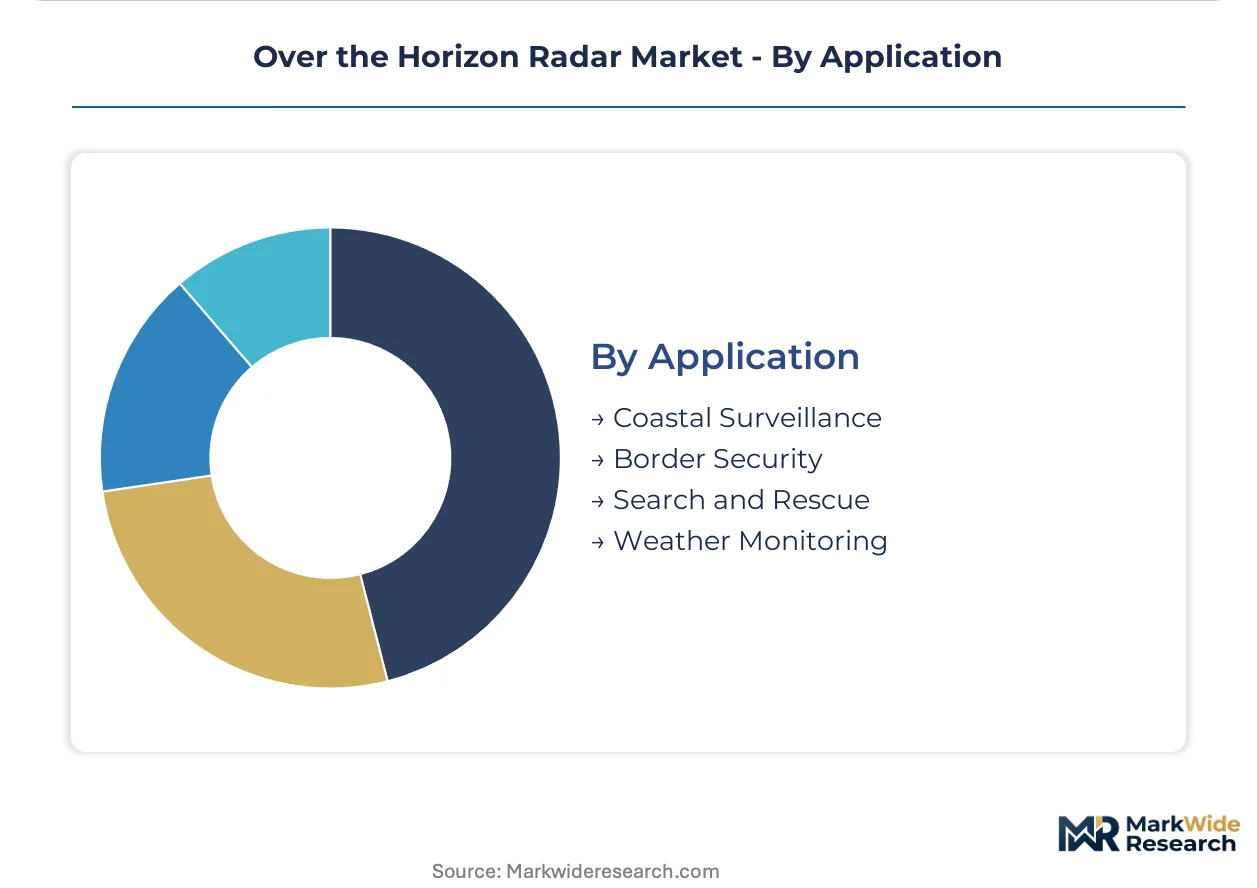
Coastal Surveillance leads application demand. Border Security is climbing the fastest as territorial tensions intensify procurement urgency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement concentrates in coastal nations confronting maritime boundary disputes, with system-of-systems contracts replacing discrete radar purchases. Sovereign control requirements and spectrum allocation frameworks shape supplier eligibility across national markets.
United States
The Department of Defense accelerates phased array procurement for Pacific theater coverage, with distributed sensing architectures closing mobile gaps. NTIA and FCC frequency standards constrain civilian encroachment on military HF bands, preserving operational spectrum for early warning networks. Naval installations in Virginia and California anchor ground-based deployment timelines.
Australia
Coastal surveillance networks across northern approaches drive persistent wide-area monitoring requirements for exclusive economic zone protection. DSTG interoperability certifications mandate standardized data formats, forcing foreign exporters to redesign interface protocols prior to market entry. Darwin and Cairns concentrate installation activity as maritime patrol priorities intensify.
Japan
Southwestern island chains prioritize integrated command infrastructure for territorial water monitoring against regional air and vessel threats. METI industrial standards align defense electronics procurement with domestic semiconductor fabrication capabilities. Okinawa and Kyushu host primary system installations supporting layered defense architectures.
South Korea
Maritime patrol programs modernize fleet capabilities to address intensifying East China Sea disputes, with airborne variants gaining procurement priority. National champions consolidate bundled detection and communications contracts under sovereign technology development mandates. Busan-Ulsan industrial corridors concentrate manufacturing partnerships for platform-integrated systems.
United Kingdom
BAE Systems anchors domestic supply chains for NATO interoperability compliance, with backward integration into semiconductor packaging reducing foreign component dependencies. CE marking frameworks streamline electromagnetic compatibility certification for cross-border European sales. Scotland and South England concentrate research activity in software-defined signal processing architectures.
Over the Horizon Radar Market Competitive Landscape
System-of-systems bundling dominates the current landscape as defense ministries consolidate procurement around integrated surveillance architectures rather than discrete radar units. The vendor base separates into three tiers: prime contractors with layered defense portfolios, specialized radar technology houses, and platform integrators seeking captive detection capabilities. Prime contractors absorb subsystem suppliers to capture integrated program margins. Technology licensing and strategic partnerships represent the dominant competitive moves as firms seek semiconductor fabrication access.
Within the prime contractor tier, Lockheed Martin Corporation and Raytheon Technologies Corporation exemplify bundled portfolio strategies that combine over-the-horizon detection with satellite networks and command infrastructure. Northrop Grumman Corporation occupies a specialist position in software-defined architectures that compress hardware refresh cycles. These three US-based corporations anchor competitive positioning through sustained access to Department of Defense procurement channels and allied Pacific navy modernization programs.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Raytheon Technologies Corporation |
| Northrop Grumman Corporation |
| BAE Systems |
| Thales Group |
| Leonardo S.p.A. |
| Saab AB |
| Israel Aerospace Industries |
| L3Harris Technologies |
| Others |
Value Network & Pricing Analysis
Ionospheric physics specialists concentrated in Australia and the United States command wage premiums that compress margins for active electronically scanned array suppliers while widening spreads between premium bundled system-of-systems contracts and unbundled hardware-only transactions. Labor-cost differentials between sovereign certification-required installations and commercial off-the-shelf alternatives stratify pricing tiers across defense procurement channels.
Pricing Analysis
Extended warranty and through-life service commitments anchor premium-tier contracts for Australia's DSTG-certified coastal surveillance networks, while unbundled hardware-only purchases dominate research institution procurement. Three-tier pricing structure across premium, standard, and economy levels separates integrated detection-communications-command packages from standalone radar units and passive architecture components. Cost compression in the economy tier is intensifying because semiconductor fabrication constraints limit captive foundry access for smaller suppliers. Defense agencies exhibit lowest price sensitivity due to sovereign control mandates, while commercial shipping operators face acute pressure from FCC and NTIA frequency allocation compliance costs.
Supply Chain Analysis
Australia's DSTG interoperability certifications and Japan's METI industrial standards gate supplier eligibility through mandatory interface protocol redesigns and domestic semiconductor fabrication requirements. Active electronically scanned array production draws from Taiwan, South Korea, and the United States for gallium nitride substrate supply and advanced packaging capabilities. Gallium nitride wafers, high-frequency power amplifiers, and software-defined radio chipsets constitute critical input dependencies. Single-source vulnerability concentrates in Taiwan's foundry capacity for military-grade semiconductor fabrication. Distribution runs through prime contractor system-of-systems bundling rather than discrete component channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance narrative where Australia's DSTG certification mandates and NATO interoperability standards erect barrier-to-entry moats favoring incumbent prime contractors with established sovereign relationships and captive semiconductor access.
For Market Incumbents: Hedge against passive radar substitution threats by accelerating software-defined signal processing R&D investments that compress hardware refresh cycles. Absorb specialized HF propagation engineering firms to lock in aging ionospheric physics talent pools. Prioritize backward integration into gallium nitride semiconductor packaging to reduce Taiwan foundry dependency exposure.
For New Entrants and Emerging Players: Begin with airborne radar platform integration opportunities in South Korea's maritime patrol modernization programs, where mobility requirements outpace incumbent capacity allocation. Target research institution passive radar development contracts as the most penetrable segment given lower electromagnetic signature hardware requirements and compressed certification timelines. Pursue technology licensing partnerships with established semiconductor fabricators rather than greenfield fabrication investment.
For Investors and Strategic Acquirers: The window for entry favors mid-cap specialists with captive HF engineering talent and software-defined architecture portfolios over pure hardware manufacturers. Long-term viability hinges on spectrum-sharing framework adaptation capability as defense-commercial maritime agreements reshape system design priorities. Monitor Australia's DSTG certification queue backlogs as the signal indicating procurement timeline acceleration or delay.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Architecture Development | Compresses hardware refresh cycles for Northrop Grumman's signal processing positioning. |
| Gallium Nitride Foundry Partnership | Secures captive semiconductor supply for Raytheon's high-frequency propagation systems. |
| DSTG Certification Pre-Alignment | Accelerates Australian market entry for Thales and BAE Systems interface protocol investments. |
| Airborne Platform Integration | Captures South Korean naval mobility requirements through Lockheed Martin's layered defense bundling. |
| Passive Radar Technology Licensing | Enables research institution market penetration with lower electromagnetic signature architectures. |
Research Methodology
Document review covered defense procurement databases, FCC and NTIA frequency allocation filings, and Australia's DSTG interoperability certification records, complemented by interviews with radar system program executives, HF propagation engineering specialists, defense ministry procurement officers, and semiconductor fabrication supply managers. Secondary validation drew from Department of Defense budget justification documents, NATO standardization agreements, METI industrial policy briefings, and customs trade data for high-frequency electronic component flows. Bottom-up unit economics triangulated against top-down defense budget allocation analysis.
Cross-referencing historical procurement patterns with expert panel input on technology transition timelines shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product configuration, end-user category, technology architecture, and application purpose alongside regional regulatory cluster differentiation. CAGRs were synthesized through iterative reconciliation of volume deployment trajectories and value-per-unit trends informed by ionospheric propagation reliability indices and phased array beam steering latency benchmarks.
Underlying measurement precision varies by segment; ground-based installations with established sovereign territory verification protocols carry tighter precision than airborne variants subject to platform integration timeline uncertainty. Forecasts reflect assumptions regarding spectrum-sharing agreement progression and HF engineering workforce replenishment rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Navigation & Surveillance
Global X-Band Radar Market
Communication Navigation & Surveillance
Spain Satellite Communications Market
Communication Navigation & Surveillance
Radar Transmitter Market
Communication Navigation & Surveillance
UWB Anchor Market
Communication Navigation & Surveillance
Airborne SATCOM Market
Communication Navigation & Surveillance
High Frequency Military Communications Market
Communication Navigation & Surveillance
Tactical Radio Market
Communication Navigation & Surveillance
Autonomous Navigation Processing Unit Market
Communication Navigation & Surveillance
Global Navigation Satellite System (GNSS) Market
Communication Navigation & Surveillance
Infrared Search and Track (IRST) System Market
Communication Navigation & Surveillance
Tactical Communications Market
Communication Navigation & Surveillance
Defense Communication System Market
Communication Navigation & Surveillance
Missile Guidance Radar Market
Communication Navigation & Surveillance
Latin America Inertial Systems Market
Communication Navigation & Surveillance
Navigational Inertial Systems Market
Communication Navigation & Surveillance
Navigation Satellite System Technology Market