
 Spain Satellite Communications Market | 2026-2036
Spain Satellite Communications Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Satellite Communications Market Insights
Spain is tilting its satellite infrastructure investments toward sovereign capabilities and Iberian Peninsula coverage resilience. Hispasat anchors transatlantic and Latin American connectivity routes through its GEO fleet positioned at strategic orbital slots. Thales Alenia Space España leverages Spanish manufacturing heritage to compete for European institutional payloads and export programs. Indra sustains defense-grade ground systems integration, supplying encrypted command-and-control terminals to national security clients.
Satellite communications encompasses the transmission, relay, and reception of radio frequency signals via orbiting spacecraft operating in L-band through Ka-band frequencies, with link budgets engineered to overcome free-space path loss over 35,786 kilometers for geostationary orbits. The primary commercial purpose is to deliver connectivity where terrestrial fiber and cellular infrastructure prove economically unviable or physically impossible. Data services and broadcasting occupy the largest revenue pools within service type segments, reflecting enterprise cloud backhaul and direct-to-home television distribution. LEO technology is expanding fastest among orbital architectures, driven by latency-sensitive IoT and maritime tracking contracts that GEO constellations cannot fulfill.
Spain's national regulator, the Centro Nacional de Vigilancia Espacial, coordinates spectrum allocation with ITU filings while the Ministry of Defense classifies military satellite procurement under NATO-compatible encryption standards. The EU Space Programme and its GOVSATCOM initiative are reshaping how Spanish agencies access secure bandwidth, favoring European-flagged operators over non-regional providers. Stakeholders must monitor whether Madrid accelerates domestic launch service procurement or continues relying on French Guiana and foreign ride-share missions for national payload deployment.
Market Dynamics
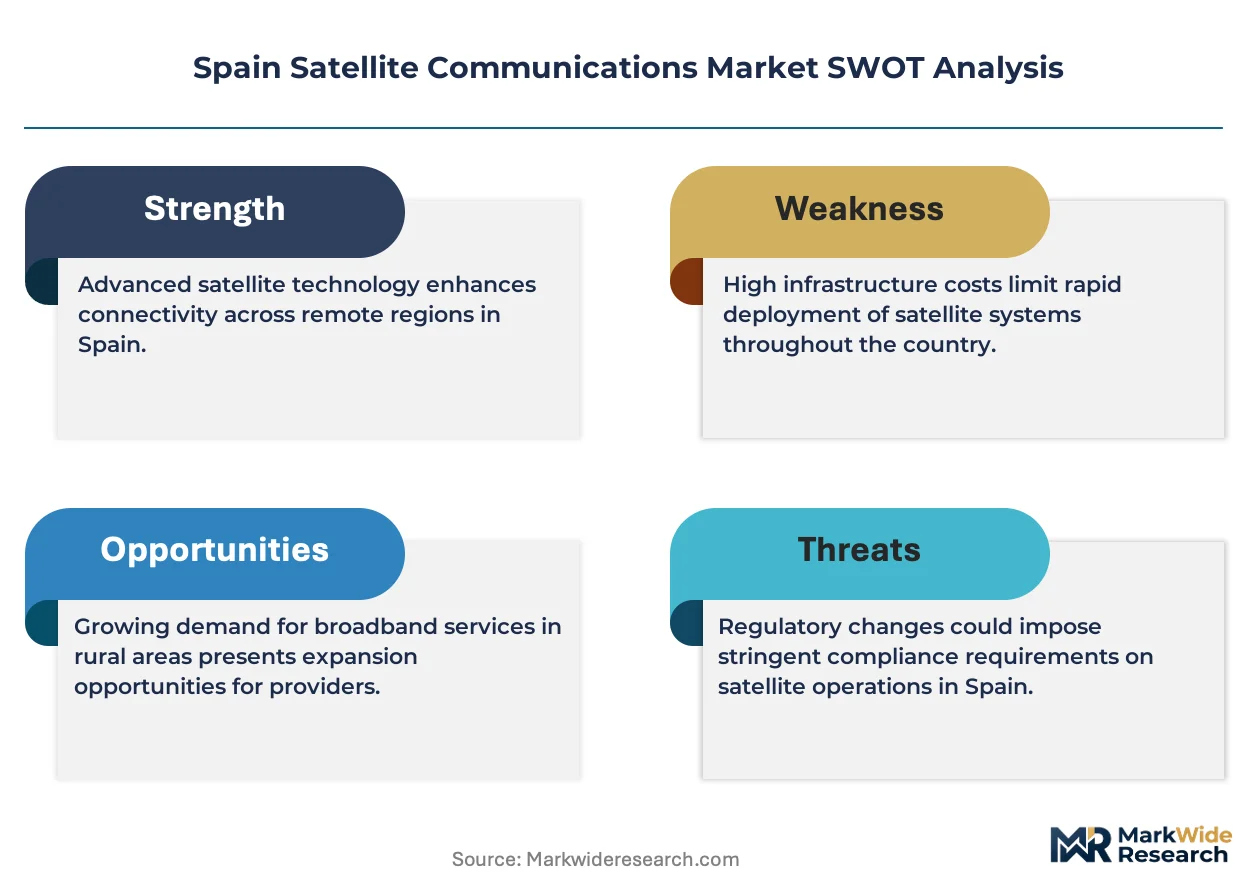
Spain's satellite communications sector faces a structural pivot as sovereign bandwidth requirements collide with the EU Space Programme's GOVSATCOM integration mandates, forcing domestic operators to requalify procurement channels and ground segment architectures.
Growth Catalysts
- EU GOVSATCOM Framework:The initiative redirects Spanish defense and civil agency bandwidth procurement toward European-flagged operators, creating preferential access conditions for Madrid-based service providers.
- Earth Observation Budget Reallocation:ESA funding directives are channeling national space budgets into sovereign satellite infrastructure, expanding domestic manufacturing and ground segment engineering capacity.
- LEO Constellation Proliferation:Low-latency orbital architectures are capturing maritime tracking and IoT connectivity contracts that legacy GEO networks cannot fulfill, opening new service verticals for Spanish integrators.
Market Restraints
- Launch Access Concentration:Spain lacks domestic orbital launch capability, forcing payload deployment reliance on French Guiana's CSG facility and foreign ride-share missions, creating schedule and cost vulnerabilities.
- Spectrum Coordination Friction:ITU filing backlogs and cross-border interference disputes with Portuguese and French orbital neighbors extend licensing timelines for new satellite deployments.
- Terrestrial Fiber Substitution:Subsea cable expansions across the Mediterranean and Atlantic are eroding price premiums for satellite backhaul in coastal enterprise markets.
Strategic Opportunities
- Andalusian Ground Segment Cluster:Seville-to-Cádiz aerospace corridors offer underutilized manufacturing and test facilities for export-oriented antenna and terminal production.
- Quantum Key Distribution Integration:Convergence of optical satellite links with quantum cryptography protocols positions Spanish research institutes to capture next-generation secure communications contracts.
- Canary Islands Teleport Expansion:Equatorial-adjacent latitude and existing fiber landing stations create optimal conditions for Atlantic-spanning gateway infrastructure serving African and Latin American routes.
Industry Challenges
- RF Engineering Talent Scarcity:Madrid and Barcelona clusters compete for limited domestic microwave and phased-array antenna specialists, forcing recruitment from Toulouse and Milan aerospace pools.
- NATO Interoperability Certification:Military terminal approvals require dual-track validation through Spain's Ministry of Defense and Allied communications authorities, extending product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Satellite Communications Market |
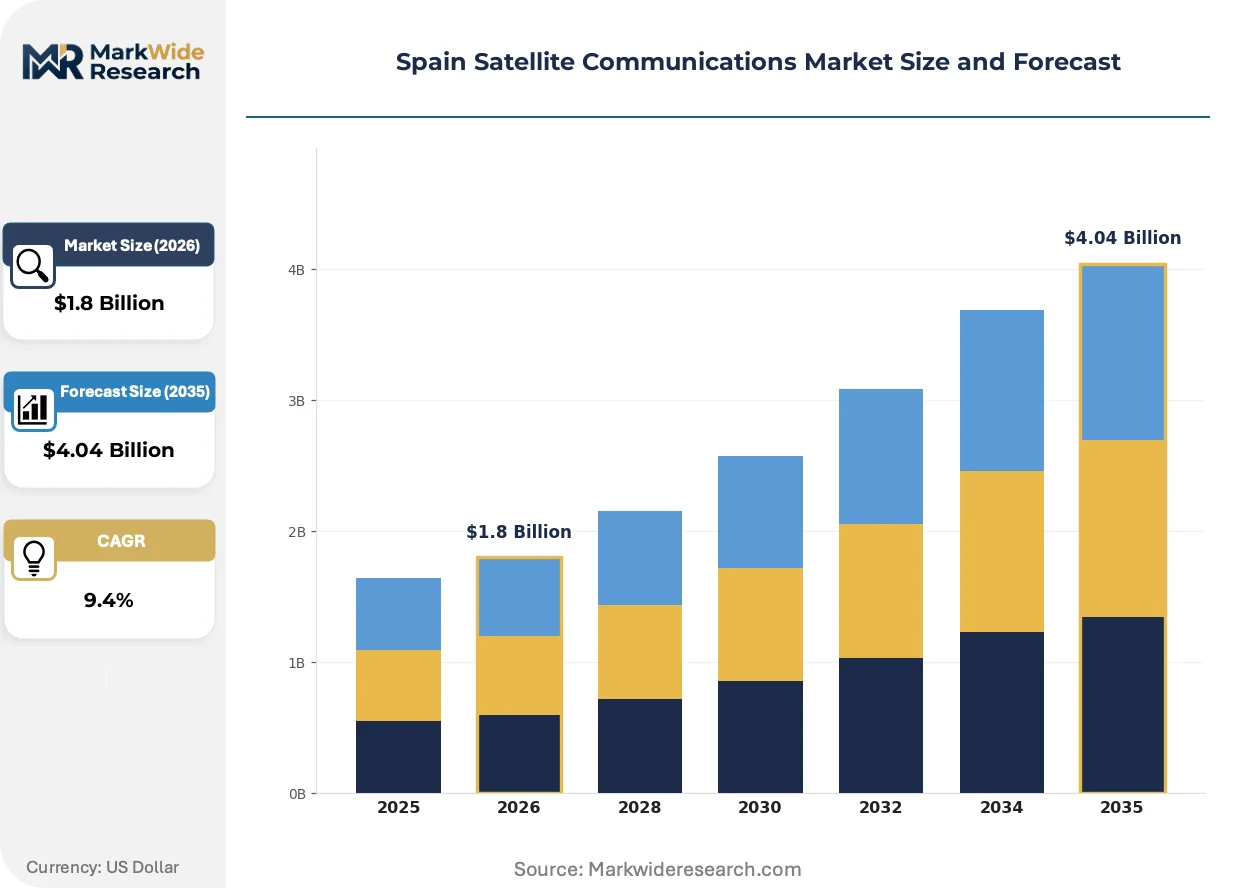
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Data Services, Voice Services, Video Services, Broadcasting Technology: LEO, MEO, GEO, HTS Application: Government, Military, Maritime, Remote Sensing End User: Enterprises, Consumers, Telecommunications, Defense |
| Companies Covered | GMV, Indra, Hispasat, Satlink, Telefónica, Hisdesat Servicios Estratégicos SA, Sateliot, Telespazio S.p.A., Thales Alenia Space España, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Satellite Communications Market Trends and Innovations
Spain's satellite sector is experiencing accelerated architectural disruption as legacy geostationary models confront software-defined payload alternatives and multi-orbit service integration demands from enterprise and defense clients.
Software-defined radios (SDRs) and digital transparent processors are enabling dynamic bandwidth allocation across hybrid GEO-LEO constellations. Spanish ground system integrators are adopting these platforms to offer unified network management for maritime and aeronautical clients. The technology is migrating from experimental defense programs into commercial service catalogs, compressing hardware refresh cycles and flattening supplier margins.
Spain's national regulator, the Centro Nacional de Vigilancia Espacial, is enforcing stricter debris mitigation and end-of-life disposal requirements aligned with EU Space Traffic Management guidelines. These rules are elevating propulsion and deorbiting system costs for domestic satellite manufacturers. Small satellite builders in Madrid's aerospace corridor are responding by integrating electric propulsion earlier in design phases to maintain launch mass competitiveness.
Defense and civil agency buyers are consolidating satellite service procurement under framework agreements rather than transactional capacity leases. This concentration is squeezing independent resellers and favoring vertically integrated operators with direct spectrum access. The shift is most visible in Madrid, where national security clients now mandate encrypted command-and-control terminal bundles rather than standalone bandwidth contracts.
Spain Satellite Communications Market Segmentation
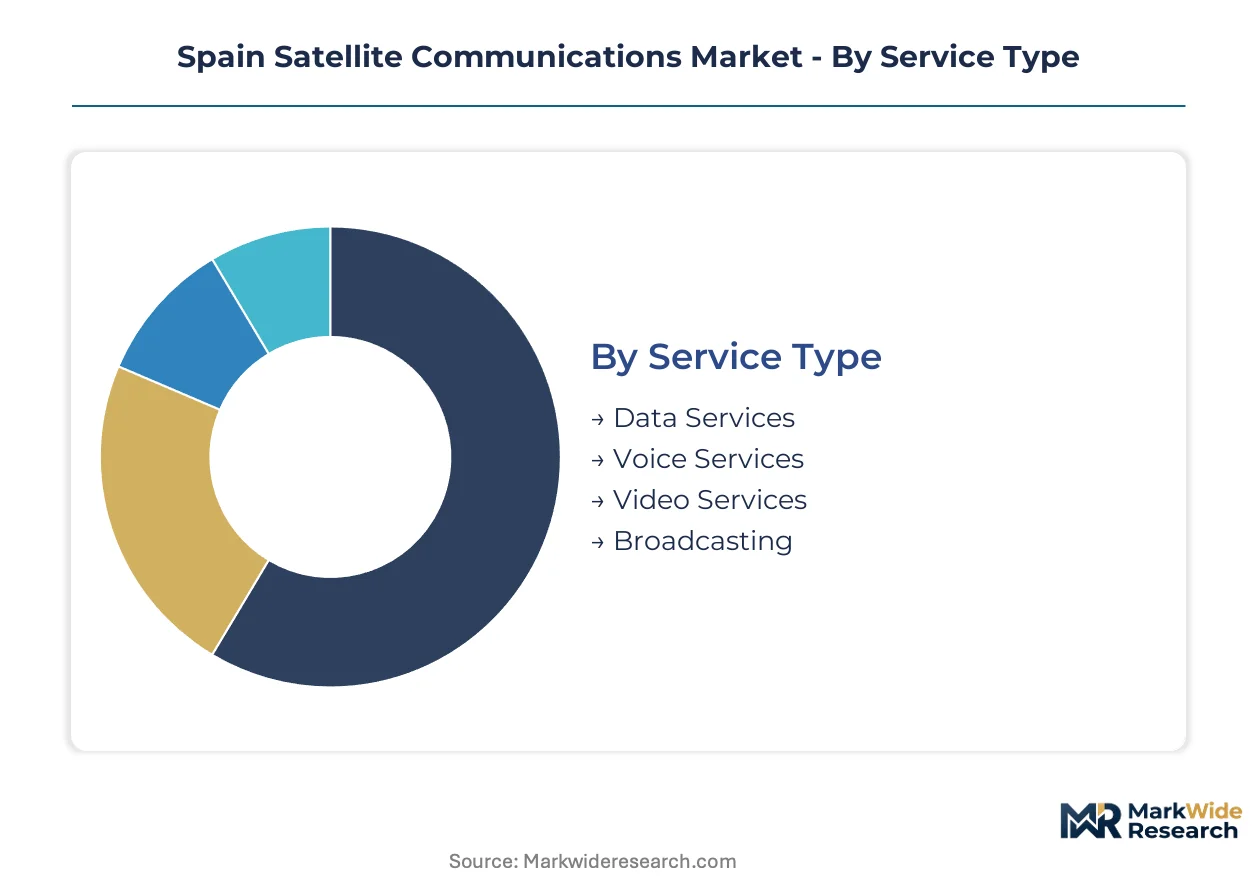
Spain's satellite communications market segments along four operational dimensions that shape procurement patterns and infrastructure deployment priorities. Service type and technology architecture determine capital intensity and margin structures, while application and end-user categories dictate regulatory compliance requirements and security protocols.
Service Type:
The use-case spectrum spans enterprise backhaul, consumer broadband, secure government channels, and mass-market broadcasting distribution.
- Data Services:Enterprise cloud connectivity and IoT backhaul dominate commercial deployments, with Madrid-based financial institutions and logistics operators driving contracted bandwidth growth. Maritime fleet operators along Barcelona and Bilbao ports are migrating from legacy VSAT to managed data service bundles.
- Broadcasting:Direct-to-home television distribution retains substantial subscriber bases across rural Castile-La Mancha and Extremadura regions where terrestrial infrastructure remains sparse. Content licensing costs and orbital slot access fees compress margins for regional platform operators.
- Voice Services:Narrowband satellite telephony serves emergency response agencies and remote construction camps in Aragon and the Pyrenees.
- Video Services:Occasional-use satellite news gathering and event contribution feeds support broadcasters covering regional political and sporting events.
The dominant share belongs to Data Services, while Broadcasting is closing the gap fastest through hybrid satellite-OTT platform integration.
Technology:
Cost tier differentiation separates legacy geostationary assets from emerging low-latency constellations requiring ground segment reinvestment.
- GEO:Geostationary platforms at 35,786 kilometers deliver proven reliability for broadcast distribution and maritime connectivity. Hispasat's orbital slots at 30°W and 61°W anchor transatlantic traffic, though latency limitations exclude financial trading and real-time gaming applications.
- LEO:Low Earth orbit constellations at 550-1,200 kilometer altitudes enable sub-50 millisecond latency for autonomous shipping and connected vehicle trials in Catalonia's automotive test corridors. Ground station density requirements and frequency coordination complexity elevate operational costs versus GEO equivalents.
- MEO:Medium Earth orbit systems balance coverage footprint with latency performance for government trunking networks.
- HTS:High-throughput satellite spot-beam architectures multiply spectral efficiency for cellular backhaul in Andalusian tourist corridors.
GEO retains installed base dominance, though LEO is expanding most quickly through maritime and mobility service contracts.
Application:
Customer type concentration shapes procurement sophistication, with defense and government buyers demanding sovereign control over civilian maritime and environmental monitoring segments.
- Military:Encrypted tactical communications and beyond-line-of-sight datalinks for NATO-interoperable forces drive classified procurement through Spain's Ministry of Defense. GOVSATCOM framework integration mandates European-flagged operator preference for new bandwidth awards.
- Government:Civil agency networks for emergency management and rural connectivity rely on framework agreements rather than spot-market capacity leasing. The Centro Nacional de Vigilancia Espacial coordinates spectrum allocation for national security missions.
- Maritime:Commercial shipping fleets operating from Valencia and Algeciras container terminals require continuous connectivity for crew welfare and engine telemetry.
- Remote Sensing:Earth observation payload downlink and command uplink services support ESA-funded climate monitoring programs.
Military applications command premium pricing tiers, while Maritime is gaining share fastest through IoT-enabled fleet management adoption.
End User:
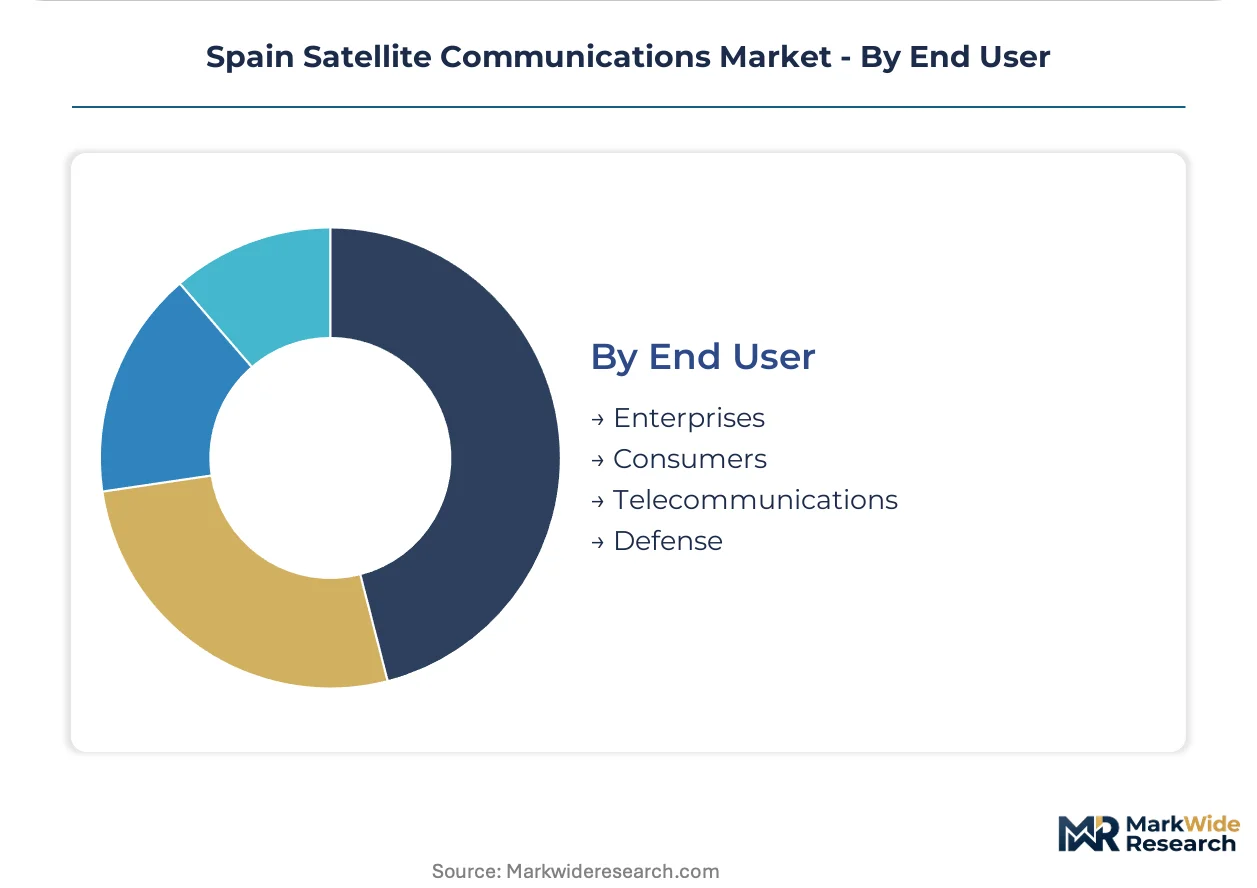
Volume concentration among enterprise accounts contrasts with fragmented consumer acquisition economics and specialized defense procurement channels.
- Enterprises:Mining operations in Asturias, renewable energy farms in Castile and León, and retail banking networks in secondary cities purchase managed connectivity services with guaranteed service level agreements. Multi-site corporations favor hybrid terrestrial-satellite failover architectures.
- Defense:National security clients mandate encrypted terminal bundles and sovereign ground segment control, consolidating procurement under multi-year framework agreements that exclude independent resellers.
- Telecommunications:Mobile network operators deploy satellite backhaul for rural base stations in Galicia and Cantabria mountain regions.
- Consumers:Residential broadband subscribers in disconnected municipalities represent price-sensitive demand with high churn susceptibility.
Enterprises generate the dominant revenue share, while Defense is climbing the fastest through GOVSATCOM-mandated procurement restructuring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain's satellite communications infrastructure concentrates in Madrid's aerospace corridor, where ground segment engineering clusters serve both domestic defense procurement and export contracts across the Iberian Peninsula and Atlantic routes.
Madrid
Madrid anchors Spain's sovereign satellite capabilities through the Centro Nacional de Vigilancia Espacial and concentrated defense procurement channels. The Ministry of Defense classifies military satellite bandwidth under NATO-compatible encryption standards, directing classified contracts to Madrid-based integrators. The city's aerospace corridor sustains RF engineering talent pools and ground system manufacturing for Hispasat and Thales Alenia Space España operations.
Catalonia
Catalonia's maritime economy drives commercial satellite demand through Barcelona and Tarragona port operations requiring continuous fleet connectivity. The regional government participates in EU Space Programme initiatives, aligning local aerospace research with GOVSATCOM framework requirements. Barcelona hosts satellite IoT development for autonomous shipping trials in automotive test corridors.
Andalusia
Andalusia offers underutilized manufacturing capacity in the Seville-to-Cádiz aerospace corridor for export-oriented antenna and terminal production. The region's Atlantic coastline positions Algeciras and Cádiz as maritime connectivity hubs for container shipping routes to Latin America. Local engineering institutes collaborate with Madrid contractors on ground segment component manufacturing.
Basque Country
Basque Country's industrial base generates enterprise satellite demand from mining operations and renewable energy installations requiring remote connectivity failover. Bilbao's port authority contracts managed VSAT services for vessel traffic management and crew welfare systems. Regional technology centers support RF component testing for defense-grade terminal integration.
Canary Islands
Canary Islands provide equatorial-adjacent latitude optimal for Atlantic-spanning gateway infrastructure serving African and Latin American routes. Existing fiber landing stations on Tenerife and Gran Canaria enable hybrid terrestrial-satellite backhaul for submarine cable redundancy. The archipelago's geographic isolation sustains dedicated satellite broadband demand from residential and tourism sectors.
Spain Satellite Communications Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying RF subsystems and antenna assemblies to prime contractors. Spain's satellite communications sector exhibits moderate consolidation around vertically integrated operators with direct spectrum access and sovereign ground segment control. Three archetypes dominate: national flag carriers with orbital slot holdings, defense-focused system integrators with NATO certification pathways, and emerging LEO constellation operators targeting IoT verticals. Competitive dynamics center on framework agreement capture for government bandwidth procurement and ground station network densification for multi-orbit service delivery.
Among Madrid-based platform operators, Hispasat anchors transatlantic connectivity through geostationary orbital positions, while Hisdesat Servicios Estratégicos SA occupies a position within the sovereign defense services tier. Indra exemplifies the defense system integrator archetype, supplying encrypted command-and-control terminals to national security clients under Ministry of Defense procurement channels. These three entities represent the core competitive structure through which EU GOVSATCOM mandates are being operationalized in the Spanish market.
| Leading Market Players |
|---|
| GMV |
| Indra |
| Hispasat |
| Satlink |
| Telefónica |
| Hisdesat Servicios Estratégicos SA |
| Sateliot |
| Telespazio S.p.A. |
| Thales Alenia Space España |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Madrid's RF engineering clusters drives aggressive talent recruitment from Toulouse and Milan aerospace pools, compressing supplier margins while elevating pricing power for ground segment integrators with captive technical workforces.
Pricing Analysis
The EU GOVSATCOM Framework dictates the pricing tier structure across Spanish satellite communications procurement, mandating European-flagged operator preference that stratifies pricing across sovereign-certified, dual-use, and commercial tiers. NATO interoperability certification and encrypted terminal bundling differentiate premium defense contracts from standard civil agency frameworks. Cost compression in commercial maritime connectivity intensifies as LEO constellation operators undercut legacy GEO pricing for IoT backhaul contracts. Consumer broadband subscribers in Castile-La Mancha exhibit highest price sensitivity, while national security clients accept premium positioning for sovereign ground segment control.
Supply Chain Analysis
Thales Alenia Space España and Indra hold dominant contract manufacturing capacity for defense-grade terminals and encrypted command-and-control systems. Component sourcing draws from France for digital transparent processors, Italy for phased-array antenna subsystems, and Germany for precision RF components. Gallium nitride amplifiers, radiation-hardened integrated circuits, and carbon fiber composite structures constitute critical input dependencies. Single-source vulnerability concentrates in French Guiana launch access, where CSG facility scheduling constraints create deployment bottlenecks for Madrid-based payload integrators. Distribution runs through Ministry of Defense procurement channels for classified contracts and framework agreements for civil agency bandwidth leasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's satellite communications sector is emerging from a procurement cycle trough as EU GOVSATCOM mandate implementation accelerates sovereign bandwidth requalification and ground segment reinvestment.
For Market Incumbents: Entrench framework agreement capture by deepening sovereign ground segment control through Canary Islands teleport infrastructure expansion. Accelerate electric propulsion integration in small satellite designs to preempt debris mitigation cost escalation from Centro Nacional de Vigilancia Espacial enforcement. LEO constellation proliferation threatens GEO-dominant revenue pools; backward integration into RF component manufacturing insulates margin pressure from Toulouse talent poaching. For New Entrants and Emerging Players: Establish a beachhead in maritime IoT connectivity for autonomous shipping trials operating from Barcelona and Tarragona ports. Target Andalusian aerospace corridor manufacturing partnerships for export-oriented antenna production serving Latin American routes. GOVSATCOM-mandated procurement restructuring opens white-space in civil agency emergency management networks previously locked to legacy operators. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated operators with direct spectrum access and multi-year defense framework agreements. Five-to-ten year viability favors Madrid-based platform operators with orbital slot holdings and NATO certification pathways. Monitor EU Space Programme budget allocations to ESA Earth observation directives as sovereign infrastructure spending inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Quantum Key Distribution Integration | Spanish research institutes capture next-generation secure communications contracts through optical satellite link convergence. |
| Canary Islands Teleport Expansion | Equatorial-adjacent latitude enables Atlantic-spanning gateway infrastructure for African and Latin American routes. |
| Andalusian Ground Segment Cluster Development | Seville-to-Cádiz aerospace corridors absorb export-oriented antenna manufacturing from capacity-constrained Madrid clusters. |
| LEO Constellation Ground Station Densification | Hybrid GEO-LEO service integration demands unified network management platforms for maritime and aeronautical clients. |
| Software-Defined Payload Migration | Digital transparent processors enable dynamic bandwidth allocation that compresses hardware refresh cycles across defense programs. |
Research Methodology
A standing panel of satellite procurement officers at Spain's Ministry of Defense, ground segment engineering directors at Madrid aerospace corridor firms, maritime fleet connectivity managers at Valencia and Algeciras terminals, and Centro Nacional de Vigilancia Espacial spectrum coordinators provided ongoing calibration across primary interview rounds. Secondary validation drew from EU Space Programme implementation documents, ESA funding directive disclosures, NATO standardization agreements, ITU satellite network filings, and Spanish national budget appropriations for space infrastructure. Bottom-up service provider revenue aggregation triangulated against top-down national space spending allocation models.
Scenario bracketing anchored projections across baseline, accelerated GOVSATCOM adoption, and delayed sovereign launch capability development pathways. Segmentation dimensions modeled encompass service type, orbital architecture, application category, and end-user procurement sophistication across the projection horizon. CAGRs derived from satellite bandwidth demand elasticity functions calibrated to maritime IoT deployment curves and defense procurement cycle phasing. Forecast inputs incorporated ESA Earth observation budget reallocation trajectories and LEO constellation gateway deployment timelines.
Sensitivities concentrate around French Guiana launch access disruptions, ITU filing backlog resolution timelines, and subsea cable substitution rates for Mediterranean enterprise backhaul. Forecasts embed assumptions regarding EU GOVSATCOM framework enforcement consistency and NATO interoperability certification pathway stability. Quarterly review of ESA ministerial council funding decisions and Centro Nacional de Vigilancia Espacial licensing throughput metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Navigation & Surveillance
Surface Radars Market
Communication Navigation & Surveillance
Missile Guidance Radar Market
Communication Navigation & Surveillance
Man-Portable Military Communication Systems Market
Communication Navigation & Surveillance
Navigation Satellite System Technology Market
Communication Navigation & Surveillance
Asia-Pacific Autonomous Navigation Market
Communication Navigation & Surveillance
Tactical Radio Market
Communication Navigation & Surveillance
Through the Wall Radar Market
Communication Navigation & Surveillance
GNSS Smart Antenna Market
Communication Navigation & Surveillance
Flight Tracking System Market
Communication Navigation & Surveillance
Naval Tactical Communication Market
Communication Navigation & Surveillance
Radar Transmitter Market
Communication Navigation & Surveillance
Global Navigation Satellite System (GNSS) Market
Communication Navigation & Surveillance
Tactical Communications Market
Communication Navigation & Surveillance
Over the Horizon Radar Market
Communication Navigation & Surveillance
Latin America Inertial Systems Market
Communication Navigation & Surveillance
Airborne Laser Obstacle Avoidance Monitoring Systems Market