
 Synthetic Aperture Radar (SAR) Market | 2026-2036
Synthetic Aperture Radar (SAR) Market Size, Share, and Industry Trends Forecast 2026-2036
Synthetic Aperture Radar (SAR) Market Analysis
Modular payload configurations is expanding across the SAR industry as defense buyers shift from monolithic satellite platforms to distributed small-satellite constellations with interchangeable sensor packages. Northrop Grumman leverages its legacy in large-aperture radar systems to anchor high-value military contracts. Leonardo S.p.A. competes through European sovereign capacity in dual-use Earth observation programs. ICEYE specializes in microsatellite SAR with rapid revisit capabilities, dominating commercial insurance and maritime monitoring segments.
Synthetic Aperture Radar constructs high-resolution two-dimensional images by processing radar echoes collected from a moving platform, typically achieving spatial resolutions below one meter at X-band frequencies through synthetic processing of successive pulse returns. Its primary commercial purpose spans all-weather Earth observation where cloud cover and darkness disable optical sensors. Spaceborne deployment generates the dominant revenue pool given capital intensity and launch costs, while airborne systems retain margin strength in tactical military and disaster-response applications where rapid tasking flexibility outweighs orbital revisit constraints. X-band technology leads in defense and intelligence markets for fine-resolution target identification, whereas L-band penetrates vegetation and soil surfaces to serve agriculture and environmental monitoring end users.
United States procurement operates under Federal Acquisition Regulation frameworks with National Reconnaissance Office security classifications shaping vendor qualification requirements. European programs align with EU Space Programme objectives and European Defence Agency capability development plans, while ITAR restrictions govern United States technology transfer to foreign platforms. Stakeholders must monitor evolving frequency allocation disputes between commercial SAR operators and telecommunications interests at the International Telecommunication Union.
Market Dynamics
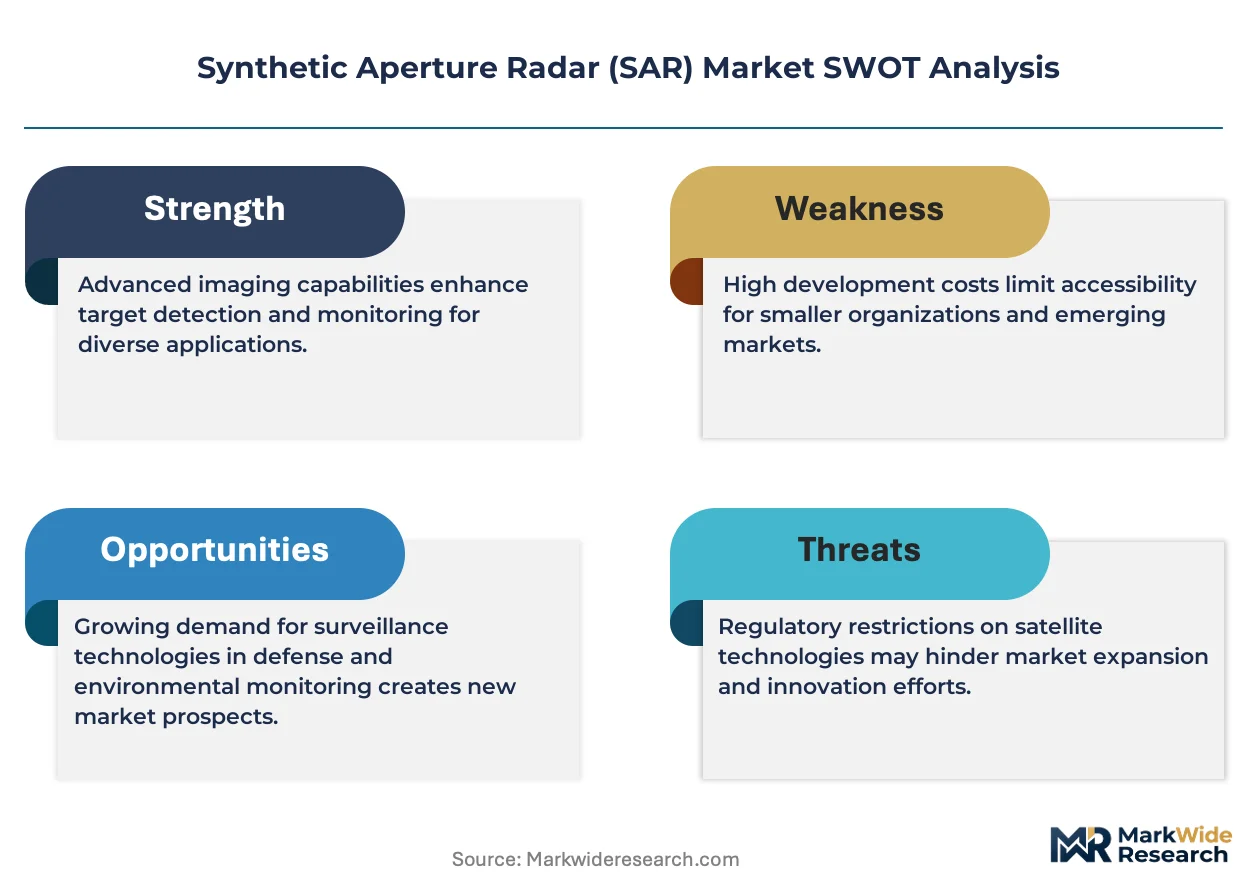
Defense ministries across NATO member states are accelerating procurement of spaceborne SAR constellations for all-weather surveillance, creating a structural pull toward distributed small-satellite architectures with rapid revisit capabilities.
Growth Catalysts
- Defense procurement frameworks:NATO capability targets and the European Defence Agency's Permanent Structured Cooperation are mandating sovereign Earth observation capacity. Member states must field national SAR assets to meet collective intelligence requirements.
- Maritime domain awareness:Coast guards and fisheries enforcement agencies require persistent monitoring of exclusive economic zones where optical sensors fail under cloud cover. SAR delivers 24/7 vessel detection and oil spill identification.
- L-band penetration:Agriculture ministries in Brazil and Canada deploy L-band SAR for soil moisture mapping beneath vegetation canopies. This frequency band enables biomass estimation and crop yield forecasting where optical imagery cannot reach.
Market Restraints
- Launch cost concentration:Access to orbit depends on a limited set of launch providers. Falcon 9 and Ariane 6 pricing volatility directly impacts constellation deployment economics for commercial operators.
- ITAR classification:United States export controls restrict X-band radar component transfers to foreign satellite platforms. Non-US manufacturers face supply chain barriers when sourcing high-performance transmit-receive modules.
- Frequency allocation disputes:Commercial SAR operators compete with terrestrial telecommunications interests at the International Telecommunication Union. Spectrum encroachment threatens operational bandwidth for C-band and X-band systems.
Strategic Opportunities
- Disaster response automation:Insurance carriers in Japan and Australia are integrating SAR-derived flood extent maps into parametric payout triggers. This eliminates claims adjustment delays following tropical cyclone landfall.
- EU Space Programme alignment:The Copernicus Expansion Missions include C-band SAR continuity and new L-band capacity. European manufacturers can anchor production through institutional anchor tenancy.
- AI inference at edge:Onboard processing architectures enable real-time change detection aboard microsatellites. This convergence of machine learning and miniaturized computing reduces downlink bandwidth requirements.
Industry Challenges
- RF engineering talent scarcity:Phased array antenna design requires specialized expertise in microwave engineering. Universities in Finland and Italy produce limited graduates with space-qualified radar experience.
- Space debris mitigation compliance:Operators must demonstrate post-mission disposal and collision avoidance under national licensing regimes. The FCC and national regulators impose escalating compliance documentation burdens.
- Integration with legacy ground segments:Defense customers maintain proprietary data formats from Cold War-era reconnaissance systems. New commercial providers must build translation layers for interoperability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synthetic Aperture Radar (SAR) Market |
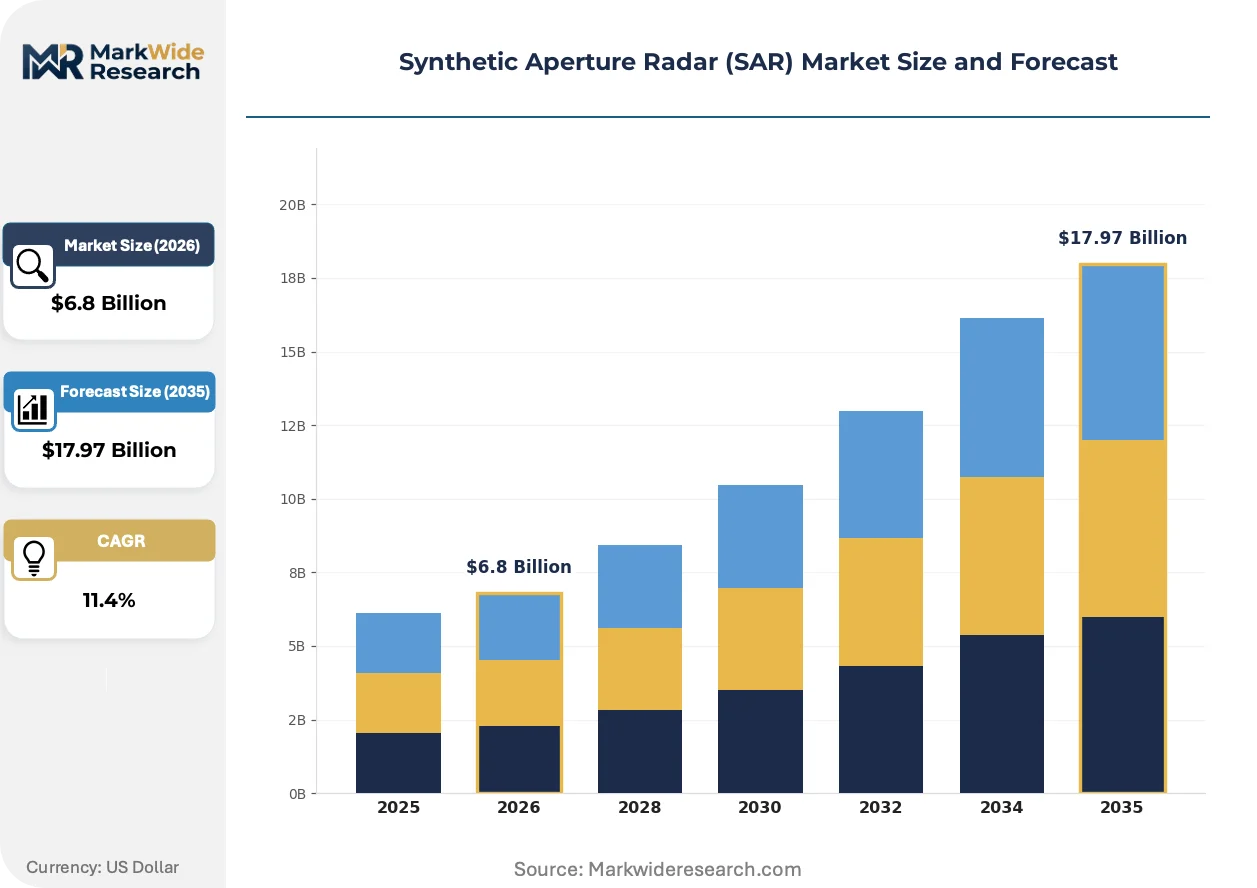
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Earth Observation, Environmental Monitoring, Disaster Management, Military Surveillance End User: Aerospace, Defense, Agriculture, Telecommunication Technology: X-band, Ku-band, L-band, Ka-band Deployment: Airborne, Spaceborne, Ground-based, Hybrid |
| Companies Covered | Northrop Grumman Corporation, Leonardo S.p.A., Lockheed Martin, Capella Space, ICEYE, RTX Corporation, Thales Group, Israel Aerospace Industries, Airbus Defense and Space, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synthetic Aperture Radar (SAR) Market Emerging Trajectories
Distributed satellite architectures are compressing the trade-off between revisit frequency and spatial resolution. This structural shift enables applications previously reserved to classified military systems.
Digital beamforming technology is electrifying SAR payload design. This approach synthesizes multiple simultaneous receive beams from a single aperture. Intelligence agencies in the United States and United Kingdom are adopting it for wide-area surveillance. The technology is electrifying competitive positioning by enabling smaller satellites to match the coverage rates of legacy large-aperture platforms.
The EU AI Act's risk classification framework is reshaping automated image analysis deployments. Providers must document training data provenance and algorithmic transparency for high-risk geospatial AI applications. European Earth observation service contracts now require conformity assessments for vessel detection and change monitoring algorithms.
Subscription-based data access is displacing per-scene licensing in commercial segments. Maritime insurers and commodity traders prefer unlimited tasking over archived image purchases. This model shift is most visible in the North Sea and Gulf of Mexico, where energy sector buyers demand continuous asset monitoring without transaction friction.
Synthetic Aperture Radar (SAR) Market Segmentation
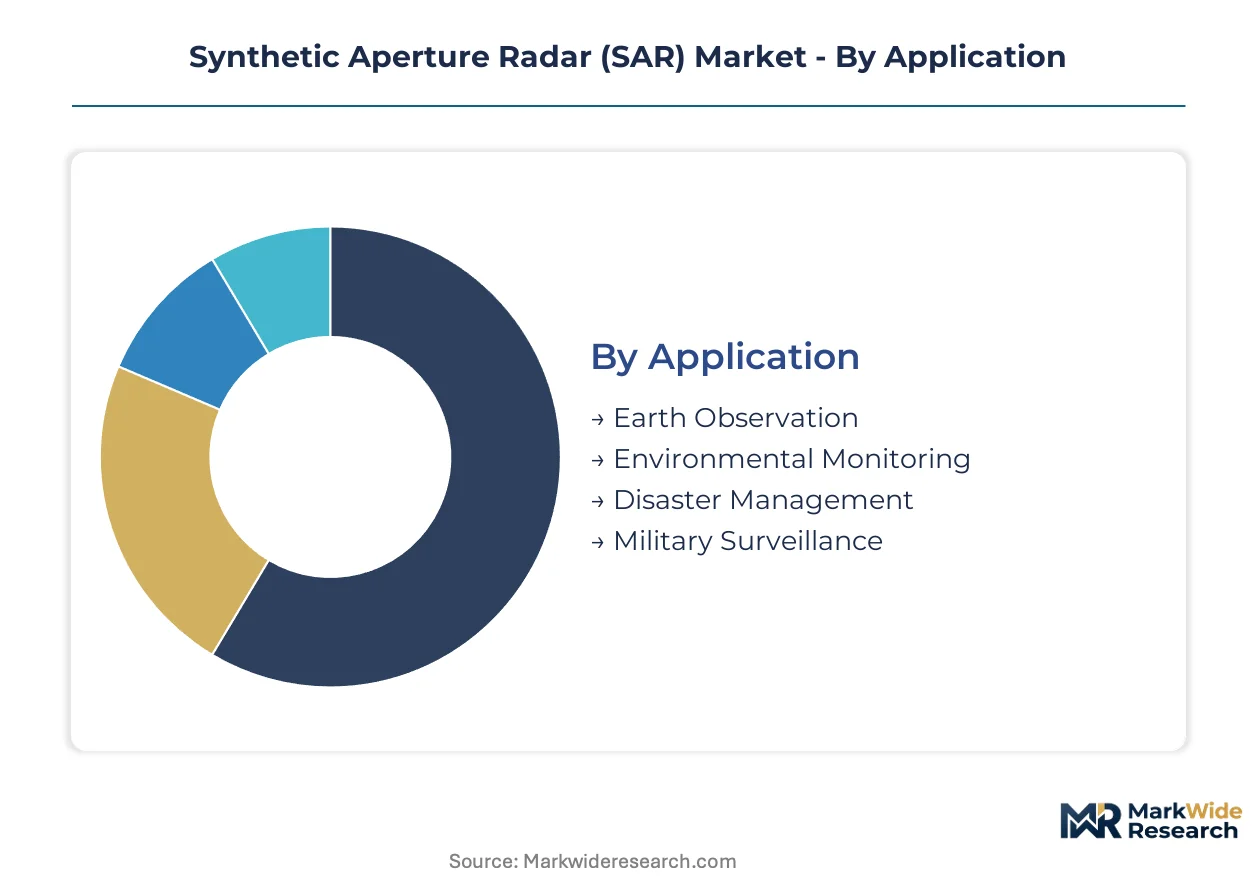
SAR segmentation reveals distinct procurement patterns across defense, commercial, and institutional buyers. Frequency band selection and deployment architecture determine unit economics and revisit capabilities for specific mission profiles.
Application:
Standalone SAR systems dominate sovereign defense programs requiring dedicated tasking authority, while embedded multi-sensor platforms serve commercial Earth observation constellations.
- Earth Observation:Commercial satellite operators deploy X-band and L-band payloads for all-weather imaging of agricultural parcels, urban sprawl, and infrastructure corridors. Demand clusters in United States and Finland where ICEYE and Capella Space maintain manufacturing facilities for rapid-revisit constellations.
- Military Surveillance:Classified programs require fine-resolution target identification under cloud cover and darkness. NATO member states procure spaceborne SAR through national defense ministries with ITAR-compliant supply chains restricting component sourcing.
- Environmental Monitoring:L-band penetration enables biomass tracking beneath forest canopies. Brazil and Canada deploy these systems for carbon accounting and deforestation enforcement.
- Disaster Management:Rapid tasking flexibility drives airborne SAR adoption for flood extent mapping and earthquake damage assessment. Japanese insurers integrate automated triggers for parametric payouts.
Volume placements concentrate in Earth Observation; the faster expansion belongs to Military Surveillance.
End User:
Defense agencies command premium pricing for classified tasking authority, while agricultural ministries drive standardization through multi-year framework contracts.
- Defense:National reconnaissance offices procure dedicated satellite constellations with sovereign control over imaging priorities. United States National Reconnaissance Office and European Defence Agency capability targets mandate independent SAR capacity.
- Aerospace:Satellite manufacturers integrate SAR payloads into multi-instrument platforms for commercial data resale. Italian and Finnish production facilities supply European Space Agency missions.
- Agriculture:Ministries in Brazil and Canada deploy L-band systems for soil moisture monitoring beneath vegetation. Crop yield forecasting applications require seasonal revisit consistency.
- Telecommunication:Spectrum management authorities utilize SAR for interference monitoring and infrastructure planning. Limited deployment relative to other segments.
Defense agencies anchor procurement value; Agriculture climbs fastest as climate monitoring budgets expand.
Technology:
Frequency selection trades resolution against penetration depth, with X-band dominating defense applications and L-band serving environmental monitoring.
- X-band:Fine spatial resolution below one meter enables target identification and change detection. ITAR restrictions govern United States component transfers to foreign platforms.
- L-band:Vegetation and soil penetration supports biomass estimation and subsurface moisture mapping. European Copernicus Expansion Missions include new L-band capacity.
- Ku-band:Intermediate resolution for maritime surveillance and ice monitoring applications.
- Ka-band:Emerging frequency for high-resolution commercial imaging with limited atmospheric penetration.
X-band retains the dominant placement base; L-band gains share fastest through environmental mandate expansion.
Deployment:
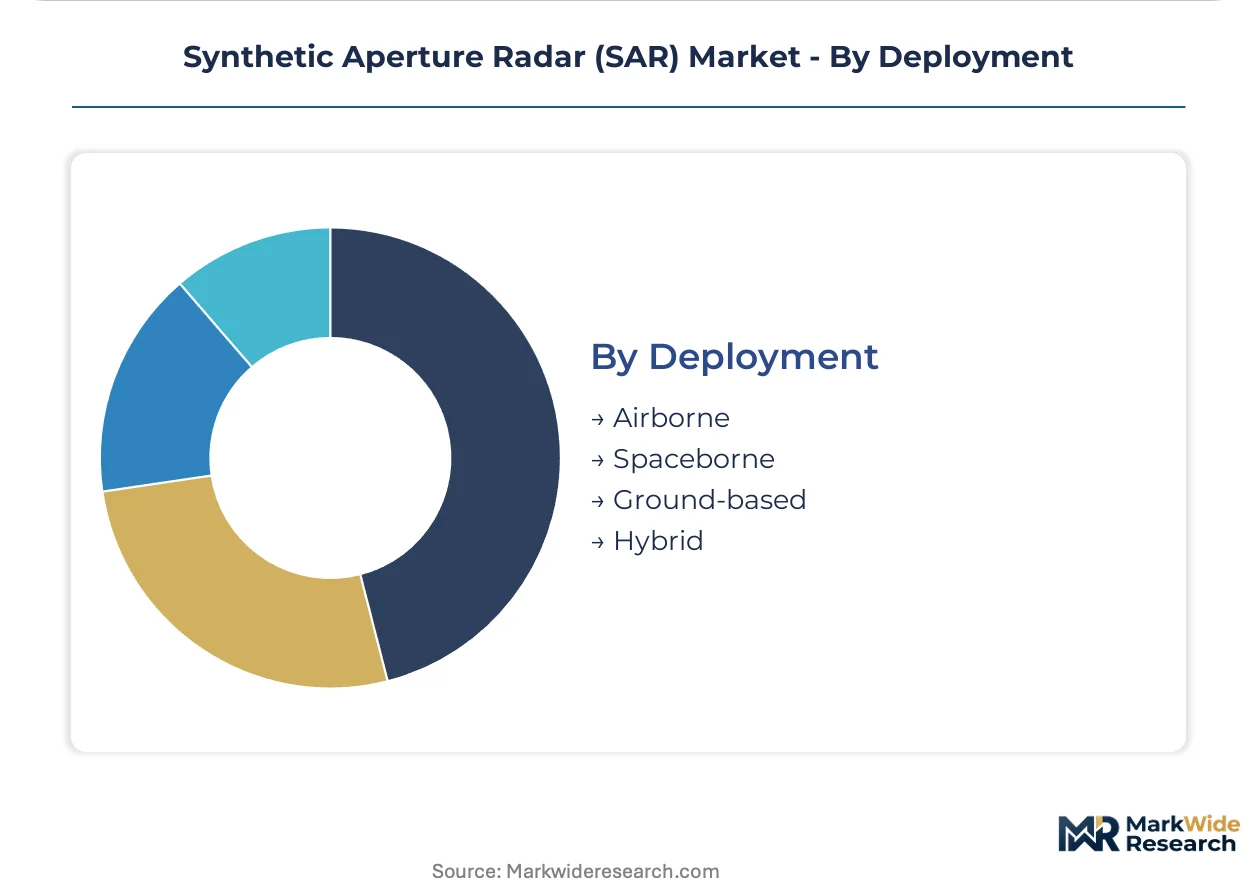
Spaceborne systems generate capital-intensive revenue pools, while airborne platforms preserve margin through rapid tasking flexibility.
- Spaceborne:Orbital constellations deliver persistent global coverage with revisit intervals compressing below one hour. Launch cost concentration on Falcon 9 and Ariane 6 directly impacts constellation economics.
- Airborne:Tactical military and disaster response applications prioritize tasking agility over revisit frequency. Northrop Grumman leverages legacy large-aperture radar expertise in this segment.
- Ground-based:Limited to calibration, research, and specialized interferometric applications.
- Hybrid:Multi-platform architectures combining orbital persistence with airborne responsiveness for critical infrastructure monitoring.
Spaceborne deployments concentrate volume; Hybrid architectures show steepest expansion trajectory as operators combine platform strengths.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in established aerospace clusters while consumption spreads across defense ministries and commercial operators seeking sovereign Earth observation capacity. Manufacturing gravity pulls toward facilities with heritage radar engineering and ITAR-compliant supply chains.
United States
The National Reconnaissance Office procures dedicated SAR constellations with classified tasking authority, while the FCC licenses commercial orbital operations under debris mitigation rules. California hosts Capella Space manufacturing for rapid-revisit microsatellites serving maritime insurers and energy sector buyers.
Finland
ICEYE anchors European microsatellite SAR production with commercial insurance and disaster response contracts driving volume. The country's national space regulator aligns licensing with EU Space Programme objectives for Copernicus participation. Helsinki maintains specialized RF engineering programs feeding phased array antenna design.
Italy
Leonardo S.p.A. supplies dual-use Earth observation platforms through European Defence Agency frameworks and national defense procurement. The national telecommunications regulator manages spectrum coordination with SAR operators at the International Telecommunication Union. Rome and Florence host sovereign satellite manufacturing for institutional anchor tenancy.
United Kingdom
Intelligence agencies adopt digital beamforming architectures for wide-area surveillance under national security procurement. The UK Space Agency coordinates frequency allocation with commercial operators through national licensing. Harwell Space Cluster aggregates SAR payload engineering and downstream analytics capabilities.
Israel
Israel Aerospace Industries maintains defense-focused SAR production for regional surveillance and export markets with sovereign technology control. The national defense export regulator governs component transfers under bilateral security agreements. Tel Aviv concentrates radar systems engineering with heritage in phased array development.
Synthetic Aperture Radar (SAR) Market Vendor Landscape
The competitive structure tilts toward defense-anchored primes with classified contract access. Tiering separates ITAR-restricted US suppliers from European sovereign capacity and commercial microsatellite specialists. Three archetypes dominate: legacy aerospace conglomerates with large-aperture heritage, agile small-satellite operators with rapid revisit platforms, and European dual-use manufacturers with institutional funding access. Capacity expansion and strategic partnerships constitute the dominant competitive moves.
Among US-based defense primes, Northrop Grumman Corporation and Lockheed Martin occupy positions anchored by National Reconnaissance Office relationships and ITAR-compliant supply chains. Leonardo S.p.A. represents the European sovereign archetype with dual-use production aligned to EU Space Programme and European Defence Agency requirements. ICEYE exemplifies the commercial microsatellite specialist tier with manufacturing in Finland and subscription-based data access disrupting per-scene licensing models.
| Leading Market Players |
|---|
| Northrop Grumman Corporation |
| Leonardo S.p.A. |
| Lockheed Martin |
| Capella Space |
| ICEYE |
| RTX Corporation |
| Thales Group |
| Israel Aerospace Industries |
| Airbus Defense and Space |
| Others |
Supply Flow & Price Mechanics
Phased array antenna engineering talent concentration in Finland and Italy creates labor-cost differentials that widen pricing-tier spreads between sovereign defense contracts and commercial microsatellite deployments.
Pricing Analysis
Margin tightening in commercial Earth observation reflects subscription-based data access displacing per-scene licensing. Three-tier pricing structure across premium, standard, and economy levels separates defense-grade tasking authority from maritime monitoring subscriptions. Price differentiation rests on ITAR certification status and sovereign control over imaging priorities. Defense agencies exhibit lowest price sensitivity; commodity traders and agricultural ministries drive hardest bargaining.
Supply Chain Analysis
Launch freight costs from Cape Canaveral, Kourou, and Vandenberg concentrate supply chain leverage among Falcon 9 and Ariane 6 operators. Component sourcing draws from United States transmit-receive modules, European phased array substrates, and Israeli radar signal processors. Single-source vulnerability pervades ITAR-restricted X-band component supply. Distribution runs through national defense procurement offices and commercial data resellers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ITAR compliance burdens and launch cost concentration are forcing weaker commercial operators toward acquisition or exit, consolidating viable capacity around defense-anchored primes and sovereign-funded European manufacturers.
For Market Incumbents: To counter digital beamforming disruption from agile microsatellite operators, Northrop Grumman and Lockheed Martin should deepen backward integration into space-qualified transmit-receive module production while expanding capacity in ITAR-compliant California facilities. Certification investment in FCC debris mitigation compliance preserves licensing access against regulatory escalation. For New Entrants and Emerging Players: AI inference at edge architectures offer entry paths around established downlink infrastructure. Disaster response automation in Japanese and Australian insurance markets presents the most penetrable commercial segment. Go-to-market positioning should emphasize parametric payout integration rather than raw imagery resale. For Investors and Strategic Acquirers: The window for entry favors European dual-use manufacturers with Copernicus anchor tenancy and ITAR-free export capacity. Long-term viability hinges on sovereign funding access through EU Space Programme and European Defence Agency frameworks. Watch for frequency allocation rulings at the International Telecommunication Union as inflection signal for C-band and X-band operator valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Beamforming Adoption | Intelligence agencies in the United States and United Kingdom deploy wide-area surveillance capabilities from smaller satellite platforms. |
| Copernicus Anchor Tenancy | European manufacturers secure production volume through EU Space Programme institutional procurement commitments. |
| ITAR Compliance Investment | United States primes maintain component transfer restrictions that block foreign platform integration. |
| Subscription Model Transition | Maritime insurers in the North Sea and Gulf of Mexico prefer unlimited tasking over transactional image purchases. |
| Onboard AI Processing | Microsatellite operators reduce downlink bandwidth requirements through real-time change detection at edge. |
Methodological Framework
Multi-period observation of constellation deployment rates, launch manifest backlogs, and defense procurement announcements anchored the trend analysis, supplemented by interviews with satellite payload engineers, defense procurement officers at NATO member ministries, commercial data resale executives, and phased array RF specialists. Secondary validation drew from FCC licensing databases, ESA procurement disclosures, National Reconnaissance Office budget justifications, and ITAR amendment filings. Bottom-up unit economics modeling triangulated against top-down addressable market sizing.
Input-output matrices mapped frequency band selection, deployment architecture, and end-user budget cycles across the projection horizon. Segmentation dimensions modeled included application type, technology band, deployment mode, and sovereign versus commercial procurement channel. CAGRs derived from elasticity-adjusted demand curves and launch cost trajectory assumptions. Industry-specific inputs incorporated Falcon 9 and Ariane 6 pricing volatility and EU Space Programme funding allocation schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ITAR restriction expansion or launch provider consolidation. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
ISR
Active Phased Array Radar (APAR) Market
ISR
C5ISR Market
ISR
North America C5ISR Market
ISR
United States C4ISR Market
ISR
Saudi Arabia C4ISR Market
ISR
Air Based C4ISR Market
ISR
Land Based C4ISR Market
ISR
Infrared Suppression Systems Market
ISR
Eastern Europe C4ISR Market
ISR
C4ISR Market
ISR
Brazil C4ISR Market
ISR
Global Interferometric Synthetic Aperture Radar (Insar) Market
ISR
Airborne ISR Market
ISR
NATO C4ISR Market
ISR
Asia-Pacific C4ISR Market
ISR
IFF System Market