
 EMEA Mission Critical Wireless Communications Market | 2026-2036
EMEA Mission Critical Wireless Communications Market Size, Share, and Industry Trends Forecast 2026-2036
EMEA Mission Critical Wireless Communications Market Insights
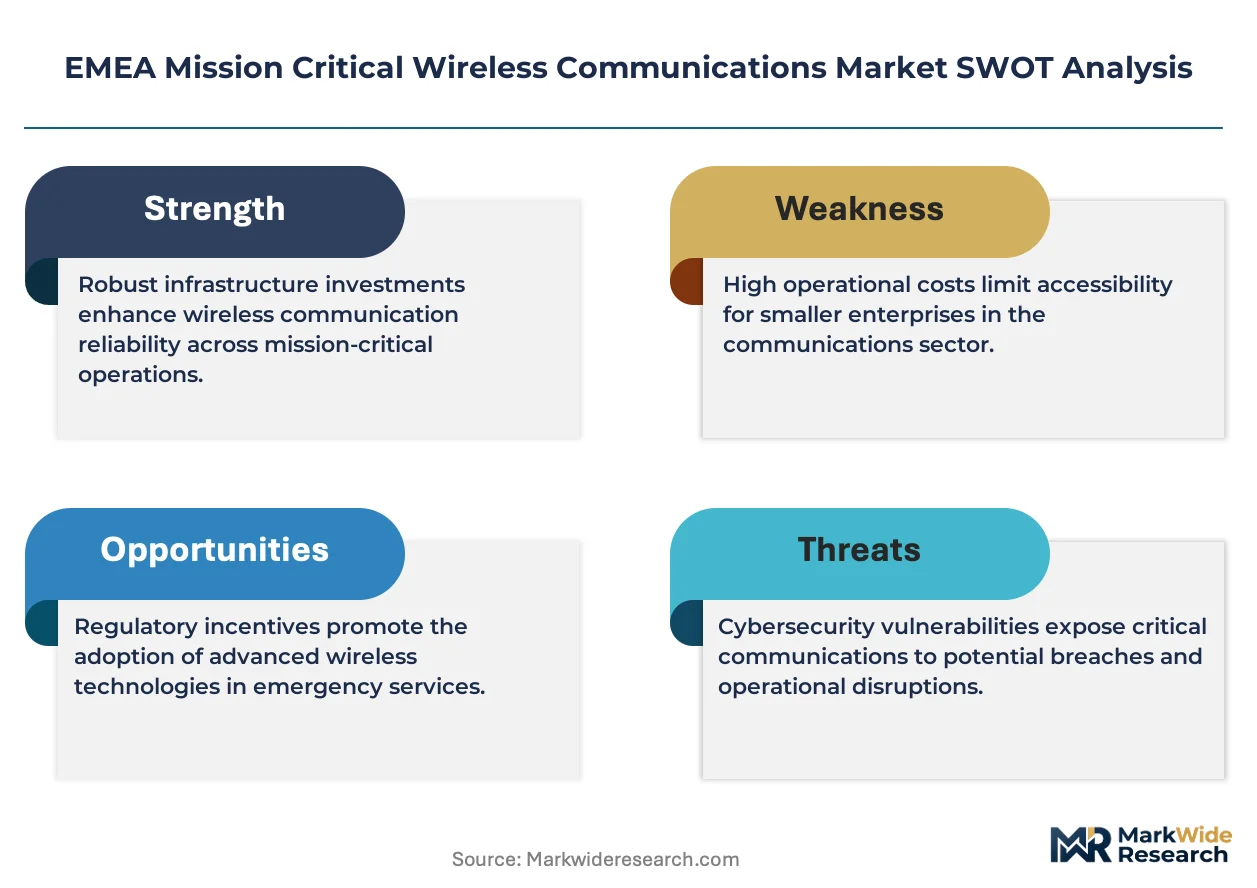
The EU's Cybersecurity Act is broadening compliance burdens for equipment vendors seeking EMEA-wide contracts. Motorola Solutions leverages its installed TETRA base to anchor long-term upgrade cycles across European public safety agencies. Nokia competes through 3GPP-standardized mission critical core platforms that interoperate with national broadband networks. Thales Group specializes in encrypted military-grade waveform technologies that differentiate its portfolio from commercial LTE offerings.
Mission critical wireless communications denotes engineered radio systems delivering guaranteed availability, priority access, and sub-300 millisecond latency for first responders and infrastructure operators. These networks employ hardened base stations, spectrum-agile terminals, and redundant backhaul to maintain service during natural disasters or deliberate interference. Push-to-Talk and LTE product categories currently dominate procurement budgets as agencies phase out narrowband legacy systems. Mesh Networking represents the fastest-growing segment for disaster-zone and temporary event coverage where fixed infrastructure proves unavailable. The Military end user category sustains premium pricing through classified waveform requirements and sovereign encryption mandates.
ETSI, ECHA, and national regulators such as BNetzB in Germany enforce harmonized spectrum allocation and interoperability testing that shapes vendor market access. The EU's Radio Equipment Directive combined with country-specific frequency licensing creates a fragmented compliance landscape favoring established players with regulatory affairs capacity. Stakeholders must monitor spectrum re-farming decisions and 3GPP Release evolution timelines to align R&D roadmaps with procurement cycles.
Market Dynamics
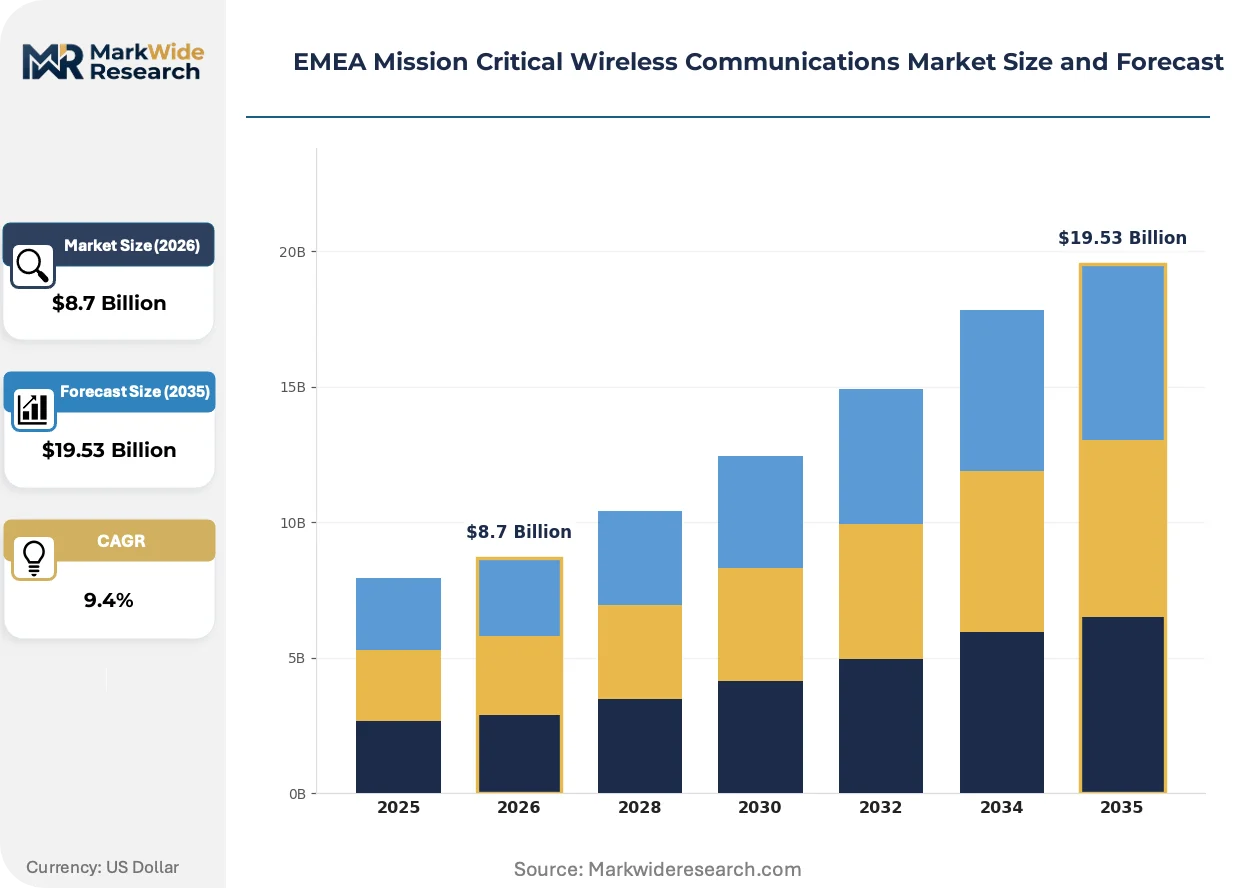
The migration from TETRA to mission critical LTE networks is creating a multi-year replacement cycle across European public safety agencies. This technology transition demands simultaneous investment in new spectrum licenses, hardened infrastructure, and interoperable terminal ecosystems.
Growth Catalysts
- EU Cybersecurity Act:Mandatory certification for critical infrastructure devices is expanding addressable market for vendors with pre-approved security architectures. Operators in Germany and France now require certified equipment for network tenders.
- First responder broadband programs:National governments are allocating dedicated spectrum and capital for LTE-based emergency communications. The United Kingdom's Emergency Services Network exemplifies this procurement pattern.
- Mesh networking adoption:Disaster response agencies across Italy and Spain are deploying self-healing radio systems for temporary coverage zones. This technology addresses infrastructure gaps in mountainous and remote terrain.
Market Restraints
- Semiconductor supply concentration:Specialized baseband processors for military-grade waveforms source from a limited supplier base in Asia-Pacific. This creates vulnerability in Thales Group and Nokia production schedules.
- Spectrum licensing fragmentation:National regulators including BNetzB in Germany and Ofcom in the United Kingdom maintain divergent auction timelines and band plans. Vendors face duplicated compliance costs across EMEA markets.
- TETRA sunk cost inertia:Agencies with recently upgraded narrowband infrastructure resist full replacement cycles. Poland and Hungary exhibit extended depreciation timelines for legacy Motorola Solutions deployments.
Strategic Opportunities
- Nordic defense modernization:Sweden and Norway are procuring next-generation tactical communications with sovereign encryption requirements. This creates premium pricing segments distinct from commercial LTE.
- Critical infrastructure operator segment:Power utilities and railway operators in the Netherlands and Belgium require private LTE networks with guaranteed availability. These industrial buyers offer multi-year service contracts.
- 3GPP Release 18 convergence:Integration of 5G NR with mission critical push-to-talk standards enables new waveform architectures. Vendors aligning R&D with this timeline capture early procurement cycles.
Industry Challenges
- RF engineering talent scarcity:Design of spectrum-agile terminals requires expertise in military waveform protocols. European universities produce insufficient graduates with combined RF and cybersecurity skills.
- Multi-mode certification complexity:Devices must pass ETSI interoperability testing plus national type approval. This extends product launch timelines by 18-24 months for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EMEA Mission Critical Wireless Communications Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Push-to-Talk, LTE, Satellite, Mesh Networking End User: Public Safety, Transportation, Utilities, Military Deployment Model: On-Premises, Cloud-Based, Hybrid, Dedicated Network Technology: 5G, LMR, Wi-Fi, Narrowband |
| Companies Covered | Telefonaktiebolaget LM Ericsson, Motorola Solutions, Cobham Satcom, Thales Group, Nokia, Inmarsat Global Limited, Saudi Telecom Company, Airbus, Eutelsat Communications SA, Others |
| Regions Covered | EMEA: Germany, UK, France, Saudi Arabia, UAE, South Africa, Russia, Italy, Rest of EMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EMEA Mission Critical Wireless Communications Market Trends and Innovations
Radio access network architectures are converging toward software-defined platforms that decouple hardware from waveform processing. This shift enables faster feature deployment and reduces dependency on specialized silicon foundries.
3GPP-standardized mission critical push-to-talk over cellular is electrifying procurement patterns among European police and fire services. Agencies in France and Germany are piloting broadband voice services that replace narrowband group calls. This technology is compressing the traditional 15-year infrastructure replacement cycle into 7-10 year horizons as agencies accelerate LTE adoption.
The EU's Radio Equipment Directive combined with country-specific CE marking enforcement is tightening market access for non-European suppliers. Manufacturers must maintain notified body relationships in multiple member states to sustain tender eligibility. Military end-use segments in the United Kingdom and Italy are responding by prioritizing vendors with established European regulatory affairs capacity.
Buyer concentration among national procurement agencies is consolidating vendor relationships around framework agreements. Small municipal police forces in Spain and Portugal now purchase through centralized government contracts rather than independent tenders. This pattern is most visible in southern Europe where fiscal austerity has compressed local agency budgets.
EMEA Mission Critical Wireless Communications Market Segmentation
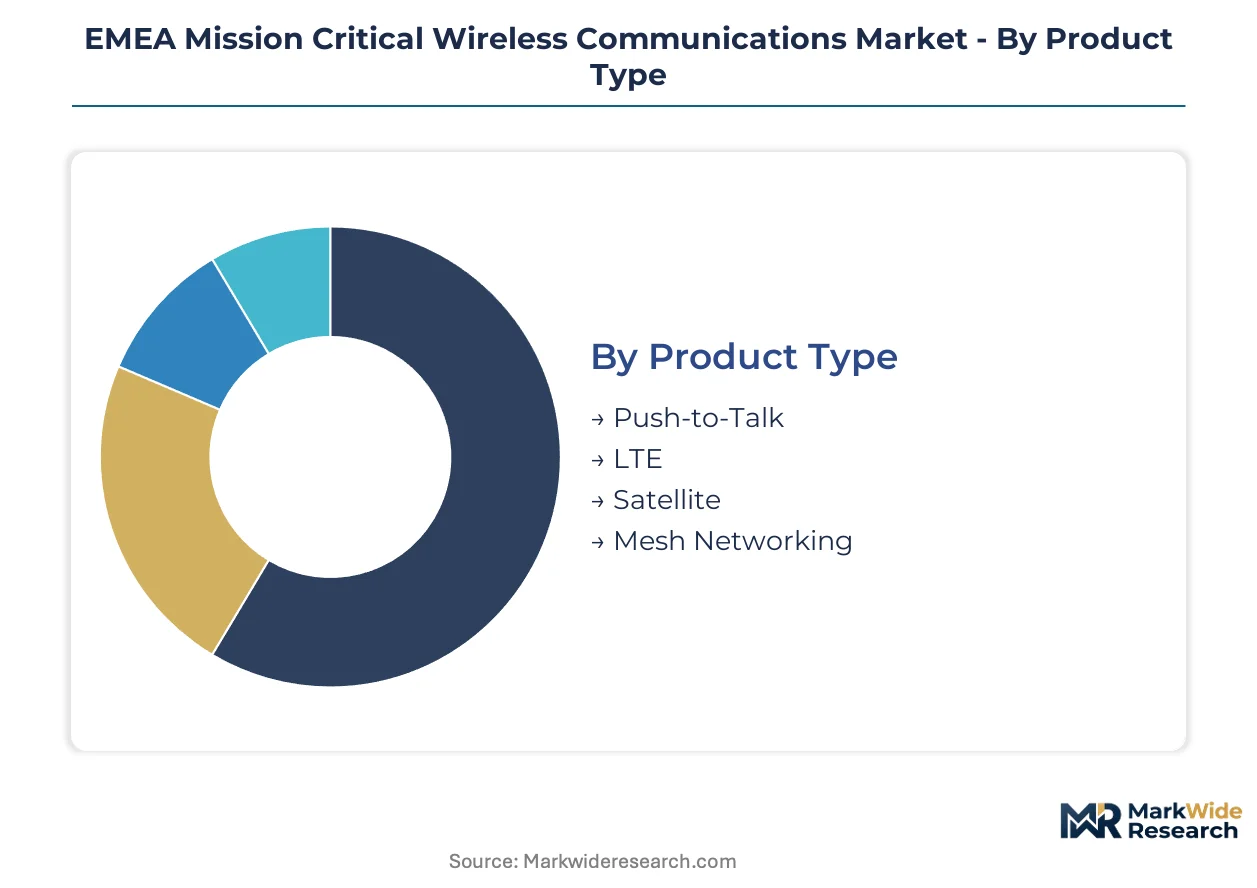
Mission critical wireless communications procurement splits along operational requirements rather than commercial preferences. Buyers prioritize guaranteed availability and sovereign encryption over cost optimization, creating distinct vendor qualification barriers across each segment category.
Product Type:
Agencies select radio platforms based on infrastructure maturity and coverage gaps rather than feature richness.
- Push-to-Talk:Narrowband voice systems with sub-300 millisecond call setup engineered for group coordination during emergencies. German and French public safety agencies concentrate procurement here as they phase out legacy TETRA infrastructure. Spectrum licensing timelines accelerate replacement cycles.
- LTE:Broadband data networks supporting video streaming, biometric transmission, and location services alongside voice. The United Kingdom's Emergency Services Network anchors regional demand for hardened cellular base stations. Interoperability with national broadband infrastructure shapes vendor selection.
- Satellite:Beyond-line-of-sight connectivity for maritime and remote terrain operations where terrestrial infrastructure fails. Nordic defense commands drive specialized waveform requirements.
- Mesh Networking:Self-healing radio clusters that autonomously route traffic when fixed infrastructure collapses. Italian and Spanish disaster response agencies deploy these for temporary coverage in mountainous zones.
Volume sits with Push-to-Talk; growth tilts toward Mesh Networking.
End User:
Budget authority and encryption classification separate buyers into procurement tiers with diverging contract structures.
- Public Safety:Police, fire, and emergency medical services requiring guaranteed priority access during mass casualty events. Municipal and national agencies across Germany, France, and the United Kingdom dominate procurement volume. Framework agreements consolidate purchasing power.
- Transportation:Railway operators and port authorities demanding continuous coverage across linear infrastructure corridors. Dutch and Belgian networks prioritize private LTE with 99.999% availability targets.
- Utilities:Power grid operators and water treatment facilities monitoring distributed assets through hardened telemetry. Cybersecurity Act certification mandates now govern tender eligibility.
- Military:Defense ministries procuring sovereign-encrypted waveforms for tactical operations. Sweden and Norway are expanding next-generation communications modernization programs with classified requirements.
Public Safety commands procurement volume; Military segments capture premium pricing through encryption mandates.
Deployment Model:
Data sovereignty requirements and latency tolerance determine infrastructure ownership structures.
- On-Premises:Dedicated hardware installations within agency facilities with full operational control. German critical infrastructure operators favor this model under BNetzB spectrum licensing frameworks.
- Cloud-Based:Centralized network management with remote base station operation reducing capital intensity. Smaller municipal agencies in Spain and Portugal access capabilities through government framework contracts.
- Hybrid:Mixed architectures combining local switching with cloud analytics for resource optimization. French agencies pilot these configurations during technology transition periods.
- Dedicated Network:Physically isolated infrastructure with no shared carrier resources. Military and nuclear facility operators mandate this architecture for electromagnetic resilience.
On-Premises retains installed base; Hybrid deployments are expanding most quickly among budget-constrained agencies.
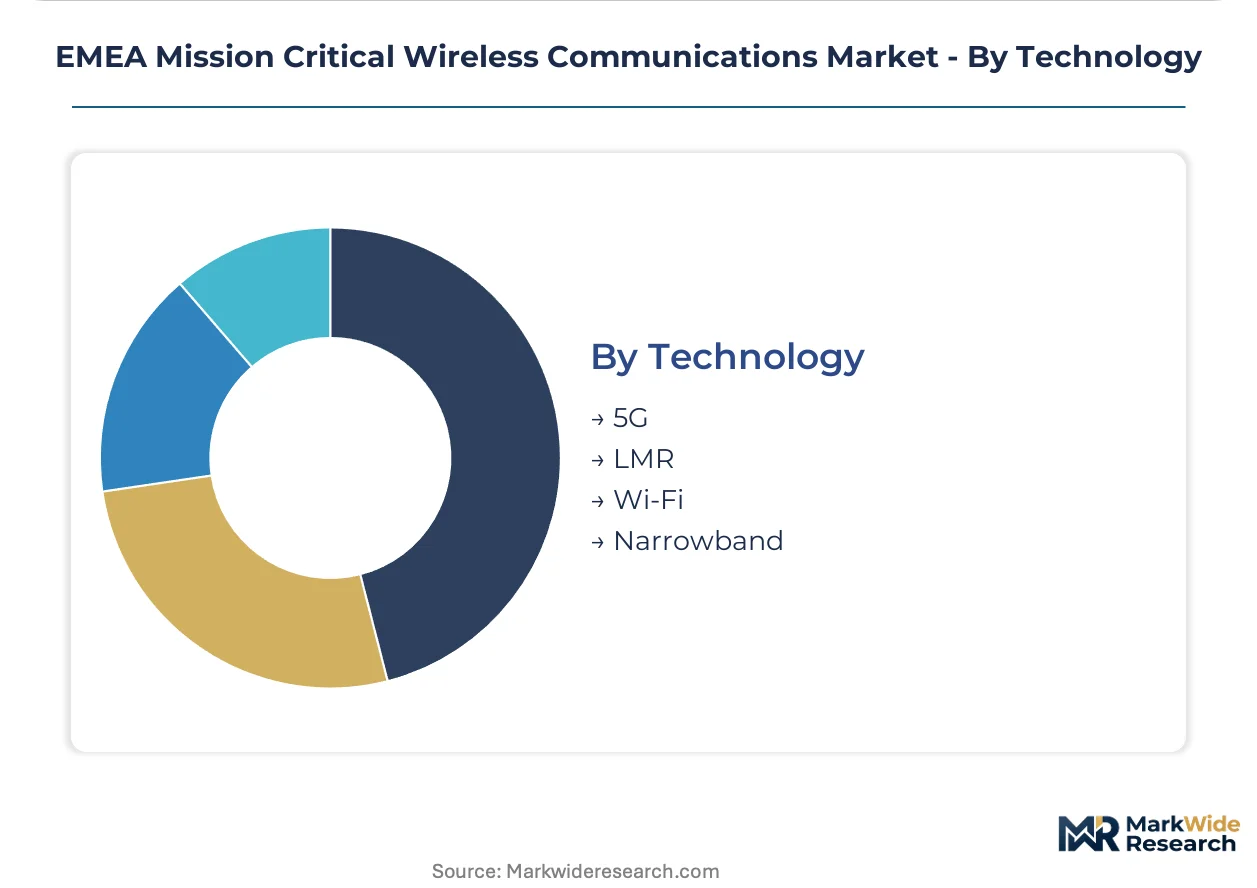
Technology:
Standardization maturity and spectrum availability constrain technology selection more than performance benchmarks.
- 5G:New radio interfaces enabling network slicing and ultra-reliable low-latency communication for autonomous systems. Early procurement concentrates in Nordic defense and advanced railway signaling trials.
- LMR:Land Mobile Radio systems including TETRA and P25 protocols with proven interoperability. Legacy installed base across Poland and Hungary resists accelerated replacement.
- Wi-Fi:Unlicensed spectrum coverage for indoor facilities and temporary command posts. Airport and hospital security deployments in the United Kingdom leverage existing IT infrastructure.
- Narrowband:Spectrum-efficient voice channels for rural coverage where broadband economics fail. Eastern European agencies extend depreciation timelines for recent TETRA investments.
LMR carries legacy volume; 5G claims the steepest expansion trajectory as Release 18 standards mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The European Union's special economic zones for critical infrastructure development concentrate mission critical wireless investment across Germany, France, and the United Kingdom. National broadband programs and defense modernization cycles drive procurement concentration in these three markets.
Germany
BNetzB spectrum licensing frameworks accelerate TETRA-to-LTE transitions for police and fire services. The EU Cybersecurity Act mandates certified equipment for critical infrastructure tenders, tightening vendor qualification. Bavaria hosts concentrated base station manufacturing clusters serving Central European export markets.
France
ANSM and national regulators enforce harmonized spectrum allocation for first responder networks. The country's defense procurement agency funds sovereign-encrypted waveform development for tactical communications. Paris-Île-de-France anchors systems integration capabilities for Mediterranean export markets.
United Kingdom
Ofcom spectrum auctions and the Emergency Services Network program anchor regional LTE infrastructure demand. Military end-use segments prioritize vendors with established European regulatory affairs capacity. London and the Southeast concentrate cloud-based network management pilot programs.
Sweden
Nordic defense modernization programs procure next-generation tactical communications with classified encryption requirements. National agencies specify sovereign waveform architectures distinct from commercial LTE standards. Stockholm anchors military-grade terminal engineering clusters serving Scandinavian interoperability frameworks.
Italy
Disaster response agencies deploy mesh networking systems for temporary coverage in mountainous and remote terrain. National procurement frameworks consolidate purchasing for municipal police forces in southern regions. Rome and Milan host dual-use technology development bridging public safety and defense applications.
EMEA Mission Critical Wireless Communications Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the EMEA mission critical wireless communications market. The vendor base stratifies around three strategic archetypes: legacy TETRA providers leveraging installed base relationships, 3GPP-standardized platform vendors, and military-grade encryption specialists. Dominant competitive moves include spectrum licensing partnerships with national regulators and R&D alignment with 3GPP Release evolution timelines.
Within the military-grade encryption tier, Thales Group exemplifies sovereign waveform specialization for defense ministries. Among Nordic infrastructure providers, Telefonaktiebolaget LM Ericsson occupies a position in software-defined radio access network architectures. At the legacy integration end, Motorola Solutions anchors long-term upgrade cycles across European public safety agencies transitioning from narrowband systems.
| Leading Market Players |
|---|
| Telefonaktiebolaget LM Ericsson |
| Motorola Solutions |
| Cobham Satcom |
| Thales Group |
| Nokia |
| Inmarsat Global Limited |
| Saudi Telecom Company |
| Airbus |
| Eutelsat Communications SA |
| Others |
Pricing and Supply Chain Analysis
Gallium nitride substrate pricing indices cascade through EMEA mission critical radio manufacturing, compressing margins for baseband processor vendors while amplifying premiums for military-grade waveform suppliers with captive material streams.
Pricing Analysis
Lead-time premiums of 40-60% apply to spectrum-agile terminals delivering within 12 weeks versus standard 26-week cycles, while spot inventory from distributors trades at 15-25% discounts. Three-tier pricing structure across sovereign-encrypted, certified-commercial, and uncertified-economy levels separates defense ministry contracts from municipal agency frameworks. Cost compression in commercial LTE tiers intensifies because semiconductor foundry allocation favors consumer volumes. Municipal police forces in Spain and Portugal exhibit highest price sensitivity through centralized procurement, while Nordic defense commands show least sensitivity due to classified encryption mandates.
Supply Chain Analysis
Specialized baseband processors for military-grade waveforms rest on concentrated foundry capacity in Taiwan, South Korea, and Japan, with final assembly anchoring in Germany and France. RF front-end components draw from III-V compound semiconductor suppliers, precision crystal oscillators, and hardened enclosure manufacturers. Single-source vulnerability concentrates in gallium arsenide wafer supply for high-frequency amplifiers. Distribution runs through national systems integrators holding framework agreements with BNetzB and Ofcom licensing authorities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into sovereign encryption IP and spectrum licensing partnerships represents the decisive competitive race, with downstream control over national framework contracts proving as critical as upstream waveform development.
For Market Incumbents: Deploy regulatory affairs capacity expansion across Berlin, Paris, and London to secure BNetzB, ANSM, and Ofcom certification pipelines ahead of 3GPP Release 18 procurement cycles. Anchor long-term service contracts with German critical infrastructure operators resisting full TETRA replacement. Counter emerging pure-play mesh networking specialists through pre-integrated hybrid architecture offerings. For New Entrants and Emerging Players: Cloud-based network management platforms offer the most penetrable entry vector among budget-constrained municipal agencies in southern Europe accessing capabilities through Portuguese and Spanish government framework contracts. Target mesh networking deployments for Italian and Spanish disaster response agencies where fixed infrastructure gaps persist. Pursue channel partnerships with national systems integrators rather than direct tender competition. For Investors and Strategic Acquirers: Distressed-cycle entries favor software-defined radio IP holders in Sweden and Norway with sovereign encryption credentials and established Nordic defense relationships. Five-to-ten year viability hinges on 3GPP standardization alignment rather than proprietary waveform lock-in. Monitor spectrum re-farming announcements from BNetzB and Ofcom as inflection indicators for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Encryption IP Acquisition | Defense ministries in Sweden and Norway mandate classified waveforms inaccessible to commercial LTE vendors. |
| 3GPP Release 18 Alignment | Early standardization capture enables mission critical push-to-talk over 5G NR procurement in France and Germany. |
| National Framework Contract Anchoring | BNetzB and Ofcom licensing partnerships secure multi-year critical infrastructure operator relationships. |
| Mesh Networking Capability Integration | Italian and Spanish disaster response agencies prioritize self-healing coverage for mountainous terrain gaps. |
| Software-Defined RAN Platform Development | Decoupled hardware architectures reduce dependency on Taiwan and South Korea foundry allocation cycles. |
Research Methodology
Independent corroboration across primary interviews with public safety procurement directors, defense ministry communications officers, critical infrastructure operator technical leads, and ETSI regulatory affairs specialists underwrites the qualitative findings. Secondary validation draws from BNetzB spectrum licensing records, Ofcom auction documentation, 3GPP release specifications, and ECHA cybersecurity certification databases. Bottom-up terminal shipment estimates triangulate against top-down national broadband program budget allocations.
Rate-of-change decomposition separates volume effects from mix-shift and pricing dynamics across the analysis window. Segmentation dimensions model deployment model hierarchies, end-user encryption classification tiers, product technology generations, and national regulatory cluster patterns. CAGRs derive from installed base replacement cycle analysis, spectrum license expiration schedules, and defense modernization program announcements. Forecast inputs incorporate semiconductor foundry allocation trends and EU Cybersecurity Act certification timeline assumptions.
Inputs from BNetzB, Ofcom, and ANSM regulatory filings were available through the study window; gaps in classified defense procurement specifications introduce uncertainty bands around military segment projections. Forecasts reflect documented assumptions regarding 3GPP standardization adoption curves and national broadband program continuity. A small set of triggers—spectrum re-farming acceleration, foundry allocation shocks, and EU cybersecurity tier reclassification—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Navigation & Surveillance
Latin America Inertial Systems Market
Communication Navigation & Surveillance
Asia-Pacific Autonomous Navigation Market
Communication Navigation & Surveillance
Global Antenna Market
Communication Navigation & Surveillance
Tactical Inertial Systems Market
Communication Navigation & Surveillance
Missile Guidance Radar Market
Communication Navigation & Surveillance
Infrared Search and Track (IRST) System Market
Communication Navigation & Surveillance
Anti-Jamming Market
Communication Navigation & Surveillance
Tactical Radio Market
Communication Navigation & Surveillance
High Frequency Military Communications Market
Communication Navigation & Surveillance
Man Portable Communication Systems Market
Communication Navigation & Surveillance
Defense Communication System Market
Communication Navigation & Surveillance
Land-Based Situational Awareness Systems Market
Communication Navigation & Surveillance
Naval Navigation and Communication Systems Market
Communication Navigation & Surveillance
Naval Tactical Communication Market
Communication Navigation & Surveillance
Weapon Locating Radar Market
Communication Navigation & Surveillance
Space Situational Awareness (SSA) Systems Market