
 Global Antenna Market | 2026-2036
Global Antenna Market Size, Share, and Industry Trends Forecast 2026-2036
Global Antenna Market Analysis
Multi-sourced antenna procurement is expanding across telecom equipment manufacturers seeking supply chain resilience. CommScope Holding Company Inc. leverages its broadband infrastructure heritage to dominate North American cable operator supply. Murata Manufacturing Co., Ltd. anchors high-frequency component supply for smartphone OEMs through ceramic-based solutions. TE Connectivity Ltd. competes in ruggedized industrial and automotive antenna segments with connector-integrated designs.
An antenna converts electrical signals into electromagnetic waves and vice versa, typically operating across specified frequency bands with gain measured in decibels relative to an isotropic radiator. Manufacturing employs precision metallization, dielectric substrate lamination, and automated tuning to achieve impedance matching and radiation pattern consistency for reliable wireless communication. Microstrip antennas capture margin pools in consumer electronics where planar integration and low profile dominate design constraints. Military applications sustain premium pricing through phased-array architectures with beam-steering capabilities. 5G technology segments outpace 4G replacements as massive MIMO deployments require densely packed radiating elements.
The FCC mandates electromagnetic compatibility testing under Part 15 rules for unlicensed device antennas, while ETSI enforces harmonized spectrum efficiency standards across European member states. China's MIIT coordinates GB standards compliance with domestic 5G base station procurement specifications, creating market access filters for foreign suppliers. Stakeholders must monitor spectrum auction outcomes and O-RAN interoperability mandates to anticipate procurement shifts among tier-one operators.
Market Dynamics
Massive MIMO architecture deployment by mobile network operators is compressing antenna element spacing requirements while multiplying channel capacity demands per base station site.
Growth Catalysts
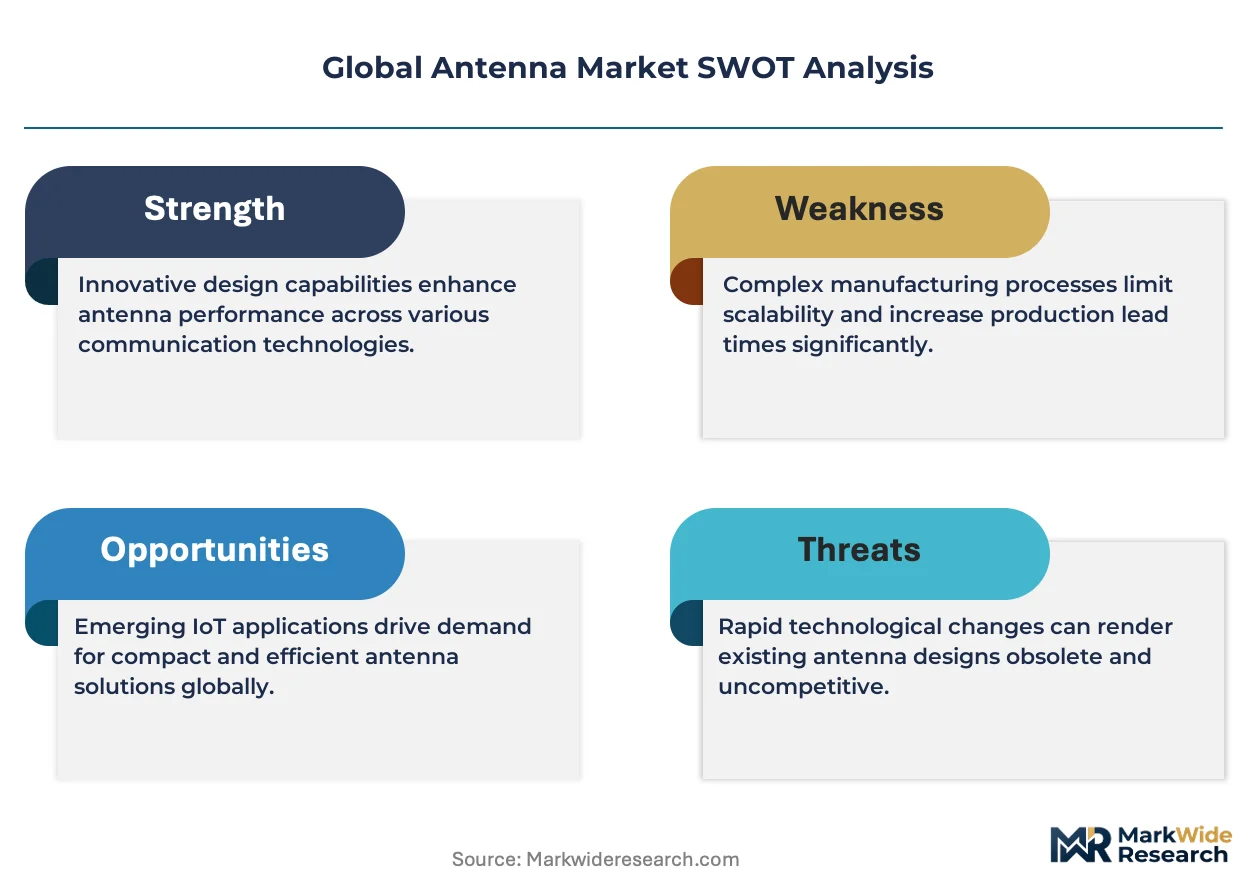
- 5G spectrum auctions:The FCC's mid-band reallocation creates immediate procurement windows for C-band and mmWave antenna arrays across United States carrier networks.
- Automotive radar integration:77-81 GHz antenna modules penetrate vehicle safety systems as NHTSA mandates advance driver-assistance capabilities.
- Smartphone ceramic antenna adoption:High-frequency 5G FR2 bands drive LTCC substrate demand for compact handheld devices.
Market Restraints
- Gallium arsenide substrate concentration:Six-inch wafer supply concentrates among three foundries, creating input cost volatility for III-V semiconductor antennas.
- Phased-array thermal limits:Active electronically scanned arrays face power dissipation ceilings that constrain transmit power in compact platforms.
- REACH substance restrictions:European ECHA candidate list expansion threatens lead-free solder alternatives and certain dielectric formulations.
Strategic Opportunities
- India telecom infrastructure:Reliance Jio and Bharti Airtel 5G rollouts under TRAI spectrum guidelines create fresh demand for sub-6 GHz massive MIMO panels.
- Satellite terminal flat panels:Low Earth orbit constellation ground equipment converges electronically steered antennas with consumer price points.
- EU Green Deal incentives:Energy-efficient base station designs qualify for recovery funding, favoring antenna systems with integrated power amplifiers.
Industry Challenges
- Electromagnetic simulation talent scarcity:Computational electromagnetics expertise for full-wave 3D modeling commands premium wages across RF engineering functions.
- O-RAN interoperability certification:Open radio access network split 7-2x fronthaul specifications delay product qualification timelines for multi-vendor deployments.
- Legacy coaxial infrastructure integration:Existing 4G feeder cable networks resist retrofit for fiber-optic fronthaul without site reconstruction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Antenna Market |
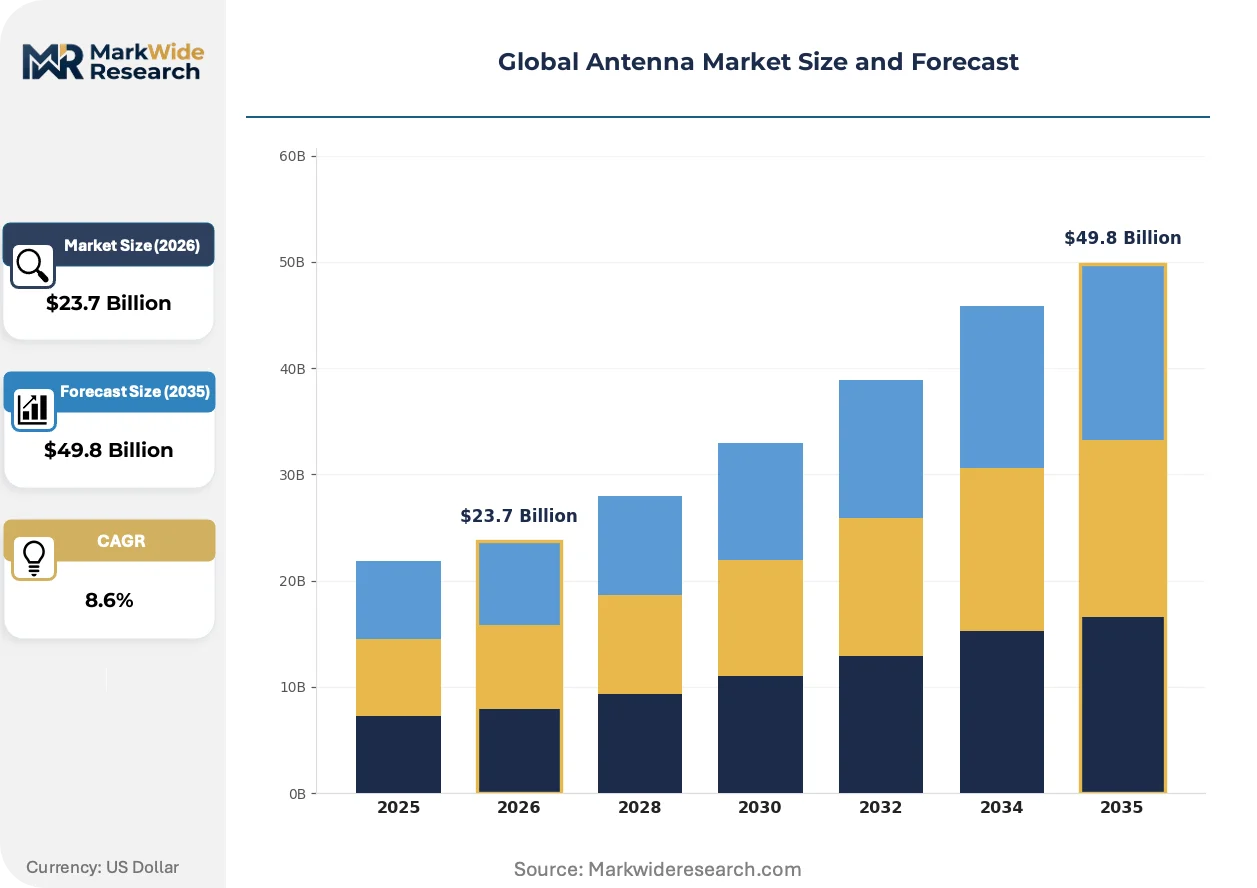
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $49.8 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wire Antennas, Yagi Antennas, Microstrip Antennas, Parabolic Antennas Application: Telecommunications, Broadcasting, Satellite Communication, Military End User: Consumer Electronics, Automotive, Aerospace, Healthcare Technology: 4G, 5G, Wi-Fi, Bluetooth |
| Companies Covered | Amphenol Corporation, Molex, LLC, CommScope Holding Company Inc., Airgain, Inc., Galtronics USA, Inc., Murata Manufacturing Co., Ltd., TE Connectivity Ltd., Sunway Communication Co., Ltd., Linx Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Antenna Market Emerging Trajectories
Metamaterial surfaces and reconfigurable intelligent surfaces are rewriting antenna physics, enabling beam manipulation without mechanical steering or dense active element arrays.
Reconfigurable intelligent surfaces are absorbing passive scattering functions previously requiring powered amplification. Telecom infrastructure deployers in Germany and South Korea pilot programmable metasurface panels that redirect signals around obstacles. This architecture is absorbing relay station capex while reducing base station density requirements in urban canyons.
ETSI's harmonized standard for 6 GHz Wi-Fi 6E and 7 devices mandates automated frequency coordination protocols. European manufacturers must embed sensing capabilities that detect incumbent radar and satellite services. The unlicensed device segment faces redesign cycles to satisfy listen-before-talk specifications across 27 EU member states.
Defense procurement agencies now bundle antenna subsystems with integrated cyber-resilience specifications. United States Department of Defense contracts require supply chain provenance documentation and anti-tamper hardware for tactical communications. This certification-driven preference shift filters vendor eligibility toward domestic or allied-nation manufacturing sources.
Global Antenna Market Segmentation
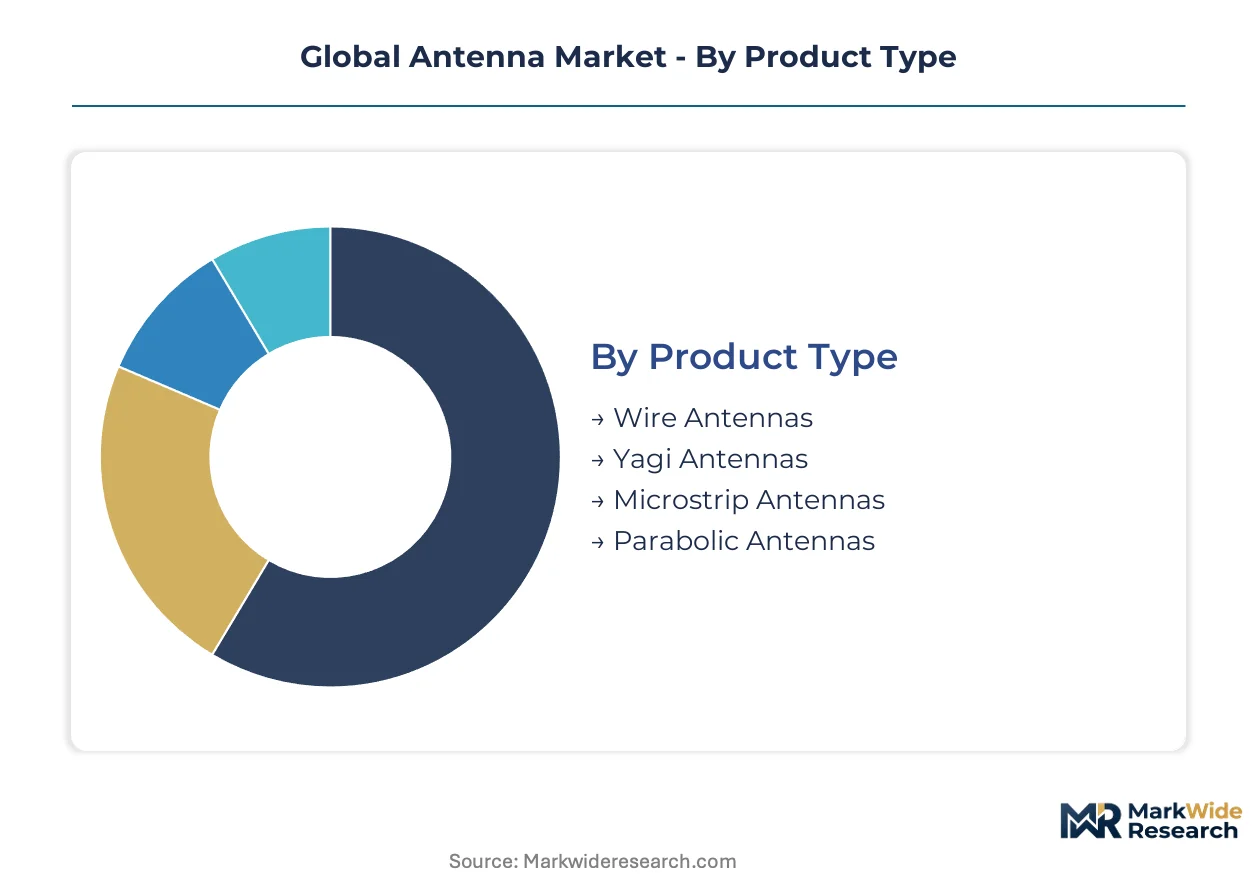
Antenna procurement patterns diverge sharply across frequency requirements, physical form factors, and regulatory compliance burdens. Understanding these segment boundaries enables suppliers to align R&D pipelines with operator deployment timelines and certification pathways.
Product Type:
Volume manufacturing concentrates on planar structures for consumer devices, while premium pricing attaches to steerable architectures for infrastructure and defense.
- Wire Antennas:Simple conductive elements—dipoles, loops, and helices—fabricated from copper or aluminum alloys dominate AM/FM broadcast and basic IoT telemetry. Demand clusters in rural telecommunications retrofits across India and Brazil where cost minimization overrides performance optimization.
- Microstrip Antennas:Thin metallic patches printed on dielectric substrates enable flush mounting in smartphones and tablets. South Korean and Chinese OEMs drive procurement for 5G FR2 mmWave bands where substrate thickness directly impacts efficiency.
- Yagi Antennas:Directional arrays with driven and parasitic elements serve terrestrial television reception and point-to-point backhaul.
- Parabolic Antennas:Precision-molded reflector dishes focus signals for satellite earth stations and deep-space communications.
Mature deployment sits with wire antennas in legacy broadcast. Newer deployment is concentrated in microstrip arrays for handheld 5G.
Application:
Commercial infrastructure absorbs the majority of unit volume, yet defense programs sustain the highest per-unit margins through classified performance specifications.
- Telecommunications:Base station antennas for macro cells, small cells, and massive MIMO configurations handle subscriber density in urban corridors. China's MIIT-coordinated buildouts and India's TRAI-spectrum auctions are compressing supplier lead times for sub-6 GHz panels.
- Military:Phased-array radars and tactical communications demand radiation pattern agility under electronic countermeasure conditions. United States Department of Defense contracts now mandate anti-tamper hardware and supply chain provenance documentation.
- Broadcasting:Terrestrial television and radio transmission infrastructure requires wideband impedance matching.
- Satellite Communication:Ground terminals for geostationary and low Earth orbit constellations require polarization tracking.
Telecommunications generates the steepest expansion trajectory as 5G massive MIMO multiplies radiating elements per site. Military procurement is gaining share fastest through cyber-resilience bundling.
End User:
Automotive integration is displacing consumer electronics as the primary volume growth vector, driven by safety mandate acceleration.
- Automotive:77-81 GHz radar modules for adaptive cruise control and collision avoidance integrate patch antennas behind bumper fascias. NHTSA mandates in the United States and equivalent regulations in Germany and Japan are standardizing multi-sensor fusion architectures.
- Consumer Electronics:Smartphones, tablets, and wearables embed ceramic-based antennas for cellular and short-range wireless. LTCC substrate demand concentrates among Chinese and Vietnamese assembly operations.
- Aerospace:Commercial aviation and unmanned platforms require conformal antennas with minimal drag profiles.
- Healthcare:Implantable and wearable medical devices demand biocompatible encapsulation with stable impedance.
Consumer electronics holds mature deployment in smartphone saturation markets. Automotive represents the fastest-climbing segment through radar mandate proliferation.
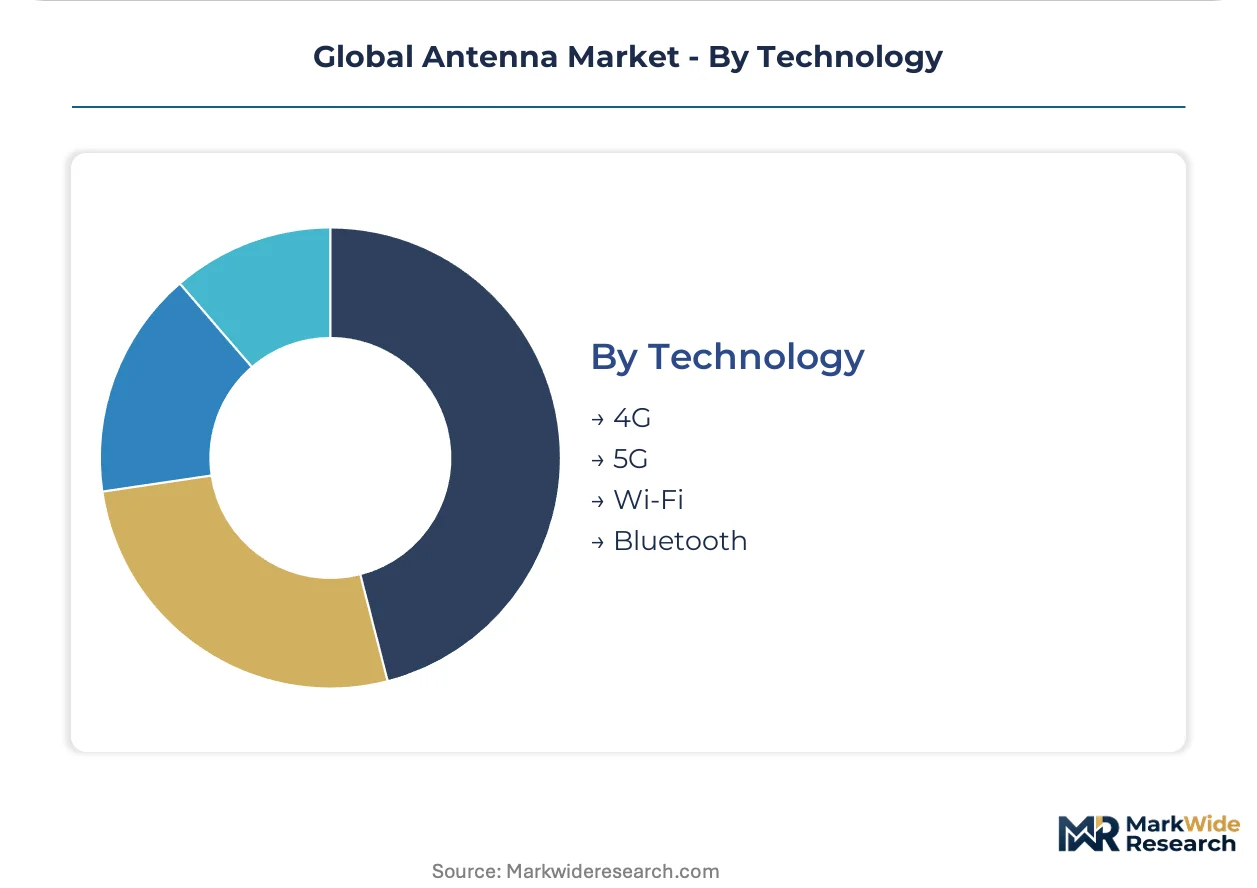
Technology:
Generational transitions in cellular standards are fragmenting supplier portfolios across incompatible frequency allocations and modulation schemes.
- 5G:Massive MIMO and beamforming architectures require densely packed radiating elements with active impedance tuning. C-band and mmWave deployments in the United States, South Korea, and Germany are driving qualification cycles for integrated antenna-radio units.
- Wi-Fi:6E and 7 standards expand into 6 GHz spectrum with automated frequency coordination mandates under ETSI harmonized rules. European manufacturers must embed radar detection sensing.
- 4G:Legacy LTE infrastructure sustains replacement demand and rural coverage extension.
- Bluetooth:Low-energy protocols for IoT peripherals utilize compact ceramic chip antennas.
4G represents mature deployment in maintenance and rural infill. 5G is concentrating newer deployment through spectrum auction execution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gallium arsenide wafer fabrication concentrates in Taiwan, Japan, and the United States, creating foundational supply dependencies for III-V semiconductor antennas deployed across 5G infrastructure and defense platforms worldwide.
United States
FCC spectrum reallocation for C-band and mmWave bands accelerates massive MIMO procurement by Verizon, AT&T, and T-Mobile. NHTSA mandates for 77-81 GHz automotive radar compress qualification timelines for domestic tier-one suppliers. Phoenix and Austin anchor defense antenna development clusters where Raytheon and Lockheed Martin coordinate phased-array production for tactical communications.
Germany
Telefónica and Deutsche Telekom 5G rollouts under BNetzA spectrum guidelines drive demand for sub-6 GHz base station antennas. EU Green Deal recovery funding prioritizes energy-efficient base station designs with integrated power amplifiers. Munich and Stuttgart host automotive radar engineering centers where Bosch and Continental develop conformal antenna modules for adaptive cruise control systems.
China
MIIT-coordinated 5G base station buildouts by China Mobile, China Telecom, and China Unicom concentrate demand for massive MIMO panels. GB standards compliance creates market access filters favoring domestic suppliers for state-backed carrier procurement. Shenzhen and Dongguan cluster LTCC substrate manufacturing for smartphone ceramic antennas serving OPPO, vivo, and Xiaomi assembly operations.
South Korea
SK Telecom and KT Corporation mmWave deployments in Seoul and Busan require densely packed antenna-radio units for urban corridor coverage. MSIT spectrum management aligns 28 GHz allocations with equipment qualification protocols. Suwon and Gumi anchor Samsung Electronics and LG Innotek antenna module production for 5G FR2 handheld devices and automotive radar integration.
India
Reliance Jio and Bharti Airtel 5G expansions under TRAI spectrum guidelines generate fresh demand for sub-6 GHz massive MIMO panels in Delhi-Mumbai corridors. PLI scheme incentives for telecom equipment manufacturing attract component suppliers to establish local assembly. Bengaluru and Hyderabad cluster RF engineering talent pools supporting indigenous antenna design for rural telecommunications retrofits and satellite ground terminals.
Global Antenna Market Vendor Landscape
Global majors compete with regional champions across certification pathways and spectrum-specific product portfolios. The vendor base organizes into three tiers: integrated connectivity conglomerates with broadband infrastructure heritage, ceramic substrate specialists serving high-frequency consumer electronics, and ruggedized industrial component fabricators. Consolidation pressures intensify as O-RAN interoperability mandates force multi-vendor qualification investments. Dominant competitive moves include strategic partnerships for fronthaul integration and geographic expansion into India and Southeast Asia.
Among United States-based connectivity conglomerates, CommScope Holding Company Inc. and Amphenol Corporation exemplify infrastructure-scale positioning through broadband heritage and connector-integrated architectures. Murata Manufacturing Co., Ltd. and TE Connectivity Ltd. represent divergent specialization vectors—ceramic-based high-frequency solutions versus ruggedized industrial and automotive segments. Sunway Communication Co., Ltd. anchors Chinese volume manufacturing for smartphone antenna modules.
| Leading Market Players |
|---|
| Amphenol Corporation |
| Molex, LLC |
| CommScope Holding Company Inc. |
| Airgain, Inc. |
| Galtronics USA, Inc. |
| Murata Manufacturing Co., Ltd. |
| TE Connectivity Ltd. |
| Sunway Communication Co., Ltd. |
| Linx Technologies |
| Others |
Supply Flow & Price Mechanics
State-backed carrier procurement in China concentrates demand volume for massive MIMO panels, forcing suppliers into competitive bidding structures that compress margins while demanding extended warranty coverage and field service bundling. This buyer concentration enables tier-one operators to extract price concessions through multi-year framework agreements that lock in volume commitments.
Pricing Analysis
After-sales service bundling separates premium antenna suppliers from commodity competitors, with field calibration and remote diagnostics now standard in telecommunications infrastructure contracts. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—FCC Part 15 and ETSI harmonized compliance command 15-20% premiums over unlicensed device alternatives. Cost compression in consumer electronics microstrip antennas intensifies as Chinese OEMs consolidate procurement through LTCC substrate specialists. Automotive radar modules exhibit lowest price sensitivity due to NHTSA mandate-driven specification rigidity, while rural telecommunications retrofits in India and Brazil face acute budget constraints.
Supply Chain Analysis
Freight cost volatility from Taiwan and Japan to North American defense contractors has prompted strategic inventory positioning for gallium arsenide wafers and ceramic dielectric substrates. Six-inch GaAs wafer fabrication concentrates in Taiwan, Japan, and the United States, creating input dependencies for III-V semiconductor antennas deployed across 5G infrastructure and phased-array radar platforms. REACH substance restrictions and ECHA candidate list expansion threaten lead-free solder alternatives, introducing regulatory compliance risk into European supply channels. Distribution runs through tier-one telecom equipment manufacturers who integrate antenna-radio units before carrier site deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around O-RAN interoperability certification requirements that force multi-vendor qualification investments beyond mid-tier specialist capabilities. Smaller players lacking fronthaul integration partnerships face exclusion from tier-one operator procurement shortlists.
For Market Incumbents: Hedge against margin erosion in commoditized microstrip consumer electronics by deepening backward integration into LTCC substrate manufacturing in Shenzhen and Dongguan clusters. Pursue anti-tamper hardware certification for United States Department of Defense tactical communications contracts before cyber-resilience bundling filters vendor eligibility toward domestic or allied-nation sources. For New Entrants and Emerging Players: Satellite terminal flat panel manufacturers for low Earth orbit constellations represent an underserved buyer archetype seeking electronically steered antennas at consumer price points. Target this segment through software-defined beamforming architectures that bypass traditional phased-array thermal constraints. Establish engineering presence in Bengaluru and Hyderabad to access RF talent pools supporting indigenous antenna design for India's PLI scheme telecom equipment incentives. For Investors and Strategic Acquirers: The window for entry favors ceramic substrate specialists with established smartphone OEM relationships before 5G FR2 mmWave band proliferation saturates qualified supplier lists. Long-term viability hinges on capturing positions in automotive radar integration as NHTSA mandates standardize 77-81 GHz module deployment. Monitor O-RAN split 7-2x fronthaul specification finalization as the inflection indicator for multi-vendor deployment qualification timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into LTCC Substrates | Captures margin pools in 5G FR2 mmWave smartphone antenna procurement from Chinese OEMs. |
| Anti-Tamper Hardware Certification | Unlocks United States Department of Defense tactical communications contracts with cyber-resilience bundling requirements. |
| O-RAN Interoperability Qualification | Enables participation in multi-vendor fronthaul deployments by Deutsche Telekom and Telefónica. |
| Automotive Radar Module Partnership | Positions suppliers for NHTSA-mandated 77-81 GHz integration at Bosch and Continental engineering centers. |
| Reconfigurable Intelligent Surface Pilot | Absorbs relay station capex in German and South Korean urban canyon deployments through programmable metasurface panels. |
Methodological Framework
Trade association filings, customs records, and SEC 10-K disclosures formed the secondary backbone for supply chain mapping and competitive positioning assessment. Primary interviews with RF engineering directors at telecom equipment manufacturers, procurement leads at state-backed carriers, antenna module specialists at smartphone OEMs, and defense contract officers supplemented secondary validation. Bottom-up and top-down triangulation cross-checked unit volume assumptions against capital expenditure disclosures from China Mobile, Verizon, and Reliance Jio.
Bottom-up modeling aggregated segment-level demand across product type, application, end user, and technology dimensions over the projection horizon. Top-down validation anchored aggregate market size against carrier spectrum auction commitments and base station deployment schedules. CAGRs were derived from regression analysis of historical procurement patterns and forward-looking infrastructure buildout timelines. Forecast inputs incorporated MIIT-coordinated 5G base station targets, TRAI spectrum allocation trajectories, and FCC mid-band reallocation implementation pace.
Revisions become necessary when regulatory timing shifts, raw material supply disruptions, or O-RAN standard finalization delays materialize beyond modeled assumptions. Forecasts reflect documented assumptions about carrier capex cycles and semiconductor foundry capacity expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Navigation & Surveillance
Russia Autonomous Navigation Market
Communication Navigation & Surveillance
EMEA Mission Critical Wireless Communications Market
Communication Navigation & Surveillance
Doppler Radar Market
Communication Navigation & Surveillance
Asia-Pacific Inertial Systems Market
Communication Navigation & Surveillance
High-End Inertial Systems Market
Communication Navigation & Surveillance
Tactical Data Link Market
Communication Navigation & Surveillance
Latin America Inertial Systems Market
Communication Navigation & Surveillance
Navigation Satellite System Technology Market
Communication Navigation & Surveillance
Man-Portable Military Communication Systems Market
Communication Navigation & Surveillance
Coherent Radar Market
Communication Navigation & Surveillance
Tactical Inertial Systems Market
Communication Navigation & Surveillance
Naval Navigation and Communication Systems Market
Communication Navigation & Surveillance
Dual Axis Gyro Stabilized Platform Market
Communication Navigation & Surveillance
Tactical Communications Market
Communication Navigation & Surveillance
Airborne SATCOM Equipment Market
Communication Navigation & Surveillance
Tactical Radio Market