

High Frequency Military Communications Market Size, Share, and Industry Trends Forecast 2026-2036
High Frequency Military Communications Market Insights
The EU Green Deal is expanding military procurement sustainability criteria across European defense ministries, compelling suppliers to demonstrate energy-efficient transmission architectures and reduced electromagnetic footprints. L3Harris Technologies leverages its software-defined radio portfolio to sustain long-term platform refresh contracts with U.S. and allied forces. Thales Group anchors European supply through its dominance of NATO STANAG-compliant waveform development and battlefield network integration.
High frequency military communications encompass terrestrial and airborne radio systems operating within the 3-30 MHz band, utilizing skywave and near-vertical incidence skywave propagation to establish beyond-line-of-sight connectivity across hundreds to thousands of kilometers without satellite dependency. These systems employ automatic link establishment protocols, adaptive frequency management, and embedded encryption to maintain resilient command links in contested electromagnetic environments. Transceivers and software defined radio platforms capture the dominant share of product-level investment as forces prioritize modular, upgradeable architectures over fixed-function hardware. Frequency hopping and spread spectrum technologies represent the fastest-expanding technology categories, driven by requirements for low-probability-of-intercept signatures against sophisticated electronic warfare threats.
The U.S. Department of Defense mandates MIL-STD-188-141B interoperability standards, while NATO enforces STANAG 4538 for automatic link establishment across allied forces, creating dual compliance burdens for multinational suppliers. The FCC regulates spectrum allocation for military training and reserve operations within domestic territories, constraining frequency agility testing and development cycles. Stakeholders must monitor evolving electromagnetic spectrum superiority doctrines and corresponding procurement shifts toward cognitive radio and artificial intelligence-enabled frequency management.
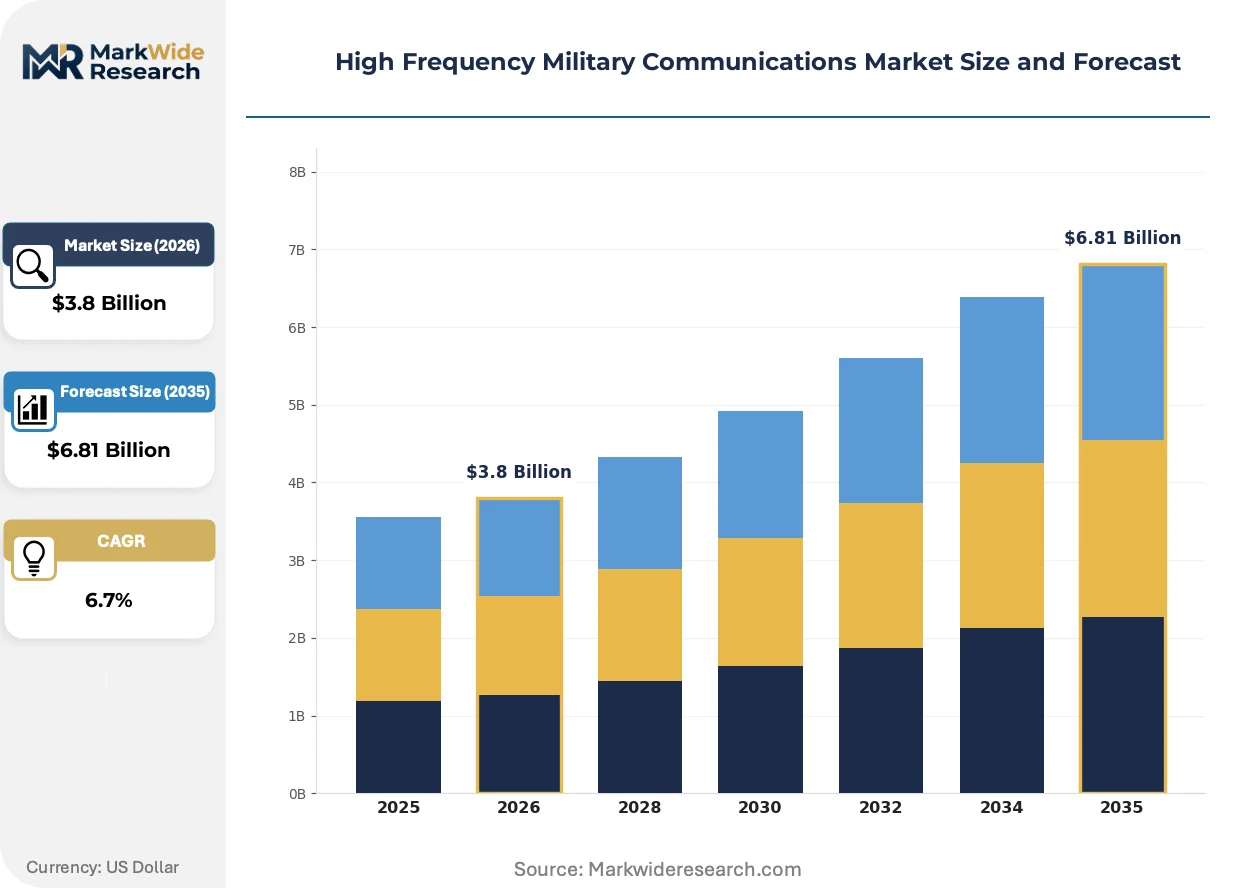
Market Dynamics
Software-defined radio architectures are compressing platform refresh cycles across NATO allied forces, as modular upgrade paths displace fixed-function hardware procurement and reshape supplier-contract structures.
Growth Catalysts
- NATO STANAG 4538 Mandate:Automatic link establishment protocols are becoming mandatory across allied naval and ground forces, forcing hardware refresh timelines and opening procurement windows for compliant waveform developers.
- Beyond-Line-of-Sight Naval Modernization:Surface combatant programs in the United States, United Kingdom, and Australia are accelerating skywave system deployment to reduce satellite dependency in contested theaters.
- Frequency Hopping Technology:Low-probability-of-intercept signatures against electronic warfare threats are driving investment in spread spectrum architectures across expeditionary force packages.
Market Restraints
- Dual Compliance Burden:Suppliers must simultaneously satisfy U.S. MIL-STD-188-141B and NATO STANAG requirements, extending certification timelines and fragmenting engineering resources across incompatible test regimes.
- Input Concentration Risk:Specialized high-power amplifiers and radiation-hardened semiconductors concentrate sourcing from a limited supplier base in East Asian manufacturing clusters.
- Spectrum Allocation Friction:FCC constraints on military training frequencies within domestic U.S. territories limit adaptive frequency management testing and compress development cycle efficiency.
Strategic Opportunities
- Cognitive Radio Convergence:Artificial intelligence-enabled frequency management systems offer white space for suppliers capable of integrating machine learning with legacy transceiver architectures.
- Australian Defense Investment:The AUKUS security pact is accelerating sovereign HF communications capability development, creating procurement channels outside traditional NATO supply chains.
- EU Green Deal Tailwinds:Energy-efficient transmission architectures and reduced electromagnetic footprint requirements are opening competitive differentiation for compliant European suppliers.
Industry Challenges
- Embedded Cryptography Talent Gap:Shortages of engineers with both signals intelligence and commercial encryption expertise are delaying secure waveform development timelines.
- Legacy System Integration Complexity:Fielded analog transceiver infrastructure across reserve and National Guard units requires costly bridging architectures to maintain interoperability with digital networks.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Frequency Military Communications Market Trends and Innovations
Adaptive frequency management and cognitive processing capabilities are displacing manual spectrum allocation across military communications architectures, compressing link establishment times and reducing operator workload in contested electromagnetic environments.
Artificial intelligence-enabled frequency prediction is electrifying tactical network resilience. Machine learning algorithms analyze real-time propagation data to anticipate optimal operating frequencies. U.S. Army and Marine Corps expeditionary units are piloting these systems for rapid deployment scenarios. This capability is compressing the competitive advantage window for suppliers lacking cognitive radio development pipelines.
EU Green Deal sustainability criteria are reshaping European defense procurement specifications. Energy efficiency benchmarks and electromagnetic footprint reduction mandates now accompany traditional performance requirements. French and German defense ministries are embedding these criteria into platform modernization tenders. Suppliers must demonstrate compliant architectures to maintain eligibility for core allied contracts.
Consolidated platform procurement is displacing component-level purchasing across major allied programs. Defense ministries are bundling transceiver, antenna, and encryption subsystems into single-vendor awards to reduce integration risk. This pattern is most visible in U.S. Navy and Royal Australian Navy surface combatant programs. Component specialists face margin pressure unless they secure tier-1 system integrator partnerships.
High Frequency Military Communications Market Segmentation
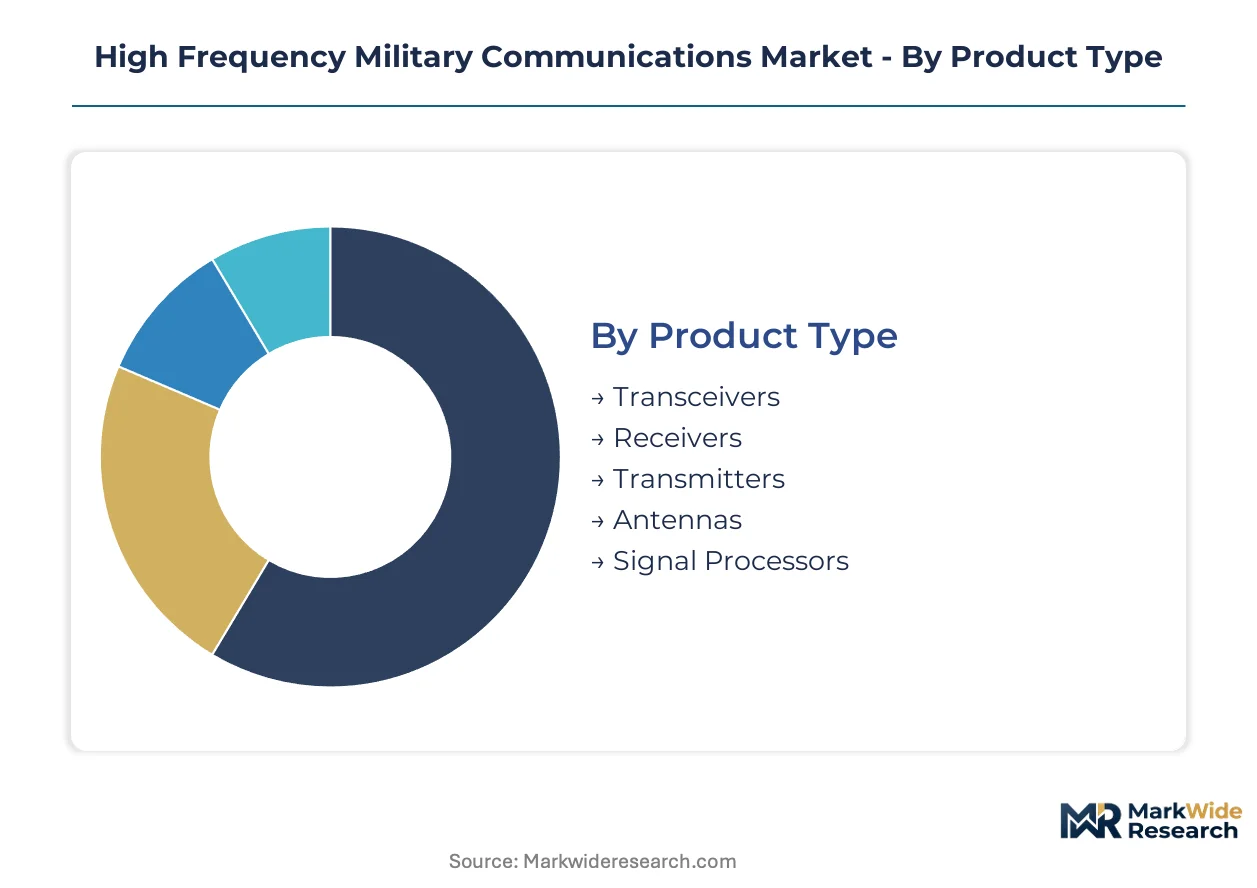
Segmentation in military HF communications reveals how procurement priorities fragment across technical architectures and operational domains. Defense ministries allocate budgets differently across hardware tiers, with modular systems commanding premium pricing against fixed-function alternatives. Understanding these splits exposes where supplier margins concentrate and where volume opportunities hide.
Product Type:
Volume procurement concentrates in transceiver platforms, while antenna subsystems capture premium engineering margins through custom integration requirements.
- Transceivers:Integrated transmit-receive units form the core hardware investment across tactical radio programs. U.S. Army expeditionary units and Royal Australian Navy surface combatants drive demand for software-upgradeable architectures that compress refresh cycles.
- Antennas:Skywave and near-vertical incidence skywave configurations require mission-specific tuning for beyond-line-of-sight propagation. NATO naval modernization programs in the United Kingdom and France prioritize compact, multi-band designs that reduce electromagnetic signatures aboard vessels.
- Receivers:Standalone reception hardware serves intelligence gathering and electronic warfare support roles.
- Transmitters:High-power amplification units support fixed-site command infrastructure and broadcast applications.
- Signal Processors:Digital baseband modules enable adaptive filtering and encryption offload in software-defined architectures.
Mature deployment sits with transceivers. Newer deployment is concentrated in signal processors as forces retrofit cognitive capabilities into fielded platforms.
Technology:
Cost tiering separates legacy waveform implementations from artificial intelligence-enabled frequency management systems that command development premiums.
- Software Defined Radio:Reconfigurable architectures displace fixed-function hardware through firmware-upgradable signal paths. U.S. Department of Defense MIL-STD-188-141B mandates and NATO STANAG 4538 compliance requirements accelerate procurement of modular platforms across allied forces.
- Frequency Hopping:Low-probability-of-intercept transmission protocols expand fastest against sophisticated electronic warfare threats. Australian Defense Force and U.S. Marine Corps expeditionary packages prioritize rapid-hop sequences for contested theater survivability.
- Automatic Link Establishment:Protocol-driven frequency negotiation reduces operator workload in dynamic spectrum environments.
- Spread Spectrum:Wideband signaling techniques enhance resistance to jamming and interception.
- Digital Signal Processing:Algorithmic waveform manipulation enables software-defined flexibility in legacy hardware envelopes.
Procurement volume clusters around software defined radio. Steepest expansion trajectory belongs to frequency hopping as electronic warfare threats intensify across Indo-Pacific theaters.
Application:
Customer type differentiation separates platform-integrated programs from standalone tactical procurement, with naval systems commanding longer contract horizons.
- Naval Communications:Shipboard skywave systems provide beyond-line-of-sight connectivity independent of satellite vulnerability. U.S. Navy and Royal Navy surface combatant programs accelerate installation of NATO STANAG-compliant architectures to reduce theater dependency.
- Battlefield Communications:Man-portable and vehicle-mounted systems serve expeditionary ground forces. U.S. Army and British Army modernization timelines prioritize automatic link establishment for rapid deployment scenarios.
- Airborne Communications:Aircraft-integrated HF supports long-range patrol and transport missions.
- Command & Control:Fixed-site infrastructure maintains strategic connectivity across continental distances.
- Intelligence Gathering:Signals collection platforms exploit HF propagation for intercept and direction-finding operations.
Platform integration maturity sits with command and control infrastructure. Newer deployment is concentrated in naval communications as surface combatant programs accelerate across AUKUS partners.
End User:
Margin structure varies by procurement authority, with special operations units funding rapid technology insertion outside standard platform refresh cycles.
- Naval Forces:Surface combatant and submarine programs drive integrated system procurement with multi-year contract structures. Royal Australian Navy and U.S. Navy bundling of transceiver, antenna, and encryption subsystems reduces integration risk through single-vendor awards.
- Special Operations:Expeditionary units prioritize rapid fielding of low-probability-of-intercept capabilities. U.S. Army Special Forces and British Special Boat Service procurement channels bypass standard acquisition timelines for emerging frequency hopping and cognitive radio technologies.
- Army Units:Ground force modernization spans active duty and reserve component equipment refresh.
- Air Force Squadrons:Long-range patrol and transport aircraft integration requires airborne-qualified hardware.
- Defense Contractors:System integrators and subsystem suppliers serve as indirect procurement channels for platform OEMs.
Established procurement volume sits with army units. Newer deployment is concentrated in special operations as irregular warfare doctrine drives technology acceleration outside standard programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Washington DC-Arlington corridor anchors defense procurement concentration for high frequency military communications, with Pentagon acquisition offices and NATO liaison commands co-located to compress contract award timelines.
United States
U.S. Navy surface combatant programs and Army expeditionary units drive procurement volume for software-defined radio architectures. FCC spectrum allocation constraints on domestic military training frequencies compress development cycle efficiency for adaptive frequency management systems. The San Diego naval cluster hosts integration facilities for beyond-line-of-sight skywave systems aboard Pacific Fleet vessels.
United Kingdom
Royal Navy modernization and British Army rapid deployment requirements accelerate demand for NATO STANAG 4538-compliant automatic link establishment protocols. Ministry of Defence procurement frameworks embed interoperability mandates that extend certification timelines for multinational suppliers. The Portsmouth naval base serves as the primary integration site for shipboard HF communications aboard Type 26 and Type 31 frigates.
Australia
AUKUS security pact commitments are accelerating sovereign HF capability development outside traditional NATO supply chains. Australian Defense Force procurement channels prioritize low-probability-of-intercept frequency hopping systems for Indo-Pacific theater survivability. The Osborne naval shipyard in South Australia hosts surface combatant construction programs bundling transceiver, antenna, and encryption subsystems.
Germany
Bundeswehr platform modernization and NATO burden-sharing obligations drive investment in energy-efficient transmission architectures compliant with EU Green Deal sustainability criteria. Federal Office for Information Security regulations govern embedded cryptography standards for tactical radio systems. The Kiel naval cluster concentrates subsystem integration for German Navy surface combatants and submarine programs.
France
French Navy aircraft carrier and surface combatant programs sustain demand for compact multi-band antenna designs reducing electromagnetic signatures. Direction Générale de l'Armement procurement specifications integrate electromagnetic footprint reduction mandates alongside traditional performance benchmarks. The Toulon naval base anchors Mediterranean Fleet HF communications modernization timelines.
High Frequency Military Communications Market Competitive Landscape
Premium-margin players sit above commodity-margin players across waveform development capability and NATO STANAG certification depth. The supplier base concentrates around three structural tiers: full-spectrum system integrators bundling transceiver, antenna, and encryption subsystems; waveform specialists commanding recurring licensing revenue from protocol compliance; and component suppliers feeding tier-one platforms. Consolidation pressure intensifies as defense ministries consolidate procurement into single-vendor awards, while dual compliance burdens for U.S. MIL-STD and NATO standards extend engineering resource fragmentation.
Within the full-spectrum integrator tier, L3Harris Technologies and Thales Group exemplify contrasting geographic anchors for allied procurement flows. L3Harris occupies a position aligned with U.S. Department of Defense platform refresh cycles, while Thales anchors European supply through NATO STANAG-compliant waveform development concentration. Rohde & Schwarz represents the specialized instrumentation and test equipment archetype that sustains certification infrastructure for compliance-heavy procurement regimes.
| Leading Market Players |
|---|
| L3Harris Technologies |
| Thales Group |
| Collins Aerospace |
| Elbit Systems |
| Leonardo |
| BAE Systems |
| Rohde & Schwarz |
| General Dynamics |
| Viasat |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between NATO STANAG-compliant waveform developers and commodity transceiver suppliers manifests in both pricing premiums and supply chain exclusivity arrangements. Defense ministries award multi-year platform refresh contracts to certified integrators while relegating uncertified component vendors to spot-market procurement with compressed margins.
Pricing Analysis
Value-based pricing anchored to mission uptime guarantees dominates procurement for expeditionary force packages. Three-tier pricing structure across premium, standard, and economy levels separates full-spectrum system integrators from waveform specialists and component suppliers. Pricing pressure stems from consolidated single-vendor awards bundling transceiver, antenna, and encryption subsystems. Special operations units exhibit lowest price sensitivity due to rapid fielding mandates outside standard acquisition timelines.
Supply Chain Analysis
MIL-STD-188-141B and NATO STANAG qualification gating restricts amplifier and semiconductor sourcing to radiation-hardened foundries in the United States, Germany, and Japan. High-power gallium nitride devices and software-defined radio chipsets draw from specialized defense-qualified fabrication lines. Single-source vulnerability concentrates in East Asian packaging and testing facilities. Distribution runs through prime defense contractors with direct platform OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Defense procurement consolidation into single-vendor awards is accelerating margin compression for component specialists without tier-1 integrator partnerships. Dual compliance burdens for U.S. and NATO standards are forcing weaker engineering teams toward exit.
For Market Incumbents: To counter embedded cryptography talent shortages delaying secure waveform development, L3Harris Technologies and Thales Group should deepen vertical integration into software-defined radio firmware pipelines while securing exclusive antenna subsystem partnerships with Royal Australian Navy and U.S. Navy surface combatant programs. For New Entrants and Emerging Players: Begin with cognitive radio convergence opportunities in Australian Defense Force procurement channels outside traditional NATO supply chains. AUKUS sovereign capability development represents the most penetrable geography. Pursue rapid-hop frequency hopping specialization for U.S. Marine Corps expeditionary packages through direct special operations procurement channels. For Investors and Strategic Acquirers: Re-rating potential sits with waveform specialists commanding recurring NATO STANAG licensing revenue given accelerating automatic link establishment mandates across allied naval forces. Long-term viability favors targets with demonstrated STANAG 4538 certification depth. Monitor electromagnetic spectrum superiority doctrine shifts as inflection indicators for cognitive radio investment prioritization.| Strategic Initiative | Industry Significance |
|---|---|
| STANAG 4538 Waveform Certification | Unlocks multi-year NATO allied procurement contracts across surface combatant programs. |
| Software-Defined Radio Platform Integration | Compresses refresh cycles and displaces fixed-function hardware across U.S. Army expeditionary units. |
| AUKUS Supply Chain Partnership | Establishes sovereign HF capability channels outside traditional European defense procurement flows. |
| Cognitive Radio R&D Investment | Captures artificial intelligence-enabled frequency management premiums in contested electromagnetic environments. |
| EU Green Deal Compliance Program | Secures eligibility for French and German defense ministry platform modernization tenders. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with program managers at U.S. Navy PEO C4I, Royal Australian Navy capability acquisition staff, and NATO communications standardization directors combined with secondary validation from FCC spectrum allocation dockets, EU Green Deal defense procurement specifications, and AUKUS implementation guidance. Bottom-up equipment procurement tracking and top-down defense budget allocation analysis provided triangulation across the analysis window.
Segment-level granularity modeled product type at transceiver-antenna-processor disaggregation, technology at software-defined versus fixed-function architecture, application at naval-battlefield-airborne-command differentiation, and end user at special operations versus conventional force procurement authority. CAGRs derived from equipment refresh timeline compression and platform modernization schedule acceleration. Forecast inputs incorporated electromagnetic spectrum superiority doctrine evolution and STANAG mandate implementation pace.
Allied interoperability commitment reversals, AUKUS pact restructuring, and cognitive radio technology maturation delays are the dominant revision risks to projection assumptions. A model refresh is warranted upon material change in NATO STANAG 4538 enforcement timelines or electromagnetic spectrum allocation policy shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.