
 Global X-Band Radar Market | 2026-2036
Global X-Band Radar Market Size, Share, and Industry Trends Forecast 2026-2036
Global X-Band Radar Market Foresight
Aftermarket service revenue is reshaping margin distribution across the X-Band radar value chain, pulling profitability from initial hardware sales into lifecycle sustainment contracts. RTX Corporation leverages its integrated defense electronics portfolio to capture long-term platform support agreements. Saab AB anchors its regional footprint through localized maintenance hubs and training infrastructure. Northrop Grumman Corporation differentiates via advanced signal-processing architectures that extend operational lifespans of deployed systems.
X-Band radar denotes coherent detection systems operating within the 8.0–12.0 GHz frequency window, employing parabolic or phased-array apertures to achieve centimetric resolution for target discrimination, weather cell mapping, and surface tracking at ranges extending to hundreds of nautical miles. Solid-state technology dominates new procurement for maritime and weather applications due to improved mean-time-between-failures and reduced cooling overhead, while traveling wave tube amplifiers retain share in high-power defense platforms where peak output requirements exceed solid-state thresholds. Mobile radar configurations represent the fastest-expanding product category as expeditionary forces and disaster response agencies prioritize rapid deployability over fixed-site installations.
The Federal Communications Commission and the Federal Aviation Administration in the United States, EASA and EU radio spectrum frameworks in Europe, and Japan's Ministry of Internal Affairs and Communications collectively govern X-Band allocation, emission limits, and interference mitigation protocols that constrain product design and market entry. Compliance with ITU-R spectrum coordination standards shapes export eligibility for manufacturers targeting cross-border defense and aviation contracts. Stakeholders must monitor evolving frequency reallocation proceedings and dual-use export control harmonization to anticipate procurement timeline disruptions and qualification cost shifts.
Market Dynamics
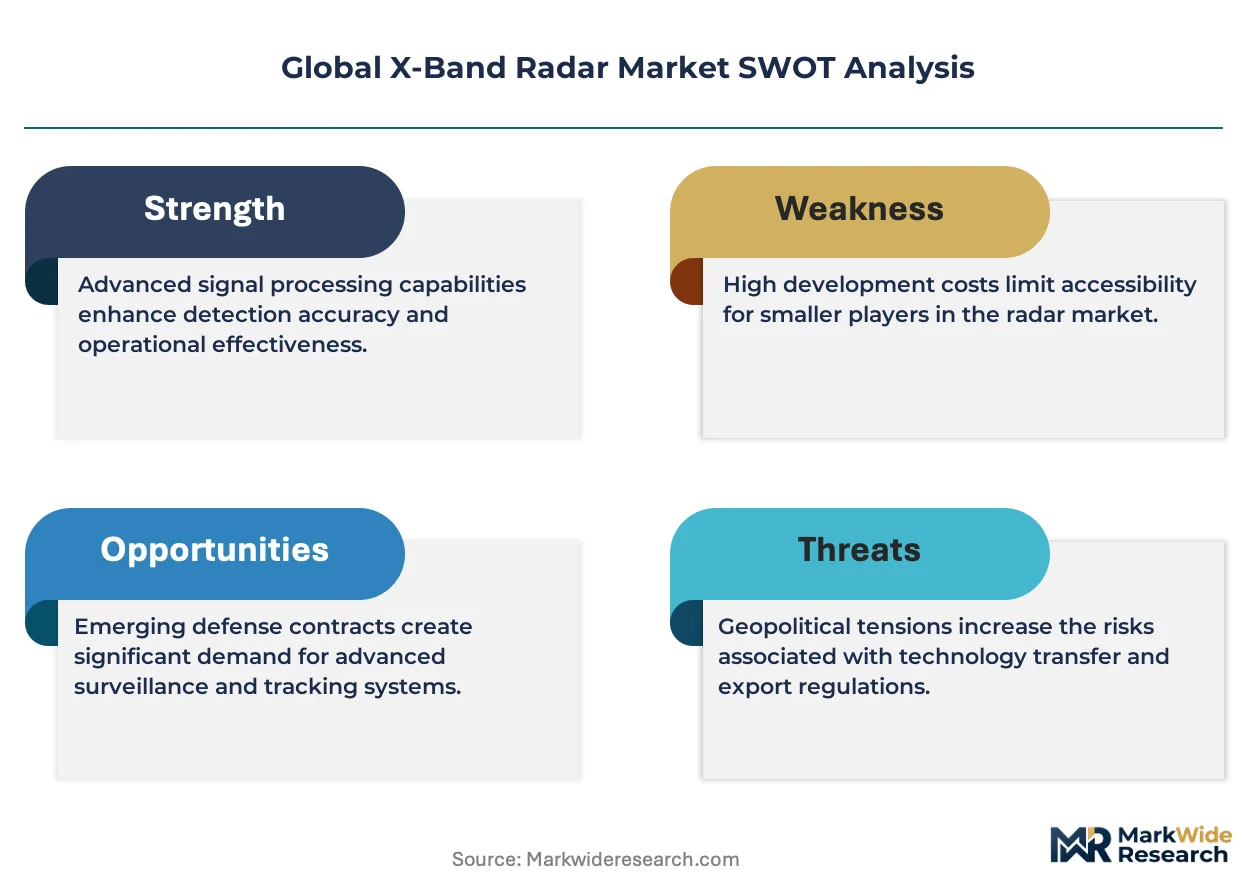
Solid-state transmitter technology is displacing magnetron architectures across maritime and weather radar installations, tightening efficiency mandates from the FCC, EASA, and Japan's Ministry of Internal Affairs and Communications while compressing procurement cycles for legacy system replacements.
Growth Catalysts
- Port Modernization Mandates:Coastal infrastructure upgrades across Singapore, Rotterdam, and Long Beach are driving synchronized procurement of X-Band navigation systems for vessel traffic management and berthing precision.
- Solid-State Reliability Standards:Mean-time-between-failures improvements of solid-state transmitters are accelerating fleet-wide retrofits as commercial shipping operators prioritize uptime over initial acquisition cost.
- Indo-Pacific Territorial Monitoring:Overlapping coastal surveillance requirements and commercial shipping density in the South China Sea corridor are creating dual-use procurement cycles for naval and maritime safety platforms.
Market Restraints
- Traveling Wave Tube Dependency:High-power defense applications exceeding solid-state output thresholds remain captive to traveling wave tube amplifier supply chains concentrated in specialized aerospace electronics manufacturers.
- Spectrum Reallocation Friction:ITU-R coordination proceedings for X-Band frequency sharing with 5G terrestrial networks are extending qualification timelines and raising certification costs for new market entrants.
- Gallium Nitride Substrate Constraints:Solid-state transmitter production depends on gallium nitride semiconductor foundry capacity, where defense and telecommunications demand are competing for limited wafer supply.
Strategic Opportunities
- Mobile Radar Configurations:Expeditionary military forces and disaster response agencies in Australia and Southeast Asia are prioritizing rapid-deployable trailer-mounted systems over fixed-site installations.
- Dual-Use Export Harmonization:Convergence of Wassenaar Arrangement controls and EU dual-use regulation revisions are streamlining cross-border defense and aviation contract eligibility for qualified manufacturers.
- Lifecycle Sustainment Contracts:Aftermarket service revenue is pulling profitability from initial hardware sales into long-term platform support agreements spanning signal processor upgrades and antenna refurbishment.
Industry Challenges
- RF Engineering Talent Scarcity:Specialized expertise in phased-array calibration and gallium nitride thermal management is concentrating among defense contractors, constraining commercial sector hiring pipelines.
- Legacy System Integration Complexity:New solid-state transmitters must interface with existing magnetron-era antenna pedestals and display consoles, requiring custom interface development for each retrofit installation.
- Multi-Jurisdiction Certification Burden:Simultaneous FCC, EASA, and Japan MIC approval processes for maritime radar exports are extending time-to-revenue by 18-24 months for new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global X-Band Radar Market |
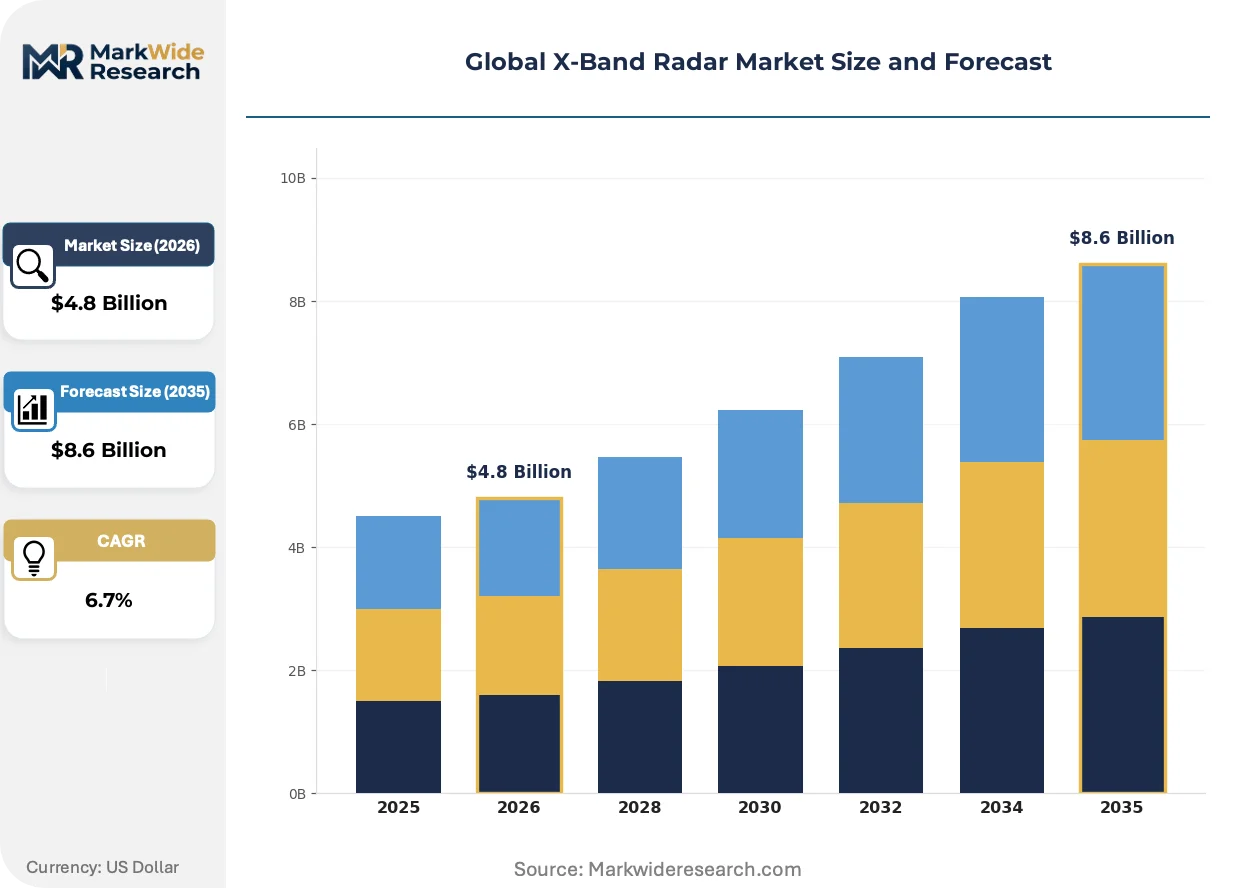
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stationary Radar, Mobile Radar, Maritime Radar, Weather Radar, Spaceborne Radar Technology: Solid State, Magnetron, Traveling Wave Tube, Doppler, Synthetic Aperture Radar Application: Air Traffic Control, Border Surveillance, Maritime Navigation, Weather Forecasting, Space Research End User: Defense Forces, Meteorological Organizations, Shipping Companies, Aerospace Manufacturers, Research Institutes |
| Companies Covered | RTX Corporation, Saab AB, Leonardo S.p.A., Furuno Electric Co., Ltd., Israel Aerospace Industries, Northrop Grumman Corporation, Hensoldt AG, Japan Radio Co., Ltd., Thales, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global X-Band Radar Market Shifts & Advancements
Software-defined architectures are virtualizing signal processing functions that previously required dedicated hardware, compressing product development cycles and enabling over-the-air capability upgrades without physical retrofits.
Active electronically scanned arrays are virtualizing beam steering through solid-state phase shifters rather than mechanical antenna rotation. Naval surface combatants and offshore patrol vessels are adopting these configurations for multi-target tracking and electronic protection. This virtualization is collapsing the distinction between search and track radar functions, reducing platform sensor count.
The EU AI Act and accompanying product liability frameworks are imposing algorithmic transparency requirements on autonomous radar target classification systems. Manufacturers must now document training data provenance and decision boundary logic for maritime collision avoidance algorithms. Weather radar segments are responding by segregating AI-enhanced nowcasting features into separately certifiable software modules.
Defense procurement agencies are unbundling hardware acquisition from sustainment services, creating separate contracting vehicles for initial system delivery and decade-long maintenance. This bifurcation is visible most acutely in US Navy and Royal Australian Navy maritime radar programs, where original equipment manufacturers now compete with third-party service providers for depot-level repair contracts.
Global X-Band Radar Market Segmentation
X-Band radar procurement cycles vary dramatically by segment, with defense platforms operating on 15-20 year refresh timelines while commercial maritime systems turn over every 7-10 years. Understanding these velocity differentials helps manufacturers align R&D pipelines with revenue recognition patterns.
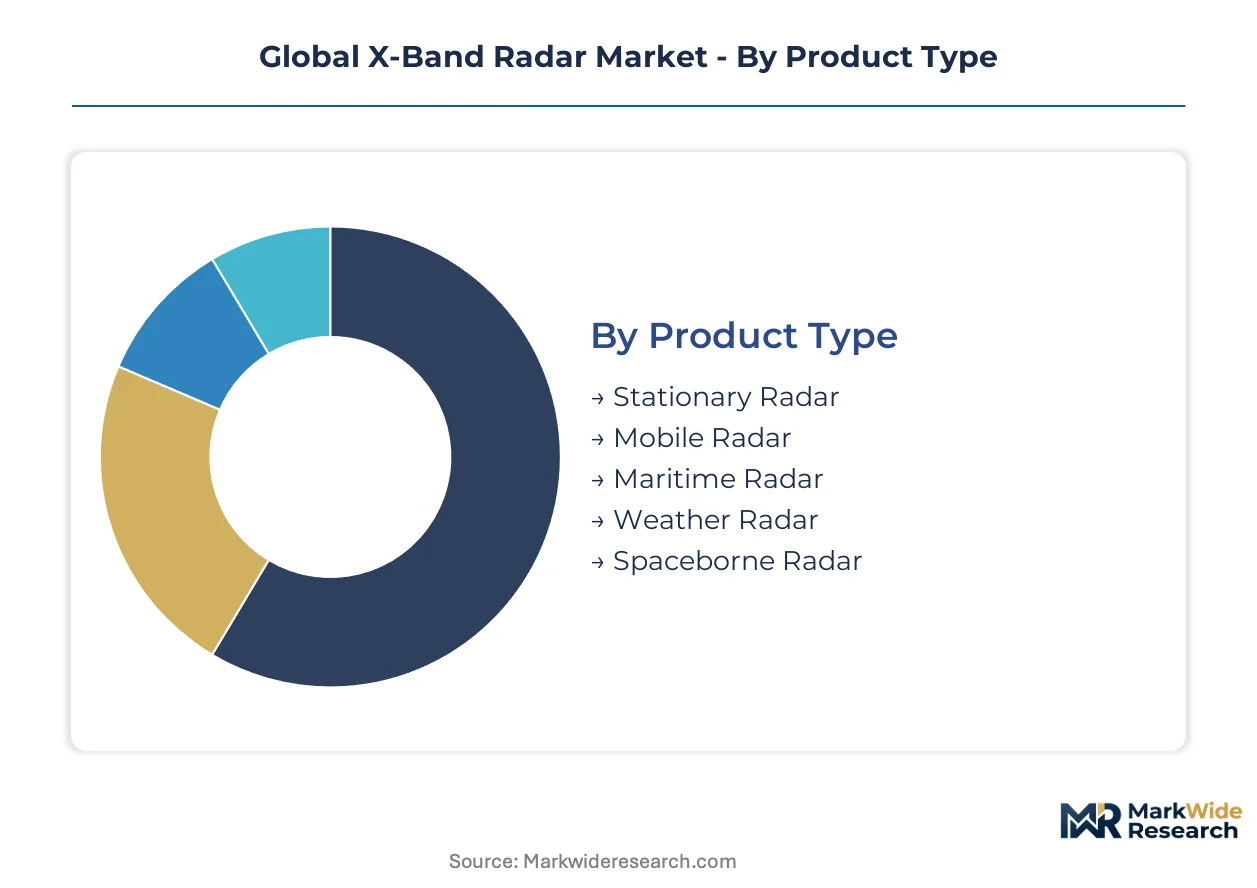
Product Type:
Maritime and weather installations cycle fastest due to salt corrosion and continuous operation, while spaceborne assets remain on orbit for decades.
- Stationary Radar:Fixed-site installations employing parabolic or phased-array apertures for air traffic control and coastal surveillance. Port authorities in Singapore and Rotterdam favor these for vessel traffic management, though concrete foundation requirements extend deployment timelines.
- Mobile Radar:Trailer-mounted or containerized configurations with rapid deployability for expeditionary military operations and disaster response. The Australian Defence Force and Southeast Asian emergency agencies are prioritizing these systems for flood and typhoon monitoring, creating procurement velocity unmatched by fixed alternatives.
- Maritime Radar:Shipborne navigation and collision avoidance systems with solid-state transmitters displacing magnetron architectures across commercial fleets.
- Weather Radar:Ground-based precipitation monitoring networks operated by national meteorological services, with dual-polarization upgrades driving replacement demand.
- Spaceborne Radar:Synthetic aperture systems on low-earth orbit satellites for earth observation and maritime domain awareness, where launch costs constrain constellation expansion.
Stationary radar dominates installed base. Mobile radar is where expansion concentrates.
Technology:
Cost tiers separate legacy vacuum tube systems from premium solid-state architectures, with gallium nitride foundry economics determining accessibility.
- Solid State:Gallium nitride and gallium arsenide transmitter modules with improved mean-time-between-failures and reduced cooling overhead. Commercial shipping operators in Japan and the United States are retrofitting fleets despite higher upfront costs, prioritizing uptime and fuel efficiency.
- Magnetron:Vacuum tube oscillators with mature supply chains but declining reliability metrics. Legacy fishing fleets and developing-world port authorities continue procurement where capital constraints outweigh lifecycle cost considerations.
- Traveling Wave Tube:High-power amplifiers for long-range defense applications where peak output requirements exceed solid-state thresholds. Naval radar on surface combatants remains dependent on specialized aerospace electronics manufacturers with concentrated supply.
- Doppler:Velocity-sensing signal processing architectures for weather precipitation measurement and maritime current mapping.
- Synthetic Aperture Radar:Coherent processing techniques achieving fine spatial resolution from moving platforms, deployed on reconnaissance aircraft and satellites.
Magnetron technology retains volume in price-sensitive segments. Solid-state architectures are climbing the fastest across maritime and weather applications.
Application:
Customer maturity varies sharply, with aviation regulators imposing certification burdens that extend sales cycles versus commercial shipping's specification-driven procurement.
- Air Traffic Control:Precision approach and en-route surveillance systems governed by FAA and EASA certification protocols. Airport modernization at Long Beach and secondary hubs in India is synchronizing procurement, though multi-jurisdiction approval processes extend time-to-revenue.
- Border Surveillance:Coastal and land frontier monitoring networks with dual-use naval and law enforcement applications. Territorial monitoring requirements in the South China Sea corridor are creating overlapping procurement cycles for sovereign and commercial platforms.
- Maritime Navigation:Vessel traffic management and berthing precision systems for commercial shipping lanes. Port modernization mandates across Singapore, Rotterdam, and Long Beach are driving synchronized fleet-wide upgrades.
- Weather Forecasting:National precipitation monitoring networks with dual-polarization and phased-array upgrades. Meteorological organizations in Japan and Australia are prioritizing nowcasting capabilities for severe storm warning.
- Space Research:Planetary observation and orbital debris tracking installations with extended development timelines and concentrated government funding.
Maritime navigation commands the largest active procurement pool. Border surveillance represents the steepest expansion trajectory as territorial monitoring intensifies.
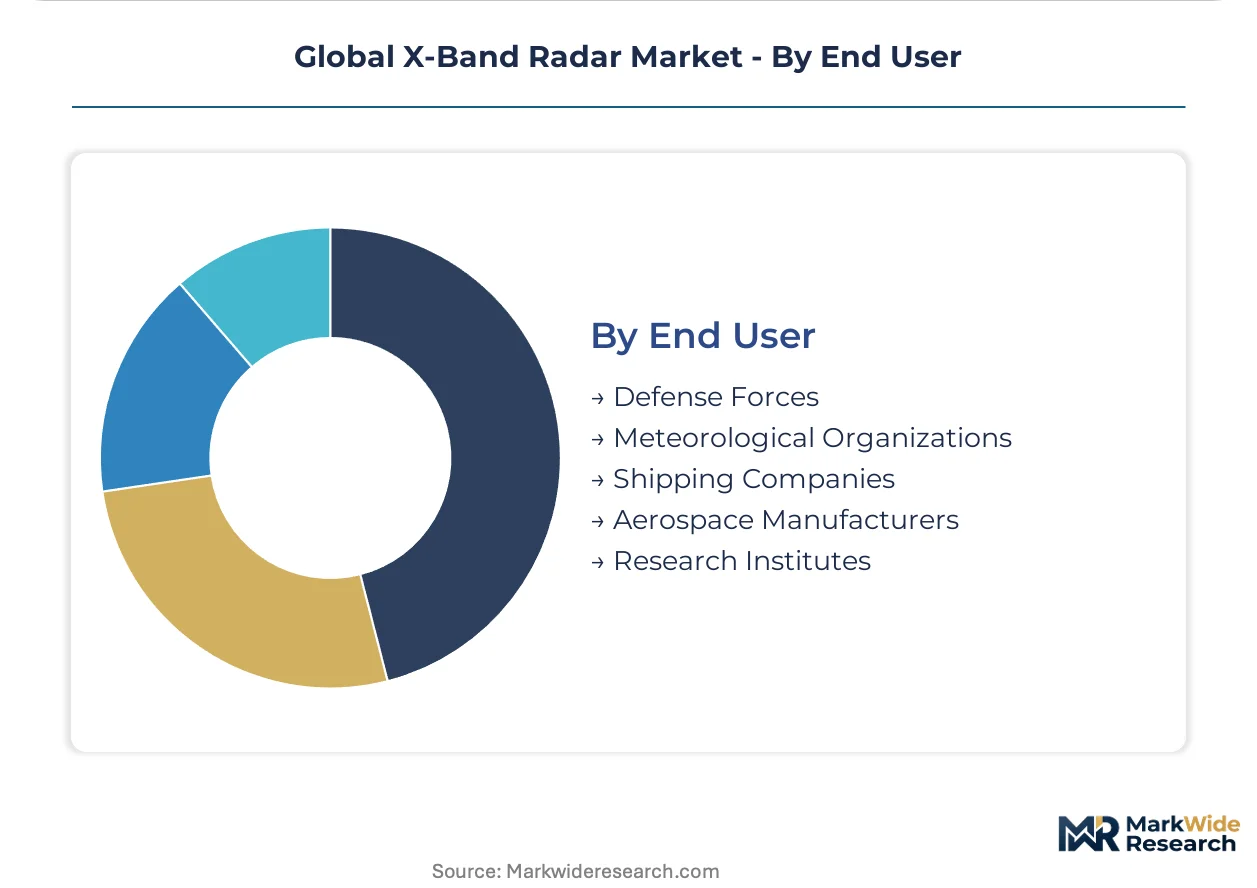
End User:
Volume concentration sits with institutional buyers operating on multi-year budget cycles, while commercial operators prioritize total cost of ownership over specification compliance.
- Defense Forces:Naval surface combatants, offshore patrol vessels, and expeditionary radar platforms with classified performance requirements. The US Navy and Royal Australian Navy are unbundling hardware acquisition from decade-long sustainment services, reshaping vendor revenue recognition.
- Meteorological Organizations:National weather services operating ground-based precipitation networks with public funding constraints and dual-polarization upgrade mandates.
- Shipping Companies:Commercial fleet operators prioritizing solid-state reliability and fuel efficiency over initial acquisition cost. Japanese and European container lines are accelerating retrofit schedules as efficiency standards tighten.
- Aerospace Manufacturers:Satellite integrators and aircraft radar suppliers with synthetic aperture and weather radar payload requirements.
- Research Institutes:Academic and government laboratories with specialized space observation and atmospheric science applications.
Defense forces anchor committed demand through long-term platform support agreements. Shipping companies are gaining share fastest as commercial fleet retrofits accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial shipping operators in Japan and Singapore exhibit the lowest price elasticity, prioritizing solid-state reliability over acquisition cost, while legacy fishing fleets in developing economies remain highly sensitive to upfront expenditure. Defense procurement cycles across the Indo-Pacific corridor show intermediate elasticity, balancing performance mandates with decade-long sustainment obligations.
United States
The US Navy and Coast Guard drive naval radar modernization, with port authorities at Long Beach and Seattle synchronizing vessel traffic management upgrades. The FCC and FAA govern X-Band allocation and emission limits for maritime and aviation applications. Defense contractors concentrate in the Baltimore-Washington corridor, where RTX Corporation and Northrop Grumman Corporation anchor integrated electronics manufacturing.
Japan
Commercial container lines and the Japan Coast Guard generate overlapping demand for navigation and surveillance platforms. The Ministry of Internal Affairs and Communications enforces radio spectrum frameworks and interference mitigation protocols. Manufacturing clusters in Tokyo and Osaka host Japan Radio Co., Ltd. and Furuno Electric Co., Ltd., with solid-state transmitter production expanding to meet fleet-wide retrofit schedules.
Germany
Hensoldt AG supplies naval radar for German surface combatants and European export programs, with the EU Radio Spectrum Framework and EASA certification protocols shaping product design. Industrial concentration in Bavaria and Baden-Württemberg supports precision engineering for phased-array calibration and gallium nitride thermal management systems.
Australia
The Royal Australian Navy and emergency response agencies prioritize mobile radar configurations for expeditionary operations and disaster monitoring. The Australian Communications and Media Authority administers spectrum coordination aligned with ITU-R standards. Procurement activity concentrates in Adelaide and Sydney, where sustainment contracts are unbundled from initial hardware acquisition.
Singapore
The Maritime and Port Authority mandates navigation system upgrades for vessel traffic management and berthing precision in the world's second-busiest container port. The Infocomm Media Development Authority regulates X-Band allocation for coastal surveillance. Port modernization creates synchronized procurement cycles for commercial shipping operators and naval platforms operating in adjacent waters.
Global X-Band Radar Market Competitive Landscape
Integrated defense conglomerates and specialized maritime electronics fabricators split the market along capability-depth versus application-breadth lines. The vendor base concentrates among ten to fifteen established suppliers with multi-decade platform heritage, creating barriers for new entrants facing 18-24 month certification timelines. Three archetypes dominate: diversified aerospace-defense primes with captive radar divisions, regional specialists anchoring localized maintenance networks, and commercial marine electronics houses with high-volume manufacturing scale. Competitive dynamics center on sustainment contract capture and gallium nitride foundry partnerships rather than pure hardware pricing.
Within the integrated prime tier, RTX Corporation and Northrop Grumman Corporation exemplify the aerospace-defense conglomerate archetype, leveraging cross-divisional electronics portfolios to secure decade-long platform support agreements. Saab AB occupies a position representing the regional specialist model, with localized maintenance hubs and training infrastructure anchoring European and Indo-Pacific footprints. Among commercial marine electronics houses, Furuno Electric Co., Ltd. and Japan Radio Co., Ltd. sit within the high-volume manufacturing segment, serving commercial shipping operators with solid-state navigation systems.
| Leading Market Players |
|---|
| RTX Corporation |
| Saab AB |
| Leonardo S.p.A. |
| Furuno Electric Co., Ltd. |
| Israel Aerospace Industries |
| Northrop Grumman Corporation |
| Hensoldt AG |
| Japan Radio Co., Ltd. |
| Thales |
| Others |
Supply & Pricing Matrix
The Shanghai-Rotterdam maritime corridor carries gallium nitride substrates and phased-array components through concentrated chokepoints, where freight cost volatility amplifies pricing power for solid-state transmitter manufacturers while forcing tiered differentiation between defense-grade and commercial maritime buyers.
Pricing Analysis
Lifecycle sustainment contracts now drive lifetime value more than initial hardware sales. Three-tier pricing structure across premium, standard, and economy levels separates defense platforms with decade-long support obligations from commercial shipping retrofits and developing-world port installations. Cost compression in magnetron replacement segments is intensifying because shipping operators prioritize uptime metrics over acquisition price. Commercial fishing fleets exhibit highest price sensitivity, while Japan Coast Guard and Singapore port authorities show lowest elasticity.
Supply Chain Analysis
Specialized gallium nitride foundries in Japan, Germany, and the United States hold captive capacity for defense-grade transmitter modules. Raw material dependencies center on high-purity semiconductor substrates, rare-earth magnet components for antenna pedestals, and precision-machined waveguide assemblies. Single-source vulnerability concentrates in traveling wave tube amplifier manufacturing, where qualified aerospace electronics suppliers number fewer than six globally. Distribution runs through direct defense procurement channels and marine electronics distributors serving commercial retrofit markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state transmitter displacement of magnetron architectures represents a high-growth disruption, with FCC efficiency mandates and EASA certification protocols accelerating fleet-wide replacement cycles across commercial and naval platforms.
For Market Incumbents: Insulate proprietary gallium nitride thermal management expertise through targeted hiring from constrained RF engineering talent pools and captive foundry partnerships with Japanese semiconductor manufacturers. Secure long-term platform support agreements before third-party service providers capture depot-level repair contracts unbundled from hardware acquisition. For New Entrants and Emerging Players: Build out mobile radar configurations for Australian emergency response agencies and Southeast Asian disaster monitoring authorities, where procurement velocity exceeds fixed-site alternatives and certification burdens concentrate on rapid-deployability specifications rather than multi-jurisdiction harmonization. Target commercial fishing fleet retrofits in developing economies through magnetron-compatible solid-state interface modules. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated defense electronics primes with captive gallium nitride foundry access and established sustainment contract pipelines. Five-to-ten-year viability hinges on software-defined architecture transitions enabling over-the-air upgrades without physical retrofits. Monitor ITU-R spectrum reallocation proceedings as the critical inflection signal for qualification timeline compression or extension.| Strategic Initiative | Industry Significance |
|---|---|
| Gallium Nitride Foundry Partnership | Captive substrate supply secures defense contract eligibility against capacity-constrained competitors. |
| Software-Defined Architecture Launch | Virtualized signal processing enables over-the-air capability upgrades without antenna replacement. |
| Localized Maintenance Hub Expansion | Singapore and Sydney facilities anchor Indo-Pacific sustainment revenue capture from naval programs. |
| Dual-Use Export Certification Pathway | Wassenaar Arrangement alignment streamlines cross-border defense and aviation contract eligibility. |
| Magnetron Retrofit Interface Development | Custom pedestal adapters unlock commercial shipping fleet replacement demand. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across radar system procurement, including naval program managers at the US Navy and Royal Australian Navy, commercial shipping fleet engineers at Japanese container lines, port authority technical directors in Singapore and Rotterdam, and defense electronics manufacturing executives. Secondary validation drew from FCC equipment authorization databases, EASA certification registries, ITU-R spectrum coordination filings, and customs trade records for gallium nitride substrate movements. Bottom-up installation counts triangulated against top-down defense budget appropriations and commercial fleet retrofit schedules.
Calibration against historical procurement cycles informed projections across the analysis window. Segmentation dimensions modeled include product type, transmitter technology architecture, application domain, and end-user category with regional regulatory cluster overlays. CAGRs were derived from weighted average of replacement cycle velocities and new platform introduction rates. Forecast inputs incorporated solid-state reliability improvement curves and gallium nitride foundry capacity expansion announcements.
Stress conditions across gallium nitride wafer supply constraints, ITU-R reallocation timeline extensions, and defense budget authorization delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding technology transition rates and regulatory harmonization progress. Cross-checking against national meteorological service precipitation network upgrade announcements and naval shipbuilding program schedules is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Navigation & Surveillance
Global Antenna Market
Communication Navigation & Surveillance
Tactical Radio Market
Communication Navigation & Surveillance
Naval Tactical Communication Market
Communication Navigation & Surveillance
Man Portable Communication Systems Market
Communication Navigation & Surveillance
Global Tactical Headset Market
Communication Navigation & Surveillance
3D Radar Market
Communication Navigation & Surveillance
Defense Communication System Market
Communication Navigation & Surveillance
Missile Guidance Radar Market
Communication Navigation & Surveillance
Surface Radars Market
Communication Navigation & Surveillance
Naval Navigation and Communication Systems Market
Communication Navigation & Surveillance
Military Antenna Market
Communication Navigation & Surveillance
UK Autonomous Navigation Market
Communication Navigation & Surveillance
Airborne SATCOM Equipment Market
Communication Navigation & Surveillance
Tactical Communications Market
Communication Navigation & Surveillance
Space Situational Awareness (SSA) Systems Market
Communication Navigation & Surveillance
Over the Horizon Radar Market