
 Aviation Weather Radar Market | 2026-2036
Aviation Weather Radar Market Size, Share, and Industry Trends Forecast 2026-2036
Aviation Weather Radar Market Analysis
A shortage of RF engineering talent with dual expertise in meteorology and airborne radar design is unwinding the pace of next-generation product rollouts. Honeywell International Inc. leverages its integrated avionics ecosystem to bundle weather radar with flight management systems, while Collins Aerospace sustains its position through deep ties to Boeing and Airbus OEM channels. L3Harris Technologies Inc. competes on military specialization, anchoring its portfolio in defense programs that demand hardened phased array architectures.
Aviation weather radar detects atmospheric hydrometeors, turbulence boundaries, and wind shear phenomena using X-band or C-band pulsed or continuous-wave emissions, with solid-state transmitters now displacing vacuum-tube magnetrons for improved reliability and reduced maintenance intervals. Its primary purpose is to furnish flight crews and ground dispatchers with real-time hazard maps that inform route amendments and altitude changes. Solid-state radar leads product type margins due to longer service life and lower total cost of ownership, while phased array radar represents the fastest-growing category as active electronically scanned arrays enable simultaneous multi-beam surveillance. Civil aviation dominates end-user value capture, though military aviation commands premium pricing for encrypted data links and electronic protection features.
FAA airworthiness directives and the EU's EASA CS-25 certification standards mandate minimum weather detection capabilities for transport-category aircraft, directly shaping R&D priorities and retrofit timelines. The EU AI Act and emerging CSRD disclosure requirements are beginning to influence supplier environmental reporting, adding compliance layers to component sourcing. Stakeholders must monitor how dual-use technology export controls from the US Department of Commerce and analogous frameworks from European regulators reshape cross-border component flows and partnership structures.
Market Dynamics
Solid-state transmitter technology is compressing product lifecycles and forcing incumbent suppliers to retool manufacturing lines away from magnetron-dependent architectures. This hardware transition coincides with FAA mandates for enhanced turbulence detection capabilities, creating simultaneous pull on R&D budgets and certification resources.
Growth Catalysts
- FAA Turbulence Detection Mandates:Updated airworthiness directives require transport-category aircraft to deploy advanced weather radar with automated turbulence reporting. Commercial carriers are accelerating fleet-wide retrofits to maintain operational certificates.
- Solid-State Reliability Gains:Active electronically scanned arrays eliminate vacuum-tube failure modes and extend mean time between overhauls. Airlines prioritize total cost of ownership in procurement evaluations.
- Defense Modernization Cycles:Hardened phased array architectures for military platforms drive premium R&D investment. Encrypted data links and electronic protection features command pricing premiums in defense procurement.
Market Restraints
- Gallium Nitride Substrate Costs:Solid-state transmitters depend on specialized semiconductor materials with concentrated supply chains. Price volatility in rare earth processing constrains margin expansion for radar manufacturers.
- Dual-Use Export Controls:US Department of Commerce restrictions on phased array components limit technology transfer to certain jurisdictions. Cross-border partnership structures face compliance friction.
- Magnetron Installed Base Inertia:Thousands of legacy systems remain airworthy with available spare parts. Carriers delay replacement until mandatory retirement thresholds trigger upgrade decisions.
Strategic Opportunities
- Unmanned Aerial Systems Integration:Cargo drones and urban air mobility platforms require compact weather radar with minimal power draw. Sensor miniaturization opens addressable markets outside traditional commercial aviation.
- Predictive Maintenance Analytics:Solid-state architectures generate rich operational data streams. Radar health monitoring services create recurring revenue attachments alongside hardware sales.
- EU CSRD Disclosure Alignment:Environmental reporting requirements for avionics suppliers favor longer-service-life solid-state designs. Sustainability-linked procurement criteria advantage next-generation technology.
Industry Challenges
- RF-Meteorology Hybrid Talent Scarcity:Engineering programs produce few candidates with simultaneous expertise in atmospheric science and airborne radar design. Recruitment pipelines lag product development timelines.
- EASA CS-25 Certification Complexity:European validation of new weather radar architectures requires extensive flight testing and documentation. Approval timelines extend 18-24 months beyond initial technical readiness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aviation Weather Radar Market |
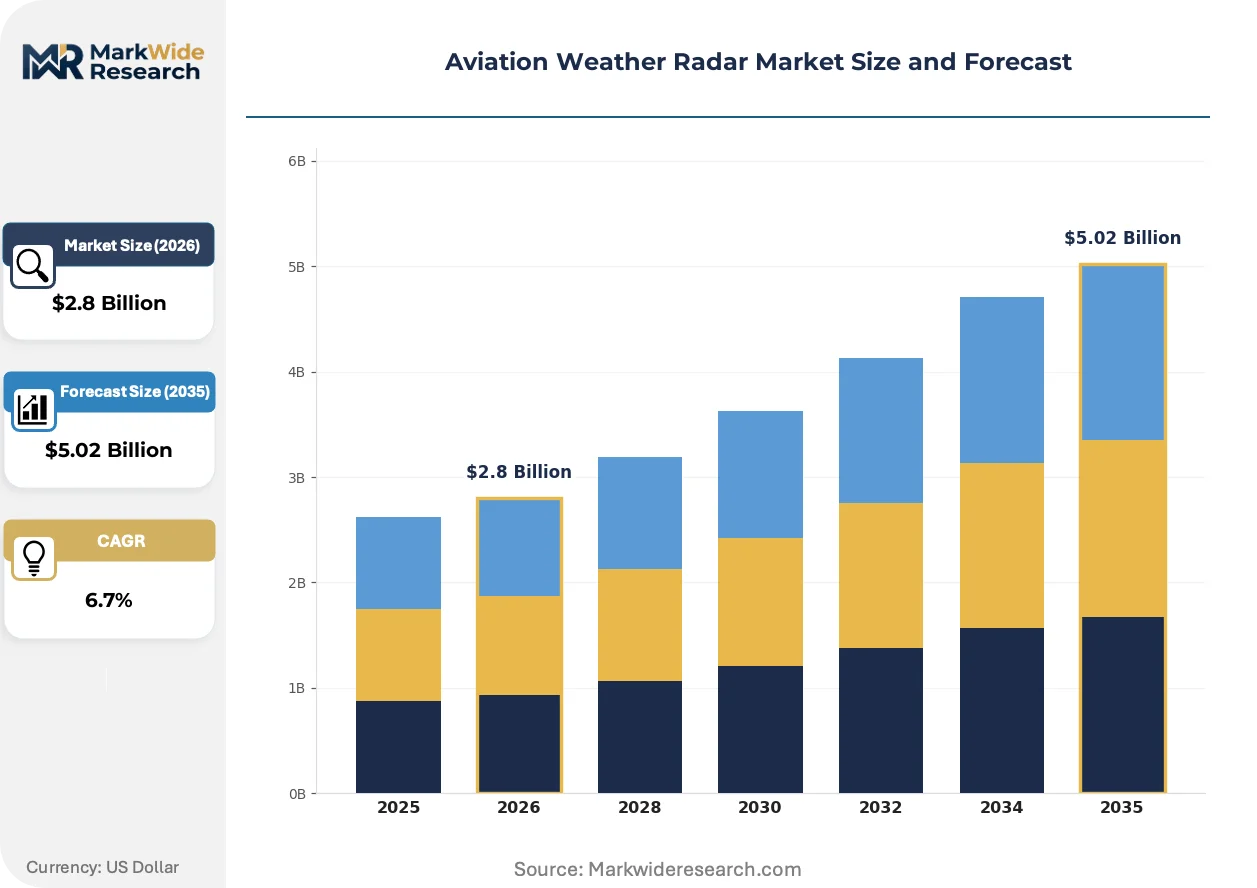
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional Radar, Phased Array Radar, Doppler Radar, Solid-State Radar Technology: Radar Signal Processing, Data Fusion Techniques, Cloud Integration, Real-Time Monitoring End User: Civil Aviation, Military Aviation, Research Institutions, Airports Installation: Fixed Installation, Mobile Installation, Temporary Installation, Integrated Systems |
| Companies Covered | Honeywell International Inc., Collins Aerospace, L3Harris Technologies Inc., Raytheon Technologies Corporation, Garmin Ltd., Leonardo SpA, Telephonics Corporation, EWR Radar Systems Inc., Selex ES GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aviation Weather Radar Market Emerging Trajectories
Hardware architecture decisions are locking in competitive positioning for the next decade as solid-state platforms enable software-defined functionality previously impossible with magnetron systems. Three developments are restructuring supplier capabilities and buyer expectations.
Active electronically scanned arrays with gallium nitride front-ends are supplanting mechanically scanned dish antennas across new aircraft programs and major retrofit campaigns. Major carriers in the United States are specifying AESA-based weather radar as standard equipment on narrowbody and widebody deliveries. This transition compresses the addressable market for legacy magnetron suppliers and elevates software competency as a competitive differentiator.
The EU AI Act's risk classification framework is beginning to influence avionics software validation requirements for automated hazard detection algorithms. European regulators are scrutinizing machine-learning-based turbulence prediction systems for transparency and traceability standards. Radar suppliers serving Airbus OEM channels are restructuring development processes to document algorithmic decision pathways for certification authorities.
Airlines are unbundling weather radar maintenance from comprehensive avionics service agreements and negotiating direct relationships with component manufacturers. This disintermediation of traditional OEM service networks concentrates procurement leverage with fleet engineering departments. US-based legacy carriers with large in-house technical operations are pioneering this model, pressuring incumbent integrated suppliers to modularize service offerings.
Aviation Weather Radar Market Segmentation
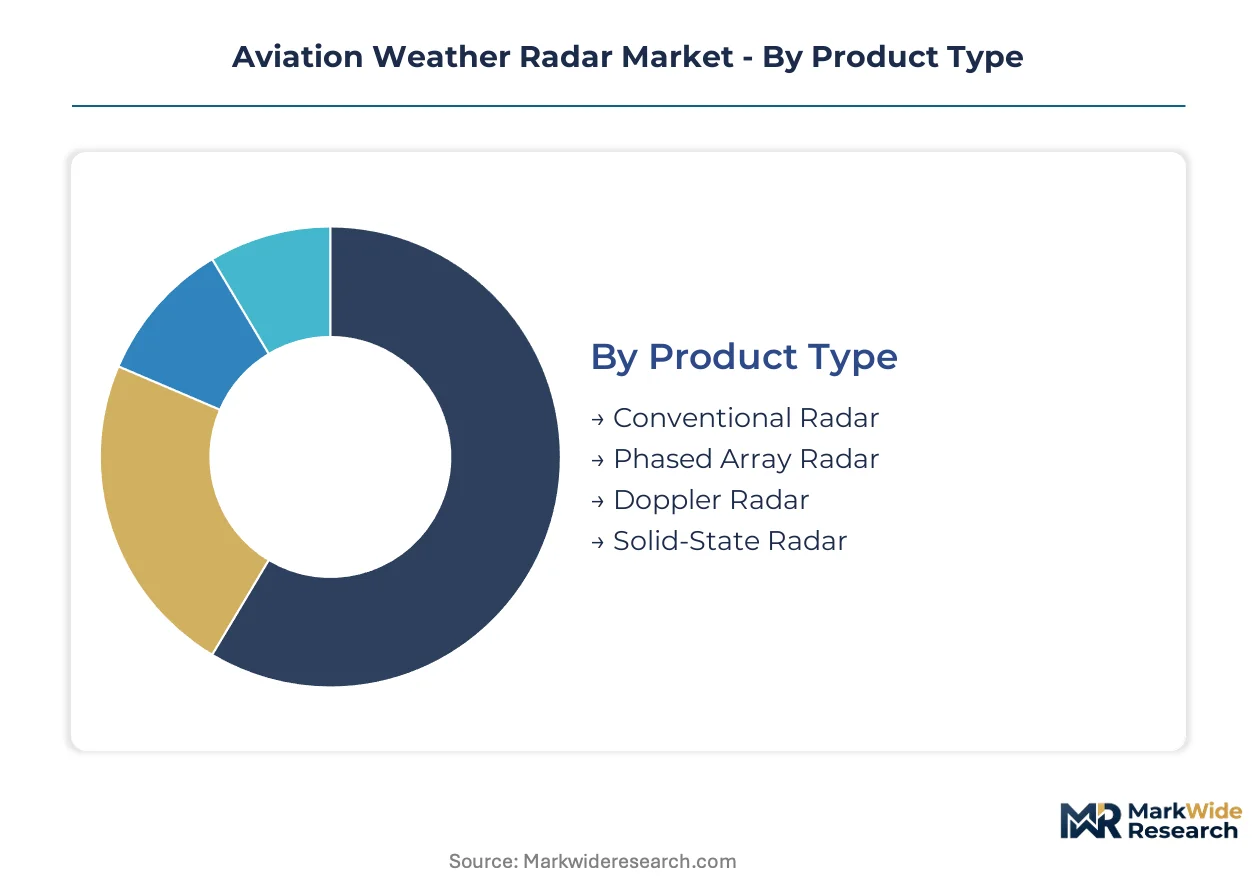
Aviation weather radar procurement channels diverge sharply across product architectures and end-user missions. Understanding these segment-specific pathways enables suppliers to align certification investments with actual buyer decision flows and service attach rates.
Product Type:
Channel mix varies by transmitter architecture, with solid-state and phased array systems flowing through avionics OEM partnerships while conventional radar retrofits concentrate in aftermarket distributors.
- Solid-State Radar:Active electronically scanned arrays with gallium nitride front-ends eliminate vacuum-tube failure modes and extend mean time between overhauls. Demand concentrates among US legacy carriers prioritizing total cost of ownership in fleet-wide procurement evaluations.
- Phased Array Radar:Active electronically scanned arrays enable simultaneous multi-beam surveillance with software-defined beam steering. Military platforms in the United States drive premium procurement through defense contractors requiring hardened architectures with encrypted data links.
- Conventional Radar:Magnetron-based systems persist in regional airline retrofit channels where FAA mandates trigger mandatory replacement timelines.
- Doppler Radar:Velocity-sensing architectures support wind shear detection for airport terminal approach applications.
Conventional radar dominates installed base. Phased array radar is where expansion concentrates.
Technology:
Technology tiering follows certification complexity, with radar signal processing commanding premium pricing while cloud integration penetrates fastest in greenfield airport deployments.
- Radar Signal Processing:Digital pulse compression and clutter suppression algorithms extract hazard signatures from raw radar returns. FAA turbulence detection mandates require transport-category aircraft to deploy automated processing with standardized reporting protocols.
- Data Fusion Techniques:Multi-sensor integration combines weather radar with lightning detection and satellite imagery for unified hazard displays. Airbus and Boeing OEM specifications increasingly require fusion-capable architectures for flight deck integration.
- Cloud Integration:Ground-based data aggregation enables fleet-wide weather picture sharing between dispatch and flight crews.
- Real-Time Monitoring:Continuous health diagnostics support predictive maintenance contracts with US-based legacy carriers operating large in-house technical operations.
Radar signal processing captures the highest attach rates. Cloud integration is climbing the fastest as airports modernize ground infrastructure.
End User:
End-user segmentation maps directly to procurement authority structures, with civil aviation channeling through fleet engineering departments while military aviation routes through defense acquisition programs.
- Civil Aviation:Commercial carriers specify weather radar as line-fit equipment on narrowbody and widebody deliveries or pursue fleet-wide retrofits to maintain operational certificates under FAA airworthiness directives. United States major carriers anchor procurement volumes through integrated avionics bundles.
- Military Aviation:Defense platforms require hardened phased array architectures with electronic protection features and encrypted data links. US Department of Commerce export controls constrain technology transfer to certain jurisdictions, reshaping partnership structures.
- Research Institutions:Atmospheric science programs acquire specialized configurations for storm penetration and validation studies.
- Airports:Terminal area surveillance systems support ground-based wind shear alerting for approach corridors.
Civil aviation dominates installed base. Military aviation is gaining share fastest through modernization cycles.
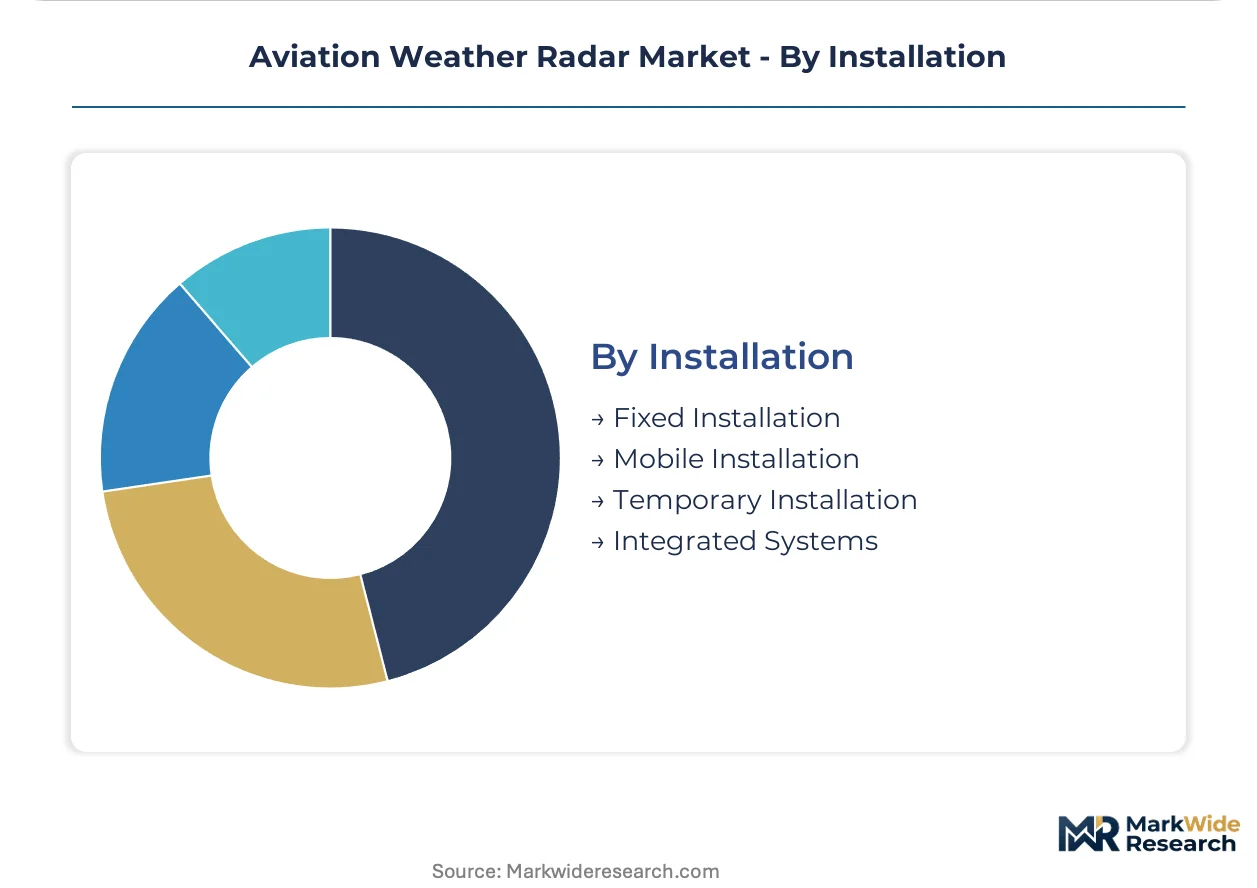
Installation:
Installation mode determines service revenue attachment, with fixed installations generating long-term maintenance contracts while mobile and temporary configurations favor equipment rental models.
- Fixed Installation:Permanent aircraft-mounted systems integrate with flight management computers and display suites. EASA CS-25 certification standards mandate extensive flight testing and documentation, extending approval timelines 18-24 months beyond technical readiness.
- Integrated Systems:Factory-installed configurations bundled with avionics suites dominate new aircraft programs at Boeing and Airbus. Honeywell and Collins Aerospace anchor OEM channel positions through deep supplier relationships.
- Mobile Installation:Transportable ground-based units support expeditionary military operations and disaster response.
- Temporary Installation:Short-term deployments serve flight test programs and certification campaigns.
Fixed installation dominates installed base. Integrated systems is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aviation weather radar procurement patterns diverge sharply by geography, with the United States prioritizing defense-hardened phased arrays while European carriers emphasize EASA-certified solid-state retrofits for sustainability compliance.
United States
Major commercial carriers and defense contractors anchor global procurement volumes through integrated avionics bundles and military modernization programs. FAA turbulence detection mandates require transport-category aircraft to deploy advanced weather radar with automated reporting protocols. Seattle and Wichita aerospace clusters concentrate OEM integration activity for both civil and military platforms.
Germany
Airbus supply chain requirements drive demand for EASA CS-25 certified architectures with data fusion capabilities. EU AI Act transparency standards reshape software validation processes for automated hazard detection algorithms. Bavaria's aerospace engineering corridor hosts radar subsystem suppliers serving Airbus final assembly lines in Hamburg and Toulouse.
France
Airbus headquarters proximity influences radar specification standards across European carrier fleets. EASA certification timelines extend development cycles for new product introductions. Toulouse-Blagnac aerospace cluster anchors flight test and validation activities for weather radar integration programs.
United Kingdom
Royal Air Force modernization programs sustain demand for hardened military radar architectures with electronic protection features. Export control compliance shapes partnership structures with Commonwealth and NATO allies. BAE Systems supply chain concentration in Lancashire and Greater Manchester supports defense avionics integration.
Japan
Japan Airlines and ANA fleet expansion drives line-fit procurement for narrowbody and widebody deliveries. METI industrial policy supports domestic radar component manufacturing to reduce import dependency. Nagoya aerospace cluster concentrates Mitsubishi Heavy Industries integration activity for regional aircraft programs.
Aviation Weather Radar Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with consolidated OEM channel control characterizing the upper layer and component suppliers and regional retrofit houses populating the lower. The market structure rewards deep certification relationships and long-term service contracts over pure hardware pricing. Three archetypes dominate: vertically integrated avionics platforms, defense-specialized phased array developers, and aftermarket retrofit distributors. Competitive moves concentrate on strategic OEM partnerships and predictive maintenance service bundling.
Among US-based integrated suppliers, Honeywell International Inc. and Collins Aerospace exemplify the platform-tier archetype through avionics ecosystem bundling, while L3Harris Technologies Inc. occupies a distinct position within defense-specialized phased array development. These three entities anchor the competitive structure by representing the primary pathways through which weather radar reaches end-user aircraft programs.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Collins Aerospace |
| L3Harris Technologies Inc. |
| Raytheon Technologies Corporation |
| Garmin Ltd. |
| Leonardo SpA |
| Telephonics Corporation |
| EWR Radar Systems Inc. |
| Selex ES GmbH |
| Others |
Supply Flow & Price Mechanics
EASA CS-25 certification standards gate both supplier qualification timelines and price differentiation across aviation weather radar tiers, forcing manufacturers to absorb extended validation costs while carriers segment procurement by operational criticality.
Pricing Analysis
Long-term offtake contracts dominate procurement for integrated avionics suites, with spot purchasing limited to aftermarket retrofits and emergency replacements. Three-tier pricing structure across premium phased array, standard solid-state, and economy magnetron levels reflects certification grade and mean-time-between-overhaul guarantees. Cost compression in legacy magnetron tiers is intensifying because spare parts availability extends replacement cycles. Regional carriers with thin technical operations exhibit highest price sensitivity, while defense programs with encrypted data link requirements show lowest elasticity.
Supply Chain Analysis
Inventory buffers for gallium nitride substrates stretch lead times to 26-32 weeks, constraining solid-state transmitter output scheduling. Manufacturing concentrates in the United States, Germany, and Japan, with GaN wafer processing anchored in North American foundries and final assembly distributed across Wichita and Toulouse aerospace clusters. Raw material dependencies include rare earth elements from concentrated mining jurisdictions, specialized semiconductor substrates, and precision machined antenna components. Single-source vulnerability in GaN substrate supply creates disruption exposure. Distribution runs through OEM direct channels for line-fit equipment and avionics distributors for retrofit markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat arena where EASA and FAA certification entrenchment creates switching costs that lock carriers into incumbent supplier relationships for entire fleet lifecycles.
For Market Incumbents: Consolidate control over AESA software-defined architectures through captive GaN substrate supply arrangements, neutralizing gallium nitride cost volatility that threatens margin stability. Deepen OEM channel exclusivity with Boeing and Airbus through bundled flight management system integration, raising rival replacement costs.
For New Entrants and Emerging Players: Differentiate on predictive maintenance analytics services that attach to solid-state radar health monitoring, bypassing hardware certification barriers that block direct avionics competition. Target cargo drone and urban air mobility platforms where compact sensor requirements and minimal power draw specifications favor nimble engineering teams over entrenched avionics platforms.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed radar component suppliers holding EASA validation credentials but lacking OEM channel depth. Five-to-ten year viability hinges on defense modernization budget continuity and civil fleet replacement cycles. Monitor FAA mandate implementation timelines as inflection signal for retrofit demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| GaN Substrate Backward Integration | Captive wafer supply insulates Honeywell and Collins Aerospace from rare earth price volatility. |
| Predictive Maintenance Service Launch | Health monitoring contracts generate recurring revenue alongside hardware sales at US legacy carriers. |
| UAS Radar Miniaturization Program | Compact AESA designs open cargo drone procurement channels outside traditional commercial aviation. |
| EASA AI Act Compliance Investment | Algorithmic transparency documentation enables Airbus OEM channel retention under emerging software standards. |
| Defense Export Control Restructuring | Phased array technology licensing partnerships navigate US Department of Commerce dual-use restrictions. |
Methodological Framework
A standing panel of avionics engineering directors, airline fleet procurement managers, FAA certification specialists, and defense program officers provided ongoing calibration against primary field observations and secondary validation. Data synthesis combined structured interviews with radar subsystem suppliers and aftermarket distributors against EASA certification databases, FAA airworthiness directive filings, Department of Commerce export control notices, and customs trade records. Bottom-up unit economics triangulated with top-down aerospace OEM procurement disclosures.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation modeling spanned transmitter architecture, end-user mission profile, installation mode, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to disclosed fleet expansion schedules and mandate-driven retrofit timelines. Forecast inputs incorporated defense modernization cycle phasing and civil airline delivery backlogs.
The analysis sits within stated boundaries; outcomes outside sustained FAA enforcement of turbulence detection mandates or relaxation of GaN export controls would require recalibration. Forecasts reflect documented assumptions regarding certification timeline stability and semiconductor supply continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Navigation and Communication
Aircraft Turn Coordinator Market
Aircraft Navigation and Communication
5G Adoption Analysis in Aviation Market
Aircraft Navigation and Communication
Air-Based Tactical Data Link Market
Aircraft Navigation and Communication
Helicopter Meteorological Software Market
Aircraft Navigation and Communication
Ultra Short Base Line Positioning System Market
Aircraft Navigation and Communication
Global Air Traffic Control Equipment Market
Aircraft Navigation and Communication
Asia-Pacific VHF Air-Ground Communication Stations Market
Aircraft Navigation and Communication
Global Aviation Mapping Software Market
Aircraft Navigation and Communication
Automatic Dependent Surveillance-Broadcast (ADS-B) Market
Aircraft Navigation and Communication
Aircraft Navigation Software Market
Aircraft Navigation and Communication
America Air Traffic Management Market
Aircraft Navigation and Communication
Airborne Situational Awareness Systems Market
Aircraft Navigation and Communication
In Flight Connectivity Market
Aircraft Navigation and Communication
Connected Aircraft Market
Aircraft Navigation and Communication
Airborne Telemetry Market
Aircraft Navigation and Communication
Middle-East and Africa Air Traffic Management Market