
 3D Radar Market | 2026-2036
3D Radar Market Size, Share, and Industry Trends Forecast 2026-2036
3D Radar Market Intelligence
The traditional procurement model centered on large, monolithic defense contracts is collapsing as civil end-users like Airport Authorities and Meteorological Departments gain purchasing influence. Thales Group specializes in dual-use systems serving both civil air traffic control and military surveillance missions. Raytheon Technologies Corporation leverages its deep integration with the US Department of Defense to secure long-range surveillance contracts. Hensoldt AG competes with advanced sensor solutions for naval and ground-based platforms across Europe.
A 3D radar system provides target information in three dimensions: range, azimuth, and elevation. These systems often utilize Phased Array technology and operate in frequency bands like the S-band or X-band to generate detailed situational awareness. Ground-Based systems represent the largest product segment, providing foundational infrastructure for defense and civil surveillance. Within applications, demand for Air Traffic Control and Border Surveillance systems is driving investment in more advanced Doppler and Pulse Compression technologies.
Regulatory mandates from aviation authorities, including the US FAA and the European Union's EASA, define the performance requirements for 3D radar in air traffic management. Concurrently, spectrum allocation rules set by bodies like the FCC in the US and national regulators in India govern operational frequencies for both civil and military systems. Stakeholders must now decide how to balance the high cost of advanced Phased Array systems against the increasing operational need for superior target discrimination.
Market Dynamics
The central dynamic reshaping the 3D radar market is the diffusion of purchasing power from traditional, monolithic defense ministries to a diverse base of civil authorities. This shift compels vendors to develop dual-use systems that meet both military and civil air traffic control standards.
Growth Catalysts
- Defense Modernization Programs:National security imperatives in countries like India and Saudi Arabia are driving procurement of advanced ground-based 3D radar systems to replace aging surveillance infrastructure and enhance airspace sovereignty.
- Aviation Safety Mandates:Regulatory standards from bodies such as the FAA and EASA are compelling airport authorities to invest in next-generation air surveillance systems with superior target detection and tracking capabilities to manage increasing air traffic density.
- Phased Array Technology Adoption:Demand for enhanced situational awareness in complex environments is accelerating the adoption of Phased Array technology, which offers superior beam steering agility and multi-target tracking compared to mechanically scanned antennas.
Market Restraints
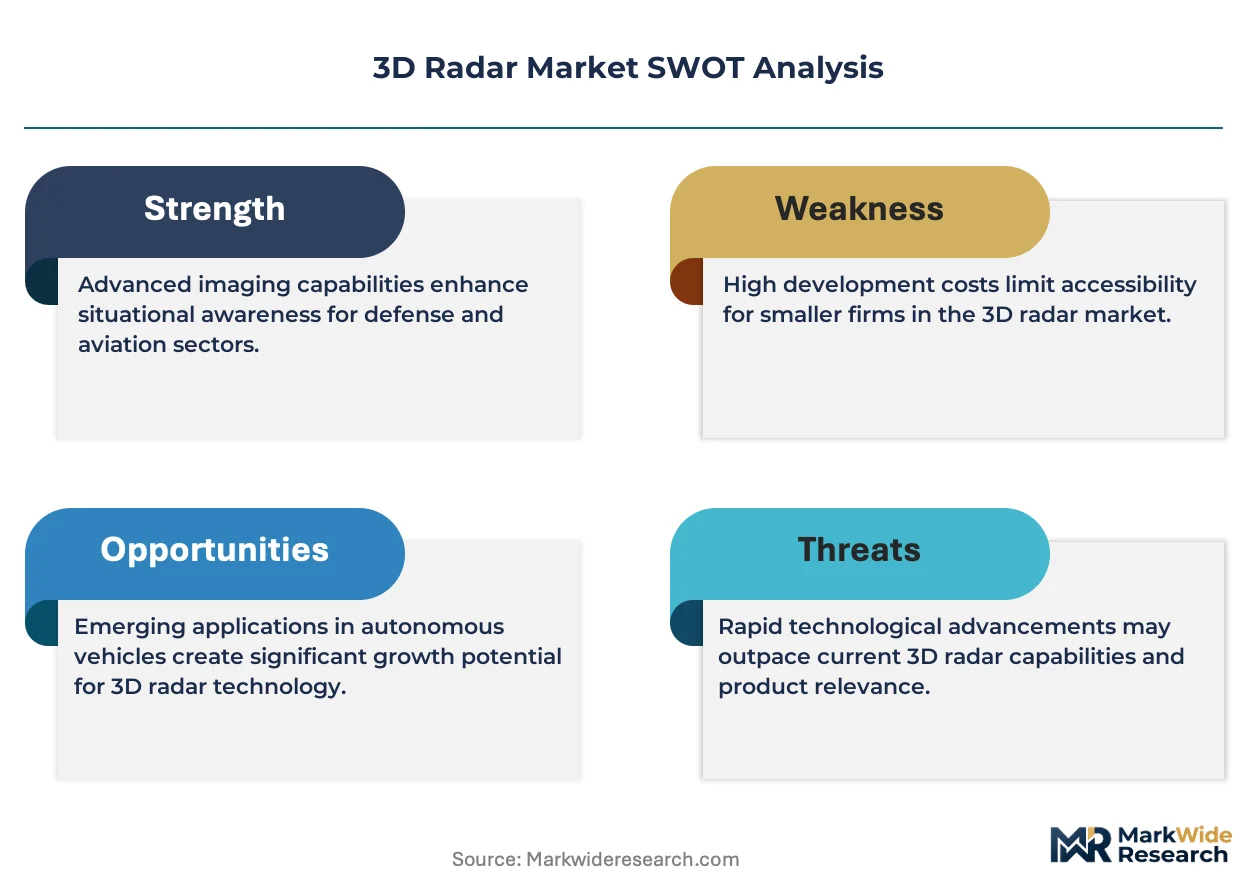
- High System Costs:The significant capital investment required for acquiring and deploying advanced Phased Array and AESA radar systems acts as a major barrier, particularly for smaller nations or civil agencies with limited budgets.
- Spectrum Allocation Conflicts:Competition for limited radio frequency spectrum, governed by regulators like the US FCC, creates operational constraints and potential interference issues for both military and civil radar deployments, especially in the congested S-band.
- Legacy System Integration:The technical complexity and high cost associated with integrating modern 3D radar systems into existing, often decades-old, command and control and air traffic management networks can delay or limit upgrade programs.
Strategic Opportunities
- Counter-UAV Applications:The proliferation of small, low-flying unmanned aerial vehicles presents a significant opportunity for specialized 3D radar systems designed for drone detection, classification, and tracking in border surveillance and critical infrastructure protection.
- Sensor Fusion with AI:Integrating 3D radar data with artificial intelligence and machine learning algorithms offers a pathway to develop predictive threat assessment and autonomous decision-support tools, moving beyond simple target detection.
- Airport Expansion in Emerging Economies:Rapid airport construction and modernization projects across Southeast Asia and Africa create new greenfield opportunities for vendors to supply complete air traffic control surveillance suites, bypassing legacy integration challenges.
Industry Challenges
- Specialized Talent Scarcity:A shortage of engineers and technicians with expertise in RF engineering, signal processing, and Phased Array system maintenance poses a significant operational challenge for both manufacturers and end-users.
- Complex Certification Cycles:Navigating the lengthy and rigorous certification processes mandated by aviation authorities like EASA and the FAA for new air traffic control radar systems can significantly extend product development and deployment timelines.
- Cybersecurity Vulnerabilities:As radar systems become more networked and software-defined, ensuring their resilience against cyberattacks and electronic warfare threats is a critical and increasingly complex operational requirement for all stakeholders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Radar Market |
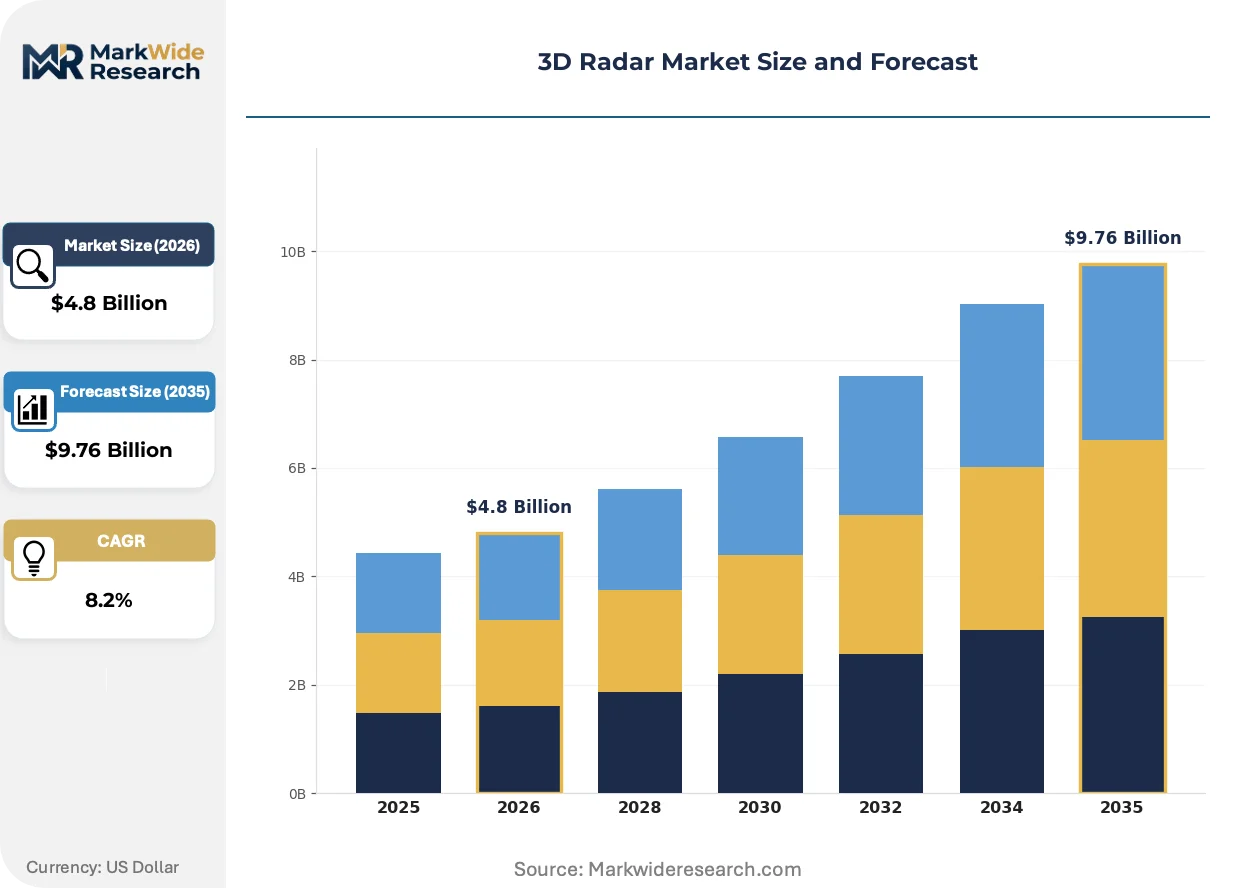
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.76 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Airborne, Ground-Based, Spaceborne, Naval, Portable Technology: Phased Array, Doppler, Pulse Compression, Frequency Modulated Continuous Wave, Synthetic Aperture Application: Border Surveillance, Weather Forecasting, Air Traffic Control, Maritime Navigation, Disaster Management End User: Defense Forces, Space Agencies, Meteorological Departments, Airport Authorities, Maritime Operators |
| Companies Covered | Lockheed Martin Corporation, BAE Systems plc, Raytheon Technologies Corporation, Leonardo S.p.A., Hensoldt AG, Northrop Grumman Corporation, Saab AB, L3Harris Technologies, Inc., Thales Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Radar Market Strategic Shifts & Innovations
The market's evolution is defined by a technological push toward solid-state components and a demand-side pull for more flexible, data-centric surveillance solutions. This dual pressure is forcing a re-evaluation of traditional hardware-centric business models across both defense and civil segments.
Gallium Nitride (GaN) semiconductor technology enables the development of more powerful, efficient, and compact Active Electronically Scanned Array (AESA) antennas. Defense end-users, particularly for naval and mobile ground-based platforms, are rapidly adopting GaN-based systems to achieve superior detection range and reliability. The proliferation of these high-performance, smaller-form-factor components is fragmenting the market dominance of large, fixed-site radar installations by enabling distributed and relocatable sensor networks.
Europe's Single European Sky Air Traffic Management Research (SESAR) initiative is a key regulatory driver. The program mandates greater data sharing and system interoperability among the continent's air navigation service providers to improve efficiency and safety. Air traffic management system suppliers are most affected, as they must now engineer 3D radar products that adhere to new EASA standards for open architecture and standardized data formats.
A clear behavioral shift is occurring away from large capital-expenditure sales toward more flexible service-based agreements for surveillance data. This model disrupts the traditional hardware procurement cycle, allowing civil entities like port authorities and environmental agencies to access advanced 3D radar capabilities without the burden of asset ownership and maintenance. This trend is gaining the most traction in applications like coastal surveillance and wind farm monitoring in Australia and parts of Northern Europe.
3D Radar Market Segmentation
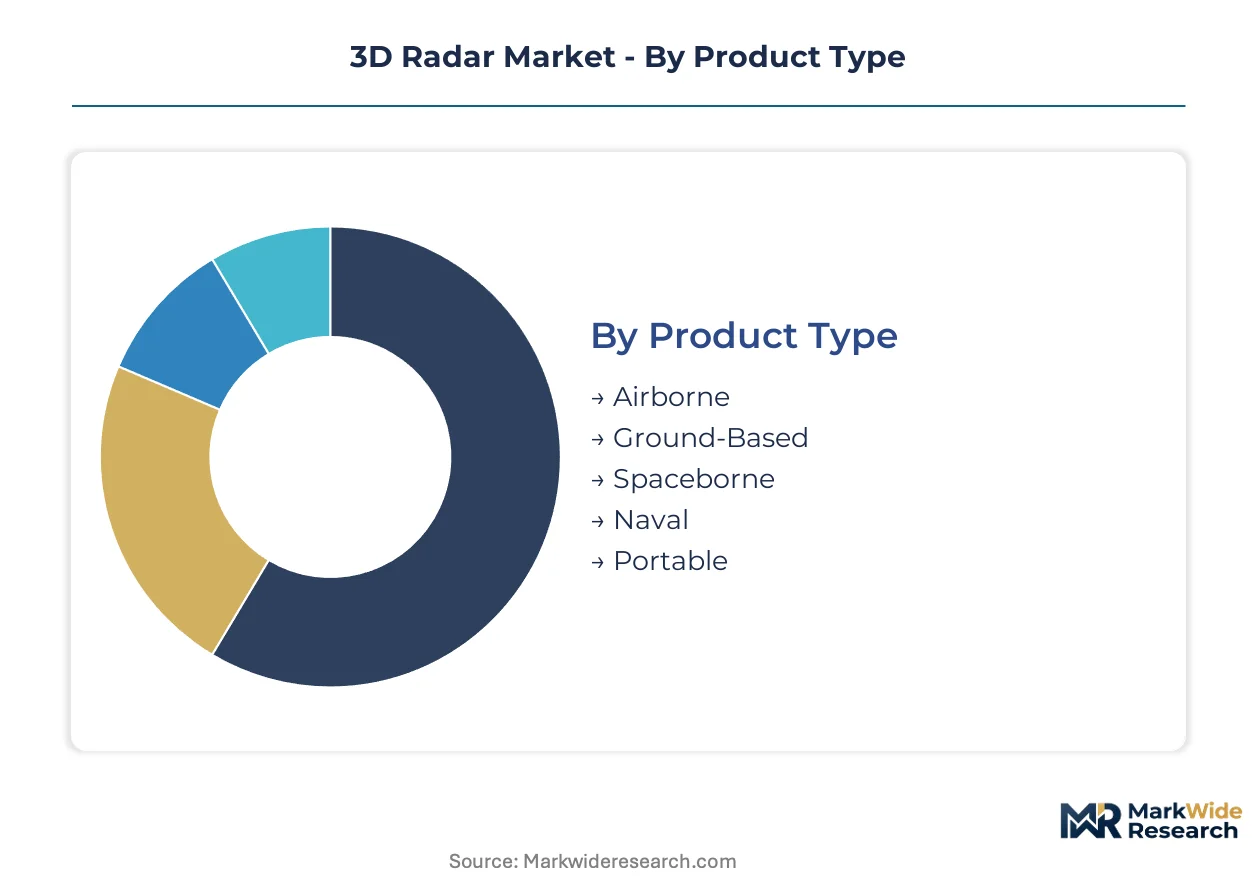
Understanding the segmentation within the 3D Radar Market is crucial for identifying areas of concentrated investment and evolving operational requirements. The market's diverse applications and technological advancements necessitate a granular view of product types, underlying technologies, specific applications, and the end-user base driving procurement decisions.
Product Type:
Margin pools within the 3D radar market's product types are heavily influenced by system complexity and deployment environments.
- Airborne:Integrated into aircraft for surveillance and early warning missions, airborne systems provide mobile and flexible coverage for defense and border security.
- Ground-Based:These systems represent foundational infrastructure, deployed in fixed installations or mobile configurations for comprehensive defense and civil surveillance. Defense modernization programs in India and Saudi Arabia are driving procurement of advanced ground-based systems to enhance airspace sovereignty.
- Spaceborne:Orbiting platforms provide wide-area surveillance and environmental monitoring capabilities, primarily for governmental and scientific agencies.
- Naval:Integrated into shipboard combat systems, naval 3D radars often utilize Active Electronically Scanned Array technology for maritime situational awareness. Defense end-users are rapidly adopting Gallium Nitride-based systems for superior detection range and reliability on naval platforms.
- Portable:Lightweight systems support rapid deployment for tactical military operations or temporary border control scenarios, offering flexibility for varied missions.
Ground-Based systems hold installed capacity. Naval systems are rotating up the share rankings.
Technology:
The cost tier for 3D radar technologies varies significantly based on complexity and performance capabilities.
- Phased Array:This technology utilizes multiple radiating elements for electronic beam steering without mechanical movement, offering superior agility and multi-target tracking. Demand for enhanced situational awareness in complex environments is accelerating the adoption of Phased Array technology.
- Doppler:Doppler radar measures target velocity by detecting frequency shifts in reflected signals, enabling precise tracking of moving objects. Investment in more advanced Air Traffic Control and Border Surveillance systems drives demand for enhanced Doppler and Pulse Compression technologies.
- Pulse Compression:This technique enhances range resolution and signal-to-noise ratio in radar systems, improving detection capabilities in challenging conditions.
- Frequency Modulated Continuous Wave:This technology provides continuous target illumination for high-resolution ranging, commonly used in short-range applications like autonomous vehicles and industrial sensing.
- Synthetic Aperture:Synthetic Aperture Radar utilizes platform motion to synthesize a large antenna, achieving high spatial resolution imagery for reconnaissance and mapping.
Phased Array technology is climbing the fastest. Doppler technology continues to see robust investment.
Application:
Diverse application areas for 3D radar systems reflect critical operational needs across civil and defense sectors.
- Border Surveillance:These systems detect and track unauthorized entries across national borders, including ground and low-altitude air targets like unmanned aerial vehicles. The proliferation of small, low-flying unmanned aerial vehicles presents a significant opportunity for specialized 3D radar systems in border surveillance.
- Weather Forecasting:Meteorological departments utilize 3D radar to provide real-time data on precipitation, wind shear, and storm systems for accurate weather prediction.
- Air Traffic Control:Air Traffic Control systems monitor aircraft movements in controlled airspace, providing precise range, azimuth, and elevation data for safe and efficient operations. Regulatory mandates from the US FAA and Europe's EASA compel airport authorities to invest in next-generation air surveillance systems.
- Maritime Navigation:This application assists vessels in collision avoidance and port approaches by detecting other ships, obstacles, and navigational hazards.
- Disaster Management:3D radar supports emergency services by monitoring hazardous weather events, assessing damage post-disaster, and guiding rescue operations.
Air Traffic Control applications currently dominate investment. Border Surveillance applications are gaining share fastest.
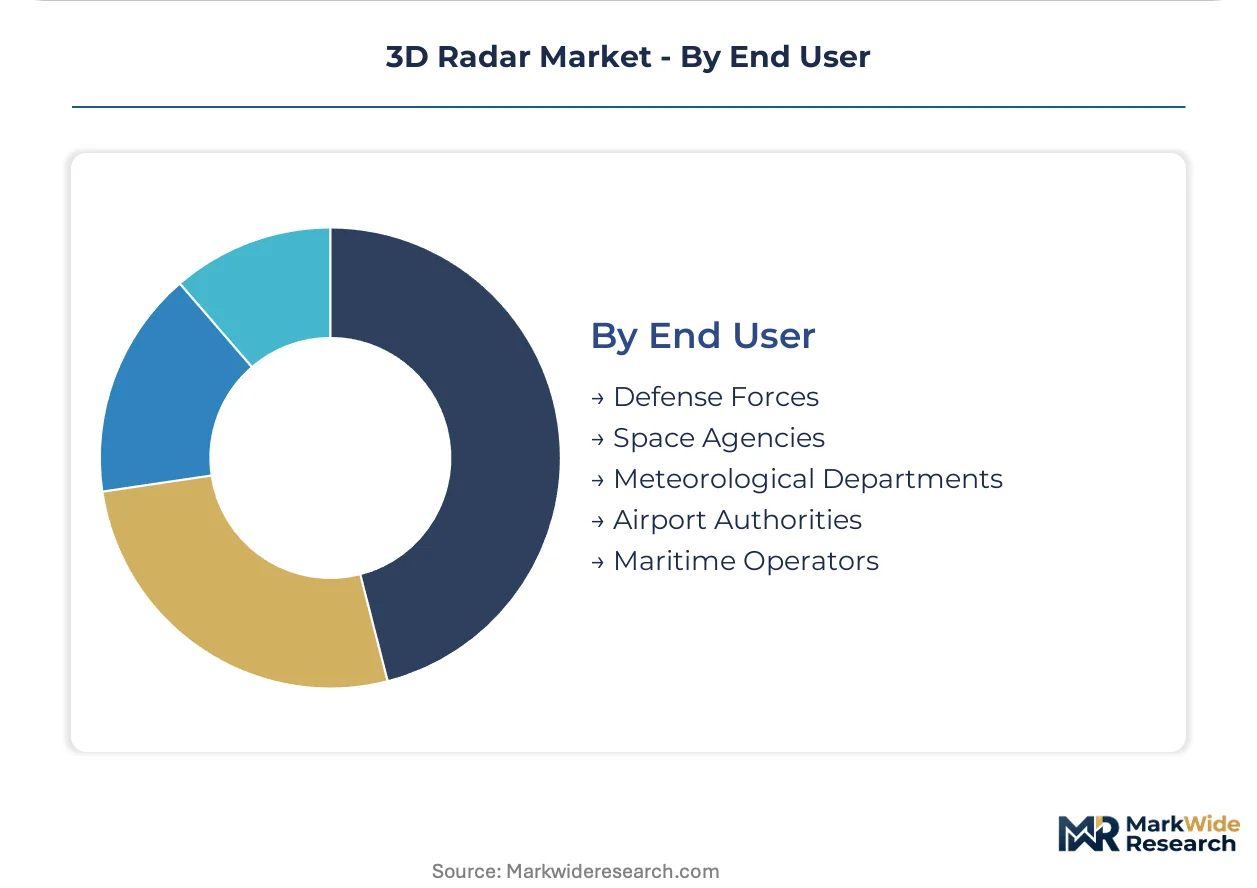
End User:
The customer type for 3D radar solutions has diversified, moving beyond traditional defense procurement.
- Defense Forces:Military organizations utilize 3D radar for air defense, early warning, ground-based surveillance, and counter-battery missions. Procurement is concentrating in nations undergoing extensive defense modernization, including the United States, India, and Saudi Arabia.
- Space Agencies:These agencies employ 3D radar for space debris tracking, satellite monitoring, and orbital trajectory analysis to ensure space safety.
- Meteorological Departments:National meteorological departments require advanced radar for weather forecasting, severe storm detection, and climate monitoring.
- Airport Authorities:These civil entities are responsible for air traffic control, requiring precise target information for managing increasing air traffic density. Regulatory standards from bodies such as the FAA and EASA are compelling airport authorities to invest in next-generation air surveillance systems.
- Maritime Operators:Port authorities, coast guards, and commercial shipping companies utilize 3D radar for port security, coastal surveillance, and vessel traffic management.
Defense Forces remain a foundational end-user. Airport Authorities are on the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global 3D radar market sees purchasing influence diffusing from traditional defense ministries to diverse civil authorities. Airport authorities and meteorological departments globally now drive significant procurement. This shift necessitates dual-use systems meeting both military and civil air traffic control standards.
United States
Demand for advanced 3D radar systems in the United States stems from ongoing defense modernization and critical air traffic control upgrades. The FAA mandates stringent performance requirements for next-generation air traffic management. Aerospace and defense hubs like Seattle foster innovation in radar signal processing and integration technologies.
India
India's market expansion is driven by national security imperatives, significant defense modernization, and extensive airport infrastructure projects. The PLI scheme actively encourages domestic manufacturing of defense electronics and advanced surveillance systems. Bengaluru's vibrant defense R&D centers focus on developing sophisticated ground-based radar for airspace sovereignty.
Saudi Arabia
Saudi Arabia exhibits strong demand from ambitious defense modernization initiatives and substantial new infrastructure developments. The Saudi Vision 2030 explicitly prioritizes enhancing national defense capabilities and securing critical assets. Riyadh serves as a central hub for defense procurement and strategic partnerships, attracting global radar system providers.
Germany
Germany sees demand for advanced 3D radar solutions, particularly for naval and ground-based platforms, emphasizing precision and reliability. EASA standards significantly guide air traffic management system development, ensuring interoperability across the European Union. Bavaria hosts key radar manufacturers like Hensoldt AG, specializing in advanced sensor solutions.
France
France drives procurement for sophisticated dual-use systems, balancing civil air traffic control requirements with military surveillance missions. The SESAR initiative promotes greater data sharing and interoperability for efficient European air traffic management. Toulouse’s robust aerospace industry actively integrates advanced radar systems into new aircraft and ground control infrastructure.
3D Radar Market Key Industry Players
Player mix skews toward large, established defense contractors and specialized sensor solution providers. The market structure exhibits a tiered consolidation, with a few global giants dominating high-value defense contracts and system integration. Strategic archetypes include integrated aerospace and defense conglomerates, advanced sensor specialists, and niche technology innovators. Companies are increasingly pursuing portfolio diversification into dual-use systems and strategic partnerships to expand market reach and address evolving end-user needs.
Integrated aerospace and defense conglomerates, such as Thales Group, exemplify the shift towards dual-use systems serving both civil air traffic control and military surveillance missions globally. US-based Raytheon Technologies Corporation occupies a position leveraging deep integration with the US Department of Defense, securing long-range surveillance contracts for national security. German-based Hensoldt AG represents specialists in advanced sensor solutions for naval and ground-based platforms across Europe, focusing on cutting-edge radar technologies and AESA advancements.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| BAE Systems plc |
| Raytheon Technologies Corporation |
| Leonardo S.p.A. |
| Hensoldt AG |
| Northrop Grumman Corporation |
| Saab AB |
| L3Harris Technologies, Inc. |
| Thales Group |
| Others |
Cost & Logistics Intelligence
High capital expenditure requirements for advanced 3D radar systems drive economies of scale, concentrating manufacturing capabilities among a few large defense contractors. This concentration directly influences price floors for complex Phased Array solutions.
Pricing Analysis
Cost-plus contracts, often indexed to defense spending and specialized component costs like Gallium Nitride, dominate procurement for complex 3D radar systems. Price differentiation stems from Phased Array technology sophistication, stringent FAA and EASA certification levels, and comprehensive after-sales service bundles. Pricing pressure stems from civil agencies, with Airport Authorities being highly price-sensitive due to public funding constraints. Defense Forces, prioritizing national security, exhibit lower price sensitivity for mission-critical systems.
Supply Chain Analysis
Strategic stockpiles of critical components, rather than just-in-time inventory, characterize the supply chain for high-value 3D radar systems due to long lead times. Geographic supply concentrates in the United States, Germany, and France, where major manufacturers are based. The industry relies on specialized RF components and Gallium Nitride semiconductors, creating single-source vulnerability for advanced GaN components. Distribution runs through direct sales channels to government entities and prime contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The 3D radar market offers fragmentation opportunities as diverse civil authorities expand their purchasing influence. This shift, driven by increasing air traffic density and new counter-UAV needs, creates niches for specialized surveillance systems.
For Market Incumbents: Compound existing technological leadership by prioritizing investment in dual-use systems that meet both military and civil air traffic control standards. Strategic partnerships in rapidly modernizing regions like India and Saudi Arabia can counter market fragmentation from niche players. Deepen certification investment for new EASA and FAA performance requirements, addressing the threat of regulatory non-compliance. Expand service-based agreements to capture recurring revenue streams.
For New Entrants and Emerging Players: Lead with specialized solutions for under-addressed segments, such as counter-UAV applications for critical infrastructure protection. Focus on portable systems designed for rapid deployment in tactical military operations or temporary border control scenarios. The most penetrable segment lies within airport expansion projects in emerging economies like Southeast Asia, bypassing legacy integration challenges. Offer flexible service-based agreements for surveillance data, reducing upfront capital expenditure for civil agencies.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among firms offering long-term maintenance contracts and service-based data subscriptions for 3D radar systems. The market offers sustained growth over the next decade, driven by ongoing defense modernization and civil aviation safety mandates. Niche technology innovators specializing in GaN-based AESA systems or AI-driven sensor fusion represent attractive acquisition targets. Proliferation of service-based radar data agreements indicates a shift towards predictable revenue streams, a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Use System Development | Addresses demand from both military and civil air traffic control end-users, expanding market reach. |
| GaN AESA Technology Investment | Enables superior detection range and reliability for naval and ground-based platforms. |
| AI-Driven Sensor Fusion Integration | Develops predictive threat assessment tools, moving beyond basic target detection capabilities. |
| Service-Based Data Offerings | Lowers entry barriers for civil entities, providing access to advanced radar without asset ownership. |
| Certification for Aviation Standards | Ensures compliance with strict regulatory mandates from bodies like FAA and EASA. |
Research Approach
A standing panel of air traffic controllers, defense procurement officers, radar engineers, and meteorological data scientists provided ongoing calibration for market assumptions. This primary research, combining in-depth interviews with industry stakeholders, was validated against secondary sources. These included FAA regulatory documents, EASA technical specifications, defense modernization program reports, and industry association publications. Bottom-up and top-down analysis ensured comprehensive data triangulation.
Consistency checks against external benchmarks ensured the robustness of the analytical framework over the projection horizon. The quantitative model segmented the market by product type, technology, application, end-user, and regional defense spending. Compound Annual Growth Rates were derived from historical data trends and projected adoption rates. National defense budgets and air traffic volume projections served as key industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside significant geopolitical shifts or unforeseen technological breakthroughs would require recalibration. Forecasts reflect assumptions regarding market dynamics and regulatory stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Navigation & Surveillance
Autonomous Navigation Processing Unit Market
Communication Navigation & Surveillance
Autonomous Navigation System Market
Communication Navigation & Surveillance
Advanced Antenna System Market
Communication Navigation & Surveillance
Tactical Radio Market
Communication Navigation & Surveillance
Airborne SATCOM Equipment Market
Communication Navigation & Surveillance
Military Antenna Market
Communication Navigation & Surveillance
Naval Tactical Communication Market
Communication Navigation & Surveillance
Man-Portable Military Communication Systems Market
Communication Navigation & Surveillance
Global Military Communications Market
Communication Navigation & Surveillance
Man Portable Communication Systems Market
Communication Navigation & Surveillance
Advanced Surface Movement Guidance and Control System (A-SMGCS) Market
Communication Navigation & Surveillance
Asia-Pacific Autonomous Navigation Market
Communication Navigation & Surveillance
Missile Guidance Radar Market
Communication Navigation & Surveillance
EMEA Mission Critical Wireless Communications Market
Communication Navigation & Surveillance
Space Situational Awareness Sensor and Tracking Performance Test Systems Market
Communication Navigation & Surveillance
Dual Axis Gyro Stabilized Platform Market