
 Inertial Systems Market | 2026-2036
Inertial Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Inertial Systems Market Outlook
The performance gap between fiber-optic inertial navigation and commodity MEMS sensors is realigning procurement patterns across defense and commercial channels. Honeywell International Inc. leverages its ring-laser gyroscope heritage to dominate strategic-grade navigation contracts. Bosch Sensortec GmbH anchors high-volume automotive MEMS supply through captive wafer fabrication and tier-one channel control. KVH Industries Inc. specializes in maritime and unmanned platform stabilization where medium-precision fiber systems occupy a defensible margin tier.
Inertial systems encompass gyroscopes, accelerometers, and integrated navigators that measure angular rate and linear acceleration to compute position, velocity, and attitude without external references. Fiber-optic gyroscopes achieve drift rates below 0.001 degrees per hour through Sagnac-effect interferometry, enabling submarine-launched ballistic missile guidance where GPS denial is assumed. Accelerometer demand concentrates in automotive end-use as electric vehicle platforms integrate six-axis inertial measurement units for torque vectoring and regenerative braking control. Microelectromechanical systems technology leads unit volume while ring-laser systems retain the highest value concentration in aerospace and defense applications.
FAA certification requirements for commercial unmanned aircraft systems mandate redundant inertial navigation architectures, expanding addressable demand for dual-GNSS/INS platforms. The EU AI Act and CE marking frameworks for autonomous mobility systems impose traceability standards on sensor fusion algorithms that incorporate inertial data streams. Stakeholders must monitor how export control classifications under the Wassenaar Arrangement restrict ring-laser gyroscope technology transfers, as these constraints reshape supplier eligibility for defense programs and determine which manufacturers can compete in allied nation procurement cycles.
Market Dynamics
Defense procurement for precision-guided munitions is accelerating as NATO members modernize guidance packages under updated defense frameworks. MEMS-based inertial measurement units are displacing legacy mechanical systems in automotive stability control, compressing supplier margins while expanding unit volumes.
Growth Catalysts
- FAA certification requirements:Commercial unmanned aircraft systems now mandate redundant inertial navigation architectures, expanding addressable demand for dual-GNSS/INS platforms across US airspace.
- Electric vehicle platforms:Six-axis inertial measurement units integrate for torque vectoring and regenerative braking control, pulling accelerometer demand into automotive end-use.
- EU AI Act traceability standards:Autonomous mobility systems must demonstrate algorithmic accountability for sensor fusion incorporating inertial data streams.
Market Restraints
- Ring-laser gyroscope export controls:Wassenaar Arrangement classifications restrict technology transfers, reshaping supplier eligibility for defense programs in allied nations.
- High-purity fiber coil supply:Strategic-grade fiber-optic gyroscope production depends on concentrated specialty fiber sources, creating single-point vulnerability.
- MEMS performance ceiling:Drift rates in commodity microelectromechanical systems remain orders of magnitude above fiber-optic baselines, limiting navigation-grade applicability.
Strategic Opportunities
- Maritime unmanned platforms:Medium-precision fiber systems occupy defensible margin tiers in vessel stabilization and autonomous surface vehicle navigation.
- CE marking convergence:EU regulatory frameworks for autonomous mobility create certification pathways for integrated inertial-GNSS platforms entering European markets.
- Automotive tier-one channel control:Captive wafer fabrication and direct OEM relationships enable volume positioning in stability control module supply chains.
Industry Challenges
- Sensor fusion algorithm validation:Demonstrating traceability for AI Act compliance demands specialized expertise in inertial data stream integration.
- Dual-use technology licensing:Navigating export control classifications requires legal specialization distinct from standard commercial contracting.
- Legacy mechanical system obsolescence:Transitioning defense platforms from mechanical gyroscopes demands sustained engineering support for mixed-fleet operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inertial Systems Market |
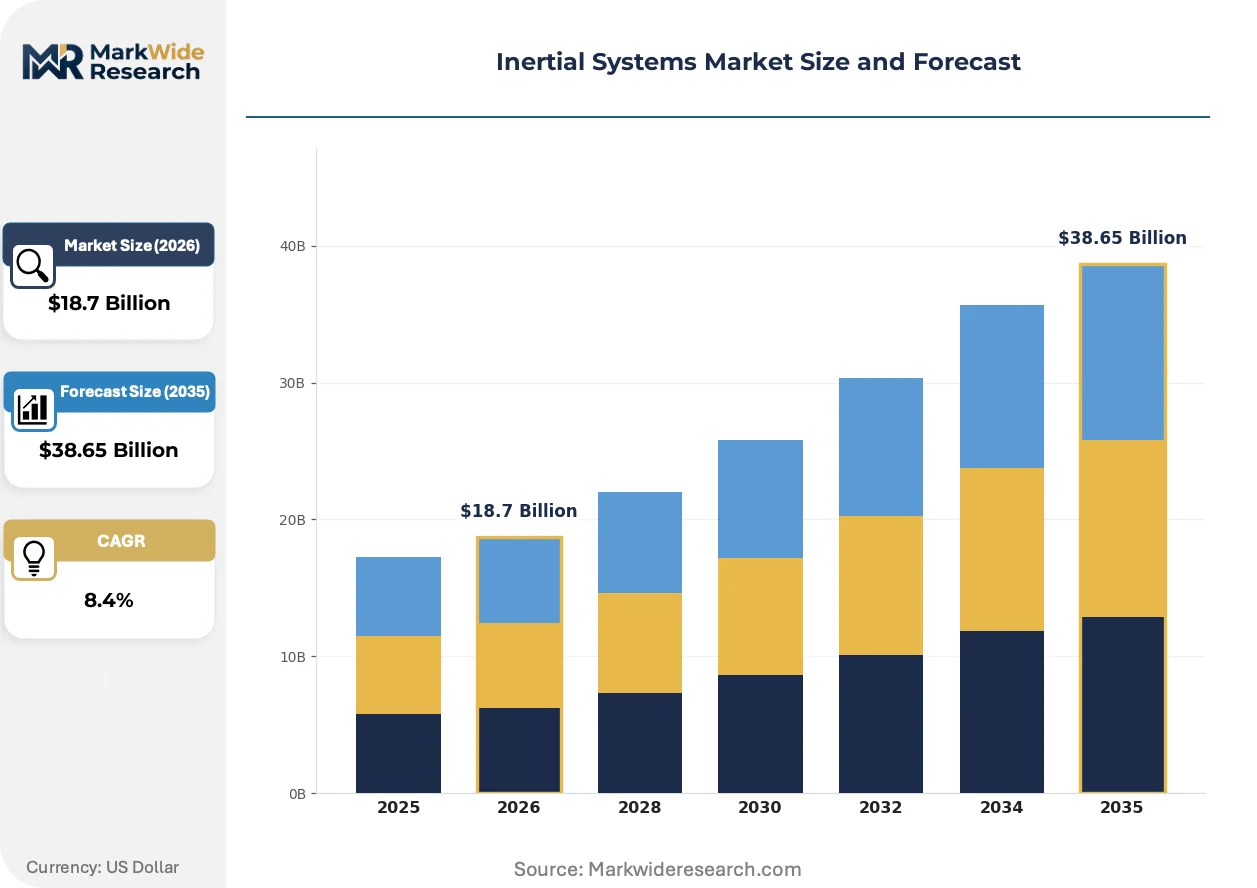
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gyroscopes, Accelerometers, Navigators, Sensors End User: Aerospace, Automotive, Defense, Robotics Technology: Microelectromechanical Systems, Fiber Optic, Ring Laser, Quartz Application: Guidance, Navigation, Control Systems, Stabilization |
| Companies Covered | Honeywell International Inc., Northrop Grumman Corporation, Safran S.A., Thales S.A., Raytheon Technologies Corporation, KVH Industries Inc., Hexagon AB, L3 Harris Technologies, Bosch Sensortec GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inertial Systems Market Strategic Shifts
Performance tier fragmentation is reshaping competitive positioning across defense and commercial channels. Technology convergence between fiber-optic precision and MEMS cost structures is creating new intermediate product categories.
Photonic integrated circuit gyroscopes are expanding into tactical-grade navigation applications previously reserved for discrete fiber-optic systems. Defense contractors in the United States are piloting these compact platforms for unmanned aerial vehicle guidance where SWaP constraints dominate. The technology is expanding into medium-precision market tiers, compressing the addressable space for conventional fiber coils while opening volume opportunities below strategic-grade thresholds.
EU AI Act algorithmic accountability requirements are mandating traceability documentation for sensor fusion systems processing inertial data streams. Autonomous vehicle manufacturers must demonstrate reproducible decision pathways for safety-critical navigation outputs. German automotive regulators at KBA are advancing technical interpretations that treat inertial-GNSS fusion as high-risk AI under the Act's classification framework.
Defense procurement cycles are compressing as NATO members accelerate munitions guidance modernization under updated collective defense commitments. Multi-year inertial navigation contracts are fragmenting into shorter development phases with faster technology refresh requirements. United States Department of Defense testing protocols are adapting to accommodate rapid insertion of improved MEMS and fiber-optic components without full platform recertification.
Inertial Systems Market Segmentation
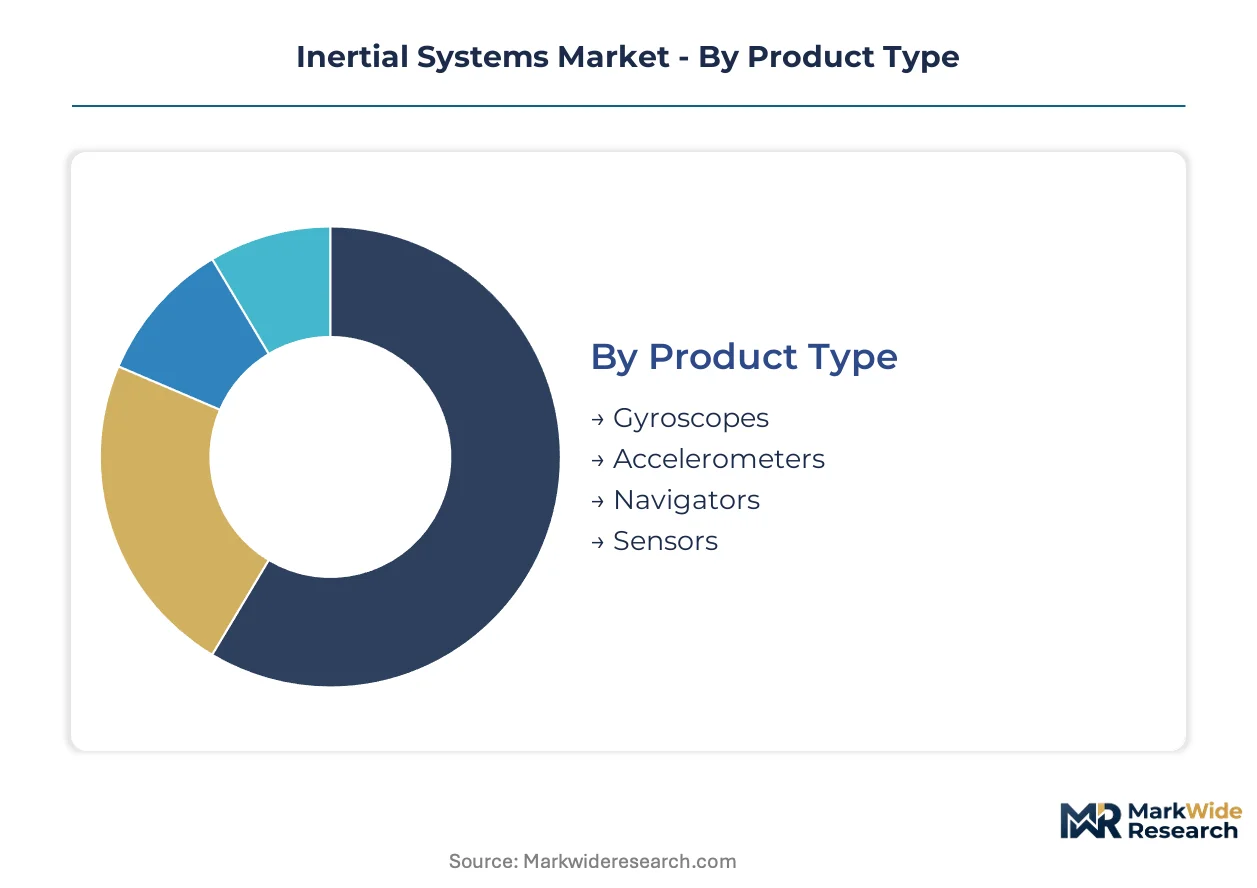
Performance tier fragmentation across inertial systems creates distinct procurement channels where strategic-grade specifications command premium positioning while MEMS volume economics reshape automotive supply chains. Technology convergence between fiber-optic precision and microelectromechanical cost structures generates new intermediate categories that compress traditional segmentation boundaries.
Product Type:
Specification hierarchies differentiate products by drift tolerance, environmental resilience, and integration complexity for platform-specific deployment.
- Gyroscopes:Ring-laser configurations achieve sub-0.001 degree-per-hour drift rates through helium-neon cavity stabilization, sustaining demand for submarine-launched ballistic missile guidance where GPS denial is operational doctrine. Sagnac-effect fiber-optic variants occupy tactical-grade tiers in unmanned aerial vehicle stabilization.
- Accelerometers:Capacitive MEMS devices measure linear acceleration through proof-mass displacement detection, concentrating demand in electric vehicle torque vectoring systems where six-axis inertial measurement units integrate with regenerative braking controllers. Automotive OEMs specify these for stability control modules.
- Navigators:Integrated inertial-GNSS platforms combine gyroscopic and accelerometric inputs with satellite correction for redundant position computation in commercial unmanned aircraft systems.
- Sensors:Discrete inertial elements serve custom fusion architectures where OEMs demand algorithm-specific data stream characteristics.
Mature deployment sits with gyroscopes in defense guidance applications. Newer deployment is concentrated in accelerometers for electric vehicle platform integration.
End User:
Customer procurement patterns diverge sharply between defense multi-year contracting cycles and automotive annual volume negotiations.
- Aerospace:Commercial unmanned aircraft systems mandate redundant inertial navigation architectures under FAA certification protocols, expanding dual-GNSS/INS platform demand across US airspace operations. Regional jet manufacturers specify medium-precision fiber systems for flight control backup.
- Defense:NATO munitions modernization programs accelerate precision-guided weapon guidance package procurement under updated collective defense frameworks. Multi-year inertial navigation contracts fragment into shorter technology refresh phases.
- Automotive:Electric vehicle platforms integrate six-axis inertial measurement units for torque vectoring and regenerative braking control, pulling accelerometer demand through tier-one supplier channels.
- Robotics:Autonomous mobile platforms require medium-precision stabilization for navigation in GPS-degraded environments.
Defense procurement sustains longest contract horizons. Automotive volumes are climbing the fastest as electrification accelerates platform sensor integration.
Technology:
Fabrication method determines performance ceiling, unit economics, and export control classification for cross-border supply.
- Microelectromechanical Systems:Silicon wafer fabrication enables sub-dollar unit costs at million-scale volumes, displacing legacy mechanical systems in automotive stability control while drift rates remain orders of magnitude above optical baselines. Bosch Sensortec anchors supply through captive foundry capacity.
- Fiber Optic:Specialty high-purity fiber coil winding achieves tactical-grade precision for maritime unmanned platform stabilization where medium-accuracy navigation suffices. KVH Industries specializes in this defensible margin tier.
- Ring Laser:Helium-neon cavity gyroscopes retain highest value concentration in strategic-grade aerospace and defense applications where Honeywell leverages heritage positioning.
- Quartz:Piezoelectric resonant structures serve cost-sensitive industrial applications with moderate precision requirements.
Ring-laser systems anchor highest-value defense contracts. Photonic integrated circuit platforms are gaining share fastest as SWaP-constrained unmanned systems demand compact alternatives.
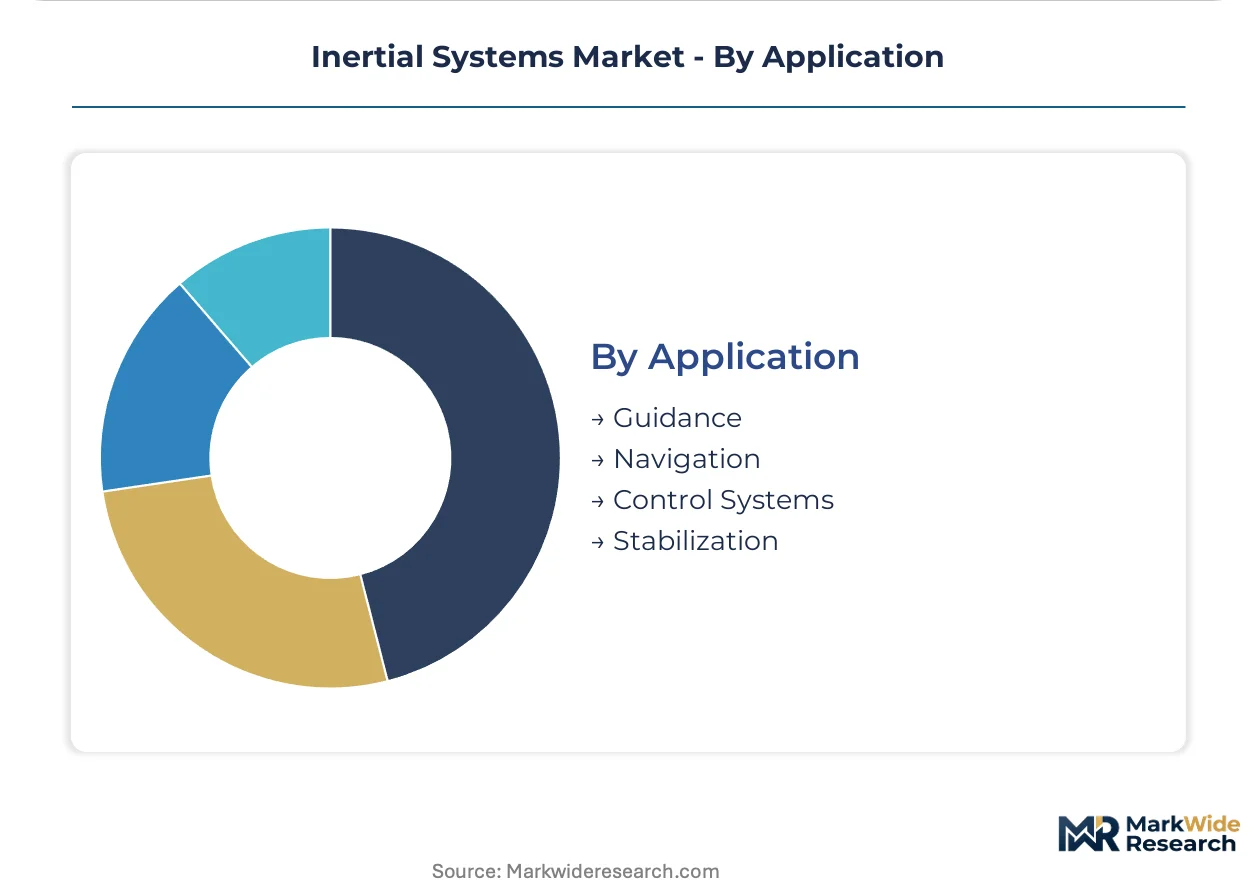
Application:
Functional use case dictates redundancy requirements, certification burden, and algorithmic accountability standards.
- Guidance:Precision-guided munitions integrate inertial measurement units with terminal seekers, with NATO members modernizing packages under updated defense frameworks. Drift compensation algorithms must demonstrate reproducible decision pathways.
- Navigation:Commercial unmanned aircraft systems require redundant inertial-GNSS fusion for FAA certification, with EU AI Act traceability standards mandating algorithmic accountability for sensor fusion outputs.
- Control Systems:Electric vehicle stability modules process six-axis inertial data for torque vectoring decisions under German KBA technical interpretations treating fusion as high-risk AI.
- Stabilization:Maritime unmanned surface vehicles employ medium-precision fiber systems for vessel attitude control in wave-induced motion environments.
Guidance applications retain longest qualification cycles. Navigation platforms are expanding most quickly as regulatory mandates proliferate across US and European airspace.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater Boston anchors North American inertial systems development, hosting defense contractors and precision navigation startups clustered around MIT Lincoln Laboratory and Draper Laboratory research corridors. The metro's concentration of submarine navigation heritage and autonomous vehicle testing infrastructure shapes procurement patterns for both strategic-grade and automotive-grade inertial platforms.
United States
The Department of Defense sustains multi-year inertial navigation contracts for precision-guided munitions modernization, while commercial autonomous vehicle testing accelerates in Arizona and California. FAA certification requirements for commercial unmanned aircraft systems mandate redundant inertial-GNSS architectures, expanding dual-platform demand across US airspace. The Pentagon's rapid technology refresh protocols are compressing procurement cycles in the Baltimore-Washington defense corridor.
Germany
Automotive OEMs specify six-axis inertial measurement units for electric vehicle torque vectoring systems, pulling accelerometer demand through Stuttgart and Munich tier-one channels. KBA technical interpretations treat inertial-GNSS sensor fusion as high-risk AI under the EU AI Act, mandating algorithmic traceability documentation. The Bavarian automotive cluster is advancing certification pathways for integrated navigation platforms entering European markets.
France
Safran and Thales anchor defense navigation supply for NATO munitions guidance modernization programs under updated collective defense frameworks. The EU AI Act's CE marking requirements for autonomous mobility systems impose traceability standards on sensor fusion algorithms incorporating inertial data streams. The Paris-Saclay research cluster is piloting photonic integrated circuit gyroscopes for tactical-grade unmanned aerial vehicle applications.
Japan
Automotive electrification is accelerating MEMS inertial sensor integration for stability control modules in Toyota City and Nagoya manufacturing zones. METI industrial standards for autonomous vehicle safety systems are aligning with EU AI Act accountability frameworks for sensor fusion outputs. The Kanto region's precision manufacturing base is expanding medium-precision fiber-optic production for maritime unmanned platform stabilization.
United Kingdom
BAE Systems and defense primes are modernizing guidance packages for precision munitions under NATO framework commitments, fragmenting multi-year contracts into shorter technology refresh phases. The Civil Aviation Authority is adapting certification protocols for dual-GNSS/INS platforms in commercial unmanned aircraft systems. The Bristol aerospace cluster is developing compact inertial navigators for SWaP-constrained unmanned aerial vehicles.
Inertial Systems Market Competitive Environment
Premium-margin players sit above commodity-margin players across performance-grade stratification, with strategic-grade navigation commanding value multiples above automotive MEMS volumes. The vendor base organizes into heritage defense contractors with ring-laser gyroscope legacies, high-volume MEMS fabricators with captive wafer capacity, and maritime specialists occupying defensible medium-precision tiers. Dominant competitive moves include backward integration into specialty fiber coil supply and strategic partnerships for photonic integrated circuit development.
Within the heritage defense contractor tier, Honeywell International Inc. and Northrop Grumman Corporation exemplify positioning built on decades of strategic-grade navigation heritage. Among European-based diversified aerospace groups, Safran S.A. and Thales S.A. occupy positions spanning defense and commercial aviation channels. At the specialized maritime and unmanned platform end, KVH Industries Inc. represents the medium-precision fiber-optic specialist archetype where defensible margins persist below strategic-grade thresholds.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Northrop Grumman Corporation |
| Safran S.A. |
| Thales S.A. |
| Raytheon Technologies Corporation |
| KVH Industries Inc. |
| Hexagon AB |
| L3 Harris Technologies |
| Bosch Sensortec GmbH |
| Others |
Value Chain & Pricing Dynamics
EU AI Act traceability mandates for autonomous mobility systems gate qualified supply access and premium-tier pricing power, as sensor fusion algorithm documentation requirements separate certified vendors from commodity suppliers. Pricing stratifies across strategic-grade navigation, tactical-grade stabilization, and automotive MEMS tiers, with Wassenaar Arrangement export controls on ring-laser gyroscope technology further segmenting supplier eligibility and contract value.
Pricing Analysis
Navigation-grade uptime guarantees anchor value-based pricing for submarine and ballistic missile guidance contracts where GPS denial tolerance determines contract awards. Three-tier pricing structure across strategic-grade ring-laser systems, tactical-grade fiber-optic platforms, and commodity automotive MEMS reflects certification burden and drift-rate performance specifications. Cost compression in automotive MEMS intensifies as Bosch Sensortec's captive wafer fabrication scales million-unit volumes, while defense buyers show lowest price sensitivity due to mission-critical performance requirements and multi-year procurement horizons.
Supply Chain Analysis
High-purity fiber coil winding equipment rests on concentrated Japanese and German specialty manufacturing bases, with photonic integrated circuit foundry capacity clustering in United States and French defense research corridors. Helium-neon gas mixtures for ring-laser cavities, specialty optical fibers for Sagnac-effect gyroscopes, and silicon-on-insulator wafers for MEMS proof-mass fabrication constitute critical input dependencies. Single-source vulnerability in strategic-grade fiber supply creates procurement risk for defense contractors qualifying alternative coil sources. Distribution runs through tier-one automotive supplier channels for MEMS volumes and direct defense prime contracting for navigation-grade systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive control over specialty fiber coil supply and photonic integrated circuit fabrication capacity determines margin capture across performance tiers.
For Market Incumbents: To counter photonic integrated circuit displacement of discrete fiber-optic systems in tactical-grade applications, Honeywell and Northrop Grumman should deepen backward integration into specialty fiber coil winding capacity while accelerating compact navigator development for SWaP-constrained unmanned platforms. Defense contract fragmentation demands faster technology refresh cycles without full platform recertification.
For New Entrants and Emerging Players: Maritime autonomous surface vehicle manufacturers represent the most penetrable channel partner type for medium-precision fiber system suppliers seeking defensible margin tiers below strategic-grade thresholds. White-space concentration sits in vessel stabilization for unmanned platforms and photonic integrated circuit gyroscopes for tactical navigation. CE marking pathway investment unlocks European autonomous mobility certification demand.
For Investors and Strategic Acquirers: NATO munitions guidance modernization contract awards are the leading indicator that precision inertial navigation demand is accelerating beyond historical procurement cycles. Long-term viability favors vertically integrated suppliers controlling both fiber coil fabrication and algorithmic sensor fusion expertise. Watch for Department of Defense rapid technology refresh protocol expansions as inflection signal for component supplier consolidation opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Specialty Fiber Coil Backward Integration | Captive supply of high-purity fiber coils insulates KVH and defense primes from single-source vulnerability in Japanese specialty fiber sources. |
| Photonic Integrated Circuit Platform Development | Compact gyroscope alternatives for unmanned aerial vehicle guidance address SWaP constraints in Pentagon rapid insertion protocols. |
| EU AI Act Certification Pathway Investment | Algorithmic traceability documentation for inertial-GNSS fusion systems opens German KBA-regulated autonomous vehicle markets. |
| Tier-One Automotive Channel Control | Direct OEM relationships and captive wafer fabrication anchor Bosch Sensortec's positioning in electric vehicle stability module supply chains. |
| Maritime Unmanned Platform Specialization | Medium-precision fiber systems for vessel stabilization occupy defensible margin tiers where strategic-grade specifications exceed operational requirements. |
Study Parameters
Multi-period observation of defense procurement contract awards, FAA certification filings, and automotive platform sensor integration timelines anchored the trend analysis, supplemented by interviews with inertial navigation program managers at defense primes, MEMS product directors at tier-one automotive suppliers, fiber-optic gyroscope engineering leads, and autonomous vehicle sensor fusion architects. Secondary validation drew from Department of Defense budget justifications, EU AI Act technical interpretation documents, FAA unmanned aircraft system certification databases, and SEC filings of publicly traded navigation technology suppliers. Bottom-up unit demand modeling across gyroscope, accelerometer, and integrated navigator categories triangulated against top-down market value estimates from defense and automotive production forecasts.
Segment-weighting approaches distributed total market value across product type, end user, technology, and application dimensions, with additional stratification by performance grade and export control classification tier. CAGRs across the analysis window derived from regression-based projection of defense modernization cycle intensity, electric vehicle platform sensor content trajectories, and regulatory mandate adoption curves. Industry-specific forecast inputs incorporated NATO collective defense commitment refresh schedules, German KBA technical interpretation evolution for AI Act compliance, and photonic integrated circuit technology readiness level advancement.
Several conditions sit outside the modeled scope, including specific Wassenaar Arrangement reclassification events, individual defense program cancellation decisions, and automotive OEM platform delays beyond publicly announced timelines. Forecasts reflect documented assumptions about technology refresh protocol adoption and regulatory interpretation stability. A small set of named triggers warrants ongoing watch: Department of Defense rapid insertion protocol scope expansion, EU AI Act enforcement precedence establishment for sensor fusion systems, and specialty fiber coil supplier consolidation events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Navigation & Surveillance
Latin America Inertial Systems Market
Communication Navigation & Surveillance
UK Autonomous Navigation Market
Communication Navigation & Surveillance
Radar Transmitter Market
Communication Navigation & Surveillance
Autonomous Navigation Processing Unit Market
Communication Navigation & Surveillance
Global Military Communications Market
Communication Navigation & Surveillance
Naval Navigation and Communication Systems Market
Communication Navigation & Surveillance
Anti-Jamming Market
Communication Navigation & Surveillance
Integrated 3D Radar Market
Communication Navigation & Surveillance
EMEA Mission Critical Wireless Communications Market
Communication Navigation & Surveillance
Man Portable Communication Systems Market
Communication Navigation & Surveillance
Airborne SATCOM Market
Communication Navigation & Surveillance
Global X-Band Radar Market
Communication Navigation & Surveillance
Asia-Pacific Autonomous Navigation Market
Communication Navigation & Surveillance
Flight Tracking System Market
Communication Navigation & Surveillance
Doppler Radar Market
Communication Navigation & Surveillance
3D Radar Market