
 Global Interferometric Synthetic Aperture Radar (Insar) Market | 2026-2036
Global Interferometric Synthetic Aperture Radar (Insar) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Interferometric Synthetic Aperture Radar (Insar) Market Foresight
The gap between premium persistent-scatterer analytics and commodity repeat-pass processing is repositioning how vendors capture value. Airbus Defence and Space leverages its SAR satellite constellation to anchor high-margin defense and intelligence contracts. ICEYE competes through rapid-revisit capabilities and on-demand tasking models. CGG specializes in geophysical integration, extending InSAR outputs into reservoir monitoring workflows for energy clients.
Interferometric Synthetic Aperture Radar measures millimetric ground deformation by comparing phase differences between successive SAR acquisitions, typically operating at C-band, L-band, or X-band frequencies with spatial resolutions from meters to sub-meter scales. Its primary purpose is remote terrain stability assessment without physical ground instrumentation. Satellite-based deployment leads the value chain due to orbital persistence and coverage scalability, while unmanned aerial vehicles represent the fastest-expanding segment for site-specific, high-resolution campaigns. Government agencies dominate end-user spending, though environmental consultancies are capturing growing shares as climate-risk disclosure mandates tighten.
ESA's Copernicus framework and Sentinel data policy shape European demand by subsidizing baseline SAR imagery, while the US FAA regulates commercial remote-sensing licensing and orbital operations for domestic operators. Japan's METI promotes disaster-management InSAR integration through national Earth observation roadmaps. Stakeholders must weigh sovereign data-access rules against proprietary constellation investments when selecting sourcing strategies.
Market Dynamics
The divergence between freely available Sentinel-1 data and proprietary high-resolution SAR constellations is fragmenting vendor business models while expanding total addressable use cases across infrastructure monitoring.
Growth Catalysts
- Copernicus Data Policy:ESA's open-access Sentinel-1 archive eliminates imagery procurement costs for public-sector deformation monitoring programs, accelerating adoption in municipal subsidence tracking.
- Mining Sector Automation:Pit wall stability monitoring via InSAR reduces manual surveyor deployment in hazardous open-cut operations, particularly in Australia's iron ore districts and Chile's copper belts.
- Liquefied Natural Gas Infrastructure:Coastal LNG terminal operators deploy persistent-scatterer interferometry to detect settlement in reclaimed land foundations, driven by FERC-mandated integrity management protocols.
Market Restraints
- Atmospheric Phase Noise:Tropospheric water vapor variability corrupts C-band interferograms in tropical latitudes, forcing operators toward L-band alternatives with higher unit costs per square kilometer processed.
- Specialized Talent Scarcity:SAR signal processing expertise concentrates within aerospace engineering programs at TU Delft, Politecnico di Milano, and select French grandes écoles, creating recruitment bottlenecks for commercial analytics firms.
- GPS Augmentation Dependency:Precise orbit determination requires continuous ground station networks; gaps in Antarctic or oceanic coverage degrade coherence over remote pipeline corridors.
Strategic Opportunities
- Indonesia's Urban Corridor Expansion:Jakarta's northern reclamation zones and Bandung's volcanic basin settlements lack dense leveling networks, creating first-mover advantages for satellite-based subsidence services.
- AI-Assisted Phase Unwrapping:Deep learning architectures trained on synthetic interferograms reduce processing latency from days to hours, enabling near-real-time landslide early warning systems.
- Carbon Capture and Storage Integrity:EPA Class VI well permit applications now require surface deformation monitoring plans, opening federal compliance contracts for InSAR verification of CO2 plume containment.
Industry Challenges
- Interoperability with Legacy Survey Networks:Mining engineers accustomed to total station measurements distrust millimetric satellite claims without ground-truthing campaigns, slowing contract conversions.
- Certification Timeline for Aviation Applications:FAA's remote sensing licensing framework lacks specific InSAR data quality standards, delaying UAV-borne SAR deployment for airport runway settlement monitoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Interferometric Synthetic Aperture Radar (Insar) Market |
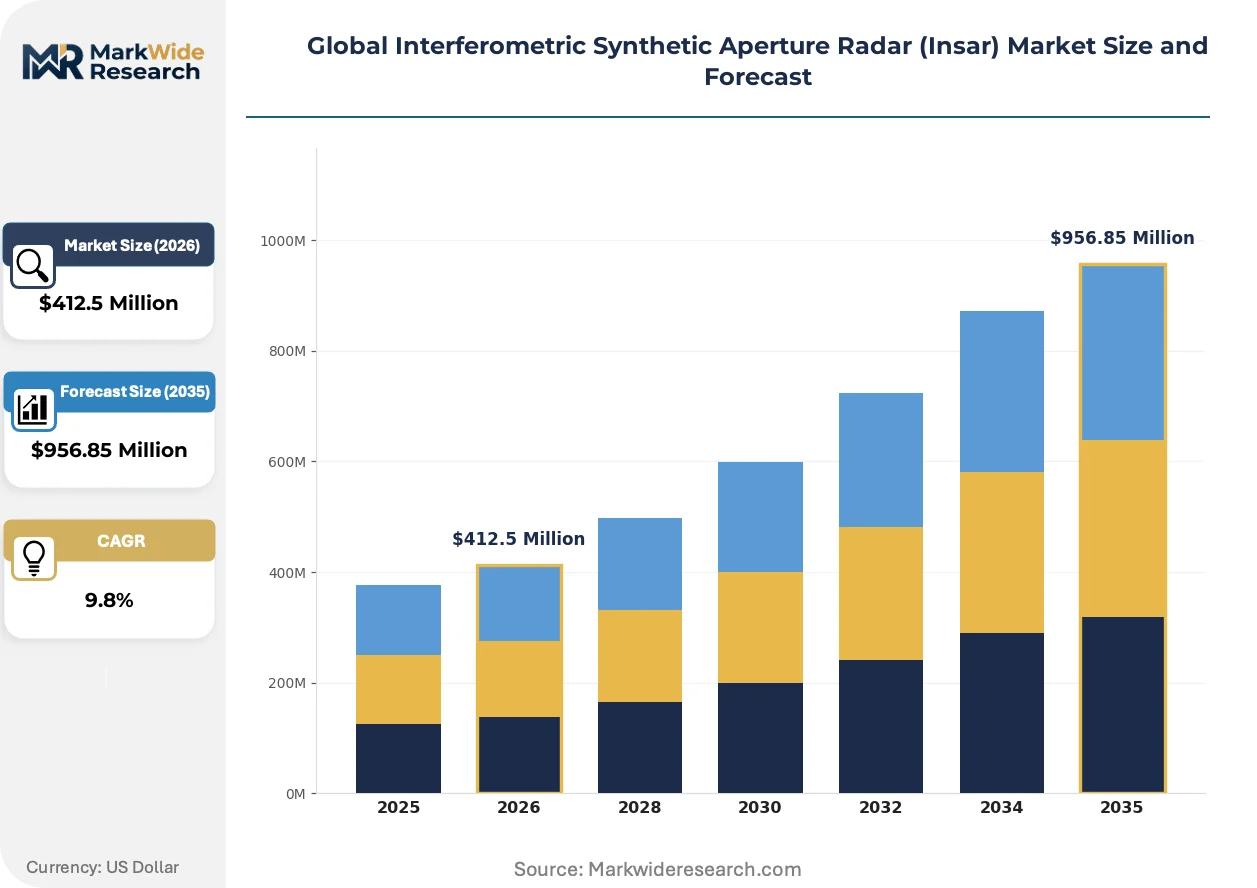
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $956.85 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Single-Baseline, Repeat-Pass, Persistent Scatterer, Differential, Tomographic, Polarimetric Application: Earthquake Monitoring, Land Subsidence Detection, Volcanology, Glacier Movement, Urban Planning, Agriculture Monitoring Deployment: Satellite-Based, Airborne Platforms, Ground-Based, Unmanned Aerial Vehicles, Balloons End User: Government Agencies, Research Institutions, Environmental Consultancies, Defense Organizations, Infrastructure Developers |
| Companies Covered | Raytheon Technologies, Lockheed Martin Corporation, Northrop Grumman Corporation, Airbus Defence and Space, Thales, MDA, ICEYE, Capella Space, CGG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Interferometric Synthetic Aperture Radar (Insar) Market Shifts & Advancements
Multi-constellation fusion is collapsing the historical trade-off between revisit frequency and spatial resolution, enabling deformation alerts that previously required dedicated tasking contracts.
Synthetic aperture radar tomography is unifying vertical structure retrieval with traditional surface displacement measurement. Forestry managers in Finland and Sweden now extract canopy height profiles alongside ground subsidence data from single acquisition stacks. This capability is compressing the addressable market for airborne LiDAR campaigns in boreal biomass estimation.
Japan's METI has embedded InSAR requirements into national disaster management roadmaps following the 2024 Noto Peninsula earthquake response failures. Municipal governments must now maintain pre-event SAR archives for rapid post-disaster damage assessment. Prefecture-level procurement contracts are consolidating around vendors offering guaranteed 24-hour interferogram delivery.
Engineering consultancies are unbundling deformation monitoring from traditional geotechnical investigation packages. Rio Tinto and Vale now contract satellite analytics separately from drilling programs, treating InSAR as a subscription utility rather than project-specific deliverable. This pattern is most advanced in Western Australia's Pilbara region where mine site density supports shared infrastructure cost amortization.
Global Interferometric Synthetic Aperture Radar (Insar) Market Segmentation
InSAR procurement decisions hinge on which regulatory frameworks apply to each deployment mode and end-use. Certification requirements from the FAA, ESA data policies, and national Earth observation roadmaps segment buyer priorities across technology tiers.
Technology:
FAA remote sensing licensing governs airborne differential and tomographic systems, while ESA's Copernicus framework subsidizes satellite-based persistent scatterer processing without procurement certification.
- Persistent Scatterer:Millimetric precision measurement relies on stable radar reflectors across urban infrastructure and bedrock outcrops. German lignite mining regions and Jakarta's northern reclamation zones command sustained public investment for subsidence verification. ESA's open-access Sentinel-1 archive eliminates imagery costs for this processing tier.
- Tomographic:Vertical structure retrieval unifies canopy height profiling with surface displacement in single acquisition stacks. Forestry managers in Finland and Sweden compress addressable demand for airborne LiDAR campaigns in boreal biomass estimation. METI's disaster management roadmaps now mandate pre-event SAR archives enabling rapid post-earthquake response.
- Single-Baseline:Basic interferometric comparison between two SAR acquisitions suits rapid assessment campaigns.
- Repeat-Pass:Sequential orbital revisit patterns enable deformation tracking without dedicated constellation tasking.
- Differential:Atmospheric noise removal techniques enhance measurement reliability in tropical latitudes.
- Polarimetric:Multi-polarization scattering analysis extends applications into agricultural biomass and soil moisture mapping.
Persistent Scatterer sits at the top of the volume ranking, with Tomographic climbing the fastest.
Application:
Cost tiering separates municipal subsidence programs using subsidized Sentinel-1 data from premium glacier monitoring requiring dedicated tasking contracts.
- Land Subsidence Detection:Coastal LNG terminal operators deploy persistent-scatterer interferometry to detect settlement in reclaimed land foundations. FERC-mandated integrity management protocols drive procurement in US Gulf Coast facilities. Australia's iron ore districts and Chile's copper belts reduce manual surveyor deployment through pit wall stability automation.
- Urban Planning:Municipal governments lacking dense leveling networks adopt satellite-based monitoring for corridor stability assessment. Bandung's volcanic basin settlements and Jakarta's reclamation zones create first-mover advantages for deformation services. Japan's prefecture-level contracts now consolidate around 24-hour interferogram delivery guarantees.
- Earthquake Monitoring:Rapid post-disaster damage assessment requires pre-event archive maintenance under national roadmaps.
- Volcanology:Magma chamber inflation tracking demands specialized L-band alternatives in tropical atmospheric conditions.
- Glacier Movement:Ice velocity measurement supports hydrological modeling and sea-level rise projections.
- Agriculture Monitoring:Crop health and soil moisture retrieval extends InSAR into precision farming workflows.
Land Subsidence Detection commands the largest procurement volumes, with Urban Planning gaining share fastest.
Deployment:
Customer type fragmentation positions government agencies for satellite-based contracts while environmental consultancies capture UAV-borne site-specific campaigns.
- Satellite-Based:Orbital persistence and coverage scalability anchor the value chain through constellations including Sentinel-1 and commercial SAR providers. ESA's Copernicus program accelerates data availability for public-sector deformation programs. Defense and intelligence contracts attach to high-margin proprietary constellation access.
- Unmanned Aerial Vehicles:Site-specific high-resolution campaigns represent the fastest-expanding segment for infrastructure developers and mining operators. FAA's remote sensing licensing framework lacks specific InSAR data quality standards, delaying airport runway settlement monitoring applications. Rio Tinto and Vale now contract satellite analytics as subscription utilities separate from drilling programs.
- Airborne Platforms:Manned aircraft missions bridge resolution and coverage gaps for regional assessment programs.
- Ground-Based:Terrestrial SAR systems enable continuous monitoring of critical slope stability.
- Balloons:Stratospheric platforms offer persistent station-keeping for localized observation campaigns.
Satellite-Based deployment dominates absolute volumes, with Unmanned Aerial Vehicles expanding most quickly.
End User:
Supply concentration in aerospace engineering programs at TU Delft and Politecnico di Milano creates recruitment bottlenecks affecting service delivery to commercial analytics firms.
- Government Agencies:Dominant end-user spending concentrates in municipal subsidence tracking and national disaster management procurement. Germany's sustained public investment for lignite mining regions and urban corridor stability assessment anchors European demand. METI's embedding of InSAR requirements into national roadmaps mandates prefecture-level contract consolidation.
- Environmental Consultancies:Climate-risk disclosure mandates tighten procurement from this segment as engineering consultancies unbundle deformation monitoring from traditional geotechnical investigation packages. Western Australia's Pilbara region supports shared infrastructure cost amortization across mine site density. AI-assisted phase unwrapping reduces processing latency for near-real-time landslide early warning systems.
- Research Institutions:Academic programs advance SAR signal processing expertise and algorithm development.
- Defense Organizations:Intelligence and surveillance applications attach to proprietary constellation tasking models.
- Infrastructure Developers:Linear asset monitoring for pipelines and transportation corridors drives recurring contract structures.
Government Agencies sit at the top of the volume ranking, with Environmental Consultancies climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAR signal processing expertise concentrates within aerospace engineering programs at TU Delft, Politecnico di Milano, and select French grandes écoles, creating recruitment bottlenecks that shape regional competitive dynamics.
Germany
Lignite mining regions in North Rhine-Westphalia and Brandenburg drive sustained public investment for subsidence verification. ESA's Copernicus framework subsidizes baseline SAR imagery procurement for municipal programs. Urban corridor stability assessment in the Rhine-Ruhr metropolitan area commands recurring government contracts.
United States
Coastal LNG terminal operators along the Gulf Coast deploy persistent-scatterer interferometry for settlement detection in reclaimed land foundations. FERC-mandated integrity management protocols drive procurement at export facilities. The FAA's remote sensing licensing framework governs commercial orbital operations for domestic SAR providers.
Japan
Prefecture-level governments must now maintain pre-event SAR archives for rapid post-disaster damage assessment under METI's national Earth observation roadmaps. The 2024 Noto Peninsula earthquake response failures accelerated InSAR embedding into disaster management protocols. Municipal procurement contracts consolidate around vendors offering guaranteed 24-hour interferogram delivery.
Australia
Pit wall stability monitoring via InSAR reduces manual surveyor deployment in hazardous open-cut operations across Western Australia's Pilbara iron ore districts. Rio Tinto and Vale now contract satellite analytics as subscription utilities separate from drilling programs. Shared infrastructure cost amortization across dense mine site concentrations supports this utility model.
Indonesia
Jakarta's northern reclamation zones and Bandung's volcanic basin settlements lack dense leveling networks, creating first-mover advantages for satellite-based subsidence services. Tropical atmospheric conditions force operators toward L-band alternatives with higher unit costs per square kilometer processed. National urban corridor expansion programs lack established deformation monitoring baselines.
Global Interferometric Synthetic Aperture Radar (Insar) Market Competitive Landscape
Top-tier vendors anchor proprietary constellation operations, while mid-tier specialists compete through rapid-revisit capabilities and geophysical integration services. Defense contractors leverage classified SAR satellite access for high-margin intelligence contracts, while commercial analytics firms differentiate through processing speed and AI-assisted phase unwrapping. Strategic moves concentrate on multi-constellation data fusion partnerships and vertical integration into persistent-scatterer analytics workflows.
Within the defense-intelligence tier, Raytheon Technologies, Lockheed Martin Corporation, and Northrop Grumman Corporation exemplify constellation-anchored positioning through classified infrastructure access. These US-based contractors occupy positions where sovereign data requirements and national security procurement protocols create structural barriers to commercial competitors. Their market presence represents the premium segment where tasking priority and orbital persistence command substantial contract values.
| Leading Market Players |
|---|
| Raytheon Technologies |
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| Airbus Defence and Space |
| Thales |
| MDA |
| ICEYE |
| Capella Space |
| CGG |
| Others |
Supply & Pricing Matrix
Government procurement programs for subsidence monitoring anchor pricing power on the demand side, while supply concentration in aerospace engineering talent pools shapes vendor margin structures across persistent-scatterer and tomographic service tiers.
Pricing Analysis
Bundled project-based contracts dominate legacy relationships, yet unbundled subscription utilities are displacing them in Western Australia's Pilbara mining clusters. Pricing stratifies across premium persistent-scatterer analytics, standard repeat-pass processing, and economy-tier Sentinel-1 derivative products. Cost compression in standard-tier processing stems from ESA's open-access data policy eliminating imagery procurement fees. Environmental consultancies exhibit highest price sensitivity, while defense-intelligence buyers accept substantial premiums for proprietary constellation tasking priority.
Supply Chain Analysis
Direct-to-agency channels handle public-sector deformation programs, with value-added resellers penetrating environmental consultancy segments. SAR sensor manufacturing concentrates in France, Germany, and Finland through Airbus Defence and Space, Thales, and ICEYE operations. Processing workflows draw from specialized GPU clusters, atmospheric correction datasets, and precise orbit determination services. Single-source vulnerability in L-band sensor supply creates structural risk for tropical latitude operators. Distribution runs through geospatial analytics platforms and dedicated defense contracting vehicles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in AI-assisted processing automation and carbon capture verification workflows, where premium pricing attaches to federal compliance mandates rather than commodity imagery resale.
For Market Incumbents: Extend proprietary constellation persistence advantages into guaranteed 24-hour interferogram delivery contracts for Japanese prefecture-level disaster management procurement. Deepen upstream control over SAR signal processing talent pipelines through captive relationships with TU Delft and Politecnico di Milano programs. ICEYE's rapid-revisit capabilities represent the most credible substitution threat; counter through multi-constellation data fusion partnerships that collapse revisit-spatial resolution trade-offs. For New Entrants and Emerging Players: AI-assisted phase unwrapping architectures offer the most penetrable wedge for processing latency reduction from days to hours. Target Indonesia's urban corridor expansion where Jakarta's northern reclamation zones lack established deformation monitoring baselines and dense leveling networks. Lead with near-real-time landslide early warning systems as the go-to-market angle, leveraging subscription utility models proven in Western Australian mining clusters. For Investors and Strategic Acquirers: Defense contractors are the most active acquirer in this space, seeking proprietary SAR satellite access for intelligence contract anchoring. Long-term viability favors vertically integrated operators controlling both constellation assets and persistent-scatterer analytics workflows rather than pure-play processing services. Watch EPA Class VI well permit application volumes as the inflection indicator for carbon capture and storage integrity monitoring demand.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Constellation Data Fusion Partnership | Collapses historical revisit-frequency versus spatial-resolution trade-offs for deformation alerts. |
| AI-Assisted Phase Unwrapping Deployment | Reduces processing latency from days to hours for near-real-time landslide warning systems. |
| Carbon Capture Verification Service Launch | Captures EPA Class VI well permit compliance contracts for CO2 plume containment monitoring. |
| Prefecture-Level 24-Hour Delivery Guarantee | Consolidates Japanese municipal procurement around guaranteed interferogram response capabilities. |
| SAR Signal Processing Talent Pipeline Captive | Secures recruitment access through TU Delft and Politecnico di Milano aerospace engineering programs. |
Research Methodology
Direct dialogue with SAR satellite operators, geophysical analytics firm executives, mining sector geotechnical directors, and government Earth observation program managers grounded qualitative findings. Secondary validation drew from ESA Copernicus data policy documentation, FAA remote sensing licensing records, METI national roadmap publications, and FERC integrity management protocols. Bottom-up and top-down triangulation cross-checked vendor revenue estimates against public-sector procurement disclosures and constellation capacity disclosures.
Bottom-up modeling segmented volume and value across technology tiers, deployment modes, and end-user categories throughout the forecast period. Segmentation dimensions included persistent-scatterer versus tomographic processing, satellite-based versus unmanned aerial vehicle deployment, and government agency versus environmental consultancy demand. CAGRs were derived from weighted average growth assumptions across these segments, with inputs from Sentinel-1 data availability trajectories and commercial SAR constellation launch schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to atmospheric correction algorithm advances and sovereign data-access rule modifications. Periodic stress-testing of base assumptions is recommended, particularly regarding ESA Copernicus program continuity and FAA regulatory framework evolution for commercial remote-sensing licensing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
ISR
IFF System Market
ISR
Asia-Pacific C4ISR Market
ISR
Active Phased Array Radar (APAR) Market
ISR
Land Based C4ISR Market
ISR
Low Altitude Radar Market
ISR
Brazil C4ISR Market
ISR
Eastern Europe C4ISR Market
ISR
North America Airborne ISR Market
ISR
C5ISR Market
ISR
C4ISR Market
ISR
Air Based C4ISR Market
ISR
C6ISR Market
ISR
North America C5ISR Market
ISR
Saudi Arabia C4ISR Market
ISR
Japan C4ISR Market
ISR
Synthetic Aperture Radar (SAR) Market