
 Advanced Surface Movement Guidance and Control System (A-SMGCS) Market | 2026-2036
Advanced Surface Movement Guidance and Control System (A-SMGCS) Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Surface Movement Guidance and Control System (A-SMGCS) Market Analysis
Military installations are reorganizing procurement priorities toward dual-use A-SMGCS platforms that serve both civilian contingency and sovereign defense operations. Thales Group leverages its multilateration heritage to anchor European defense-adjacent contracts. Raytheon Technologies Corporation sustains North American radar integration leadership through captive sensor manufacturing. Saab AB specializes in cold-climate surface movement solutions, dominating Nordic military and joint-use airfields.
Advanced Surface Movement Guidance and Control System denotes an integrated airport ground traffic management architecture combining surveillance, routing, and guidance functions to prevent runway incursions and optimize taxiway throughput. The system typically fuses radar tracks, multilateration returns, and surface movement sensor feeds into a single correlated display operating at one-second update rates for high-velocity targets. Ground Surveillance System deployments lead current revenue pools, reflecting legacy radar replacement cycles at tier-one hubs. Multilateration technology represents the fastest-expanding segment, driven by its superior accuracy in non-line-of-sight terminal geometries where standalone radar suffers multipath degradation. Data Processing Unit demand concentrates in upgrade and retrofit Installation Type categories, as airports seek to preserve existing sensor infrastructure while layering modern fusion algorithms.
Eurocontrol SESAR standards, FAA NextGen surface requirements, and ICAO Annex 14 provisions collectively mandate performance-based surveillance minima that filter vendor eligibility by certified integration depth. The EU AI Act and national cybersecurity frameworks are adding algorithmic transparency requirements to data processing subsystems, reshaping procurement specifications. Stakeholders must monitor how emerging machine-learning track correlation methods align with evolving air navigation service provider certification protocols.
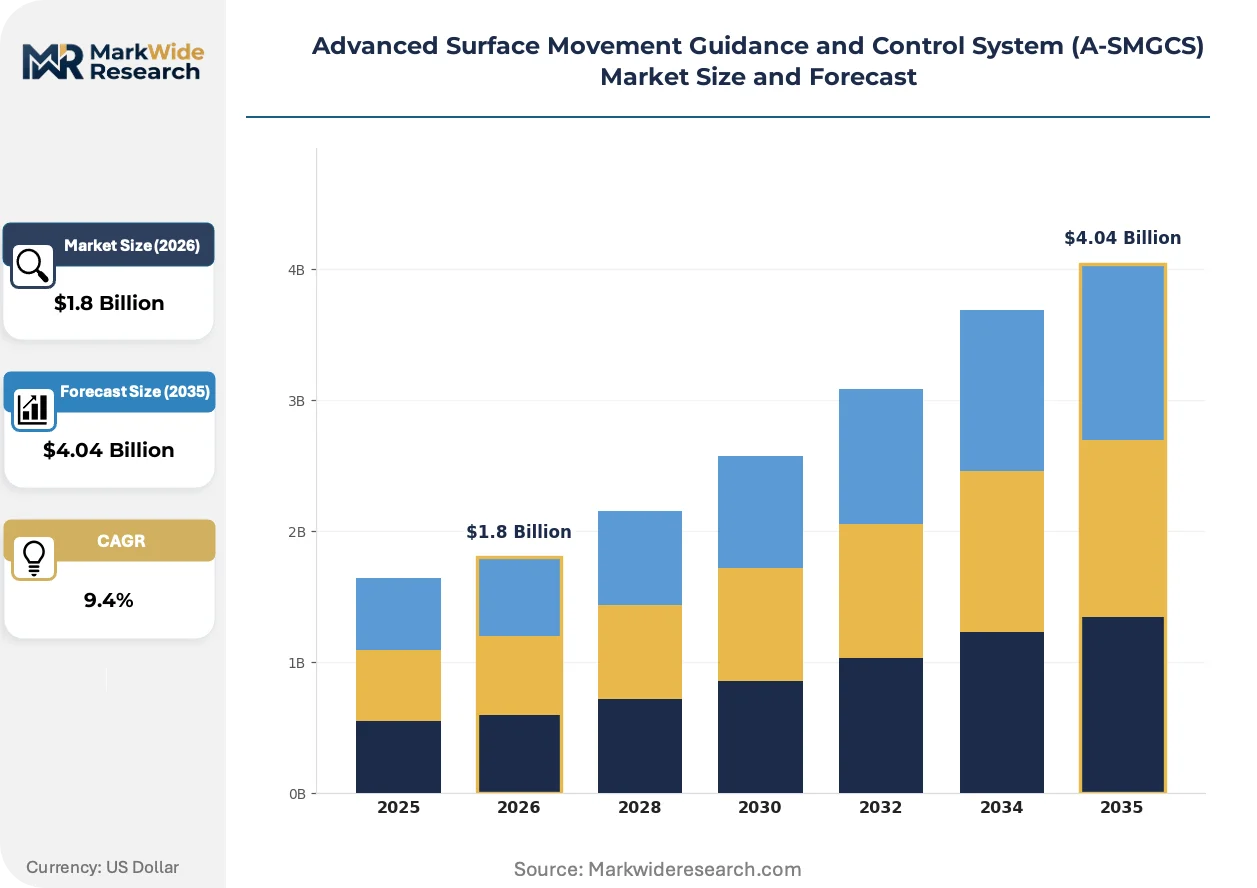
Market Dynamics
Eurocontrol's SESAR deployment mandates and FAA NextGen surface initiatives are compressing hardware refresh cycles at tier-one airports, forcing vendors to certify integrated surveillance platforms against performance-based minima that privilege multilateration accuracy over legacy radar architectures.
Growth Catalysts
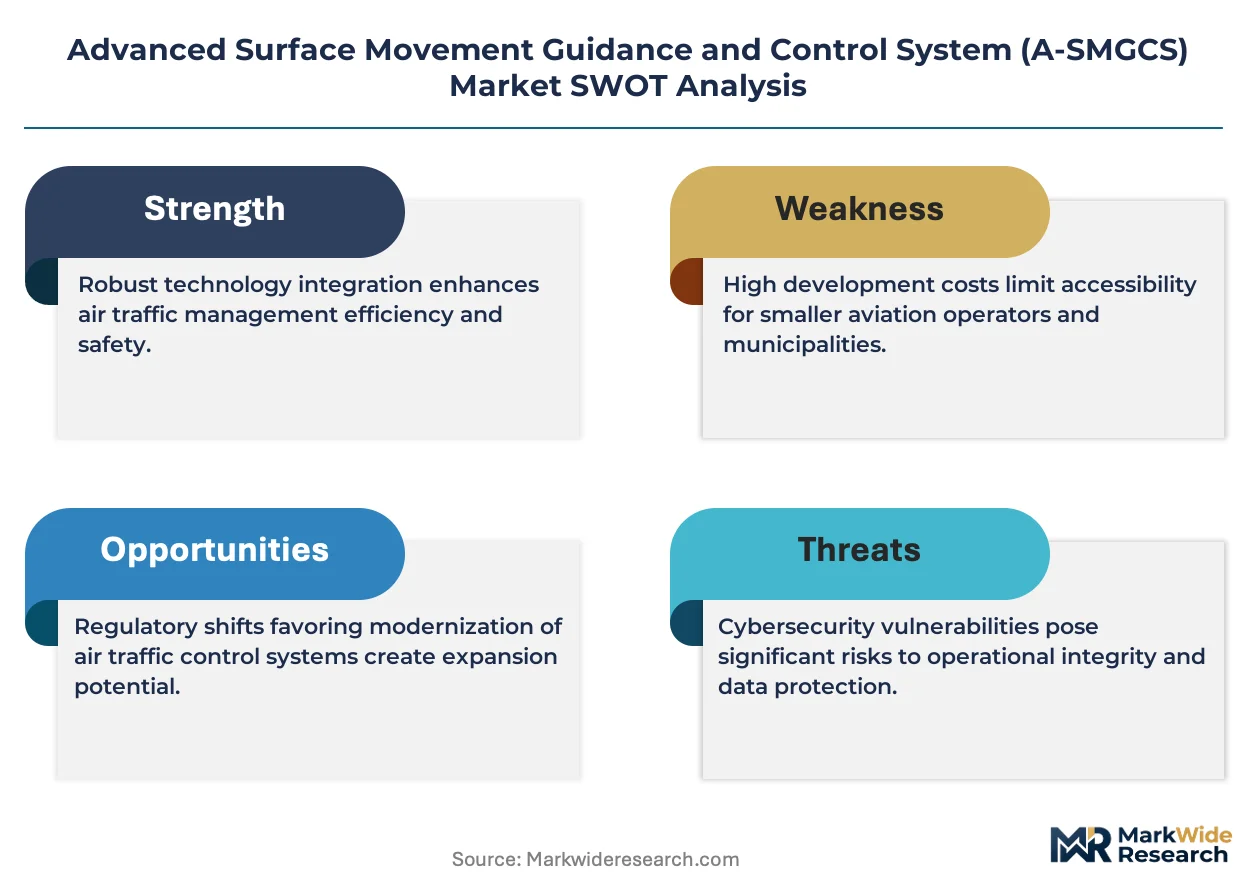
- SESAR Deployment Mandates:Eurocontrol's Single European Sky initiative requires certified A-SMGCS integration at high-density airports, creating procurement pull in Germany, France, and the Netherlands.
- Runway Incursion Prevention:ICAO Annex 14 provisions mandate one-second update rates for high-velocity surface targets, accelerating sensor fusion adoption.
- Multilateration Superiority:Non-line-of-sight terminal geometries at complex hub airports favor multilateration systems over standalone radar in high-multipath environments.
Market Restraints
- Certification Timeline Compression:EU AI Act algorithmic transparency requirements add validation layers to data processing subsystems, extending vendor qualification periods.
- Sensor Infrastructure Lock-in:Airports with recent radar investments face stranded asset risk when layering modern fusion algorithms atop legacy hardware.
- Cybersecurity Compliance Burden:National cybersecurity frameworks impose penetration testing and supply chain audit requirements that filter smaller integrators from competitive bidding.
Strategic Opportunities
- Dual-Use Military-Civilian Platforms:NATO airfields and joint-use installations seek unified A-SMGCS architectures serving sovereign defense and contingency civilian operations.
- Cold-Climate Specialization:Nordic and Canadian airports require ice-resistant sensor housings and heated multilateration units, creating niche vendor differentiation.
- Machine-Learning Track Correlation:Neural network-based target fusion offers accuracy gains that align with evolving air navigation service provider certification protocols.
Industry Challenges
- Multidisciplinary Integration Expertise:System integrators must combine radar engineering, software-defined radio, and air traffic control domain knowledge, creating talent scarcity in specialized labor markets.
- Legacy Display Compatibility:Controller working position upgrades must preserve ergonomic familiarity while introducing fused-track visualization, complicating human-factors certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Surface Movement Guidance and Control System (A-SMGCS) Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ground Surveillance System, Multi-Sensor Integration, Data Processing Unit, Control Center Technology: Radar, Automatic Dependent Surveillance, Multilateration, Surface Movement Sensors End User: Airports, Air Traffic Control Centers, Ground Handling Operators, Military Installations Installation Type: New Installation, Upgrade, Retrofit, Expansion |
| Companies Covered | Indra Sistemas S.A., Frequentist AG, Thales Group, Raytheon Technologies Corporation, Leonardo Spa, Honeywell International Inc., ADB SAFEGATE, Northrop Grumman Corporation, Saab AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Surface Movement Guidance and Control System (A-SMGCS) Market Emerging Trajectories
Sensor fusion architectures are actively displacing standalone surveillance modalities, while regulatory mandates restructure procurement specifications around algorithmic transparency and performance-based surveillance minima.
Multilateration technology is supplanting monostatic radar as the primary surveillance modality at complex terminal geometries. Frankfurt and Munich airports anchor European deployment, with Nordic military airfields adopting cold-hardened variants. The shift compresses vendor margins on legacy radar maintenance contracts while opening recurring revenue pools for fusion software licensing.
EU AI Act provisions are adding algorithmic transparency requirements to data processing subsystems, reshaping procurement specifications toward explainable track correlation methods. Vendors must document decision pathways for machine-learning fusion algorithms. Air navigation service providers in Germany and France are revising technical specifications to mandate interpretability documentation.
Airport procurement committees are consolidating vendor relationships around full-system integrators capable of delivering surveillance, routing, and guidance functions under unified performance guarantees. Tier-one hubs in the United States and Germany now favor single-contractor accountability over multi-vendor sensor assemblies. This concentration pressures specialized sensor manufacturers to embed within larger platform ecosystems or exit competitive segments.
Advanced Surface Movement Guidance and Control System (A-SMGCS) Market Segmentation
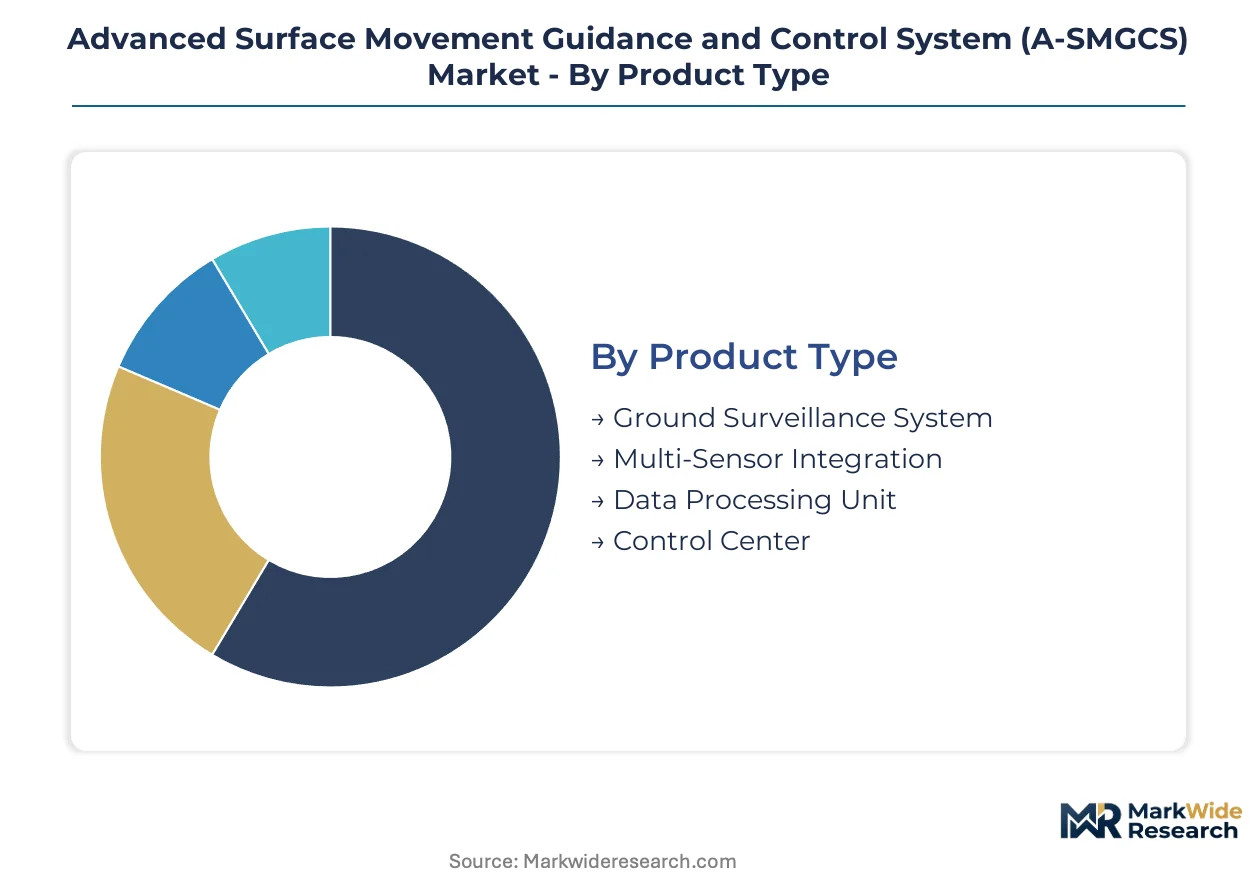
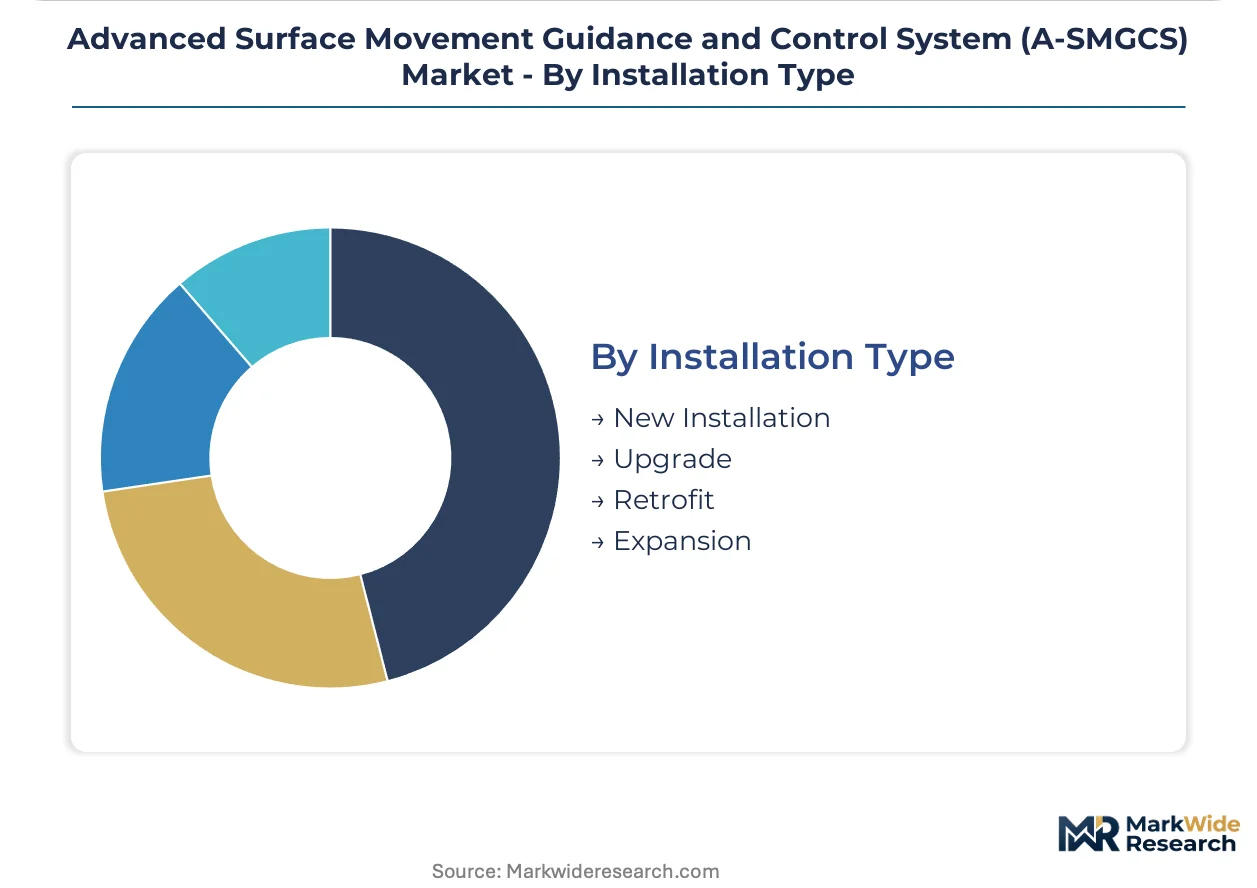
A-SMGCS procurement splits across four dimensions that determine integration complexity and certification pathways. Product type dictates hardware-software balance, while installation type reveals whether airports preserve legacy infrastructure or pursue greenfield deployments.
Product Type:
Regulatory differentiation across EU AI Act transparency mandates and FAA NextGen performance specifications shapes procurement eligibility for each subsystem tier.
- Ground Surveillance System:Legacy radar and multilateration arrays form the physical detection layer, typically operating at one-second update rates for high-velocity targets. Frankfurt and Munich anchor European deployment, driven by Eurocontrol SESAR mandates requiring certified integration depth at high-density hubs.
- Multi-Sensor Integration:Fusion platforms correlate radar tracks, multilateration returns, and surface movement sensor feeds into unified displays. Demand concentrates in tier-one airports seeking single-contractor accountability over fragmented sensor assemblies.
- Data Processing Unit:Algorithmic subsystems execute track correlation and conflict detection, now subject to EU AI Act explainability requirements. Upgrade and retrofit categories dominate as airports layer modern fusion algorithms atop existing infrastructure.
- Control Center:Controller working positions present fused-track visualization while preserving ergonomic familiarity for human-factors certification.
Ground Surveillance System handles the majority of throughput; Multi-Sensor Integration is the fastest mover on share.
Technology:
Cost tier differentiation separates capital-intensive radar deployments from software-defined multilateration architectures with lower infrastructure requirements.
- Radar:Monostatic and multistatic arrays provide primary surveillance in line-of-sight configurations. Tier-one hubs with recent radar investments face stranded asset risk when modernizing.
- Automatic Dependent Surveillance:GPS-derived position reporting reduces ground infrastructure density. Favored at secondary airports with limited sensor installation budgets.
- Multilateration:Time-difference-of-arrival processing achieves superior accuracy in non-line-of-sight terminal geometries where standalone radar suffers multipath degradation. Nordic military airfields adopt cold-hardened variants.
- Surface Movement Sensors:Active and passive infrared, lidar, and video analytics provide supplementary detection in low-visibility conditions.
Radar retains installed base dominance; Multilateration exhibits the steepest expansion trajectory.
End User:
Application differentiation separates sovereign defense requirements from commercial air navigation service provider specifications.
- Airports:Commercial hubs procure integrated surveillance-routing-guidance platforms under unified performance guarantees. German airports anchor European modernization.
- Air Traffic Control Centers:Area control facilities require A-SMGCS data feeds for terminal airspace integration.
- Ground Handling Operators:Ramp control towers at large hubs deploy simplified surveillance for apron management.
- Military Installations:NATO airfields and joint-use installations seek dual-use architectures serving sovereign defense and contingency civilian operations.
Airports command the largest procurement volume; Military Installations are climbing the fastest on budget priority.
Installation Type:
Customer type differentiation splits between greenfield airports with unconstrained infrastructure choices and established hubs managing legacy system transitions.
- New Installation:Greenfield airports deploy unified sensor-fusion architectures without legacy compatibility constraints.
- Upgrade:Partial subsystem replacement preserves existing infrastructure while enhancing specific performance parameters.
- Retrofit:Modern data processing units and fusion algorithms overlay legacy sensor networks, minimizing stranded asset exposure.
- Expansion:Capacity additions at growing hubs extend surveillance coverage to new taxiways or terminals.
Retrofit handles the majority of project volume; New Installation is gaining share fastest in emerging airport construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Air navigation service providers and defense ministries concentrate procurement authority at national levels, with tier-one hub airports driving sensor modernization cycles. Certification requirements from Eurocontrol, FAA, and ICAO filter vendor eligibility differently across jurisdictions.
Germany
Frankfurt and Munich airports anchor European A-SMGCS deployment through Eurocontrol SESAR mandates requiring certified multilateration integration. The country's national aviation regulator enforces algorithmic transparency standards aligned with EU AI Act provisions for data processing subsystems. Bavaria hosts cold-climate testing facilities where Nordic military specifications are validated before NATO-wide procurement.
United States
FAA NextGen surface initiatives compress hardware refresh cycles at Atlanta, Chicago O'Hare, and Dallas-Fort Worth hubs. The agency mandates performance-based surveillance minima that privilege sensor fusion accuracy over standalone radar architectures. Raytheon Technologies leverages captive manufacturing in Arizona and Massachusetts to sustain North American integration leadership.
France
Paris Charles de Gaulle and Orly airports drive demand for controller working position upgrades preserving ergonomic familiarity. The country's national cybersecurity agency imposes penetration testing requirements on data processing subsystems. Thales Group anchors European defense-adjacent contracts from its multilateration heritage base near Paris.
Sweden
Nordic military and joint-use airfields prioritize ice-resistant sensor housings and heated multilateration units for Arctic operations. The Swedish Transport Agency coordinates certification with Finnish and Norwegian regulators for cross-border standardization. Saab AB dominates regional cold-climate surface movement solutions from its Gothenburg engineering cluster.
United Kingdom
Heathrow and Gatwick procurement committees favor single-contractor accountability over fragmented sensor assemblies. The Civil Aviation Authority aligns technical specifications with Eurocontrol SESAR timelines post-Brexit transitional arrangements. Leonardo Spa secures defense-adjacent positioning through historic radar integration contracts with RAF installations.
Advanced Surface Movement Guidance and Control System (A-SMGCS) Market Vendor Landscape
Player mix skews toward full-system integrators capable of unified surveillance-routing-guidance delivery, with specialized sensor manufacturers facing consolidation pressure. Tier-one hubs in Germany and the United States now demand single-contractor performance guarantees. Two strategic archetypes dominate: European multilateration heritage firms and North American radar-captive manufacturers. Competitive moves center on algorithmic certification speed and cold-climate specialization licensing.
Within the European heritage tier, Thales Group and Saab AB exemplify divergent specialization vectors—Thales anchoring continental defense-adjacent contracts, Saab occupying Nordic cold-climate niches. Raytheon Technologies Corporation represents North American radar-captive integration, leveraging in-house sensor manufacturing for FAA certification timelines. Indra Sistemas S.A. and Leonardo Spa sit within Mediterranean-European positioning, while Frequentist AG and ADB SAFEGATE exemplify mid-tier specialists seeking embedding within larger platform ecosystems. Honeywell International Inc. and Northrop Grumman Corporation occupy diversified conglomerate positions where A-SMGCS serves adjacent aviation electronics portfolios.
| Leading Market Players |
|---|
| Indra Sistemas S.A. |
| Frequentist AG |
| Thales Group |
| Raytheon Technologies Corporation |
| Leonardo Spa |
| Honeywell International Inc. |
| ADB SAFEGATE |
| Northrop Grumman Corporation |
| Saab AB |
| Others |
Supply Flow & Price Mechanics
Scale economies in multilateration sensor manufacturing concentrate production among German and Swedish engineering clusters, compressing unit costs for tier-one airport deployments while establishing price floors for cold-climate specialized variants. Frankfurt and Munich procurement committees leverage this concentration through multi-year framework agreements that index hardware costs to Eurocontrol certification timelines.
Pricing Analysis
Cost-plus contracts with Eurocontrol SESAR indexation dominate tier-one airport procurement, locking in margins for certified integrators while exposing specialized sensor manufacturers to margin compression. Three-tier pricing structure across certified-integration, standard-compliance, and basic-surveillance levels separates Thales and Saab premium positioning from mid-tier European specialists. Pricing pressure stems from EU AI Act validation layers extending vendor qualification periods. Commercial airports exhibit highest price sensitivity due to stranded asset risk from recent radar investments, while NATO military installations prioritize performance guarantees over unit cost.
Supply Chain Analysis
Germany, Sweden, and the United States anchor A-SMGCS component manufacturing, with Bavaria hosting cold-climate testing facilities and Arizona sustaining Raytheon's captive sensor production. Gallium nitride semiconductors, precision timing modules, and heated sensor housings draw from Taiwan, Switzerland, and Nordic specialist suppliers. Single-source vulnerability concentrates in precision multilateration receivers where Saab and Thales maintain proprietary designs. Distribution runs through national air navigation service provider procurement frameworks rather than open commercial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among tier-one hub procurement committees that demand single-contractor accountability, fragmenting the vendor base and compressing margins for specialized sensor manufacturers unable to embed within integrated platforms.
For Market Incumbents: Fortify algorithmic certification speed against EU AI Act transparency mandates by embedding explainable track correlation methods within data processing subsystems. Deepen backward integration into precision timing module supply to reduce exposure to Swiss single-source dependencies. Anchor European defense-adjacent positioning through NATO cold-climate specification licensing before Nordic competitors consolidate Arctic procurement. For New Entrants and Emerging Players: Lead with machine-learning fusion algorithms targeting retrofit installation categories where airports seek modern correlation methods atop legacy radar infrastructure. White-space concentrates in Canadian and Nordic military airfields requiring ice-resistant sensor housings outside Saab's incumbent positioning. Go-to-market should route through national cybersecurity framework pre-qualification to bypass tier-one hub procurement committee barriers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among full-system integrators delivering surveillance-routing-guidance under unified performance guarantees rather than fragmented sensor assemblies. Long-term viability across the projection horizon rests on certification depth against evolving Eurocontrol and FAA performance minima. Target acquisition archetype: mid-tier multilateration specialists with NATO cold-climate validation seeking platform embedding. The signal to watch is Eurocontrol SESAR timeline acceleration compressing vendor qualification windows.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Certification Investment | EU AI Act explainability mandates filter vendor eligibility at German and French hubs. |
| Cold-Climate Specialization Licensing | NATO Arctic specifications create defendable niches beyond generic surveillance platforms. |
| Backward Integration into Timing Modules | Captive supply of precision components reduces Swiss single-source vulnerability. |
| Retrofit Installation Targeting | Upgrade categories dominate project volume while preserving legacy infrastructure. |
| Dual-Use Military-Civilian Platform Development | NATO joint-use installations seek unified architectures serving sovereign defense operations. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with air traffic control center directors, airport procurement committee leads, ANS provider technical specification managers, and defense ministry acquisition officers; and secondary validation against Eurocontrol SESAR deployment databases, FAA NextGen surface initiative filings, ICAO Annex 14 regulatory repositories, and national cybersecurity framework documentation. Bottom-up segmentation modeling triangulated against top-down market sizing from certified integration deployment tracking.
Across the analysis window, forecasts applied analytical frameworks spanning product type, technology modality, end-user archetype, and installation category dimensions. CAGRs derived from certified platform deployment velocity indexed to Eurocontrol and FAA mandate timelines. Industry-specific inputs incorporated multilateration accuracy benchmarks against legacy radar performance minima and machine-learning track correlation certification pathway assumptions.
The analysis sits within stated boundaries; outcomes outside Eurocontrol SESAR deployment adherence or FAA NextGen surface initiative acceleration would require recalibration. Forecasts reflect assumptions around algorithmic transparency validation timelines and NATO cold-climate specification adoption rates. Recalibration cycles align with material shifts in EU AI Act enforcement patterns and national cybersecurity framework penetration testing requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Navigation & Surveillance
Military GNSS Anti-Jamming Systems Market
Communication Navigation & Surveillance
Autonomous Navigation System Market
Communication Navigation & Surveillance
Military Antenna Market
Communication Navigation & Surveillance
Spain Satellite Communications Market
Communication Navigation & Surveillance
Defense Communication System Market
Communication Navigation & Surveillance
Surface Radars Market
Communication Navigation & Surveillance
Integrated 3D Radar Market
Communication Navigation & Surveillance
Man-Portable Military Communication Systems Market
Communication Navigation & Surveillance
Navigation Satellite System Technology Market
Communication Navigation & Surveillance
Industrial Inertial Systems Market
Communication Navigation & Surveillance
Latin America Inertial Systems Market
Communication Navigation & Surveillance
Inertial Systems Market
Communication Navigation & Surveillance
Global X-Band Radar Market
Communication Navigation & Surveillance
UK Autonomous Navigation Market
Communication Navigation & Surveillance
Global Antenna Market
Communication Navigation & Surveillance
Weapon Locating Radar Market