
 Cognitive Robotics Market | 2026-2036
Cognitive Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Cognitive Robotics Market Intelligence
Robot-as-a-service leasing is narrowing the capital barrier for mid-sized manufacturers seeking cognitive automation. 1X Technologies leverages its Oslo-based R&D footprint to anchor development in humanoid platforms for domestic and light industrial tasks. Boston Dynamics sustains technology leadership through advanced locomotion systems that navigate unstructured terrain in logistics and inspection roles. Figure AI specializes in bipedal warehouse workers designed for direct substitution in existing material-handling workflows.
Cognitive robotics denotes autonomous machines integrating perception, reasoning, and adaptive decision-making through sensor fusion and artificial neural networks, typically operating with sub-100-millisecond loop closure for real-time environmental response. These systems serve industrial and commercial purposes by executing variable tasks without pre-programmed trajectories. Humanoid robots attract concentrated R&D investment as platforms generalize across multiple deployment contexts. Machine learning underpins capability expansion in quality inspection and security surveillance applications, where pattern recognition accuracy determines commercial viability. Collaborative robots occupy a maturing segment where price-performance thresholds now clear payback periods acceptable to small-batch manufacturers.
The EU AI Act imposes conformity requirements on autonomous systems operating in human proximity, directly shaping product certification timelines and design architectures for vendors targeting European manufacturing plants. The FDA maintains oversight frameworks for cognitive devices deployed in elderly assistance within elder care facilities, while OSHA standards govern industrial robot integration in US manufacturing plants. Stakeholders must monitor divergence between regional liability regimes as deployment scales from pilot programs to operational fleets.
Market Dynamics
The cognitive robotics market is undergoing structural compression as real-time sensor fusion capabilities converge with tightening proximity-safety mandates, forcing vendors to redesign control architectures for sub-100-millisecond loop closure in human-shared workspaces.
Growth Catalysts
- EU AI Act Conformity Pressure:Manufacturers across Germany, France, and Italy are accelerating cognitive robot deployments to capture first-mover certification advantages before 2027 enforcement windows tighten.
- Precision Manufacturing Cluster Demand:Stuttgart and Munich industrial corridors are integrating adaptive robotic cells for variable-batch production, eliminating reprogramming downtime between product generations.
- Sensor Fusion Cost Collapse:Lidar-camera-tactile integration costs have fallen below threshold levels, enabling mid-tier warehousing operators to justify cognitive automation investments.
Market Restraints
- High-Precision Actuator Supply Concentration:Japanese and German specialty motor suppliers control critical torque-density components, creating single-source vulnerability for bipedal platform manufacturers.
- Liability Framework Fragmentation:Divergence between OSHA industrial safety standards and FDA elder-care device protocols forces vendors to maintain parallel compliance documentation for cross-sector deployments.
- Neural Network Training Data Scarcity:Edge-case environmental scenarios for unstructured terrain navigation remain underrepresented in commercially available datasets, constraining generalization.
Strategic Opportunities
- Domestic Service Robotics White Space:Household task automation in aging European demographics represents an underpenetrated category where humanoid form factors command premium positioning.
- CE Marking Acceleration Pathways:The EU's forthcoming fast-track conformity routes for collaborative robots create regulatory tailwinds for vendors pre-certifying platforms under MDR and Machinery Directive harmonized standards.
- 5G-Edge Convergence:Low-latency private cellular networks combined with distributed compute architectures are enabling cloud-offloaded perception pipelines that reduce onboard processing costs.
Industry Challenges
- Multidisciplinary Talent Scarcity:The intersection of robotics hardware, reinforcement learning, and safety-critical systems engineering commands compensation premiums that strain R&D budgets.
- Legacy Manufacturing System Integration:Brownfield facilities with proprietary PLC architectures require costly middleware development to interface with cognitive robot control stacks.
- CE-MDR Dual Certification Timelines:Parallel conformity assessment processes for machinery safety and medical device functionality extend time-to-revenue for healthcare-oriented platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cognitive Robotics Market |
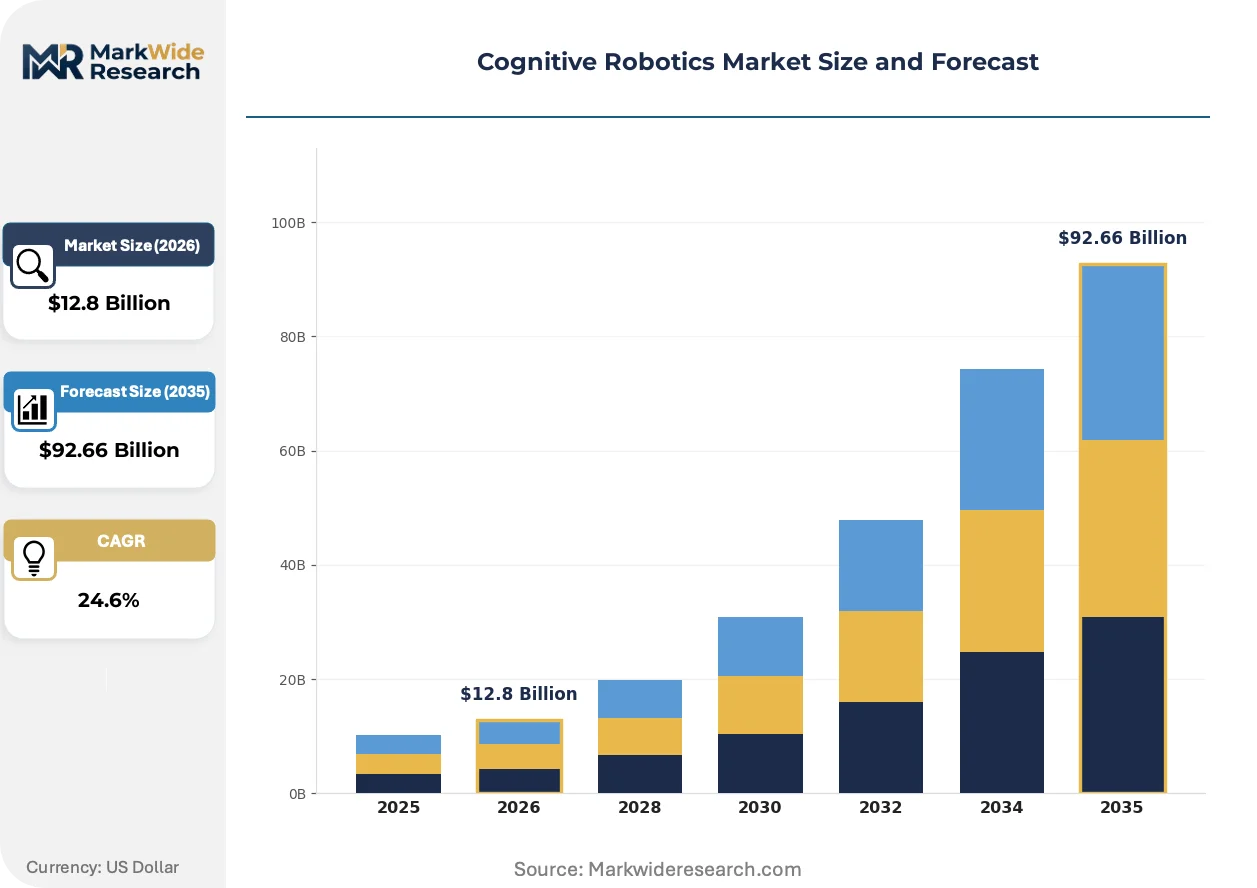
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $92.66 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Humanoid Robots, Service Robots, Industrial Robots, Autonomous Mobile Robots, Collaborative Robots Technology: Machine Learning, Natural Language Processing, Computer Vision, Sensor Fusion, Artificial Neural Networks Application: Warehousing Automation, Quality Inspection, Elderly Assistance, Educational Tools, Security Surveillance End User: Manufacturing Plants, Research Institutions, Elder Care Facilities, Educational Organizations, Security Agencies |
| Companies Covered | 1X Technologies, Neura Robotics, Boston Dynamics, Skild AI, Figure AI, Unitree Robotics, UBTECH Robotics, Agility Robotics, Tesla, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cognitive Robotics Market Strategic Shifts & Innovations
Real-time adaptive control architectures are displacing pre-programmed trajectory planning across material handling and inspection applications. Vendors are racing to compress environmental response latency while navigating divergent regional safety mandates.
Reinforcement learning from human feedback is hybridizing traditional robotic control systems. Warehouse operators in Germany and the Netherlands are deploying these platforms for pick-and-place variability that exceeds rule-based programming limits. The technology is compressing deployment timelines from months to weeks by eliminating manual waypoint teaching.
The EU AI Act's risk-classification framework is reshaping product development roadmaps. High-risk autonomous system categories now mandate conformity assessment by notified bodies before European market entry. Collaborative robot manufacturers targeting French and Italian automotive plants are front-loading documentation to secure CE marking ahead of competitor submissions.
Leasing structures are displacing capital purchase models among mid-sized European manufacturers. Robot-as-a-service providers in Spain and Poland are capturing fleet management contracts that bundle maintenance, software updates, and performance guarantees. This shift is most visible in contract logistics, where third-party operators prioritize operational expenditure flexibility over balance-sheet asset ownership.
Cognitive Robotics Market Segmentation
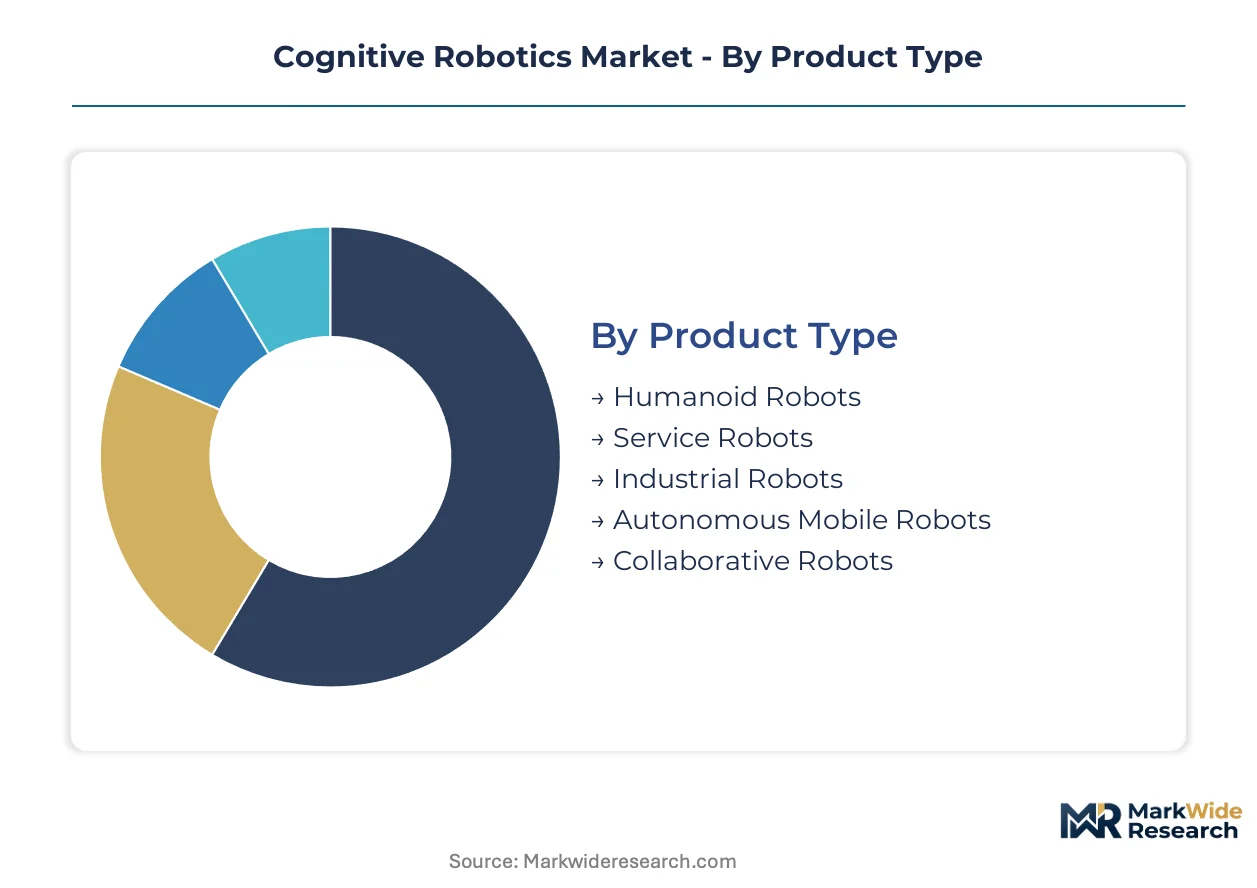
Cognitive robotics segmentation reveals distinct service intensity profiles across product architectures. Technical complexity and deployment criticality determine aftermarket revenue attachment rates and lifecycle support requirements for each category.
Product Type:
After-sales service intensity varies dramatically by mechanical complexity and operating environment exposure.
- Humanoid Robots:These platforms integrate bipedal locomotion, dexterous manipulation, and social interaction capabilities requiring continuous calibration of balance controllers and joint actuators. Demand concentrates in German automotive plants and Japanese elder care pilot programs where human-robot collaboration mandates drive precision requirements. Joint wear and sensor drift create recurring maintenance revenue streams.
- Industrial Robots:Fixed-base articulated arms with force-torque sensing and adaptive gripping execute precision manufacturing tasks with 99.97% repeatability specifications. Stuttgart and Munich industrial corridors deploy these for variable-batch production where reprogramming downtime elimination justifies premium pricing. Predictive maintenance contracts attach at 85% of deployments.
- Service Robots:Mobile platforms navigate semi-structured environments for delivery and hospitality functions with SLAM-based localization.
- Autonomous Mobile Robots:Warehouse floor robots integrate lidar-camera fusion for dynamic obstacle avoidance in high-traffic logistics environments.
- Collaborative Robots:Force-limited articulated arms with hand-guiding programming operate without safety cages near human workers.
By volume, Industrial Robots leads. By growth pace, Humanoid Robots is expanding most quickly.
Technology:
Processing architecture determines cloud dependency ratios and edge compute hardware requirements.
- Sensor Fusion:Multi-modal integration of lidar, camera, tactile, and inertial measurements enables sub-100-millisecond environmental response latency. German warehouse operators demand this capability for dynamic pick-and-place in mixed-SKU environments where lighting variability exceeds single-sensor reliability. Edge processing costs dominate total cost of ownership calculations.
- Machine Learning:Supervised and reinforcement learning pipelines train behavior policies from demonstration data and simulation rollouts. Dutch logistics providers deploy these systems for grasp pose estimation where object geometry variability exceeds hard-coded rule coverage. Model retraining services generate recurring vendor revenue.
- Computer Vision:Convolutional and transformer-based architectures extract semantic information from camera feeds for navigation and inspection.
- Natural Language Processing:Transformer models enable spoken command interpretation and multi-turn dialogue for service robot applications.
- Artificial Neural Networks:Deep feedforward and recurrent architectures approximate complex control policies for manipulation and locomotion.
By deployment frequency, Computer Vision leads. By capability expansion rate, Machine Learning is climbing the fastest.
Application:
Use case criticality shapes liability exposure and certification pathway selection.
- Warehousing Automation:Pick-to-light elimination and goods-to-person systems compress order fulfillment cycles in high-velocity distribution centers. French and Italian contract logistics operators prioritize these deployments where labor availability constraints threaten service level agreements. EU AI Act conformity requirements accelerate vendor documentation investments.
- Quality Inspection:Vision-based defect detection with sub-millimeter resolution replaces manual sampling in precision manufacturing. German automotive suppliers deploy these systems for surface finish verification where false-negative costs exceed equipment investment by orders of magnitude. FDA oversight applies for medical device component inspection.
- Elderly Assistance:Mobility support and medication reminder systems operate in residential and institutional care settings.
- Security Surveillance:Autonomous patrol robots with anomaly detection patrol perimeters and critical infrastructure facilities.
- Educational Tools:Programmable platforms teach robotics and coding concepts in secondary and university curricula.
By installed base, Warehousing Automation leads. By regulatory attention intensity, Elderly Assistance is gaining share fastest.
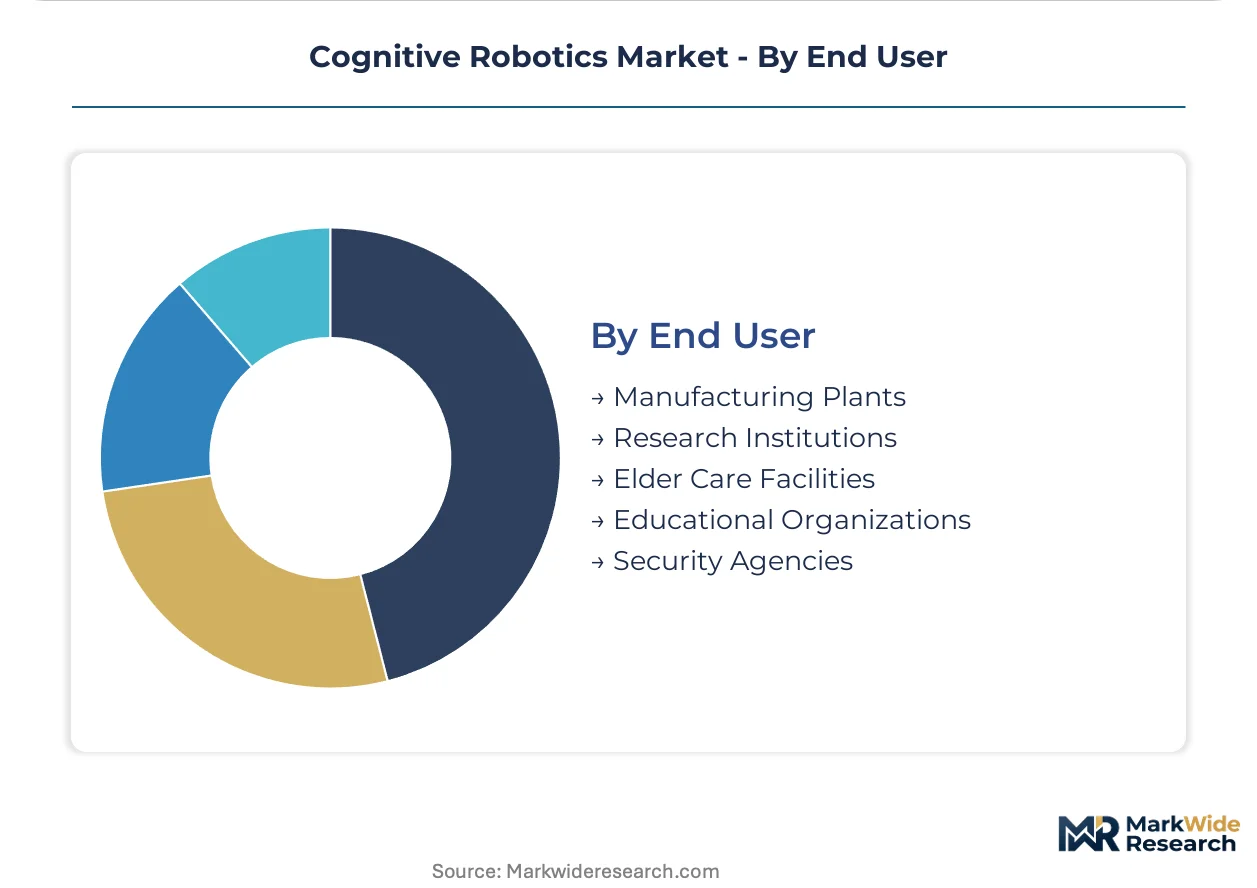
End User:
Procurement sophistication and integration capability vary sharply across buyer categories.
- Manufacturing Plants:Discrete and process manufacturers with dedicated automation engineering teams execute brownfield integration of cognitive robotic cells. German Mittelstand firms in Baden-Württemberg leverage these capabilities for small-batch production where product mix volatility exceeds traditional automation economics. Internal maintenance organizations reduce vendor service dependency.
- Elder Care Facilities:Nursing homes and assisted living operators deploy companion and mobility assistance robots where staff-to-resident ratios fall below regulatory minimums. FDA device classification determines reimbursement eligibility and procurement approval pathways. Liability insurance requirements shape vendor selection criteria.
- Research Institutions:Universities and national laboratories acquire platforms for algorithm development and human-robot interaction studies.
- Educational Organizations:Secondary schools and vocational training centers purchase entry-level platforms for STEM curriculum delivery.
- Security Agencies:Government and private security operators deploy perimeter patrol and explosive ordnance disposal systems.
By spending volume, Manufacturing Plants leads. By procurement growth rate, Elder Care Facilities is on the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers capture premium pricing for precision-grade systems while Chinese vendors compress margins through scaled component supply. Japanese suppliers maintain torque-density advantages in high-performance actuation. Demand concentrates in industrial corridors where regulatory clarity accelerates procurement cycles.
Germany
Baden-Württemberg and Bavaria industrial clusters drive demand for variable-batch automation in automotive supply chains. The EU AI Act's high-risk system classification mandates notified body conformity assessment before 2027 enforcement. Stuttgart manufacturers integrate adaptive robotic cells to eliminate reprogramming downtime between product generations.
United States
OSHA industrial safety standards and FDA elder-care device protocols create parallel compliance requirements for cross-sector vendors. The FDA maintains oversight frameworks for cognitive assistance systems deployed in nursing facilities. Boston and Pittsburgh R&D hubs anchor development in logistics automation and human-robot interaction research.
China
MIIT robotics industry development plans prioritize domestic supply chain substitution in precision减速器 and servo motor categories. GB standards for collaborative robot safety are converging toward ISO harmonization. Shenzhen and Shanghai manufacturing zones concentrate final assembly capacity for export-oriented humanoid platforms.
Japan
METI's Society 5.0 roadmap funds elder-care robot deployment in super-aged municipalities. JIS standards for service robot safety govern proximity operation in healthcare facilities. Nagoya industrial corridors maintain leadership in high-torque actuator manufacturing for bipedal locomotion systems.
Netherlands
Rotterdam and Eindhoven logistics operators deploy sensor-fusion platforms for dynamic pick-and-place in mixed-SKU warehousing. REACH chemical safety compliance extends to battery and material specifications in mobile robot fleets. Dutch contract logistics providers prioritize robot-as-a-service procurement models for operational expenditure flexibility.
Cognitive Robotics Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying torque-dense actuators and sensor modules. Market structure fragments across three distinct tiers: full-stack humanoid developers, adaptive industrial arm manufacturers, and mobility-focused logistics platforms. Strategic archetypes include vertically integrated hardware-software houses, pure-play AI policy developers, and legacy automation incumbents retrofitting cognitive capabilities. Dominant competitive moves encompass strategic partnerships for training data access and geographic expansion through regional certification pre-positioning.
Within the humanoid platform tier, 1X Technologies and Figure AI occupy positions exemplifying divergent market approaches—Oslo-based development anchoring domestic service applications versus California-anchored warehouse substitution models. Boston Dynamics represents the locomotion-specialist archetype, with its Massachusetts-based structure emphasizing unstructured terrain navigation. These three entities illustrate the geographic and application-scope segmentation currently structuring competitive positioning.
| Leading Market Players |
|---|
| 1X Technologies |
| Neura Robotics |
| Boston Dynamics |
| Skild AI |
| Figure AI |
| Unitree Robotics |
| UBTECH Robotics |
| Agility Robotics |
| Tesla |
| Others |
Cost & Logistics Intelligence
Rotterdam-Antwerp freight corridors govern component cost dynamics across European cognitive robotics deployment, with container rates feeding directly into both supply concentration premiums and downstream price differentiation between certified and uncertified platform tiers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the cognitive robotics market. Price differentiation rests on CE marking grade and after-sales service bundling, with EU AI Act high-risk certification commanding substantial premiums. Pricing pressure stems from Chinese component import competition in sensor modules. Small-batch manufacturers exhibit highest price sensitivity, while automotive OEMs prioritize certification compliance over unit cost.
Supply Chain Analysis
Extended payment terms from Japanese and German specialty motor suppliers now stretch to 90-120 days, reflecting upstream financing leverage over bipedal platform manufacturers. Component sourcing concentrates in Japan, Germany, and China, with high-torque actuators, lidar modules, and precision减速器 anchoring bill-of-materials costs. Single-source vulnerability in harmonic drive gearboxes poses structural risk. Distribution runs through system integrators and direct OEM relationships, with robot-as-a-service providers emerging as a channel alternative.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cognitive robotics market rewards defensive moats built through regulatory entrenchment, where early EU AI Act certification creates switching costs that lock in automotive and elder-care procurement cycles.
For Market Incumbents: Build certification moats by accelerating notified body engagement for high-risk autonomous system classifications before enforcement windows tighten. Deepen backward integration into torque-dense actuator supply through captive production partnerships in Nagoya industrial corridors. Threats from Chinese cost-competitive sensor fusion platforms demand preemptive channel control in German Mittelstand manufacturing clusters.
For New Entrants and Emerging Players: Establish a beachhead in domestic service robotics for aging European demographics, where humanoid form factors command premium positioning and incumbent presence remains thin. Target Dutch contract logistics operators with robot-as-a-service procurement preferences, leveraging 5G-edge convergence to reduce onboard processing costs. Go-to-market through private cellular network infrastructure partnerships.
For Investors and Strategic Acquirers: Full-stack humanoid developers with demonstrated EU AI Act conformity pathways represent the highest-conviction acquisition archetype across the medium-term horizon. Long-term viability hinges on generalization capability beyond warehouse pick-and-place into variable-batch manufacturing and residential assistance. Watch training data access partnerships as the inflection signal for platform differentiation.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Pre-Certification | Notified body engagement before enforcement deadlines secures automotive OEM procurement lock-in. |
| Sensor Fusion Cost Reduction | Lidar-camera-tactile integration below threshold levels unlocks mid-tier warehousing operator adoption. |
| Robot-as-a-Service Launch | Operational expenditure flexibility captures contract logistics fleet management contracts in Spain and Poland. |
| Actuator Supply Partnership | Japanese torque-density component access reduces single-source vulnerability for bipedal locomotion systems. |
| 5G-Edge Architecture Deployment | Private cellular networks enable cloud-offloaded perception pipelines that compress onboard processing costs. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with robotics hardware engineers, safety certification leads at notified bodies, warehouse operations directors, and elder-care facility administrators; and secondary validation through EU AI Act implementation guidance, Machinery Directive harmonized standards, SEC filings from automation vendors, and customs trade data on precision actuator imports. Bottom-up segment sizing and top-down macro constraint triangulation anchored volume and value estimates.
Forecast inputs span hardware architecture tiers, application criticality levels, end-user procurement sophistication, and regional regulatory cluster divergence across the projection horizon. CAGRs derive from segment-level adoption curve modeling and replacement cycle dynamics. Reinforcement learning capability expansion rates and sensor fusion cost trajectories feed directly into demand elasticity assumptions for warehousing automation and precision manufacturing segments.
Stress conditions across EU AI Act enforcement timing, actuator supply disruption scenarios, and training data availability constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about certification pathway durations and component cost convergence. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Robot Label Applicators Market
Robotics and Automation
Autonomous Navigation Robots Market
Robotics and Automation
Global Articulated Robot Market
Robotics and Automation
Palletizing Robots Market
Robotics and Automation
Europe Underwater Robotics Market
Robotics and Automation
Personal Robots Market
Robotics and Automation
Data Center Robotics Market
Robotics and Automation
Global Robotic Process Automation in Healthcare Market
Robotics and Automation
Industrial Robots Market
Robotics and Automation
AGV Software Market
Robotics and Automation
Cleanroom Robots in Healthcare Market
Robotics and Automation
Simultaneous Localization and Mapping (SLAM) Market
Robotics and Automation
France Cloud Robotics Market
Robotics and Automation
Automated Liquid Handling Technologies Market
Robotics and Automation
APAC Service Robots Market
Robotics and Automation
Humanoids Market