
 Global Robotic Process Automation in Healthcare Market | 2026-2036
Global Robotic Process Automation in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Global Robotic Process Automation in Healthcare Market Foresight
Cloud-native orchestration is tilting RPA architecture toward API-first automation that bypasses legacy screen-scraping. UiPath Inc leverages attended automation bots to anchor its position in hospital front-office workflows. Automation Anywhere Inc sustains competitive pressure through unattended automation clusters deployed across diagnostic laboratory networks. International Business Machines Corporation differentiates by embedding Watson cognitive layers into hybrid automation stacks for clinical documentation.
Robotic Process Automation in Healthcare deploys software bots to execute rule-based tasks across electronic health record systems, revenue cycle platforms, and insurance portals, typically operating through user interface manipulation or direct API integration with HL7 FHIR interoperability standards. Its primary commercial purpose is to reduce administrative labor costs while accelerating claims throughput and minimizing coding errors that trigger payer denials. Unattended automation dominates volume deployment in billing and coding operations where bots process high-volume transactions without human intervention. Cognitive automation represents the fastest-expanding margin pool as natural language processing engines parse unstructured clinical notes for automated documentation. Cloud-based deployment models are displacing on-premise installations among ambulatory surgical centers seeking lower capital barriers.
The FDA regulates clinical decision support software embedded within RPA workflows through its software-as-a-medical-device framework, while the EU AI Act imposes conformity requirements on automated systems processing patient data across European hospitals. HIPAA in the United States and GDPR in Europe constrain bot access to protected health information, forcing vendors to architect role-based access controls and audit trails into every deployment. Stakeholders must monitor how emerging AI liability frameworks redefine accountability when autonomous bots generate erroneous clinical codes or scheduling decisions.
Market Dynamics
The FDA's software-as-a-medical-device framework and the EU AI Act are forcing RPA vendors to reengineer validation protocols for clinical automation, compressing deployment timelines while elevating compliance costs across hospital networks.
Growth Catalysts
- HL7 FHIR interoperability mandates:Healthcare systems in the United States are accelerating API-first bot deployments to meet federal data exchange requirements, creating standardized integration pathways.
- Revenue cycle digitization:German hospital networks are automating claims verification to reduce administrative labor costs and minimize payer denial rates.
- Cognitive NLP engines:Natural language processing technologies are parsing unstructured clinical notes for automated documentation, expanding automation scope beyond rule-based tasks.
Market Restraints
- Validation cost inflation:FDA software-as-a-medical-device compliance is requiring extensive clinical evidence packages, elevating upfront deployment costs for diagnostic automation workflows.
- Technical debt accumulation:Legacy EHR systems lacking modern API layers force continued reliance on brittle screen-scraping architectures, limiting bot reliability.
- Concentrated vendor dependency:Cloud-native orchestration platforms are consolidating around hyperscaler infrastructure, creating single-point-of-failure risks for hospital IT departments.
Strategic Opportunities
- Japan's aging provider workforce:Hospital administrative staffing shortages are creating urgent demand for unattended automation in patient scheduling and billing operations.
- EU AI Act conformity services:European hospitals require third-party validation support for automated patient data processing systems, opening consulting revenue streams.
- Diagnostic laboratory networks:Unattended automation clusters are penetrating high-volume specimen processing and results reporting workflows across integrated delivery systems.
Industry Challenges
- Clinical informatics talent scarcity:Healthcare organizations lack sufficient staff trained in both HL7 FHIR standards and bot configuration, slowing implementation velocity.
- Legacy EHR integration complexity:Proprietary data formats in entrenched hospital information systems require custom middleware development, extending project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Robotic Process Automation in Healthcare Market |
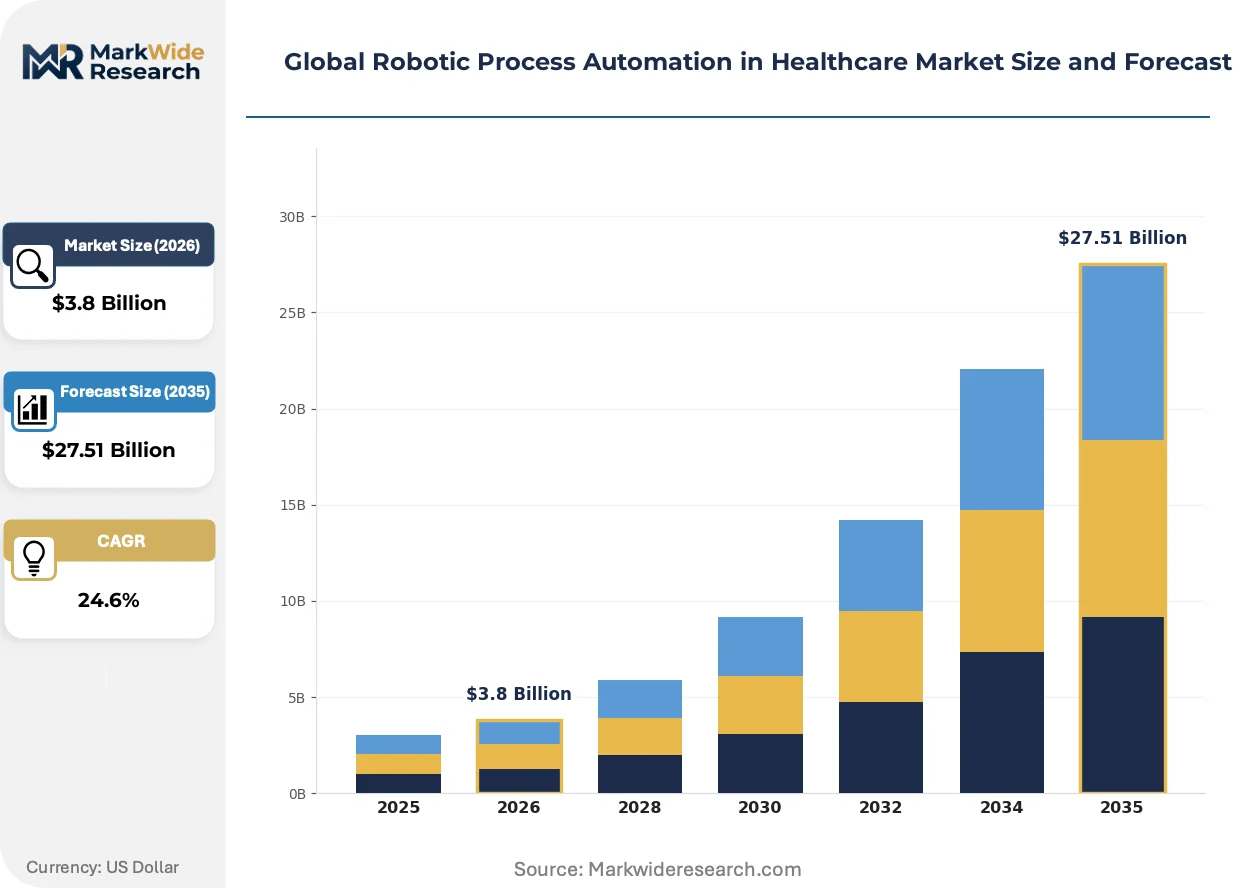
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $27.51 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Attended Automation, Unattended Automation, Hybrid Automation, Cognitive Automation Application: Claims Processing, Patient Scheduling, Billing & Coding, Clinical Documentation End User: Hospitals, Diagnostic Laboratories, Ambulatory Surgical Centers, Insurance Providers Deployment: On-Premise, Cloud-Based, Hybrid Models, Hosted Solutions |
| Companies Covered | UiPath Inc, Automation Anywhere Inc, Blue Prism Group, International Business Machines Corporation, NICE Ltd, Kofax Inc, Pegasystems Inc, Appian Corp, WorkFusion Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Robotic Process Automation in Healthcare Market Shifts & Advancements
Cloud-native orchestration architectures are displacing on-premise bot deployments, while regulatory frameworks on both sides of the Atlantic are redefining validation requirements for clinical automation tools.
API-first automation platforms are digitizing healthcare revenue cycle operations by replacing screen-scraping bots with direct HL7 FHIR integrations. Ambulatory surgical centers in the United States are adopting these architectures fastest, driven by lower capital barriers and faster deployment cycles. This shift is digitizing claims throughput while reducing bot maintenance overhead and error rates in payer interactions.
The EU AI Act imposes conformity assessment requirements on automated systems processing patient data across European hospitals, mandating risk classification and audit trail documentation. Germany's hospital networks are investing heavily in compliance infrastructure to meet these obligations ahead of enforcement deadlines. Diagnostic laboratory automation workflows face the steepest compliance burden due to their direct impact on clinical decision-making.
Subscription-based RPA licensing is replacing perpetual software purchases among mid-sized hospital systems seeking operational flexibility. Value-added resellers and systems integrators are capturing margin by bundling bot deployment with ongoing managed services. Japan's regional hospital networks exhibit the strongest preference for this model, reflecting constrained IT capital budgets and staffing limitations.
Global Robotic Process Automation in Healthcare Market Segmentation
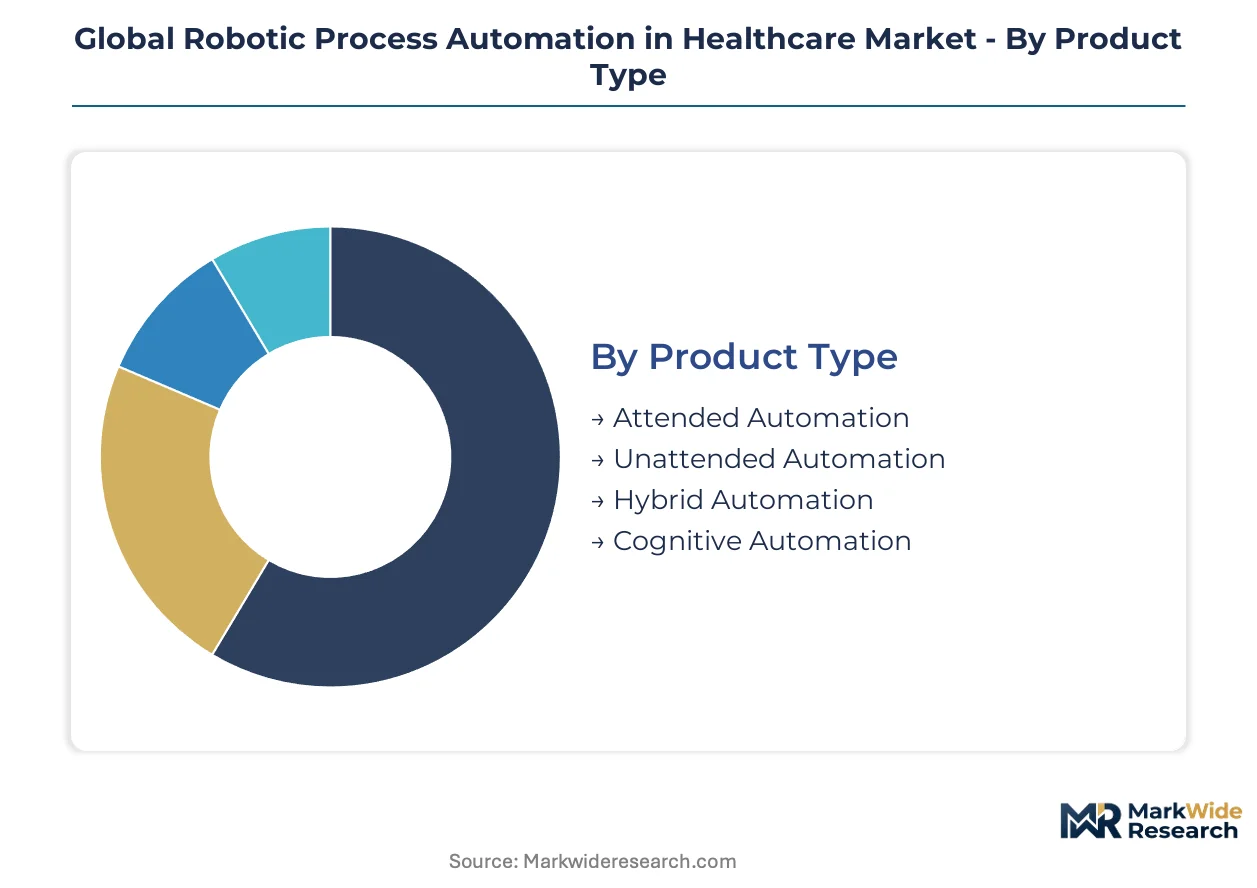
RPA vendors architect product portfolios around automation intensity levels and healthcare workflow complexity. Segmentation reveals where cognitive capabilities command premium pricing versus where unattended bots deliver volume economics.
Product Type:
Automation intensity tiers separate rule-based task execution from AI-augmented decision support, with cost structures scaling from attended desktop assistants to full cognitive stacks.
- Unattended Automation:Software bots execute high-volume transactions without human intervention, operating 24/7 across claims verification and eligibility checking workflows. German hospital networks deploy these clusters to compress revenue cycle timelines and reduce administrative headcount. This segment holds installed capacity.
- Cognitive Automation:Natural language processing engines parse unstructured clinical notes and auto-generate documentation codes. United States health systems facing clinician burnout invest here to reduce EHR data entry burden. This segment is rotating up the share rankings.
- Attended Automation:Desktop assistants trigger on clinician or staff action, guiding front-office scheduling and registration workflows in Japan's understaffed regional hospitals.
- Hybrid Automation:Architectures blend attended triggers with unattended back-end execution, common in ambulatory surgical centers requiring flexible human handoff points.
Unattended bots anchor current deployments. Cognitive layers are climbing fastest as NLP accuracy crosses clinical utility thresholds.
Application:
Workflow digitization priorities reflect where administrative labor costs most severely compress operating margins across health system types.
- Billing & Coding:Bots extract diagnosis and procedure codes from clinical documentation, submitting clean claims to payers with minimized denial risk. Diagnostic laboratories in the United States deploy these at scale to handle high-volume specimen-to-bill pipelines. This application commands the deepest current penetration.
- Clinical Documentation:Automated note generation and coding suggestion engines reduce physician administrative time. EU hospitals invest here to meet AI Act documentation requirements while addressing workforce shortages. This application is expanding most quickly.
- Claims Processing:End-to-end automation of eligibility verification, prior authorization, and denial management dominates insurance provider operations.
- Patient Scheduling:Self-service portal integration and automated appointment optimization address front-desk staffing gaps in Japan's aging provider workforce.
Billing & Coding retains volume leadership. Clinical Documentation is gaining share fastest as NLP engines mature.
End User:
Customer type segmentation tracks organizational scale, IT sophistication, and regulatory exposure as determinants of deployment architecture choice.
- Hospitals:Integrated delivery networks require enterprise orchestration platforms spanning revenue cycle, clinical documentation, and supply chain workflows. United States academic medical centers lead here, driven by HIPAA compliance infrastructure and capital availability. This end user category anchors vendor revenue.
- Diagnostic Laboratories:High-throughput specimen processing demands unattended automation clusters with direct LIS-EHR integration. German laboratory networks automate results reporting to meet EU AI Act audit trail mandates. This category is ascending fastest in deployment velocity.
- Ambulatory Surgical Centers:Cloud-native deployments predominate given limited on-premise IT staff and preference for subscription pricing models.
- Insurance Providers:Payer organizations automate claims adjudication and fraud detection, with regulatory pressure from CMS driving standardization.
Hospitals retain the deepest installed base. Diagnostic Laboratories are climbing the fastest as compliance automation becomes mandatory.
Deployment:
Infrastructure location choices trade data sovereignty and latency against capital efficiency and scalability in healthcare's regulated environment.
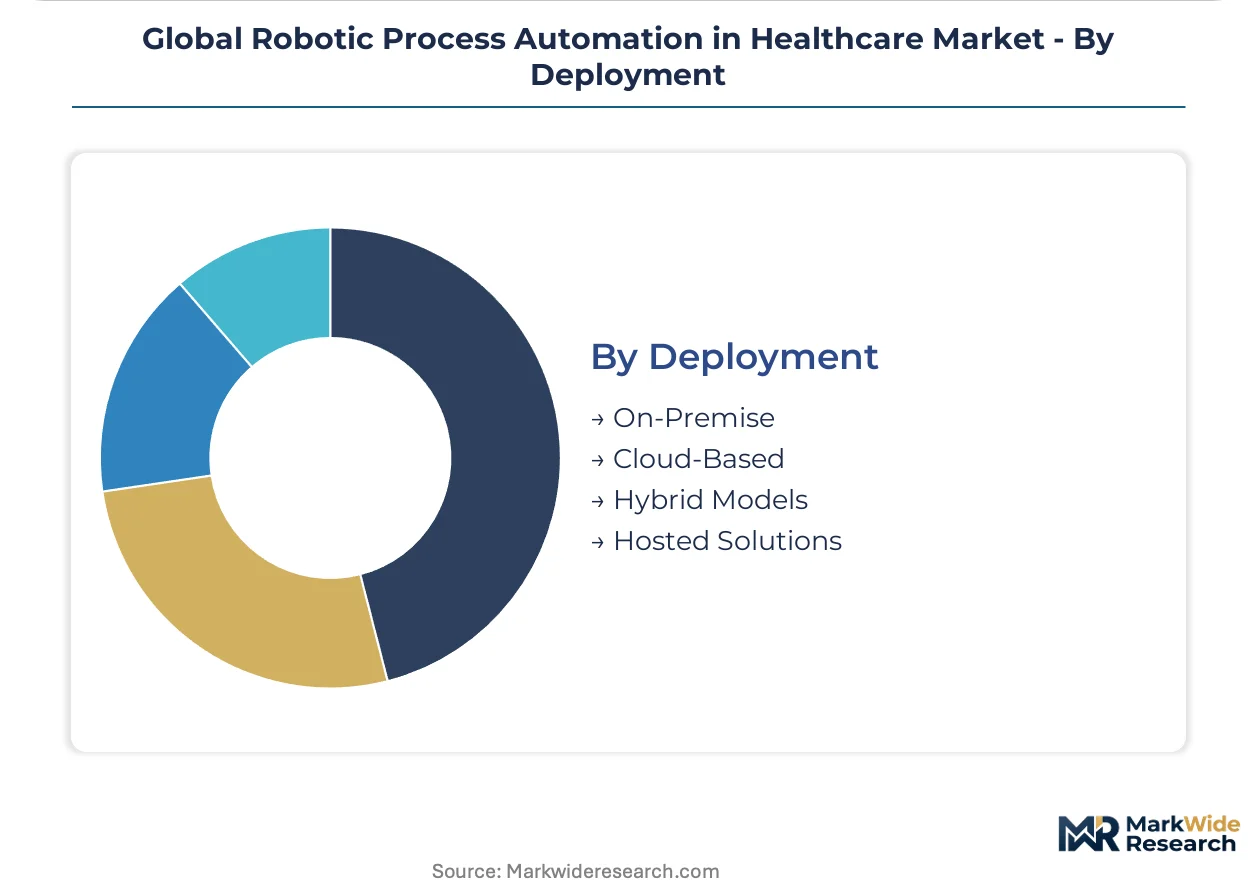
- Cloud-Based:Hyperscaler-hosted orchestration platforms reduce upfront capital requirements and accelerate deployment cycles. Ambulatory surgical centers in the United States adopt these fastest, prioritizing operational flexibility over data localization. This model is expanding most rapidly.
- On-Premise:Hospital data centers host bots processing protected health information under direct IT control, preferred by United States systems with extensive HIPAA compliance investments. This model retains the largest legacy footprint.
- Hybrid Models:Sensitive patient data remains on-premise while compute-intensive NLP processing shifts to cloud infrastructure, common in EU hospitals navigating GDPR constraints.
- Hosted Solutions:Managed service providers operate dedicated single-tenant cloud instances, addressing mid-sized hospital systems lacking internal DevOps capacity.
On-Premise retains legacy dominance. Cloud-Based is rotating up fastest as API-first architectures mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Healthcare systems in Germany export RPA validation expertise to United States hospital networks navigating FDA software-as-a-medical-device compliance. This transatlantic knowledge corridor accelerates deployment timelines while elevating audit standards.
United States
Academic medical centers in Boston and the Research Triangle deploy enterprise orchestration platforms spanning revenue cycle and clinical documentation workflows. HIPAA enforcement actions by the Office for Civil Rights compel role-based access controls in every bot deployment. The Cleveland Clinic and Mayo Clinic anchor concentrated demand in the Midwest.
Germany
Hospital networks in North Rhine-Westphalia automate claims verification to compress administrative labor costs and reduce payer denial rates. The EU AI Act imposes conformity assessment requirements on automated patient data processing systems. Berlin-based systems integrators capture consulting revenue from validation services.
Japan
Regional hospitals in Kansai and Kyushu deploy attended automation for patient scheduling amid acute administrative staffing shortages. METI guidelines on healthcare digitization accelerate procurement cycles for front-office bots. Osaka medical centers lead unattended automation adoption in diagnostic laboratory networks.
United Kingdom
NHS trusts in London and the Midlands integrate RPA into electronic health record systems to address clinician burnout and documentation burden. NHS England's digitization mandates create standardized procurement pathways for cognitive automation tools. Manchester's health innovation cluster anchors NLP engine development.
India
Diagnostic laboratory chains in Maharashtra and Karnataka deploy unattended bots for high-volume specimen processing and results reporting. CDSCO guidance on clinical decision support software shapes validation requirements for diagnostic automation. Hyderabad's health-tech corridor concentrates systems integration capacity.
Global Robotic Process Automation in Healthcare Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure consolidating around three tiers. Hyperscaler-backed platforms anchor the enterprise segment while mid-sized vendors capture ambulatory surgical center demand through subscription models. Strategic archetypes include full-stack orchestration providers, cognitive layer specialists, and vertical-focused healthcare integrators. M&A activity concentrates on NLP engine acquisitions and regional systems integrators.
Among publicly traded automation platforms, UiPath Inc and Automation Anywhere Inc exemplify the scale-driven tier, with the former representing attended automation archetypes and the latter anchoring unattended deployment clusters. International Business Machines Corporation occupies a hybrid position, embedding cognitive layers into enterprise healthcare stacks. These three entities collectively illustrate how vendor strategies diverge across automation intensity levels and customer scale segments.
| Leading Market Players |
|---|
| UiPath Inc |
| Automation Anywhere Inc |
| Blue Prism Group |
| International Business Machines Corporation |
| NICE Ltd |
| Kofax Inc |
| Pegasystems Inc |
| Appian Corp |
| WorkFusion Inc |
| Others |
Supply & Pricing Matrix
Hyperscaler cloud infrastructure concentration in the United States anchors downstream margin pools for RPA orchestration platforms, with AWS Azure and Google Cloud capacity scarcity feeding into subscription pricing power for healthcare automation vendors.
Pricing Analysis
Screen-scraping legacy bots trade at substantial discounts against API-first cognitive automation suites, with the technology-generation pricing gap widening as HL7 FHIR interoperability becomes mandatory. Three-tier pricing structure across premium cognitive stacks, standard unattended clusters, and economy attended licenses dominates vendor portfolios. Price differentiation rests on FDA software-as-a-medical-device certification tier and embedded NLP engine accuracy. Pricing pressure stems from subscription fatigue among mid-sized hospital systems. Ambulatory surgical centers exhibit highest price sensitivity; academic medical centers with dedicated IT capital budgets show lowest.
Supply Chain Analysis
Extended payment terms from diagnostic laboratory networks in Germany and Japan are reshaping vendor cash flow dynamics across the RPA value chain. Component sourcing concentrates on United States hyperscaler infrastructure, Indian systems integration labor pools, and German compliance consulting expertise. Raw material dependencies include GPU compute capacity, FHIR-compliant middleware licenses, and clinical NLP training datasets. Single-source vulnerability runs through AWS GovCloud for HIPAA-compliant deployments. Distribution feeds from direct enterprise sales teams into hospital procurement committees and GPO contract vehicles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Healthcare RPA is recovering from a cyclical trough as post-pandemic administrative staffing shortages force automation investment cycles. Hospital labor cost compression serves as the primary cyclical driver resetting procurement priorities.
For Market Incumbents: Insulate installed base revenue by embedding Watson-style cognitive layers into existing hospital contracts before API-first challengers displace screen-scraping architectures. Pursue backward integration into clinical NLP engine development to capture margin migrating from orchestration to intelligence. Prioritize FDA software-as-a-medical-device pre-certification to erect compliance barriers against unvalidated entrants. For New Entrants and Emerging Players: Japan's regional hospital administrative staffing crisis represents the most penetrable entry point for attended automation suites targeting front-office workflows. EU AI Act conformity services for German diagnostic laboratories offer consulting-led beachhead opportunities. Pursue channel partnerships with Berlin-based systems integrators already embedded in hospital validation processes. For Investors and Strategic Acquirers: Capital is best deployed toward clinical NLP engine specialists with proven FHIR integration capabilities and existing FDA submission track records. Long-term viability hinges on cognitive automation's displacement of rule-based bots across clinical documentation workflows. Monitor HL7 FHIR mandate enforcement velocity as the critical inflection signal for API-first platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-a-Medical-Device Pre-Certification | Accelerates hospital sales cycles by preempting validation bottlenecks in diagnostic automation workflows. |
| HL7 FHIR API-First Platform Migration | Replaces brittle screen-scraping with direct EHR integration, reducing maintenance overhead for United States health systems. |
| Clinical NLP Engine Acquisition | Captures margin migrating from orchestration layers to cognitive documentation automation in academic medical centers. |
| EU AI Act Conformity Service Launch | Opens recurring revenue streams from German hospital networks facing mandatory audit trail requirements. |
| Japan Regional Hospital Channel Partnership | Addresses acute administrative staffing shortages through localized attended automation deployment support. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital CIOs, RPA platform product managers, clinical informaticists, and healthcare GPO contracts managers. Secondary validation drew from FDA software-as-a-medical-device guidance documents, CMS Medicare claims processing data, EU AI Act regulatory filings, and hospital procurement database extracts. Bottom-up deployment counts across United States Germany and Japan health systems were triangulated against top-down vendor revenue segmentation.
Calibration against historical automation adoption curves in revenue cycle and clinical documentation applications anchored the projection framework across the analysis window. Segmentation dimensions modeled include automation intensity tier, deployment architecture, end-user organization scale, and regional regulatory cluster. CAGRs were derived from S-curve penetration modeling calibrated to HL7 FHIR mandate implementation timelines and hospital labor cost inflation trajectories. NLP engine accuracy improvement curves and cloud infrastructure cost deflation served as industry-specific forecast inputs.
Practitioners should monitor FDA enforcement actions on clinical decision support software and EU AI Act conformity deadline adherence for early signals of demand acceleration or compliance-driven deployment delays. Forecasts reflect assumptions about regulatory stability, hyperscaler pricing continuity, and clinical NLP accuracy progression. Macroeconomic contraction affecting hospital capital budgets, regulatory deviation from current software-as-a-medical-device frameworks, or breakthrough generative AI disruption of documentation workflows would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Global Molecular Robotics Market
Robotics and Automation
Hospital Robots Market
Robotics and Automation
Automotive Robotics Market
Robotics and Automation
Southeast Asia Industrial and Service Robot Market
Robotics and Automation
Latin America Automated Guided Vehicle (AGV) Market
Robotics and Automation
Delta Robots Market
Robotics and Automation
Lab Robotics Market
Robotics and Automation
United States Agricultural Robots Market
Robotics and Automation
Medical Service Robots Market
Robotics and Automation
Smart Curtain Robot Market
Robotics and Automation
Gantry (Cartesian) Robot Market
Robotics and Automation
South Korea Cloud Robotics Market
Robotics and Automation
Logistics Robots Market
Robotics and Automation
Robotics Actuators Market
Robotics and Automation
Robot End-Effector Market
Robotics and Automation
United Kingdom Cloud Robotics Market