
 Simultaneous Localization and Mapping (SLAM) Market | 2026-2036
Simultaneous Localization and Mapping (SLAM) Market Size, Share, and Industry Trends Forecast 2026-2036
Simultaneous Localization and Mapping (SLAM) Market Intelligence
The emergence of robotics-as-a-service (RaaS) subscription models is tilting the competitive field away from pure hardware sales toward integrated service providers. This shift allows companies like Locus Robotics to scale rapidly in the logistics sector with lower upfront costs for end-users. In contrast, established industrial players such as KUKA AG are integrating advanced SLAM capabilities into their capital-intensive automation systems, focusing on performance and reliability for large manufacturing clients.
Simultaneous Localization and Mapping is a computational method enabling an autonomous agent to build a map of an unknown area while tracking its own position. The technology fuses data from sensors like LiDAR or cameras to achieve locational accuracy, often to within a few centimeters. Lidar SLAM technology currently dominates high-precision industrial applications, while lower-cost Visual SLAM sees rapid uptake in consumer electronics and augmented reality. Robotics navigation remains the principal application, commanding significant R&D investment across end-user segments.
Regulatory frameworks such as the FAA's rules for unmanned aerial vehicles and the EU's GDPR for data privacy directly influence SLAM system design and deployment. These standards set operational boundaries for autonomous navigation and mandate strict data handling protocols, particularly for consumer-facing applications. The key decision for developers now involves balancing algorithm performance with the computational constraints imposed by edge computing hardware for real-time operation.
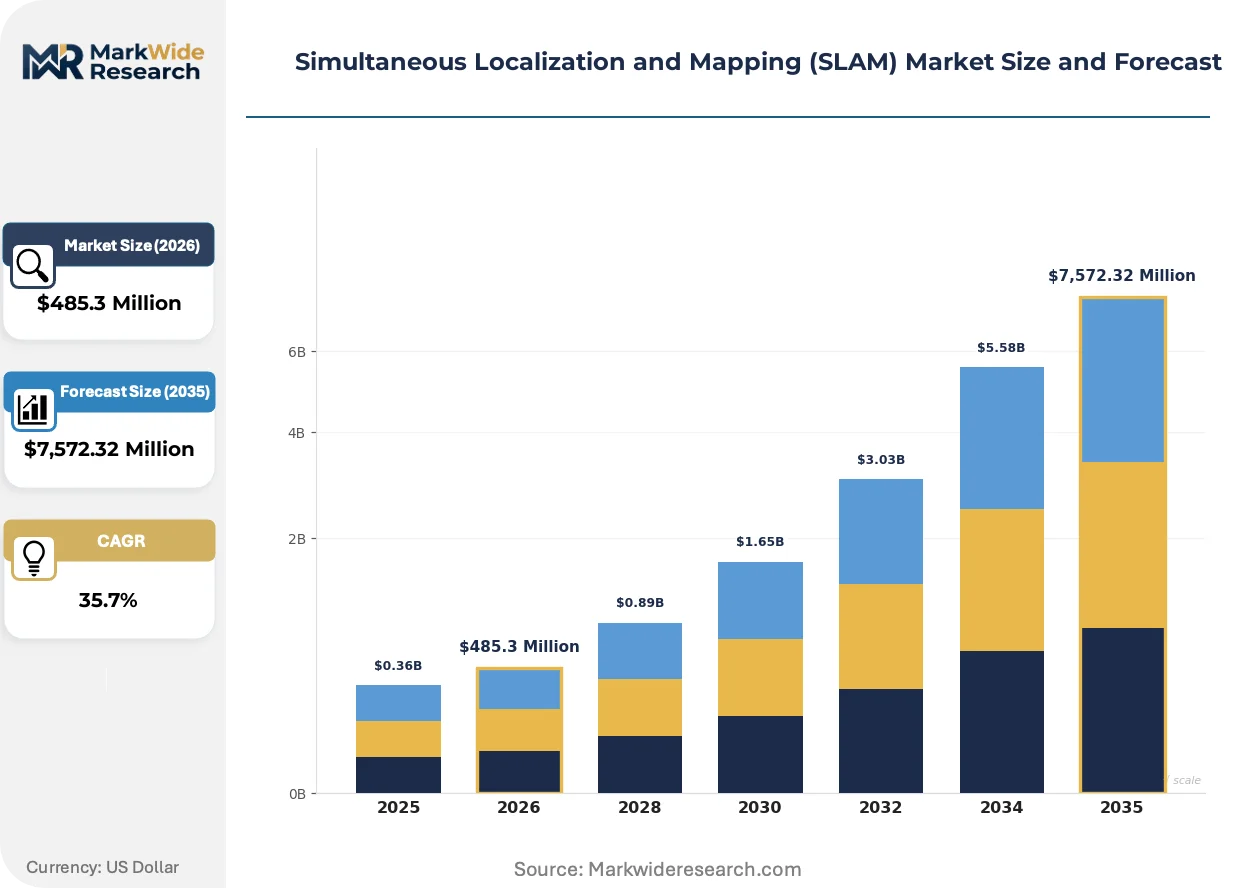
Market Dynamics
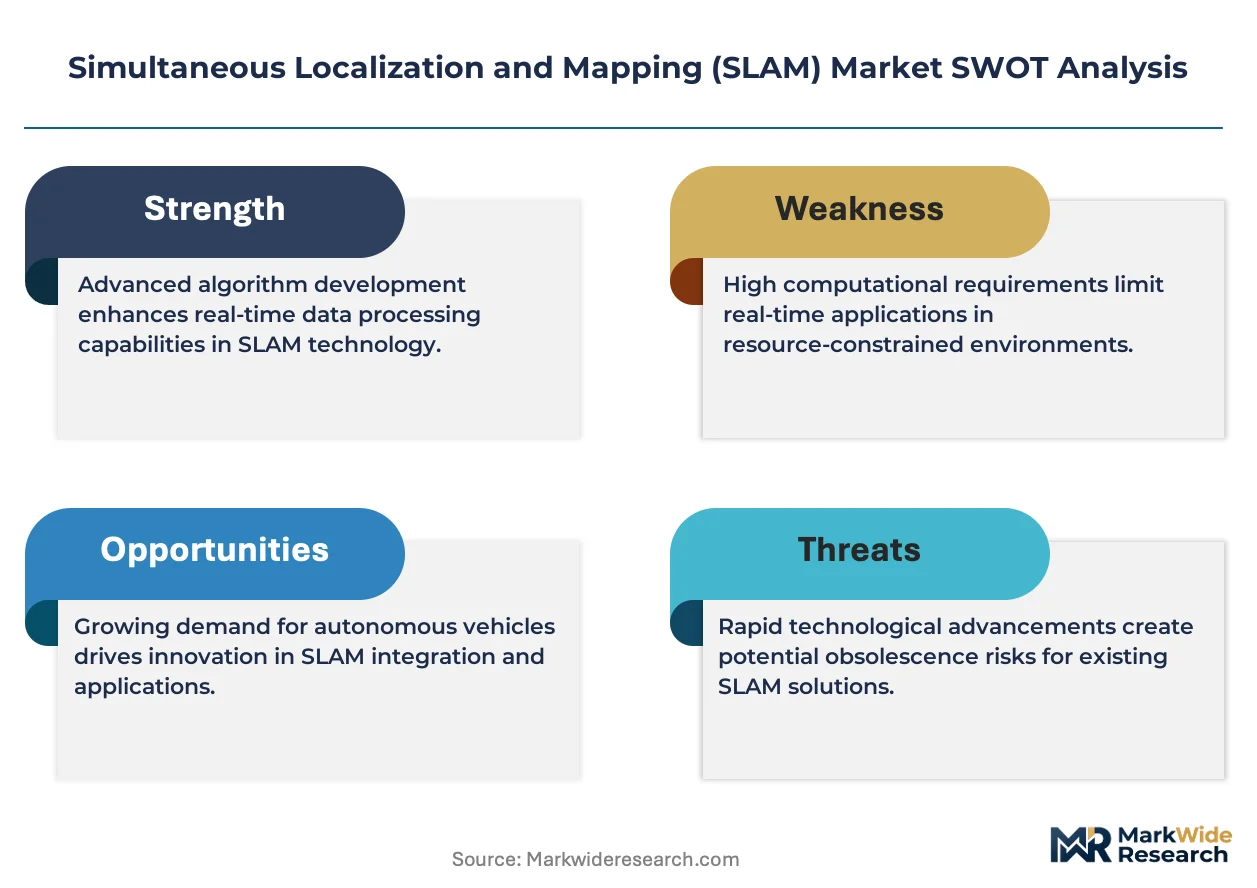
The central structural force shaping the SLAM market is the convergence of advanced sensor fusion with machine learning algorithms on edge computing hardware. This combination is democratizing autonomous navigation, moving it beyond high-cost industrial robotics into broader commercial and consumer applications.
Growth Catalysts
- Industry 4.0 Initiatives:Government-backed manufacturing modernization programs, particularly in Germany and China, are accelerating the deployment of SLAM-enabled autonomous mobile robots (AMRs) on factory floors to improve productivity and supply chain efficiency.
- E-commerce Expansion:The proliferation of automated fulfillment centers and logistics hubs to meet online retail demand creates a direct need for robust SLAM navigation in fleets of warehouse robots for picking, sorting, and transport tasks.
- Advanced Sensor Fusion:The integration of data from LiDAR, cameras, and inertial measurement units (IMUs) through sophisticated algorithms is significantly improving localization accuracy and mapping reliability, expanding the technology's viability for mission-critical applications.
Market Restraints
- High Cost of Precision Sensors:The significant expense associated with industrial-grade LiDAR sensors continues to be a primary barrier to entry, particularly for small-to-medium enterprises and cost-sensitive consumer electronics applications.
- Computational Hardware Limitations:Real-time SLAM algorithms demand substantial processing power, which presents thermal management and battery life challenges for developers of small, power-constrained autonomous devices like drones and service robots.
- Dynamic Environment Instability:The performance of many SLAM systems degrades significantly in highly dynamic or unstructured environments with constant human movement or changing layouts, limiting deployment in public spaces or chaotic worksites.
Strategic Opportunities
- Augmented and Virtual Reality:The development of consumer and enterprise AR/VR platforms creates a substantial new market for Visual SLAM (vSLAM) to enable world-scale tracking and persistent digital content overlays in shared spaces.
- Precision Agriculture:Underpenetrated agricultural sectors in countries like Australia and Brazil offer significant opportunities for SLAM-guided drones and autonomous ground vehicles for crop monitoring, targeted spraying, and automated harvesting.
- Solid-State LiDAR Commercialization:The emergence of lower-cost, more durable solid-state LiDAR technology is poised to unlock mass-market applications in automotive driver-assistance systems and consumer robotics that were previously cost-prohibitive.
Industry Challenges
- Algorithm Development Talent Scarcity:A persistent shortage of engineers with combined expertise in sensor fusion, machine learning, and embedded systems optimization is a key bottleneck that slows down innovation and product development cycles.
- Data Privacy and Security:Navigating complex data privacy regulations, such as the EU's GDPR, is a major compliance hurdle for applications that capture detailed 3D maps of private or public spaces, requiring robust data anonymization and security protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Simultaneous Localization and Mapping (SLAM) Market |
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $7,572.32 Million |
| CAGR (2026 – 2036) | 35.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Visual SLAM, Lidar SLAM, RGB-D SLAM, Inertial SLAM, Acoustic SLAM Application: Autonomous Navigation, Augmented Reality, Robotics Navigation, Unmanned Aerial Vehicles, Industrial Automation End User: Consumer Electronics, Aerospace & Defense, Manufacturing, Agriculture Technology, Construction Deployment: Cloud-Based, On-Premises, Edge Computing, Hybrid Solutions |
| Companies Covered | KUKA AG, Locus Robotics, Google, Parrot SA, SLAMcore, Apple, Clearpath Robotics, GeoSLAM, Amazon Robotics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Simultaneous Localization and Mapping (SLAM) Market Strategic Shifts & Innovations
The push for greater autonomy in increasingly complex and unstructured environments is the core theme driving innovation. This necessitates SLAM systems that are not only more accurate but also more contextually aware, computationally efficient, and compliant with evolving safety and data privacy standards.
AI-powered semantic SLAM algorithms provide robots with a higher-level understanding of their surroundings by identifying and classifying objects. Robotics developers in logistics and domestic assistance are adopting this technology to enable more intelligent navigation. This contextual awareness is rendering obsolete purely geometric point-cloud maps, allowing for more sophisticated and human-like interaction with the environment.
New regulatory frameworks, such as the EU AI Act, are imposing stringent requirements on systems deemed high-risk, including many autonomous navigation applications. This is forcing developers to integrate principles of transparency, auditability, and "explainable AI" directly into their SLAM algorithms. Consequently, robotics manufacturers targeting Europe are embedding rigorous validation and documentation processes throughout their development lifecycle.
A notable behavioral change is the move away from large, upfront capital expenditures toward more flexible Robotics-as-a-Service (RaaS) subscription models. This trend disrupts traditional equipment sales channels, favoring integrated service providers who can offer a complete package of hardware, software, and support. This service-oriented consumption is most advanced in the North American logistics and warehousing sector, where it lowers adoption barriers for end-users.
Simultaneous Localization and Mapping (SLAM) Market Segmentation
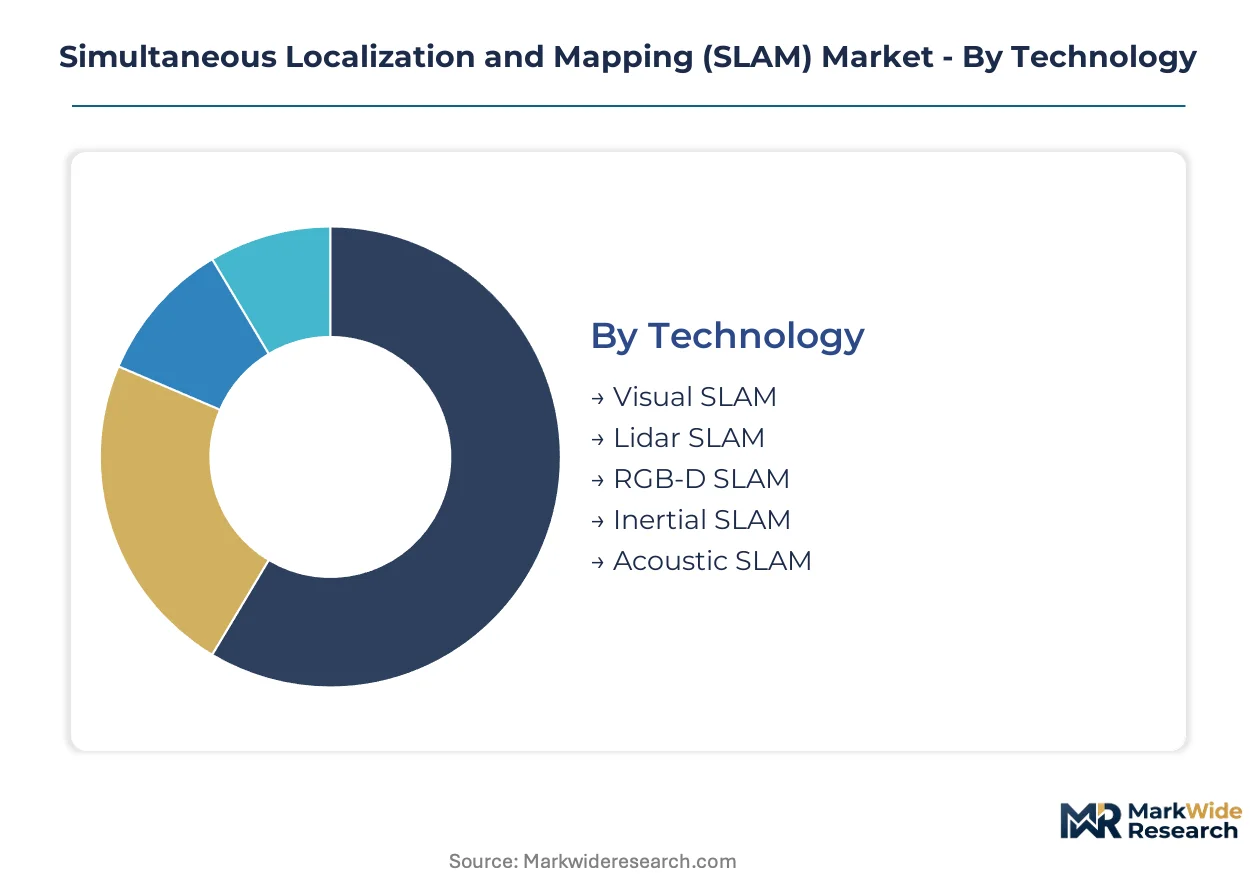
The Simultaneous Localization and Mapping (SLAM) market segments highlight the diverse technological approaches and application areas driving its expansion. Understanding these distinctions is crucial for developers and integrators targeting specific operational requirements and performance benchmarks across industries.
Technology:
The technology segmentation for SLAM illustrates the diverse computational approaches employed to achieve real-time localization and mapping across various operational demands.
- Lidar SLAM:This technology utilizes pulsed laser light to measure distances, generating highly accurate 3D point clouds for mapping. It currently dominates high-precision industrial applications like warehouse automation where millimeter-level accuracy is critical for robot navigation in complex environments.
- Visual SLAM:Employing cameras to capture visual data, this method reconstructs environments and tracks position by analyzing image features. Visual SLAM sees rapid uptake in consumer electronics and augmented reality, balancing cost-effectiveness with sufficient accuracy for human-scale interaction.
- RGB-D SLAM:Integrating color (RGB) and depth (D) information from specialized sensors, this approach offers robust performance in indoor settings. RGB-D SLAM is particularly useful for domestic robots that need to understand object proximity and surface properties.
- Inertial SLAM:This method fuses inertial measurement unit (IMU) data with other sensor inputs to maintain localization during temporary sensor occlusions or rapid movements. Inertial SLAM enhances stability for drones and fast-moving autonomous vehicles.
- Acoustic SLAM:Using sound waves to map environments, this niche technology is applied in underwater robotics or dark, dusty, and smoky conditions where visual or LiDAR sensors are ineffective.
The dominant share belongs to Lidar SLAM, while Visual SLAM is closing the gap fastest.
Application:
The application breakdown delineates how SLAM capabilities are tailored for distinct operational environments and user requirements.
- Robotics Navigation:This segment involves guiding autonomous robots through physical spaces, leveraging SLAM for path planning, obstacle avoidance, and precise positioning. Robotics navigation remains the principal application, commanding significant R&D investment across end-user segments like logistics.
- Industrial Automation:SLAM enables autonomous mobile robots (AMRs) to operate efficiently on factory floors and in warehouses, automating tasks such as material handling and inventory management. Industry 4.0 initiatives in Germany and China are accelerating this deployment.
- Autonomous Navigation:This broad category encompasses self-driving cars, drones, and other vehicles that use SLAM to perceive their surroundings and plan routes without human intervention. Regulatory frameworks like the FAA's rules for unmanned aerial vehicles directly influence system design.
- Augmented Reality:SLAM provides the foundational tracking for AR systems, allowing virtual objects to be accurately anchored to real-world environments. The development of consumer and enterprise AR platforms creates a substantial new market for Visual SLAM.
- Unmanned Aerial Vehicles:Drones utilize SLAM for stable flight, mapping, and inspection tasks in complex or GPS-denied environments. This application benefits from advanced sensor fusion and lightweight computational hardware.
This segment is driven by the imperative for efficient movement in structured environments, with robotics navigation seeing sustained investment.
End User:
The end-user segmentation reveals the varying scales of SLAM deployment, from individual consumer devices to large-scale industrial operations.
- Manufacturing:This sector integrates SLAM into AMRs and robotic arms for enhanced productivity and supply chain efficiency on factory floors. Government-backed modernization programs, particularly in Germany and China, accelerate this adoption.
- Consumer Electronics:SLAM is embedded in smartphones, AR/VR headsets, and domestic robots to enable features like indoor navigation, spatial computing, and persistent digital content overlays. Data privacy regulations such as the EU's GDPR influence system design.
- Aerospace & Defense:SLAM technology is critical for autonomous drones, surveillance systems, and exploration robots in challenging environments. Performance reliability and secure data handling are paramount for these applications.
- Agriculture Technology:Underpenetrated agricultural sectors utilize SLAM-guided drones and autonomous ground vehicles for precision farming tasks. Crop monitoring, targeted spraying, and automated harvesting offer significant opportunities.
- Construction:SLAM assists with site mapping, progress monitoring, and autonomous equipment operation in dynamic construction environments. This helps improve safety and project efficiency.
Growth is concentrated in manufacturing and consumer electronics, reflecting automation trends and personal device integration.
Deployment:
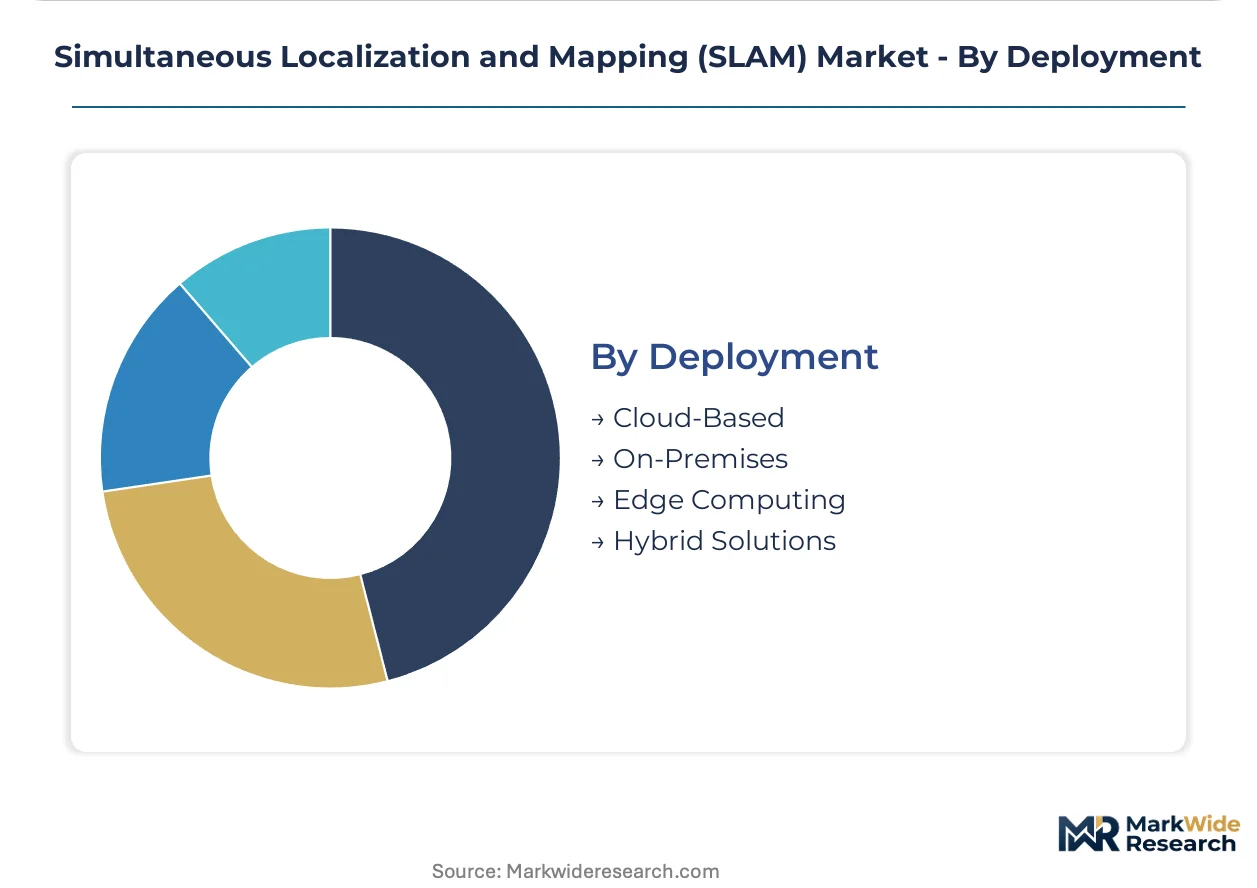
The deployment model segmentation reflects the diverse infrastructure strategies adopted by organizations to manage computational load and data access for SLAM systems.
- Edge Computing:SLAM algorithms run directly on the autonomous device, enabling real-time processing and decision-making without constant cloud connectivity. This approach addresses computational constraints and latency concerns for small, power-constrained robots.
- Cloud-Based:Data from SLAM sensors is transmitted to remote servers for processing, offering scalable computational resources and centralized data management. Cloud-based solutions are suitable for large-scale mapping projects or applications requiring extensive data analysis.
- On-Premises:SLAM systems are deployed and managed entirely within an organization's local infrastructure, providing maximum control over data security and system customization. This is common in sensitive industrial environments or defense applications.
- Hybrid Solutions:This model combines edge processing for real-time tasks with cloud or on-premises infrastructure for heavy computational loads, data storage, and long-term map building. Hybrid solutions offer a balance of performance, scalability, and data control.
The market is increasingly favoring edge computing for real-time applications, while hybrid models offer flexibility for complex deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The SLAM market's regional dynamics reflect concentrated demand from advanced manufacturing and logistics sectors. Government-backed Industry 4.0 initiatives in key economies accelerate autonomous mobile robot deployment. This drives significant investment in SLAM technology across diverse end-user applications.
Germany
Demand for SLAM-enabled AMRs in Germany stems from its robust automotive and machinery manufacturing sectors. Industry 4.0 initiatives, supported by the German government, promote automation for productivity gains. Clusters like Bavaria and Baden-Württemberg are centers for robotics research and advanced factory automation.
China
China's rapid e-commerce expansion and manufacturing modernization programs fuel demand for SLAM in logistics and factory automation. The "Made in China 2025" strategy prioritizes robotics and intelligent manufacturing, driving local SLAM development. Industrial hubs in the Yangtze River Delta integrate SLAM for efficient warehouse and production line operations.
United States
The United States market sees strong demand for SLAM in warehouse automation, consumer electronics, and defense applications. FAA regulations for unmanned aerial vehicles influence SLAM system design for drone navigation and mapping. Silicon Valley and Boston are key innovation centers for robotics and AI-driven autonomous systems.
Japan
Japanese manufacturing and logistics sectors are significant consumers of SLAM technology for high-precision robotics navigation. The METI's robot strategy encourages the integration of advanced automation in industries facing labor shortages. Tokyo and Nagoya host major robotics companies and research institutions focused on SLAM applications.
South Korea
South Korea's advanced manufacturing and consumer electronics industries drive SLAM adoption for factory automation and smart devices. Government initiatives support R&D in AI and robotics, fostering SLAM innovation for various applications. The Seoul Capital Area is a hub for tech companies developing visual SLAM for AR and domestic robots.
Simultaneous Localization and Mapping (SLAM) Market Key Industry Players
Channel-controlling players compete with product-specialist players in the SLAM market, creating a tiered competitive structure. The landscape features established industrial automation firms integrating SLAM into their capital-intensive systems, alongside agile robotics-as-a-service providers scaling rapidly through subscription models. Specialized algorithm developers also emerge, focusing on specific sensor fusion or machine learning optimizations. These archetypes often pursue strategic partnerships to integrate diverse capabilities or prioritize portfolio diversification to capture new end-user segments.
On the industrial automation front, KUKA AG exemplifies established players who integrate advanced SLAM capabilities into their capital-intensive systems for large manufacturing clients. In contrast, Locus Robotics represents the rapidly scaling robotics-as-a-service providers, offering flexible subscription models to logistics and warehousing end-users. UK-based SLAMcore, meanwhile, sits within the specialized algorithm developer archetype, focusing on robust software solutions for spatial intelligence. These players demonstrate the varied approaches to market penetration and value delivery within the SLAM ecosystem.
| Leading Market Players |
|---|
| KUKA AG |
| Locus Robotics |
| Parrot SA |
| SLAMcore |
| Apple |
| Clearpath Robotics |
| GeoSLAM |
| Amazon Robotics |
| Others |
Cost & Logistics Intelligence
Precision sensor manufacturing, particularly for high-fidelity LiDAR components, concentrates margin pools within specialized hardware providers. This concentration influences downstream pricing for integrated SLAM systems in industrial applications.
Pricing Analysis
Performance accuracy, particularly for millimeter-level precision, creates the primary pricing spread within the SLAM market. Robotics-as-a-service (RaaS) subscription models are prevalent, especially for logistics, while capital-intensive industrial systems often use project-based pricing. Lidar SLAM systems command higher prices due to their precision and reliability, contrasted with lower-cost Visual SLAM solutions. Pricing pressure stems from the commoditization of Visual SLAM components for consumer electronics, while high-performance industrial applications maintain premium pricing. Small-to-medium enterprises and consumer electronics developers are highly price-sensitive, whereas large manufacturing clients prioritize performance and reliability over cost.
Supply Chain Analysis
Single-source vulnerability for specialized LiDAR sensors and advanced semiconductors poses a significant supply chain risk for SLAM system manufacturers. Component manufacturing concentrates in China, Taiwan, and South Korea, impacting global availability. The supply chain relies heavily on high-precision LiDAR sensors, inertial measurement units (IMUs), and powerful edge computing chips. Geopolitical tensions affecting semiconductor production in Taiwan could disrupt the flow of critical processing hardware. Industrial SLAM solutions often use direct sales channels with extensive integration support, while consumer electronics rely on embedded component sales and broader distribution networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The SLAM market is experiencing a cyclical recovery, driven by renewed investment in automation spurred by global e-commerce expansion and Industry 4.0 initiatives. This creates sustained demand for autonomous navigation solutions across diverse sectors.
For Market Incumbents: Build a robust intellectual property moat around advanced sensor fusion and AI-powered semantic SLAM algorithms. Established players like KUKA AG should deepen vertical integration into software platforms to control core technology. They must also pursue strategic acquisitions of specialized algorithm developers to secure talent and IP. The rise of agile Robotics-as-a-Service (RaaS) providers threatens traditional hardware sales models. Investment in R&D for explainable AI features can meet evolving regulatory frameworks such as the EU AI Act.
For New Entrants and Emerging Players: Underpenetrated agricultural sectors in Australia and Brazil represent a significant white-space opportunity for SLAM-guided drones and autonomous ground vehicles. Focus on developing cost-effective Visual SLAM solutions for consumer AR/VR platforms and domestic robots. The consumer electronics segment, particularly for AR/VR applications, offers rapid uptake due to existing ecosystem development. Offer flexible Robotics-as-a-Service (RaaS) models to lower upfront costs and accelerate adoption in logistics and warehousing.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized software companies developing robust, explainable AI for SLAM algorithms. The market shows strong long-term viability over the next 5-10 years, driven by the increasing demand for autonomous systems across all industries. Seek out agile startups with proven expertise in sensor fusion and machine learning optimization, particularly those focused on edge computing solutions. Monitor the commercialization rate of solid-state LiDAR technology, as it will unlock mass-market applications and reshape cost structures.
| Strategic Initiative | Industry Significance |
|---|---|
| Deepen Vertical Integration into Software | Secures proprietary algorithm development, enhancing competitive advantage against emerging RaaS providers. |
| Invest in Explainable AI Research | Ensures compliance with evolving regulatory frameworks like the EU AI Act for high-risk autonomous systems. |
| Expand Robotics-as-a-Service Offerings | Lowers adoption barriers for end-users, accelerating market penetration in logistics and warehousing sectors. |
| Strategic Partnerships for Solid-State LiDAR | Accesses lower-cost, durable sensor technology, enabling new mass-market applications in consumer robotics. |
| Target Precision Agriculture Applications | Captures underpenetrated market segments in regions like Australia with significant demand for autonomous farming. |
Research Approach
Findings reconcile primary fieldwork against secondary review of academic journals, patent databases, and regulatory filings from the FAA and EU. Interviews included robotics engineers, logistics managers, AI algorithm developers, and supply chain executives. This involved cross-referencing information from technical reports, company annual statements, and government-backed innovation programs. A rigorous bottom-up and top-down triangulation approach validated market sizing and growth projections.
Forecast inputs considered include technological advancements in sensor fusion, evolving regulatory frameworks, and end-user adoption rates across the analysis window. The analytical framework integrates supply-side capacity, demand-side adoption, and competitive dynamics over the projection horizon. Segmentation dimensions modeled include technology type, application area, end-user industry, and deployment model. Compound Annual Growth Rates were derived from historical data analysis and projected future market penetration rates. These projections account for the commercialization timeline of solid-state LiDAR and the impact of Industry 4.0 initiatives.
Practitioners should monitor shifts in geopolitical trade policies and the pace of AI regulatory development for early signals impacting SLAM market forecasts. Forecasts reflect assumptions regarding technological maturity and economic stability. Unforeseen supply chain disruptions or rapid changes in consumer electronics adoption could revise these projections. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Social Robots Market
Robotics and Automation
Smart Worker Market
Robotics and Automation
Delta Robots Market
Robotics and Automation
Autonomous Robot Market
Robotics and Automation
Mobile Cobots Market
Robotics and Automation
Vision Guided Robotics Market
Robotics and Automation
Asia-Pacific Data Center Robotics Market
Robotics and Automation
Africa Agricultural Robots and Mechatronics Market
Robotics and Automation
Nanorobots in Healthcare Market
Robotics and Automation
Underwater Rescue Robot Market
Robotics and Automation
Articulated Robots for Injection Molding Machine Market
Robotics and Automation
Healthcare Companion Robots Market
Robotics and Automation
United Kingdom Cloud Robotics Market
Robotics and Automation
Robotics Software Platforms Market
Robotics and Automation
Metal Fabrication Robots Market
Robotics and Automation
Healthcare Assistive Robot Market