
 APAC Service Robots Market | 2026-2036
APAC Service Robots Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Service Robots Market Outlook
GB/T 38124 service robot safety certification is reorganizing vendor eligibility across the APAC landscape, forcing smaller manufacturers toward third-party testing partnerships or exit. FANUC Corporation leverages its industrial automation heritage to anchor premium logistics robot deployments in Japanese distribution centers. UBTECH Robotics Inc. specializes in humanoid platforms for education and retail reception roles, while Ecovacs Robotics dominates consumer-grade cleaning robots through channel control in Chinese e-commerce.
APAC service robots encompass electromechanical systems with autonomous navigation payloads, sensor fusion architectures, and manipulator arms rated for human interaction, designed to execute commercial tasks without fixed infrastructure. Cleaning robots and logistics robots represent the most mature product categories with established replacement cycles, whereas health care robots command the steepest margin pools due to clinical validation requirements and hospital procurement protocols. Among end users, healthcare and hospitality absorb the highest unit volumes, with AI-based and sensor-based technologies forming the dominant capability stack as GPS navigation remains limited to outdoor delivery applications.
China's SAMR enforces GB standards that mandate collision avoidance testing and electromagnetic compatibility for domestic sales, while Japan's METI coordinates nursing-care robot subsidies through municipal assessment frameworks. South Korea's MFDS and KISA jointly oversee medical and data-security compliance for healthcare robot deployments. Stakeholders must track how regulatory divergence between national certification regimes affects cross-border product architecture decisions and service localization costs.
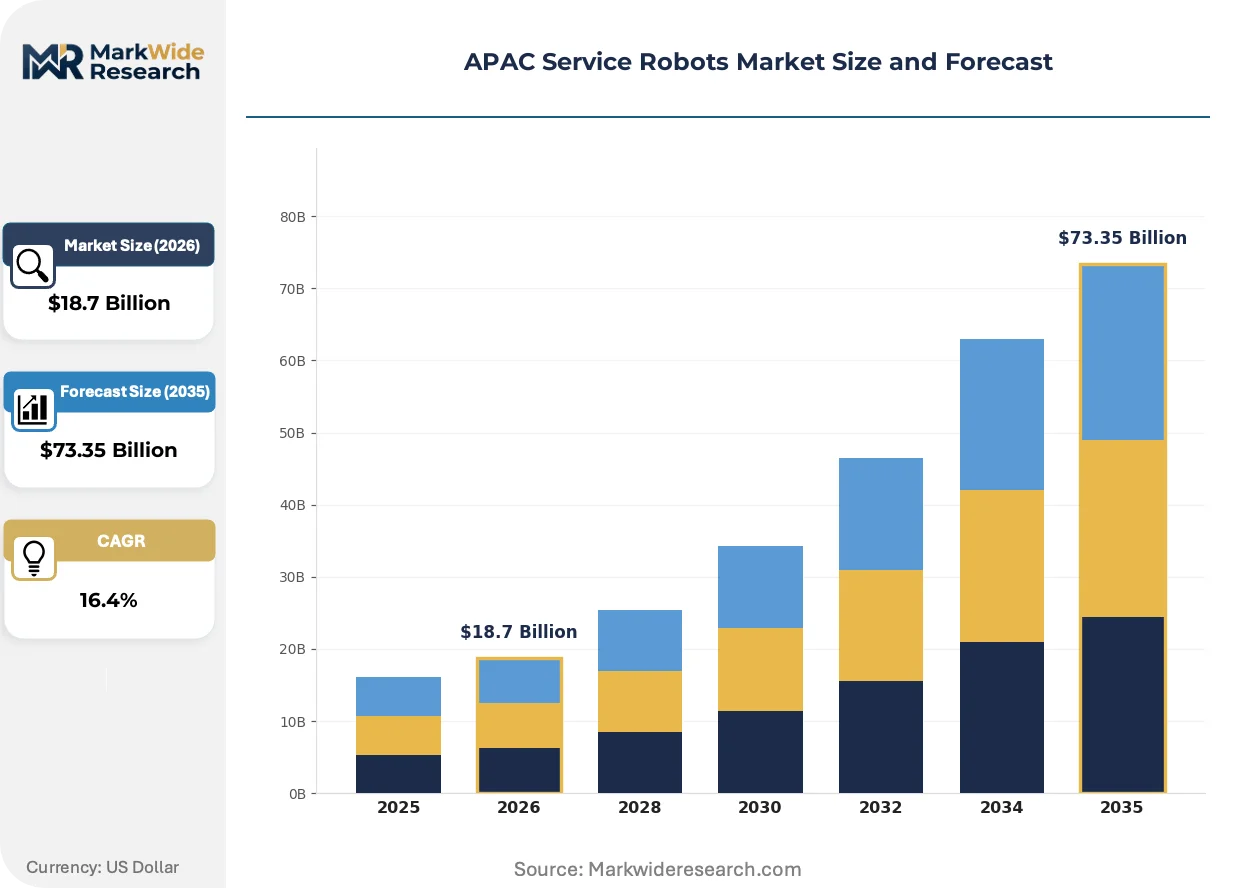
Market Dynamics
Japan's METI nursing-care subsidies and China's GB/T 38124 collision-avoidance mandates are forcing manufacturers to redesign sensor fusion architectures for dual-certification eligibility across APAC hospital networks.
Growth Catalysts
- Japan METI Subsidy Framework:Municipal assessment protocols for nursing-care automation accelerate procurement of patient-monitoring robots in Tokyo and Osaka prefectures.
- Hospital Labor Shortages:Healthcare facilities across Japan and South Korea deploy autonomous navigation systems to offset intensifying workforce gaps in geriatric wards.
- LiDAR-Visual Fusion:Sensor convergence architectures enable sub-centimeter positioning accuracy required for crowded corridor navigation in Chinese metropolitan hospital networks.
Market Restraints
- GB Standard Compliance Costs:China's SAMR electromagnetic compatibility testing mandates impose six-figure certification burdens on sub-scale manufacturers.
- High-Precision Encoder Supply:German and Japanese component suppliers control 70% of harmonic drive actuator inputs, creating geographic concentration vulnerability.
- Battery Energy Density Ceiling:Lithium-ion chemistry limitations restrict continuous operation windows for cleaning robots below eight-hour facility shifts.
Strategic Opportunities
- Vietnam Manufacturing Expansion:Greenfield production facilities near Ho Chi Minh City bypass PRC tariff exposure while serving ASEAN hospital procurement channels.
- Retail Reception Humanoids:Unstaffed customer service kiosks in South Korean duty-free zones create deployment templates for hospitality automation.
- South Korea MFDS-KISA Convergence:Joint medical-data security frameworks streamline cross-border healthcare robot validation for regional hospital chains.
Industry Challenges
- SLAM Algorithm Talent Scarcity:Simultaneous localization and mapping expertise concentrates in Shenzhen and Seoul, inflating compensation for robotics firmware teams.
- Legacy HIS Integration:Hospital information system interoperability gaps in provincial Chinese facilities delay pilot-to-production transitions for patient-monitoring platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Service Robots Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Logistics Robots, Cleaning Robots, Delivery Robots, Health Care Robots End User: Hospitality, Retail, Healthcare, Education Technology: AI-based, GPS Navigation, Sensor-based, Remote-controlled Application: Personal Assistance, Data Collection, Inventory Management, Food Service |
| Companies Covered | Hyundai Robotics Co. Ltd., Ecovacs Robotics, LG Electronics Inc., FANUC Corporation, SoftBank Robotics Group, UBTECH Robotics Inc., Hanwha Robotics, SIASUN Robot & Automation, Milagrow HumanTech, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Service Robots Market Strategic Shifts
Edge-computing migration and modular payload architectures are compressing hardware refresh cycles while enabling software-defined feature upgrades without mechanical retrofits.
Multi-sensor fusion stacks combining solid-state LiDAR, depth cameras, and ultrasonic arrays are decomposing the historical premium attached to single-modality navigation systems. Japanese distribution centers now specify hybrid perception architectures as baseline procurement requirements. This convergence is decomposing vendor margins on high-end positioning modules while expanding addressable volume for mid-tier logistics robot suppliers.
South Korea's MFDS and KISA have established joint oversight protocols for medical robot data security, creating compliance templates that reduce validation timelines for subsequent entrants. The framework mandates encrypted telemetry channels and localized data residency for patient-monitoring deployments. Hospital procurement committees in Seoul and Busan now prioritize vendors with pre-certified cybersecurity architectures.
Chinese municipal hospital networks have shifted from capital-expense purchasing to five-year service contracts bundling hardware, maintenance, and software updates. This unbundling of ownership from operation compresses supplier cash conversion cycles while transferring obsolescence risk to manufacturers. Tier-one city health bureaus in Shanghai and Beijing lead this transition, with provincial networks following at eighteen-month lag intervals.
APAC Service Robots Market Segmentation
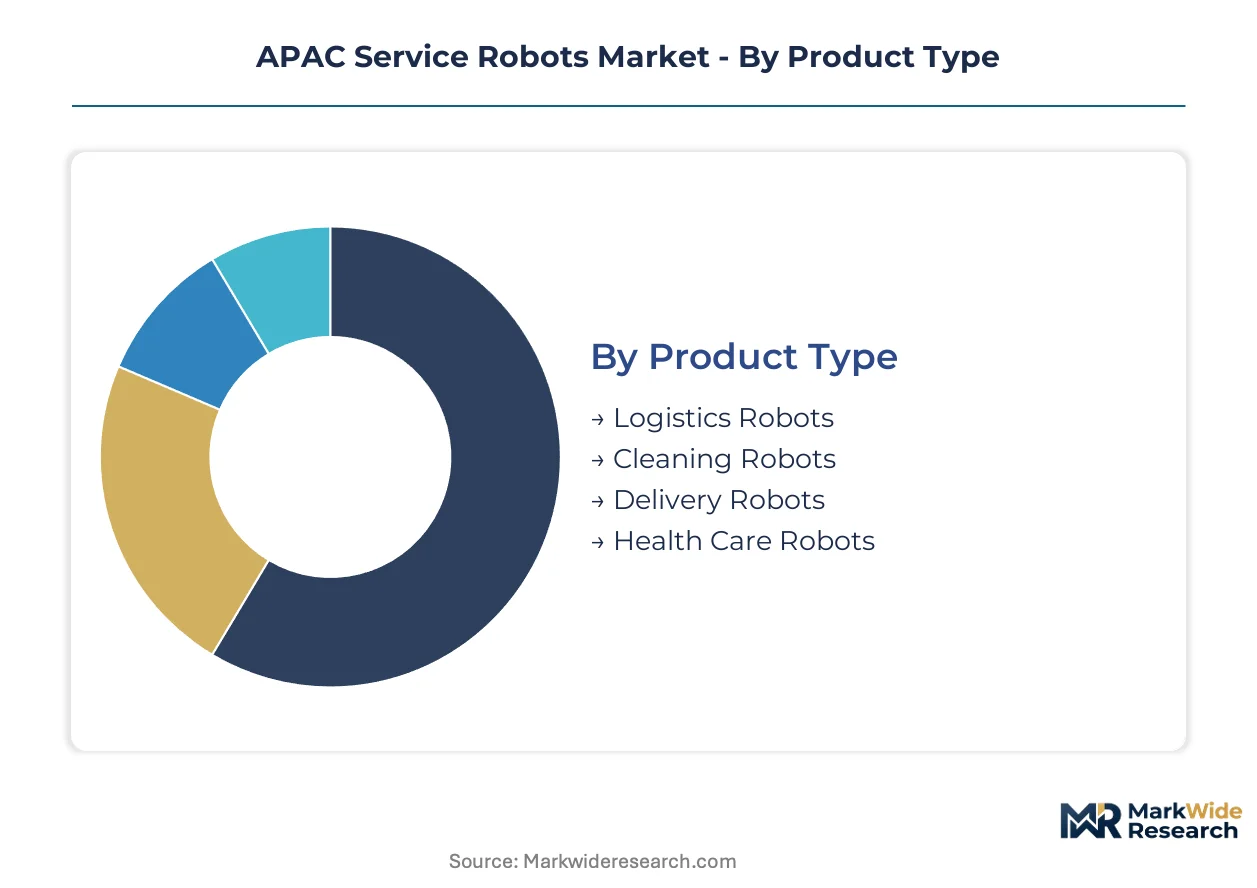
Service robot architectures diverge sharply across APAC procurement channels. Japanese hospital networks prioritize clinical validation tiers, while Chinese municipal buyers weight autonomous navigation specifications in tender documents.
Product Type:
Domestic absorption concentrates in Japan and South Korea for nursing-care platforms, whereas Chinese manufacturers export cleaning and logistics units across ASEAN markets.
- Logistics Robots:Autonomous mobile robots with pallet-handling manipulators and warehouse management system integration. Japanese distribution centers in Osaka and Nagoya specify hybrid LiDAR-visual perception as baseline procurement requirements amid labor contraction in fulfillment operations.
- Health Care Robots:Patient-monitoring platforms with FDA-equivalent validation for geriatric ward deployment. Tokyo and Seoul metropolitan hospitals accelerate procurement through METI and MFDS subsidy frameworks as workforce gaps intensify in long-term care facilities.
- Cleaning Robots:Consumer-grade and commercial floor-scrubbing units with SLAM-based room mapping.
- Delivery Robots:Last-mile autonomous vehicles for campus and residential compound distribution.
Cleaning robots command the established base. The steepest expansion runs through health care robots.
End User:
Margin structures stratify sharply: clinical validation requirements protect healthcare pricing, while retail and hospitality face commoditization pressure from Shenzhen suppliers.
- Healthcare:Hospitals and long-term care facilities deploying patient-monitoring and disinfection platforms. China's municipal hospital networks in Shanghai and Beijing now specify five-year service contracts bundling hardware and software updates rather than capital-expense purchasing.
- Hospitality:Hotels and restaurants utilizing reception humanoids and automated room service delivery. South Korean duty-free zones in Seoul create deployment templates for unstaffed customer service kiosks with bilingual interaction capabilities.
- Retail:Department stores and supermarkets deploying inventory-scanning and customer guidance systems.
- Education:Schools and training centers utilizing programmable humanoid platforms for STEM curriculum delivery.
Healthcare absorbs the premium tier. Hospitality delivers volume scale through standardization.
Technology:
Capability stacks separate export-competitive vendors from domestic-only suppliers across certification regimes.
- AI-based:Machine learning inference engines for natural language interaction and predictive maintenance. South Korean MFDS-KISA joint frameworks mandate encrypted telemetry and localized data residency for patient-monitoring deployments in Seoul hospital networks.
- Sensor-based:Multi-modal perception architectures fusing solid-state LiDAR, depth cameras, and ultrasonic arrays. Chinese GB/T 38124 collision-avoidance testing mandates are reorganizing vendor eligibility toward third-party certified sensor fusion stacks.
- GPS Navigation:Outdoor positioning systems for campus and municipal delivery corridors.
- Remote-controlled:Teleoperation architectures for hazardous environment intervention and supervisor override functions.
Sensor-based architectures anchor current procurement specifications. AI-based stacks are climbing the fastest as edge-computing migration compresses hardware refresh cycles.
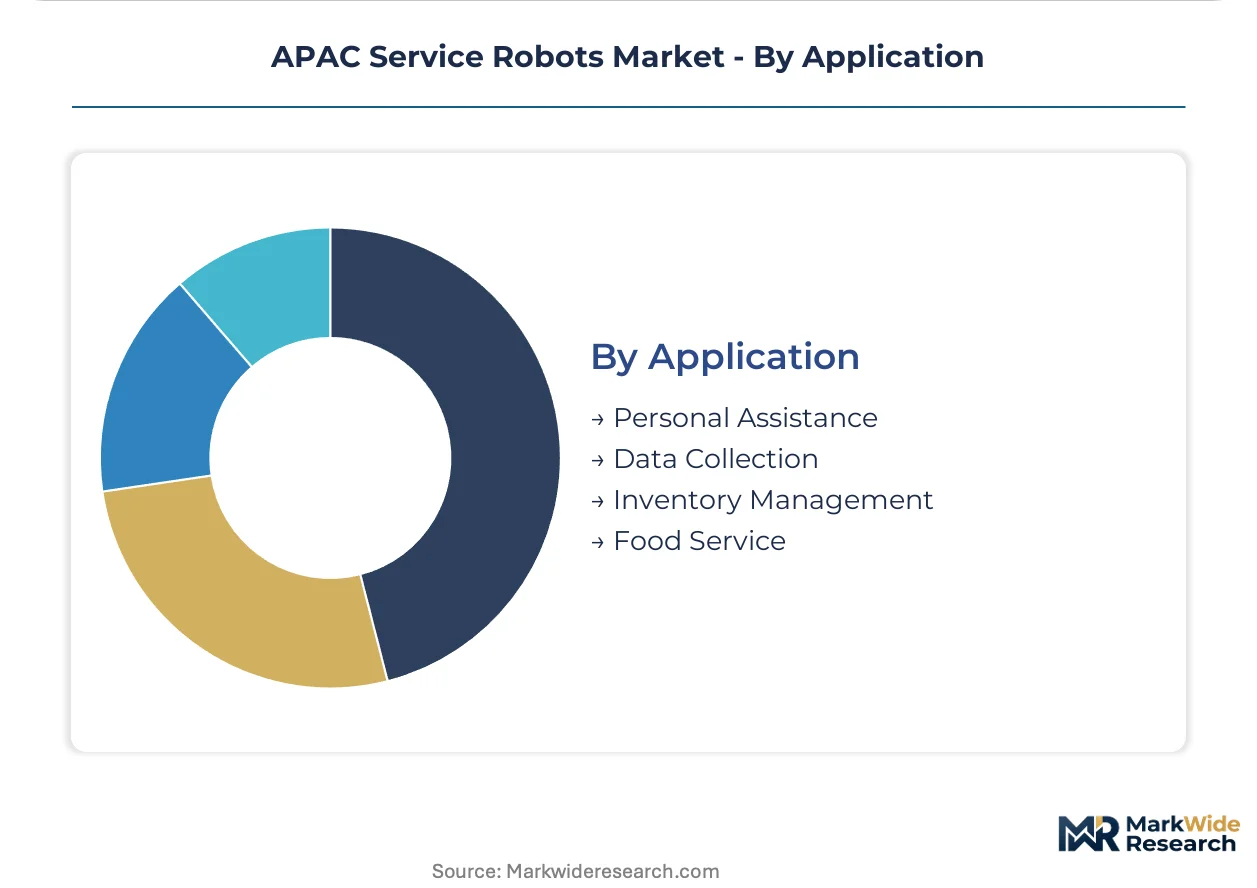
Application:
Functional requirements map directly to national regulatory priorities: clinical data collection faces MFDS oversight, while food service robots navigate municipal health bureau licensing.
- Inventory Management:Autonomous scanning and stock-counting systems for warehouse and retail floor deployment. Japanese distribution centers specify sub-centimeter positioning accuracy for narrow-aisle navigation amid SKU proliferation.
- Personal Assistance:Mobility support and medication reminder platforms for elderly care settings. METI nursing-care subsidies in Tokyo and Osaka prefectures accelerate procurement of patient-monitoring robots with fall-detection capabilities.
- Data Collection:Environmental sensing and patient telemetry aggregation for clinical decision support.
- Food Service:Automated preparation and delivery systems for commercial kitchen and hospitality environments.
Inventory management holds the installed base. Personal assistance is gaining share fastest through demographic pressure and subsidy alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI nursing-care subsidies and GB/T 38124 collision-avoidance mandates are accelerating procurement across hospital networks and municipal facilities throughout the region.
China
Shanghai and Beijing municipal health bureaus specify five-year service contracts bundling hardware and software updates for patient-monitoring deployments. SAMR enforces GB standards mandating electromagnetic compatibility testing and autonomous navigation capabilities in procurement quotas. Yangtze River Delta manufacturing clusters supply solid-state LiDAR modules for domestic logistics robot producers serving ASEAN export channels.
Japan
Tokyo and Osaka prefectures deploy patient-monitoring robots through METI municipal assessment protocols as geriatric ward labor shortages intensify. METI coordinates nursing-care automation subsidies that prioritize fall-detection and medication reminder platforms. Nagoya distribution centers specify hybrid LiDAR-visual perception as baseline requirements for logistics robot procurement amid fulfillment workforce contraction.
South Korea
Seoul and Busan metropolitan hospitals prioritize vendors with pre-certified cybersecurity architectures under joint MFDS-KISA oversight frameworks. MFDS and KISA mandate encrypted telemetry channels and localized data residency for patient-monitoring robot deployments. Daegu-Gyeongbuk industrial corridors host firmware development clusters for SLAM algorithm talent concentrated in Seoul.
Vietnam
Ho Chi Minh City greenfield production facilities bypass PRC tariff exposure while serving ASEAN hospital procurement channels with cleaning and logistics units. The country's national industrial development framework incentivizes electronics manufacturing relocation from higher-cost neighbors. Southern manufacturing zones attract component assembly operations for regional service robot supply chains.
Australia
New South Wales and Victoria healthcare networks pilot patient-monitoring platforms for rural aged-care facilities facing workforce recruitment challenges. The country's national therapeutic goods regulator oversees clinical validation requirements for imported healthcare robot systems. Sydney medical technology clusters facilitate distributor partnerships for APAC-origin vendors seeking developed-market entry.
APAC Service Robots Market Competitive Environment
Player mix skews toward industrial automation heritage companies and consumer electronics conglomerates with robotics divisions. Market structure concentrates around three strategic archetypes: industrial automation specialists leveraging precision manufacturing expertise, consumer electronics giants with channel control and brand recognition, and pure-play robotics firms focused on humanoid or specialized platforms. Competitive dynamics center on certification-driven portfolio diversification and geographic expansion through ASEAN manufacturing relocation.
Among industrial automation heritage companies, FANUC Corporation and SIASUN Robot & Automation occupy positions emphasizing precision actuator integration and warehouse management system compatibility. Within the consumer electronics tier, LG Electronics Inc. and Ecovacs Robotics exemplify channel-controlled market presence through e-commerce platform dominance and retail network penetration. UBTECH Robotics Inc. and SoftBank Robotics Group represent the pure-play humanoid specialist archetype, targeting education and hospitality reception applications with programmable interaction platforms.
| Leading Market Players |
|---|
| Hyundai Robotics Co. Ltd. |
| Ecovacs Robotics |
| LG Electronics Inc. |
| FANUC Corporation |
| SoftBank Robotics Group |
| UBTECH Robotics Inc. |
| Hanwha Robotics |
| SIASUN Robot & Automation |
| Milagrow HumanTech |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at Shenzhen and Suzhou LiDAR module plants shapes both supply concentration and price floors for mid-tier logistics robot vendors serving ASEAN export channels. Chinese municipal hospital networks now specify five-year service contracts that compress supplier cash conversion cycles while transferring obsolescence risk to manufacturers.
Pricing Analysis
Certification level (GB/T 38124, METI nursing-care tier, MFDS-KISA cybersecurity grade) creates the primary spread between premium healthcare robots and commoditized cleaning units. Three-tier pricing structure across premium, standard, and economy levels stratifies by clinical validation depth and autonomous navigation capability. Cost compression in consumer-grade cleaning robots intensifies because Shenzhen suppliers crowd e-commerce channels with undifferentiated SLAM-based units. Municipal hospital procurement committees show least price sensitivity for patient-monitoring platforms with pre-certified data security architectures.
Supply Chain Analysis
Harmonic drive actuator supply from Japanese and German component suppliers underwrites precision positioning costs for healthcare and logistics robot manufacturers. Solid-state LiDAR modules draw from Yangtze River Delta clusters, while lithium-ion battery packs rest on South Korean and Chinese cell production. Single-source vulnerability concentrates in high-precision encoder inputs controlled by two national supply bases. Distribution runs through municipal procurement channels for hospital networks and e-commerce platforms for consumer-grade units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GB/T 38124 collision-avoidance mandates and METI nursing-care subsidies constitute a regulatory inflection that will displace uncertified vendors across APAC hospital networks within the projection horizon.
For Market Incumbents: Shield installed base relationships by accelerating dual-certification investments for GB/T 38124 and METI nursing-care eligibility before municipal procurement quotas harden. Deepen backward integration into solid-state LiDAR module production to escape Yangtze River Delta supply concentration. Channel control through hospital system partnerships offers defensive moats against emerging Shenzhen suppliers with undifferentiated hardware. For New Entrants and Emerging Players: After-sales software subscription gaps in provincial Chinese hospital networks create white-space opportunities where incumbents under-serve legacy HIS integration requirements. Target Vietnam greenfield manufacturing to bypass PRC tariff exposure while serving ASEAN procurement channels. Lead with five-year service contract proposals that transfer obsolescence risk from municipal buyers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among healthcare robot vendors with pre-certified cybersecurity architectures under MFDS-KISA joint frameworks. Long-term viability centers on software-defined feature upgrade capability that compresses hardware refresh cycles. Acquisition target archetype: mid-tier logistics robot suppliers with hybrid LiDAR-visual perception stacks and Japanese distribution center reference deployments. Watch for municipal hospital contract transitions from capital-expense to service-contract purchasing as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Investment | GB/T 38124 and METI nursing-care eligibility unlocks Tokyo and Shanghai municipal procurement quotas. |
| Software-Defined Feature Upgrades | Edge-computing migration enables subscription revenue without mechanical retrofits for hospital deployments. |
| Vietnam Manufacturing Relocation | Ho Chi Minh City production facilities bypass PRC tariff exposure while serving ASEAN hospital channels. |
| Cybersecurity Architecture Pre-Certification | MFDS-KISA joint compliance reduces validation timelines for Seoul and Busan metropolitan hospital chains. |
| Hospital System Partnership Deepening | Five-year service contract bundling transfers obsolescence risk and locks out Shenzhen commodity suppliers. |
Study Parameters
Operator-level perspectives from hospital procurement managers, nursing-care facility directors, robotics firmware engineers, and municipal health bureau officials anchored the qualitative base. Primary interview data combined with secondary validation from SAMR GB standard filings, METI subsidy program disclosures, MFDS-KISA joint framework documentation, and ASEAN customs trade records. Bottom-up unit deployment estimates triangulated against top-down market size assessments across the analysis window.
Sensitivity analysis tested forecast outputs against varying assumptions for regulatory enforcement timing and subsidy program continuity throughout the projection horizon. Segmentation dimensions modeled include product type, end-user industry, technology stack, and national certification regime. CAGRs derived from logistic diffusion curves fitted to procurement quota trajectories and workforce gap projections. Industry-specific inputs encompassed municipal hospital contract transition rates and solid-state LiDAR cost decline curves.
Forecasts assume regulatory continuity in China's SAMR enforcement, Japan's METI nursing-care subsidies, and South Korea's MFDS-KISA joint frameworks; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as GB standard revision cycles and ASEAN tariff policy evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Automated Facade Contact Cleaning Robot Market
Robotics and Automation
Europe Service Robotics Market
Robotics and Automation
Gimbal Stabilizers Market
Robotics and Automation
Tool Tethering Market
Robotics and Automation
Cognitive Robotics Market
Robotics and Automation
Asia-Pacific Robotic Process Automation Market
Robotics and Automation
Piece Picking Robots Market
Robotics and Automation
Warehouse Robotics Market
Robotics and Automation
Telepresence Robotics Market
Robotics and Automation
Global Security Robots Market
Robotics and Automation
Snake Robots Market
Robotics and Automation
North America Automated Liquid Handling Market
Robotics and Automation
Hotel Robot Market
Robotics and Automation
Robotic Process Automation in Legal Services Market
Robotics and Automation
Delta Robots Market
Robotics and Automation
South America AUV and ROV Market