
 Global Cognitive Automation Market | 2026-2036
Global Cognitive Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cognitive Automation Market Foresight
North American cloud infrastructure providers is repositioning cognitive automation delivery toward sovereign and hybrid architectures. UiPath sustains technology leadership in robotic process automation orchestration for enterprise clients. IBM anchors its competitive stance through deep vertical integration of Watson AI with legacy enterprise systems. Microsoft leverages Azure cognitive services to compete across natural language processing and computer vision workloads.
Cognitive automation fuses artificial intelligence with robotic process automation to execute judgment-intensive tasks previously requiring human perception, combining machine learning inference engines with structured workflow engines operating at sub-second latency. Its primary commercial purpose is augmenting or replacing human cognitive labor in high-volume, rules-variant business processes. Machine Learning and Natural Language Processing currently occupy the largest technology segments, while Computer Vision is recording the fastest expansion in manufacturing quality assurance and medical imaging. Cloud deployment dominates new implementations, though Hybrid architectures are capturing margin pools from regulated BFSI Institutions and Healthcare Providers requiring data residency controls.
The EU AI Act imposes risk-tiered compliance obligations on automated decision systems deployed in European member states, directly shaping product development roadmaps for vendors seeking market access. The FDA regulates cognitive automation embedded in clinical decision support software through its Software as a Medical Device framework, while China's SAMR enforces algorithmic recommendation provisions under its GB standards regime. Stakeholders must monitor divergence between Brussels' risk-based classification and Washington's sector-specific enforcement to anticipate certification costs and market entry sequencing.
Market Dynamics
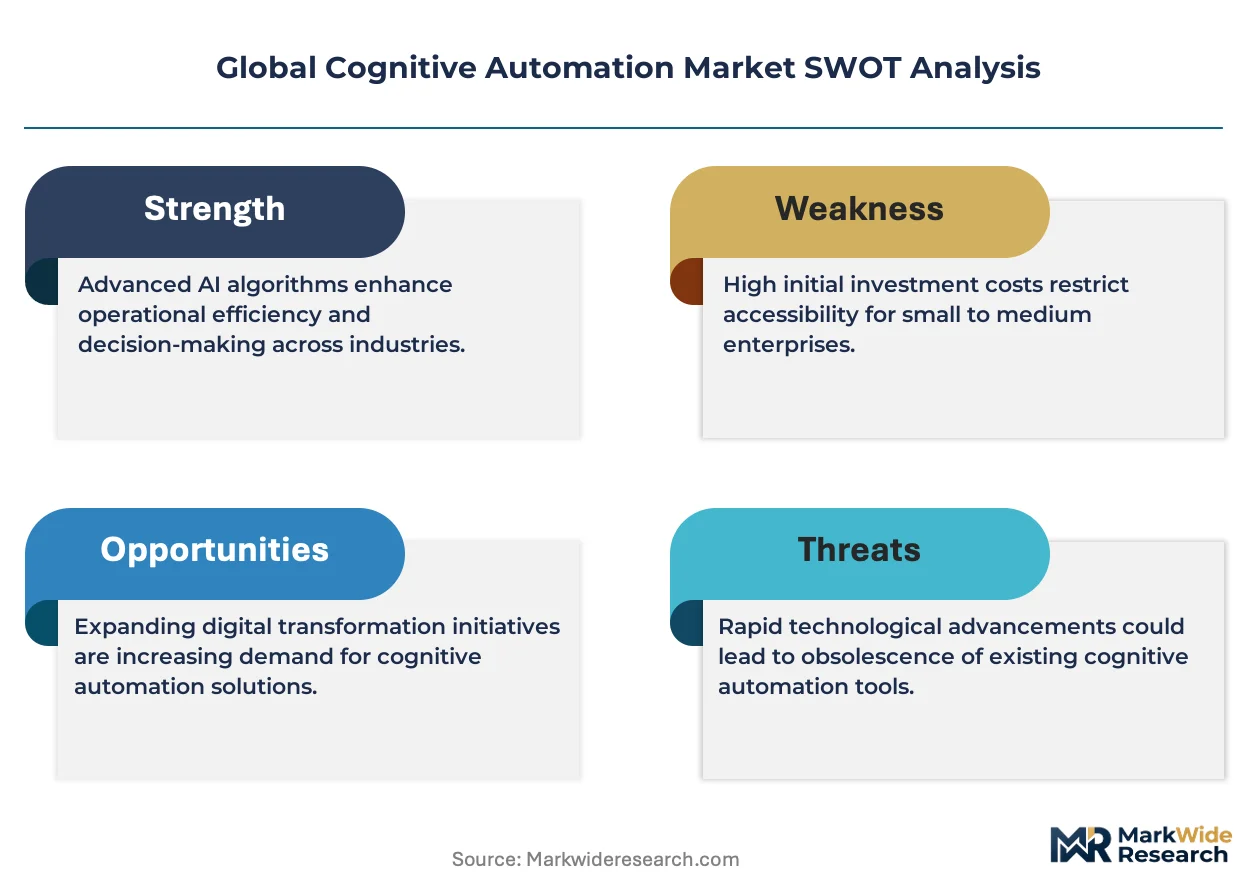
The EU AI Act's risk-tiered compliance framework is forcing vendors to rearchitect product roadmaps around algorithmic transparency mandates, while enterprise buyers simultaneously demand sovereign cloud deployments that fragment previously centralized delivery models.
Growth Catalysts
- Clinical Decision Support Expansion:Healthcare Providers in the United States are embedding cognitive automation into diagnostic workflows under FDA Software as a Medical Device guidelines, creating pull for validated AI inference engines.
- EU AI Act Compliance Services:European enterprises facing high-risk system classification obligations are procuring automated audit and documentation tools, generating secondary revenue streams for workflow orchestration vendors.
- Optical Character Recognition Fusion:Manufacturing quality assurance lines are integrating computer vision with legacy RPA bots to automate defect detection at sub-second latency without human inspection loops.
Market Restraints
- Graphics Processing Unit Supply Concentration:Training and inference workloads depend on Taiwan Semiconductor Manufacturing Company fabrication capacity, exposing deployment timelines to geopolitical friction in advanced node access.
- Cross-Border Data Localization Requirements:China's SAMR algorithmic recommendation provisions and EU GDPR Article 44 transfer mechanisms impose conflicting architectural constraints on multi-national rollout strategies.
- Structured Data Dependency:Cognitive automation performance degrades sharply in environments lacking digitized process histories, limiting addressable market in legacy-heavy industrial verticals.
Strategic Opportunities
- India's PLI Scheme for Electronics Manufacturing:Contract manufacturers establishing capacity under production-linked incentives are prime targets for quality assurance automation deployment at greenfield facilities.
- Natural Language Processing-Computer Vision Convergence:Multimodal systems that simultaneously parse documents and visual inputs are opening claims processing and underwriting automation in property and casualty insurance.
- Japan's METI AI Governance Guidelines:Voluntary framework adoption by Keidanren member corporations is creating demand for explainability tooling that vendors can productize across Asia-Pacific markets.
Industry Challenges
- Machine Learning Operations Talent Scarcity:Enterprises lack personnel capable of maintaining model drift monitoring and retraining pipelines, forcing reliance on vendor-managed services that compress margins.
- Legacy Enterprise Resource Planning Integration Complexity:SAP and Oracle system environments require custom connector development that extends implementation timelines and inflates professional services costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cognitive Automation Market |
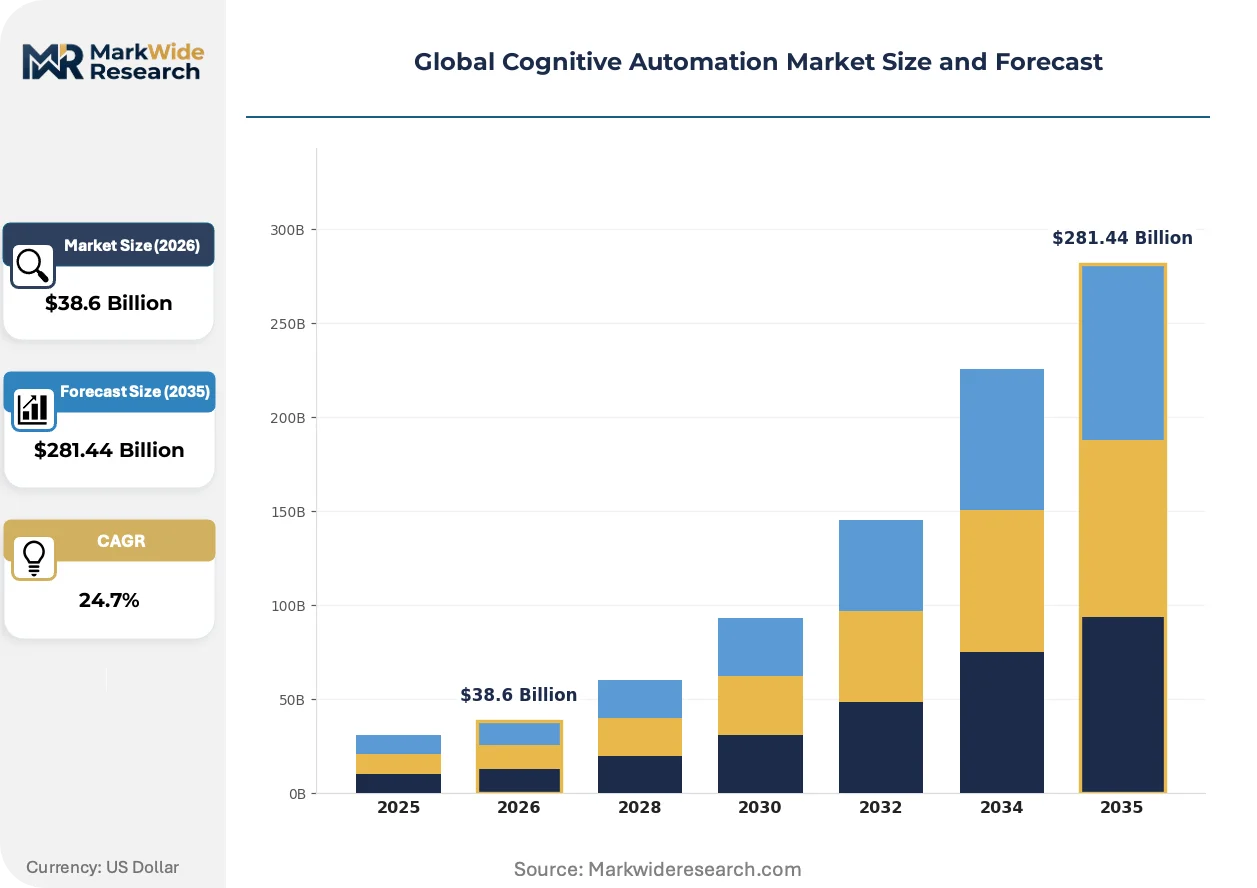
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $281.44 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Natural Language Processing, Computer Vision, Robotics Process Automation, Neural Networks Application: Customer Support, Fraud Detection, Document Processing, Workforce Management, Predictive Analytics Deployment: On-Premises, Cloud, Hybrid, Edge, Virtual Environments End User: BFSI Institutions, Telecom Operators, Healthcare Providers, Manufacturing Units, Government Agencies |
| Companies Covered | IBM, Blue Prism, UiPath, Kofax, NICE Systems, Automation Anywhere, Pegasystems, Accenture, Microsoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cognitive Automation Market Shifts & Advancements
Foundation model architectures are compressing development cycles for cognitive automation applications, while regulatory pressure on algorithmic transparency accelerates investment in explainability tooling and audit infrastructure.
Retrieval-augmented generation is modularizing knowledge access for enterprise automation platforms. Healthcare Providers and Financial Services institutions are deploying these architectures to ground large language model outputs in proprietary document corpora without retraining. This approach is modularizing previously monolithic cognitive engines into composable components that buyers can license separately.
The EU AI Act's high-risk system obligations are mandating conformity assessments for automated decision systems deployed in European member states. Vendors must now maintain technical documentation, human oversight protocols, and accuracy metrics that satisfy notified body review. Medical device manufacturers and credit scoring platforms face the steepest compliance burden, with many restructuring product tiers to fall below high-risk thresholds.
Enterprise buyers are unbundling automation software from implementation services, preferring to retain system integrator relationships separately from platform licensing. This pattern concentrates in the United States, where mature procurement functions have built internal centers of excellence for bot development. Vendors responding with pure-play subscription pricing are capturing margin from competitors locked into legacy bundled models.
Global Cognitive Automation Market Segmentation
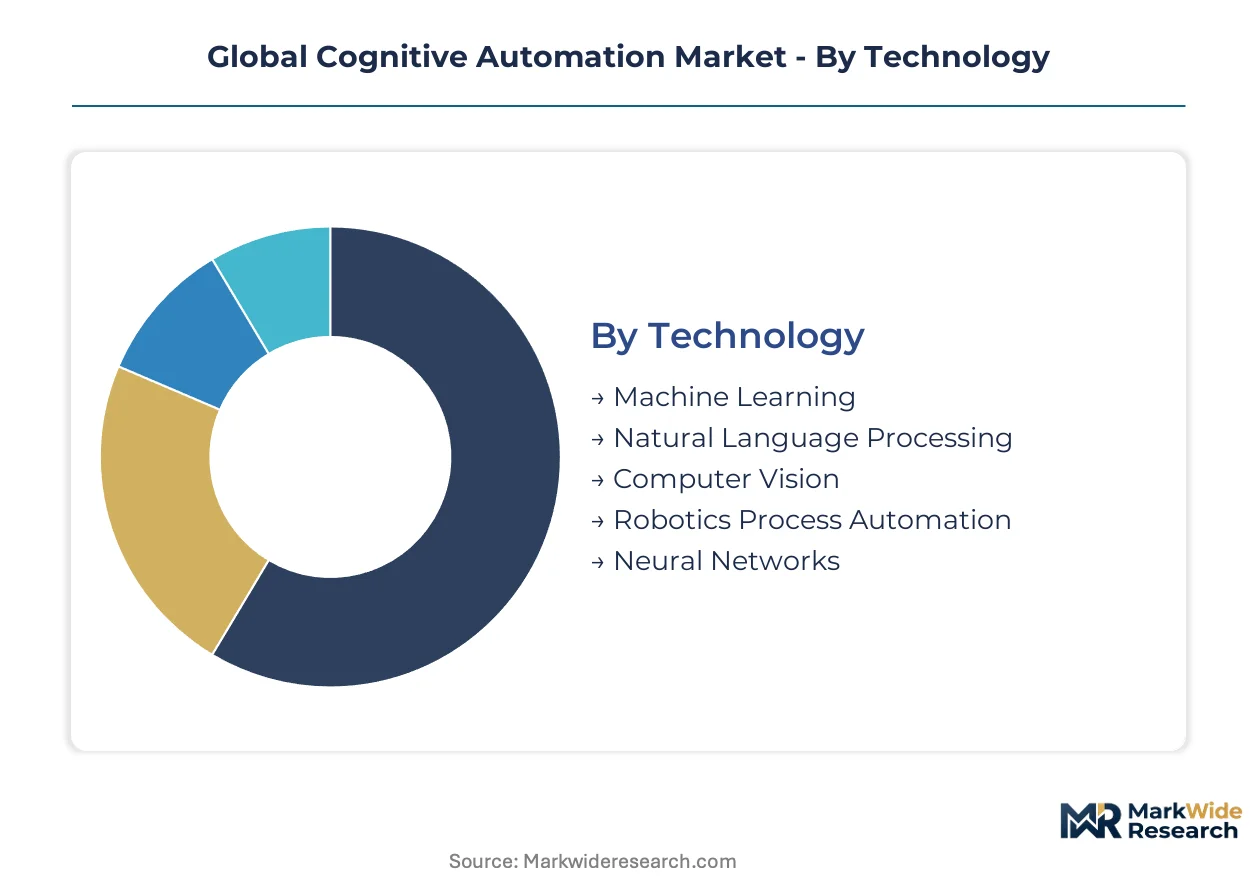
Cognitive automation vendors architect product portfolios around distinct technology stacks and deployment topologies. Segmentation reveals where margin pools concentrate versus where standardization pressures dominate procurement decisions.
Technology:
Technology selection determines inference latency, training data requirements, and regulatory audit complexity for automated decision systems.
- Machine Learning:Statistical inference engines process structured historical data to classify outcomes and predict probabilities. BFSI Institutions in the United States deploy these systems for credit risk scoring under Federal Reserve supervisory guidance.
- Natural Language Processing:Transformer architectures parse unstructured text for sentiment extraction, entity recognition, and document summarization. Healthcare Providers embed NLP into clinical documentation workflows to reduce physician administrative burden.
- Computer Vision:Convolutional neural networks classify visual inputs for defect detection and biometric verification. Manufacturing quality assurance lines in Germany and Japan integrate these systems at sub-second inspection speeds.
- Robotics Process Automation:Rule-based bots execute repetitive UI interactions across legacy enterprise applications. Back-office functions in insurance claims processing represent mature deployment territory.
- Neural Networks:Deep learning architectures enable multimodal fusion across text, image, and tabular inputs. Emerging applications in autonomous systems and real-time decisioning face steep compute cost barriers.
Mature deployment sits with Natural Language Processing in document-intensive verticals. Newer deployment is concentrated in Computer Vision for manufacturing quality assurance and medical imaging diagnostics.
Application:
Application segmentation tracks where judgment-intensive tasks yield measurable labor substitution economics.
- Customer Support:Conversational AI handles tier-one inquiry resolution across chat, voice, and email channels. Telecom Operators in India and Brazil deploy these systems to manage subscriber volume at fractional human cost.
- Fraud Detection:Anomaly detection models flag transaction patterns deviating from behavioral baselines. Real-time scoring requirements in payment networks drive sub-100-millisecond inference demands.
- Document Processing:Intelligent document understanding extracts structured data from invoices, contracts, and regulatory filings. Financial services procurement concentrates here for Know Your Customer automation.
- Workforce Management:Scheduling optimization and performance analytics automate managerial coordination tasks. Retail and logistics operations deploy these for shift planning across distributed workforces.
- Predictive Analytics:Forecasting models project demand, churn, and equipment failure probabilities. Manufacturing predictive maintenance applications are gaining share fastest among industrial end users.
Revenue concentration favors Document Processing in regulated financial services. Fastest expansion is occurring in Fraud Detection as real-time payment rails proliferate across jurisdictions.
Deployment:
Deployment topology selection reflects data residency requirements, latency constraints, and capital expenditure preferences.
- On-Premises:Dedicated hardware installations within enterprise data centers satisfy air-gapped security mandates. Defense contractors and classified government facilities maintain this architecture despite higher total cost of ownership.
- Cloud:Hyperscaler-managed infrastructure delivers elastic compute for training and inference workloads. Startups and mid-market enterprises default here to avoid data center capital commitments.
- Hybrid:Split architectures keep sensitive data on-premises while bursting compute to cloud resources. Healthcare Providers facing HIPAA obligations and EU GDPR constraints increasingly specify this model.
- Edge:Distributed inference nodes process data at network periphery to minimize round-trip latency. Manufacturing quality lines and autonomous vehicle systems require millisecond-response decisioning.
- Virtual Environments:Containerized and sandboxed deployments isolate automation workloads for security compliance. Software vendors seeking FedRAMP authorization adopt this pattern for federal agency sales.
Procurement volume concentrates in Cloud deployments for new implementations. Hybrid architectures are capturing margin from regulated BFSI Institutions and Healthcare Providers requiring data residency controls.
End User:
End user segmentation reveals vertical-specific compliance burdens and workflow integration complexity.
- BFSI Institutions:Banks, insurers, and asset managers deploy cognitive automation for compliance reporting, claims processing, and algorithmic trading surveillance. EU AI Act high-risk system classifications apply to credit scoring and insurance pricing automation.
- Telecom Operators:Subscriber management, network optimization, and field service dispatch represent primary automation targets. Emerging market operators lead adoption for cost competitiveness.
- Healthcare Providers:Hospitals and clinics embed clinical decision support and revenue cycle automation. FDA Software as a Medical Device framework governs diagnostic AI deployment in the United States.
- Manufacturing Units:Quality assurance, supply chain planning, and predictive maintenance drive computer vision and forecasting demand. India's PLI scheme beneficiaries represent greenfield automation opportunities.
- Government Agencies:Tax administration, benefits eligibility, and procurement automation face stringent transparency requirements. Explainability tooling investments concentrate here for algorithmic accountability mandates.
Implementation maturity sits with BFSI Institutions following decades of back-office automation investment. Steepest expansion trajectory belongs to Healthcare Providers integrating FDA-validated diagnostic support systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's hyperscaler concentration anchors cognitive automation software development, while enterprise procurement concentrates across five national markets with divergent regulatory architectures.
United States
FDA Software as a Medical Device guidelines drive healthcare provider adoption of diagnostic AI, while Federal Reserve supervisory guidance shapes BFSI credit risk automation. HIPAA obligations and state-level privacy laws fragment cloud deployment strategies. New York and Boston financial centers concentrate document processing automation for Know Your Customer compliance.
Germany
Manufacturing quality assurance lines in automotive and industrial machinery sectors deploy computer vision at sub-second inspection speeds. EU AI Act high-risk system classifications force algorithmic transparency investments. Stuttgart and Munich industrial clusters anchor predictive maintenance automation for Mittelstand exporters.
China
SAMR algorithmic recommendation provisions and GB standards enforce data localization for automated decision systems. Manufacturing units under dual carbon goals deploy cognitive automation for energy optimization. Shenzhen and Shanghai technology corridors concentrate multimodal AI development for smart city applications.
India
PLI scheme beneficiaries establishing electronics manufacturing capacity represent greenfield automation targets. RBI and SEBI guidelines shape BFSI compliance automation procurement. Bengaluru and Hyderabad technology hubs concentrate NLP development for customer support and document processing outsourcing.
Japan
METI AI Governance Guidelines create demand for explainability tooling among Keidanren member corporations. Aging demographics accelerate healthcare provider automation for clinical documentation. Nagoya industrial belt integrates cognitive automation into automotive supply chain quality assurance.
Global Cognitive Automation Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue sovereign cloud and edge deployment architectures. The vendor landscape fragments across three maturity tiers: legacy enterprise systems integrators, pure-play automation specialists, and hyperscaler platform providers. Strategic archetypes include vertical-integrated AI stack owners, workflow orchestration pure-plays, and consulting-led implementation bundlers. Dominant competitive moves center on M&A for ML operations talent and strategic partnerships for sovereign cloud infrastructure.
Within the enterprise systems integrator tier, IBM and Accenture exemplify vertical integration strategies that embed cognitive automation into legacy ERP environments. UiPath occupies a position among pure-play orchestration specialists focused on robotic process automation scalability. Microsoft anchors the hyperscaler platform vector through Azure cognitive services integration across natural language processing and computer vision workloads.
| Leading Market Players |
|---|
| IBM |
| Blue Prism |
| UiPath |
| Kofax |
| NICE Systems |
| Automation Anywhere |
| Pegasystems |
| Accenture |
| Microsoft |
| Others |
Supply & Pricing Matrix
Healthcare Providers and BFSI Institutions command pricing leverage through volume procurement of cognitive automation platforms, compressing margins for vendors locked into bundled implementation models while rewarding pure-play subscription architectures.
Pricing Analysis
Warranty and service bundling separates enterprise-grade cognitive automation contracts from self-managed deployments, with UiPath and Automation Anywhere unbundling implementation services to capture margin from legacy integrators. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade for FDA-validated diagnostic AI versus unvalidated workflow bots. Pricing pressure stems from hyperscaler platform competition as Microsoft Azure cognitive services commoditize natural language processing APIs. Mid-market enterprises exhibit highest price sensitivity, while defense contractors and classified government facilities absorb premium for air-gapped on-premises installations.
Supply Chain Analysis
Freight and logistics costs for GPU-accelerated hardware concentrate supply risk in Taiwan, South Korea, and United States fabrication corridors serving training and inference workloads. NVIDIA and AMD accelerator cards draw from TSMC advanced node capacity, while memory modules source from Samsung and SK Hynix facilities. Single-source vulnerability in Taiwan Semiconductor Manufacturing Company exposure threatens deployment timelines for healthcare AI and fraud detection systems requiring sub-100-millisecond inference. Distribution runs through hyperscaler cloud marketplaces, direct enterprise sales teams, and systems integrator channels serving regulated verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from EU AI Act compliance costs will eliminate vendors lacking automated audit infrastructure, favoring incumbents with notified body relationships and documented accuracy metrics.
For Market Incumbents: Hedge against hyperscaler platform commoditization by deepening Watson AI and Azure cognitive services integration into SAP and Oracle legacy environments. Acquire ML operations talent to maintain model drift monitoring pipelines that enterprise buyers cannot staff internally. Defensive consolidation through workflow orchestration pure-plays protects margin from unbundling trends in United States procurement.
For New Entrants and Emerging Players: India's PLI scheme electronics manufacturers represent an underserved buyer archetype seeking greenfield quality assurance automation without legacy ERP integration burden. Target sovereign cloud deployments for European Healthcare Providers facing GDPR Article 44 transfer constraints. Lead with edge inference appliances for manufacturing quality lines requiring millisecond-response defect detection outside hyperscaler latency zones.
For Investors and Strategic Acquirers: The window for entry favors explainability tooling specialists serving EU AI Act high-risk system obligations and Japan METI governance guideline adopters. Long-term viability hinges on regulatory certification moats rather than model performance alone. Watch for FDA Software as a Medical Device framework expansion into clinical decision support as inflection signal for diagnostic AI valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of ML Operations Specialist | Addresses talent scarcity forcing vendor-managed service reliance and margin compression. |
| Sovereign Cloud Infrastructure Partnership | Captures Healthcare Provider and BFSI procurement requiring data residency under EU AI Act. |
| FDA SaMD Validation Pathway Investment | Unlocks diagnostic AI revenue from United States hospitals under federal supervision. |
| Retrieval-Augmented Generation Productization | Modularizes knowledge access for Financial Services document processing without retraining costs. |
| Edge Inference Hardware Development | Serves manufacturing quality lines in Germany and Japan demanding sub-second inspection latency. |
Research Methodology
Independent corroboration across CTOs at Healthcare Providers, IT procurement officers at BFSI Institutions, platform engineers at hyperscalers, and integration specialists at systems integrators underwrites the qualitative findings. Secondary validation draws from FDA Software as a Medical Device filings, EU AI Act notified body documentation, SEC 10-K hyperscaler capex disclosures, and hospital procurement databases. Bottom-up deployment estimates triangulate against top-down enterprise digital transformation budget allocations across the analysis window.
Historical reference periods anchor the forecast framework to pre-pandemic automation adoption baselines and post-EU AI Act compliance investment surges. Segmentation dimensions model technology stack selection, deployment topology preference, end-user vertical compliance burden, and regional regulatory cluster divergence. CAGRs derive from elasticity-adjusted adoption curves incorporating GPU supply constraints and sovereign cloud infrastructure buildout timelines. Foundation model compression cycles and retrieval-augmented generation modularization serve as technology-specific forecast inputs.
Revisions become necessary when Taiwan Semiconductor Manufacturing Company advanced node access restrictions materialize or when EU AI Act high-risk system classifications expand beyond credit scoring and medical devices. Forecasts reflect assumptions about regulatory harmonization timelines and enterprise talent pipeline recovery. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Conversational AI Market
Artificial Intelligence (AI)
Aiops Market
Artificial Intelligence (AI)
Artificial Intelligence Platform Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) Software Market
Artificial Intelligence (AI)
Enterprise LLM Market
Artificial Intelligence (AI)
Cognitive Collaboration Market
Artificial Intelligence (AI)
Industrial AI Software Market
Artificial Intelligence (AI)
AI Mirror Market
Artificial Intelligence (AI)
Europe Synthetic Data Generation Market
Artificial Intelligence (AI)
Enterprise Generative AI Market
Artificial Intelligence (AI)
Explainable AI Market
Artificial Intelligence (AI)
Global Aiops Platform Market
Artificial Intelligence (AI)
Global Legaltech Artificial Intelligence (AI) Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Sports Market
Artificial Intelligence (AI)
United States Artificial Intelligence Market
Artificial Intelligence (AI)
Global Deep Learning Neural Networks (Dnns) Market