
 Palletizing Robots Market | 2026-2036
Palletizing Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Palletizing Robots Market Outlook
The performance gap between high-speed articulated systems and entry-level Cartesian units is repositioning procurement criteria across end-user segments. FANUC Corporation leverages its servo-motor integration to sustain premium positioning in automotive palletizing cells. ABB Ltd. anchors European demand through its software-agnostic controller architecture that spans food and beverage installations.
Palletizing robots are programmable manipulator arms designed to stack products onto pallets with repeatability typically rated at ±0.5 mm and payload capacities ranging from 5 kg to over 800 kg; they execute layer-forming, slip-sheet insertion, and load stabilization to streamline outbound logistics in manufacturing and distribution environments. Articulated robots dominate heavy-payload applications where six-axis flexibility handles heterogeneous case sizes, while collaborative robots are capturing mid-volume food and beverage lines where ISO/TS 15066 safety protocols permit reduced guarding. Vision systems within the technology segment are concentrating margin pools as end users demand barcode-verified layer patterns and real-time defect rejection.
FDA food-contact surface regulations and OSHA machine-guarding standards shape North American equipment specifications, while CE marking under the EU Machinery Directive governs European market access and forces redesigns of collaborative robot force-limiting mechanisms. ISO 10218-1 and ISO/TS 15066 create transnational baselines for safety-rated monitored stops and power-force limiting that manufacturers must embed at the controller level. Stakeholders should track how AI-driven predictive maintenance modules shift total cost of ownership calculations against traditional preventive service contracts.
Market Dynamics
The performance gap between high-speed articulated systems and entry-level Cartesian units is repositioning procurement criteria across end-user segments, forcing buyers to trade off payload flexibility against footprint constraints and integration speed.
Growth Catalysts
- ISO 10218-1 safety mandates:Transnational baselines for safety-rated monitored stops are accelerating retrofit demand in automotive plants seeking collaborative robot deployments without full guarding enclosures.
- Food and beverage throughput targets:Manufacturers are expanding automated palletizing to meet outbound logistics volumes, particularly in dairy and baked goods segments where case heterogeneity demands six-axis flexibility.
- Servo-motor integration advances:Tighter controller-motor coupling is reducing cycle times in high-payload cells, enabling layer-forming precision that meets pharmaceutical serialization requirements.
Market Restraints
- CE marking redesign costs:EU Machinery Directive compliance is forcing collaborative robot force-limiting mechanism redesigns, extending time-to-market for European launches by 8-14 months.
- Harmonic drive supply concentration:Precision gear component sourcing clusters in Japanese and German supplier bases, exposing lead time volatility for mid-volume robot OEMs.
- Technical limitation in vision-lag:Real-time defect rejection at line speeds above 120 cases per minute remains constrained by processing latency in mid-tier vision systems.
Strategic Opportunities
- Underpenetrated cold-chain logistics:Frozen food distribution centers in the United States are deploying collaborative palletizers for mixed-SKU handling where temperature-rated guarding is cost-prohibitive.
- AI-driven predictive maintenance convergence:Machine learning modules trained on vibration and torque signatures are shifting total cost of ownership calculations against traditional preventive service contracts.
- Pharmaceutical serialization tailwinds:FDA track-and-trace mandates are creating verified layer-pattern requirements that vision-integrated palletizers uniquely satisfy.
Industry Challenges
- Controls integration skill scarcity:PLC programming and safety controller configuration expertise is concentrating among integrators in Germany and Japan, inflating deployment costs for first-time adopters.
- Legacy line retrofit complexity:Brownfield automotive plants face conveyor synchronization and spatial constraints when inserting six-axis units into fixed-rhythm assembly environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Palletizing Robots Market |
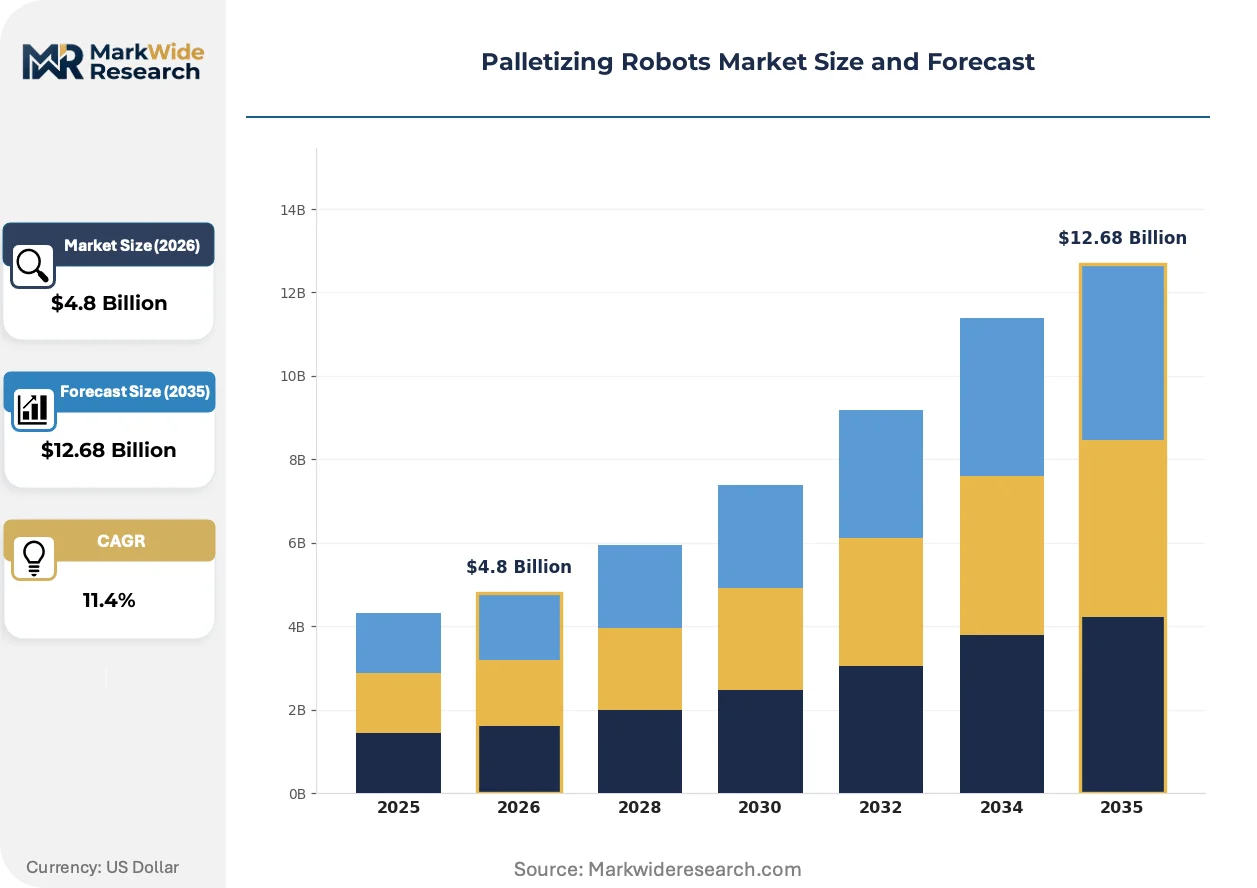
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
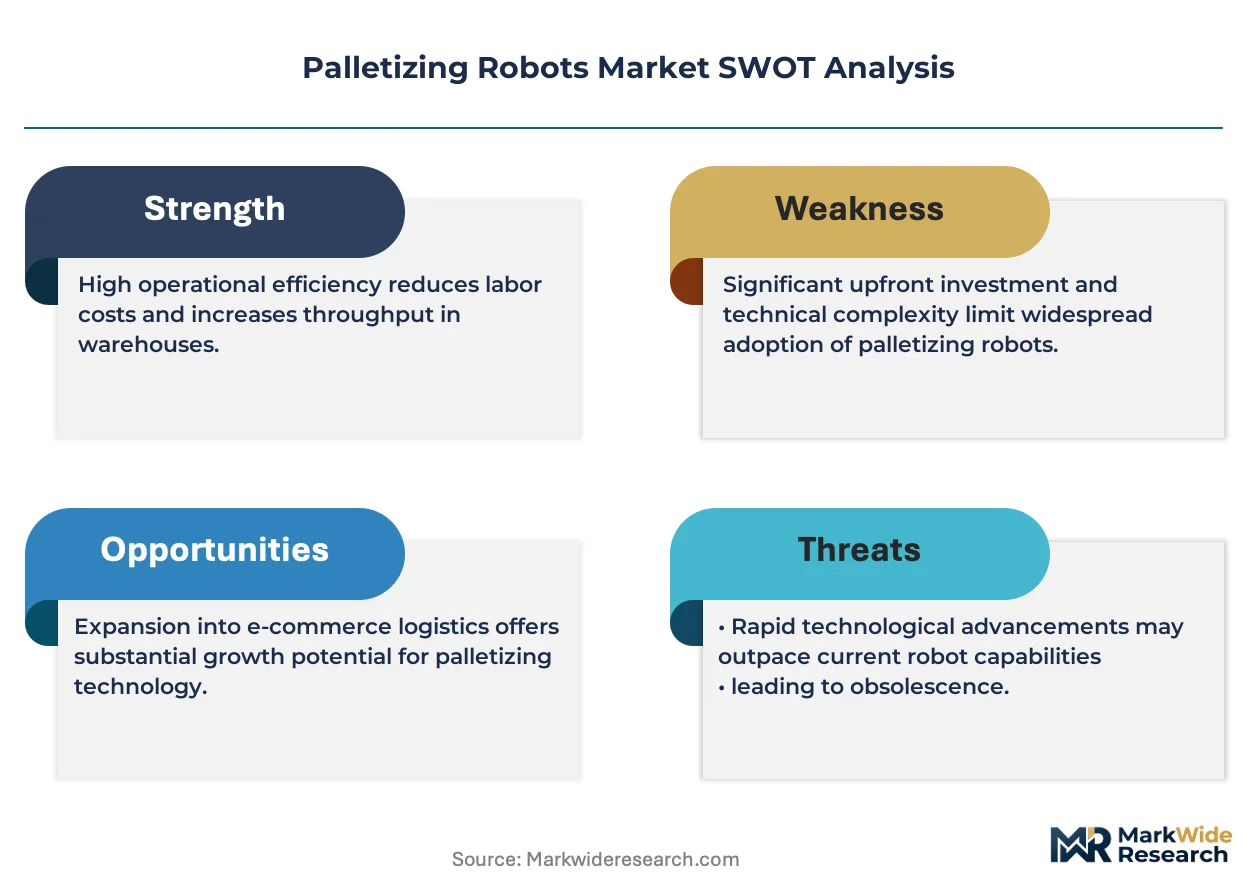
| Segmentation | Product Type: Articulated Robots, Cartesian Robots, Collaborative Robots, Delta Robots Application: Food & Beverage, Consumer Goods, Pharmaceuticals, Electronics End User: Manufacturers, Warehouses, Distribution Centers, Retailers Technology: Vision Systems, AI & Machine Learning, Sensor Integration, Software Solutions |
| Companies Covered | FANUC Corporation, ABB Ltd., KUKA AG, Yaskawa Electric Corporation, Kawasaki Heavy Industries Ltd., Mitsubishi Electric Corporation, KION GROUP AG, Universal Robots A/S, Krones AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Palletizing Robots Market Strategic Shifts
Vision-guided layer formation is compressing the boundary between palletizing and quality inspection, while force-limited collaborative architectures are rewriting safety-zone economics for mid-volume operations.
Adaptive gripping technology using vacuum and mechanical hybrid end-effectors is expanding into food and beverage lines handling irregular case geometries. Dairy processors are adopting these systems at pilot scale to reduce changeover downtime between SKU formats. The technology is expanding into applications previously reserved for fixed-format dedicated tooling, compressing the viable market for single-purpose mechanical grippers.
EU Machinery Directive amendments governing collaborative robot force-limiting are tightening maximum permissible pressure thresholds in human-robot shared workspaces. Industrial consequence includes mandatory recertification of installed collaborative palletizers in European automotive and logistics facilities. Food and beverage end-users in Germany and France are responding by accelerating purchases of safety-rated monitored stop systems ahead of enforcement windows.
Service contract unbundling is separating hardware purchase from predictive maintenance subscriptions, with buyers in the United States negotiating per-cycle uptime guarantees rather than annual preventive visit schedules. System integrators are displacing traditional OEM service departments as the primary maintenance channel. This shift is most visible in automotive tier-one supplier plants where total cost of ownership scrutiny has intensified.
Palletizing Robots Market Segmentation
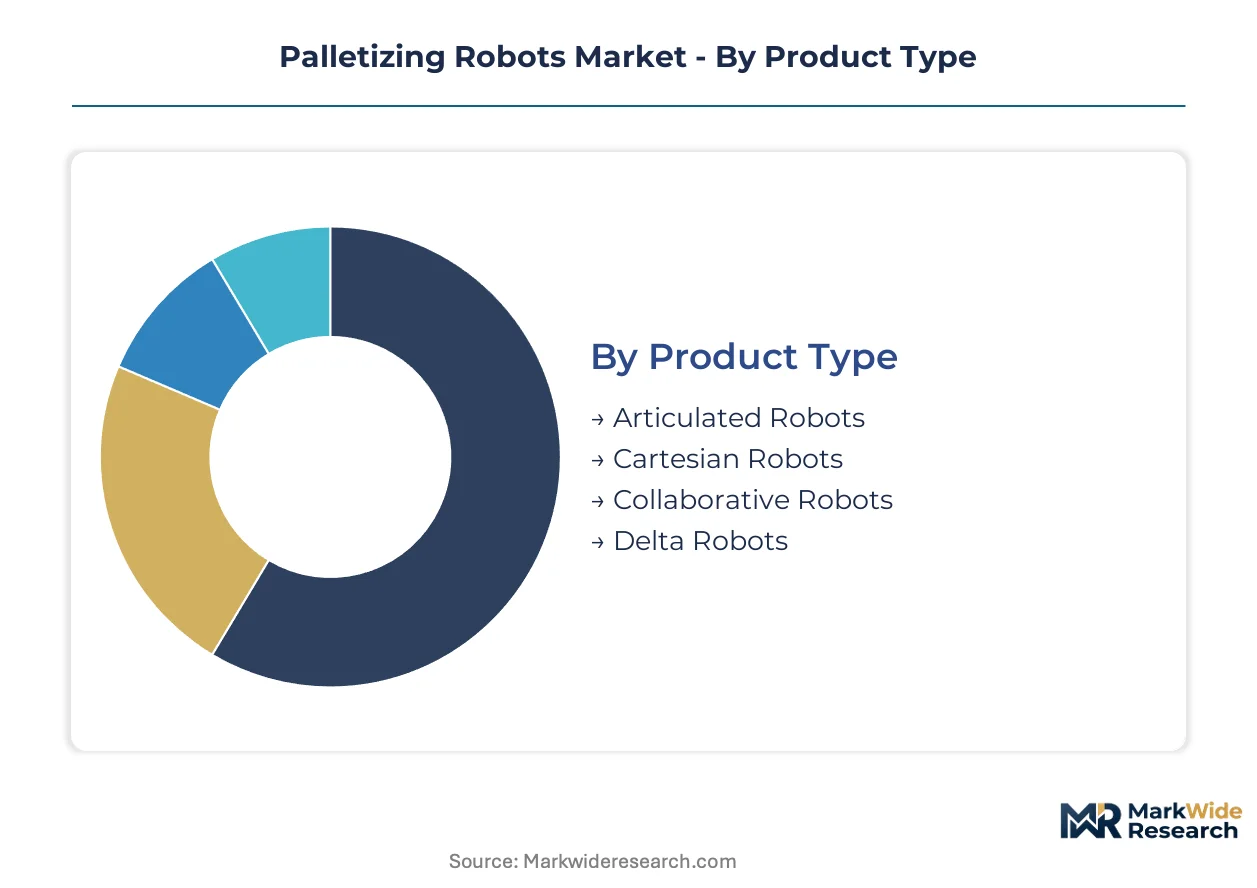
Palletizing robot procurement diverges sharply between standardized high-volume deployments and customized cells engineered for heterogeneous handling. Understanding where flexibility premiums apply versus where commodity specifications dominate separates efficient capital allocation from overspending on unused capability.
Product Type:
Customization intensity spans from fully configurable six-axis architectures to fixed-gantry Cartesian systems with minimal parameter adjustment.
- Articulated Robots:Six-axis configurations deliver payload capacities exceeding 800 kg with ±0.5 mm repeatability. Automotive manufacturers in Germany and the United States deploy these units for mixed-case handling where layer patterns vary by SKU.
- Cartesian Robots:Linear-axis designs optimize footprint efficiency in high-throughput lines with uniform case dimensions. Food and beverage plants favor these systems for single-format dairy and baked goods palletizing where speed outweighs flexibility requirements.
- Collaborative Robots:Force-limited architectures with ISO/TS 15066 compliance enable reduced guarding in mid-volume operations.
- Delta Robots:Parallel kinematic structures excel in lightweight, high-speed pick-and-place preceding pallet formation.
Most installed capacity flows through Articulated Robots. Expansion is steepest in Collaborative Robots.
Application:
Margin capture potential correlates with regulatory stringency and serialization requirements across end-use verticals.
- Food & Beverage:FDA food-contact surface regulations and cold-chain integrity demands shape equipment specifications. Dairy processors in France and frozen distribution centers in the United States drive adoption of temperature-rated collaborative systems.
- Pharmaceuticals:FDA track-and-trace mandates and EU FMD serialization requirements create verified layer-pattern specifications that vision-integrated palletizers uniquely satisfy. German and Swiss facilities lead deployment density.
- Consumer Goods:Seasonal volume spikes and promotional packaging variety favor flexible reconfiguration capabilities.
- Electronics:ESD-sensitive handling and compact footprint constraints define procurement criteria for semiconductor and consumer electronics assembly environments.
Food & Beverage holds the largest installed base. Pharmaceuticals is climbing the fastest as serialization deadlines tighten.
End User:
Integration complexity and in-house technical capability determine whether buyers self-deploy or rely on system integrators.
- Manufacturers:Brownfield automotive plants in Germany and Japan face conveyor synchronization challenges when retrofitting six-axis units into fixed-rhythm assembly lines.
- Warehouses:Mixed-SKU handling requirements in United States cold-chain facilities favor collaborative architectures where temperature-rated guarding is cost-prohibitive.
- Distribution Centers:Throughput targets and seasonal volatility drive demand for rapid reconfiguration between case formats.
- Retailers:Store-specific pallet configuration requirements and direct-to-store delivery models create decentralized deployment patterns.
Manufacturers account for the majority of legacy deployments. Warehouses are gaining share fastest as e-commerce fulfillment reshapes logistics networks.
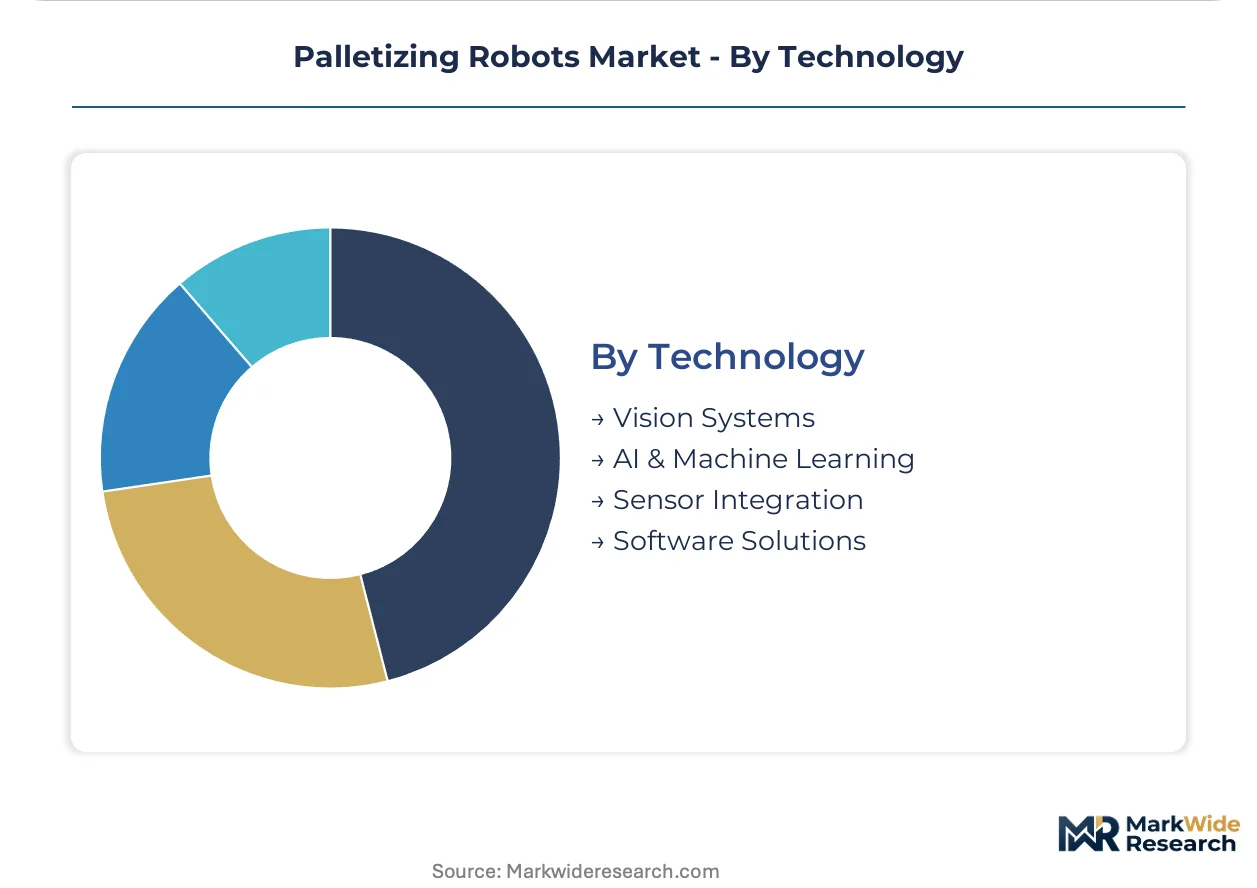
Technology:
Component modularity versus integrated system architecture defines competitive positioning among technology suppliers.
- Vision Systems:Barcode-verified layer patterns and real-time defect rejection concentrate margin pools as processing latency constraints ease in premium-tier implementations. Pharmaceutical serialization applications in Germany and the United States drive specification intensity.
- AI & Machine Learning:Predictive maintenance modules trained on vibration and torque signatures shift total cost of ownership calculations against traditional preventive service contracts in automotive tier-one supplier plants.
- Sensor Integration:Force-torque and proximity sensing enable collaborative safety protocols without full enclosure requirements.
- Software Solutions:Controller-agnostic programming environments reduce integration friction for multi-vendor installations.
Vision Systems command the deepest integration into high-value applications. AI & Machine Learning is expanding most quickly as service contract unbundling accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Systems integration expertise clusters in Germany and Japan, while automotive and logistics end-users in China and the United States drive retrofit demand for legacy production lines.
Germany
Automotive manufacturers in Bavaria and Baden-Württemberg deploy six-axis articulated units for mixed-case handling where layer patterns vary by SKU. CE marking under the EU Machinery Directive forces collaborative robot force-limiting mechanism redesigns, extending time-to-market for European launches. Stuttgart and Munich anchor the densest concentration of automotive tier-one supplier plants integrating vision-verified palletizing cells.
China
Domestic logistics operators and e-commerce fulfillment centers scale collaborative deployments for mixed-SKU handling in temperature-variable environments. GB standards issued by SAMR govern safety-rated monitored stops and power-force limiting requirements for human-robot shared workspaces. The Yangtze River Delta manufacturing corridor, particularly Shanghai and Suzhou, hosts the fastest expansion of pharmaceutical serialization-driven palletizing installations.
United States
Frozen food distribution centers deploy collaborative palletizers where temperature-rated guarding is cost-prohibitive, while automotive plants retrofit legacy lines for throughput targets. FDA food-contact surface regulations and OSHA machine-guarding standards shape equipment specifications for dairy and baked goods segments. Michigan and Ohio brownfield automotive facilities face conveyor synchronization challenges when inserting six-axis units into fixed-rhythm assembly environments.
Japan
Precision gear component sourcing for harmonic drives concentrates in Japanese supplier bases, exposing lead time volatility for mid-volume robot OEMs. METI industrial automation incentives support collaborative robot adoption in food and beverage lines requiring ISO/TS 15066 compliance. The Chubu region around Nagoya maintains the highest density of servo-motor integration specialists serving automotive palletizing cell manufacturers.
Switzerland
Pharmaceutical serialization requirements under EU FMD mandates create verified layer-pattern specifications that vision-integrated palletizers uniquely satisfy. Swissmedic regulations align with FDA track-and-trace standards, enabling dual-certified equipment deployments. Basel and Zurich anchor pharmaceutical manufacturing clusters where German and Swiss facilities lead deployment density for serialization-compliant palletizing systems.
Palletizing Robots Market Competitive Environment
Top-tier vendors anchor premium-tier positioning through servo-motor integration and software-agnostic controller architectures, while mid-tier specialists compete on footprint efficiency and reduced integration friction. The vendor base stratifies across integrated system providers, component technology suppliers, and application-focused integrators. Two strategic archetypes dominate: vertically integrated industrial automation conglomerates with captive controller and motor production, and collaborative robot specialists emphasizing force-limited safety architectures. Competitive moves concentrate on M&A for vision technology capabilities and strategic partnerships for cold-chain logistics penetration.
Within the integrated industrial automation tier, FANUC Corporation and ABB Ltd. occupy positions exemplifying servo-motor integration depth and software-agnostic controller breadth respectively. KUKA AG represents the European automotive-focused archetype with concentrated exposure to brownfield retrofit demand. Among collaborative robot specialists, Universal Robots A/S anchors the force-limited architecture segment where ISO/TS 15066 compliance enables reduced guarding economics.
| Leading Market Players |
|---|
| FANUC Corporation |
| ABB Ltd. |
| KUKA AG |
| Yaskawa Electric Corporation |
| Kawasaki Heavy Industries Ltd. |
| Mitsubishi Electric Corporation |
| KION GROUP AG |
| Universal Robots A/S |
| Krones AG |
| Others |
Value Chain & Pricing Dynamics
Family-owned precision gear specialists in Japan and Germany anchor component supply for harmonic drives, creating pricing discipline that resists commoditization despite pressure from mid-volume robot OEMs seeking cost-down paths. Their captive production of strain-wave gears ties palletizing robot pricing power to regional manufacturing depth rather than assembly labor arbitrage.
Pricing Analysis
The bundled-vs-unbundled service split now dominates procurement negotiations, with automotive tier-one suppliers in Germany and the United States demanding per-cycle uptime guarantees rather than annual preventive visit schedules. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 10218-1 certification grade and servo-motor integration depth. Cost compression in standard-tier articulated units is intensifying because Chinese logistics operators are scaling domestic collaborative deployments. Food and beverage manufacturers in France and the United States exhibit the sharpest price sensitivity due to seasonal volume volatility, while pharmaceutical facilities in Switzerland and Germany accept premium positioning for vision-verified serialization compliance.
Supply Chain Analysis
Precision gear component supply rests on Japanese and German specialty producers, with strain-wave gear manufacturing clustering in Nagoya and Stuttgart industrial corridors. Controller-motor coupling assemblies draw from South Korean power electronics and Chinese rare-earth magnet processing. Single-source vulnerability in harmonic drive sourcing exposes lead time volatility for mid-volume robot OEMs lacking backward integration into gear production. Distribution runs through system integrators in Bavaria and Michigan who configure safety-rated monitored stop architectures for brownfield automotive retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Palletizing robot margins are expanding through AI-driven predictive maintenance unbundling, which shifts revenue from hardware sales toward recurring software subscriptions and displaces traditional OEM service departments.
For Market Incumbents: To counter collaborative robot specialists capturing mid-volume food and beverage lines, incumbents should deepen backward integration into servo-motor production to sustain cycle-time advantages in high-payload cells. Certification investment in ISO/TS 15066 force-limiting architectures for European automotive facilities ahead of EU Machinery Directive enforcement windows preserves installed-base revenue. For New Entrants and Emerging Players: Enter via underpenetrated cold-chain logistics in United States frozen distribution centers, where temperature-rated guarding costs favor collaborative architectures over conventional six-axis enclosures. Target pharmaceutical serialization applications in Swiss and German facilities where FDA track-and-trace mandates create verified layer-pattern specifications that vision-integrated systems uniquely satisfy. Partner with regional system integrators in Ohio and Michigan to bypass direct sales channel buildout. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier vision technology specialists lacking controller-agnostic software platforms but holding barcode-verification IP for pharmaceutical applications. Long-term viability across the analysis window hinges on predictive maintenance module attach rates displacing preventive service contracts. Monitor AI-driven uptime guarantee penetration in automotive tier-one supplier plants as the inflection signal for subscription revenue durability.| Strategic Initiative | Industry Significance |
|---|---|
| Vision Technology Acquisition | Barcode-verified layer patterns satisfy pharmaceutical serialization mandates in German and Swiss facilities. |
| Predictive Maintenance Platform Launch | Vibration-signature machine learning shifts total cost calculations against traditional OEM service contracts. |
| Cold-Chain Logistics Partnership | Temperature-rated collaborative deployments penetrate United States frozen distribution center networks. |
| Controller-Agnostic Software Integration | Multi-vendor programming environments reduce friction for brownfield automotive retrofit installations. |
| Force-Limiting Safety Certification | ISO/TS 15066 compliance enables reduced guarding economics in mid-volume food and beverage lines. |
Study Parameters
Multiple input streams — interviews with plant engineers and maintenance directors at automotive and food and beverage facilities, aftermarket service heads at system integrators, and OEM procurement teams — were reconciled against SEC filings, customs and trade data for precision gear imports, and ISO certification registries. Bottom-up unit deployment estimates across Germany, China, the United States, Japan, and Switzerland were cross-referenced with top-down capital expenditure disclosures from logistics operators and pharmaceutical manufacturers.
Historical shipment trajectories for articulated, Cartesian, and collaborative robot configurations were cross-referenced against panel input from controller and motor suppliers to anchor growth assumptions across the projection horizon. Segmentation modeling spanned product architecture, application vertical, end-user integration complexity, and technology component modularity. CAGRs were derived from layer-forming throughput requirements and serialization compliance deadlines rather than extrapolated trend fitting.
Inputs from plant-level automation managers and pharmaceutical manufacturing engineers were available through the study window; gaps in real-time collaborative robot deployment data from Chinese e-commerce fulfillment centers introduce uncertainty bands around mid-volume adoption curves. Forecasts reflect assumptions regarding EU Machinery Directive enforcement timing and FDA track-and-trace mandate adherence. Material deviation in harmonic drive supply availability or METI incentive program renewal warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
LAMEA Waste Sorting Robots Market
Robotics and Automation
Telepresence Robot Market
Robotics and Automation
Search and Rescue Robots Market
Robotics and Automation
Simultaneous Localization and Mapping (SLAM) Technology Market
Robotics and Automation
GCC AUV Market
Robotics and Automation
Europe Warehouse Robotics Market
Robotics and Automation
Assistive Robotics Market
Robotics and Automation
Global Robot Teach Pendant Market
Robotics and Automation
Global Robotic Process Automation in Healthcare Market
Robotics and Automation
Japan Articulated Robot Market
Robotics and Automation
Asia-Pacific Data Center Robotics Market
Robotics and Automation
Food Robotics Market
Robotics and Automation
Global Robotics Market
Robotics and Automation
Drone-Based NDT Inspection Systems for Energy and Infrastructure Assets Market
Robotics and Automation
Consumer Robotics Market
Robotics and Automation
Underwater Rescue Robot Market