
 Robotic Tool Changer Market | 2026-2036
Robotic Tool Changer Market Size, Share, and Industry Trends Forecast 2026-2036
Robotic Tool Changer Market Analytics
Modularization of tool changer product lines is broadening buyer choice across mid-tier automation budgets. ATI Industrial Automation leverages its North Carolina manufacturing base to sustain rapid-turn custom configurations for defense and aerospace integrators. Staubli dominates European high-precision applications through its cleanroom-validated tool changer architectures. Schunk specializes in force-torque sensing integration that differentiates its offerings in collaborative robot deployments.
A robotic tool changer is a mechanical device that enables automatic exchange of end-effectors on industrial robots, typically featuring pneumatic locking mechanisms, electrical pass-through contacts rated for signal and power transmission, and compliance with ISO 9409-1 mechanical interface standards to ensure interoperability across robot brands. Its primary purpose is to maximize equipment utilization by allowing a single robot arm to perform sequential operations such as welding, material handling, and quality inspection without manual intervention. The electromechanical technology segment anchors the largest revenue pool due to its precision repeatability in automotive assembly, while the hybrid technology segment is capturing specification share in applications demanding combined pneumatic and electrical utility lines. Among end users, automotive occupies the deepest installed base, whereas healthcare represents the fastest-growing specification frontier as surgical and diagnostic robots adopt sterile tool exchange protocols.
ISO 9409-1 and ISO 10218-2 safety standards shape product design requirements for mechanical interfaces and collaborative operation protocols across all major robot OEM supply chains. The EU Machinery Directive and CE marking requirements enforce validation documentation that filters out non-compliant suppliers from European automation integrator procurement lists. FDA device regulations in the United States impose sterilization compatibility and biocompatibility testing on tool changers intended for surgical robot platforms. Stakeholders must monitor how regional safety standard divergence between ISO frameworks and national implementations affects cross-border system integration costs and supplier qualification timelines.
Market Dynamics
ISO 9409-1 standardization for mechanical interfaces is compressing integration timelines and eroding proprietary lock-in advantages among incumbent suppliers, forcing modular product architectures across the competitive base.
Growth Catalysts
- Automotive mixed-model production:German and Japanese OEMs are mandating automatic tool changer deployment on flexible assembly lines to minimize changeover downtime between vehicle variants.
- ISO 9409-1 adoption:The mechanical interface standard is reducing engineering validation costs for system integrators sourcing multi-brand robot fleets.
- Cleanroom-validated architectures:Semiconductor and pharmaceutical manufacturing in Taiwan and South Korea is pulling tool changers with validated particle containment specifications.
Market Restraints
- High-precision bearing supply concentration:Swiss and German specialty bearing manufacturers control critical input supply for sub-micron repeatability tool changers, creating bottleneck risk.
- CE marking documentation burden:The EU Machinery Directive's validation requirements extend supplier qualification timelines by 4-8 months for non-European entrants.
- Pneumatic-electric hybrid complexity:Dual utility line integration raises failure mode count and service training costs versus single-technology alternatives.
Strategic Opportunities
- Surgical robotics sterilization protocols:FDA device regulations for biocompatibility and autoclave compatibility are creating specification premiums for compliant tool changer suppliers.
- Collaborative robot force-torque integration:Convergence of haptic sensing with tool changer mechanics enables human-robot collaborative cells without safety fencing.
- Indian precision engineering clusters:PLI scheme incentives for automotive component manufacturing are accelerating automation capex in Pune and Chennai industrial corridors.
Industry Challenges
- Mechatronics integration skill scarcity:System integrators face recruitment gaps for engineers capable of calibrating pneumatic locking sequences with electrical signal integrity validation.
- Legacy robot fleet retrofit friction:Pre-ISO 9409-1 robot arms require mechanical adapter engineering that compresses margin on upgrade projects.
- Multi-standard certification sequencing:Suppliers targeting both FDA surgical applications and CE industrial marking face non-overlapping test protocols that extend product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robotic Tool Changer Market |
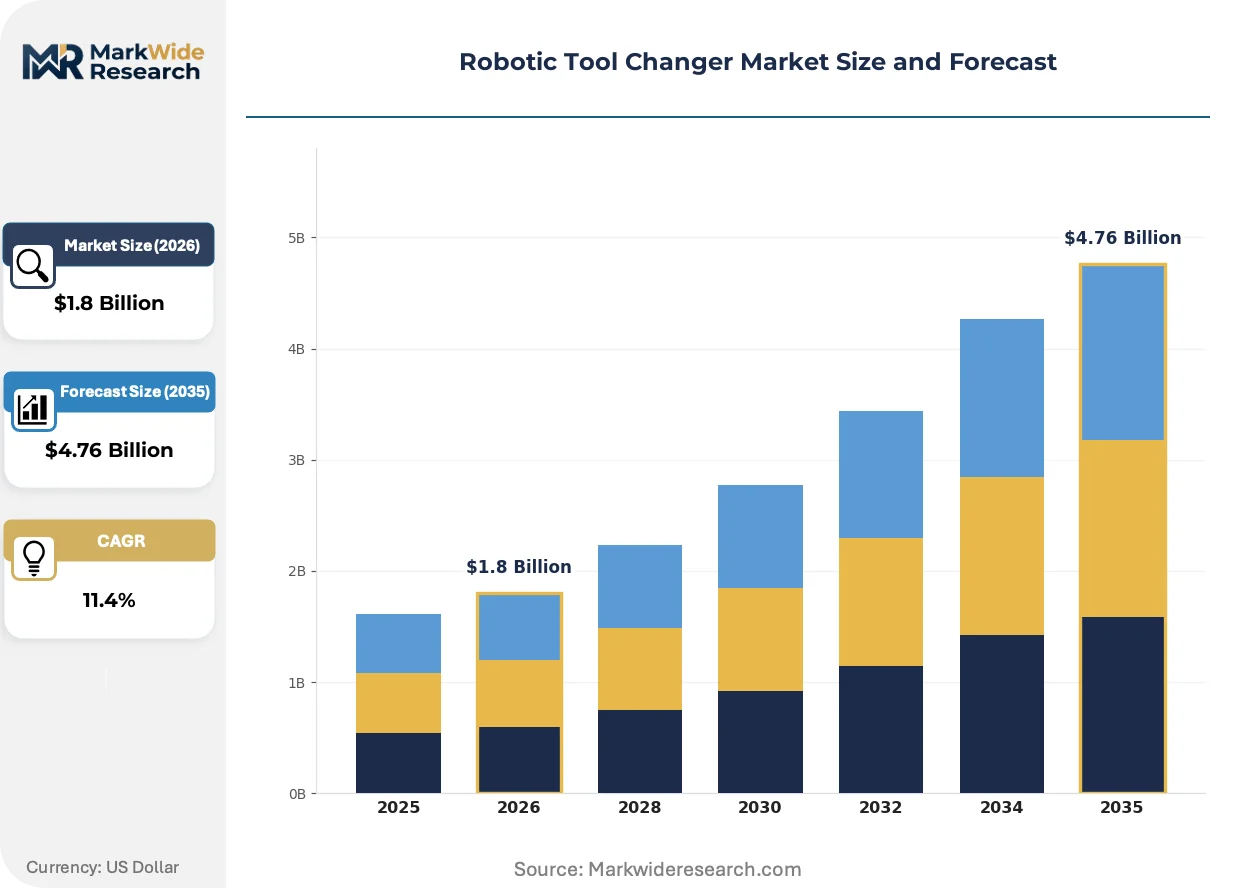
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Manual, Magnetic, Pneumatic Technology: Electromechanical, Hydraulic, Vacuum, Hybrid Application: Manufacturing, Assembly, Packaging, Palletizing End User: Automotive, Electronics, Aerospace, Healthcare |
| Companies Covered | ATI Industrial Automation, Staubli, Schunk, Destaco, Applied Robotics, Robot System Products, Nitta Corporation, AGI Corporation, Zimmer Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robotic Tool Changer Market Evolving Landscape
Tool changer technology is bifurcating between precision-electromechanical systems for automotive volume production and modular hybrid architectures for multi-utility collaborative applications, with regulatory compliance emerging as the primary differentiation vector.
Hybrid pneumatic-electrical tool changer technology is expanding into collaborative robot deployments where combined utility lines reduce cabling complexity. Automotive tier-one suppliers in Germany and Japan are specifying these configurations for mixed-material handling and light assembly sequences. The technology is compressing the traditional separation between material handling and process tool categories, enabling single-arm cells that alternate between gripping and welding operations without manual changeover.
REACH substance restrictions and RoHS compliance deadlines are forcing material substitutions in electrical contact plating and sealing compounds. European tool changer suppliers are reformulating product lines to eliminate restricted substances ahead of 2026 enforcement windows. Medical device and food-contact applications face the tightest substitution timelines, with Swiss and German manufacturers accelerating validation of alternative contact metallurgies.
Specification authority is migrating from robot OEMs to end-user engineering teams with direct ISO 9409-1 compliance verification capabilities. Large automotive and electronics manufacturers in South Korea and Taiwan are bypassing traditional distributor channels to source validated tool changers through direct technical procurement. This shift is compressing aftermarket service margins and forcing suppliers to unbundle hardware from integration support contracts.
Robotic Tool Changer Market Segmentation
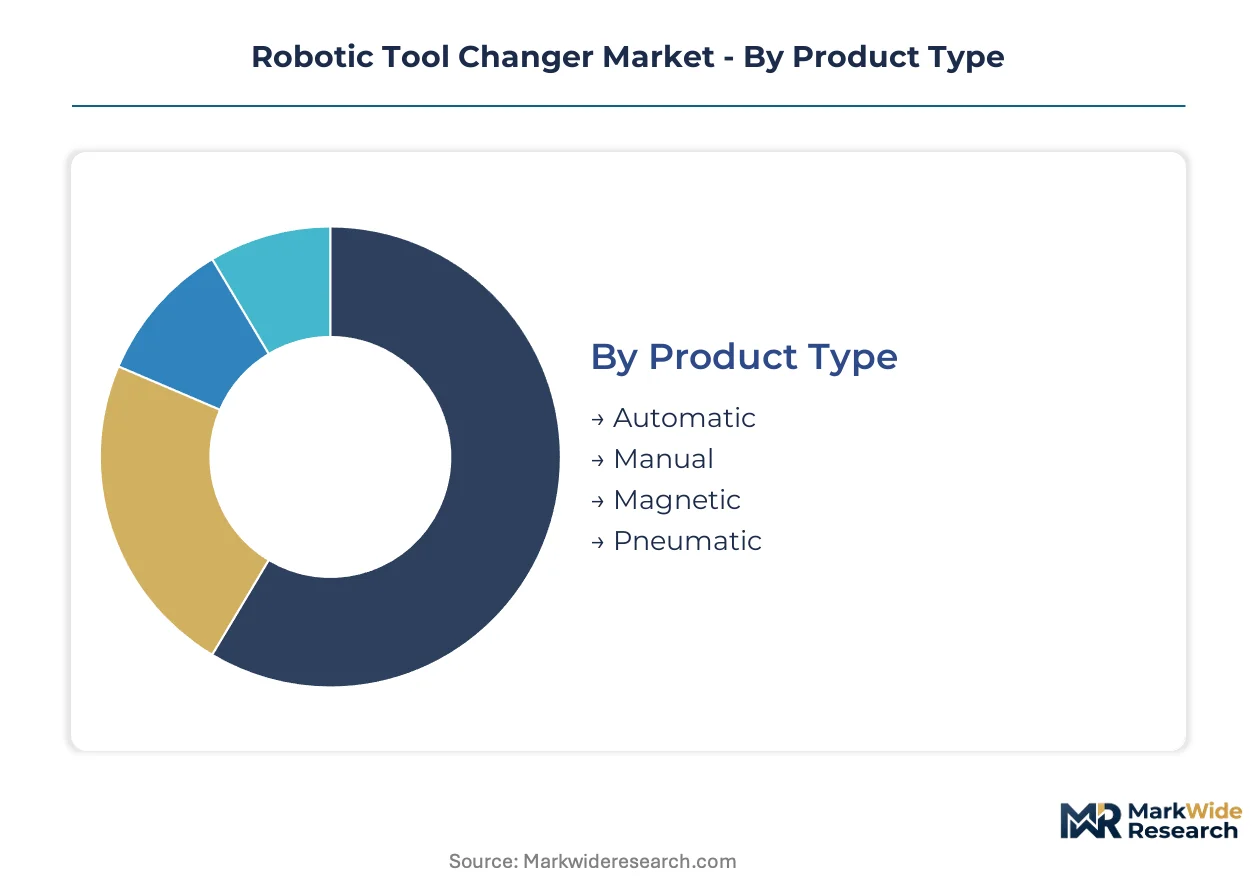
Segmentation in robotic tool changers reveals how specification authority migrates between standard ISO interfaces and custom-engineered solutions. Each dimension—product type, technology, application, and end user—carries distinct margin profiles and qualification timelines that reshape supplier competitive positioning.
Product Type:
Customization intensity spans from fully standardized automatic systems to application-specific magnetic configurations, with pneumatic variants occupying the middle ground of configurable commodity supply.
- Automatic:Pneumatic or electromechanical locking mechanisms enable sub-10-second tool exchanges without operator intervention. German automotive OEMs mandate these configurations on mixed-model lines where changeover downtime directly compresses throughput economics.
- Manual:Hand-actuated mechanical interfaces serve prototype shops and low-volume contract manufacturers where capital constraints override cycle time optimization. Demand concentrates in Indian precision engineering clusters where PLI scheme incentives still leave mid-tier automation budgets exposed.
- Magnetic:Rare-earth coupling systems eliminate mechanical wear surfaces for cleanroom-validated semiconductor handling in Taiwan and South Korea.
- Pneumatic:Compressed-air locking architectures dominate legacy robot fleet retrofits where electrical pass-through retrofit costs prove prohibitive.
Leading the category by volume: Automatic. Growing fastest: Magnetic.
Technology:
Cost tier stratification separates precision-electromechanical premium systems from utility-grade hydraulic alternatives, with hybrid architectures commanding specification premiums for multi-utility convergence.
- Electromechanical:Servo-controlled locking mechanisms deliver sub-micron repeatability for automotive body-in-white welding sequences. Swiss and German bearing supply concentration creates bottleneck risk for suppliers targeting this precision tier.
- Hybrid:Combined pneumatic-electrical utility lines reduce cabling complexity in collaborative robot deployments. FDA surgical robotics applications in the United States specify these configurations for sterile tool exchange protocols where autoclave compatibility validates premium pricing.
- Hydraulic:High-force locking systems serve heavy-payload material handling in aerospace structural assembly.
- Vacuum:Negative-pressure gripping integration enables non-contact wafer handling in semiconductor front-end processes.
Electromechanical systems anchor revenue concentration. Hybrid configurations gain share fastest in collaborative and medical applications.
Application:
Customer type segmentation separates high-volume automotive integrators from batch-oriented packaging specialists, with palletizing operations occupying the automation maturity frontier.
- Manufacturing:Process tool exchange for machining, welding, and surface treatment dominates installed base economics. Japanese tier-one suppliers specify automatic changers for flexible cells alternating between aluminum and steel processing without manual intervention.
- Assembly:Mixed-material handling and light joining sequences pull hybrid pneumatic-electrical configurations. Electronics contract manufacturers in Taiwan bypass distributor channels for direct ISO 9409-1 validated procurement.
- Packaging:End-of-line format flexibility drives specification for quick-change gripper families in food and beverage operations.
- Palletizing:Heavy-payload vacuum and mechanical hybrid systems serve logistics automation retrofits.
Manufacturing commands the deepest specification intensity. Assembly applications expand most quickly as collaborative robot penetration accelerates.
End User:
Maturity differentiation separates automotive's established validation protocols from healthcare's emerging sterilization requirements, with aerospace occupying the qualification timeline extreme.
- Automotive:Mixed-model production mandates compress changeover economics to sub-60-second targets. German OEM engineering teams now conduct direct ISO 9409-1 compliance verification, bypassing traditional robot OEM specification authority.
- Healthcare:Surgical and diagnostic robotics adopt sterile tool exchange protocols with FDA biocompatibility and autoclave compatibility requirements. This segment climbs the fastest as robotic surgery platforms expand procedural scope.
- Electronics:Cleanroom-validated architectures serve semiconductor and display manufacturing in South Korea and Taiwan.
- Aerospace:Force-torque sensing integration enables collaborative drilling and fastening in airframe assembly.
Automotive retains the largest installed base. Healthcare claims the steepest expansion trajectory amid regulatory-driven specification premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany produces the highest concentration of precision tool changer systems, while the United States and Japan consume the largest installed volumes for automotive and electronics manufacturing. China is narrowing the gap through domestic automation capex acceleration.
Germany
Automotive OEMs in Stuttgart and Munich mandate ISO 9409-1 validated systems for mixed-model welding lines. The KBA enforces CE marking documentation that filters non-compliant suppliers from procurement lists. Bavarian precision engineering clusters around Augsburg drive specification intensity for sub-micron repeatability systems.
United States
FDA device regulations impose sterilization compatibility requirements on surgical robotics tool changers in Boston and Minneapolis medical device corridors. The EPA monitors REACH substance restrictions affecting electrical contact plating formulations. Detroit automotive engineering teams now conduct direct ISO compliance verification, bypassing traditional robot OEM channels.
Japan
METI industrial automation incentives accelerate deployment of hybrid pneumatic-electrical configurations for collaborative robot cells in Nagoya and Osaka. JIS standards convergence with ISO 9409-1 reduces validation costs for multi-brand robot fleets. Toyota City and Yokohama manufacturing clusters specify automatic changers for aluminum-steel processing flexibility.
South Korea
MFDS medical device regulations and semiconductor cleanroom protocols pull validated particle containment architectures for Seoul and Suwon electronics manufacturing. The national semiconductor cluster drives specification for magnetic coupling systems in non-contact wafer handling. Busan precision engineering corridors adopt force-torque integrated systems for collaborative airframe assembly.
India
PLI scheme incentives for automotive component manufacturing accelerate automation capex in Pune and Chennai industrial corridors. BIS standards adoption for industrial machinery creates qualification pathways for ISO 9409-1 compliant imports. Gujarat precision engineering clusters in Ahmedabad and Vadodara specify manual tool changers where capital constraints limit automatic system deployment.
Robotic Tool Changer Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered technology segments. The vendor base organizes around three strategic archetypes: precision-electromechanical system houses, hybrid utility integrators, and cleanroom-validated specialists. Consolidation pressure concentrates in the mid-tier where ISO 9409-1 standardization erodes proprietary lock-in advantages. Dominant competitive moves include portfolio diversification into surgical robotics and backward integration into bearing supply chains.
Among North Carolina-based manufacturers, ATI Industrial Automation occupies a position within the rapid-turn custom configuration segment. Staubli exemplifies the European precision-electromechanical archetype through its Swiss-origin corporate structure. Schunk represents the force-torque integration specialist tier that differentiates offerings in collaborative robot deployments. These three anchors illustrate how geographic origin and corporate structure map to distinct competitive positioning vectors.
| Leading Market Players |
|---|
| ATI Industrial Automation |
| Staubli |
| Schunk |
| Destaco |
| Applied Robotics |
| Robot System Products |
| Nitta Corporation |
| AGI Corporation |
| Zimmer Group |
| Others |
Value Network & Pricing Analysis
Mechatronics integration engineers concentrated in Stuttgart and Augsburg command wage premiums that widen pricing spreads between premium electromechanical systems and economy pneumatic alternatives. Labor-cost differentials between German precision manufacturing clusters and Indian assembly operations create tiered procurement options for automotive OEMs balancing cycle-time requirements against capital constraints.
Pricing Analysis
Cost-down pressure on standard pneumatic systems accelerates as Indian contract manufacturers exploit PLI scheme incentives to source manual tool changers at reduced capital outlay. Three-tier pricing structure across premium, standard, and economy levels separates ISO 9409-1 validated electromechanical units from CE-marked mid-tier hybrids and non-certified pneumatic alternatives. Price differentiation hinges on certification grade and after-sales service bundling. Tier-one automotive buyers in Germany and Japan exhibit lowest price sensitivity due to changeover downtime economics, whereas Indian precision engineering clusters face acute capital constraints that favor economy-tier procurement.
Supply Chain Analysis
Freight cost volatility from Swiss and German bearing manufacturers to global assembly sites compresses margins on sub-micron repeatability systems. Supply concentrates in Germany for precision electromechanical components, Switzerland for specialty bearings, and Taiwan for magnetic coupling subassemblies. Raw material dependencies include rare-earth magnets for cleanroom applications, hardened steel alloys for locking mechanisms, and specialized contact metallurgies for electrical pass-through. Single-source vulnerability around Swiss bearing supply creates bottleneck risk for automotive body-in-white welding sequences. Distribution runs through robot OEM authorized channels for validated systems and direct technical procurement for ISO 9409-1 compliant alternatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance arena where FDA device regulations for surgical robotics create barrier-to-entry moats that protect validated suppliers from commodity-tier competition. CE marking documentation burdens under the EU Machinery Directive similarly filter non-compliant entrants from European procurement lists.
For Market Incumbents: Anticipate margin compression from ISO 9409-1 standardization eroding proprietary lock-in advantages by deepening backward integration into bearing supply chains and accelerating sterilization protocol validation for surgical robotics applications. Capacity addition in Tamil Nadu industrial corridors captures PLI scheme-driven demand from Indian automotive component manufacturers. For New Entrants and Emerging Players: Enter via healthcare sterilization protocols where FDA biocompatibility requirements limit incumbent supplier count and specification premiums reward compliant entrants. Indian precision engineering clusters in Pune and Chennai present the most penetrable geography given capital constraints that favor manual and pneumatic alternatives over electromechanical premium systems. Go-to-market positioning should emphasize rapid-turn custom configuration capabilities for defense and aerospace integrators. For Investors and Strategic Acquirers: Re-rating potential sits with force-torque integration specialists given collaborative robot penetration accelerating specification demand for haptic-enabled tool changers. Long-term viability favors suppliers with captive bearing supply and dual FDA-CE certification capabilities. The signal to watch is surgical robotics platform expansion into diagnostic procedures requiring sterile tool exchange protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bearing Supply | Captive access to Swiss and German sub-micron repeatability components insulates margin from supply bottleneck risk. |
| Sterilization Protocol Validation | FDA biocompatibility and autoclave compatibility certification unlocks premium pricing in surgical robotics applications. |
| Hybrid Technology Platform Launch | Combined pneumatic-electrical utility lines reduce cabling complexity in collaborative robot deployments across Japanese automotive cells. |
| Geographic Manufacturing Footprint | Tamil Nadu and Pune production presence captures PLI scheme incentives for Indian automotive component automation. |
| Force-Torque Sensing Integration | Haptic-enabled mechanics enable safety-fencing-free human-robot collaborative cells in aerospace airframe assembly. |
Research Methodology
Document review covered SEC filings from automation component suppliers, EU Machinery Directive validation databases, and FDA 510(k) surgical device submissions, complemented by interviews with plant engineers at German automotive OEMs, procurement leads at Taiwanese electronics contract manufacturers, and aftermarket service heads at North American robotics integrators. Secondary sources included ISO certification registries, BIS machinery standards documentation, and customs trade data for precision bearing imports. Bottom-up unit economics triangulated against top-down market sizing from robot OEM shipment disclosures.
Segment-level outputs across product type, technology, application, and end-user dimensions were generated through driver-based modeling over the projection horizon. CAGRs were derived from regression analysis against automotive production forecasts and collaborative robot deployment trajectories. Industry-specific inputs included mixed-model line changeover downtime economics and semiconductor cleanroom particle containment specifications.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory divergence scenarios between ISO frameworks and national implementations. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Robot Fleet Management Software Market
Robotics and Automation
Smart Machines Market
Robotics and Automation
Warehouse Robotics Market
Robotics and Automation
Healthcare Robots Market
Robotics and Automation
Logistics Robotics Market
Robotics and Automation
Logistics Robots Market
Robotics and Automation
Top Robotics Market
Robotics and Automation
Cleaning Robot Market
Robotics and Automation
Global Entertainment Robots Market
Robotics and Automation
Global Autonomous Mobile Robot Market
Robotics and Automation
Robotics in Shipbuilding Market
Robotics and Automation
Global IT Robotic Automation Market
Robotics and Automation
Global Soldering Robot Market
Robotics and Automation
Sweeper Robot Market
Robotics and Automation
AGV & AMR in Logistics Market
Robotics and Automation
Global AI Based Surgical Robots Market