
 Europe Underwater Robotics Market | 2026-2036
Europe Underwater Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Underwater Robotics Market Foresight
Modular payload architectures are decoupling sensor packages from vehicle hulls, letting buyers customize mission-specific configurations without platform swaps. Kongsberg Gruppen ASA leverages its integrated sonar and navigation stack to dominate Norwegian deep-water survey contracts. ECA Group specializes in mine-countermeasure variants for European naval programs. Fugro sustains its position through proprietary autonomous vessel fleets deployed across North Sea offshore wind zones.
Europe underwater robotics encompasses tethered, autonomous, and hybrid platforms engineered to operate at depths exceeding 3,000 meters for seabed intervention, pipeline inspection, and marine data acquisition. Pressure-rated titanium housings, fiber-optic tethers, and multibeam sonar arrays define core system specifications. Remotely Operated Vehicles retain the largest installed base across mature oil and gas fields, though Autonomous Underwater Vehicles capture the fastest expansion as offshore wind developers demand persistent seabed monitoring without surface vessel support. Artificial Intelligence integration in sonar data processing now separates premium system tiers from standard offerings.
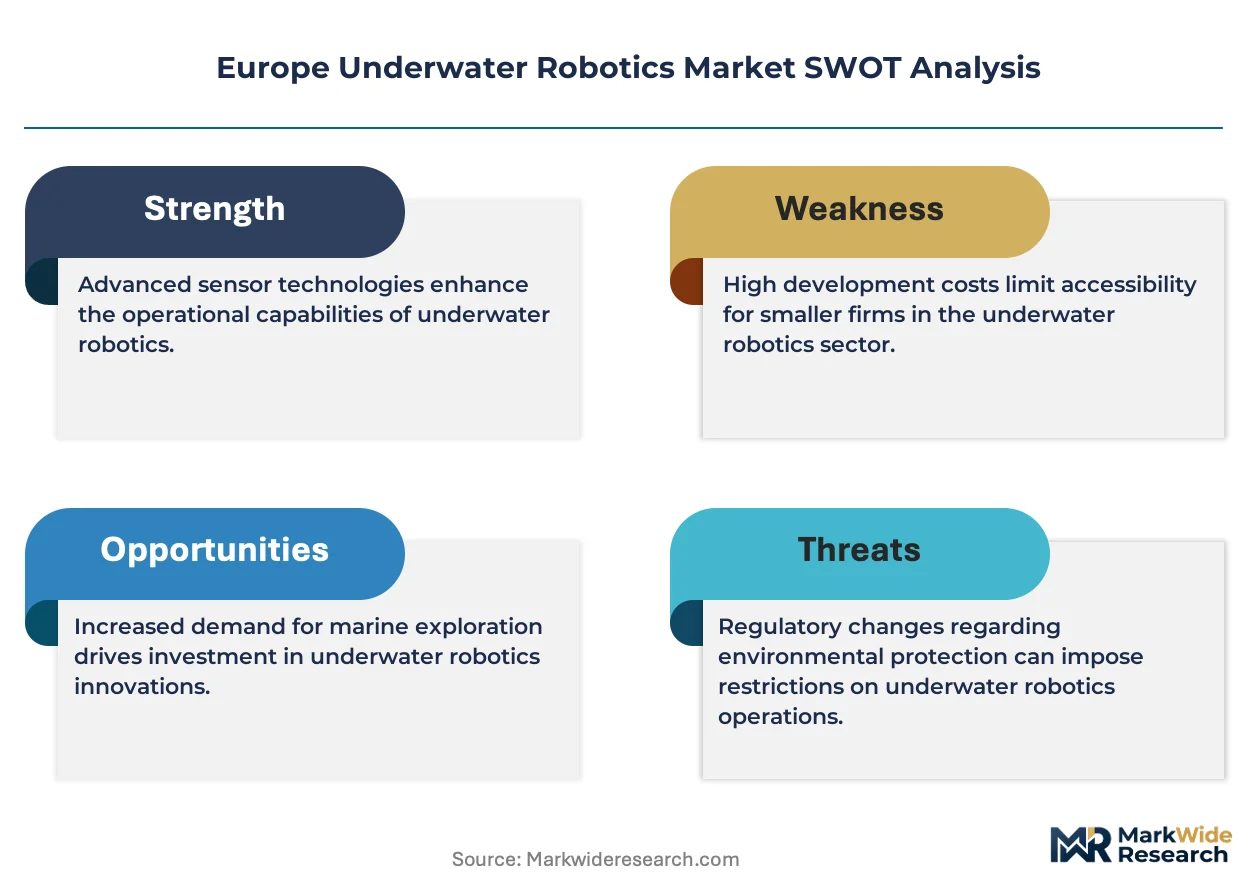
EMA equipment certification, REACH substance restrictions on hydraulic fluids, and the EU Green Deal marine strategy directives collectively elevate compliance costs while opening public funding channels for sustainable platform development. CE marking under the Marine Equipment Directive governs market access for vessels operating in European Economic Area waters. Stakeholders must weigh regulatory-driven R&D obligations against the contracting timelines that offshore wind developers impose for array commissioning.
Market Dynamics
The North Sea offshore wind buildout is compressing project timelines for subsea cable surveys, forcing AUV fleet operators to reconfigure deployment models around persistent autonomous monitoring rather than campaign-based inspection cycles.
Growth Catalysts
- EU Green Deal marine strategy:Mandates for seabed habitat mapping before offshore construction are generating dedicated procurement streams for environmentally certified ROV and AUV platforms.
- Fiber-optic tether advancement:Real-time high-bandwidth data transmission from 3,000-meter depths enables remote piloting of complex intervention tasks without surface vessel positioning.
- Platform decommissioning wave:Aging North Sea oil and gas infrastructure in Norwegian and UK waters requires robotic cutting, lifting, and seabed clearance operations through 2035.
Market Restraints
- Titanium alloy supply concentration:Pressure-rated hull material sourcing clusters with a limited set of specialized European metallurgical suppliers, creating input cost volatility.
- REACH hydraulic fluid compliance:Restrictions on legacy lubricant formulations force complete system redesigns for work-class ROVs, extending R&D cycles.
- Acoustic positioning limitation:Multipath interference in complex seabed terrain degrades navigation accuracy, constraining fully autonomous operations in certain geologies.
Strategic Opportunities
- Polish and Baltic offshore wind:Emerging seabed lease rounds in these markets lack established local AUV service infrastructure, creating first-mover positioning for fleet operators.
- AI-sonar convergence:Machine learning classification of multibeam backscatter data is enabling real-time benthic habitat identification without post-processing delays.
- EMA public funding channels:Equipment certification subsidies for sustainable platform development offset compliance-driven R&D cost burdens for EU-based manufacturers.
Industry Challenges
- Subsea robotics technician scarcity:Cross-disciplinary skill requirements combining marine engineering, acoustic systems, and software integration outpace vocational training program output.
- CE Marine Equipment Directive timeline:Certification delays for novel autonomous platforms mismatch offshore wind developer array commissioning schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Underwater Robotics Market |
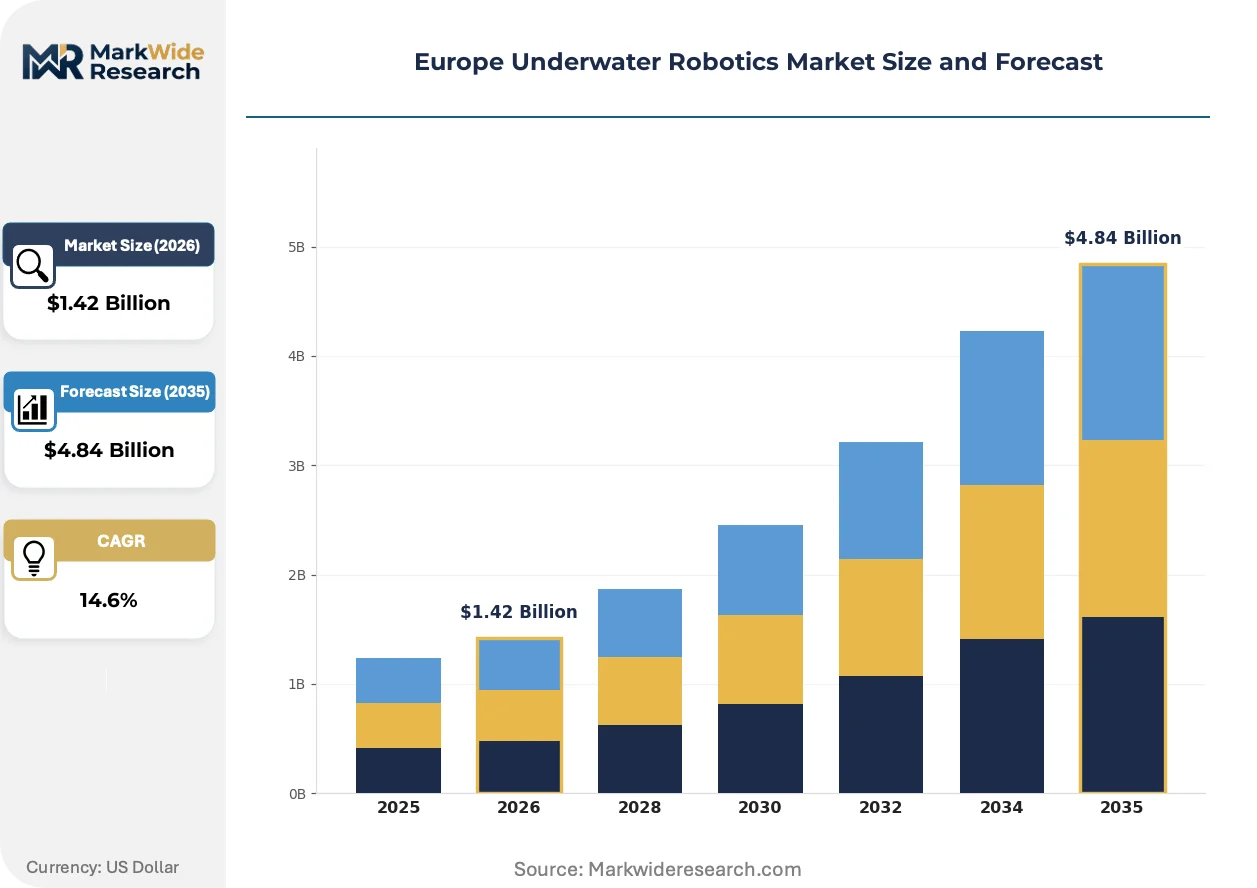
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $4.84 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Remotely Operated Vehicles, Autonomous Underwater Vehicles, Hybrid ROVs, Underwater Drones End User: Defense, Oil & Gas, Research Institutions, Environmental Monitoring Technology: Artificial Intelligence, Machine Learning, GPS Navigation, Sonar Systems Application: Inspection, Surveying, Data Collection, Underwater Maintenance |
| Companies Covered | Fugro, Soil Machine Dynamics Ltd., Kongsberg Gruppen ASA, Atlas Elektronik, HydroSurv Ltd., Saab AB, Oceaneering International Inc., Subsea 7, ECA Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Underwater Robotics Market Shifts & Advancements
Artificial intelligence is rewiring how underwater robotics platforms process sensor data, compressing the gap between raw acoustic collection and actionable seabed intelligence. Three developments are reconfiguring competitive positioning.
Edge-deployed neural networks for sonar target classification are integrating directly into AUV payload computers, eliminating surface tether dependency for mission-critical decision loops. Offshore wind developers in the North Sea are deploying these systems for real-time cable touchdown monitoring. The structural consequence is a compression in survey vessel day rates as persistent autonomy displaces campaign-based crewed operations.
REACH substance restrictions on hydraulic fluids are compelling work-class ROV manufacturers to redesign power transmission architectures around seawater-based alternatives or all-electric actuation. The industrial consequence is a bifurcation in fleet replacement cycles between compliant newbuilds and grandfathered legacy systems. Norwegian operators are accelerating decommissioning of hydraulic-intensive platforms ahead of regulatory deadlines.
Service unbundling is fragmenting traditional integrated contracts as offshore wind developers separate platform procurement from data interpretation. Independent analytics firms are capturing margin previously retained by full-service robotics operators. This pattern is most visible in UK Round 4 and Round 5 lease areas where developers maintain direct relationships with seabed data specialists.
Europe Underwater Robotics Market Segmentation
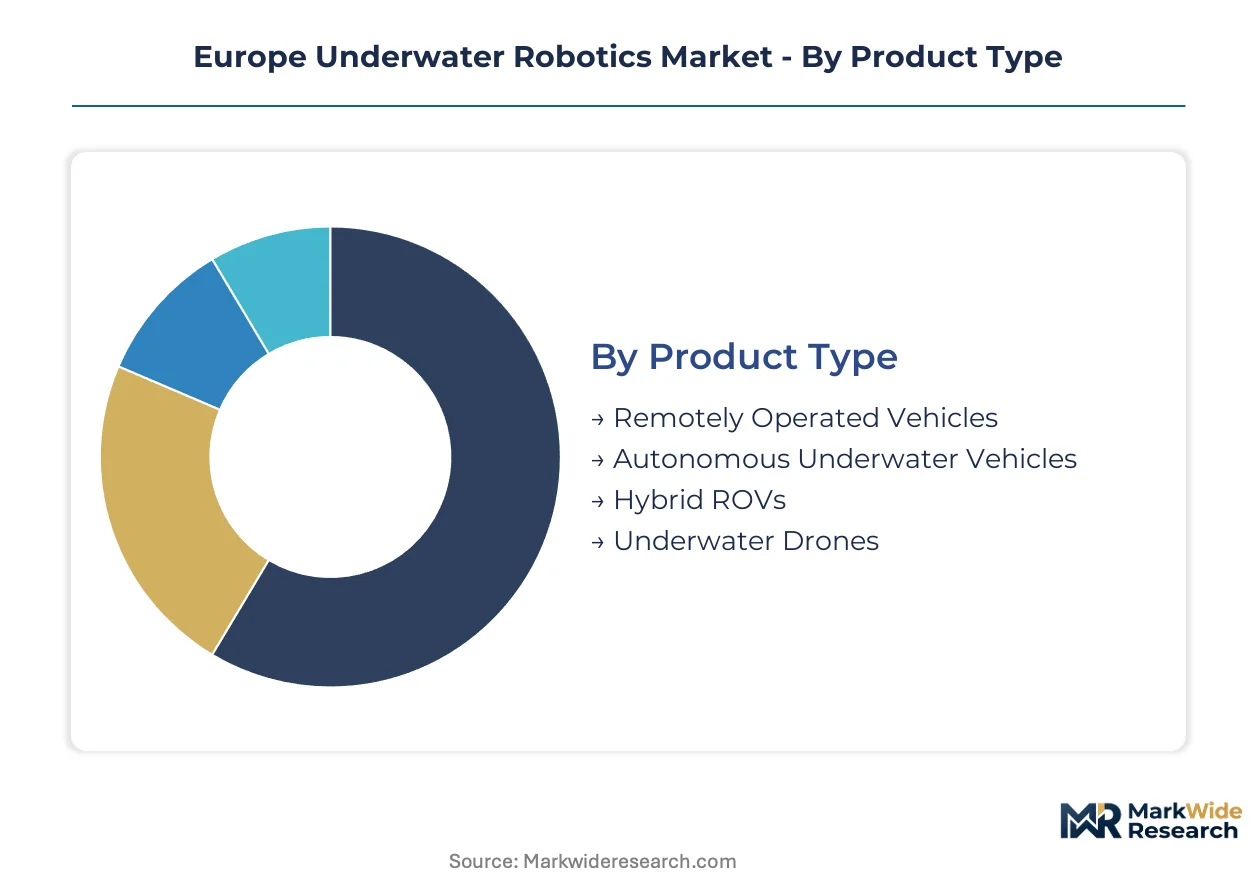
Platform architecture choices determine deployment economics across North Sea offshore wind and Norwegian decommissioning contracts. Segmentation reveals where autonomous systems displace tethered alternatives and which technology stacks command procurement priority.
Product Type:
Volume concentration sits with legacy tethered platforms. Premium expansion concentrates in untethered autonomous systems.
- Remotely Operated Vehicles:Fiber-optic tethered platforms with real-time pilot control dominate mature oil and gas field intervention. Norwegian operators deploy work-class ROVs for platform decommissioning cutting and lifting operations in UK and Norwegian waters.
- Autonomous Underwater Vehicles:Untethered battery-powered hulls with pre-programmed mission profiles enable persistent seabed monitoring without surface vessel positioning. North Sea offshore wind developers in UK Round 4 and Round 5 lease areas are standardizing AUV fleets for cable touchdown surveys.
- Hybrid ROVs:Systems switching between tethered piloting and autonomous waypoint navigation bridge operational flexibility demands. These platforms serve Polish and Baltic offshore wind markets lacking established local service infrastructure.
- Underwater Drones:Compact shallow-depth platforms with consumer-grade sensor payloads address environmental monitoring and nearshore inspection tasks. EU Green Deal marine conservation mandates in Mediterranean coastal zones are generating procurement for benthic habitat mapping.
Mature deployment sits with Remotely Operated Vehicles. Newer deployment is concentrated in Autonomous Underwater Vehicles.
End User:
Procurement scale separates capital-intensive energy infrastructure from mission-funded scientific programs.
- Oil & Gas:Supermajor operators in Norwegian and UK North Sea waters sustain the largest installed base of work-class ROVs for subsea infrastructure inspection. Platform decommissioning obligations through 2035 are locking in replacement cycles for hydraulic-intensive legacy fleets.
- Defense:Naval mine-countermeasure programs across European littoral states demand specialized variants with magnetic and acoustic signature suppression. ECA Group and Kongsberg Gruppen ASA compete for national procurement frameworks in France, Norway, and the United Kingdom.
- Environmental Monitoring:EU Green Deal seabed habitat mapping mandates are creating dedicated funding streams for benthic survey platforms. These operators prioritize REACH-compliant hydraulic alternatives and low-acoustic-impact propulsion.
- Research Institutions:University and oceanographic laboratory procurement focuses on modular payload architectures for deep-water biological and geological sampling. Budget constraints favor leasing over ownership in Mediterranean and Atlantic research clusters.
Procurement volume concentrates with Oil & Gas. Fastest policy-driven expansion is occurring in Environmental Monitoring.
Technology:
Navigation accuracy and data processing speed define competitive tiers.
- Sonar Systems:Multibeam and synthetic aperture sonar arrays generate bathymetric and seabed classification data. These systems face multipath interference constraints in complex North Sea glacial terrain.
- Artificial Intelligence:Edge-deployed neural networks for real-time target classification are integrating directly into AUV payload computers. Offshore wind developers are deploying these for cable touchdown monitoring without surface tether dependency.
- Machine Learning:Backscatter data training sets enable automated benthic habitat identification, compressing survey interpretation timelines. UK seabed data specialists are capturing margin previously retained by full-service robotics operators.
- GPS Navigation:Surface positioning integration provides drift correction for shallow-water operations. Signal attenuation below 10 meters depth limits standalone utility for deep-water platforms.
Core navigation infrastructure relies on Sonar Systems. Capability differentiation is concentrating in Artificial Intelligence.
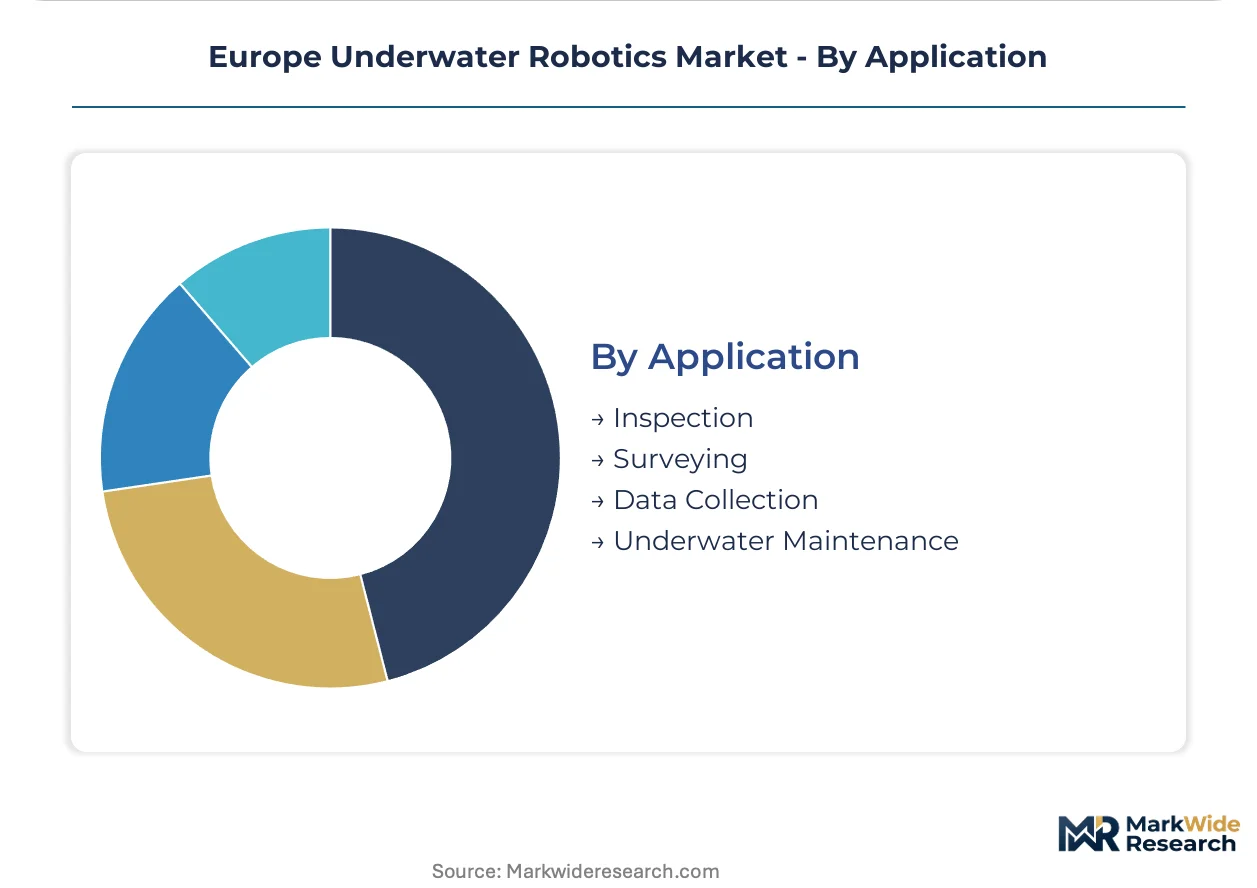
Application:
Revenue per mission day separates intervention from observation tasks.
- Inspection:Visual and sensor-based assessment of subsea infrastructure integrity commands premium day rates. North Sea offshore wind cable array commissioning timelines are compressing campaign schedules.
- Surveying:Systematic seabed mapping for pre-construction environmental baselines and route planning. EU Green Deal mandates require these surveys before offshore construction permitting.
- Underwater Maintenance:Robotic cutting, valve operation, and debris clearance on live production infrastructure. Norwegian platform decommissioning is accelerating demand for heavy-lift capable work-class systems.
- Data Collection:Long-duration environmental sensor deployment for oceanographic and climate research. These missions prioritize energy efficiency over intervention capability.
Contract value concentrates in Inspection. Mission frequency is climbing fastest in Surveying.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Norwegian and UK subsea engineering clusters while consumption spreads across North Sea offshore wind lease areas. Service deployment patterns follow seabed lease licensing timelines rather than manufacturing geography.
Norway
Deep-water survey contracts and platform decommissioning obligations drive procurement of work-class systems. The Norwegian Maritime Authority enforces strict EMA equipment certification for vessels operating in national waters. Kongsberg Gruppen ASA anchors the Kongsberg technology cluster, supplying integrated sonar and navigation stacks for North Sea operators.
United Kingdom
Offshore wind cable array commissioning in Round 4 and Round 5 lease areas compresses survey timelines. The Marine Management Organisation implements seabed habitat mapping mandates under EU Green Deal directives. Aberdeen maintains its position as the primary subsea robotics service hub, though fleet operators now deploy autonomous systems from Hull and Great Yarmouth.
Germany
Baltic Sea offshore wind expansion generates demand for inspection platforms in shallow, complex seabed terrain. The Federal Maritime and Hydrographic Agency coordinates environmental baseline surveys required for construction permits. Rostock and Kiel host emerging service infrastructure as Polish and Baltic markets lack established local AUV operators.
France
Naval mine-countermeasure programs and Mediterranean marine conservation projects sustain dual demand streams. The French Maritime Authority applies REACH substance restrictions to hydraulic fluids used in national fleet operations. ECA Group represents the Toulon-based defense-specialist archetype, competing for European littoral state procurement frameworks.
Netherlands
North Sea offshore wind port infrastructure and subsea cable landing zones require persistent monitoring capabilities. The Netherlands Enterprise Agency channels public funding toward sustainable platform development under EMA certification subsidies. Rotterdam and Den Helder concentrate service vessel operations supporting cross-border lease areas in Belgian and German waters.
Europe Underwater Robotics Market Competitive Landscape
The competitive structure tilts toward integrated technology-stack providers with captive navigation and sensor capabilities. Consolidation pressure runs high as offshore wind developers consolidate procurement around full-service operators. Three archetypes dominate: defense-specialist manufacturers, survey-service integrators, and component-technology suppliers. Geographic expansion through Baltic and Polish offshore wind markets and backward integration into titanium alloy sourcing represent the dominant competitive moves.
Among Norwegian and UK-based operators, Kongsberg Gruppen ASA, Fugro, and ECA Group exemplify distinct strategic positions. Kongsberg Gruppen ASA occupies the integrated-systems tier with its captive sonar and navigation technology. Fugro represents the service-integrator archetype, deploying proprietary autonomous vessel fleets across North Sea wind zones. ECA Group anchors the defense-specialist segment, supplying signature-suppressed platforms for naval mine-countermeasure programs.
| Leading Market Players |
|---|
| Fugro |
| Soil Machine Dynamics Ltd. |
| Kongsberg Gruppen ASA |
| Atlas Elektronik |
| HydroSurv Ltd. |
| Saab AB |
| Oceaneering International Inc. |
| Subsea 7 |
| ECA Group |
| Others |
Supply & Pricing Matrix
Sovereign-backed Norwegian subsea engineering clusters and private-equity-rolled-up service operators jointly shape supply discipline and pricing power across European underwater robotics procurement. Titanium alloy sourcing concentration and REACH hydraulic fluid compliance costs feed directly into platform pricing tiers, while offshore wind developer consolidation amplifies buyer leverage over fleet day rates.
Pricing Analysis
Cost-down pressure on work-class ROVs accelerates because REACH-mandated hydraulic fluid redesigns inflate R&D recovery timelines. Three-tier pricing structure across premium AI-sonar platforms, standard multibeam configurations, and economy-grade inspection hulls dominates contract structures. CE Marine Equipment Directive certification tier and fiber-optic tether bandwidth capacity serve as primary price differentiation drivers. Environmental Monitoring buyers exhibit highest price sensitivity due to grant-funded procurement constraints, while Oil & Gas operators absorb premium tier pricing for decommissioning reliability.
Supply Chain Analysis
Refurbishment flows for pressure-rated titanium housings and fiber-optic tether spools create secondary supply channels that moderate newbuild input costs. Manufacturing concentrates in Norway, the United Kingdom, and France, drawing from specialized European metallurgical suppliers for hull alloys and Baltic-region fiber producers for tether cores. Single-source vulnerability clusters around titanium alloy supply from limited certified European foundries. Distribution runs through Aberdeen, Stavanger, and Rotterdam service hubs that stage platforms for North Sea deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into captive titanium alloy sourcing and in-house AI-sonar development separates consolidators from margin-compressed assemblers across the European underwater robotics landscape.
For Market Incumbents: Hedge against REACH-driven R&D cost inflation by accelerating backward integration into compliant hydraulic component manufacturing and securing long-term titanium supply offtake from Norwegian metallurgical suppliers. Consolidate service infrastructure around persistent autonomous monitoring contracts to defend against offshore wind developer procurement consolidation. For New Entrants and Emerging Players: Capture white-space in Polish and Baltic offshore wind markets lacking established AUV service infrastructure by deploying hybrid ROV platforms with modular payload architectures. Target environmental monitoring procurement channels under EU Green Deal funding streams with REACH-compliant electric actuation systems. For Investors and Strategic Acquirers: Distressed-cycle entries favor defense-specialist manufacturers with captive mine-countermeasure technology in French and Norwegian naval procurement corridors. Monitor CE Marine Equipment Directive certification backlog duration as inflection signal for autonomous platform commissioning capacity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Titanium Sourcing | Secures pressure-rated hull supply from Norwegian metallurgical clusters against input cost volatility. |
| AI-Sonar Platform Development | Captures premium tier positioning through real-time benthic classification for offshore wind cable monitoring. |
| REACH-Compliant Hydraulic Redesign | Unlocks EU public funding channels while grandfathering non-compliant legacy fleets out of service. |
| Baltic Service Infrastructure Expansion | Establishes first-mover positioning in Polish offshore wind lease areas lacking local AUV operators. |
| Defense-Specialist Technology Licensing | Monetizes signature-suppression capabilities across European littoral state naval procurement frameworks. |
Research Methodology
Multi-period observation of AUV fleet deployment rates, ROV day-rate indices, and CE certification timelines anchored the trend analysis, supplemented by interviews with subsea robotics fleet managers, offshore wind developer survey coordinators, titanium alloy procurement leads, and EMA certification officers. Secondary validation drew from EU Green Deal marine strategy directives, Norwegian Maritime Authority vessel registries, North Sea offshore wind lease round documentation, and REACH substance restriction filings. Bottom-up platform shipment tallies and top-down energy infrastructure investment flows were triangulated to constrain volume estimates.
Segment-weighting across platform architecture, end-use sector, and navigation technology tier informed the analytical framework across the projection horizon. Modeled dimensions included tethered versus autonomous hull types, Oil & Gas versus Environmental Monitoring procurement channels, and sonar-based versus AI-integrated navigation stacks. CAGRs were derived from deployment trajectory analysis and infrastructure commissioning schedules. Forecast inputs incorporated North Sea decommissioning obligation timelines and Baltic offshore wind lease licensing waves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH enforcement intensity and titanium alloy supply disruptions. Forecasts reflect documented assumptions regarding EU Green Deal funding continuity and offshore wind developer array commissioning cadence. Material deviation in CE Marine Equipment Directive processing timelines or Norwegian platform decommissioning acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Firefighting Robots Market
Robotics and Automation
Global Construction Robot Market
Robotics and Automation
Construction Robotics Market
Robotics and Automation
Robotic Process Automation (RPA) Market
Robotics and Automation
Pharmaceutical Collaborative Robots Market
Robotics and Automation
Robotic Welding Market
Robotics and Automation
Asia-Pacific Robotics Technology Market
Robotics and Automation
AGV Intelligent Management Systems Market
Robotics and Automation
Robot Coffee Kiosk Market
Robotics and Automation
Healthcare Robots Market
Robotics and Automation
Robotics in Shipbuilding Market
Robotics and Automation
Global All Terrain Robots Market
Robotics and Automation
United Kingdom Cloud Robotics Market
Robotics and Automation
Industrial Robots Market
Robotics and Automation
China Industrial Robots Market
Robotics and Automation
Airport Robots Market