
 Cleanroom Robots in Healthcare Market | 2026-2036
Cleanroom Robots in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Cleanroom Robots in Healthcare Market Intelligence
Asset-light leasing models for cleanroom automation systems are reshaping competitive entry barriers for mid-sized pharmaceutical contractors. FANUC Corporation leverages its precision motion control heritage to dominate high-repeatability aseptic handling applications. KUKA AG anchors European demand through deep integration with pharmaceutical line builders. Yaskawa Electric Corporation specializes in compact SCARA configurations for space-constrained compounding suites.
Cleanroom robots in healthcare denote sealed-environment robotic systems engineered to ISO 14644-1 particulate standards, employing stainless steel enclosures, HEPA-filtered internal positive pressure, and smooth-surface geometries that eliminate microbial harborage points. These systems execute sterile material handling, vial filling, and surgical instrument delivery without introducing biological or particulate contamination into controlled zones. Articulated robots command the largest installed base due to six-axis dexterity in vial manipulation tasks, while mobile robots represent the fastest-expanding category as autonomous transport replaces human gowning protocols between cleanroom suites. Collaborative robots concentrate margin pools in personalized medicine batch sizes where changeover flexibility outweighs cycle speed.
FDA cGMP guidelines and EMA Annex 1 revisions on sterile manufacturing mandate validated automation for critical aseptic operations, directly elevating capital allocation toward certified robotic platforms. Japan's PMDA and ISO 13485 quality management standards further constrain market access to vendors with documented contamination control traceability. Stakeholders must monitor evolving regulatory divergence between FDA's risk-based approach and EMA's stricter mandatory automation thresholds for closed-system processing.
Market Dynamics
EMA Annex 1 revisions mandating closed-system automation for sterile manufacturing are compressing capital deployment timelines across pharmaceutical facilities, forcing rapid robot qualification cycles that favor vendors with pre-validated contamination control architectures.
Growth Catalysts
- FDA cGMP sterile processing mandates:Validation requirements for aseptic handling operations are compelling pharmaceutical manufacturers to replace manual intervention with certified robotic platforms in critical zones.
- Biologics manufacturing expansion:Cell and gene therapy production facilities require ISO 14644-1 Class 5 environments that human operators cannot sustain without excessive contamination risk.
- German precision medical device clusters:Concentrated investment in automated assembly lines for implantable devices is generating sustained procurement of six-axis articulated systems.
Market Restraints
- Stainless steel alloy cost volatility:Nickel and chromium price swings directly impact enclosure fabrication economics for HEPA-positive-pressure robot housings.
- Precision motion component supply concentration:Harmonic drive and servo motor sourcing clusters in Japan and Taiwan create single-point vulnerability for European system integrators.
- ISO 14644-1 Class 3 certification barriers:Extended validation timelines for sub-micron particulate compliance delay revenue recognition by 18-24 months.
Strategic Opportunities
- Compounding pharmacy automation:US hospital and specialty pharmacy chains are deploying compact SCARA configurations for sterile hazardous drug preparation under USP <800> guidelines.
- Autonomous mobile transport convergence:Integration of LiDAR navigation with positive-pressure sealed cabins enables human-free material flow between cleanroom suites.
- Japan PMDA quality traceability incentives:Documented contamination control genealogy requirements favor vendors offering integrated data-logging architectures.
Industry Challenges
- Multi-disciplinary commissioning expertise:Simultaneous mastery of robotic kinematics, HVAC engineering, and aseptic validation protocols commands premium compensation that mid-sized contractors cannot secure.
- Legacy SCADA integration complexity:Pharmaceutical facilities running 1990s-era distributed control systems require custom protocol bridges to connect modern robot controllers without triggering re-validation cascades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cleanroom Robots in Healthcare Market |
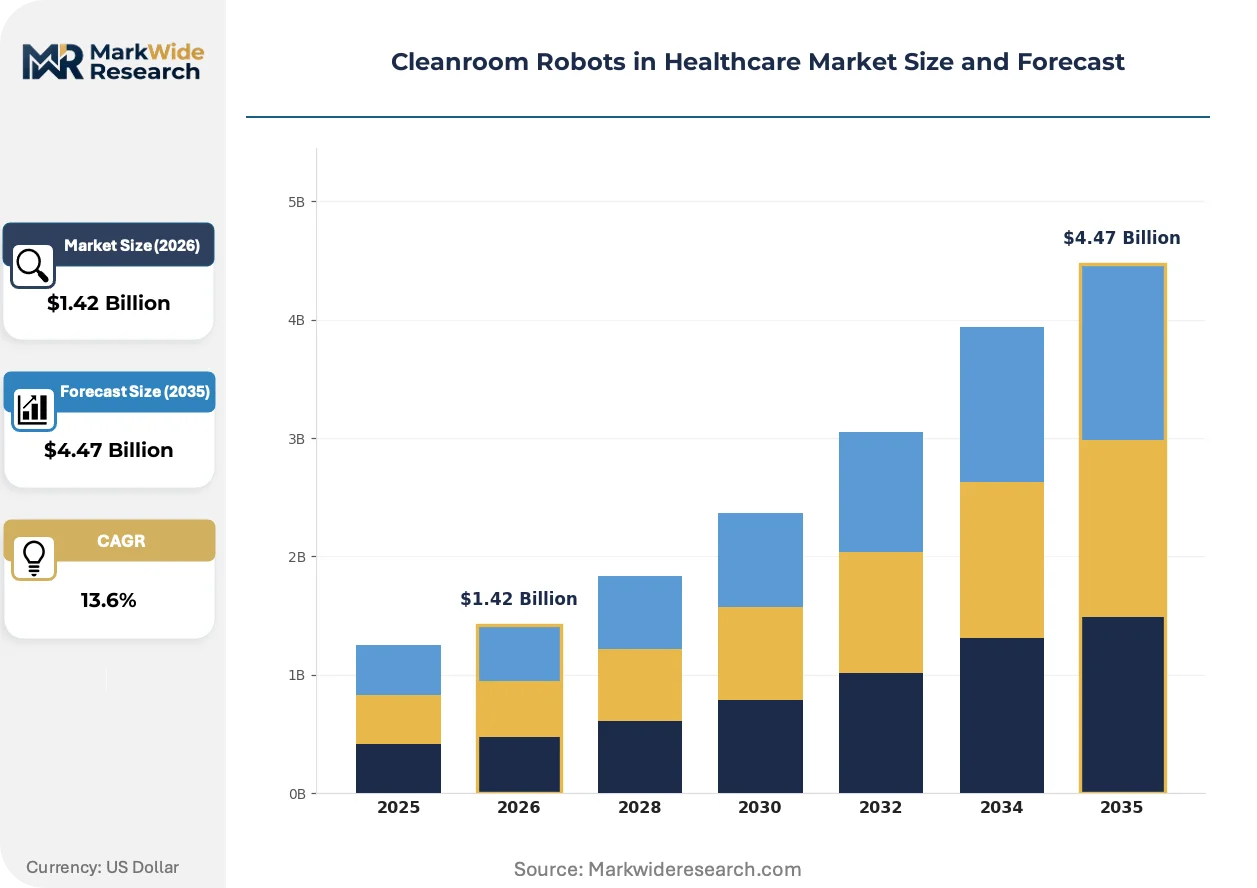
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $4.47 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Articulated Robots, Mobile Robots, SCARA Robots, Collaborative Robots Application: Pharmaceutical Manufacturing, Laboratory Automation, Surgical Assistance, Disinfection Technology: AI-Driven, Remote Monitoring, Sensor Integration, Machine Learning End User: Hospitals, Research Institutions, Biotech Companies, Contract Manufacturers |
| Companies Covered | ABB Ltd., Denso Corporation, FANUC Corporation, Kawasaki Heavy Industries, Ltd., Yaskawa Electric Corporation, Aerotech, Inc., Nachi Fujikoshi Corporation, KUKA AG, Omron Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cleanroom Robots in Healthcare Market Strategic Shifts & Innovations
Active pharmaceutical ingredient manufacturers are reconfiguring facility layouts around robot-centric workflows rather than retrofitting automation into human-scaled cleanroom architectures, compressing both contamination risk vectors and operational footprint requirements.
Collaborative robot force-limiting architectures with sealed IP69K-rated joints are rendering obsolete traditional isolator-based separation between human technicians and aseptic processing zones. Contract development and manufacturing organizations in Switzerland and Massachusetts are piloting these configurations for personalized medicine batch sizes below 500 units. The structural consequence is collapsing demand for hard-wall isolator infrastructure that previously consumed 40% of cleanroom capital budgets.
EMA's 2022 Annex 1 revision mandating barrier isolation for Grade A operations is compelling vial filling line rebuilds across European facilities. The regulation's closed-system processing language elevates capital allocation toward pre-validated robotic platforms over manual aseptic processing. German and Swiss pharmaceutical manufacturers are responding by consolidating supplier relationships with vendors offering integrated isolator-robot systems rather than assembling components from multiple sources.
Leasing and robotics-as-a-service contracts are displacing outright capital purchase for mid-sized pharmaceutical contractors facing compressed product lifecycles. Equipment financiers in the United States and Germany now underwrite robot deployments against batch throughput guarantees rather than collateral value. This shift is most visible among contract manufacturing organizations serving orphan drug sponsors where production volume uncertainty previously blocked automation investment.
Cleanroom Robots in Healthcare Market Segmentation
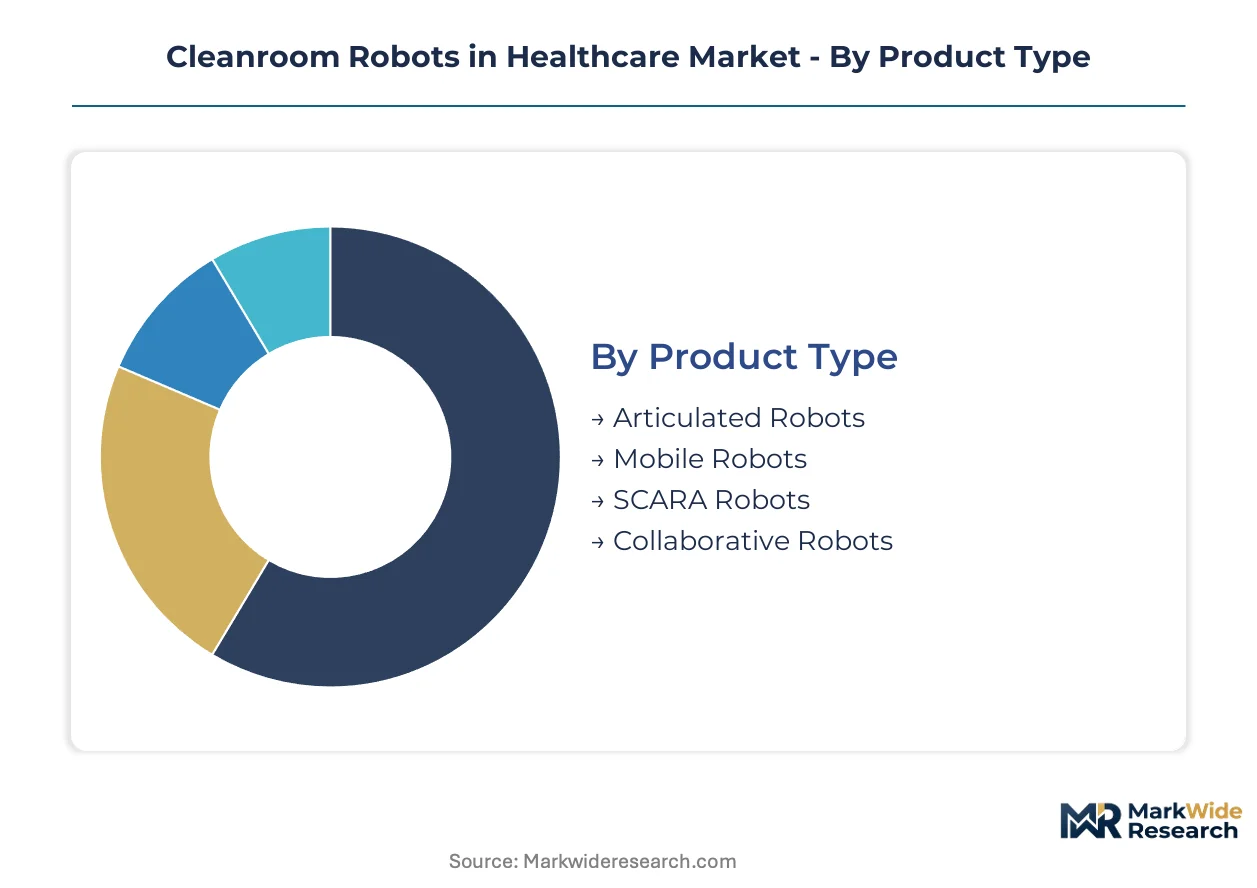
Cleanroom robot deployment varies sharply across healthcare workflows, with contamination control requirements and batch scale dictating hardware selection. Segmentation reveals how pharmaceutical manufacturers prioritize six-axis dexterity while hospitals favor compact mobility for compounding suites.
Product Type:
Use-case spectrum spans from high-repeatability vial manipulation to autonomous corridor transport between sterile zones.
- Articulated Robots:Six-axis kinematic chains with stainless steel enclosures and HEPA-positive-pressure housings execute complex vial handling in aseptic filling lines. German pharmaceutical manufacturers deploy these systems for sterile injectable production under EMA Annex 1 closed-system mandates.
- Mobile Robots:Autonomous platforms with sealed LiDAR navigation cabins eliminate human gowning protocols during material transfer between ISO 14644-1 classified suites. Massachusetts biotech clusters are accelerating procurement as FDA cGMP validation frameworks mature for mobile aseptic transport.
- SCARA Robots:Compact parallel-joint configurations with smooth-surface geometries occupy minimal footprint in space-constrained compounding pharmacies.
- Collaborative Robots:Force-limiting architectures with IP69K-rated sealed joints enable direct human-robot interaction in personalized medicine batch processing.
The dominant share belongs to Articulated Robots, while Mobile Robots is closing the gap fastest.
Application:
Cost tier stratification separates capital-intensive sterile manufacturing from operational expenditure-driven hospital automation.
- Pharmaceutical Manufacturing:Aseptic processing lines for sterile drug production require ISO 14644-1 Class 5 environments with validated robotic intervention replacing manual operations in critical zones. Swiss and German facilities are consolidating supplier relationships for integrated isolator-robot systems under tightening EMA contamination control standards.
- Laboratory Automation:High-throughput screening and analytical workflows demand precision liquid handling with documented traceability for Japan PMDA quality genealogy requirements.
- Surgical Assistance:Sterile instrument delivery and operating room logistics employ mobile platforms with positive-pressure cabins to maintain aseptic integrity.
- Disinfection:UV-C and hydrogen peroxide vapor deployment robots automate terminal cleaning of controlled environments without human re-entry.
Pharmaceutical Manufacturing commands the largest capital allocation, though Laboratory Automation is expanding most quickly as cell and gene therapy workflows proliferate.
Technology:
Application maturity separates proven sensor architectures from emerging AI validation frameworks.
- AI-Driven:Machine vision and adaptive motion planning enable real-time contamination detection and predictive maintenance in aseptic processing zones.
- Remote Monitoring:Cloud-connected telemetry architectures support FDA 21 CFR Part 11 compliant data logging for distributed pharmaceutical manufacturing networks.
- Sensor Integration:Multi-modal particulate, pressure, and temperature sensing with embedded HEPA filtration monitoring ensures continuous ISO 14644-1 compliance verification.
- Machine Learning:Pattern recognition algorithms optimize robot trajectories to minimize air turbulence generation in classified environments.
Sensor Integration holds established deployment share, while AI-Driven capabilities are gaining traction fastest among contract manufacturers seeking throughput guarantees.
End User:
Customer type determines procurement scale and validation complexity, from enterprise biopharma to fragmented hospital networks.
- Hospitals:US health systems and specialty pharmacy chains deploy compact SCARA configurations under USP 800 hazardous drug compounding guidelines, with leasing models displacing capital purchase for mid-sized operators.
- Research Institutions:Academic medical centers and national laboratories pilot collaborative robot configurations for experimental cell therapy manufacturing with batch sizes below 500 units.
- Biotech Companies:Venture-funded cell and gene therapy developers prioritize mobile robot platforms for flexible facility layouts that accommodate rapid process iteration.
- Contract Manufacturers:CDMOs in Switzerland and Massachusetts consolidate automation investment through robotics-as-a-service contracts underwritten against batch throughput rather than collateral value.
Contract Manufacturers represent the largest addressable base, while Hospitals are adopting automation most rapidly as USP 800 enforcement intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA cGMP sterile processing mandates and EMA Annex 1 revisions on closed-system automation are compressing capital deployment timelines across pharmaceutical manufacturing clusters worldwide. National regulators in Germany, Japan, Switzerland, and the United States are tightening contamination control standards that elevate procurement of ISO 14644-1 certified robotic platforms.
United States
Massachusetts biotech corridors and North Carolina Research Triangle pharmaceutical hubs are accelerating mobile robot procurement for flexible aseptic transport. FDA 21 CFR Part 11 validation frameworks for cloud-connected telemetry mature rapidly. Hospital systems in California and Texas deploy compact SCARA configurations under USP 800 hazardous drug compounding enforcement.
Germany
Precision medical device clusters in Baden-Württemberg and Bavaria sustain demand for six-axis articulated systems in automated implantable device assembly. EMA Annex 1 closed-system mandates compress supplier consolidation toward integrated isolator-robot architectures. Swiss-German border pharmaceutical facilities in Basel-Stadt drive cross-border procurement standardization.
Japan
Kanto region pharmaceutical manufacturers and Osaka-based precision equipment fabricators anchor demand for contamination control traceability systems. PMDA quality genealogy requirements favor vendors with embedded data-logging architectures. Nagoya-area automotive precision heritage transfers into medical device robot component supply.
Switzerland
Contract development and manufacturing organizations in Basel and Zürich pilot collaborative robot configurations for personalized medicine batches below 500 units. Swissmedic sterile manufacturing standards align with EMA Annex 1 automation thresholds. Robotics-as-a-service contracts underwritten against batch throughput displace capital purchase among mid-sized contractors.
India
Hyderabad and Bengaluru pharmaceutical formulation clusters expand cleanroom automation for export-oriented generic sterile injectable production. CDSCO manufacturing quality guidelines increasingly reference ISO 13485 traceability requirements. Maharashtra-based contract manufacturers evaluate leasing models to circumvent upfront capital barriers for mid-volume aseptic processing lines.
Cleanroom Robots in Healthcare Market Key Industry Players
Channel-controlling players compete with product-specialist players across tiered market strata. Consolidation concentrates among Japanese and German precision motion control heritage firms with pre-validated contamination control architectures. Three archetypes dominate: integrated system vendors bundling isolator-robot platforms, component specialists supplying harmonic drives and servo motors, and robotics-as-a-service financiers underwriting throughput guarantees. Strategic moves center on supplier consolidation for integrated qualification packages and capacity expansion in stainless steel enclosure fabrication.
Within the precision motion control tier, FANUC Corporation and Yaskawa Electric Corporation exemplify Japanese heritage in high-repeatability aseptic handling. KUKA AG anchors European demand through deep integration with pharmaceutical line builders. These three occupy positions where six-axis dexterity and sealed-environment engineering converge, representing the vendor archetype that EMA and FDA regulatory compression most favors.
| Leading Market Players |
|---|
| ABB Ltd. |
| Denso Corporation |
| FANUC Corporation |
| Kawasaki Heavy Industries, Ltd. |
| Yaskawa Electric Corporation |
| Aerotech, Inc. |
| Nachi Fujikoshi Corporation |
| KUKA AG |
| Omron Corporation |
| Others |
Cost & Logistics Intelligence
Undercapacity in Japanese harmonic drive fabrication is compressing lead times for European system integrators and amplifying pricing power among precision motion component suppliers serving ISO 14644-1 certified robot builders.
Pricing Analysis
Certification level creates the primary spread between ISO 14644-1 Class 3 validated systems and standard industrial configurations. Three-tier pricing structure across premium certified, validated standard, and economy non-certified levels reflects contamination control investment and validation documentation depth. Cost compression in economy tiers is intensifying because mid-sized pharmaceutical contractors are migrating toward robotics-as-a-service contracts. Hospital procurement committees exhibit highest price sensitivity, while contract manufacturers prioritize throughput guarantees over unit economics.
Supply Chain Analysis
Extended payment terms from German pharmaceutical OEMs are cascading stress onto Taiwanese servo motor suppliers and Japanese precision gear manufacturers. Stainless steel enclosure fabrication draws from German, Japanese, and South Korean metallurgical supply bases. Nickel and chromium commodity volatility constitutes the dominant supply chain risk. Distribution runs through pharmaceutical line builders and systems integrators rather than direct robot OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Capital expenditure cyclicality in pharmaceutical manufacturing is entering an upswing phase as EMA Annex 1 compliance deadlines compress automation procurement timelines across European facilities.
For Market Incumbents: Insulate margin pools by deepening captive supply of harmonic drive components and expanding stainless steel enclosure fabrication capacity in Baden-Württemberg. Pre-validated contamination control architectures represent the critical defensive moat against emerging robotics-as-a-service entrants. For New Entrants and Emerging Players: Establish a beachhead in US hospital compounding pharmacy automation where USP 800 enforcement is accelerating procurement of compact SCARA configurations. Leasing-based go-to-market models circumvent capital purchase barriers among mid-sized operators. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among contract manufacturers offering throughput-guaranteed robotics-as-a-service contracts. Long-term viability hinges on regulatory compliance automation capabilities. Watch for FDA validation framework maturation for mobile aseptic transport as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Pre-validated Platform Development | EMA Annex 1 compliance compression favors vendors with integrated qualification packages. |
| Robotics-as-a-Service Expansion | Equipment financiers underwrite deployments against batch throughput guarantees for CDMOs. |
| Stainless Steel Enclosure Capacity Buildout | HEPA-positive-pressure housing fabrication anchors supply security for German pharmaceutical clusters. |
| Harmonic Drive Backward Integration | Japanese precision component sourcing vulnerability demands captive supply chain control. |
| Mobile Robot FDA Validation Pathway | Cloud-connected telemetry architectures require 21 CFR Part 11 compliant data logging maturity. |
Research Approach
A spread of perspectives from pharmaceutical manufacturing executives, cleanroom validation specialists, biomedical engineers, and GPO contracts managers converged on the working assumptions. Primary fieldwork combined with secondary validation against FDA 510(k) filings, EMA submission databases, ISO 14644-1 certification registries, and hospital procurement contract repositories. Bottom-up unit economics triangulated against top-down pharmaceutical capital expenditure tracking.
Demand-supply balance modeling across the analysis window incorporated robot type segmentation, application workflow categories, technology maturity tiers, and end-user procurement scale. CAGRs derived from facility automation investment cycles, regulatory compliance deadline clustering, and biologics manufacturing capacity expansion trajectories. Cell and gene therapy facility buildout rates and personalized medicine batch size trends informed industry-specific forecast inputs.
Sensitivities concentrate around EMA-FDA regulatory divergence, stainless steel alloy cost volatility, and precision component supply disruption. Forecasts reflect documented assumptions on contamination control standard harmonization and pharmaceutical outsourcing intensity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Telepresence Robot Market
Robotics and Automation
GCC AUV Market
Robotics and Automation
Humanoid Robot Market
Robotics and Automation
Global Articulated Robot Market
Robotics and Automation
South America AUV Market
Robotics and Automation
Sweden Robotic Lawn Mower Market
Robotics and Automation
Global IT Robotic Automation Market
Robotics and Automation
Global AI Based Surgical Robots Market
Robotics and Automation
Robotic Desktop Automation (RDA) Market
Robotics and Automation
Global Underwater Robotics Market
Robotics and Automation
Global Mobile Robots Market
Robotics and Automation
Japan Agricultural Robot Market
Robotics and Automation
Metal Fabrication Robots Market
Robotics and Automation
Smart Lawn Robot Market
Robotics and Automation
Global Machine Vision and Vision Guided Robotics Market
Robotics and Automation
Automated Facade Contact Cleaning Robot Market