
 SP Routing and Ethernet Switching Market | 2026-2036
SP Routing and Ethernet Switching Market Size, Share, and Industry Trends Forecast 2026-2036
SP Routing and Ethernet Switching Market Analytics
400G port density is collapsing the cost-per-bit economics for tier-1 backbone upgrades. Cisco Systems leverages its merchant silicon partnerships to sustain router portfolio breadth across enterprise and service provider verticals. Juniper Networks anchors its position through specialized metro aggregation platforms optimized for 5G transport. Huawei competes aggressively on manufacturing scale, though geopolitical restrictions limit its addressable markets in Western geographies.
SP Routing and Ethernet Switching encompasses the hardware and control-plane systems that forward packets across service provider networks using protocols such as BGP, OSPF, and segment routing, with switching fabrics engineered for sub-microsecond latency and five-nines availability. These systems serve as the foundational infrastructure for internet transit, mobile backhaul, and cloud interconnect services. Layer 3 Routing equipment captures the dominant share of capital expenditure as operators replace legacy MPLS cores with segment routing and EVPN architectures. Software Defined Networking is expanding fastest among technology segments, though it remains a smaller revenue pool than hardware-centric switching. Data Centers represent the most concentrated end-user demand vector, driven by AI training clusters requiring spine-leaf architectures with 800G upgrade paths.
The FCC's Broadband Equity, Access, and Deployment program shapes equipment demand through mandated domestic content requirements and technical performance benchmarks. ETSI and the IEEE 802.3 working group define interoperability standards that determine which port speeds and power profiles gain market traction. The EU's F-Gas Regulation and evolving carbon disclosure rules under CSRD are beginning to influence procurement criteria for network equipment. Stakeholders must weigh silicon supply chain concentration against the operational flexibility that merchant chipset ecosystems provide when committing to multi-year platform decisions.
Market Dynamics
AI workload expansion is collapsing refresh cycles for backbone infrastructure, forcing operators to compress five-year depreciation schedules into three-year replacement windows to accommodate 800G port densities.
Growth Catalysts
- Hyperscaler Data Center Buildouts:Cloud service providers are deploying spine-leaf architectures with 400G and 800G interconnects to support distributed AI training clusters, driving concentrated demand for high-density switching platforms.
- FCC Broadband Equity Programs:The Broadband Equity, Access, and Deployment program mandates fiber-to-the-home deployments that require upgraded metro aggregation routers capable of supporting 10G PON backhaul.
- Segment Routing Adoption:Service providers are replacing legacy MPLS cores with SR-MPLS and SRv6 architectures, creating replacement demand for control-plane hardware optimized for source-routing paradigms.
Market Restraints
- Merchant Silicon Supply Concentration:Advanced 7nm and 5nm routing ASICs depend on a concentrated foundry base in Taiwan, creating single-source vulnerability for tier-1 platform vendors.
- Geopolitical Export Controls:US Commerce Department restrictions on semiconductor manufacturing equipment limit Chinese vendor access to leading-edge process nodes, fragmenting global supply availability.
- Copper Interconnect Limitations:Signal integrity constraints at 112G PAM4 serdes speeds restrict passive copper cable reach to under 2 meters, forcing premature optical transceiver adoption in top-of-rack deployments.
Strategic Opportunities
- India Telecom Modernization:The country's national telecom regulator TRAI has accelerated 5G spectrum allocation, creating demand for fronthaul-optimized metro routers in tier-2 and tier-3 cities.
- EU F-Gas Regulatory Tailwind:The F-Gas Regulation is phasing out high-GWP refrigerants in thermal management systems, creating upgrade cycles for liquid-cooled switching platforms with lower environmental compliance costs.
- Convergence of SRv6 and EVPN:Unified control-plane architectures are collapsing separate MPLS and Ethernet VPN operational teams, enabling vendors to capture consolidated procurement budgets from merged network functions.
Industry Challenges
- Segment Routing Engineering Talent Scarcity:Network operators face acute shortages of engineers proficient in SR-MPLS, SRv6, and BGP-LS protocol stacks, delaying production deployments despite hardware readiness.
- Multi-Generational Platform Integration:Brownfield networks must maintain interoperability between legacy VPLS cores and modern EVPN fabrics, complicating migration timelines and testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | SP Routing and Ethernet Switching Market |
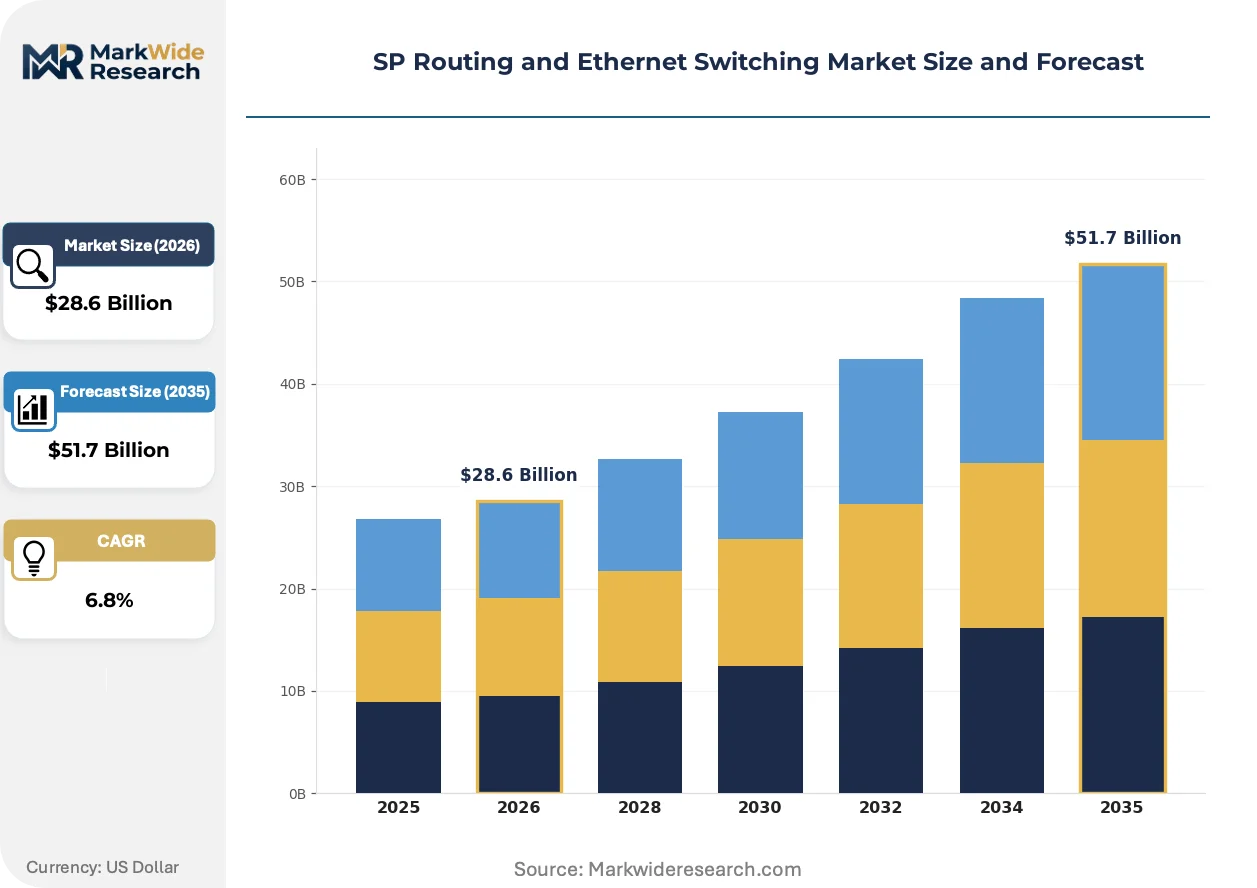
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Router, Switch, Hybrid Device, Access Point Technology: Layer 2 Switching, Layer 3 Routing, MPLS, Software Defined Networking End User: Telecommunications Providers, Data Centers, Enterprises, ISPs Deployment: On-Premises, Cloud-Based, Hybrid, Virtualized |
| Companies Covered | Arista Networks, Hewlett-Packard Enterprise, Cisco Systems, Dell Technologies, Alcatel-Lucent, Juniper Networks, Broadcom, H3C, Huawei, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
SP Routing and Ethernet Switching Market Evolving Landscape
Disaggregation of routing hardware from proprietary software stacks is redistributing value capture across the supply chain, while regulatory pressure on embodied carbon and circularity requirements reshape procurement specifications.
Merchant silicon-based whitebox routers are decomposing the traditional chassis-router market by separating forwarding-plane hardware from network operating systems. Tier-2 cloud operators and cable MSOs are adopting these platforms fastest, lured by 40-60% capital cost reductions. This decomposition is compressing gross margins for integrated-system vendors while expanding addressable market for pure-play NOS suppliers.
The EU's Corporate Sustainability Reporting Directive is mandating granular disclosure of Scope 3 emissions from network equipment procurement. European telecom operators are now embedding circularity requirements into RFPs, demanding modular designs with field-replaceable components and take-back programs. Switching platforms with aluminum enclosures and reduced PCB layer counts are winning preferential vendor status in German and French carrier evaluations.
Hyperscalers are unbundling hardware procurement from multi-year service contracts, treating routers as commodity infrastructure with independently sourced third-party maintenance. This disaggregation is displacing traditional vendor captive-service models in North American data center interconnect deployments. The practice is most visible among cloud providers operating software-defined WAN fabrics across Ashburn, Phoenix, and Dallas metro clusters.
SP Routing and Ethernet Switching Market Segmentation
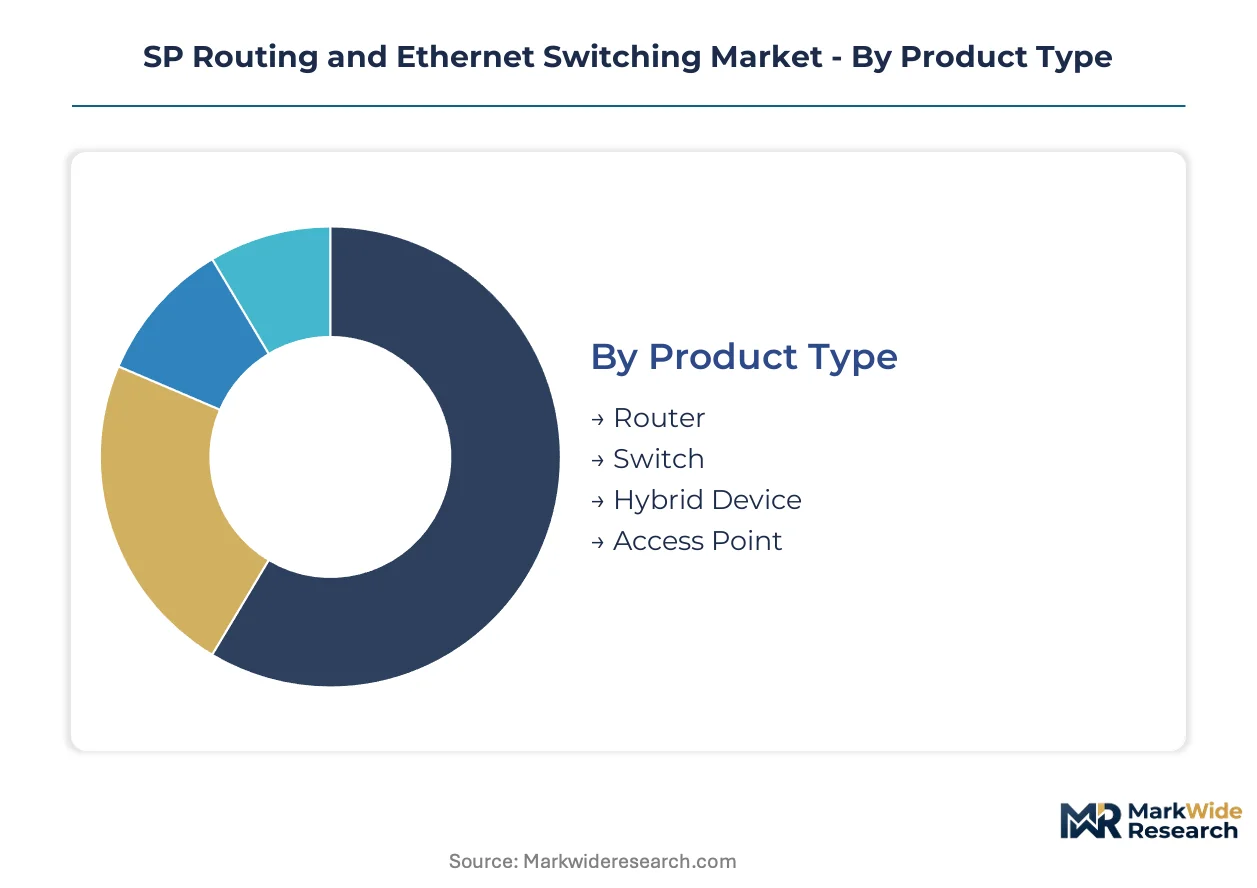
Equipment segmentation in SP routing and Ethernet switching determines procurement channels, with chassis routers flowing through direct vendor relationships while whitebox switches concentrate in hyperscale self-build programs. Technology choices lock operators into multi-year architectural commitments that reshape competitive positioning across the supply chain.
Product Type:
Router platforms dominate direct enterprise sales channels, while switches and access points flow heavier through distributor and systems integrator networks serving mid-market customers.
- Router:Chassis-based systems with modular line cards process BGP updates and segment routing policies at terabit scale. Demand concentrates in United States hyperscaler data center interconnects, where AI training clusters force 800G port density upgrades. FCC broadband infrastructure mandates accelerate metro aggregation router procurement for fiber-to-the-home backhaul.
- Switch:Fixed-form-factor and modular switching fabrics deliver sub-microsecond latency for spine-leaf architectures. Cloud service providers in Ashburn, Phoenix, and Dallas clusters drive concentrated demand for 400G and 800G platforms with merchant silicon economics.
- Hybrid Device:Converged routing-switching platforms collapse separate capital budgets into unified procurement streams.
- Access Point:Edge aggregation devices bridge subscriber-facing ports to core transport networks in cable MSO and telco deployments.
By volume, Switch leads. By growth pace, Router is ahead.
Technology:
Layer 3 Routing commands premium pricing tiers through specialized ASIC requirements, while Layer 2 Switching and SDN compete on volume through merchant silicon commoditization.
- Layer 2 Switching:MAC address learning and VLAN segmentation fabrics serve enterprise campus and data center edge deployments. Manufacturing concentration in Taiwan foundries creates supply vulnerability for advanced 7nm switch ASICs.
- Layer 3 Routing:BGP, OSPF, and IS-IS control planes with hardware-accelerated forwarding engines anchor internet transit and mobile backhaul infrastructure. United States tier-1 operators and cloud providers drive replacement demand as segment routing displaces legacy MPLS cores.
- MPLS:Label-switched path architectures persist in brownfield carrier networks requiring interoperability with modern EVPN fabrics.
- Software Defined Networking:Controller-based traffic engineering with programmable data planes is expanding most quickly among technology segments, though hardware-centric switching retains larger revenue scale.
Layer 3 Routing captures dominant capital expenditure. SDN climbs fastest.
End User:
Telecommunications Providers and Data Centers procure through direct vendor engineering relationships, while Enterprises and ISPs rely more heavily on channel partners and managed service overlays.
- Telecommunications Providers:National and regional carriers operate multi-terabit cores with five-nines availability requirements. India's TRAI 5G spectrum allocations create demand for fronthaul-optimized metro routers in tier-2 and tier-3 cities.
- Data Centers:Hyperscale and colocation facilities deploy spine-leaf architectures with 800G upgrade paths for AI training clusters. United States cloud buildouts concentrate demand in Northern Virginia, Phoenix, and Dallas-Fort Worth metro clusters.
- Enterprises:Financial services and healthcare verticals drive campus routing refresh cycles with SD-WAN integration requirements.
- ISPs:Regional internet service providers aggregate subscriber traffic through cost-optimized routing platforms with 10G PON backhaul interfaces.
Data Centers represent the most concentrated demand vector. Telecommunications Providers show steepest replacement cycle compression.
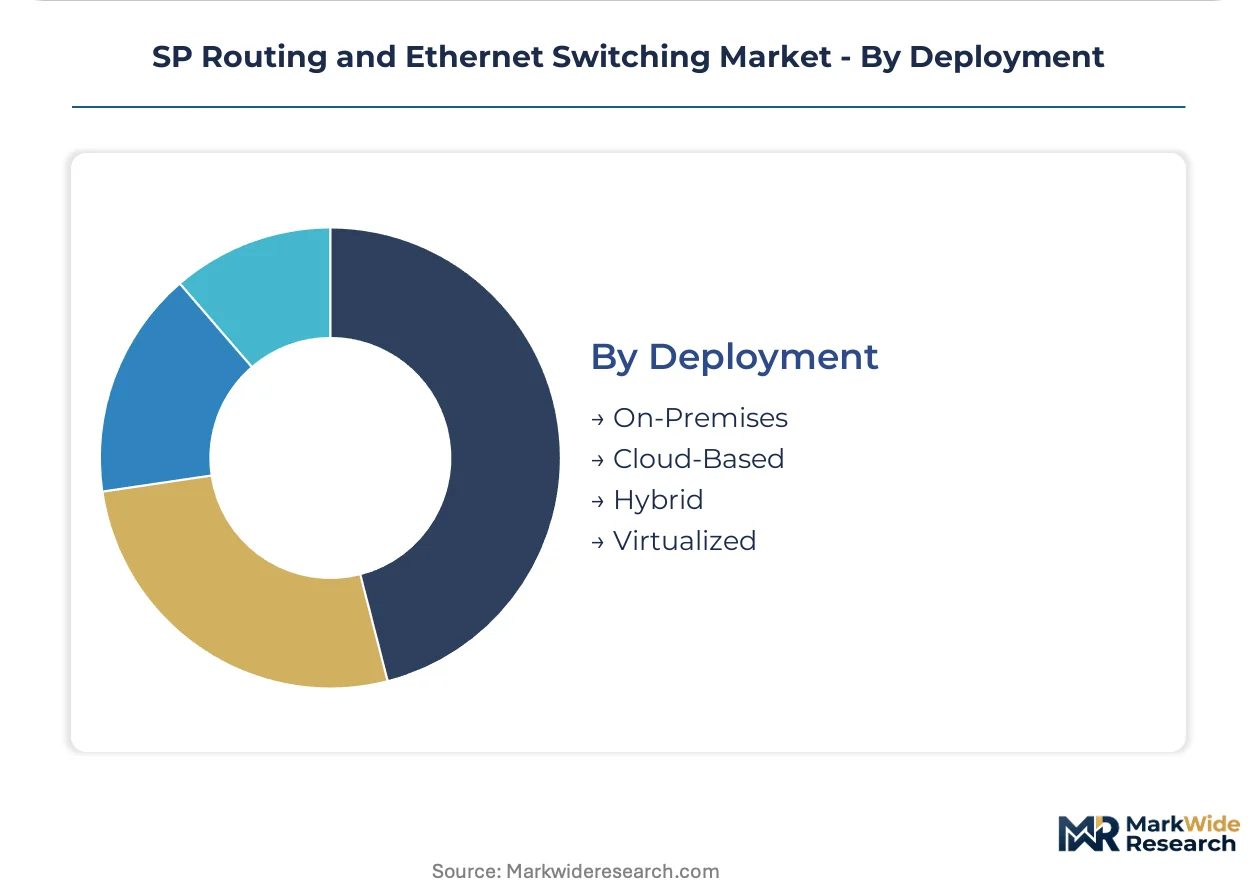
Deployment:
On-Premises deployments sustain traditional vendor service contract models, while Cloud-Based and Virtualized alternatives enable third-party maintenance disaggregation.
- On-Premises:Physical chassis and fixed appliances in operator-owned facilities with dedicated power and cooling infrastructure. European carriers embed EU F-Gas Regulation compliance into RFPs, favoring liquid-cooled platforms with modular field-replaceable components.
- Cloud-Based:Network functions delivered as managed services from hyperscale cloud infrastructure with consumption-based pricing.
- Hybrid:Split control and data plane architectures combining on-premises forwarding with cloud-hosted management.
- Virtualized:Containerized routing software on commodity compute with merchant NICs, displacing purpose-built hardware in cable MSO edge deployments.
On-Premises retains dominant installed base. Virtualized is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and Southeast Asia exhibit acute price sensitivity, compressing vendor margins on standardized switching platforms. United States and German carriers prioritize port density and software programmability over unit cost. Chinese state-directed procurement balances domestic vendor preference against technical performance benchmarks.
United States
Hyperscaler data center buildouts in Northern Virginia, Phoenix, and Dallas-Fort Worth drive concentrated demand for 800G spine-leaf architectures. FCC Broadband Equity, Access, and Deployment program mandates accelerate fiber-to-the-home deployments requiring upgraded metro aggregation routers. Ashburn's data center corridor hosts the densest concentration of AI training cluster interconnect infrastructure globally.
China
State-backed cloud providers expand backbone capacity for domestic AI workloads through MIIT-guided infrastructure investment programs. Dual carbon goals under MEE oversight shape procurement criteria favoring energy-efficient switching platforms with liquid cooling. Yangtze River Delta manufacturing clusters supply merchant silicon for whitebox router ecosystems serving regional telcos.
Germany
Deutsche Telekom and regional carriers embed EU F-Gas Regulation compliance into RFPs for thermal management systems. CSRD-mandated Scope 3 emissions disclosure reshapes vendor evaluation criteria toward modular, field-replaceable designs. Bavaria's industrial automation corridor generates specialized demand for deterministic low-latency switching in manufacturing backhaul networks.
India
TRAI-accelerated 5G spectrum allocation creates fronthaul-optimized metro router demand in tier-2 and tier-3 cities. PLI scheme incentives attract domestic assembly investments for cost-optimized access platforms. Maharashtra and Karnataka host the primary concentration of telecom equipment distribution channels serving the national carrier market.
Japan
METI-directed telecom modernization programs prioritize segment routing adoption for 5G transport networks. JIS standards interoperability requirements filter vendor participation in NTT and regional carrier procurement. Kanto region data center clusters in Tokyo and Saitama Prefecture drive spine-leaf refresh cycles for financial services cloud interconnect.
SP Routing and Ethernet Switching Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. Integrated system vendors command premium positioning through proprietary silicon and multi-service edge portfolios. Merchant silicon specialists capture hyperscale volume through disaggregated hardware-software separation. The dominant competitive moves center on strategic partnerships for ASIC supply security and geographic expansion into India and Southeast Asian markets.
Within the integrated-system tier, Cisco Systems and Juniper Networks occupy positions defined by control-plane software depth and service provider relationships. Arista Networks exemplifies the merchant-silicon archetype through hyperscale-focused switching platforms. Huawei represents the manufacturing-scale archetype, though geopolitical restrictions constrain its addressable markets in Western geographies.
| Leading Market Players |
|---|
| Arista Networks |
| Hewlett-Packard Enterprise |
| Cisco Systems |
| Dell Technologies |
| Alcatel-Lucent |
| Juniper Networks |
| Broadcom |
| H3C |
| Huawei |
| Others |
Value Network & Pricing Analysis
Merchant silicon substitution for proprietary ASICs is redrawing manufacturing geography toward Taiwan foundries while collapsing price premiums that once sustained integrated-system vendor margins. This displacement simultaneously compresses capital costs for hyperscale buyers and fragments pricing power across hardware-software boundaries.
Pricing Analysis
Multi-year service and maintenance contracts generate lifetime value exceeding initial hardware procurement by ratios of three-to-one or greater among tier-1 carriers. Three-tier pricing structure across premium chassis systems, standard fixed-form-factor platforms, and economy whitebox configurations stratifies buyer segments. Cost compression in merchant silicon tiers is intensifying because cloud operators treat routing hardware as fungible infrastructure with independently sourced third-party support. Cable MSOs and regional ISPs exhibit acute price sensitivity, while United States hyperscalers prioritize port density and programmability over unit economics.
Supply Chain Analysis
Taiwan Strait transit vulnerabilities expose the concentrated foundry base that fabricates advanced 7nm and 5nm routing ASICs for tier-1 platform vendors. Manufacturing gravity centers on Taiwan, South Korea, and the United States for leading-edge process nodes, with assembly and test operations distributed across Malaysia and Vietnam. Silicon wafer supply, advanced packaging substrates, and optical transceiver components feed from this geographic cluster. Single-source vulnerability in Taiwanese foundry capacity represents the dominant structural risk. Distribution runs through direct vendor engineering relationships for chassis routers, while merchant silicon platforms flow through hyperscale self-build procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment replacement cycles are compressing from five-year to three-year intervals as AI workload expansion forces backbone infrastructure refresh, positioning this market in an upswing phase of capital expenditure cyclicality.
For Market Incumbents: Compound defensive positioning through captive silicon supply agreements with Taiwan foundries and accelerated SRv6 control-plane certification investments. Whitebox disaggregation threatens integrated-system margins by separating hardware from proprietary software stacks. Vertical integration into merchant silicon partnerships preserves portfolio breadth across enterprise and service provider verticals.
For New Entrants and Emerging Players: CE marking fast-track for liquid-cooled switching platforms unlocks European carrier procurement channels constrained by EU F-Gas Regulation compliance timelines. India's tier-2 and tier-3 cities present the most penetrable geography given TRAI-accelerated 5G spectrum deployment. Fronthaul-optimized metro routers targeting cost-sensitive emerging markets offer the clearest go-to-market angle.
For Investors and Strategic Acquirers: Capital is best deployed toward merchant silicon specialists with established hyperscale relationships and modular thermal management IP. Five-to-ten year viability hinges on sustained disaggregation momentum and regulatory tailwinds for energy-efficient infrastructure. The inflection signal to monitor is segment routing engineering talent scarcity resolving through training program scale-up or persistent deployment delays.
| Strategic Initiative | Industry Significance |
|---|---|
| Merchant Silicon Partnership | Secures ASIC supply continuity for 800G platform roadmaps against Taiwan foundry concentration risk. |
| Liquid Cooling Platform Launch | Captures EU F-Gas Regulation-driven upgrade cycles with modular field-replaceable thermal architectures. |
| SRv6 Certification Investment | Accelerates production deployment timelines delayed by control-plane engineering talent scarcity. |
| India Distribution Expansion | Positions for TRAI-accelerated 5G fronthaul router demand in tier-2 and tier-3 urban clusters. |
| Third-Party Maintenance Disaggregation | Aligns with hyperscaler procurement models treating routing hardware as commodity infrastructure. |
Research Methodology
Desk research of FCC broadband program filings, hyperscaler capital expenditure disclosures, ETSI standards documentation, and IEEE 802.3 working group proceedings preceded structured interviews with service provider network architects, cloud infrastructure procurement officers, router platform engineering directors, and thermal systems product managers. Primary fieldwork combined with secondary validation across SEC 10-K equipment revenue disclosures, carrier RFP documentation, and foundry capacity announcements. Bottom-up equipment unit estimates and top-down infrastructure spending allocations were triangulated for convergence.
Variance decomposition across product type, technology layer, end-user vertical, and deployment model dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from replacement cycle compression dynamics, port density upgrade trajectories, and regulatory mandate timing. Segment routing adoption curves, AI training cluster interconnect scaling, and broadband infrastructure program disbursement schedules provided industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained hyperscale data center buildout momentum and stable Taiwan foundry capacity access; material deviation in either would warrant model refresh. Geopolitical export control expansion or segment routing deployment stall represent specific risk factors that could revise trajectory. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Optical Network Equipment Market
Network Technology
Global 5G Smart Antenna Market
Network Technology
Netops Market
Network Technology
Software-Defined Wide Area Network (SD-WAN) Market
Network Technology
Network Fault Monitoring Tools Market
Network Technology
Home Wi-Fi Router and Extender Market
Network Technology
Global Passive Optical Network (PON) Equipment Market
Network Technology
Gigabit Passive Optical Network (GPON) Market
Network Technology
Cloud Gateway Module Market
Network Technology
Global Network Management Market
Network Technology
UK Fixed Connectivity Market
Network Technology
Digital Repeater Market
Network Technology
Europe Private 5G Network Market
Network Technology
2.4GHz Router Market
Network Technology
Wimax Solutions Market
Network Technology
Managed Switches Market