
 Cognitive Supply Chain Market | 2026-2036
Cognitive Supply Chain Market Size, Share, and Industry Trends Forecast 2026-2036
Cognitive Supply Chain Market Analytics
Cloud infrastructure investment in Singapore's logistics technology corridor is expanding, creating regional capacity for cognitive supply chain platforms. SAP SE leverages deep enterprise integration to anchor large-scale manufacturing deployments across European automotive networks. IBM sustains competitive positioning through specialized Watson supply chain modules that dominate pharmaceutical cold-chain analytics.
Cognitive supply chain systems integrate artificial intelligence, machine learning, and real-time sensor networks to autonomously predict disruptions, optimize inventory positioning, and orchestrate multi-tier supplier responses with sub-second latency. These platforms process streaming telemetry from IoT-enabled warehouses, transportation assets, and production lines to generate prescriptive decisions without human intervention. AI and machine learning technologies capture the dominant margin pool as enterprises prioritize predictive accuracy over retrospective reporting, while logistics optimization applications show the steepest adoption curve among e-commerce fulfillment networks facing last-mile complexity.
The EU AI Act imposes risk-tiered compliance obligations on automated supply chain decision systems, compelling vendors to document algorithmic transparency and human oversight protocols. The FDA's quality system regulation extends into pharmaceutical distribution, requiring validated software for lot tracking and temperature excursion management. Stakeholders must monitor how divergent regulatory timelines across jurisdictions reshape platform architecture requirements and certification costs.
Market Dynamics
EU AI Act risk-tiered compliance obligations are forcing pharmaceutical distributors to rearchitect algorithmic transparency protocols, while semiconductor logistics corridors in South Korea demand sub-second latency integration with national digital infrastructure.
Growth Catalysts
- EU AI Act Algorithmic Documentation Mandates:Automated supply chain decision systems in Germany's pharmaceutical distribution networks must now embed human oversight protocols, accelerating investment in explainable AI platforms that satisfy regulatory audit requirements.
- Semiconductor Cold-Chain Telemetry:South Korea's national digital infrastructure enables real-time inventory synchronization across the Gyeonggi-Incheon logistics corridor, pulling demand for IoT-enabled warehouse management systems with predictive excursion alerts.
- Cloud Infrastructure Expansion:Singapore's logistics technology corridor is adding regional compute capacity specifically architected for cognitive supply chain workloads, reducing latency for ASEAN manufacturing networks.
Market Restraints
- Algorithm Validation Cost Structure:FDA quality system regulation extension into pharmaceutical distribution requires validated software for lot tracking, imposing six-figure certification costs per deployment that freeze mid-tier distributor adoption.
- Sensor Hardware Supply Concentration:Precision temperature and vibration sensors for cold-chain telemetry concentrate among Taiwanese and South Korean component suppliers, exposing platform vendors to single-source disruption risk.
- Legacy ERP Integration Friction:SAP SE's deep enterprise integration anchors European automotive networks, creating switching costs that delay cognitive overlay deployment by 18-24 months in established manufacturing environments.
Strategic Opportunities
- Indian Pharmaceutical Cold-Chain Underpenetration:CDSCO's tightening distribution integrity requirements for temperature-sensitive biologics creates first-mover advantage for AI-driven excursion management platforms in Mumbai-Pune and Hyderabad clusters.
- Digital Twin Convergence with Generative AI:The intersection of physics-based supply chain simulation with large language models enables natural-language disruption scenario planning, compressing response protocol design from weeks to hours.
- Brazilian ANVISA Track-and-Trace Mandate:Serialized pharmaceutical distribution requirements are driving demand for autonomous inventory reconciliation systems that eliminate manual lot verification bottlenecks at distribution centers.
Industry Challenges
- Industrial Data Science Talent Scarcity:The intersection of supply chain operations research and machine learning engineering remains thinly staffed, with pharmaceutical cold-chain analytics requiring hybrid skillsets that command premium compensation in Basel and Boston clusters.
- Multi-Jurisdiction Certification Timeline Compression:Platforms must simultaneously satisfy EU AI Act algorithmic transparency, FDA software validation, and emerging China's NMPA data localization requirements, fragmenting engineering roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cognitive Supply Chain Market |
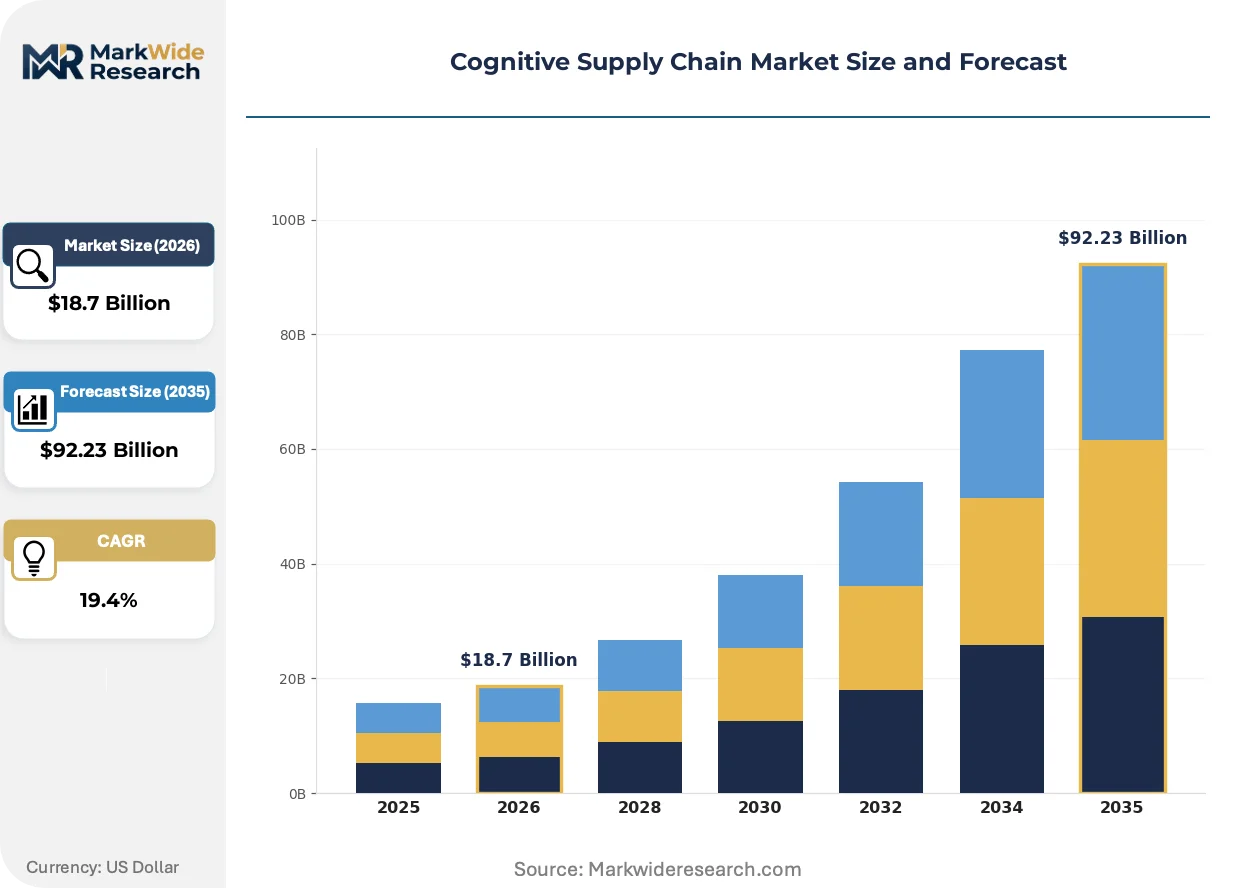
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $92.23 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: AI, Machine Learning, Blockchain, IoT Application: Inventory Management, Demand Forecasting, Risk Mitigation, Logistics Optimization End User: Manufacturers, Retailers, Distributors, E-Commerce Solution: Real-Time Analytics, Predictive Analytics, Automation Tools, Decision Support Systems |
| Companies Covered | Blue Yonder, Honeywell International Inc., IBM, C.H. Robinson Worldwide, Inc., Panasonic, Oracle, SAP SE, Accenture plc, Amazon.com, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cognitive Supply Chain Market Evolving Landscape
Autonomous decision latency is compressing from minutes to milliseconds as edge computing architectures displace cloud-only processing, while regulatory documentation requirements are hardcoding explainability into platform design specifications.
Digital twin technology paired with streaming IoT telemetry from transportation assets and production lines is automating inventory repositioning decisions without human intervention. European automotive networks are deploying these systems at scale, with BMW and Volkswagen Group facilities in Germany and Czechia leading adoption. The technology is automating supplier tier-2 and tier-3 orchestration responses that previously required manual procurement intervention.
REACH chemical substance tracking obligations are extending into packaging material compliance for pharmaceutical distribution, forcing cognitive platforms to embed substance-level genealogy tracing. The regulation requires automated documentation of SVHC content in secondary and tertiary packaging. Cold-chain logistics providers in the Netherlands and Belgium are responding by integrating ECHA database APIs directly into warehouse management system decision layers.
Buyer procurement committees are consolidating vendor evaluation criteria around algorithmic auditability rather than predictive accuracy alone. Pharmaceutical distributors in Switzerland and Germany now require documented human-in-the-loop protocols before platform selection. This behavioral shift is most visible in Basel's biologics distribution cluster, where Swissmedic inspection readiness has become a primary selection filter ahead of feature breadth.
Cognitive Supply Chain Market Segmentation
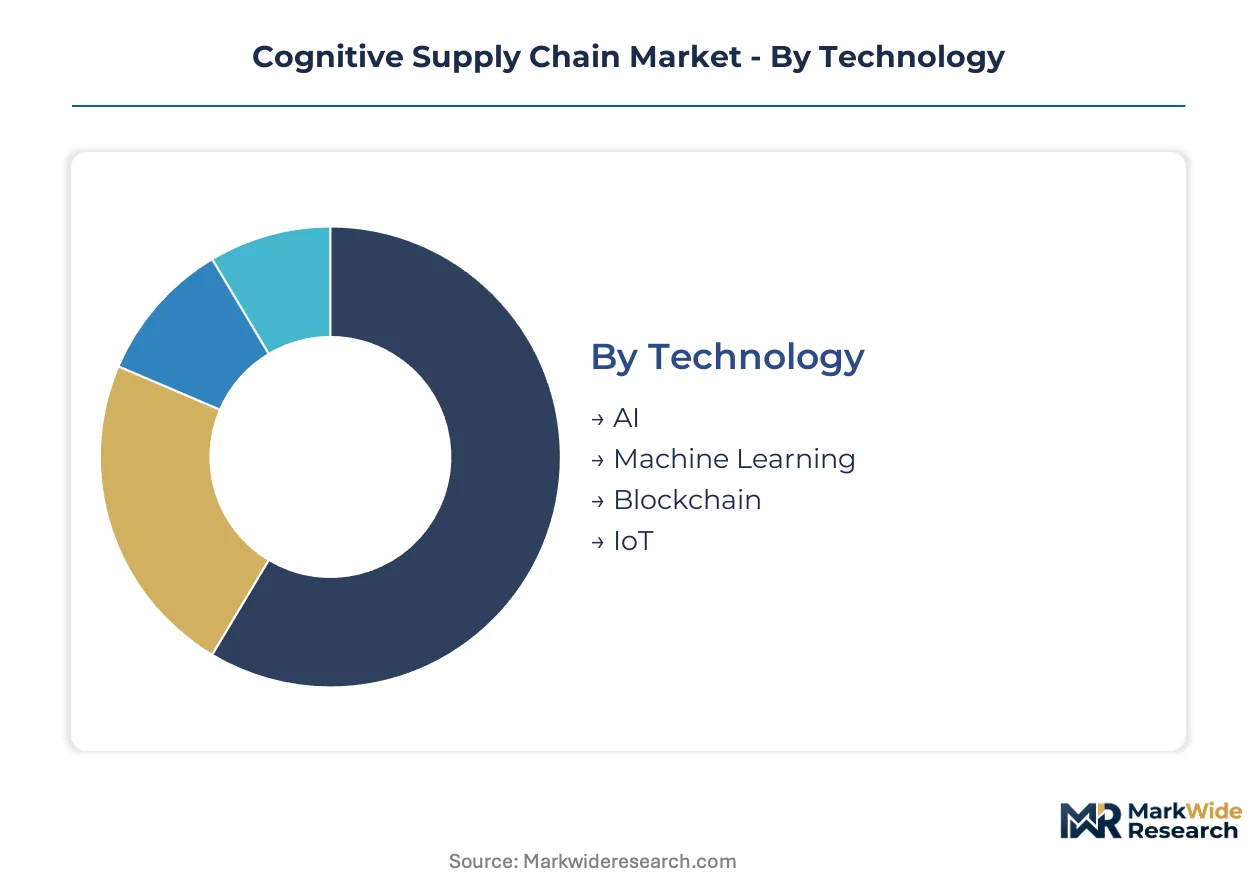
Cognitive supply chain platforms require differentiated architectural investments across technology layers, with AI and machine learning commanding premium infrastructure spend while IoT sensor networks demand distributed hardware deployment. Segmentation reveals where capital concentrates and which solution categories drive margin expansion for vendors.
Technology:
AI and machine learning infrastructure absorbs the heaviest upfront capital, with GPU clusters and specialized training pipelines requiring seven-figure minimum investments before production deployment.
- AI:Neural network architectures for autonomous decision-making process streaming telemetry from warehouse robotics and transportation assets. German pharmaceutical distributors under EU AI Act mandates prioritize explainable AI platforms with documented human oversight protocols for cold-chain excursion management.
- Machine Learning:Predictive models for demand forecasting and inventory positioning train on multi-year transaction histories. South Korea's semiconductor logistics corridor drives concentration here, with real-time synchronization demands pulling sub-second latency requirements into platform specifications.
- Blockchain:Distributed ledger systems for multi-party supply chain verification and immutable transaction records. Pharmaceutical serialization mandates in Brazil and Switzerland accelerate pilot deployments for lot provenance tracking.
- IoT:Sensor networks capturing temperature, vibration, and location telemetry from transportation assets and warehouse environments. Precision hardware concentration among Taiwanese and South Korean component suppliers creates supply vulnerability for platform vendors.
Machine learning absorbs the bulk of installed capacity; AI is expanding most quickly as regulatory documentation requirements hardcode explainability into procurement specifications.
Application:
Application layer spending correlates directly with operational risk exposure, with pharmaceutical cold-chain and semiconductor logistics commanding premium pricing for failure-tolerant systems.
- Inventory Management:Real-time positioning systems synchronize stock levels across multi-tier supplier networks. European automotive manufacturers in Czechia and Germany deploy these for just-in-sequence production line feeding.
- Demand Forecasting:AI-driven prediction engines integrate external signals from weather, macroeconomic indicators, and social sentiment. E-commerce fulfillment networks facing last-mile complexity show the steepest adoption curve here.
- Risk Mitigation:Disruption scenario modeling and autonomous supplier re-routing protocols activate during geopolitical or natural catastrophe events. Basel's biologics distribution cluster prioritizes Swissmedic inspection readiness in platform selection.
- Logistics Optimization:Route planning and carrier selection algorithms minimize cost and carbon exposure across transportation modes. Singapore's expanding cloud infrastructure reduces latency for ASEAN manufacturing network deployments.
Inventory management captures the largest share of current deployment spend; logistics optimization is climbing the fastest as e-commerce networks scale same-day delivery commitments.
End User:
End-user segmentation reflects procurement authority concentration, with large manufacturers and pharmaceutical distributors wielding multi-year contract leverage unavailable to smaller retail operators.
- Manufacturers:Discrete and process industry producers orchestrating tier-2 and tier-3 supplier responses. BMW and Volkswagen Group facilities automate procurement interventions previously requiring manual approval chains.
- Retailers:Omnichannel operators balancing store fulfillment against centralized distribution center efficiency. Inventory positioning decisions increasingly activate without human intervention during promotional demand spikes.
- Distributors:Third-party logistics providers managing temperature-sensitive biologics and serialized pharmaceutical lots. FDA validation requirements for software lot tracking impose six-figure certification costs per deployment.
- E-Commerce:Pure-play and hybrid digital retailers optimizing last-mile delivery density and returns processing. Real-time analytics integration with national digital infrastructure differentiates competitive performance in South Korea.
Manufacturers dominate current platform revenue; e-commerce is gaining share fastest as fulfillment network complexity outpaces legacy system adaptation capacity.
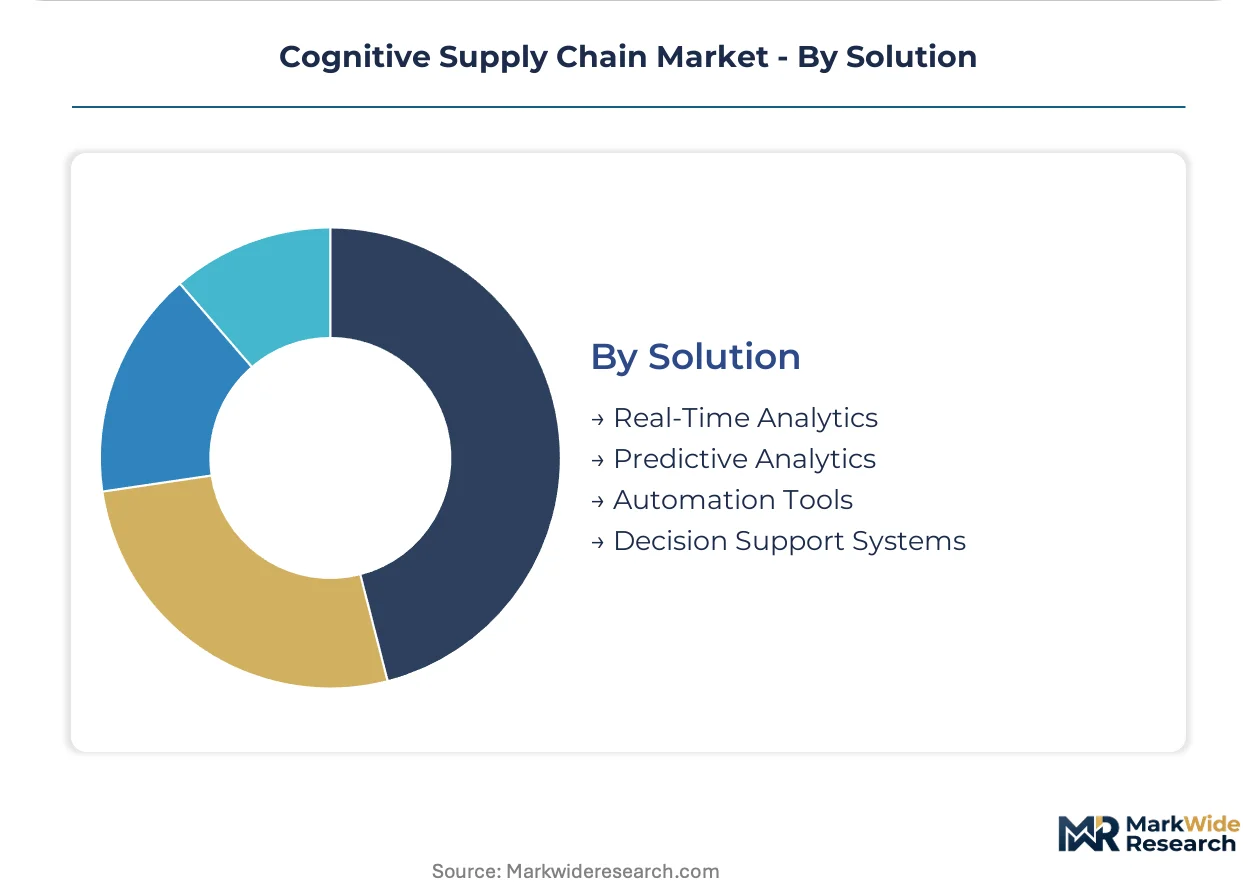
Solution:
Solution architecture determines recurring revenue potential, with predictive analytics platforms commanding subscription premiums over static decision support installations.
- Real-Time Analytics:Streaming data processing architectures delivering sub-second insight from IoT sensor networks. Edge computing displacement of cloud-only processing compresses decision latency from minutes to milliseconds in warehouse environments.
- Predictive Analytics:Forward-looking models anticipating demand spikes, supply disruptions, and maintenance requirements. Pharmaceutical cold-chain analytics in Basel and Boston clusters require hybrid data science skillsets commanding premium compensation.
- Automation Tools:Robotic process automation for purchase order generation, invoice reconciliation, and carrier selection. EU AI Act algorithmic documentation mandates accelerate investment in explainable automation platforms.
- Decision Support Systems:Human-in-the-loop interfaces presenting recommended actions with confidence scoring. Swissmedic and FDA inspection readiness requirements now prioritize documented oversight protocols ahead of feature breadth.
Predictive analytics anchors vendor recurring revenue; real-time analytics is expanding most quickly as edge infrastructure investments mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Semiconductor fabrication clusters in South Korea's Gyeonggi-Incheon corridor anchor Asia-Pacific infrastructure investment, while German automotive networks and US pharmaceutical cold-chain corridors concentrate platform deployment demand.
United States
FDA software validation requirements for pharmaceutical lot tracking and temperature excursion management drive six-figure certification investments per deployment. The IRA's domestic manufacturing incentives accelerate reshoring of semiconductor logistics networks. Boston's biologics distribution cluster commands premium compensation for hybrid data science talent managing cold-chain analytics.
Germany
EU AI Act risk-tiered compliance obligations force pharmaceutical distributors to embed human oversight protocols into automated decision systems. KBA automotive standards intersect with REACH chemical tracking for packaging material compliance. BMW and Volkswagen Group facilities in Bavaria and Baden-Württemberg automate tier-2 and tier-3 supplier orchestration previously requiring manual procurement intervention.
South Korea
Real-time inventory synchronization demands across the Gyeonggi-Incheon semiconductor logistics corridor pull sub-second latency requirements into platform specifications. MFDS pharmaceutical distribution integrity standards accelerate investment in predictive excursion alert systems. National digital infrastructure integration differentiates competitive performance for IoT-enabled warehouse management deployments.
Switzerland
Swissmedic inspection readiness has become a primary platform selection filter ahead of feature breadth in Basel's biologics distribution cluster. CDSCO-aligning distribution integrity requirements for temperature-sensitive biologics create export compliance complexity. Pharmaceutical procurement committees mandate documented human-in-the-loop protocols before vendor selection.
Singapore
Cloud infrastructure expansion specifically architected for cognitive supply chain workloads reduces latency for ASEAN manufacturing network deployments. National logistics technology corridor investments create regional compute capacity for streaming analytics processing. Edge computing displacement of cloud-only processing compresses decision latency from minutes to milliseconds in warehouse environments.
Cognitive Supply Chain Market Competitive Landscape
Global majors compete with regional champions across algorithmic transparency certification and edge infrastructure deployment. Market structure tilts toward consolidated enterprise software vendors with deep ERP integration, though specialized IoT hardware suppliers retain niche dominance in precision sensor categories. Three archetypes dominate: cloud-native analytics platforms, legacy ERP extenders, and cold-chain telemetry specialists. Competitive moves concentrate on strategic partnerships for regulatory certification bundling and geographic expansion through localized compliance engineering.
Within the legacy ERP extender tier, SAP SE and Oracle exemplify deep enterprise integration strategies that anchor European automotive and North American pharmaceutical networks respectively. IBM occupies a position bridging predictive analytics and explainable AI documentation for FDA and EU AI Act compliance requirements. Among cloud-native entrants, Amazon.com represents the logistics optimization vector with fulfillment network density advantages in e-commerce same-day delivery commitments.
| Leading Market Players |
|---|
| Blue Yonder |
| Honeywell International Inc. |
| IBM |
| C.H. Robinson Worldwide, Inc. |
| Panasonic |
| Oracle |
| SAP SE |
| Accenture plc |
| Amazon.com |
| Others |
Value Network & Pricing Analysis
EU AI Act algorithmic transparency mandates are compelling pharmaceutical procurement committees in Basel and Germany to demand documented human-in-the-loop protocols, forcing platform vendors to absorb certification engineering costs that compress margins on mid-tier deployments while premium validated systems command pricing power.
Pricing Analysis
Subscription bundling of FDA-validated software modules with ongoing compliance documentation services anchors the dominant pricing structure, separating premium certified tiers from standard SaaS offerings lacking regulatory audit trails. Price differentiation centers on EU AI Act documentation depth and FDA software validation tier, with pharmaceutical distributors in Switzerland and Germany showing lowest price sensitivity due to Swissmedic inspection readiness requirements. Cost compression in mid-market manufacturing tiers intensifies as SAP SE's deep ERP integration creates switching-cost stickiness. E-commerce fulfillment networks facing last-mile complexity demonstrate highest price sensitivity, prioritizing logistics optimization throughput over predictive analytics sophistication.
Supply Chain Analysis
Freight cost volatility across semiconductor logistics corridors exposes platform vendors to margin pressure, with precision temperature and vibration sensor hardware concentrating among Taiwanese and South Korean component suppliers. Cognitive supply chain infrastructure draws from GPU clusters manufactured in Taiwan, specialized training pipelines anchored in the United States, and edge computing hardware assembled in China and Mexico. Single-source vulnerability in cold-chain telemetry sensors creates supply disruption risk for pharmaceutical distribution deployments. Distribution runs through hyperscaler cloud regions in Singapore, Frankfurt, and Virginia, with regional compute capacity expansion reducing latency for ASEAN manufacturing networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GPU cluster availability and specialized industrial data science talent scarcity prop pricing power for vendors with captive training infrastructure, constraining supply expansion faster than demand growth across pharmaceutical and semiconductor logistics verticals.
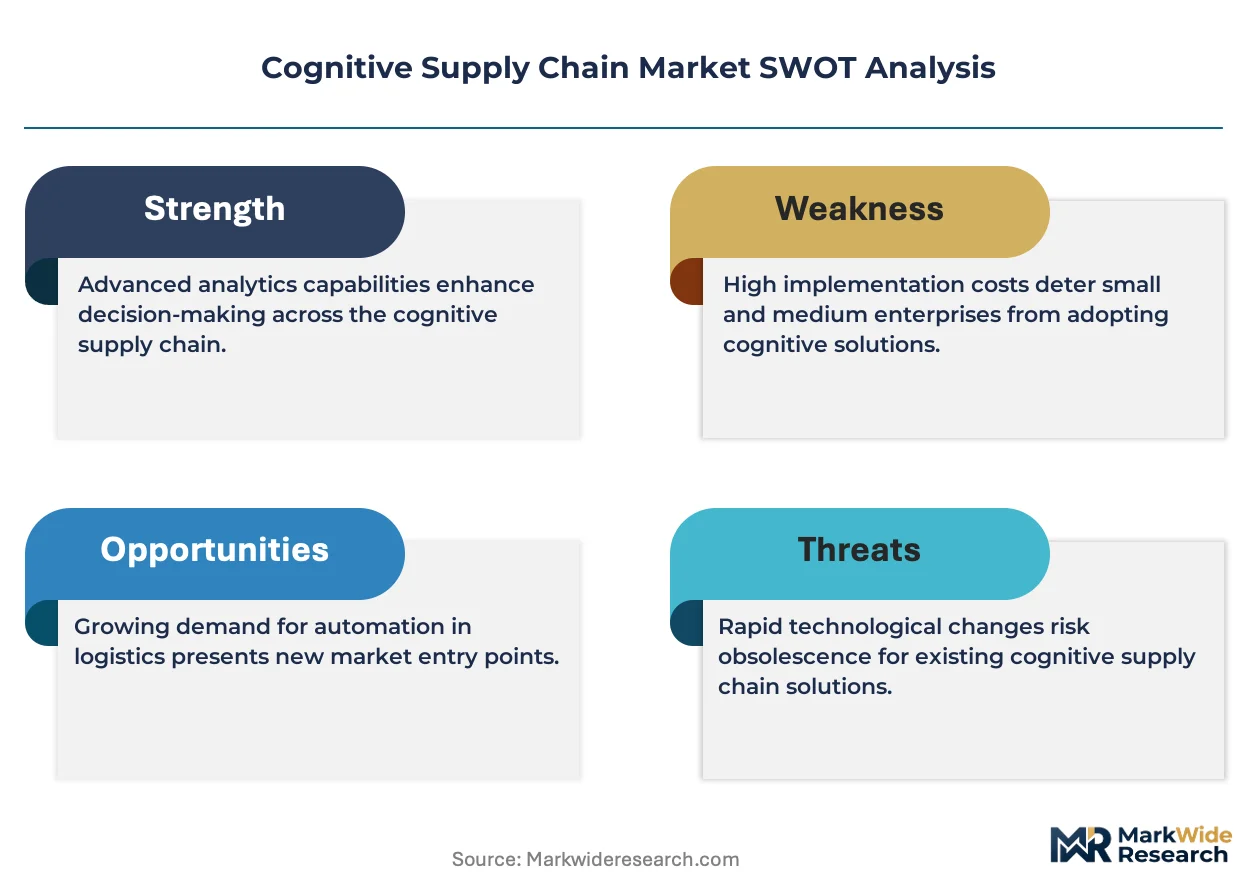
For Market Incumbents: Anchor defensive positioning through backward integration into precision sensor supply chains, securing Taiwanese and South Korean component sourcing against single-source disruption. Deepen EU AI Act certification engineering capabilities to lock in pharmaceutical distributor renewal cycles. SAP SE's ERP anchoring in European automotive networks presents acquisition vulnerability to cloud-native analytics platforms with faster deployment timelines. For New Entrants and Emerging Players: Edge-first architecture compression of decision latency from minutes to milliseconds offers the most penetrable wedge against cloud-incumbent dominance. Target Indian pharmaceutical cold-chain clusters in Mumbai-Pune and Hyderabad where CDSCO distribution integrity requirements outpace incumbent platform localization. Lead with autonomous inventory repositioning pilots demonstrating sub-second telemetry response without human intervention. For Investors and Strategic Acquirers: Re-rating potential sits with cold-chain telemetry specialists possessing FDA-validated software modules given IRA domestic manufacturing incentives accelerating reshoring of semiconductor logistics networks. Long-term viability over the coming decade favors vendors bridging predictive analytics with explainable AI documentation satisfying divergent EU AI Act and FDA regulatory timelines. Watch for algorithmic auditability becoming the primary procurement filter ahead of predictive accuracy as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Certification Bundling | EU AI Act and FDA validation documentation packages lock in pharmaceutical distributor multi-year contracts. |
| Edge Computing Infrastructure Deployment | Singapore's logistics technology corridor expansion reduces latency for ASEAN manufacturing network cognitive platform adoption. |
| Sensor Hardware Backward Integration | Taiwanese and South Korean precision temperature component sourcing secures cold-chain telemetry supply against disruption. |
| Digital Twin Convergence Development | Physics-based simulation paired with large language models compresses pharmaceutical disruption response protocol design timelines. |
| Hybrid Data Science Talent Acquisition | Basel and Boston biologics clusters command premium compensation for supply chain operations research and machine learning engineering skillsets. |
Research Methodology
SEC 10-K filings, ECHA REACH substance tracking disclosures, and hyperscaler cloud infrastructure capex reports formed the secondary backbone, cross-referenced against primary interviews with pharmaceutical distribution operations directors, semiconductor logistics corridor planners, EU AI Act compliance officers, and automotive procurement executives. Bottom-up deployment sizing across technology layers triangulated with top-down vendor revenue analysis.
Historical trendline analysis of cloud infrastructure investment patterns and regulatory certification timeline compression informed the projection framework across the analysis window. Segmentation modeling incorporated technology infrastructure type, application risk exposure tier, end-user procurement authority concentration, and solution architecture recurring revenue potential. CAGRs derived from installed capacity expansion rates and pricing power trajectories in validated pharmaceutical cold-chain versus price-sensitive e-commerce logistics optimization verticals.
Several conditions sit outside the modeled scope, including potential NMPA data localization requirements fragmenting platform architecture roadmaps and unforeseen REACH chemical substance tracking extensions into additional packaging material categories. Forecasts reflect stated assumptions around GPU cluster supply continuity and industrial data science talent pipeline expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Next Generation OSS and BSS Market
Digital Solutions
Global Website Builders Market
Digital Solutions
Online Laundry Services Market
Digital Solutions
IT Operations Management Market
Digital Solutions
Global Continuous Delivery Market
Digital Solutions
Employee Recognition and Reward System Market
Digital Solutions
Disaster Recovery As a Service (Draas) Market
Digital Solutions
Session Replay Software Market
Digital Solutions
Smart Set-Top Box and Dongle Market
Digital Solutions
Model Based Enterprise Market
Digital Solutions
Healthcare Video Conferencing Solutions Market
Digital Solutions
Global Document Scanning Services Market
Digital Solutions
Asia-Pacific Digital Pen Market
Digital Solutions
Global Content Recommendation Engine Market
Digital Solutions
Document Management System Market
Digital Solutions
Data Analytics in the Smart Home Market