
 Automated Liquid Handling Technologies Market | 2026-2036
Automated Liquid Handling Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Liquid Handling Technologies Market Intelligence
Equipment leasing and pay-per-use service models is tilting competitive dynamics toward vendors with strong recurring revenue infrastructure. Thermo Fisher Scientific leverages its global service network to anchor multi-site fleet contracts. Eppendorf AG specializes in compact benchtop systems that compete for space-constrained academic laboratories. Hamilton Company controls premium niches through in-house production of precision syringe pumps.
Automated liquid handling technologies encompass electromechanical systems that transfer precise microliter-to-milliliter volumes through programmable pipetting heads, typically achieving accuracy within one percent at sub-microliter ranges for genomic and proteomic workflows. These systems integrate robotic arms, disposable tip changers, and software-controlled calibration to eliminate human pipetting variation in high-throughput environments. Robotic workstations dominate capital expenditure budgets due to their throughput scalability in pharmaceutical compound management. Air displacement technology occupies the largest installed base, though piezoelectric systems are capturing share in nanoliter dispensing for next-generation sequencing library preparation. Academic institutions represent a growing procurement segment as federal research funding expands access to automation.
FDA 21 CFR Part 11 compliance requirements shape software architecture and audit trail capabilities across all US-deployed platforms. EPA Good Laboratory Practice standards extend validation burdens to environmental toxicology applications, while ISO 8655 pipette calibration protocols define metrological benchmarks that manufacturers must satisfy for European market access. Stakeholders should monitor how emerging EU AI Act conformity obligations will affect algorithmic liquid handling optimization tools before committing to platform roadmaps.
Market Dynamics
Contract research organizations now compress drug discovery timelines through automated workflows, forcing instrument vendors to restructure pricing around throughput guarantees rather than capital equipment sales.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records mandates push laboratories toward validated, traceable liquid handling platforms with audit-ready software architecture.
- Genomic and proteomic workflows:Sub-microliter accuracy requirements in next-generation sequencing library preparation accelerate replacement of manual pipetting.
- Boston and San Diego clusters:Biopharma R&D concentration in these metropolitan areas concentrates instrument procurement demand and shapes vendor service network investments.
Market Restraints
- Precision syringe pump supply:In-house production capabilities concentrate among a limited set of manufacturers, creating bottlenecks for premium system assembly.
- ISO 8655 calibration protocols:European metrological benchmarks extend validation timelines and compliance costs for market access.
- Manual pipetting labor pools:Low-cost technician availability in certain research environments delays automation adoption in budget-constrained settings.
Strategic Opportunities
- Academic procurement expansion:Federal research funding growth opens access to benchtop automation for space-constrained university laboratories.
- EU AI Act conformity:Algorithmic liquid handling optimization tools face emerging compliance obligations that early-mover vendors can shape.
- Piezoelectric-nanoliter convergence:Integration of non-contact dispensing with genomic workflows creates white space in next-generation sequencing preparation.
Industry Challenges
- Mechatronics engineering talent:Shortage of specialists who bridge precision fluid dynamics with robotic control systems constrains R&D velocity.
- Legacy LIMS integration:Software interoperability gaps between new automated platforms and existing laboratory information management systems extend deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Liquid Handling Technologies Market |
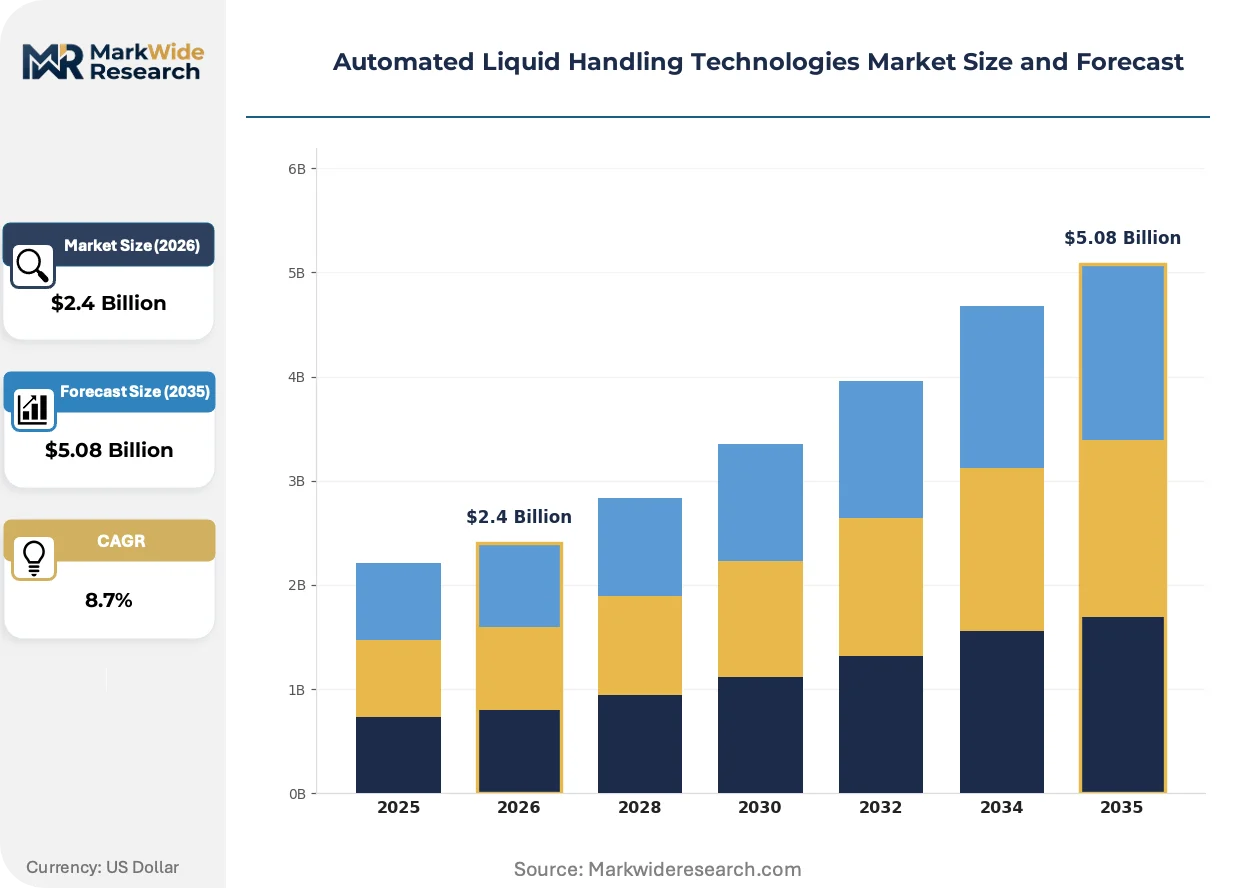
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Micropipettes, Automated Pipetting Systems, Liquid Dispensers, Robotic Workstations Technology: Positive Displacement, Air Displacement, Piezoelectric, Ultrasonic End User: Pharmaceutical Companies, Biotechnology Firms, Academic Institutions, Clinical Laboratories Application: Drug Discovery, Genomics, High Throughput Screening, Protein Engineering |
| Companies Covered | Tecan Trading AG, PerkinElmer, Thermo Fisher Scientific, Eppendorf AG, QIAGEN, Agilent Technologies, Hamilton Company, Sartorius AG, Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Liquid Handling Technologies Market Strategic Shifts & Innovations
Electromechanical precision and regulatory software architecture are converging to redefine competitive advantage in liquid handling, with vendors racing to embed compliance into hardware design rather than retrofitting it.
Piezoelectric non-contact dispensing technology achieves nanoliter precision through acoustic ejection mechanisms that eliminate mechanical tip contact. Genomics core facilities and contract sequencing providers are adopting these systems at accelerating pace for library preparation workflows. This capability is rendering obsolete air-displacement pipetting in applications requiring sub-microliter reproducibility.
EPA Good Laboratory Practice standards now extend validation documentation requirements to environmental toxicology applications using automated liquid handling. Manufacturers must architect audit trails and electronic signature capabilities into platform software from initial design. Environmental testing laboratories in the United States face the steepest compliance burdens as they retrofit existing workflows.
Service unbundling now separates instrument hardware from maintenance contracts and reagent supply agreements. Biopharma compound management facilities increasingly procure through multi-site fleet contracts with performance-based uptime guarantees rather than traditional capital purchase models. This pattern concentrates in United States coastal clusters where vendor service network density enables rapid response commitments.
Automated Liquid Handling Technologies Market Segmentation
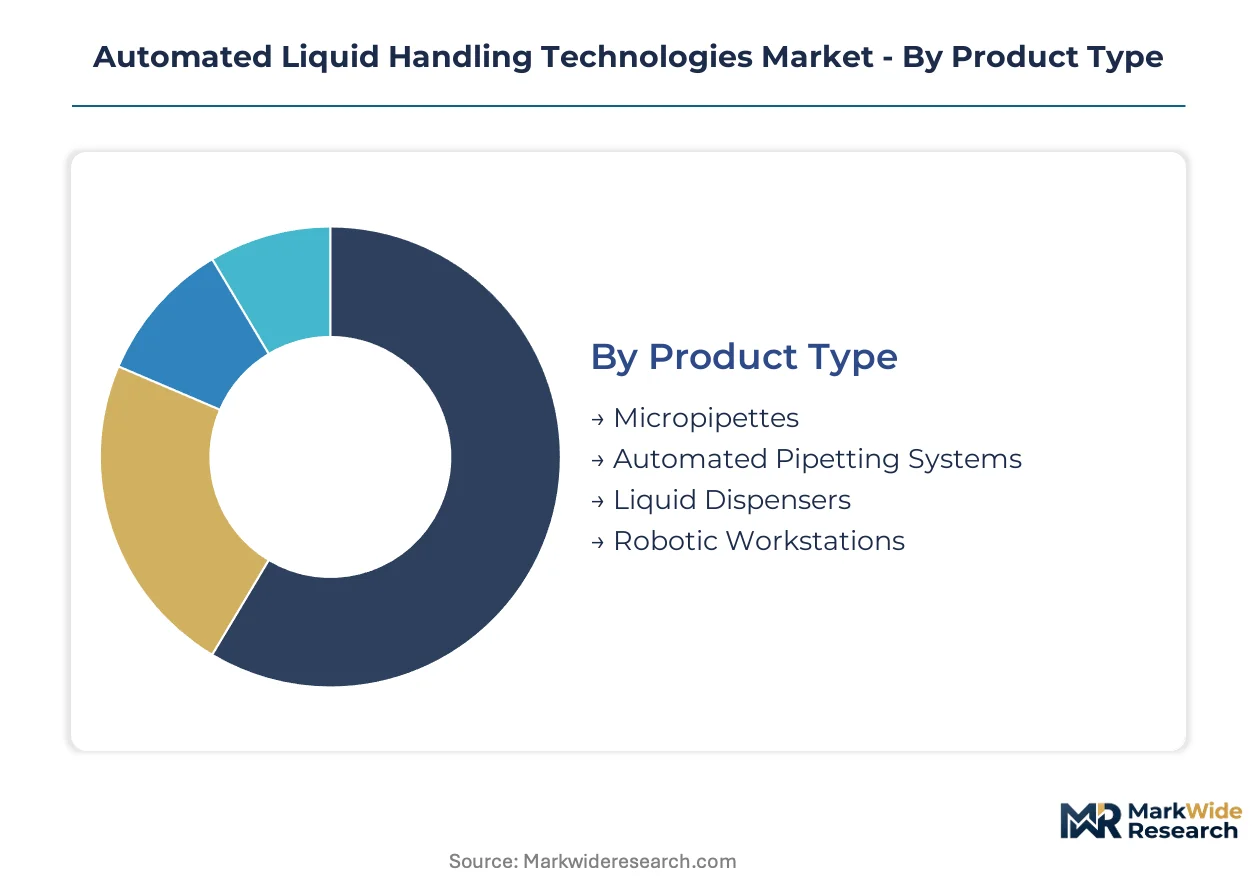
Automated liquid handling technologies fragment across hardware configurations, fluid transfer mechanisms, and end-use workflows. Each dimension carries distinct procurement patterns, validation burdens, and service attachment rates that reshape vendor go-to-market priorities.
Product Type:
Equipment cost tiers separate capital-intensive robotic installations from benchtop units accessible to smaller laboratories.
- Micropipettes:Handheld precision instruments remain ubiquitous in basic research settings. Academic core facilities in Boston and San Diego maintain extensive fleets for routine sample preparation despite automation pressure.
- Automated Pipetting Systems:Programmable multi-channel platforms eliminate technician variation in serial dilution protocols. Contract research organizations deploy these systems to compress compound management timelines and meet FDA 21 CFR Part 11 audit requirements.
- Liquid Dispensers:Bulk reagent distribution units serve high-volume media preparation workflows. Environmental toxicology laboratories under EPA Good Laboratory Practice mandates favor validated dispenser architectures with embedded audit trails.
- Robotic Workstations:Integrated systems combine pipetting heads with plate handling and incubation modules. Biopharma R&D clusters drive concentrated procurement of these capital-intensive platforms through multi-site fleet contracts.
Robotic workstations command the established base. The steepest expansion runs through automated pipetting systems.
Technology:
Fluid displacement mechanisms differentiate by precision thresholds, contamination risk, and compatibility with volatile or viscous reagents.
- Positive Displacement:Piston-driven systems achieve direct volume control without air compression effects. Viscous sample handling in protein engineering workflows concentrates demand among specialty CROs.
- Air Displacement:Compressed-air pipetting dominates the installed base through cost efficiency and tip compatibility. Genomics laboratories retain these systems for microliter-range library preparation where nanoliter precision remains unnecessary.
- Piezoelectric:Acoustic ejection mechanisms dispense nanoliter volumes without mechanical tip contact. Next-generation sequencing providers adopt these platforms fastest as sub-microliter reproducibility becomes workflow-critical.
- Ultrasonic:High-frequency vibration enables non-contact dispensing of challenging fluids including surfactants and organic solvents. Niche adoption concentrates in drug discovery screening of compound libraries with diverse physiochemical properties.
Air displacement technology anchors current installations. Piezoelectric systems are climbing the fastest as genomic precision requirements tighten.
End User:
Customer type determines procurement authority structures, funding mechanisms, and service contract sophistication.
- Pharmaceutical Companies:Integrated drug developers operate centralized compound management facilities with validated automation architectures. Multi-year service agreements with uptime guarantees replace traditional capital purchase models.
- Biotechnology Firms:Venture-funded developers prioritize benchtop flexibility and rapid deployment over throughput scale. Space-constrained laboratory footprints in Boston and San Diego clusters favor compact system configurations.
- Academic Institutions:Federal research funding expansion opens automation access to university core facilities previously constrained by capital budgets. Benchtop automated pipetting systems capture growing procurement share in space-limited settings.
- Clinical Laboratories:Diagnostic service providers face distinct regulatory pathways for patient sample handling. FDA oversight of laboratory-developed tests shapes validation documentation requirements for automated platforms.
Pharmaceutical companies dominate current revenue. Academic institutions are gaining share fastest as funding mechanisms democratize access.
Application:
Workflow-specific throughput and precision requirements drive technology selection and platform configuration decisions.
- Drug Discovery:High-density compound library management demands integrated storage, retrieval, and dispensing automation. CRO pricing models now structure around throughput guarantees rather than equipment ownership.
- Genomics:Next-generation sequencing library preparation requires nanoliter precision and cross-contamination elimination. Piezoelectric non-contact dispensing is displacing air-displacement methods in this application fastest.
- High Throughput Screening:Massive parallel assay execution drives robotic workstation deployment with integrated plate handling. Biopharma R&D clusters concentrate demand for these capital-intensive integrated systems.
- Protein Engineering:Viscous lysate handling and precise buffer exchange favor positive displacement mechanisms. Specialty biotechnology firms with directed evolution pipelines anchor this application segment.
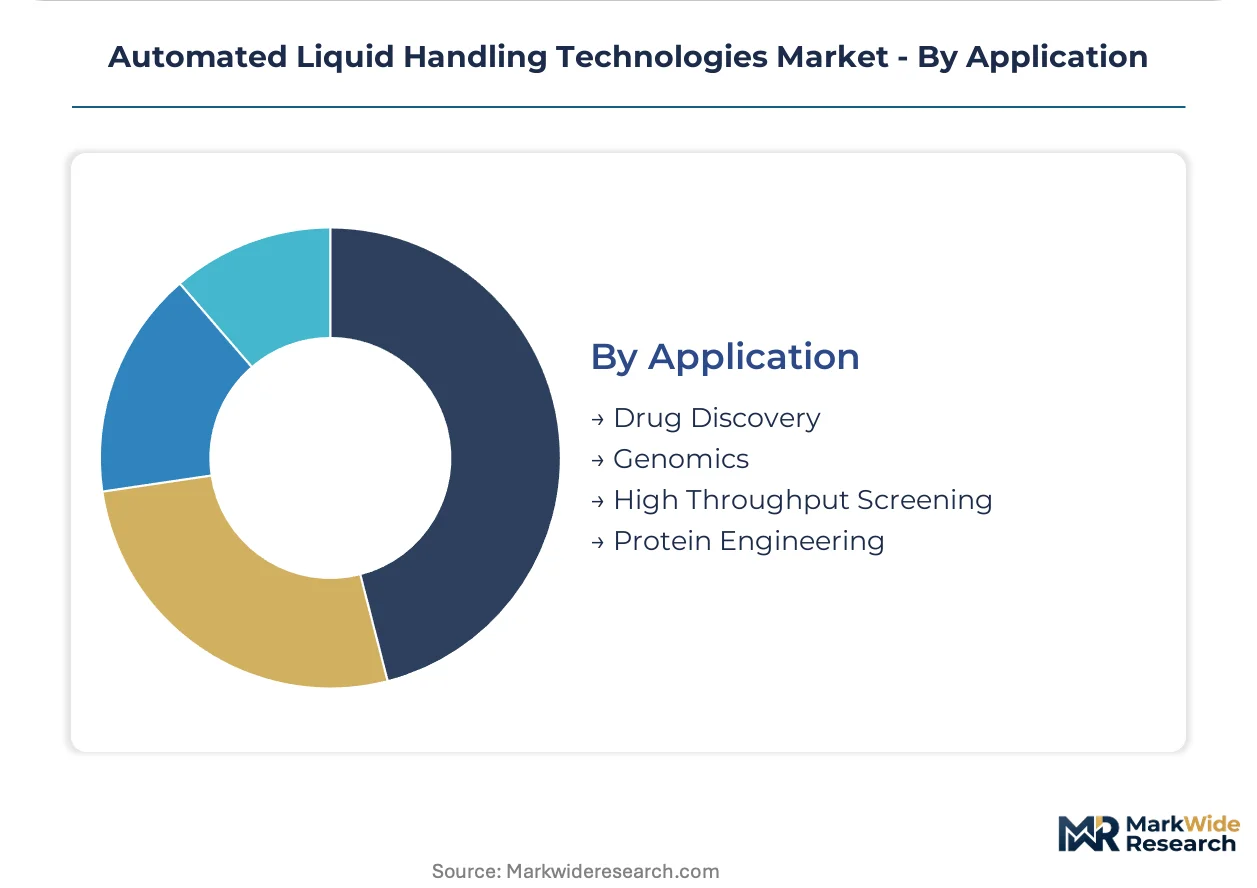
Drug discovery anchors established demand. Genomics is expanding most quickly as sequencing throughput requirements accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biopharma R&D clusters concentrate procurement authority among contract research organizations and integrated drug developers seeking validated automation architectures. FDA 21 CFR Part 11 mandates reshape software requirements for US-deployed platforms. European metrological standards and emerging AI conformity obligations create divergent compliance pathways across jurisdictions.
United States
Boston and San Diego biopharma clusters drive concentrated demand for robotic workstations with multi-site fleet contracts. FDA 21 CFR Part 11 electronic records mandates require audit-ready software architecture in all laboratory-deployed platforms. Environmental toxicology laboratories under EPA Good Laboratory Practice standards face steep validation burdens for retrofitting existing workflows.
Germany
Precision engineering heritage supports domestic production of syringe pump components for premium system assembly. ISO 8655 pipette calibration protocols define metrological benchmarks that manufacturers must satisfy for European market access. Baden-Württemberg industrial clusters anchor metrology instrument development serving pharmaceutical quality control applications.
China
Genomics service providers scale next-generation sequencing throughput driving adoption of nanoliter-precision dispensing platforms. NMPA medical device regulations shape validation documentation requirements for diagnostic applications. Yangtze River Delta biotechnology parks concentrate contract research organization expansion and automation procurement.
Switzerland
Pharmaceutical headquarters operations demand integrated compound management automation with multi-year service agreements. Swissmedic regulatory oversight extends to laboratory-developed test platforms requiring traceable liquid handling validation. Basel biopharma corridor concentrates procurement of high-throughput screening workstations.
United Kingdom
Academic core facilities expand automation access through research council funding mechanisms prioritizing benchtop flexibility. MHRA guidance on in-vitro diagnostic regulation shapes validation requirements for clinical laboratory platforms. Cambridge life sciences cluster drives procurement of compact systems for space-constrained university settings.
Automated Liquid Handling Technologies Market Key Industry Players
Channel-controlling players compete with product-specialist players across fragmented tier structures. Precision component fabrication and software validation capabilities separate premium positioning from cost-optimized alternatives. Two strategic archetypes dominate: integrated life sciences conglomerates with global service networks, and focused precision engineering specialists with captive syringe pump production. Competitive moves concentrate on multi-site fleet contract capture and algorithmic optimization tool development.
Within the precision engineering tier, Hamilton Company and Eppendorf AG exemplify specialist positioning through in-house manufacturing discipline. Thermo Fisher Scientific represents the integrated conglomerate archetype with service network density enabling rapid response commitments. Tecan Trading AG and PerkinElmer occupy positions between these poles, with geographic origins in Switzerland and United States respectively shaping their regulatory compliance expertise.
| Leading Market Players |
|---|
| Tecan Trading AG |
| PerkinElmer |
| Thermo Fisher Scientific |
| Eppendorf AG |
| QIAGEN |
| Agilent Technologies |
| Hamilton Company |
| Sartorius AG |
| Danaher Corporation |
| Others |
Cost & Logistics Intelligence
Trans-Pacific freight corridors from Shanghai to Long Beach transmit cost volatility through precision syringe pump supply chains, concentrating margin pressure on European and North American system integrators while enabling tiered pricing separation between validated FDA-compliant platforms and unvalidated alternatives.
Pricing Analysis
Cost-plus contracts indexed to rare-earth magnet prices govern long-term agreements between robotic workstation manufacturers and precision motor suppliers. Three-tier pricing structure across premium, standard, and economy levels separates Hamilton Company and Tecan Trading AG configurations from Eppendorf AG benchtop units and unbranded Asian alternatives. Price differentiation hinges on ISO 8655 calibration certification and FDA 21 CFR Part 11 software validation. Pricing pressure stems from academic procurement expansion as federal funding constraints compress capital equipment budgets. Biotechnology firms in Boston and San Diego clusters exhibit lowest price sensitivity due to venture-backed procurement authority.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for electromechanical component sourcing. Precision syringe pump fabrication concentrates in Germany, Switzerland, and Japan, with stepper motor controllers drawing from Taiwanese semiconductor foundries. Ceramic piston materials and piezoelectric actuators anchor raw material dependencies. Single-source vulnerability persists for nanoliter-precision acoustic ejection modules. Distribution runs through authorized service networks with multi-site fleet contract provisioning rather than direct equipment sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Manual pipetting labor pools in emerging research economies constitute a latent substitute threat that automation vendors must neutralize through total-cost-of-ownership demonstration and workflow integration depth.
For Market Incumbents: Entrench service network density in Boston and San Diego biopharma corridors to anchor multi-site fleet contract renewals. Deepen backward integration into precision syringe pump production to insulate margins from ceramic piston supply volatility. Counter acoustic dispensing substitutes by embedding piezoelectric modules into genomic workflow-optimized platforms. For New Entrants and Emerging Players: Establish a beachhead in academic core facilities through benchtop automated pipetting systems with rapid deployment architectures. Target space-constrained university laboratories in United Kingdom and German research clusters where federal funding expansion opens procurement access. Pursue channel partnerships with laboratory supply distributors rather than direct field sales investment. For Investors and Strategic Acquirers: EU AI Act conformity obligations reshape the acquisition landscape for algorithmic liquid handling optimization tools. Five-to-ten-year viability favors precision engineering specialists with captive syringe pump production and validated software architectures over hardware-assemblers dependent on outsourced components. Monitor NMPA medical device registration timelines in China as inflection indicator for genomics service provider automation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Service Network Expansion | Multi-site fleet contracts in Boston and San Diego clusters require rapid response uptime guarantees. |
| Precision Component Backward Integration | In-house syringe pump production insulates Hamilton Company and Eppendorf AG from ceramic piston supply bottlenecks. |
| Algorithmic Optimization Tool Development | EU AI Act conformity obligations create first-mover advantage for validated software architectures. |
| Academic Channel Partnership | Federal funding expansion opens benchtop automation access to space-constrained university laboratories. |
| Piezoelectric-Nanoliter Convergence | Acoustic ejection modules displace air-displacement methods in next-generation sequencing library preparation workflows. |
Research Approach
The analysis maps robotic workstations, automated pipetting systems, liquid dispensers, and micropipettes, each validated through laboratory directors, biopharma procurement managers, CRO operations leads, and academic core facility managers. Primary interviews with these stakeholders combined with secondary validation from FDA 510(k) filings, EPA Good Laboratory Practice guidance documents, ISO 8655 calibration standards, and NMPA medical device registration databases. Bottom-up instrument shipment tracking and top-down R&D expenditure triangulation anchored market sizing.
Assumptions held fixed include FDA 21 CFR Part 11 compliance persistence, ISO 8655 metrological benchmark continuity, and federal research funding trajectory across the analysis window. Segmentation dimensions modeled encompass product type, fluid transfer technology, end-user archetype, and application workflow. CAGRs derived from logistic diffusion curves fitted to adoption patterns in pharmaceutical compound management and genomics core facilities. Forecast inputs incorporated NGS throughput expansion rates and CRO automation penetration thresholds.
Sensitivities concentrate around EU AI Act implementation timelines, NMPA diagnostic platform registration velocity, and precision syringe pump supply disruptions. Forecasts reflect these assumptions without claiming predictive certainty. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Exoskeleton Systems Market
Robotics and Automation
Painting Robot Market
Robotics and Automation
Long-Range Drone Package Delivery Market
Robotics and Automation
Europe Cloud Robotics Market
Robotics and Automation
Asia-Pacific Logistics Robotics Market
Robotics and Automation
Robot Charging Station Market
Robotics and Automation
Mobile Cobots Market
Robotics and Automation
Soft Exoskeleton Market
Robotics and Automation
Robotics Sweeper Market
Robotics and Automation
Mobile Robot Charging Station Market
Robotics and Automation
Autonomous Security Robots Market
Robotics and Automation
Drone Package Delivery Market
Robotics and Automation
Aerospace Service Robotics Market
Robotics and Automation
Virtual 3D Nanorobots Market
Robotics and Automation
Robotics for NDT Market
Robotics and Automation
Smart Exoskeleton Market