
 Humanoids Market | 2026-2036
Humanoids Market Size, Share, and Industry Trends Forecast 2026-2036
Humanoids Market Foresight
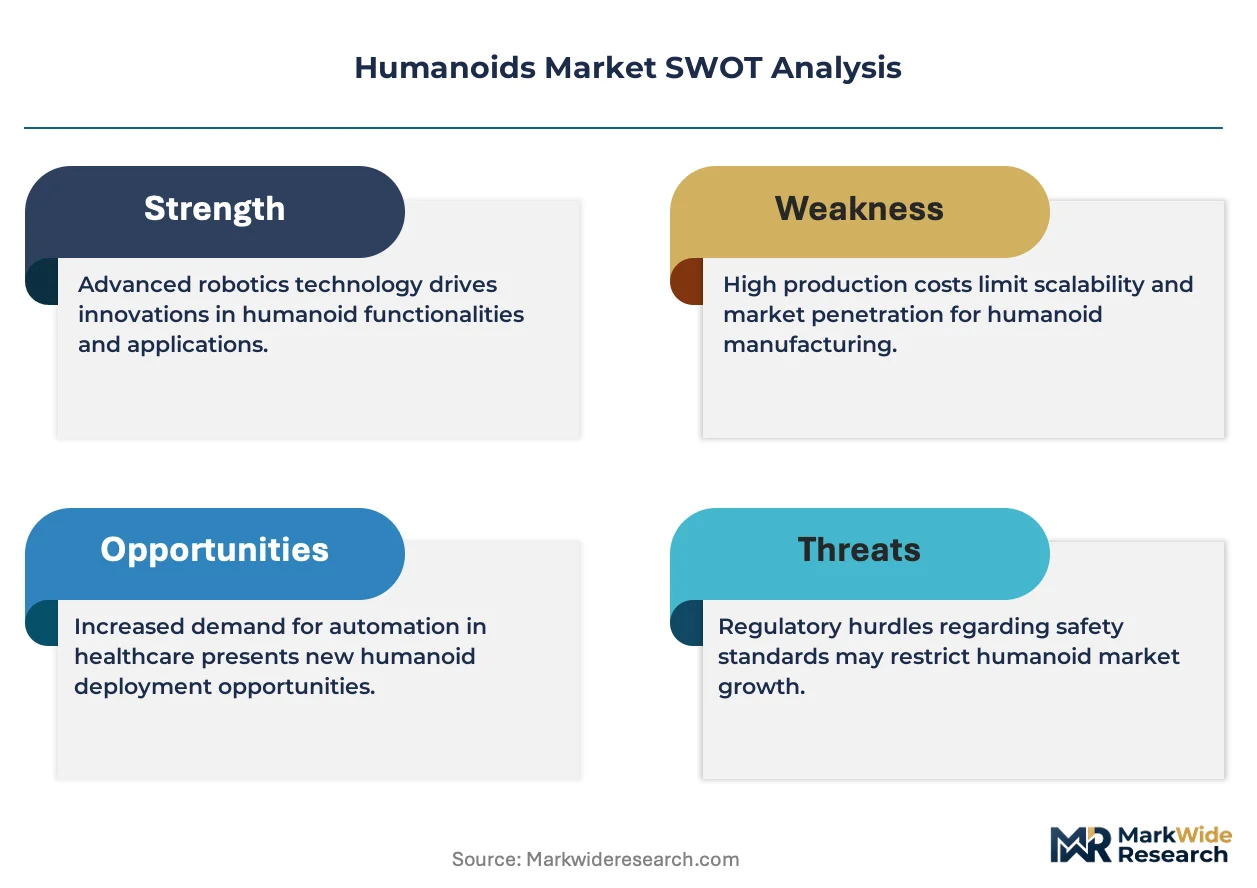
The EU AI Act is realigning product development priorities for humanoid developers serving European industrial buyers. Tesla leverages its battery and AI stack to anchor manufacturing cost curves for bipedal platforms. Boston Dynamics specializes in dynamic locomotion systems that differentiate its hardware for inspection and logistics environments. Figure AI competes through partnerships with automotive assembly lines seeking flexible manipulation capabilities.
Humanoids are electromechanical systems with bipedal locomotion, multi-degree-of-freedom manipulators, and sensor-integrated control architectures designed for task execution in human-engineered spaces. Service robots occupy the largest revenue pool as hospitality and healthcare buyers prioritize front-facing interaction platforms. Industrial robots represent the fastest-expanding category, driven by automotive and logistics end users retrofitting assembly lines with dexterous automation. AI Integration commands the deepest margin concentration, as perception and decision software layers determine functional differentiation across hardware platforms.
The EU AI Act, ISO 13482 for personal care robot safety, and Japan's METI robotics roadmap collectively shape certification requirements and market access conditions for humanoid vendors. FDA device classification pathways in the United States further constrain clinical and therapeutic deployment timelines. Stakeholders must monitor evolving liability frameworks and interoperability standards before committing to platform-scale investments.
Market Dynamics
The EU AI Act is compressing development timelines for humanoid platforms bound for European industrial buyers, forcing vendors to front-load conformity testing and documentation before commercial rollout.
Growth Catalysts
- Japan's METI robotics roadmap:Government procurement mandates for eldercare facilities are institutionalizing bipedal deployment in assisted living environments.
- Logistics automation:US warehousing operators are scaling pilot programs for material handling tasks, validating unit economics for bipedal platforms in fulfillment centers.
- Battery energy density improvements:Solid-state cell chemistries are extending operational uptime between charging cycles, enabling continuous-shift deployment models.
Market Restraints
- Actuator cost concentration:Precision torque motors and harmonic drives remain concentrated among Japanese and German component suppliers, creating input cost volatility.
- ISO 13482 certification friction:Personal care robot safety standards impose multi-year validation timelines for therapeutic and clinical applications.
- Wheeled mobile manipulators:Lower-cost autonomous platforms with robotic arms are substituting for bipedal units in controlled industrial floorspace.
Strategic Opportunities
- German automotive retrofit programs:Assembly line flexibility mandates are creating white space for dexterous manipulation platforms in mixed-model production.
- Convergence of vision-language models with tactile sensing:Multimodal AI architectures are enabling zero-shot task generalization without pre-programmed motion libraries.
- India's PLI scheme for robotics:Manufacturing incentives are attracting component localization investments for cost-down supply chain reconfiguration.
Industry Challenges
- Control systems engineering talent:The shortage of specialists in whole-body dynamics and balance control is constraining platform development velocity.
- Legacy MES integration complexity:Bipedal units require custom middleware to communicate with existing manufacturing execution systems, extending deployment timelines.
- Patent thickets in grasping mechanisms:Dense IP landscapes around adaptive grippers are forcing licensing negotiations or design-arounds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Humanoids Market |
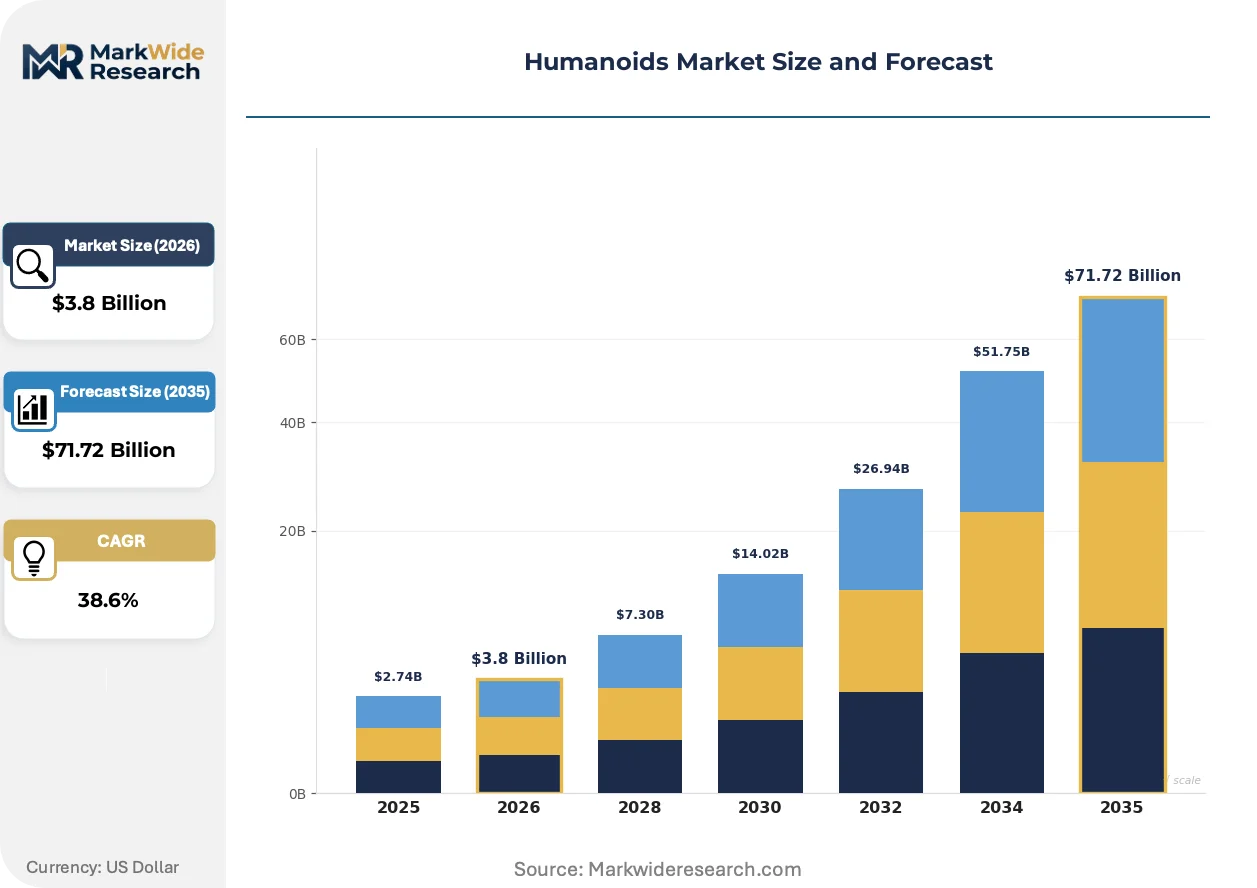
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $71.72 Billion |
| CAGR (2026 – 2036) | 38.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Robot Type: Service Robots, Industrial Robots, Telepresence Robots, Rehabilitation Robots Application: Education, Healthcare, Hospitality, Entertainment End User: Healthcare Providers, Educational Institutions, Retailers, Research Centers Technology: AI Integration, Sensor Technology, Motion Control, Human-Robot Interaction |
| Companies Covered | Tesla, AgiBot, Boston Dynamics, Figure AI, 1X Technologies, SoftBank Robotics Group, Unitree Robotics, Apptronik, ROBOTIS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Humanoids Market Shifts & Advancements
Foundation models trained on human motion capture data are compressing the programming burden for novel task sequences, shifting competitive advantage from hardware engineering to data acquisition infrastructure.
Reinforcement learning from human feedback is absorbing the traditional role of explicit motion planning in bipedal locomotion. Automotive assembly plants in Germany and Japan are deploying these architectures for adaptive gait generation across uneven factory floors. This compression of control software development cycles is reallocating R&D budgets toward sensor hardware and compute integration.
The EU AI Act's risk classification framework for autonomous systems is mandating conformity assessments before market access. Industrial buyers in France and the Netherlands are now requiring documented explainability for locomotion decisions near human workers. Vendors are responding by embedding interpretable neural architectures and audit logging capabilities into control stacks.
Japanese hospital networks are unbundling hardware procurement from service contracts, purchasing bipedal units outright while sourcing maintenance and software updates through separate agreements. This disintermediation of traditional robotics integrators is compressing vendor margins on recurring revenue streams. The shift is most visible in Tokyo and Osaka metropolitan healthcare procurement, where capital budgets are expanding faster than operational technology staffing.
Humanoids Market Segmentation
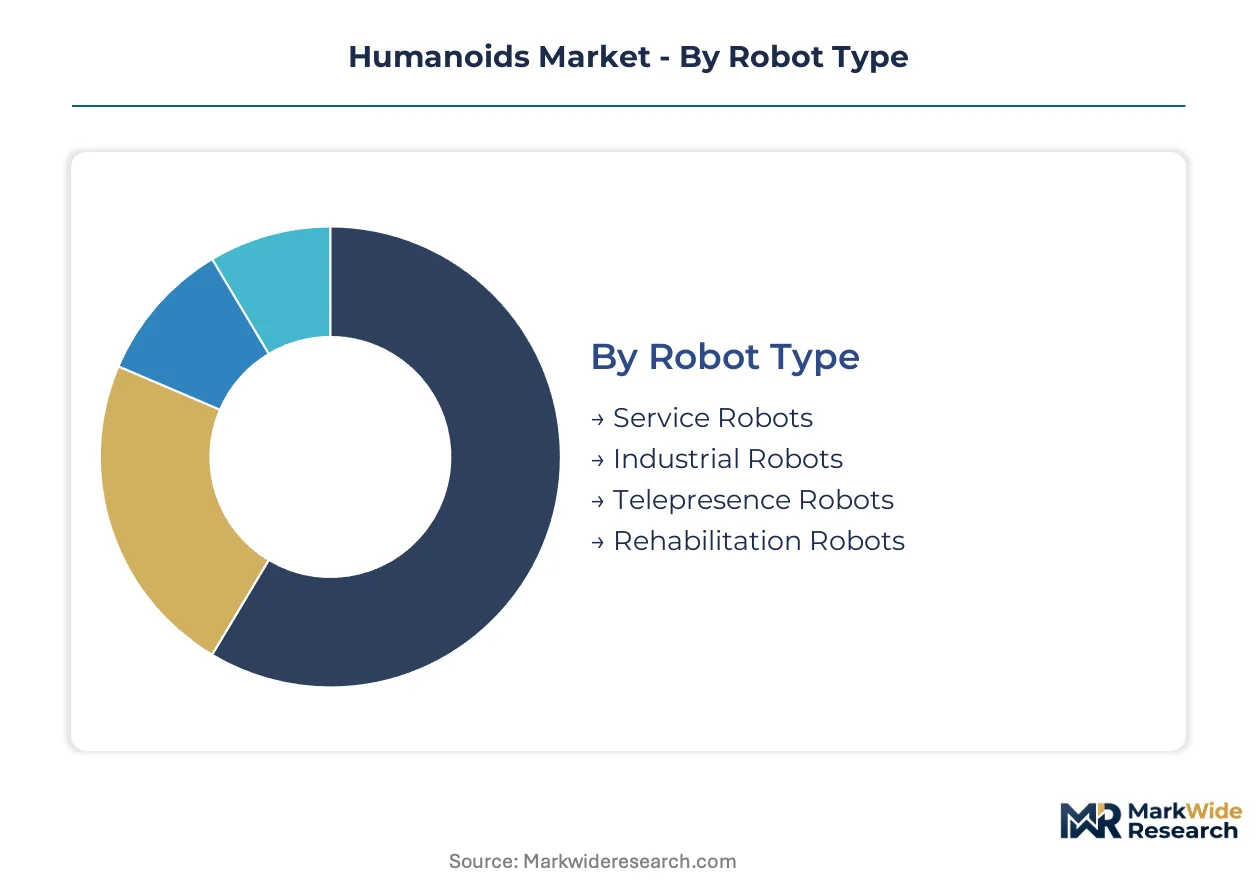
Segmentation in the humanoids market exposes divergent certification burdens and margin profiles across deployment contexts. Regulatory pathways from the EU AI Act, FDA device classification, and ISO 13482 create tiered compliance costs that reshape vendor prioritization and buyer procurement timelines.
Robot Type:
ISO 13482 personal care robot safety standards apply selectively across robot types, with therapeutic and clinical deployments facing multi-year validation timelines that compress commercial velocity for vendors targeting European and Japanese healthcare buyers.
- Service Robots:Front-facing interaction platforms with speech synthesis, emotion recognition, and navigation capabilities designed for unstructured environments. Hospitality networks in Tokyo and eldercare facilities across Japan's Kansai region are institutionalizing bipedal procurement for reception and companion roles, driven by METI robotics roadmap procurement mandates.
- Industrial Robots:Bipedal platforms with torque-optimized actuators and force-feedback manipulators engineered for assembly line retrofit. German automotive plants in Stuttgart and Wolfsburg are deploying these units for mixed-model production flexibility, validating unit economics where wheeled alternatives face floor space constraints.
- Telepresence Robots:Remote-operated bipedal units with audiovisual relay and limited autonomous locomotion for distributed workforce coordination.
- Rehabilitation Robots:Gait-training and motor-assistance platforms with patient-specific adaptive resistance and fall-detection safety architectures.
Leading the category by volume: Service Robots. Growing fastest: Industrial Robots.
Application:
Application selection determines whether deployments fall under FDA device jurisdiction, EU AI Act high-risk system classification, or lighter-touch commercial robotics frameworks, with direct implications for documentation burdens and time-to-revenue.
- Education:Curriculum-integrated platforms with programmable motion libraries and safety-rated force limits for unsupervised child interaction. K-12 districts in Texas and California are piloting bipedal units for STEM instruction and special needs support, constrained by district-level liability insurance requirements.
- Healthcare:Clinical-grade systems with sterilizable surfaces, HIPAA-compliant data handling, and FDA Class II device pathways for therapeutic claims. Hospital networks in Osaka are unbundling hardware procurement from service contracts, compressing vendor recurring revenue margins.
- Hospitality:Guest-facing platforms with multilingual natural language processing and luggage handling manipulation for concierge and housekeeping workflows.
- Entertainment:Performance-optimized bipedal units with expressive motion capture-driven choreography and audience safety perimeter systems for theme park and live event deployment.
Healthcare commands the deepest margin concentration. Education is expanding most quickly among non-industrial buyers.
End User:
End user type shapes procurement contract structures, with research centers favoring milestone-based development agreements while healthcare providers demand outcome-guaranteed service models.
- Healthcare Providers:Hospital systems and skilled nursing facilities with capital budget cycles and Joint Commission accreditation requirements driving platform selection.
- Educational Institutions:Universities and K-12 districts with grant-funded acquisition and NSF curriculum alignment priorities.
- Retailers:Big-box and specialty chains deploying customer engagement and inventory management bipedal units in flagship locations.
- Research Centers:National laboratories and corporate R&D facilities with custom middleware requirements and publication-driven technology evaluation timelines.
Healthcare Providers anchor current procurement volume. Research Centers are scaling fastest as foundation model developers seek physical embodiment testbeds.
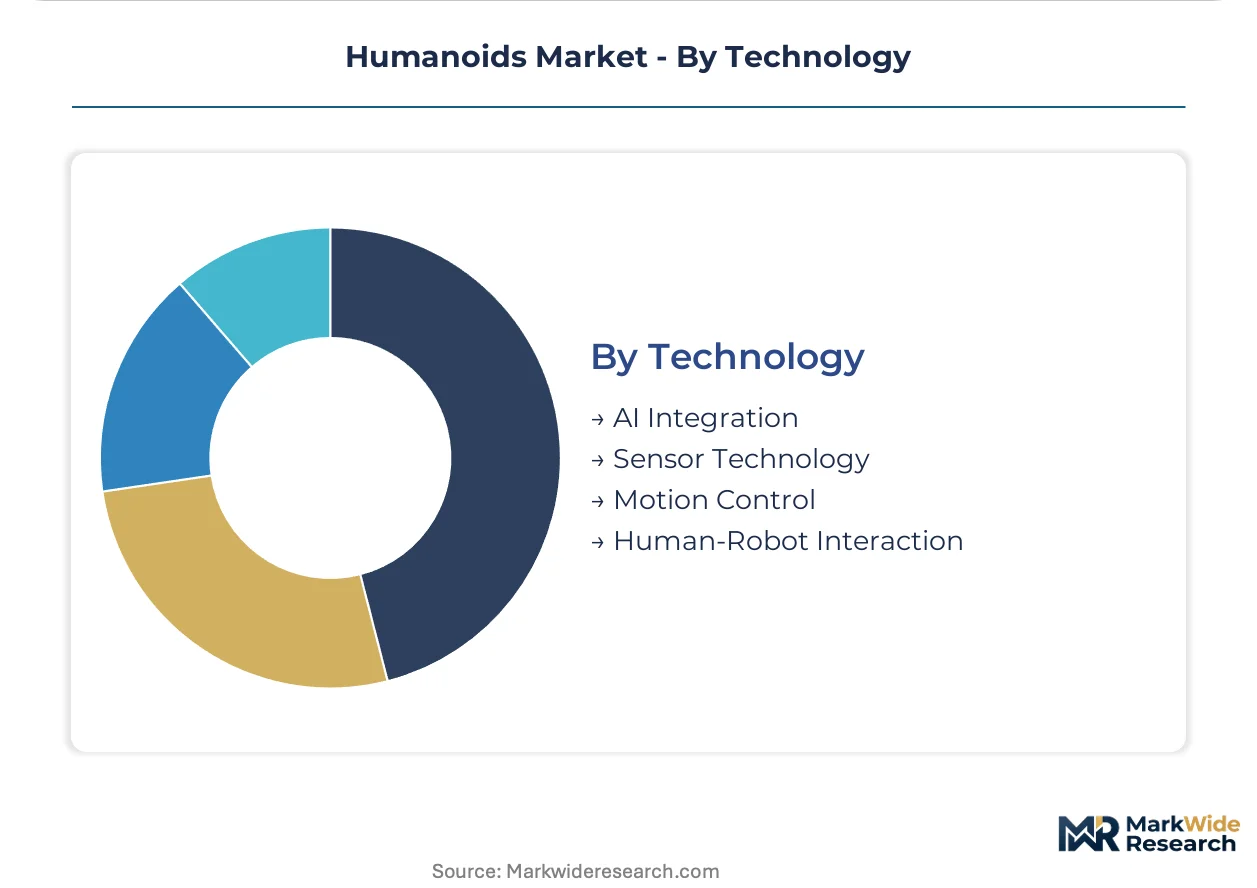
Technology:
Technology layer selection determines whether vendors capture value through hardware margins or recurring software licensing, with AI Integration commanding the steepest differentiation premiums.
- AI Integration:Perception and decision software stacks including vision-language models, reinforcement learning locomotion controllers, and explainability architectures for EU AI Act compliance. Vendors embedding interpretable neural architectures and audit logging capabilities are securing industrial buyer preference in France and the Netherlands.
- Sensor Technology:Tactile, proprioceptive, and exteroceptive sensor fusion systems enabling zero-shot task generalization without pre-programmed motion libraries.
- Motion Control:Whole-body dynamics and balance control algorithms with real-time terrain adaptation.
- Human-Robot Interaction:Natural language, gesture recognition, and affective computing interfaces for unsupervised public space deployment.
AI Integration claims the highest margin concentration. Sensor Technology is gaining share fastest as multimodal architectures converge with tactile sensing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo anchors the most concentrated humanoid procurement activity worldwide, with metropolitan healthcare networks and eldercare facilities driving institutional deployment at scale.
United States
Logistics operators in California and Texas are validating bipedal unit economics for warehouse material handling, with pilot programs expanding across fulfillment corridors. FDA device classification pathways constrain therapeutic deployment timelines for clinical applications. The Detroit automotive cluster is retrofitting mixed-model assembly lines with dexterous manipulation platforms.
Germany
Automotive plants in Stuttgart and Wolfsburg are deploying bipedal units for production flexibility where wheeled alternatives face floor space constraints. The EU AI Act mandates conformity assessments and documented explainability for locomotion decisions near human workers. Bavarian industrial buyers now require interpretable neural architectures and audit logging capabilities in control stacks.
Japan
Hospital networks in Osaka and Tokyo are unbundling hardware procurement from service contracts, purchasing bipedal units outright while sourcing maintenance separately. METI robotics roadmap procurement mandates are institutionalizing deployment in Kansai region eldercare facilities. Aging demographics and labor shortages are accelerating institutional procurement of care-oriented humanoids.
China
Research centers in Beijing and Shenzhen are scaling physical embodiment testbeds for foundation model developers seeking robotics integration. MIIT standards and GB certification frameworks shape domestic market access conditions for bipedal platforms. The Yangtze River Delta is attracting component localization investments for supply chain cost reduction.
South Korea
Corporate R&D facilities in the Seoul Capital Area are prioritizing multimodal AI architectures converging with tactile sensing for zero-shot task generalization. MFDS and national robotics safety standards govern deployment in healthcare and industrial environments. Busan-Ulsan manufacturing corridors are evaluating bipedal platforms for shipbuilding and heavy industry retrofit programs.
Humanoids Market Competitive Landscape
The competitive structure tilts toward diversified technology conglomerates with captive AI and battery supply chains. Tiered specialization separates dynamic locomotion specialists from manipulation-focused platforms and hospitality-oriented interaction systems. Strategic archetypes include automotive-anchored integrators, defense-derived robotics spinouts, and venture-backed dexterity platforms. Dominant competitive moves encompass strategic partnerships with end-user assembly lines and upstream component sourcing alliances.
Among US-based developers, Tesla exemplifies the automotive-anchored integrator archetype leveraging captive battery and AI infrastructure. Boston Dynamics occupies a position within the defense-derived tier, while Figure AI sits within the venture-backed manipulation specialist category. Japanese conglomerate SoftBank Robotics Group anchors the hospitality-oriented interaction system tier. Chinese fabricators including Unitree Robotics represent the hardware-cost optimization archetype, with AgiBot exemplifying emerging domestic challengers in the bipedal platform space.
| Leading Market Players |
|---|
| Tesla |
| AgiBot |
| Boston Dynamics |
| Figure AI |
| 1X Technologies |
| SoftBank Robotics Group |
| Unitree Robotics |
| Apptronik |
| ROBOTIS |
| Others |
Supply & Pricing Matrix
Control systems engineering specialists in Stuttgart and Wolfsburg command wage premiums that compress pricing-tier spreads between premium and standard-grade bipedal platforms, as labor-cost differentials in whole-body dynamics talent pools outweigh component savings from volume scale.
Pricing Analysis
Outcome-guaranteed uptime contracts anchor value-based pricing for industrial deployments, with German automotive buyers paying premiums for documented explainability architectures that satisfy EU AI Act conformity requirements. Price differentiation separates FDA Class II-certified therapeutic platforms from commercial-grade service units, with certification-grade tiering widening spreads as ISO 13482 validation timelines extend. Cost compression in standard-tier logistics units is intensifying because wheeled mobile manipulators are substituting for bipedal alternatives in controlled warehouse floorspace. Research centers exhibit lowest price sensitivity due to grant-funded acquisition, while K-12 districts face district-level liability insurance constraints that amplify budget rigidity.
Supply Chain Analysis
Freight cost volatility from precision torque motor shipments between Japan and Germany is amplifying landed cost differentials for harmonic drive actuators, with air-cargo premiums for just-in-time delivery compressing margins on European-bound platforms. Component manufacturing concentrates in Japan, Germany, and China, with solid-state battery cell production drawing from South Korean and Chinese chemical suppliers. Single-source vulnerability in harmonic drive gearing from Japanese specialty manufacturers creates chokepoint exposure for vendors scaling production. Distribution runs through traditional robotics integrators in industrial segments, though Japanese hospital networks are disintermediating these channels through unbundled hardware procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Actuator fabrication capacity constraints in precision torque motor supply are propping platform pricing, with Japanese and German component specialists unable to scale output commensurate with pilot program expansion across automotive and logistics buyers.
For Market Incumbents: Anchor defensive positioning through captive supply agreements with harmonic drive specialists in Japan, locking preferential allocation as wheeled mobile manipulators from Chinese fabricators threaten standard-tier bipedal demand in warehouse automation. Deepen backward integration into solid-state battery cell sourcing to secure energy density improvements that enable continuous-shift deployment models, insulating margin structures from commodity volatility in lithium-ion supply chains. For New Entrants and Emerging Players: The EU AI Act in Germany and France opens a window for compliance-native architectures, with documented explainability and audit logging capabilities creating procurement preference among Bavarian industrial buyers seeking pre-certified platforms. Target India's PLI scheme for robotics manufacturing incentives, leveraging component localization investments to undercut landed costs for cost-sensitive logistics operators in Texas and California fulfillment corridors. Pursue milestone-based development agreements with research centers in Beijing and Shenzhen as foundation model developers seek physical embodiment testbeds. For Investors and Strategic Acquirers: Re-rating potential sits with venture-backed dexterity platforms given convergence of vision-language models with tactile sensing architectures that enable zero-shot task generalization without pre-programmed motion libraries. Long-term viability favors developers with automotive-anchored integration partnerships and captive AI infrastructure rather than hardware-cost optimization specialists facing margin compression from unbundled service contracts. Watch procurement mandate velocity from Japan's METI robotics roadmap as the inflection indicator for institutional care-oriented deployment at scale.| Strategic Initiative | Industry Significance |
|---|---|
| Automotive Assembly Line Partnership | Secures validation data for adaptive gait generation across uneven factory floors in Stuttgart plants. |
| EU AI Act Conformity Pre-Certification | Accelerates market access for industrial buyers in France and Netherlands requiring documented explainability. |
| Harmonic Drive Supply Agreement | Locks preferential component allocation from Japanese specialists amid actuator cost concentration. |
| Foundation Model Data Infrastructure | Captures competitive advantage as reinforcement learning compresses traditional motion planning development cycles. |
| India PLI Localization Investment | Enables supply chain cost reduction for price-sensitive logistics operators scaling pilot programs. |
Research Methodology
SEC filings from Tesla and Boston Dynamics, EU AI Act implementation guidance from the European Commission, and METI robotics roadmap documentation formed the secondary backbone, cross-referenced with primary interviews with control systems engineering directors, automotive platform procurement leads, eldercare facility operations managers, and robotics integrator technical sales heads. Bottom-up unit economics modeling triangulated against top-down market sizing from component shipment data and pilot program disclosure patterns.
Bottom-up segmentation analysis modeled robot type, application, end user, and technology layer dimensions across the projection horizon, with CAGRs derived from deployment velocity assumptions tied to regulatory clearance timelines and labor shortage severity indices. Forecast inputs incorporated battery energy density improvement curves, ISO 13482 certification friction estimates, and foundation model training cost trajectories for multimodal AI architectures.
The model assumes a particular technology adoption path; alternative pathways for solid-state cell chemistry commercialization or vision-language model convergence rates would alter the outlook. Forecasts reflect documented assumptions regarding EU AI Act enforcement rigor and Japanese procurement mandate expansion. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Pipetting Robots Market
Robotics and Automation
Global AI Based Surgical Robots Market
Robotics and Automation
Robotics for NDT Market
Robotics and Automation
Robotic Air Purifier Market
Robotics and Automation
Robotic Process Automation in BFSI Market
Robotics and Automation
Europe Data Center Robotics Market
Robotics and Automation
Robot Label Applicators Market
Robotics and Automation
Top Robotics Market
Robotics and Automation
Global Educational Robots Market
Robotics and Automation
Robotic Flexible Washer Market
Robotics and Automation
Firefighting Robots Market
Robotics and Automation
SCARA Robots Market
Robotics and Automation
Underwater Exploration Robots Market
Robotics and Automation
Robotics Technology Market
Robotics and Automation
Latin America Warehouse Robotics Market
Robotics and Automation
Retail Robotics Market